
 North America Offshore Helicopter Services Market | 2026-2036
North America Offshore Helicopter Services Market Size, Share, and Industry Trends Forecast 2026-2036
North America Offshore Helicopter Services Market Analytics
Maintenance-as-a-service is pivoting how operators monetize fleet availability, shifting revenue from hourly flight charges to contracted uptime guarantees. Bristow Group Inc leverages its integrated logistics platform to sustain long-term contracts with supermajor energy clients across the Gulf of Mexico. CHC Group Ltd anchors its competitive position through specialized SAR capabilities that differentiate it from commodity transport providers.
Offshore helicopter services encompass rotary-wing aviation operations supporting personnel transport, cargo delivery, and emergency response to installations beyond coastal reach, typically requiring twin-engine aircraft with extended-range fuel systems and full autorotation capability for water ditching scenarios. Oil & Gas retains dominant service type share, though Renewable Energy segment growth is accelerating fastest as East Coast wind lease areas require crew transfer logistics. Among helicopter models, the Sikorsky S-92 and Airbus H225 occupy the heavy-lift tier where platform crew rotations generate the deepest margin pools due to payload-distance premiums.
FAA Part 135 rules and OSHA offshore workplace standards jointly shape aircraft equipment mandates and pilot duty limitations for Gulf of Mexico operations. Transport Canada parallel regulations for Newfoundland-Labrador offshore zones create cross-border compliance complexity for fleet operators serving both markets. Stakeholders must weigh whether to standardize on dual-certified aircraft configurations or maintain segmented fleet pools as Atlantic Canada wind development accelerates.
Market Dynamics
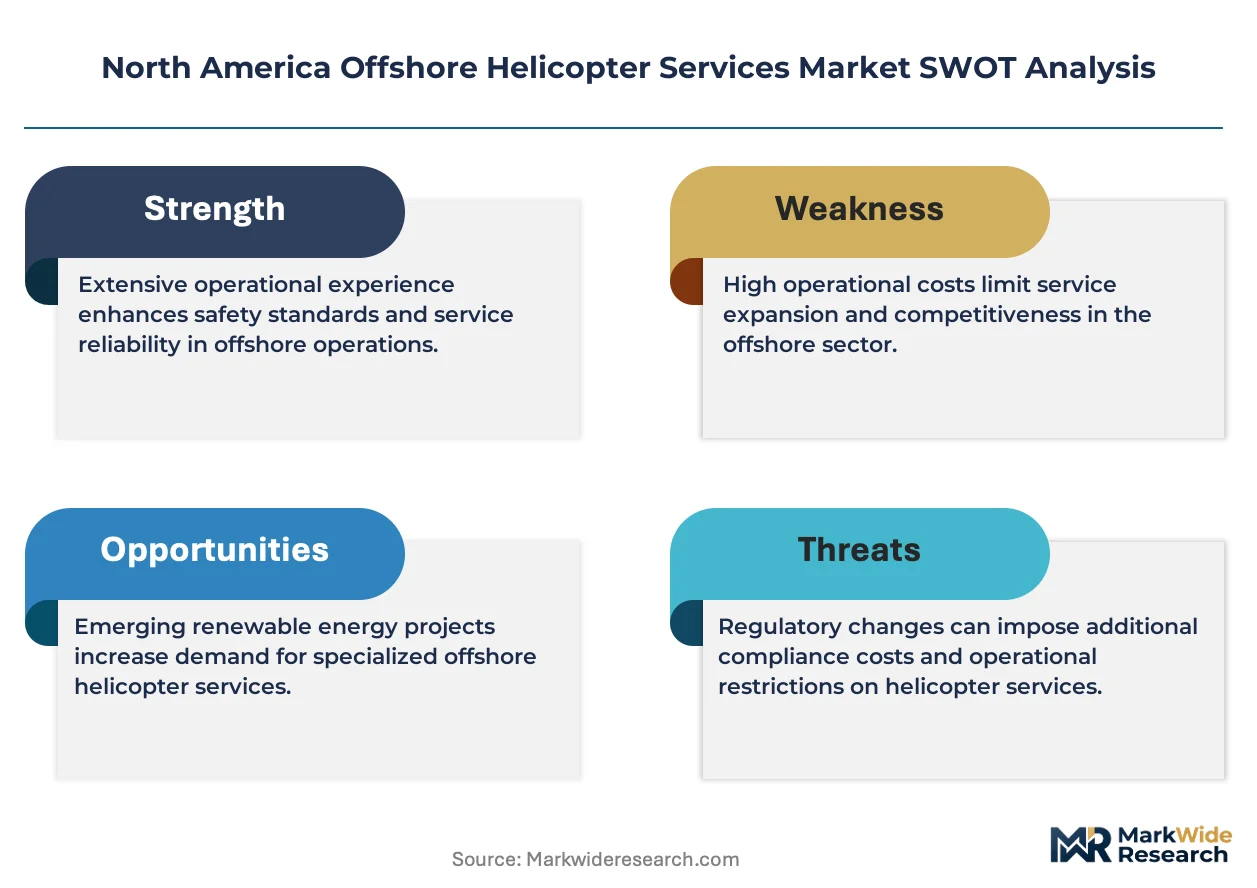
FAA Part 135 certification tightening is compressing operator margins while simultaneously erecting entry barriers that favor scaled incumbents with dedicated training infrastructure and dual-aircraft-type fleets.
Growth Catalysts
- Atlantic Coast Wind Lease Expansion:Federal offshore wind lease auctions along Massachusetts, New York, and New Jersey coastlines are generating crew transfer logistics demand that helicopter operators are positioning to capture through extended-range aircraft configurations.
- FAA Part 135 Over-Water Mandates:Stricter pilot training hour requirements and aircraft equipment standards for extended over-water operations are forcing consolidation toward operators with dedicated simulation centers and SAR-capable fleets.
- Gulf of Mexico Platform Recommissioning:Supermajor energy clients are extending production timelines on mature deepwater assets, sustaining crew rotation volumes that require heavy-lift helicopter capacity with full night-vision capability.
Market Restraints
- Aviation Fuel Price Volatility:Jet-A price swings directly compress flight-hour economics, particularly for operators running aging turbine fleets without fuel-hedging programs or long-term supply contracts with coastal refineries.
- Airframe OEM Concentration:Sikorsky and Airbus Helicopters control the heavy-lift tier, creating fleet standardization dilemmas for operators seeking to minimize parts inventory and maintenance certification complexity across mixed-type rosters.
- Autonomous Vessel Substitution:Crew transfer vessels and uncrewed surface vehicles are capturing shorter-range personnel movements from platforms within 50 nautical miles of shore, compressing addressable helicopter demand in coastal wind zones.
Strategic Opportunities
- Newfoundland-Labrador Offshore Corridor:Canada's eastern offshore oil revival and nascent wind lease development create a cross-border market where dual Transport Canada-FAA certification unlocks fleet utilization across seasonal demand cycles.
- Maintenance-as-a-Service Contracts:Long-term availability guarantees are displacing traditional hourly charter models, allowing operators to capture recurring revenue streams tied to platform production continuity rather than flight volume.
- Hybrid-Electric Range Extenders:Turboshaft-electric hybrid propulsion systems under development by engine manufacturers promise 15-20% fuel burn reduction, potentially resetting operating cost benchmarks for Gulf of Mexico route networks.
Industry Challenges
- Experienced SAR Pilot Scarcity:Night over-water search-and-rescue certification requires specialized training pipelines that exceed standard commercial pilot supply, constraining fleet expansion for operators bidding on bundled transport-plus-rescue contracts.
- Legacy Avionics Retrofit Timelines:FAA mandates for ADS-B Out and enhanced flight data monitoring are forcing accelerated airframe upgrade schedules that compete with routine heavy maintenance windows, compressing available revenue flight hours.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Offshore Helicopter Services Market |
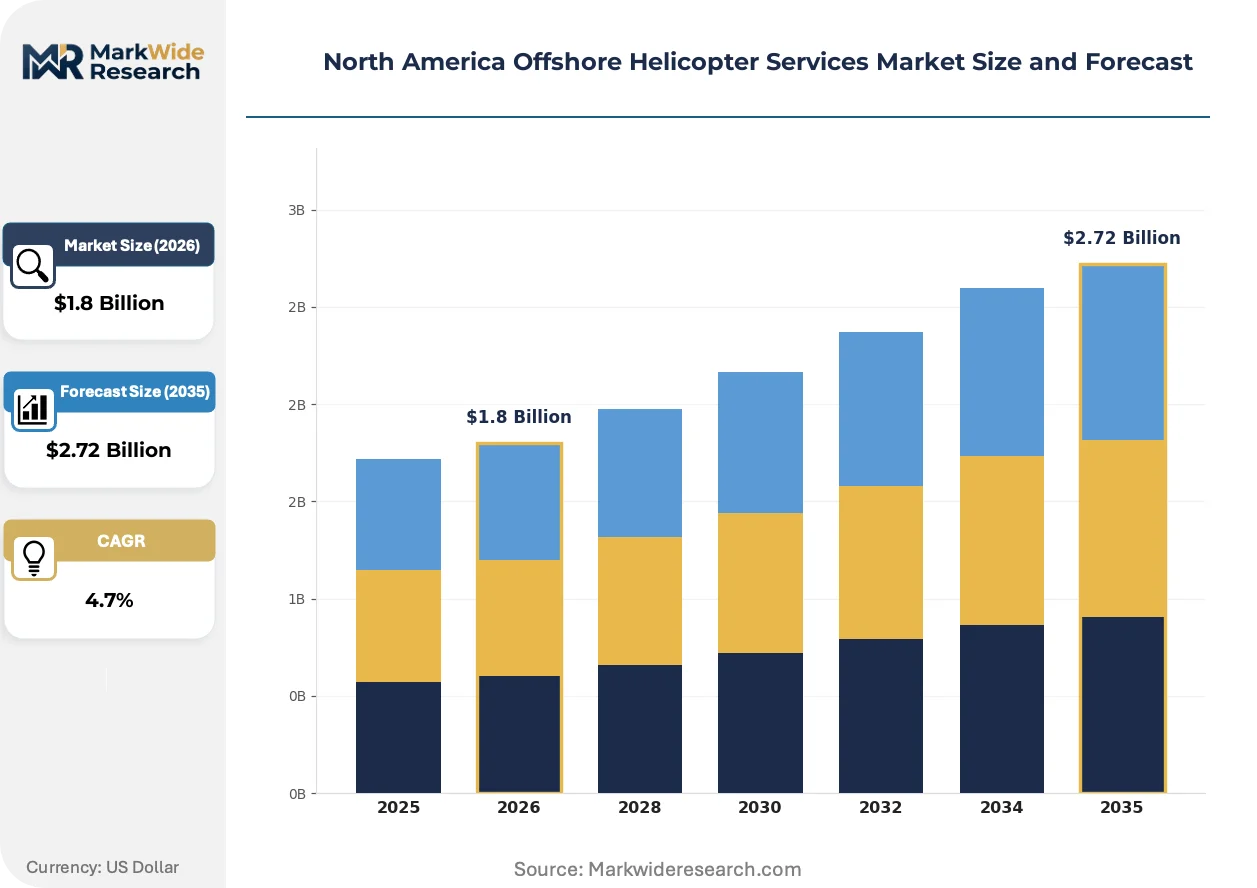
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Oil & Gas, Renewable Energy, Medical Evacuation, Search & Rescue End User: Energy Companies, Government Agencies, Emergency Services, Industrial Firms Helicopter Model: Sikorsky S-92, Airbus H225, Bell 412, Leonardo AW139 Flight Operation: Charter Services, Scheduled Services, On-Demand Services, Utility Operations |
| Companies Covered | Bristow Group Inc, Era Group Inc, CHC Group Ltd, Cougar Helicopters Inc, Petroleum Helicopters International Inc, PHI Inc, NHV Group, Textron Inc, HNZ Group Inc, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Offshore Helicopter Services Market Evolving Landscape
Digital fleet health monitoring and predictive maintenance algorithms are compressing unscheduled downtime, while regulatory pressure on emissions intensity is accelerating propulsion technology roadmaps across the heavy-lift helicopter segment.
Health and Usage Monitoring Systems (HUMS) are modularizing maintenance workflows across the Sikorsky S-92 and Airbus H225 fleets. Offshore operators with supermajor contracts are adopting these sensor suites fastest, driven by insurance premium reductions and contractual uptime penalties. The technology is modularizing how reliability data flows between operators, OEMs, and platform lessees, compressing traditional information asymmetries that once protected incumbent service providers.
Transport Canada's proposed offshore helicopter safety regulations for Newfoundland-Labrador operations are tightening weather minimums and emergency flotation requirements. These rules will force fleet standardization decisions for operators serving both Canadian and US Gulf markets, particularly around dual-certified aircraft configurations. The Atlantic Canada wind development segment faces the steepest compliance timeline, with draft rules targeting implementation before major construction phases begin.
Supermajor energy clients are unbundling crew transport from integrated logistics contracts, creating direct procurement relationships with helicopter operators that bypass traditional oilfield services intermediaries. This channel disintermediation is most visible along the Houston-New Orleans corridor, where platform operators now negotiate flight-hour minimums and cancellation terms directly rather than through bundled facility management contracts. The shift is compressing margin capture for integrated service companies while expanding addressable contract value for specialized aviation providers.
North America Offshore Helicopter Services Market Segmentation
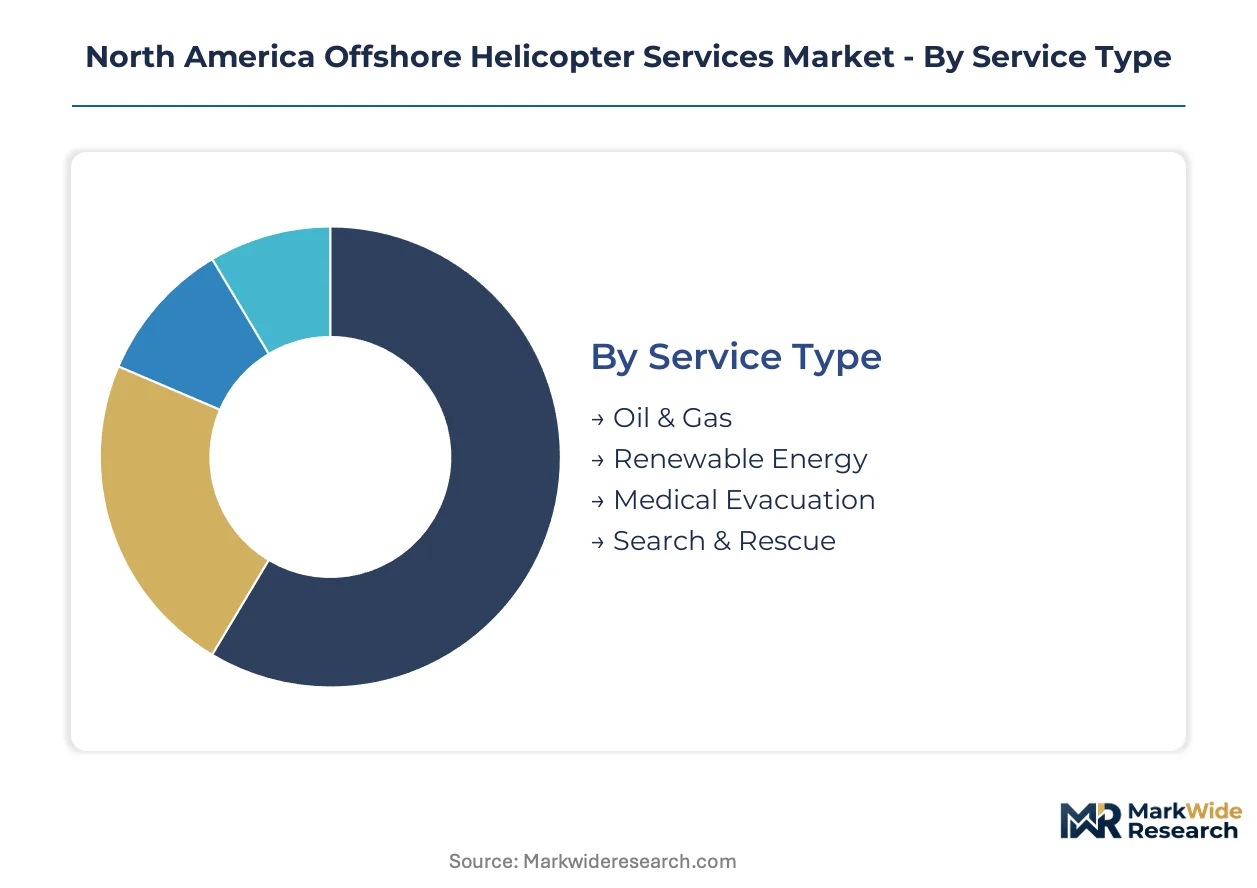
Segmentation in offshore helicopter services reveals how operational requirements diverge across energy subsectors, regulatory environments, and aircraft performance tiers. Buyers prioritize different capability bundles—SAR-equipped fleets for government contracts, heavy-lift configurations for deepwater platforms, rapid-response availability for medical evacuation. Understanding these divides clarifies why fleet standardization remains elusive and pricing varies dramatically across contract types.
Service Type:
Oil & Gas operators demand proven reliability metrics and night-vision capability, while renewable energy clients prioritize cost efficiency over redundant systems for shorter transit distances.
- Oil & Gas:Deepwater platform logistics require twin-engine heavy-lift aircraft with full autorotation capability for water ditching scenarios. Demand concentrates along the US Gulf Coast corridor from Houston to New Orleans, where supermajor clients negotiate long-term availability contracts tied to production continuity.
- Renewable Energy:Crew transfer services for offshore wind construction favor medium-lift helicopters with extended-range fuel systems for Atlantic coast transit. Massachusetts, New York, and New Jersey lease areas are multiplying flight-hour requirements faster than any other service category.
- Medical Evacuation:Dedicated air ambulance configurations with medical interior modules serve isolated platform populations.
- Search & Rescue:Specialized SAR fleets with rescue hoists and enhanced weather radar support FAA Part 135 over-water mandates.
Volume sits with Oil & Gas; growth tilts toward Renewable Energy.
End User:
Procurement sophistication varies sharply—energy majors negotiate direct operator relationships while government agencies impose rigid certification requirements.
- Energy Companies:Supermajor oil producers and offshore wind developers dominate contract value, unbundling crew transport from integrated logistics arrangements. These buyers now negotiate flight-hour minimums directly with aviation providers rather than through oilfield services intermediaries.
- Government Agencies:Coast Guard and maritime authorities mandate SAR-capable fleets with specialized night over-water certification. FAA and Transport Canada parallel regulations create dual-certification complexity for operators serving cross-border Newfoundland-Labrador zones.
- Emergency Services:Municipal and regional authorities contract for medical evacuation coverage in coastal jurisdictions.
- Industrial Firms:Construction and maintenance contractors require flexible on-demand access for project-based offshore work.
Contract value concentrates with Energy Companies; regulatory stringency peaks with Government Agencies.
Helicopter Model:
Payload-distance economics and parts commonality drive fleet decisions, with OEM concentration limiting operator choice.
- Sikorsky S-92:Heavy-lift platform with 19-passenger capacity and full ice-protection systems for North Atlantic operations. Gulf of Mexico deepwater rotations generate premium margins due to distance-payload combinations that smaller airframes cannot match.
- Airbus H225:Competing heavy-lift tier with extended-range fuel configurations for Atlantic coast wind logistics. Health and Usage Monitoring Systems (HUMS) integration is standardizing fastest on this airframe among supermajor contract holders.
- Bell 412:Medium-lift twin-engine platform serving shorter-range utility and SAR missions.
- Leonardo AW139:Intermediate-class aircraft with offshore-certified emergency flotation systems.
Fleet investment flows toward Sikorsky S-92; HUMS adoption spreads fastest on Airbus H225.
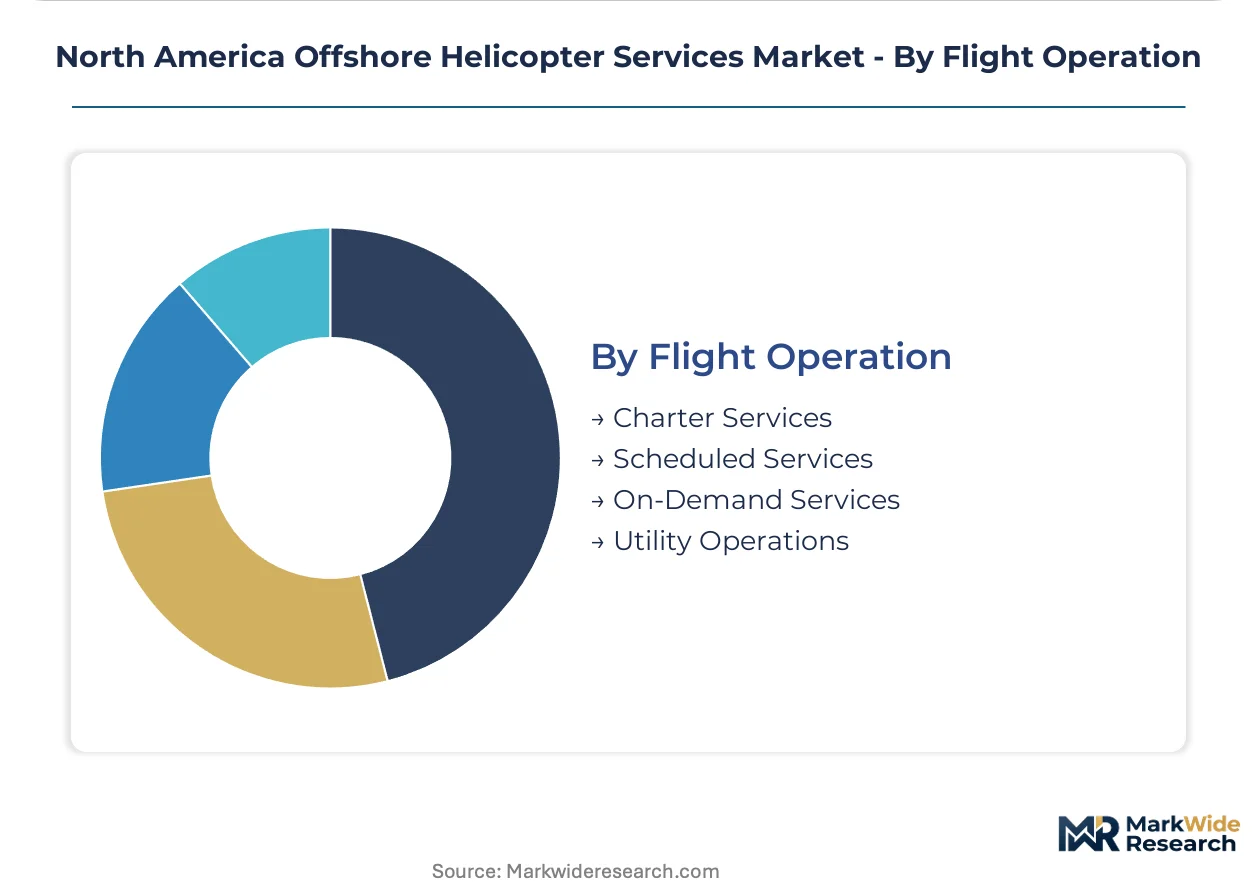
Flight Operation:
Revenue model selection determines capital intensity and pilot staffing requirements.
- Charter Services:Traditional hourly flight charges dominate legacy oil & gas contracts, though margins compress under fuel price volatility. Operators without long-term supply agreements with coastal refineries face direct Jet-A cost exposure.
- Scheduled Services:Fixed-rotation crew transfer contracts for producing platforms generate predictable utilization. Gulf of Mexico platform recommissioning is extending production timelines and sustaining these volumes.
- On-Demand Services:Ad-hoc availability for emergency response and unplanned maintenance movements commands rate premiums.
- Utility Operations:External load and specialized equipment transport serves construction and decommissioning phases.
Revenue stability favors Scheduled Services; margin expansion is shifting toward On-Demand Services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Helicopter service production concentrates along the US Gulf Coast, while Canadian Atlantic demand is accelerating fastest. Consumption patterns split between mature oil platform logistics and emerging wind farm crew transfer requirements.
United States Gulf Coast
Deepwater platform recommissioning sustains heavy-lift crew rotation volumes from Houston to New Orleans. FAA Part 135 over-water mandates tighten pilot training standards for extended-range operations. Supermajor energy clients negotiate direct procurement relationships that bypass traditional oilfield services intermediaries.
Atlantic Coast Wind Corridor
Federal offshore wind lease auctions across Massachusetts, New York, and New Jersey multiply crew transfer logistics demand. FAA certification requirements for extended over-water operations shape aircraft equipment procurement timelines. Atlantic coast construction phases drive fastest growth in medium-lift helicopter configurations with extended-range fuel systems.
Newfoundland-Labrador
Offshore oil revival and nascent wind lease development create cross-border fleet utilization opportunities. Transport Canada parallel regulations for weather minimums and emergency flotation requirements impose dual-certification complexity. St. John's anchors Atlantic Canada's helicopter logistics infrastructure for seasonal demand cycles.
Canada Pacific
British Columbia offshore exploration and coastal resource development sustain utility helicopter demand. Transport Canada certification alignment with FAA standards enables fleet rotation across North American markets. Vancouver serves as the western coordination hub for cross-border maintenance and crew positioning.
North America Offshore Helicopter Services Market Competitive Landscape
Top-tier vendors anchor the integrated logistics tier, while specialized SAR operators and regional charter providers occupy distinct competitive positions. The market structure favors scaled incumbents with dedicated training infrastructure and dual-aircraft-type fleets. Three archetypes dominate: supermajor-integrated logistics platforms, SAR-specialized operators, and regional wind-focused crew transfer providers. Consolidation pressures favor M&A activity among mid-scale operators, while technology licensing partnerships accelerate Health and Usage Monitoring Systems adoption.
Within the integrated logistics tier, Bristow Group Inc and CHC Group Ltd represent archetypal positions. Bristow's Gulf of Mexico presence exemplifies supermajor relationship depth. CHC occupies a position defined by specialized SAR capabilities that differentiate it from commodity transport providers. Era Group Inc sits within the regional specialist archetype, anchoring fleet availability models across multiple basins.
| Leading Market Players |
|---|
| Bristow Group Inc |
| Era Group Inc |
| CHC Group Ltd |
| Cougar Helicopters Inc |
| Petroleum Helicopters International Inc |
| PHI Inc |
| NHV Group |
| Textron Inc |
| HNZ Group Inc |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up specialists dominate North American offshore helicopter operations, concentrating fleet ownership among scaled incumbents who leverage training infrastructure and dual-type certifications to enforce pricing discipline against fragmented regional challengers. This ownership pattern tightens supply-side coordination while compressing margin capture for buyers locked into long-term availability contracts.
Pricing Analysis
Margin tightening in heavy-lift crew rotations reflects supermajor unbundling of transport from integrated logistics contracts, shifting negotiation leverage toward direct operator relationships. Three-tier pricing structure across SAR-equipped premium, night-vision standard, and day-only economy levels separates government agency mandates from commodity wind farm transfers. Cost-down pressure on medium-lift configurations accelerates because autonomous vessel substitution erodes addressable demand inside fifty nautical miles. Renewable energy developers exhibit highest price sensitivity, while Coast Guard SAR contracts tolerate rate premiums for specialized certification.
Supply Chain Analysis
Domestic-content mandates under FAA Part 135 and Transport Canada parallel regulations reshape sourcing toward North American maintenance, repair, and overhaul facilities for critical airframe components. Geographic supply concentration centers on Connecticut for Sikorsky final assembly, Texas for Gulf Coast MRO clusters, and Quebec for Airbus Helicopters regional support. Raw material dependencies include titanium forgings for rotor hubs, composite structures for fuselage sections, and avionics suites from specialized tier-one suppliers. Single-source vulnerability around engine OEM certification creates fleet standardization dilemmas. Distribution runs through supermajor direct procurement channels that disintermediate traditional oilfield services intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into captive pilot training infrastructure represents the decisive upstream lever in this market, as FAA Part 135 tightening and SAR certification scarcity constrain fleet expansion for operators without dedicated simulation centers.
For Market Incumbents: Anticipate autonomous vessel substitution by diversifying into hybrid-electric range extender partnerships and securing exclusive maintenance-as-a-service contracts with Atlantic Coast wind developers. Consolidate position through targeted acquisition of regional specialists holding Transport Canada-FAA dual certification, locking in cross-border fleet utilization before Newfoundland-Labrador demand accelerates. For New Entrants and Emerging Players: Capture underserved on-demand emergency response niches in decommissioning-heavy Gulf of Mexico corridors where legacy operators prioritize scheduled production rotations. Target government agency SAR contracts with bundled transport-plus-rescue proposals, leveraging specialized night over-water certification as the primary go-to-market wedge against commodity transport providers. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale operators with stranded heavy-lift capacity and established supermajor relationships in the US Gulf Coast corridor. Long-term viability hinges on fleet age profiles and HUMS technology adoption rates. Watch FAA Part 135 implementation timelines as the critical inflection signal for training infrastructure valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Maintenance-as-a-Service Contracting | Transforms revenue from hourly flight charges to guaranteed uptime commitments with supermajor energy clients. |
| Dual Certification Investment | Unlocks fleet rotation across FAA and Transport Canada jurisdictions as Atlantic Canada wind development accelerates. |
| Hybrid-Electric Propulsion Partnership | Resets fuel burn benchmarks for Gulf of Mexico route networks through turboshaft-electric range extender integration. |
| HUMS Technology Licensing | Compresses unscheduled downtime across Sikorsky S-92 and Airbus H225 fleets while reducing insurance premium exposure. |
| SAR Capability Buildout | Differentiates operators from commodity transport providers in bundled government agency contract competitions. |
Research Methodology
Multi-period observation of fleet utilization rates, certification timelines, and contract unbundling patterns anchored the trend analysis, supplemented by interviews with helicopter fleet managers, FAA certification specialists, supermajor logistics procurement officers, and Transport Canada regulatory leads. Secondary validation drew from FAA Part 135 docket filings, Transport Canada proposed rule notices, SEC 10-K disclosures from publicly traded operators, and offshore wind lease auction records from the Bureau of Ocean Energy Management. Bottom-up triangulation across operator fleet registries converged with top-down energy production forecasts.
Input-output matrix modeling connected helicopter flight-hour demand to offshore platform staffing requirements and wind farm construction schedules across the projection horizon. Segmentation dimensions included service type, end user procurement sophistication, helicopter model performance tier, and flight operation revenue model. CAGRs were derived from regression analysis against historical flight-hour correlations with oil and gas capital expenditure cycles and wind installation vessel deployment patterns.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to autonomous vessel substitution rates, aviation fuel price volatility, and regulatory harmonization between FAA and Transport Canada regimes. Forecasts reflect documented assumptions around supermajor contract renewal patterns and Atlantic Coast wind construction timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Air Mobility
Airborne Pods Market
Air Mobility
Air Transport Modifications Market
Air Mobility
Parabolic Flight Tourism Market
Air Mobility
Flying Jetpacks Market
Air Mobility
Off-Shore Helicopters Market
Air Mobility
North Sea Offshore Helicopter Services Market
Air Mobility
China Chartered Air Transport Market
Air Mobility
Hang Glider Market
Air Mobility
Air Crane Helicopter Market
Air Mobility
Global Aerodynamics Market
Air Mobility
Flying Taxi Market
Air Mobility
Advanced Aerial Mobility Market
Air Mobility
Asia Pacific Helicopter Services Market
Air Mobility
Asia-Pacific Charter Jet Service Market
Air Mobility
Urban Autonomous Air Mobility Market
Air Mobility
Global Aerial Firefighting Market