
 Commercial Electronic Flight Bag Market | 2026-2036
Commercial Electronic Flight Bag Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Electronic Flight Bag Market Outlook
The EU Green Deal is consolidating environmental accountability across aviation supply chains, pushing carriers to eliminate paper-based flight documentation. Collins Aerospace leverages its avionics integration heritage to dominate integrated hardware-software bundles. Thales Group sustains competitive positioning through cybersecurity-hardened platforms tailored for European flag carriers.
A commercial electronic flight bag comprises tablet-based or installed computing systems that deliver real-time flight information, navigation charts, and operational manuals to cockpit crews, typically operating on Class 2 or Class 3 hardware certified to DO-160G environmental standards. Software solutions lead revenue contribution as airlines prioritize subscription-based charting and performance calculation suites over capital-intensive hardware swaps. Cloud-based deployment segments are expanding fastest, driven by low-latency satellite connectivity and reduced IT infrastructure burdens for regional carriers.
The FAA enforces EFB operational authorization under AC 120-76, while EASA mandates software integrity standards through CS-25 certification pathways, collectively elevating barriers for uncertified entrants. The EU AI Act introduces emerging compliance dimensions for predictive flight analytics embedded within next-generation platforms. Stakeholders must weigh certification timelines against the accelerating pace of connectivity and autonomy integration in commercial aviation.
Market Dynamics
Full-service carriers face FAA mandates for paperless flight decks under NextGen modernization, forcing simultaneous fleet retrofit decisions across narrow-body and wide-body aircraft. This regulatory compression is synchronizing procurement cycles and concentrating vendor selection authority at airline headquarters.
Growth Catalysts
- FAA AC 120-76 Operational Authorization:The FAA's binding guidance for EFB use in all phases of flight is eliminating paper chart redundancy. Carriers must comply or face operational restrictions.
- Low-Earth Orbit Satellite Constellations:Real-time weather and NOTAM delivery via enhanced connectivity is reducing dispatch delays. Regional operators now access capabilities previously limited to major hubs.
- EU Green Deal Paper Elimination Targets:European environmental accountability frameworks are mandating digital documentation across aviation supply chains. Flag carriers face audit exposure for non-compliance.
Market Restraints
- DO-160G Certification Costs:Environmental testing for rapid decompression, temperature cycling, and electromagnetic interference requires six-figure investments per hardware variant. This limits supplier diversity.
- Avionics Integration Concentration:Three specialist firms control embedded cockpit computing architectures. Airlines face vendor lock-in for integrated EFB-flight management system bundles.
- Legacy Paper Workflow Inertia:Pilot unions and training departments maintain parallel paper backup systems during transition periods. This doubles documentation management overhead.
Strategic Opportunities
- India DGCA Digital Mandate Trajectory:India's aviation regulator is signaling paperless cockpit transitions for expanding domestic carriers. IndiGo and Air India Express retrofit programs represent immediate addressable demand.
- AI-Assisted Predictive Performance:Machine learning models for fuel optimization and runway condition assessment are converging with EFB platforms. Subscription analytics modules command premium pricing.
- Cloud-Native Charting Distribution:Browser-based chart rendering eliminates per-device licensing constraints. Low-cost carriers are piloting bring-your-own-device policies for flight crew.
Industry Challenges
- DO-178C Software Integrity Verification:Level C and D certification for flight-critical applications requires formal methods and extensive testing. Development timelines extend 18-24 months.
- Cybersecurity-Operations Integration:Airline IT departments must harden EFB endpoints against intrusion while maintaining crew usability. Security patch cycles conflict with operational continuity requirements.
- Multi-Fleet Configuration Management:Mixed aircraft types require distinct EFB software loads and mounting solutions. Technical operations teams struggle with version control across Boeing and Airbus platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Electronic Flight Bag Market |
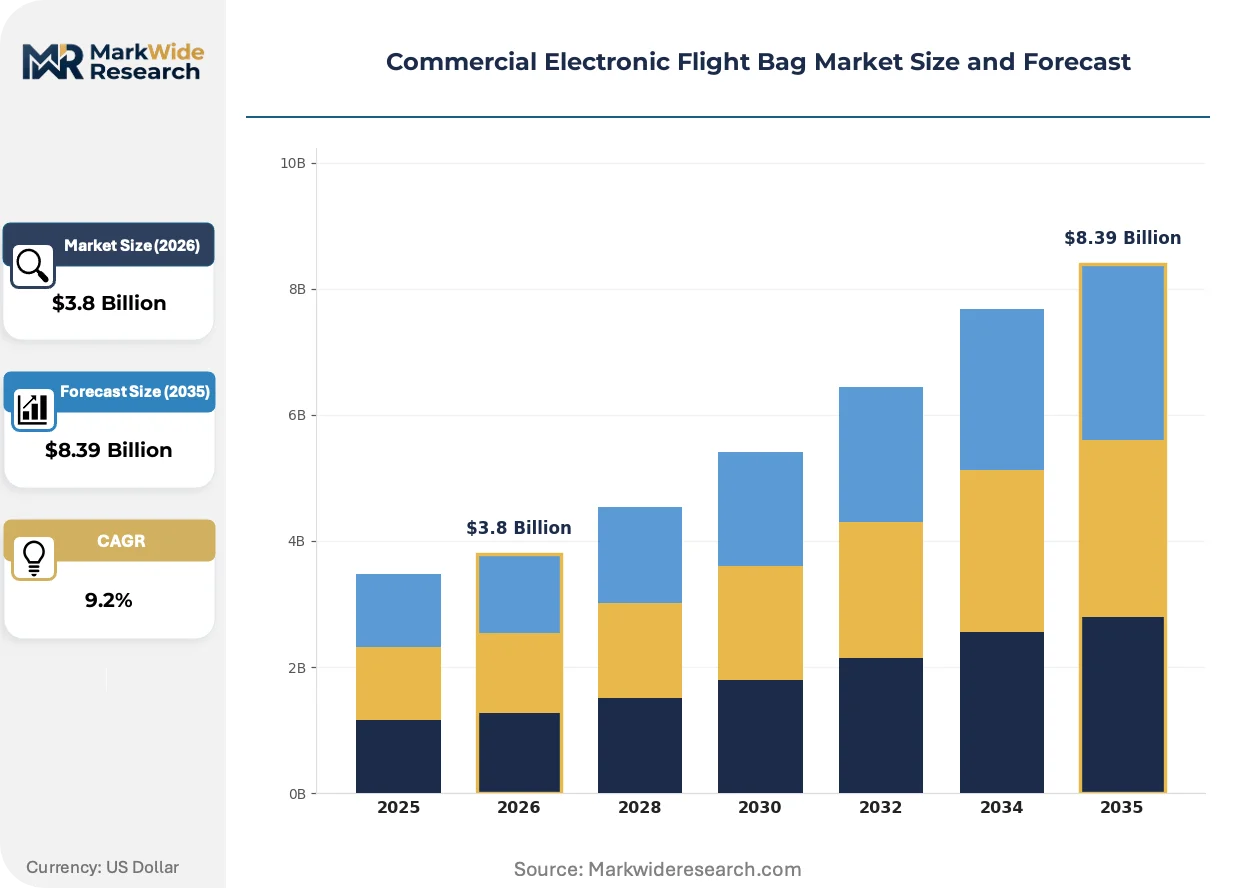
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hardware, Software, Accessories, Services End User: Airlines, Charter Operators, Cargo Carriers, Military Deployment: Cloud-Based, On-Premise, Hybrid, Mobile Functionality: Navigation, Communication, Flight Planning, Data Management |
| Companies Covered | Collins Aerospace, Honeywell International Inc., Thales Group, The Boeing Company, Teledyne Technologies Incorporated, Airbus, Lufthansa Systems, Rockwell Collins, DAC International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Electronic Flight Bag Market Strategic Shifts
Connectivity infrastructure and predictive analytics are converging within cockpit computing platforms, compressing the gap between ground-based dispatch optimization and real-time in-flight decision support. This convergence is redefining vendor capability requirements.
Machine learning algorithms for fuel burn prediction and contingency fuel optimization are automating performance calculations previously executed through manual lookup tables. Low-cost carriers in Southeast Asia are deploying these modules aggressively to offset volatile jet fuel exposure. The technology is automating dispatcher-pilot communication loops and reducing ground-based support headcount.
EASA's CS-25 certification pathway amendments for software-loaded equipment are tightening integrity requirements for EFB applications hosting aircraft performance data. Hardware manufacturers must now demonstrate fault containment for software failures affecting displayed information. European flag carriers are responding by consolidating vendor relationships to reduce certification surface area.
Airline technical procurement departments are unbundling hardware acquisition from software subscriptions, reversing prior bundled purchasing patterns. Maintenance divisions now negotiate charting and performance module contracts separately from device procurement. This bifurcation is most visible among US network carriers managing mixed fleets across multiple EFB hardware generations.
Commercial Electronic Flight Bag Market Segmentation
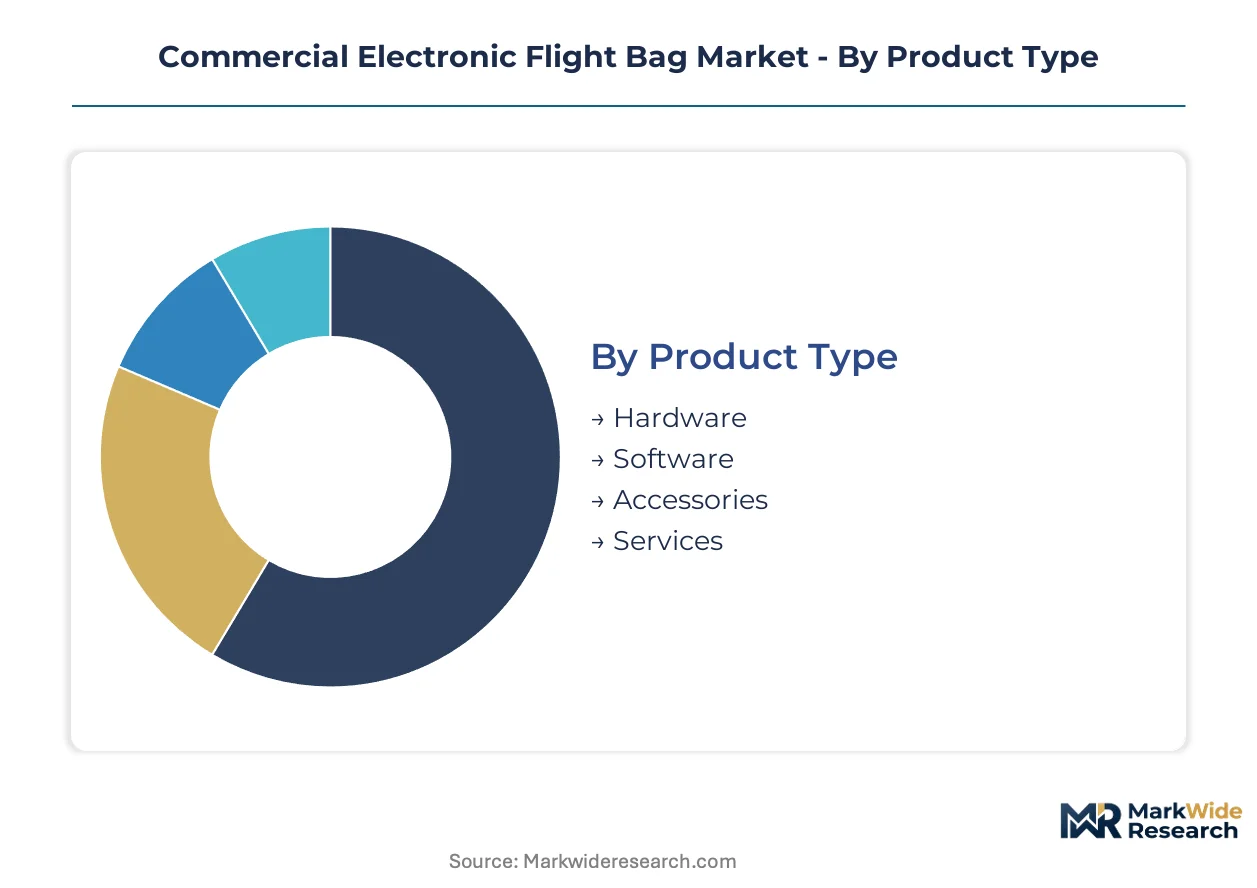
EFB procurement patterns diverge sharply across hardware-software splits and deployment architectures. Airlines unbundle purchasing decisions, separating device acquisition from subscription services. Technical operations teams manage multi-fleet configurations where each aircraft type demands distinct software loads and mounting solutions.
Product Type:
Hardware specifications anchor certification pathways, while software monetization models determine recurring revenue streams.
- Hardware:Class 2 portable and Class 3 installed computing systems must demonstrate DO-160G environmental resilience for rapid decompression and electromagnetic interference. United States major carriers concentrate procurement for narrow-body fleet retrofits under FAA NextGen mandates.
- Software:Subscription-based charting suites and performance calculation modules generate recurring revenue. European flag carriers prioritize cybersecurity-hardened platforms under EASA CS-25 software integrity amendments.
- Accessories:Mounting solutions, power adapters, and protective cases complete hardware ecosystems.
- Services:Implementation support, training programs, and ongoing technical assistance reduce airline IT burden.
Mature deployment sits with Hardware. Newer deployment is concentrated in Software.
End User:
Customer scale and operational complexity shape vendor engagement models and pricing structures.
- Airlines:Full-service and low-cost carriers drive volume procurement with centralized vendor selection authority. India DGCA digital mandate trajectories are accelerating paperless cockpit transitions for IndiGo and Air India Express retrofit programs.
- Charter Operators:Fractional ownership and business aviation fleets demand flexible, portable EFB configurations.
- Cargo Carriers:Integrated carriers require specialized performance modules for payload optimization on long-haul routes.
- Military:Defense applications demand enhanced security protocols and ruggedized hardware specifications.
Volume concentration rests with Airlines. Fastest expansion is emerging in Charter Operators.
Deployment:
Infrastructure location determines latency, connectivity dependency, and airline IT staffing requirements.
- Cloud-Based:Browser-based chart rendering eliminates per-device licensing constraints. Low-cost carriers in Southeast Asia pilot bring-your-own-device policies leveraging low-Earth orbit satellite connectivity for real-time weather delivery.
- On-Premise:Local server installations maintain operational continuity during connectivity outages. Legacy fleet operators retain this architecture for mixed-generation EFB hardware.
- Hybrid:Split architectures cache critical data locally while synchronizing updates via intermittent connectivity.
- Mobile:Tablet-native applications prioritize crew usability and rapid deployment cycles.
Legacy infrastructure persists in On-Premise. Steepest expansion trajectory belongs to Cloud-Based.
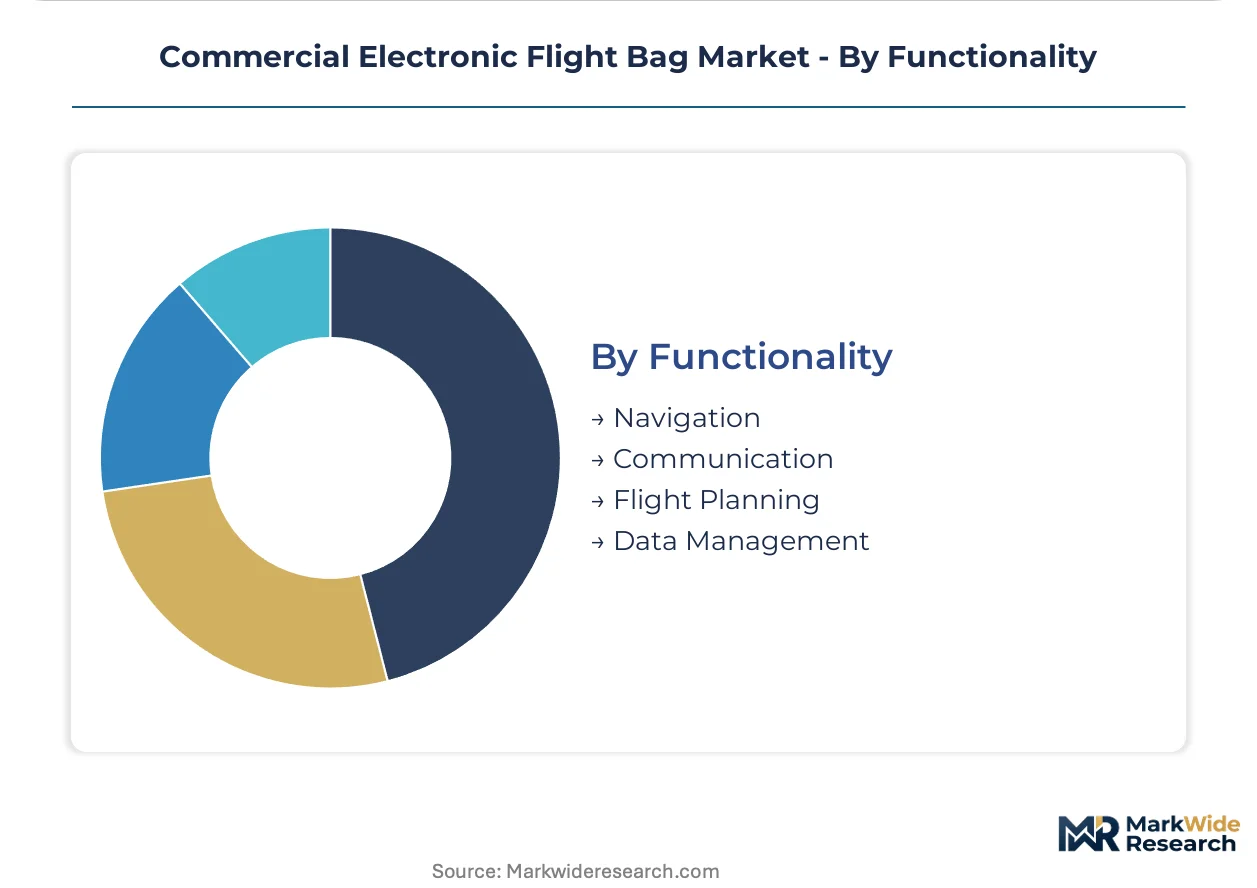
Functionality:
Core operational use cases define software module bundling and subscription tiering strategies.
- Navigation:Digital charting and moving map displays replace paper approach plates and enroute supplements. FAA AC 120-76 operational authorization mandates eliminate paper redundancy for United States operators.
- Communication:Integrated messaging and NOTAM delivery compress dispatcher-pilot coordination loops.
- Flight Planning:Performance calculation automation reduces manual lookup table dependency.
- Data Management:Electronic logbook and document distribution streamline technical records compliance.
Regulatory pressure centers on Navigation. AI-assisted enhancement is concentrating in Flight Planning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seattle anchors the commercial electronic flight bag ecosystem through Boeing's integrated avionics development corridors and adjacent supplier clusters. The concentration of airframe manufacturers and avionics specialists in the Pacific Northwest shapes procurement patterns and certification pathways for cockpit computing platforms.
United States
FAA AC 120-76 operational authorization mandates paperless flight deck transitions across major carrier fleets. The NextGen modernization program compresses retrofit timelines for narrow-body aircraft operating in domestic networks. Dallas-Fort Worth serves as the procurement decision hub where American Airlines and Southwest Airlines coordinate fleet-wide EFB standardization.
Germany
Lufthansa Group's technical operations division drives demand for cybersecurity-hardened EFB platforms across its multi-hub network. EASA CS-25 software integrity amendments tighten certification requirements for performance calculation modules. Hamburg concentrates avionics integration expertise through Lufthansa Technik's engineering centers and adjacent supplier facilities.
France
Airbus's Toulouse headquarters shapes integrated EFB-flight management system architectures for A320 and A350 families. The EU AI Act introduces emerging compliance dimensions for predictive analytics embedded in next-generation platforms. Paris-Charles de Gaulle anchors Air France's digital cockpit transformation program and vendor selection authority.
India
IndiGo and Air India Express retrofit programs represent immediate addressable demand under DGCA's signaled paperless cockpit trajectory. The country's expanding domestic carrier fleet requires scalable EFB deployment models for high-utilization operations. Bangalore concentrates software development capabilities supporting cloud-native charting distribution for regional operators.
United Kingdom
British Airways' technical procurement teams unbundle hardware acquisition from software subscriptions across mixed Boeing and Airbus fleets. The UK Civil Aviation Authority maintains alignment with EASA certification pathways post-Brexit. London Heathrow serves as the operational validation site for integrated EFB platforms serving transatlantic routes.
Commercial Electronic Flight Bag Market Competitive Environment
The competitive structure tilts toward avionics-integrated specialists with established FAA and EASA certification track records. Three specialist firms control embedded cockpit computing architectures, creating concentrated vendor relationships for hardware-software bundles. The market segments into integrated platform providers, software-only specialists, and airframe-embedded system divisions. Dominant competitive moves include strategic partnerships for connectivity integration and portfolio diversification into predictive analytics modules.
Among diversified aerospace conglomerates, Collins Aerospace and Honeywell International Inc. exemplify the integrated platform archetype through their avionics heritage and established airline relationships. Thales Group occupies a position within the cybersecurity-specialized tier, serving European flag carriers with hardened certification pathways. These three anchors represent the concentrated vendor base that airlines navigate for fleet-wide EFB procurement decisions.
| Leading Market Players |
|---|
| Collins Aerospace |
| Honeywell International Inc. |
| Thales Group |
| The Boeing Company |
| Teledyne Technologies Incorporated |
| Airbus |
| Lufthansa Systems |
| Rockwell Collins |
| DAC International |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal paper elimination targets gate qualified supply for EFB hardware-software bundles, restricting premium-tier pricing access to vendors with EASA CS-25 certification track records and DO-160G environmental testing capabilities. Airlines face vendor lock-in as certification barriers concentrate procurement authority at three specialist firms controlling embedded cockpit computing architectures.
Pricing Analysis
Value-based pricing anchors on operational uptime and fuel yield optimization delivered through AI-assisted predictive performance modules. Subscription-based SaaS tiering dominates software monetization, with cybersecurity-hardened platforms commanding premium positioning against standard charting suites. Price differentiation rests on DO-178C software integrity certification level and avionics integration depth. Cost compression in standard hardware tiers is intensifying because regional carriers pilot bring-your-own-device policies. Low-cost carriers exhibit highest price sensitivity; network carriers managing mixed fleets show lowest.
Supply Chain Analysis
Specialized aerospace electronics manufacturing clusters in the United States, Germany, and France face constrained avionics engineering workforce availability. Component sourcing draws from Taiwan for display panels, Japan for precision sensors, and domestic US suppliers for ruggedized computing enclosures. Single-source vulnerability concentrates in DO-160G-certified environmental testing facilities. Distribution runs through airline technical procurement headquarters with centralized vendor selection authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over DO-178C certification capabilities and satellite connectivity partnerships determines competitive durability. Players pursue downstream leverage through captive software subscription revenue streams.
For Market Incumbents: Deploy certification acceleration programs to outpace EASA CS-25 amendment timelines. Consolidate vendor relationships with European flag carriers to reduce certification surface area. Lock in long-term charting distribution agreements before cloud-native browser-based alternatives displace installed software loads. For New Entrants and Emerging Players: Enter via India DGCA-mandated retrofit programs for IndiGo and Air India Express narrow-body fleets. Target charter operator segments with flexible portable EFB configurations underserved by integrated platform specialists. Pursue white-label software partnerships with regional connectivity providers. For Investors and Strategic Acquirers: FAA AC 120-76 enforcement actions against non-compliant carriers is the leading indicator that regulatory compression will accelerate vendor consolidation. Long-term viability favors platforms with embedded flight management system integration and predictive analytics modules. Monitor EASA CS-25 software integrity amendment implementation as acquisition timing signal.| Strategic Initiative | Industry Significance |
|---|---|
| Cybersecurity Hardening Investment | EASA CS-25 amendments elevate integrity requirements for European flag carrier procurement. |
| Cloud-Native Platform Migration | Browser-based chart rendering eliminates per-device licensing constraints for low-cost carriers. |
| Satellite Connectivity Partnership | Low-Earth orbit constellations enable real-time weather delivery for regional operators. |
| AI Module Integration | Machine learning fuel optimization commands premium subscription pricing from network carriers. |
| Certification Portfolio Expansion | DO-178C Level C and D capabilities extend addressable market to flight-critical applications. |
Study Parameters
Independent corroboration across airline technical operations executives, avionics procurement managers, and EASA certification specialists underwrites the qualitative findings. Secondary validation draws from FAA AC 120-76 guidance documents, EASA CS-25 amendment filings, and airline fleet retrofit announcements. Bottom-up triangulation across hardware shipment patterns and software subscription disclosures converges with top-down market sizing.
Comparable-period anchoring to historical EFB deployment cycles across narrow-body and wide-body retrofit programs shapes the projection horizon. Segmentation modeling spans hardware class, deployment architecture, end-user scale, and functionality module. CAGRs derive from vendor revenue disclosures and airline procurement cycle synchronization. Forecast inputs incorporate NextGen modernization compliance deadlines and EU Green Deal audit exposure timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under delayed certification timelines or accelerated connectivity infrastructure buildouts. Assumptions reflect documented regulatory mandates and carrier fleet transition schedules. Material deviation in FAA enforcement intensity or LEO satellite constellation deployment warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Avionics
Electronic Flight Instrument System Market
Avionics
Europe Aircraft Avionics Market
Avionics
Military Avionic Systems Market
Avionics
Display for Avionics Application Market
Avionics
Europe Military Aircraft Communication Avionics Market
Avionics
Aircraft Computers Market
Avionics
Asia-Pacific Aircraft Health Monitoring System Market
Avionics
Europe Commercial Aircraft in-Flight Entertainment System Market
Avionics
Middle East Commercial Aircraft in-Flight Entertainment System Market
Avionics
Commercial Aircraft Avionics Systems Market
Avionics
North America Military Aircraft Communication Avionics Market
Avionics
Asia-Pacific Aircraft Avionics Market
Avionics
Temperature Sensor in the Aerospace & Defense Market
Avionics
Commercial Aircraft Electronic Flight Bag (EFB) Systems Market
Avionics
Asia-Pacific Semiconductor in Military and Aerospace Market
Avionics
Avionics LRU Repair and Test Services Market