
 Global Oncology Information System Market | 2026-2036
Global Oncology Information System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Oncology Information System Market Foresight
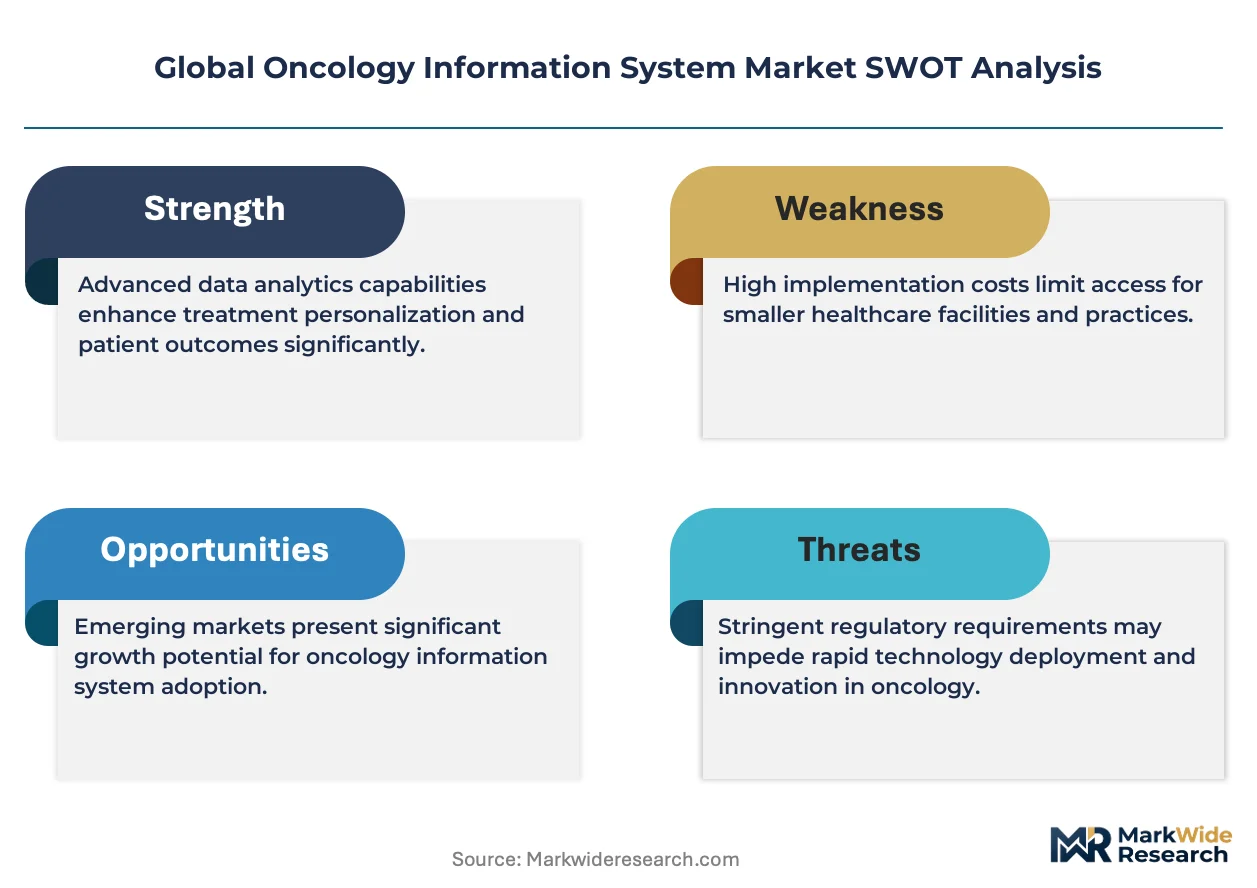
The EU AI Act is recalibrating how oncology software vendors classify clinical decision support modules across European deployments. Koninklijke Philips N.V. leverages its diagnostic imaging heritage to anchor integrated radiation oncology workflows. Siemens Healthineers sustains R&D intensity in digital twin applications for treatment planning. Epic Systems Corporation dominates hospital EHR installations in North America, positioning its oncology modules as default infrastructure for academic medical centers.
An oncology information system comprises software platforms that aggregate multimodal patient data—pathology reports, genomic sequencing results, imaging DICOM files, and radiation dose metrics—into unified records that coordinate multidisciplinary tumor boards and automate treatment protocol selection. Cloud-based deployments are capturing fastest growth as specialty clinics seek scalable infrastructure without capital-intensive server commitments, while on-premise installations retain preference among national cancer institutes with strict data sovereignty requirements. Patient data management applications lead current revenue pools, though clinical trial management modules are deepening margin profiles as pharmaceutical sponsors fund site-level system upgrades.
The FDA software-as-medical-device framework and HIPAA security rule jointly determine how vendors architect patient data flows and audit trails for US installations, while EMA's medical device regulation extends comparable conformity obligations across EU member states. Japan's PMDA digital therapeutics pathway introduces additional premarket validation layers for AI-embedded dosing algorithms. Stakeholders must monitor divergence between regional software qualification regimes when prioritizing platform localization investments.
Market Dynamics
Cloud-native architectures are compressing deployment cycles for oncology platforms while regulatory divergence between the FDA software-as-medical-device framework and EU AI Act forces vendors to maintain parallel compliance tracks.
Growth Catalysts
- Interoperability mandates:National tumor registries in Germany and Japan require standardized data exchange protocols, compelling hospital networks to upgrade legacy infrastructure.
- Proton therapy expansion:Specialized cancer centers in the United States are integrating dose-tracking modules with imaging archives to coordinate multi-modality treatment sequences.
- EMA Medical Device Regulation:The MDR's software classification criteria are accelerating vendor investment in clinical validation documentation for European deployments.
Market Restraints
- Data sovereignty requirements:National cancer institutes in France and South Korea mandate on-premise storage, blocking cloud-first vendors from public-sector contracts.
- Specialized technical labor:Health informaticists with dual competency in radiation physics and HL7 FHIR standards command premium compensation, inflating implementation costs.
- Legacy system entrenchment:Epic Systems Corporation's dominance in North American hospital EHR installations creates switching friction for competing oncology modules.
Strategic Opportunities
- Decentralized clinical trials:Pharmaceutical sponsors are funding site-level system upgrades to enable remote patient monitoring and electronic consent workflows.
- AI-embedded dosing algorithms:Japan's PMDA digital therapeutics pathway offers expedited review for validated decision-support tools in radiotherapy planning.
- Community oncology networks:Independent practices in Italy and Spain lack integrated platforms, presenting white-space entry for scalable cloud deployments.
Industry Challenges
- Multidisciplinary workflow integration:Pathology, radiology, and medical oncology departments operate disconnected data silos, complicating unified record construction.
- Cross-border data transfer compliance:GDPR adequacy determinations and HIPAA business associate agreements create legal friction for multinational health system deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Oncology Information System Market |
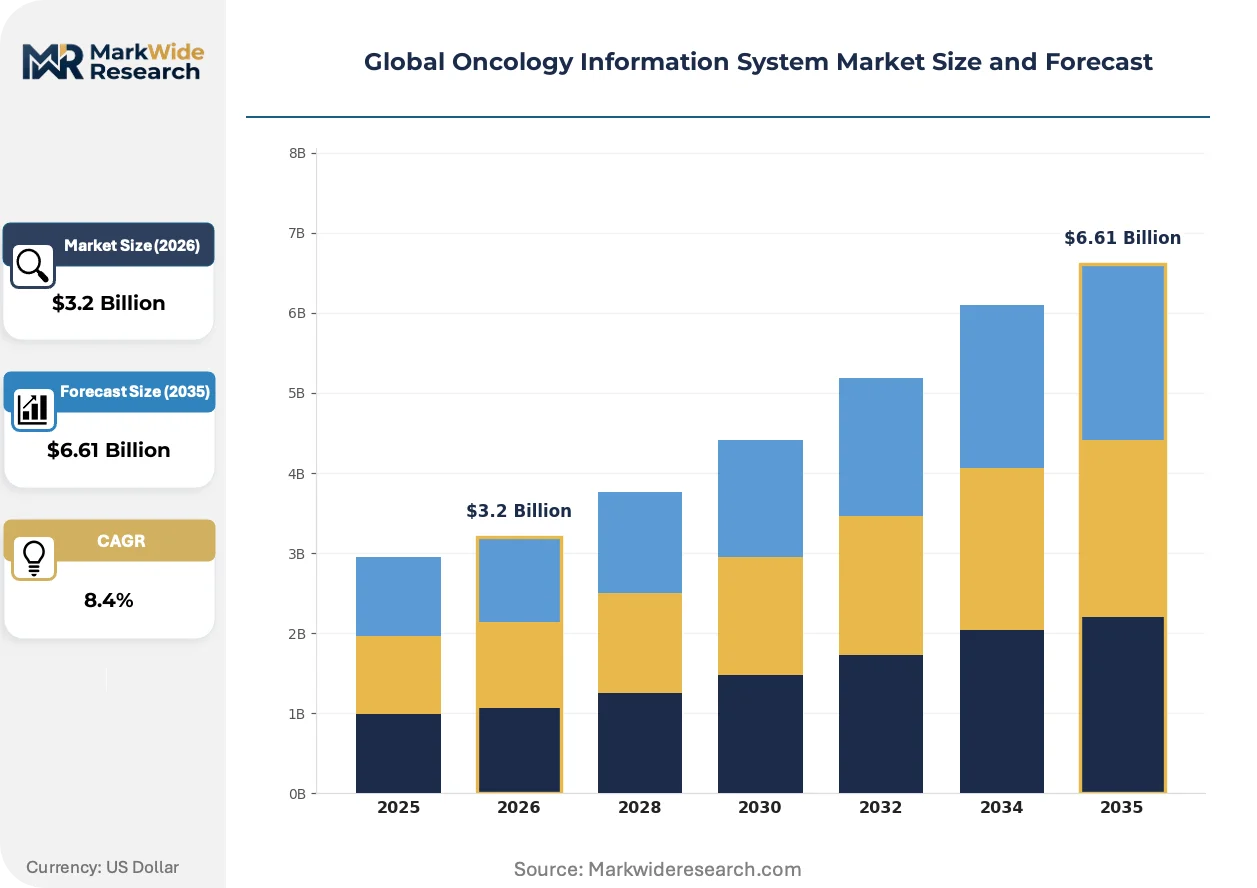
| Market Size in 2026 | $3.2 Billion |
| Market Size in 2035 | $6.61 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tumor Registry, Patient Management, Treatment Planning, Clinical Research, Billing Management Deployment: On-Premise, Cloud-Based, Web-Based, Mobile Application, Hybrid Systems End User: Specialty Clinics, Diagnostic Labs, Cancer Research Institutes, Radiation Centers, Pharmacies Application: Patient Data Management, Clinical Trial Management, Radiation Dosage Tracking, Outcome Analysis, Billing Automation |
| Companies Covered | Koninklijke Philips N.V., McKesson Corporation, Siemens Healthineers, Elekta AB, Epic Systems Corporation, Oracle Health, Accuray Incorporated, RaySearch Laboratories AB, GE Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Oncology Information System Market Shifts & Advancements
Generative AI and federated learning architectures are repositioning competitive advantage around data network effects rather than standalone software functionality.
Natural language processing engines are automating extraction of structured oncology data from unstructured pathology reports and clinician notes. Academic medical centers in the United States and Netherlands are deploying these tools to populate tumor registries without manual abstraction. This compression of data curation labor is automating the bottleneck that has historically delayed real-world evidence generation.
The EU AI Act's risk-based classification system is redefining compliance obligations for clinical decision support modules across European deployments. High-risk algorithmic tools now require conformity assessments and post-market monitoring protocols comparable to Class II medical devices. Vendors with existing MDR notified body relationships are accelerating certification timelines while new entrants face extended validation cycles.
Subscription-based pricing for cloud-native platforms is displacing perpetual license models in community oncology settings. Independent practices in Australia and Canada favor operational expenditure structures that align software costs with patient volume fluctuations. This consumption-pattern shift is compressing upfront revenue recognition while extending customer lifetime value through embedded analytics upsells.
Global Oncology Information System Market Segmentation
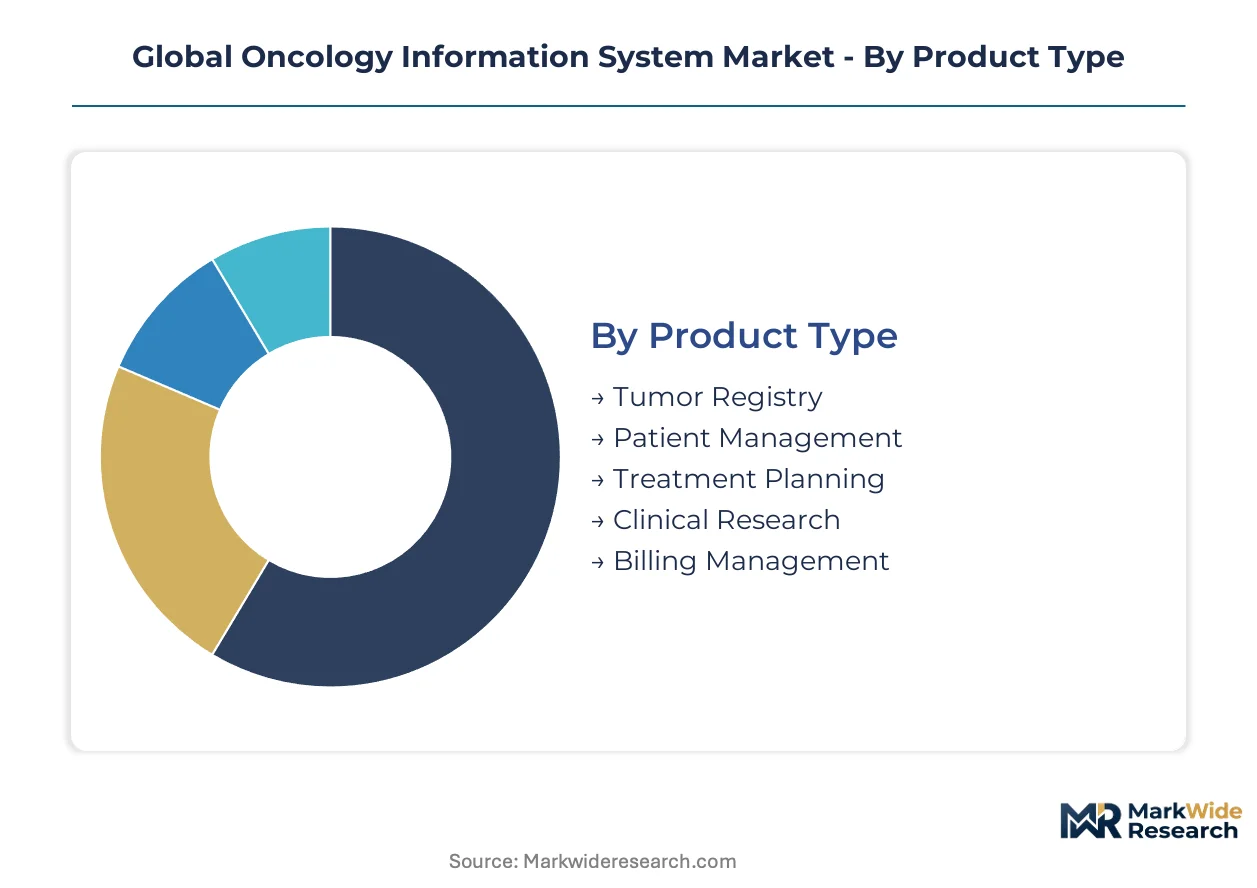
Oncology information systems fragment across four distinct axes that shape procurement decisions and vendor positioning. Product architecture determines integration complexity with existing hospital infrastructure. Deployment models reflect trade-offs between data sovereignty and operational agility.
Product Type:
Hospital procurement committees prioritize modules that demonstrate immediate workflow compression and measurable quality outcomes.
- Patient Management:Core platform aggregating multimodal patient records—pathology reports, genomic sequencing, imaging DICOM files—into unified dashboards for multidisciplinary tumor boards. Demand concentrates in academic medical centers across the United States and Germany where proton therapy networks mandate interoperable data infrastructure. The FDA software-as-medical-device framework and HIPAA security rule jointly determine how vendors architect patient data flows.
- Treatment Planning:Radiation dose calculation modules integrated with imaging archives to coordinate multi-modality treatment sequences. Cancer research institutes in Japan and the Netherlands are expanding adoption as national tumor registries require standardized data exchange protocols.
- Tumor Registry:Structured data repositories enabling population-level oncology research and quality benchmarking.
- Clinical Research:Protocol management and adverse event tracking tools for pharmaceutical-sponsored trials.
- Billing Management:Revenue cycle automation aligned with complex oncology reimbursement codes.
Volume sits with Patient Management; growth tilts toward Treatment Planning.
Deployment:
Capital availability and IT staffing density drive the deployment choice for cancer centers and specialty clinics.
- Cloud-Based:Scalable infrastructure delivered via subscription models, eliminating capital-intensive server commitments. Specialty clinics in Australia and Canada favor operational expenditure structures that align software costs with patient volume fluctuations. Cloud-native architectures are compressing deployment cycles while regulatory divergence between FDA software-as-medical-device pathways and EU AI Act forces vendors to maintain parallel compliance tracks.
- On-Premise:Local server installations retaining preference among national cancer institutes with strict data sovereignty requirements. France's CNIL and South Korea's MFDS mandate on-premise storage for public-sector contracts, blocking cloud-first vendors from these segments.
- Web-Based:Browser-accessible platforms requiring minimal local IT infrastructure.
- Hybrid Systems:Mixed architectures balancing sensitive data on-premise with analytics workloads in cloud environments.
- Mobile Application:Point-of-care access tools for clinician workflow mobility.
Revenue concentrates in Cloud-Based deployments; expansion accelerates fastest in Hybrid Systems.
End User:
Facility scale and reimbursement complexity determine module sophistication requirements across buyer categories.
- Cancer Research Institutes:Comprehensive platforms supporting translational research, clinical trial enrollment, and regulatory submission workflows. Germany's national tumor registry and Japan's proton therapy networks mandate interoperable data infrastructure, compelling these institutes to upgrade legacy systems. EMA's Medical Device Regulation accelerates vendor investment in clinical validation documentation for European deployments.
- Radiation Centers:Specialized dose-tracking and imaging coordination modules for external beam and proton therapy.
- Specialty Clinics:Focused platforms for community oncology practices with limited IT resources.
- Diagnostic Labs:Pathology integration and molecular diagnostics reporting tools.
- Pharmacies:Oncology drug inventory and hazardous medication management systems.
Investment intensity peaks at Cancer Research Institutes; addressable market broadens fastest among Specialty Clinics.
Application:
Workflow automation priority and evidence-generation requirements shape module adoption sequencing.
- Patient Data Management:Centralized aggregation of pathology, imaging, genomics, and radiation metrics into longitudinal records. Academic medical centers in the United States deploy natural language processing engines to automate extraction of structured oncology data from unstructured reports, compressing data curation labor. GDPR adequacy determinations and HIPAA business associate agreements create legal friction for multinational deployments.
- Clinical Trial Management:Protocol automation, electronic consent, and remote patient monitoring modules. Pharmaceutical sponsors are funding site-level system upgrades to enable decentralized trial workflows, deepening margin profiles for vendors with validated platforms.
- Radiation Dosage Tracking:Dose-volume histogram analysis and toxicity correlation tools.
- Outcome Analysis:Real-world evidence generation and survival analytics for quality improvement.
- Billing Automation:Prior authorization and claims management for high-cost oncology therapeutics.
Current revenue pools center on Patient Data Management; margin expansion concentrates in Clinical Trial Management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston anchors the highest concentration of proton therapy centers and academic medical centers deploying integrated oncology platforms in the United States. The city's Longwood Medical Area coordinates multidisciplinary tumor boards across Dana-Farber Cancer Institute, Massachusetts General Hospital, and Brigham and Women's Hospital. These institutions mandate interoperable data infrastructure connecting pathology, genomics, and radiation dose metrics.
United States
Academic medical centers in Houston and Seattle are expanding proton therapy networks that require unified patient data management systems. The FDA software-as-medical-device framework and HIPAA security rule jointly determine how vendors architect patient data flows and audit trails. MD Anderson Cancer Center in Texas coordinates multi-modality treatment sequences through integrated platforms linking imaging archives with dose-tracking modules.
Germany
National tumor registries mandate standardized data exchange protocols, compelling hospital networks in Munich and Heidelberg to upgrade legacy infrastructure. EMA's Medical Device Regulation accelerates vendor investment in clinical validation documentation for European deployments. The German Cancer Research Center in Heidelberg anchors interoperable data infrastructure connecting university hospitals across Baden-Württemberg and Bavaria.
Japan
Proton therapy networks in Chiba and Tsukuba require interoperable data infrastructure coordinating imaging, genomics, and radiation metrics. The PMDA digital therapeutics pathway introduces additional premarket validation layers for AI-embedded dosing algorithms. The National Cancer Center Hospital East in Chiba deploys integrated platforms supporting translational research and clinical trial enrollment workflows.
Netherlands
Academic medical centers in Amsterdam and Rotterdam deploy natural language processing engines to automate extraction of structured oncology data from unstructured pathology reports. GDPR adequacy determinations create legal frameworks for multinational health system deployments. The Netherlands Cancer Institute in Amsterdam anchors federated learning architectures repositioning competitive advantage around data network effects.
Australia
Specialty clinics in Sydney and Melbourne favor cloud-native platforms delivered via subscription models aligning software costs with patient volume fluctuations. The Therapeutic Goods Administration regulates software-as-medical-device classifications comparable to FDA pathways. Peter MacCallum Cancer Centre in Melbourne coordinates decentralized clinical trial workflows through validated platforms enabling remote patient monitoring.
Global Oncology Information System Market Competitive Landscape
Premium-margin players sit above commodity-margin players across clinical validation depth and MDR notified body relationships. The vendor base stratifies into three tiers: diversified health technology conglomerates with diagnostic imaging heritage, specialized radiation oncology software developers, and electronic health record incumbents with hospital installation dominance. Dominant competitive moves include M&A to acquire clinical validation documentation and strategic partnerships with proton therapy equipment manufacturers.
Within the diversified health technology tier, Koninklijke Philips N.V. and Siemens Healthineers exemplify players leveraging diagnostic imaging heritage to anchor integrated radiation oncology workflows. Epic Systems Corporation occupies a distinct position as an electronic health record incumbent with hospital installation dominance in North America. These three entities represent the primary archetypes shaping procurement dynamics across academic medical centers and national cancer institutes.
| Leading Market Players |
|---|
| Koninklijke Philips N.V. |
| McKesson Corporation |
| Siemens Healthineers |
| Elekta AB |
| Epic Systems Corporation |
| Oracle Health |
| Accuray Incorporated |
| RaySearch Laboratories AB |
| GE Healthcare |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up specialists in radiation oncology software are consolidating fragmented vendors across Germany and the United States, compressing margin variability through standardized subscription tiers while anchoring pricing power to clinical validation depth rather than feature breadth.
Pricing Analysis
Value-based pricing anchored to patient throughput metrics dominates cloud-native oncology platforms, with subscription tiers scaling by tumor board volume and imaging study frequency. Price differentiation separates FDA-validated decision-support modules from CE-marked baseline configurations, while customization for proton therapy workflows commands premium positioning. Pricing pressure stems from pharmaceutical sponsors funding site-level upgrades for decentralized trials, compressing direct-to-hospital margins. Community oncology practices in Australia and Canada exhibit highest price sensitivity, whereas national cancer institutes in France and Japan prioritize data sovereignty over cost optimization.
Supply Chain Analysis
Single-source vulnerability sits with specialized health informaticists commanding dual competency in radiation physics and HL7 FHIR standards, creating talent bottlenecks in Germany, Japan, and the United States. Software development draws from cloud infrastructure providers, medical imaging equipment manufacturers, and genomic data analytics specialists. Tariff exposure runs through cross-border data transfer compliance, where GDPR adequacy determinations and HIPAA business associate agreements create legal friction. Distribution runs through direct enterprise sales to academic medical centers and GPO-aggregated procurement for community networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The oncology information system market sits in a technology-transition phase, with generative AI and federated learning architectures displacing standalone workflow automation as the primary competitive anchor.
For Market Incumbents: Deploy M&A levers to acquire clinical validation documentation and MDR notified body relationships, accelerating EU AI Act conformity assessments before high-risk algorithmic classification requirements fully activate. Consolidate radiation oncology software specialists to deepen vertical integration into proton therapy planning workflows. Counter Epic Systems Corporation's EHR installation dominance through embedded analytics upsells that extend customer lifetime value beyond core platform licensing. For New Entrants and Emerging Players: Capture white-space opportunity in community oncology networks across Italy and Spain, where independent practices lack integrated platforms and favor consumption-based pricing aligned with patient volume fluctuations. Prioritize cloud-native deployments with minimal local IT infrastructure requirements. Enter through pharmaceutical sponsor-funded site-level upgrades for decentralized clinical trial enablement, leveraging validated remote patient monitoring modules as the beachhead. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized radiation oncology software developers with existing PMDA digital therapeutics pathway relationships in Japan, where AI-embedded dosing algorithms face expedited review timelines. Long-term viability hinges on data network effects rather than standalone functionality. Monitor divergence between FDA software-as-medical-device frameworks and EU AI Act risk classifications as the primary inflection signal for platform localization investment priorities.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Epic Systems Corporation leverages hospital EHR dominance to embed oncology modules as default infrastructure. |
| Regulatory Certification Pathway | EMA's MDR and EU AI Act high-risk classification requirements accelerate clinical validation documentation investment. |
| Strategic Partnership | Koninklijke Philips N.V. anchors integrated radiation oncology workflows through diagnostic imaging heritage. |
| Acquisition of Specialist Firm | Consolidation of radiation physics and HL7 FHIR dual-competency teams addresses specialized technical labor scarcity. |
| Geographic Expansion | Cloud-first vendors target Australia's subscription-favoring specialty clinics to bypass French and South Korean on-premise mandates. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, combined with primary interviews across hospital CIOs, radiation oncology department heads, biomedical informaticists, GPO contracts managers, and pharmaceutical clinical operations leads. FDA 510(k) submissions, EMA MDR technical documentation, PMDA digital therapeutics pathway filings, and hospital procurement databases provided validation layers. Bottom-up patient management module deployment counts and top-down healthcare IT expenditure estimates were triangulated to calibrate market sizing.
Data-stream reconciliation across product architecture, deployment model, end-user facility scale, and application workflow priority shaped the analytical framework over the projection horizon. CAGRs were derived from elasticity modeling of proton therapy network expansion rates and national tumor registry interoperability mandate compliance timelines. Segmentation dimensions included cloud-native versus on-premise infrastructure, academic medical center versus community clinic scale, and patient data management versus clinical trial management application focus.
The model holds under stable regulatory classification frameworks; deviation in EU AI Act enforcement intensity or FDA software-as-medical-device pathway scope expansion would shift vendor investment priorities and certification timelines. Forecasts reflect assumptions regarding pharmaceutical sponsor funding continuity for decentralized trial infrastructure and cloud infrastructure cost trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Information Systems
Global Medical Document Management Systems Market
Medical Information Systems
Urology EMR Software Market
Medical Information Systems
Ophthalmology EMR Software Market
Medical Information Systems
Global Medical Decision Support Systems for Sepsis Market
Medical Information Systems
Case Coder Market
Medical Information Systems
Artificial Intelligence in Medical Software Market
Medical Information Systems
Global Healthcare Information Systems Market
Medical Information Systems
Global Medical Terminology Software Market
Medical Information Systems
Medical Talent Management IT Market
Medical Information Systems
Donor Management Software Market
Medical Information Systems
Master Patient Index Software Market
Medical Information Systems
Medical Software Market
Medical Information Systems
US Healthcare ERP Market
Medical Information Systems
Global Clinical Documentation Improvement Market
Medical Information Systems
Global Clinical Information System Market
Medical Information Systems
Anesthesia Information Management Systems Market