
 Medical Alert Systems Market | 2026-2036
Medical Alert Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Alert Systems Market Outlook
Subscription-based leasing and asset-light monitoring models are tilting competitive dynamics toward recurring-revenue operators with lower upfront capital barriers. Philips Lifeline leverages its hospital-system partnerships to sustain institutional channel dominance. ADT anchors its position through professionally monitored security infrastructure that extends into health emergency response. Medical Guardian LLC differentiates via direct-to-consumer digital acquisition and self-install product lines.
Medical alert systems comprise wearable transmitters, base stations, and monitoring center infrastructure designed to detect emergencies and dispatch assistance through cellular, landline, or GPS-enabled communication protocols. These systems primarily serve aging individuals and people with chronic conditions who require rapid access to emergency responders without relying on telephone self-dialing capability. Wearable devices dominate hardware shipment volumes while smartphone applications represent the fastest-expanding category as software-native solutions displace dedicated hardware among tech-comfortable seniors. Monitoring services capture the largest recurring revenue share, though fall detection technology commands premium pricing tiers due to sensor complexity and liability reduction value.
FDA regulates these systems as Class II medical devices requiring 510(k) clearance for fall detection and emergency signaling functions, while FCC governs radio frequency emissions and cellular communication compliance. State-level Medicaid waiver programs and Medicare Advantage supplemental benefits increasingly reimburse monitored emergency response systems, directly expanding addressable demand. Stakeholders must track evolving CMS coverage determinations and state telehealth parity laws that could reclassify remote monitoring reimbursement eligibility.
Market Dynamics
Subscription-based recurring revenue models are compressing upfront hardware margins while shifting competitive advantage toward operators with monitoring infrastructure and customer lifetime value optimization capabilities.
Growth Catalysts
- Medicare Advantage supplemental benefits:CMS reimbursement expansion for monitored emergency response systems directly reduces out-of-pocket costs for aging subscribers across United States metropolitan clusters.
- Fall detection sensor miniaturization:Accelerometer and gyroscope integration into wrist-worn and pendant form factors enables automatic dispatch without user button activation.
- Japan's super-aged society density:Municipal governments in Tokyo, Osaka, and Fukuoka prefectures subsidize device procurement through long-term care insurance tier certification.
Market Restraints
- FCC Part 15 and Part 22 certification timelines:Radio frequency emissions testing for cellular-enabled wearables extends product launch cycles by 8-14 months.
- Lithium polymer battery supply concentration:Cell manufacturing concentrates in East Asian contract suppliers, exposing hardware assemblers to input cost volatility and logistics disruption.
- Smartphone substitution threat:Native iOS and Android emergency SOS features displace dedicated hardware among tech-literate seniors under age 75.
Strategic Opportunities
- Germany's Pflegeversicherung digitalization:Federal reimbursement code expansion for GPS-enabled mobile systems opens rural and active-senior segments previously excluded from stationary base-station coverage.
- AI-driven predictive health analytics:Integration of activity pattern recognition with fall detection creates preventive intervention revenue streams beyond emergency response.
- Direct-to-consumer telehealth bundling:Virtual primary care platforms in United States markets cross-sell monitoring hardware as membership perks, bypassing traditional durable medical equipment distribution.
Industry Challenges
- FDA 510(k) predicate device matching:Novel sensor algorithms require extensive clinical validation to establish substantial equivalence, compressing R&D efficiency for smaller manufacturers.
- Legacy POTS infrastructure decommissioning:Copper landline retirement by major United States carriers forces hardware redesign and subscriber migration to cellular architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Alert Systems Market |
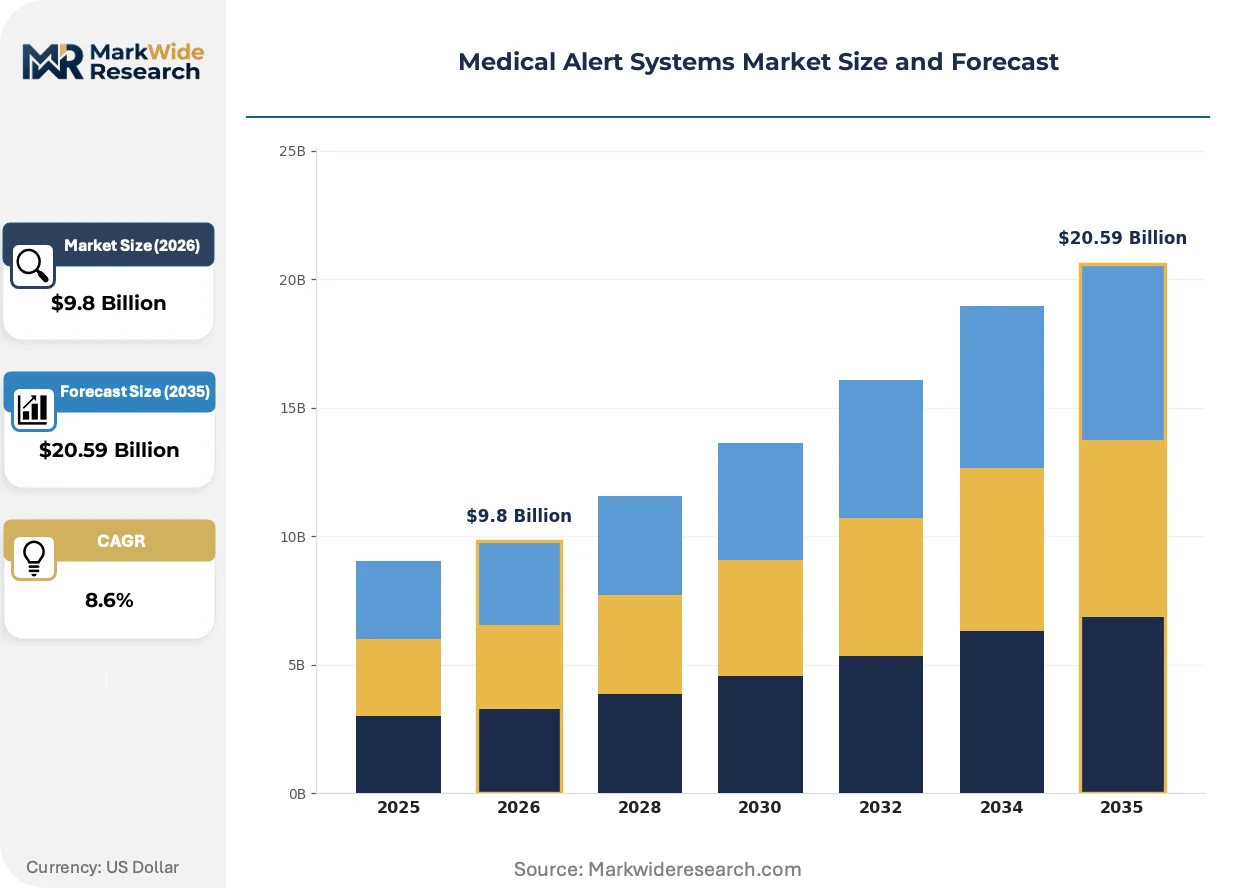
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $20.59 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Devices, Smartphone Applications, Landline Systems, Mobile Alert Systems End User: Seniors, Caregivers, Healthcare Facilities, Emergency Responders Technology: GPS Tracking, Cellular Connectivity, Bluetooth Technology, Fall Detection Service Type: Monitoring Services, Installation Services, Maintenance Services, Emergency Response Services |
| Companies Covered | Philips Lifeline, ADT, Bay Alarm Medical, Life Alert Emergency Response, Inc., Medical Guardian LLC, Connect America, MobileHelp, Tunstall Healthcare, LifeFone, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Alert Systems Market Strategic Shifts
Artificial intelligence inference at the edge is compressing response latency while enabling predictive capabilities that differentiate premium service tiers from basic emergency signaling.
Multi-sensor wearable architectures are hybridizing accelerometer, barometric pressure, and ambient light data streams to distinguish true falls from benign motion patterns. Assisted living operators in Florida and Arizona deploy these systems at scale to reduce liability exposure and staffing costs. The technology is hybridizing hardware and service margins into unified subscription pricing that obscures equipment depreciation.
Japan's PMDA revised guidance on software-as-a-medical-device clarifies classification pathways for AI-enabled fall prediction algorithms. Domestic manufacturers must submit clinical performance data demonstrating sensitivity and specificity thresholds. Wearable system exporters targeting Japanese geriatric care facilities face accelerated compliance documentation requirements.
Adult children are displacing seniors as primary purchase decision-makers through remote monitoring dashboards and subscription management portals. This proxy procurement pattern concentrates marketing spend on digital channels targeting caregivers aged 45-65 rather than traditional senior-focused media. United States markets exhibit the most pronounced divergence between device users and economic buyers.
Medical Alert Systems Market Segmentation
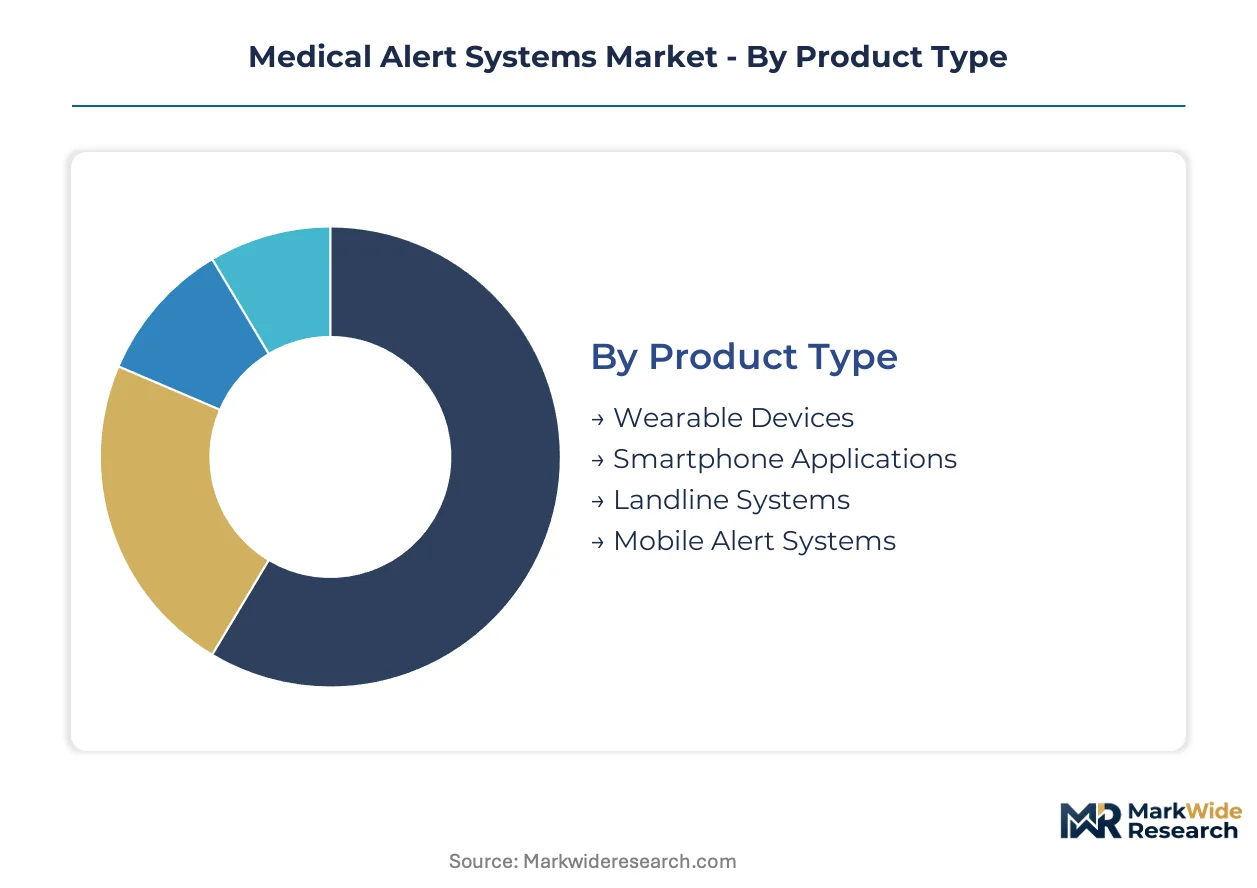
Medical alert systems fragment across hardware form factors, user archetypes, communication protocols, and service delivery models. Each dimension carries distinct margin profiles, regulatory burdens, and customer acquisition economics that shape vendor specialization.
Product Type:
The use-case spectrum spans stationary home-based protection through active-lifestyle mobile coverage, with hardware architecture directly determining addressable user scenarios and recurring revenue potential.
- Wearable Devices:Pendant and wrist-worn transmitters integrate accelerometer arrays and waterproof housings for continuous body-worn operation. Demand concentrates among seniors aged 75+ in United States suburban markets where POTS infrastructure decommissioning accelerates cellular migration. Fall detection premiums sustain 40-60% service tier markups over basic panic button offerings.
- Smartphone Applications:Native iOS and Android solutions leverage existing device ownership to eliminate hardware procurement barriers. Tech-comfortable seniors under 75 in Germany's urban centers drive fastest expansion as Pflegeversicherung reimbursement codes expand to cover software-native emergency response.
- Landline Systems:Stationary base stations with analog telephone connectivity serve rural subscribers lacking cellular coverage reliability.
- Mobile Alert Systems:GPS-enabled cellular units with two-way voice communication target active seniors requiring protection beyond home boundaries.
The dominant share belongs to Wearable Devices, while Smartphone Applications is closing the gap fastest.
End User:
Cost tier stratification separates institutional procurement with volume discounts from individual out-of-pocket purchases with premium service attachments.
- Seniors:Direct subscribers aged 65+ represent core demand with highest lifetime value and stickiest retention curves. Japan's super-aged prefectures subsidize acquisition through long-term care insurance tier certification, compressing payback periods for domestic distributors.
- Caregivers:Adult children aged 45-65 function as economic buyers through remote monitoring dashboards and subscription management portals. United States markets exhibit the most pronounced proxy procurement divergence between device users and purchase decision-makers.
- Healthcare Facilities:Skilled nursing and assisted living operators deploy at scale to reduce liability exposure and staffing costs.
- Emergency Responders:Municipal fire departments and EMS agencies integrate alert dispatch into coordinated response protocols.
Seniors command the installed base majority, though Caregivers is expanding most quickly as digital acquisition channels mature.
Technology:
Application intensity varies by mobility requirements, with outdoor-active segments demanding location precision that stationary home users bypass.
- GPS Tracking:Satellite positioning enables outdoor location determination for mobile alert units with 10-15 meter accuracy in open environments. Germany's rural senior segments previously excluded from stationary base-station coverage now qualify for Pflegeversicherung reimbursement under expanded GPS-enabled mobile system codes.
- Cellular Connectivity:4G LTE and emerging 5G modules replace retiring copper landline infrastructure across United States carrier networks. FCC Part 22 certification timelines extend product launch cycles by 8-14 months for hardware assemblers.
- Bluetooth Technology:Short-range wireless pairs wearables with smartphones or base stations for indoor proximity detection.
- Fall Detection:Multi-sensor algorithms combining accelerometer, gyroscope, and barometric pressure data trigger automatic dispatch without user activation.
Cellular Connectivity anchors current deployment volumes, while Fall Detection is gaining share fastest through liability reduction value propositions.
Service Type:
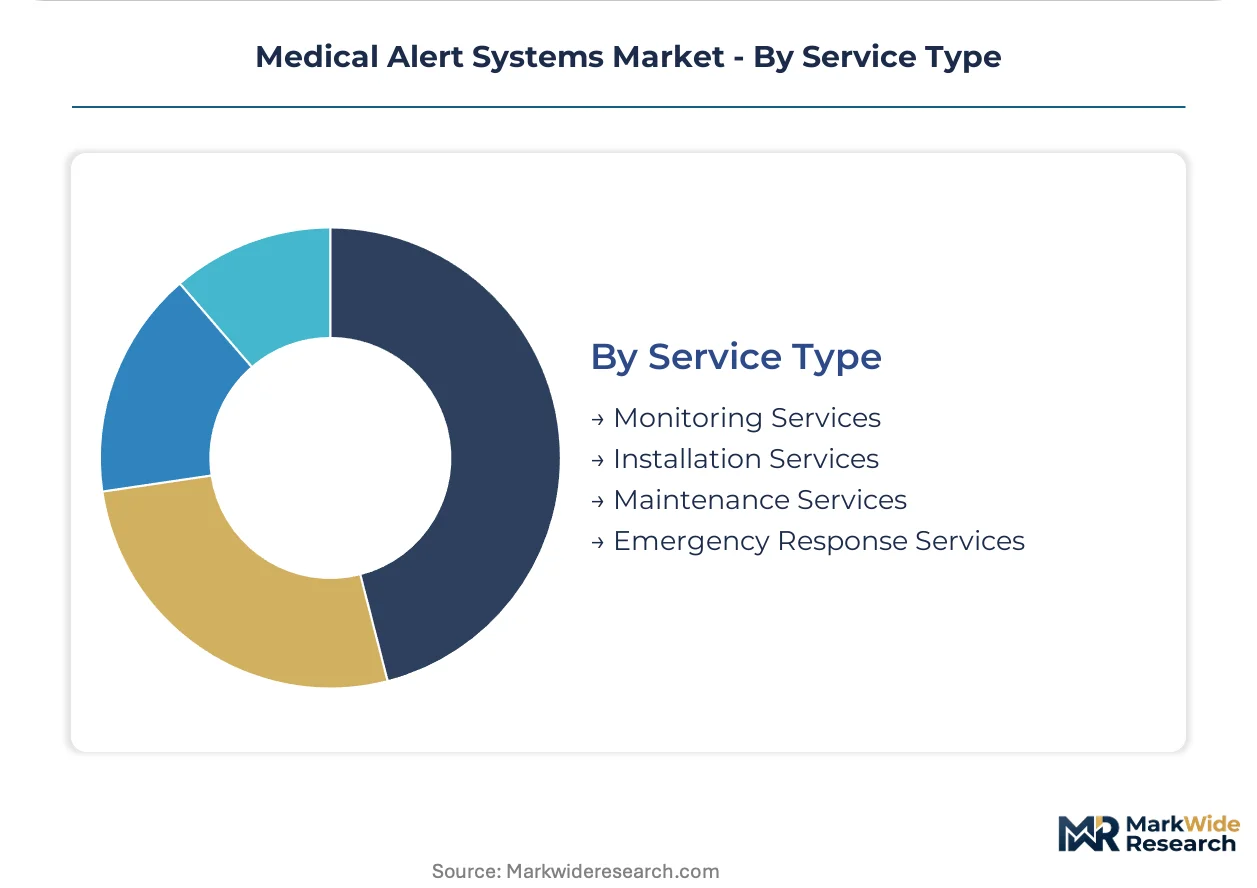
Margin concentration follows recurring revenue predictability, with monitoring subscriptions capturing disproportionate valuation multiples versus one-time installation or maintenance events.
- Monitoring Services:24/7 emergency response center operations with trained dispatchers command the largest recurring revenue share. United States Medicare Advantage supplemental benefits increasingly reimburse these services, directly expanding addressable demand across metropolitan clusters.
- Installation Services:Professional setup and system configuration generates one-time revenue with lower margin persistence.
- Maintenance Services:Battery replacement, firmware updates, and hardware troubleshooting sustain subscriber relationships between upgrade cycles.
- Emergency Response Services:Direct dispatch coordination with EMS, fire, and police departments represents the core value delivery layer.
Monitoring Services holds the revenue concentration lead, though Emergency Response Services is climbing the fastest as AI-driven predictive analytics create preventive intervention revenue streams.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Reimbursement frameworks and aging demographics concentrate demand across developed economies with established long-term care insurance programs. Municipal procurement subsidies and Medicare Advantage expansion accelerate device deployment in suburban and metropolitan clusters.
United States
Medicare Advantage supplemental benefits for monitored emergency response systems reduce subscriber out-of-pocket costs across metropolitan clusters. FDA Class II device clearance and FCC Part 15/22 certification govern product launch timelines. Suburban markets in Florida and Arizona exhibit concentrated assisted living operator deployment for liability reduction.
Germany
Pflegeversicherung digitalization expands reimbursement codes to GPS-enabled mobile systems previously excluded from stationary coverage. Federal long-term care insurance tier certification determines municipal subsidy eligibility. Rural senior segments in Bavaria and Baden-Württemberg now qualify for mobile alert procurement under revised federal guidelines.
Japan
Super-aged society density drives municipal procurement through long-term care insurance tier certification. PMDA revised guidance on software-as-a-medical-device clarifies AI-enabled fall prediction classification pathways. Tokyo, Osaka, and Fukuoka prefectures subsidize device acquisition for geriatric care facilities under accelerated compliance documentation requirements.
United Kingdom
Local authority adult social care budgets fund telecare service procurement for aging-in-place initiatives. NHS Digital integration standards shape monitoring center infrastructure requirements. Greater Manchester and West Midlands clusters concentrate assisted living operator deployment at scale.
Canada
Provincial health authority telecare programs reimburse monitored emergency response systems for rural senior populations. Health Canada medical device licensing governs fall detection algorithm validation requirements. Ontario and British Columbia health regions lead procurement volume for aging-in-place infrastructure.
Medical Alert Systems Market Competitive Environment
On the supply side, the industry is consolidating around recurring-revenue operators with captive monitoring infrastructure. Hospital-system partnerships and security-service extensions anchor institutional channel dominance. Three strategic archetypes define competitive positioning: medical-device incumbents with clinical validation capabilities, security-services extenders with professionally monitored infrastructure, and direct-to-consumer specialists with digital-native acquisition engines. Dominant competitive moves include strategic partnerships with telehealth platforms and portfolio diversification into predictive health analytics.
Within the institutional-channel tier, Philips Lifeline and ADT occupy positions anchored by hospital-system partnerships and professionally monitored security infrastructure respectively. Medical Guardian LLC exemplifies the direct-to-consumer archetype through digital acquisition and self-install product positioning. These three entities represent the strategic spectrum from clinical validation depth through security-service extension to consumer-native distribution.
| Leading Market Players |
|---|
| Philips Lifeline |
| ADT |
| Bay Alarm Medical |
| Life Alert Emergency Response, Inc. |
| Medical Guardian LLC |
| Connect America |
| MobileHelp |
| Tunstall Healthcare |
| LifeFone |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in cellular module assembly across East Asian contract manufacturers is compressing hardware margins while extending payment terms to 90-120 days for smaller monitoring service operators seeking component supply security.
Pricing Analysis
Certification level creates the primary spread across service tiers, with FDA 510(k)-cleared fall detection commanding premium positioning against basic panic-button offerings. Three-tier pricing structure across premium, standard, and economy levels segments by sensor sophistication and monitoring response speed. Cost compression in the economy tier is intensifying because smartphone-native emergency SOS features displace dedicated hardware among younger seniors. Adult children functioning as proxy purchasers exhibit lowest price sensitivity, while direct senior subscribers aged 75+ show highest responsiveness to out-of-pocket cost exposure.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from East Asian lithium polymer cell manufacturers are conditioning procurement relationships for hardware assemblers facing working capital constraints. Component sourcing concentrates in China, South Korea, and Taiwan for accelerometer arrays, cellular modules, and battery cells. Raw material dependencies span cobalt cathode chemistry, rare earth magnet materials for sensor calibration, and medical-grade silicone housings. Single-source vulnerability in advanced gyroscope MEMS fabrication creates qualification bottlenecks for fall detection algorithm validation. Distribution runs through durable medical equipment distributors, direct-to-consumer digital channels, and hospital-system group purchasing organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The medical alert systems market is entering a cyclical recovery phase as Medicare Advantage reimbursement expansion and Japan's municipal subsidy programs restore subscriber acquisition momentum following pandemic-era installation disruptions.
For Market Incumbents: Entrench monitoring infrastructure advantage through backward integration into AI-driven predictive analytics platforms that create switching costs beyond basic emergency response. Acquire direct-to-consumer digital acquisition capabilities to counter smartphone substitution threats among tech-comfortable seniors under 75. Secure FCC Part 22 certification pipelines early to compress product launch cycles against cellular migration deadlines.
For New Entrants and Emerging Players: Rural German senior segments excluded from stationary base-station coverage present immediate white-space opportunity under expanded Pflegeversicherung GPS-enabled mobile system reimbursement. Canada's provincial health authority telecare programs for rural populations offer institutional procurement entry with lower competitive density than United States Medicare Advantage channels. Pursue virtual primary care platform partnerships as cross-sell distribution, bypassing traditional durable medical equipment distributor relationships.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among operators with captive monitoring centers and customer lifetime value optimization capabilities rather than hardware-centric vendors. Long-term viability across the analysis window favors asset-light monitoring services with AI-enhanced fall prediction over pure hardware manufacturers facing smartphone displacement. Monitor CMS coverage determination shifts and state telehealth parity law evolution as primary inflection indicators for reimbursement expansion velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Accelerates market entry for fall detection algorithms in United States reimbursement channels. |
| Hospital System Partnership | Philips Lifeline leverages clinical relationships for institutional channel dominance against consumer competitors. |
| Software Companion Development | AI-driven predictive health analytics creates preventive intervention revenue beyond emergency response. |
| Reimbursement Strategy | Medicare Advantage supplemental benefit positioning directly reduces subscriber out-of-pocket cost barriers. |
| CE Marking Pathway | Unlocks Pflegeversicherung reimbursement expansion across Germany's rural and active-senior segments. |
Study Parameters
Desk research of FDA 510(k) clearance databases, FCC equipment authorization records, and CMS Medicare Advantage plan benefit filings preceded structured interviews with monitoring center operations directors, biomedical engineers at assisted living operators, GPO contracts managers, and telehealth platform product strategists. Secondary validation drew from hospital procurement databases, state Medicaid waiver program documentation, and long-term care insurance tier certification guidelines across Japan and Germany. Bottom-up subscriber volume estimates triangulated against top-down reimbursement expansion forecasts.
Assumptions held reimbursement code stability and cellular infrastructure migration timelines fixed while varying Medicare Advantage penetration rates and municipal subsidy program expansion across the projection horizon. Segmentation modeling spanned hardware form factor, user archetype, communication protocol, and service delivery model dimensions. CAGRs derived from subscriber acquisition curve analysis and average revenue per user trajectory modeling. Forecast inputs incorporated POTS decommissioning schedules and AI inference chip cost decline curves.
The forecast holds incumbent behavior within observed patterns; aggressive moves by smartphone-native emergency response platforms or unexpected FDA reclassification of software-as-a-medical-device would shift outcomes. Macroeconomic pressure on senior discretionary spending, regulatory restriction on lithium battery transport, or breakthroughs in ambient sensing technology would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Information Systems
OBGYN EHR Market
Medical Information Systems
AI in Medical Coding Market
Medical Information Systems
AI in Medical Billing Market
Medical Information Systems
ICD-10 Market
Medical Information Systems
Global Clinical Documentation Improvement Market
Medical Information Systems
Master Patient Index Software Market
Medical Information Systems
Case Coder Market
Medical Information Systems
Global Pharmacy Information System Market
Medical Information Systems
Global Laboratory Information Management System for Forensic Science Market
Medical Information Systems
Donor Management Software Market
Medical Information Systems
Electronic Medical Record Market
Medical Information Systems
Global Allergy EMR Software Market
Medical Information Systems
Medical Information Market
Medical Information Systems
Global Medical Document Management Systems Market
Medical Information Systems
Global Medical Scheduling Software Market
Medical Information Systems
Global Clinical Information System Market