
 Global Medical Document Management Systems Market | 2026-2036
Global Medical Document Management Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Global Medical Document Management Systems Market Foresight
Hospital end-user demand is pivoting toward cloud-native architectures as legacy on-premise installations strain IT budgets. Epic Systems Corporation leverages deep integration with clinical workflows to anchor its position in large academic medical centers. Cerner Corporation sustains competitiveness through broad ambulatory network penetration. Hyland Software specializes in content services platforms that bridge unstructured clinical documents with structured EHR data.
Medical document management systems comprise software platforms that capture, index, store, retrieve, and distribute clinical and administrative healthcare documents with audit trails, role-based access controls, and interoperability standards such as HL7 FHIR. These systems serve the primary commercial purpose of ensuring care continuity, regulatory compliance, and operational efficiency across fragmented healthcare delivery environments. Cloud-based systems represent the fastest-expanding product category as health systems seek elastic storage and reduced capital overhead, while on-premise deployments retain dominance in settings with strict data residency requirements. Among applications, electronic health records integration commands the deepest margin pools due to workflow embedding and switching costs.
The FDA enforces 21 CFR Part 11 requirements for electronic records and signatures, compelling vendors to validate audit trails and access controls. HIPAA mandates govern protected health information handling, shaping encryption and breach notification product features across US deployments. The EU AI Act and GDPR impose additional layers of algorithmic transparency and data governance for systems processing European patient records. Stakeholders must monitor how interoperability mandates from ONC and evolving FDA software-as-medical-device guidance reshape platform certification requirements and competitive moats.
Market Dynamics
Hospital IT departments are dismantling legacy on-premise archives under pressure from 21 CFR Part 11 audit mandates and elastic storage economics. Cloud-native document platforms are capturing budget allocations previously reserved for hardware refresh cycles.
Growth Catalysts
- FDA 21 CFR Part 11 Enforcement:Electronic records integrity requirements are compelling North American health systems to replace paper-based workflows with validated digital audit trails. Infrastructure upgrade budgets are expanding to meet compliance deadlines.
- HL7 FHIR Interoperability Mandates:The ONC's information blocking rules are accelerating API-first platform procurement. Vendors embedding FHIR R4 capabilities are securing preference in large integrated delivery network RFPs.
- Elastic Cloud Storage Economics:Health systems in Germany and the United Kingdom are migrating petabyte-scale imaging archives to consumption-based models. Capital expenditure relief is redirecting funds toward clinical analytics.
Market Restraints
- Data Residency Compliance Costs:GDPR Article 44 cross-border transfer restrictions are forcing redundant infrastructure deployments across EU member states. Operational complexity is inflating total cost of ownership for multi-national health systems.
- Legacy System Integration Friction:Proprietary EHR data formats from dominant US vendors create extraction bottlenecks. Custom interface development consumes 30-40% of implementation timelines.
- Cybersecurity Insurance Premium Surge:Ransomware targeting healthcare document repositories has hardened underwriter requirements. Premium increases are consuming IT budget elasticity.
Strategic Opportunities
- India's Ayushman Bharat Digital Mission:The national health stack is creating demand for document management platforms interoperable with ABHA identifiers. Domestic and international vendors are positioning for state-level tenders.
- AI-Assisted Clinical Documentation:Natural language processing convergence with structured data capture is opening premium pricing for ambient clinical intelligence. Academic medical centers are piloting voice-to-structure workflows.
- Subscription-Based Channel Expansion:Value-added resellers are displacing direct enterprise sales in mid-market ambulatory settings. Recurring revenue models are penetrating physician practice groups previously served by perpetual licenses.
Industry Challenges
- Health Informatics Talent Scarcity:Implementation of cloud-native architectures requires certified FHIR integration specialists. Health systems are competing with technology vendors for scarce clinical informaticists.
- Multi-Jurisdiction Certification Timelines:Simultaneous FDA software-as-medical-device qualification and EU MDR technical documentation preparation extends product launch windows. Regulatory affairs teams are constraining release velocity.
- Interoperability Testing Burden:Certification with multiple EHR platforms requires repeated validation cycles. Quality assurance resources are bottlenecked at vendor integration labs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Medical Document Management Systems Market |
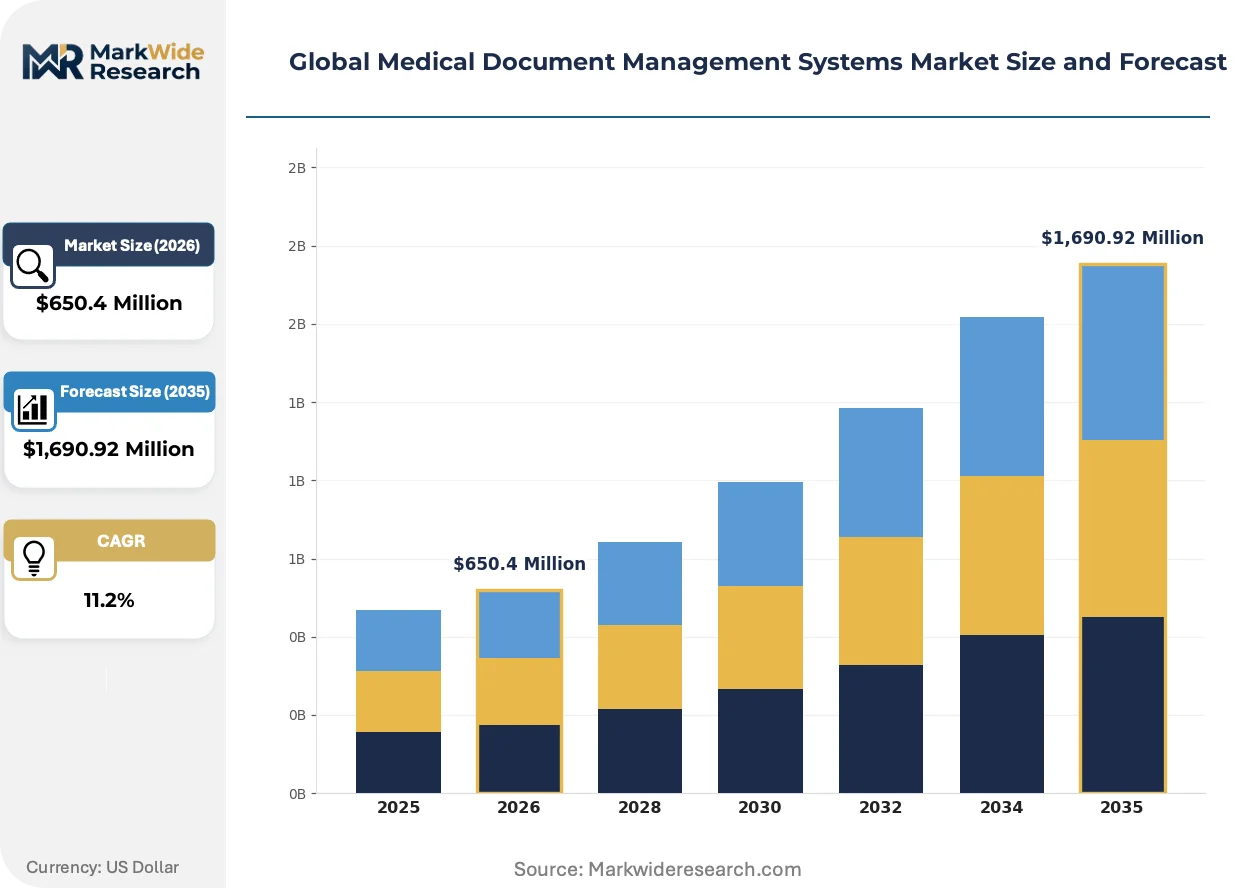
| Market Size in 2026 | $650.4 Million |
| Market Size in 2035 | $1,690.92 Million |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-Based Systems, On-Premise Systems, Hybrid Systems, Web-Based Platforms Application: Electronic Health Records, Billing & Coding, Regulatory Compliance, Patient Intake Management End User: Hospitals, Ambulatory Care Centers, Diagnostic Laboratories, Specialty Clinics Deployment: Public Cloud, Private Cloud, Hosted Services, Managed Services |
| Companies Covered | McKesson Corporation, 3M, Siemens Healthineers, GE Healthcare, Epic Systems Corporation, Cerner Corporation, Allscripts Healthcare Solutions, athenahealth, Hyland Software, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Medical Document Management Systems Market Shifts & Advancements
Artificial intelligence is compressing document classification timelines while regulatory pressure is hardening data governance requirements. Procurement patterns are rotating toward consumption-based commercial models.
Intelligent document processing platforms are unifying optical character recognition with clinical natural language understanding. Large academic medical centers in the United States are deploying these systems for automated pathology report indexing. The technology is unifying previously siloed unstructured content into queryable data lakes accessible to research informatics teams.
The EU AI Act's risk classification framework is imposing conformity assessment obligations on diagnostic document management systems. Vendors processing European patient records must now maintain algorithmic transparency documentation and human oversight protocols. High-risk system categories are triggering notified body involvement previously reserved for medical devices.
Ambulatory surgery centers are consolidating vendor relationships through platform consolidation. Single-source contracting for document management, practice management, and revenue cycle functions is displacing best-of-breed procurement. This concentration is most visible in United States metropolitan markets where private equity-backed rollups are standardizing IT infrastructure across facility portfolios.
Global Medical Document Management Systems Market Segmentation
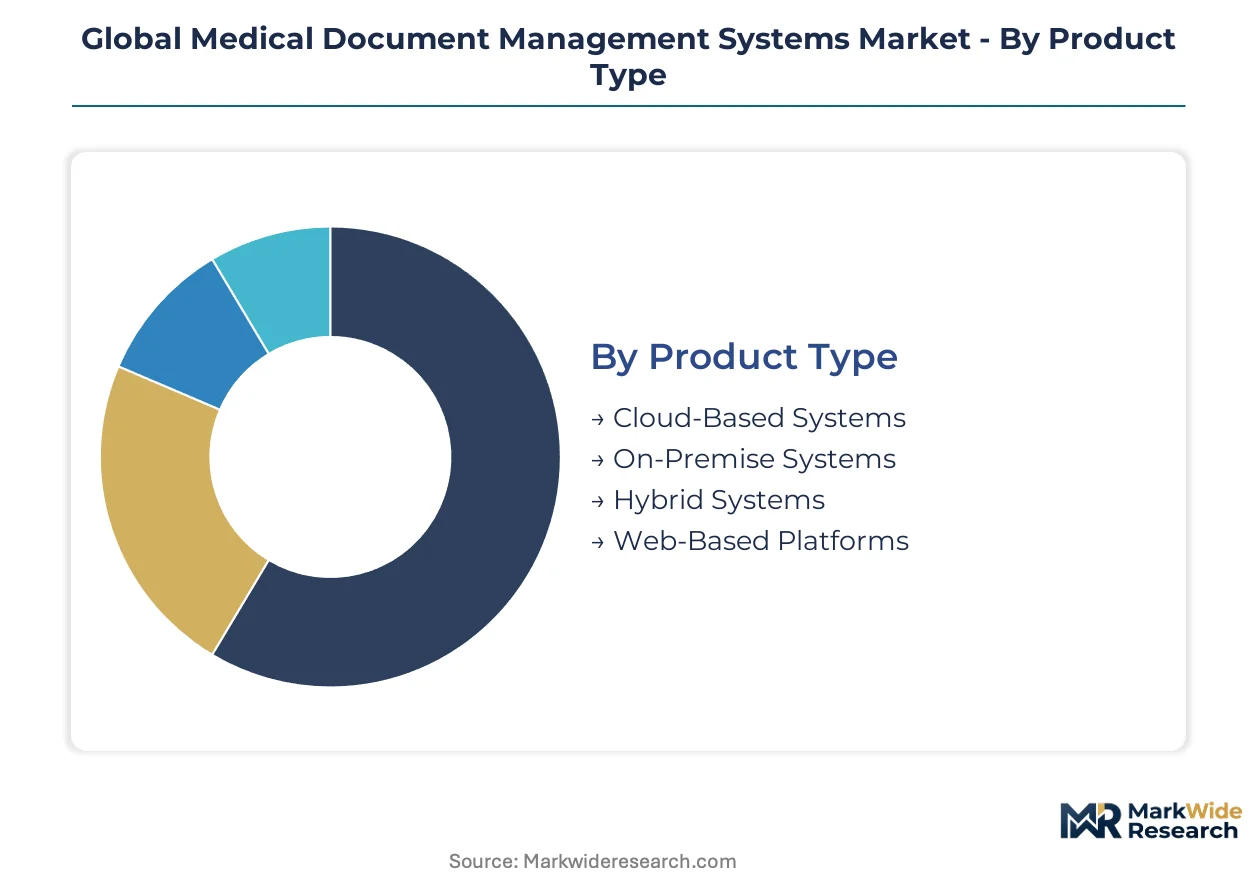
Medical document management systems fragment across four critical dimensions that determine procurement priorities and vendor selection criteria. Product architecture dictates capital expenditure profiles, while application focus shapes workflow integration depth. End-user scale influences customization requirements, and deployment models determine data governance responsibilities.
Product Type:
Buyers in this category differentiate primarily by infrastructure ownership preferences and total cost of ownership tolerance over a five-year horizon.
- Cloud-Based Systems:Multi-tenant architectures deliver elastic storage scaling through consumption-based pricing. German hospital networks and United Kingdom NHS trusts are migrating imaging archives to these platforms to redirect capital toward clinical analytics.
- On-Premise Systems:Dedicated hardware installations within facility data centers maintain complete data sovereignty. Academic medical centers in the United States with strict 21 CFR Part 11 validation requirements favor this architecture for audit trail control.
- Hybrid Systems:Split workloads between local processing and cloud archival balance latency-sensitive operations with long-term storage economics.
- Web-Based Platforms:Browser-native interfaces eliminate client-side installation burdens for distributed ambulatory networks.
On-Premise Systems lead volumes today; Cloud-Based Systems are gaining share fastest.
Application:
Commercial significance in this category tracks directly to switching costs and workflow embedding depth.
- Electronic Health Records:Native integration with clinical documentation workflows creates the highest customer lifetime values. Epic Systems and Cerner deployments in large United States integrated delivery networks anchor demand concentration here.
- Regulatory Compliance:Automated audit trail generation and FDA 21 CFR Part 11 validation documentation address the most acute compliance pain points. Infrastructure upgrade budgets are expanding across North American health systems to meet enforcement deadlines.
- Billing & Coding:Revenue cycle integration accelerates claims processing through automated document indexing.
- Patient Intake Management:Digital registration and consent form capture reduce front-desk administrative burden.
Electronic Health Records integration commands the deepest margin pools; Regulatory Compliance applications are expanding most quickly.
End User:
Scale of operations determines implementation complexity and support service requirements.
- Hospitals:Enterprise-grade platforms serving multi-facility networks require extensive customization and 24/7 support. Large academic medical centers in the United States drive premium pricing through advanced workflow requirements.
- Ambulatory Care Centers:Mid-market outpatient facilities prioritize rapid deployment and minimal IT staffing overhead. Private equity-backed rollups in United States metropolitan markets are standardizing infrastructure across facility portfolios.
- Diagnostic Laboratories:High-volume imaging and pathology report processing demands specialized indexing capabilities.
- Specialty Clinics:Niche workflows in cardiology, oncology, and orthopedics require condition-specific template libraries.
Hospitals dominate current procurement volumes; Ambulatory Care Centers show the steepest expansion trajectory.
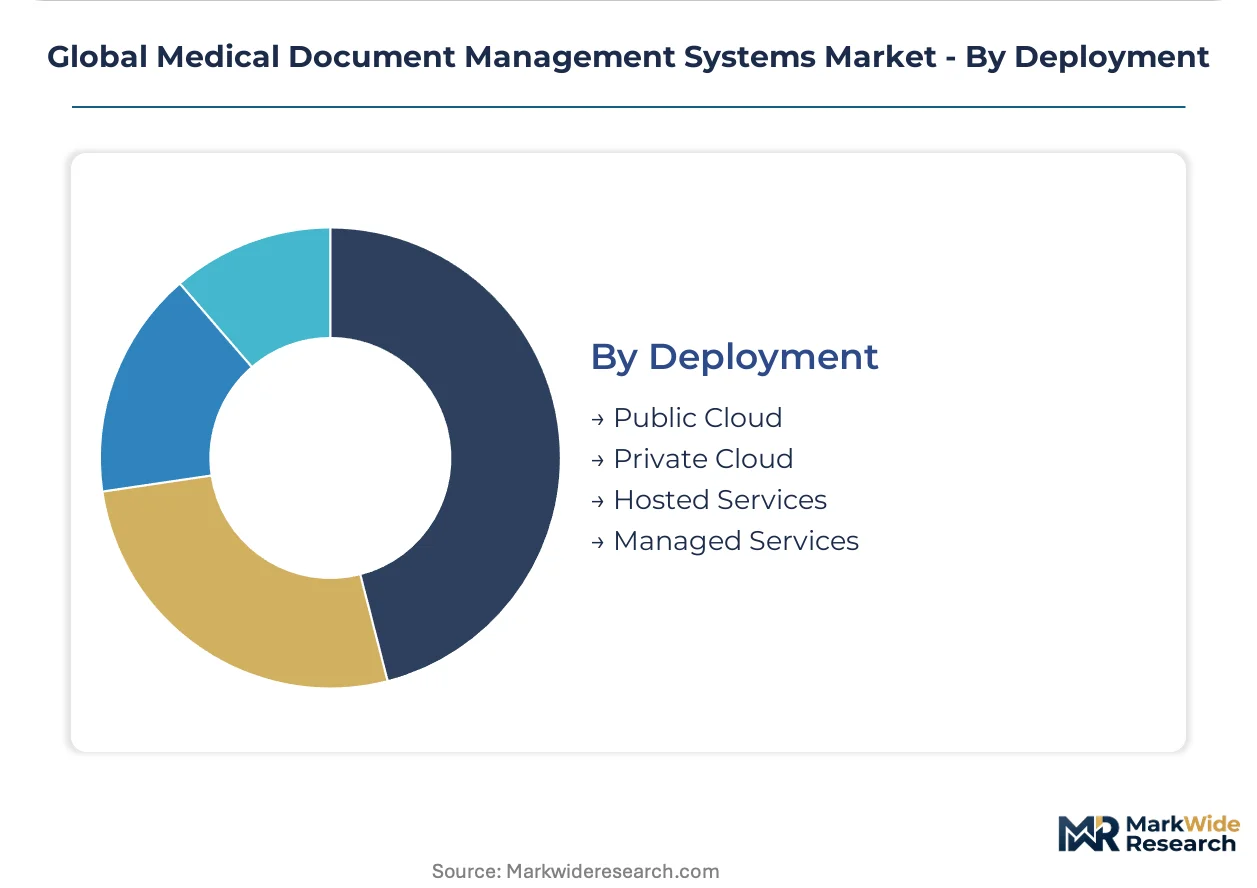
Deployment:
Data residency obligations and security postures separate buyers into distinct risk tolerance tiers.
- Private Cloud:Single-tenant virtualized environments dedicated to individual health systems balance cloud economics with isolation requirements. GDPR Article 44 cross-border transfer restrictions are forcing redundant deployments across EU member states.
- Managed Services:Vendor-operated infrastructure with outsourced security operations reduces internal IT burden. Ransomware targeting healthcare repositories has hardened underwriter requirements, making managed security attractive.
- Public Cloud:Shared infrastructure from hyperscale providers delivers lowest unit storage costs.
- Hosted Services:Single-tenant physical or virtual servers in third-party data centers provide middle-ground control.
Private Cloud deployments lead committed volumes today; Managed Services are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital networks in the United States drive procurement volumes for medical document management systems. Epic Systems and Cerner deployments anchor demand concentration across large integrated delivery networks. Regulatory enforcement from the FDA and ONC shapes infrastructure upgrade cycles.
United States
Academic medical centers in Boston and the Research Triangle demand advanced workflow integration with clinical documentation systems. The FDA enforces 21 CFR Part 11 requirements for electronic records integrity across North American health systems. Large integrated delivery networks in California and Texas are replacing legacy on-premise archives with cloud-native platforms.
Germany
Hospital networks in Bavaria and North Rhine-Westphalia are migrating petabyte-scale imaging archives to consumption-based storage models. GDPR Article 44 cross-border transfer restrictions force redundant infrastructure deployments across EU member states. The KBA and federal health regulators validate audit trail controls for multi-facility networks.
United Kingdom
NHS trusts in London and Greater Manchester prioritize elastic cloud economics to redirect capital toward clinical analytics. The country's national health regulator mandates interoperability standards for patient record platforms. Regional hospital networks are consolidating vendor relationships through single-source contracting.
India
The Ayushman Bharat Digital Mission creates demand for document management platforms interoperable with ABHA identifiers. State-level tenders in Maharashtra and Karnataka attract domestic and international vendors. The CDSCO and national health authority shape platform certification requirements for public hospital deployments.
Japan
Metropolitan hospital networks in Tokyo and Osaka require 24/7 support for enterprise-grade platforms with extensive customization. METI guidelines influence data governance frameworks for cloud-based patient record systems. Academic medical centers are piloting voice-to-structure workflows for ambient clinical intelligence.
Global Medical Document Management Systems Market Competitive Landscape
Strategic partnerships dominate the current landscape as vendors embed FHIR R4 capabilities into clinical workflows. The vendor base concentrates around three tiers: enterprise EHR-integrated platforms, specialized content services providers, and cloud-native ambulatory solutions. Two strategic archetypes anchor competitive positioning: workflow-embedded incumbents with deep switching costs, and API-first challengers capturing mid-market share. M&A activity and technology licensing agreements represent the dominant competitive moves reshaping market structure.
Within the enterprise EHR-integrated tier, Epic Systems Corporation and Cerner Corporation exemplify workflow-embedded positioning with large United States health system penetration. Hyland Software occupies a position bridging unstructured clinical documents with structured EHR data. These three anchors represent distinct competitive vectors: native clinical integration, broad ambulatory network coverage, and content services specialization.
| Leading Market Players |
|---|
| McKesson Corporation |
| 3M |
| Siemens Healthineers |
| GE Healthcare |
| Epic Systems Corporation |
| Cerner Corporation |
| Allscripts Healthcare Solutions |
| athenahealth |
| Hyland Software |
| Others |
Supply & Pricing Matrix
Cloud storage commodity indices cascading through hyperscale provider contracts reshape procurement economics for health system IT departments. Elastic consumption models compress capital expenditure cycles while amplifying price sensitivity across mid-market ambulatory networks.
Pricing Analysis
Input-cost pass-through from hyperscale infrastructure providers concentrates pricing pressure on SaaS-tiered subscription models. Three-tier pricing structure across premium, standard, and economy levels segments by FHIR certification depth and audit trail validation rigor. Price differentiation hinges on FDA 21 CFR Part 11 compliance tier and geographic data residency guarantees. Ambulatory surgery centers exhibit acute price sensitivity; academic medical centers absorb premium tiers for workflow embedding depth.
Supply Chain Analysis
India's PLI scheme for electronics manufacturing and data center infrastructure is reshaping vendor sourcing strategies for Asia-Pacific deployments. Software development concentrates in the United States, India, and Germany; cloud infrastructure rests on hyperscale facilities in Ireland, Singapore, and Virginia. Raw material dependencies span silicon for server hardware, lithium for backup power systems, and rare earth elements for storage media. Single-source vulnerability concentrates in FHIR integration engine licensing. Distribution runs through value-added resellers displacing direct enterprise sales in mid-market segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards geographic arbitrage between GDPR-constrained European deployments and elastic cloud economics in United States and Indian health systems. Regulatory compliance cost differentials exceed infrastructure savings by meaningful margins.
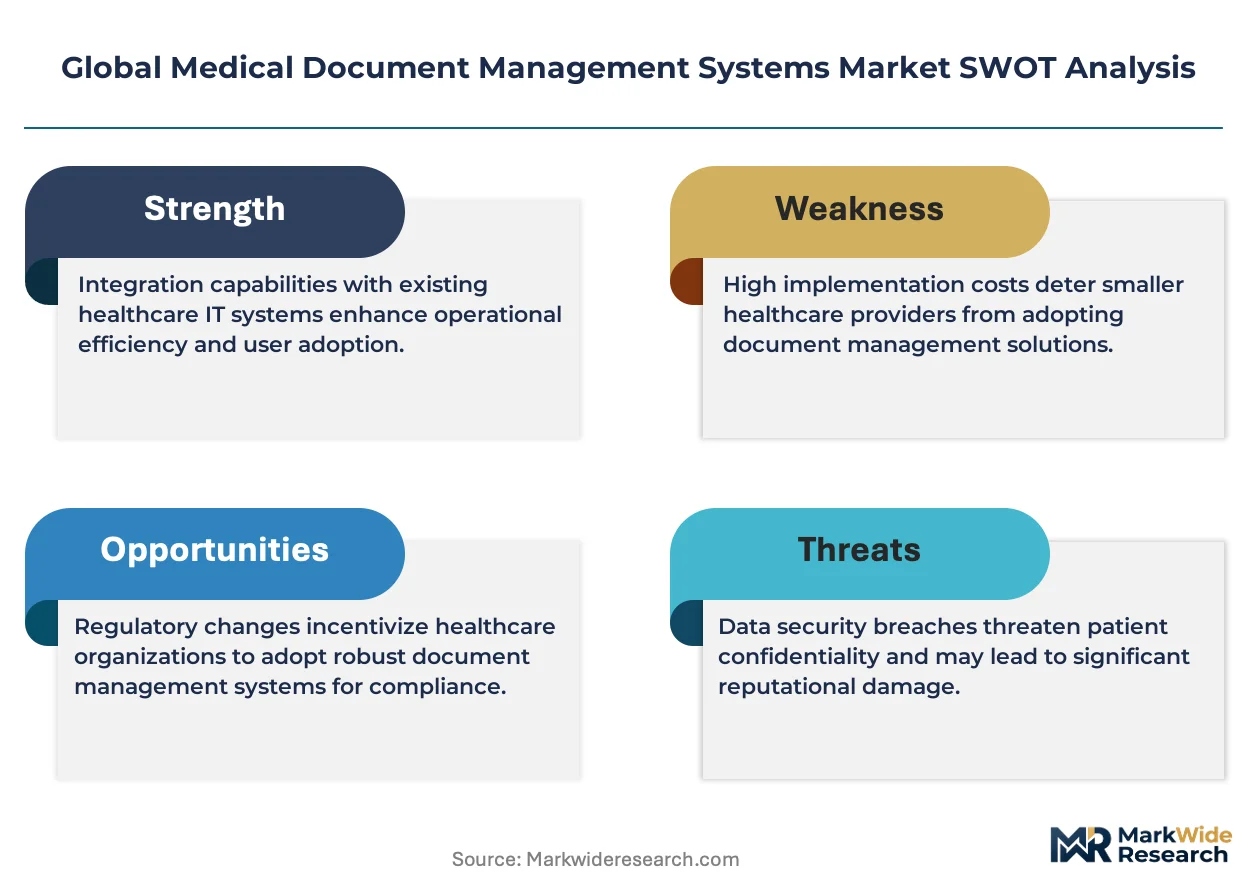
For Market Incumbents: Cement switching costs through deeper FHIR R4 workflow embedding in large integrated delivery networks. Fortify API-first platform architectures against cloud-native challengers penetrating mid-market ambulatory settings. Invest in EU MDR technical documentation capabilities to compress multi-jurisdiction certification timelines constraining release velocity. For New Entrants and Emerging Players: Begin with India's Ayushman Bharat Digital Mission state-level tenders where incumbent presence remains thin. Target private equity-backed ambulatory rollups in United States metropolitan markets standardizing infrastructure across facility portfolios. Lead with consumption-based pricing models displacing perpetual licenses in physician practice groups. For Investors and Strategic Acquirers: Consolidation pressure builds where FHIR integration specialist talent scarcity intersects with cloud-native architecture mandates. Long-term viability favors platforms with validated FDA audit trail controls and EU AI Act conformity documentation. Watch for ransomware insurance premium spikes as inflection indicators forcing managed security service adoption.| Strategic Initiative | Industry Significance |
|---|---|
| FHIR R4 Platform Integration | ONC information blocking rules accelerate API-first procurement in large United States health systems. |
| EU AI Act Conformity Pathway | Notified body involvement for high-risk diagnostic document systems extends competitive moats. |
| Hospital System Partnership | Single-source contracting consolidates vendor relationships across ambulatory surgery center rollups. |
| Managed Security Service Launch | Hardened cyber insurance requirements redirect IT budgets toward outsourced security operations. |
| ABHA Identifier Interoperability | Ayushman Bharat Digital Mission tenders demand platforms compatible with national health stack standards. |
Research Methodology
Bottom-up hospital IT procurement modeling reconciled against top-down vendor revenue tracking forms the analytical core of this study. Primary interviews with hospital CIOs, GPO contracts managers, FHIR integration specialists, and regulatory affairs directors combined with secondary validation from FDA 510(k) filings, ONC certification databases, hospital procurement records, and hyperscale cloud capex disclosures. Triangulation across stakeholder perspectives and data sources ensures coverage of both demand-side budget allocation patterns and supply-side platform capability roadmaps.
Input-output matrices map segmentation dimensions including deployment model, end-user scale, application workflow depth, and regional regulatory cluster across the projection horizon. CAGRs derive from elasticity modeling of cloud storage economics, compliance-driven infrastructure refresh cycles, and interoperability mandate adoption curves. Industry-specific forecast inputs incorporate 21 CFR Part 11 enforcement timelines and EU AI Act risk classification implementation.
Caveats apply where ransomware insurance market hardening or FHIR specialist talent scarcity could materially shift the outlook for cloud migration timelines. Forecasts reflect assumptions around regulatory enforcement consistency and hyperscale provider pricing stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Information Systems
OBGYN EHR Market
Medical Information Systems
Urology EMR Software Market
Medical Information Systems
Global Allergy EMR Software Market
Medical Information Systems
US Medical Coding Market
Medical Information Systems
Global Medical Terminology Software Market
Medical Information Systems
Master Patient Index Software Market
Medical Information Systems
Medical Coding Market
Medical Information Systems
Global Medical Transcription Software Market
Medical Information Systems
Global Medical Writing Market
Medical Information Systems
Global Healthcare Information Systems Market
Medical Information Systems
Global Clinical Information System Market
Medical Information Systems
AI in Medical Coding Market
Medical Information Systems
Medical Information Market
Medical Information Systems
Artificial Intelligence in Medical Software Market
Medical Information Systems
Healthcare Information Governance Solution Market
Medical Information Systems
Healthcare ERP Market