
 Global Allergy EMR Software Market | 2026-2036
Global Allergy EMR Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Allergy EMR Software Market Foresight
Multi-source procurement of allergy EMR modules is rebalancing toward vertically integrated platform suites as practices seek unified patient data architectures. AdvancedMD leverages cloud-native infrastructure to anchor its position among independent allergy clinics. DrChrono EHR sustains competitive traction through mobile-first design optimized for point-of-care documentation. Kareo Clinical EHR differentiates via streamlined billing integration that appeals to smaller specialty practices.
Allergy EMR software constitutes specialized electronic medical record systems engineered for immunology workflows, incorporating structured allergy testing documentation, immunotherapy tracking, and antigen inventory management with HL7 FHIR interoperability protocols. These platforms serve the commercial purpose of reducing documentation burden while enabling precision allergy care coordination across referral networks. Cloud-based software leads deployment preferences as practices exit capital-intensive on-premise infrastructure, while SaaS platforms capture expanding margin pools through subscription predictability. Patient management and allergy testing documentation applications concentrate demand as regulatory pressure intensifies on structured clinical data capture.
FDA oversees software-as-medical-device classifications affecting clinical decision support modules within allergy EMR platforms, while HIPAA mandates govern patient data exchange architectures. The 21st Century Cures Act imposes information-blocking prohibitions that reshape vendor interoperability obligations. Stakeholders must monitor evolving ONC certification requirements that determine market access eligibility for outpatient specialty systems.
Market Dynamics
Interoperability mandates from the 21st Century Cures Act are restructuring vendor competitive positions by forcing HL7 FHIR compliance as a baseline market access requirement rather than a premium feature.
Growth Catalysts
- Cloud migration:Allergy and immunology clinics across the United States are abandoning capital-intensive on-premise servers for SaaS platforms that reduce IT overhead and enable remote access.
- HIPAA information-blocking rules:These provisions accelerate data exchange requirements between specialty EMR systems and hospital networks, expanding addressable market for interoperable platforms.
- Integrated care networks in Germany:These organizations prioritize structured allergy testing documentation workflows, creating concentrated demand for specialized immunology modules.
Market Restraints
- ONC certification complexity:Evolving certification requirements for outpatient specialty systems create extended compliance timelines that delay product launches and inflate development costs.
- Legacy system entrenchment:Established practices face high switching costs when migrating historical immunotherapy records and antigen inventory data to modern platforms.
- Cybersecurity infrastructure gaps:Smaller specialty practices lack dedicated security personnel, exposing patient data to breach risks that trigger liability concerns.
Strategic Opportunities
- Pediatric allergy specialization:Underpenetrated practices serving pediatric populations require family-centric patient portals and guardian consent workflows that general EMR platforms inadequately support.
- AI-driven clinical decision support:Machine learning integration with structured allergy testing data enables predictive immunotherapy protocols that differentiate premium platform tiers.
- Mobile-first point-of-care documentation:Tablet-optimized interfaces for allergy shot administration and reaction monitoring capture workflow efficiency gains in high-volume injection clinics.
Industry Challenges
- FHIR implementation expertise:Vendor engineering teams face acute shortages of developers proficient in healthcare interoperability standards, constraining product roadmap velocity.
- Multi-stakeholder workflow alignment:Platforms must simultaneously satisfy allergists, nursing staff, billing departments, and referral coordinators with divergent interface priorities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Allergy EMR Software Market |
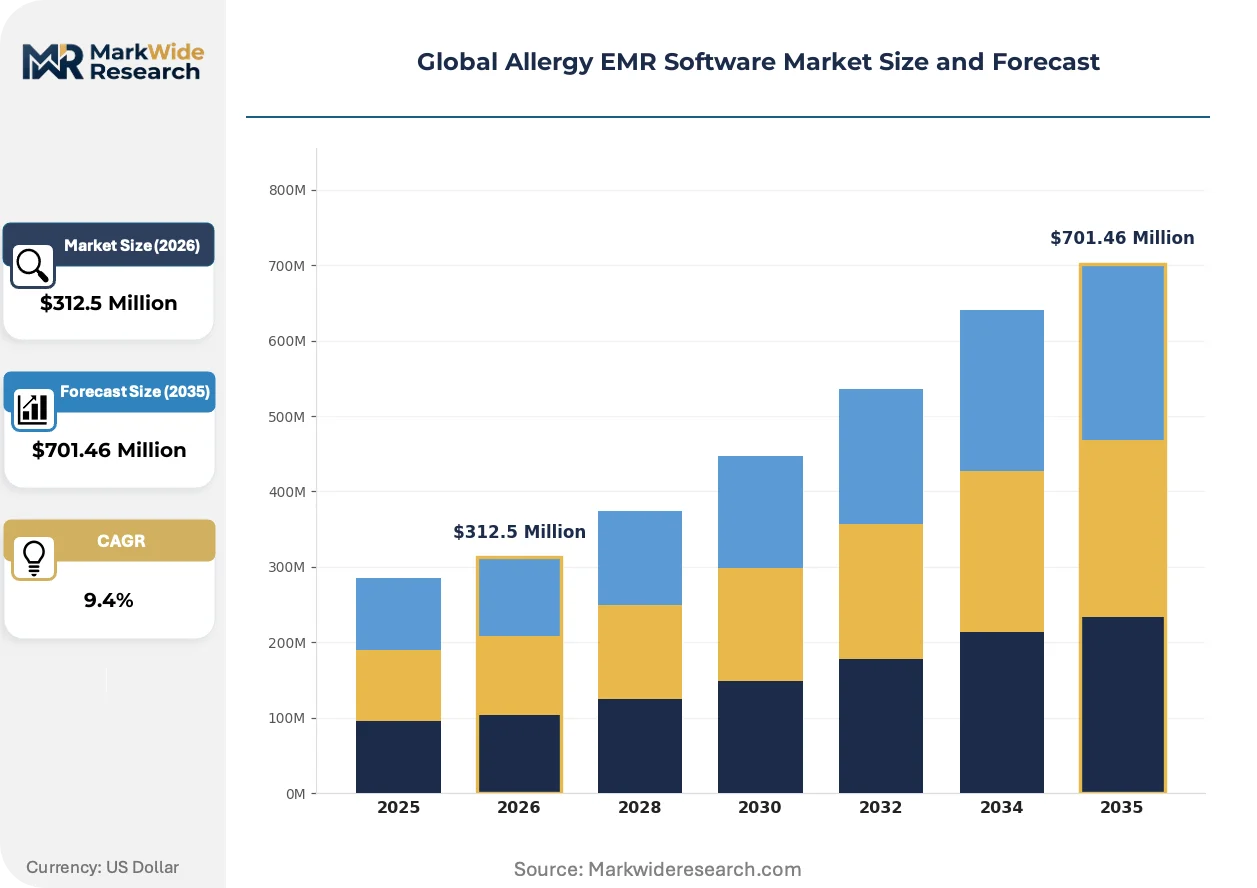
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $701.46 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-Based Software, On-Premise Software, Hybrid Software, Mobile Applications Application: Patient Management, Appointment Scheduling, Prescription Management, Billing & Coding, Allergy Testing Documentation End User: Specialty Clinics, Primary Care Centers, Diagnostic Laboratories, Telemedicine Providers Deployment Type: Hosted Solutions, Self-Hosted Solutions, SaaS Platforms, Managed Services |
| Companies Covered | AdvancedMD, DrChrono EHR, Kareo Clinical EHR, PrognoCIS by Bizmatics, Practice Fusion, CareCloud, MDConnection, Intergy by Greenway Health, Allscripts Healthcare Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Allergy EMR Software Market Shifts & Advancements
Three distinct vectors are compressing development cycles and redefining user expectations across allergy EMR platforms: infrastructure architecture, regulatory compliance automation, and care delivery models.
Serverless cloud-native architecture is overtaking traditional client-server deployments in independent allergy clinics. These platforms eliminate local hardware maintenance burdens while enabling automatic scalability during peak allergy season patient volumes. The shift is compressing total cost of ownership calculations and marginalizing vendors without multi-tenant SaaS capabilities.
EU MDR and FDA software-as-medical-device classifications are converging on clinical decision support modules within allergy EMR systems. Vendors must now document algorithm validation and risk management for immunotherapy dosing recommendations. German and United States markets are responding by segregating decision-support features into separately certified components that can be updated independently of core platform releases.
Subscription unbundling is fragmenting traditional all-inclusive EMR contracts into modular components. Smaller practices in the United States are selecting standalone allergy testing documentation tools rather than comprehensive suites, then integrating through APIs. This pattern concentrates in cash-pay allergy clinics that prioritize cost control over unified vendor relationships.
Global Allergy EMR Software Market Segmentation
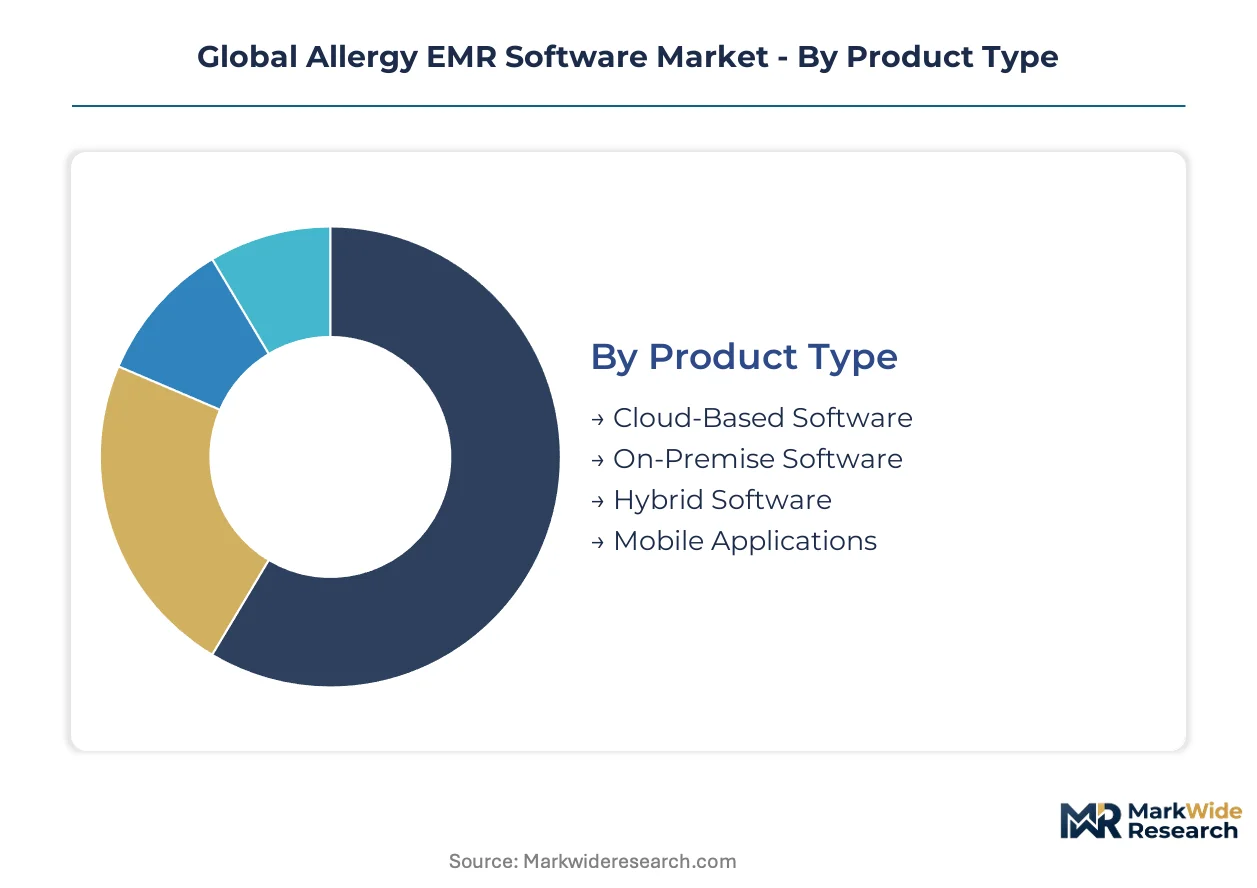
Segmentation reveals how vendor engineering resources and customer procurement priorities diverge across the allergy EMR landscape. Cloud-native architectures command premium development investment while legacy migration paths sustain residual demand for hybrid configurations.
Product Type:
Supply concentration among SaaS-native vendors is reshaping competitive dynamics across deployment modalities, with multi-tenant infrastructure investments creating durable cost advantages.
- Cloud-Based Software:Multi-tenant SaaS architectures eliminate local server maintenance while enabling automatic scaling during peak allergy season volumes. Demand concentrates among independent United States clinics seeking to exit capital-intensive infrastructure commitments under HIPAA compliance pressures.
- On-Premise Software:Client-server deployments retain traction in German integrated care networks with stringent data sovereignty requirements and dedicated IT security personnel. These installations absorb higher total cost of ownership in exchange for direct infrastructure control.
- Hybrid Software:Mixed cloud-local configurations bridge legacy system dependencies with modern interoperability requirements.
- Mobile Applications:Tablet-optimized point-of-care interfaces target high-volume injection clinics requiring bedside documentation workflows.
Cloud-based software absorbs the bulk of installed capacity; mobile applications are expanding most quickly.
Application:
Functional modules cluster around revenue cycle touchpoints versus clinical documentation workflows, with billing integration driving procurement decisions among smaller practices.
- Patient Management:Core demographic tracking, guardian consent workflows, and family portal access serve pediatric allergy populations with specialized immunology needs. German clinics prioritize these modules for integrated care network coordination.
- Allergy Testing Documentation:Structured data capture for skin prick tests, intradermal reactions, and serum-specific IgE results enables HL7 FHIR exchange with hospital referral networks. United States demand accelerates under 21st Century Cures Act information-blocking prohibitions.
- Appointment Scheduling:Seasonal volume surge handling with injection queue optimization.
- Prescription Management:Immunotherapy vial tracking with antigen inventory integration.
- Billing & Coding:Specialty-specific claim scrubbing for allergy shot administration and testing procedures.
Patient management retains the deepest installed base; allergy testing documentation is climbing the fastest as regulatory pressure intensifies.
End User:
Customer concentration patterns reflect referral network topology, with diagnostic laboratories emerging as critical interoperability nodes linking specialty clinics to hospital systems.
- Specialty Clinics:Dedicated allergist practices require comprehensive immunotherapy tracking, antigen inventory management, and patient portal engagement. These customers concentrate procurement authority for platform selection decisions.
- Telemedicine Providers:Remote consultation platforms serving allergy populations demand asynchronous documentation workflows and e-prescribing integration. Expansion concentrates among United States cash-pay models seeking geographic market extension.
- Primary Care Centers:Generalist practices with limited allergy case volumes prioritize lightweight testing documentation modules.
- Diagnostic Laboratories:Centralized testing facilities require bidirectional result exchange with ordering EMR systems.
Specialty clinics absorb the bulk of installed capacity; telemedicine providers are gaining share fastest.
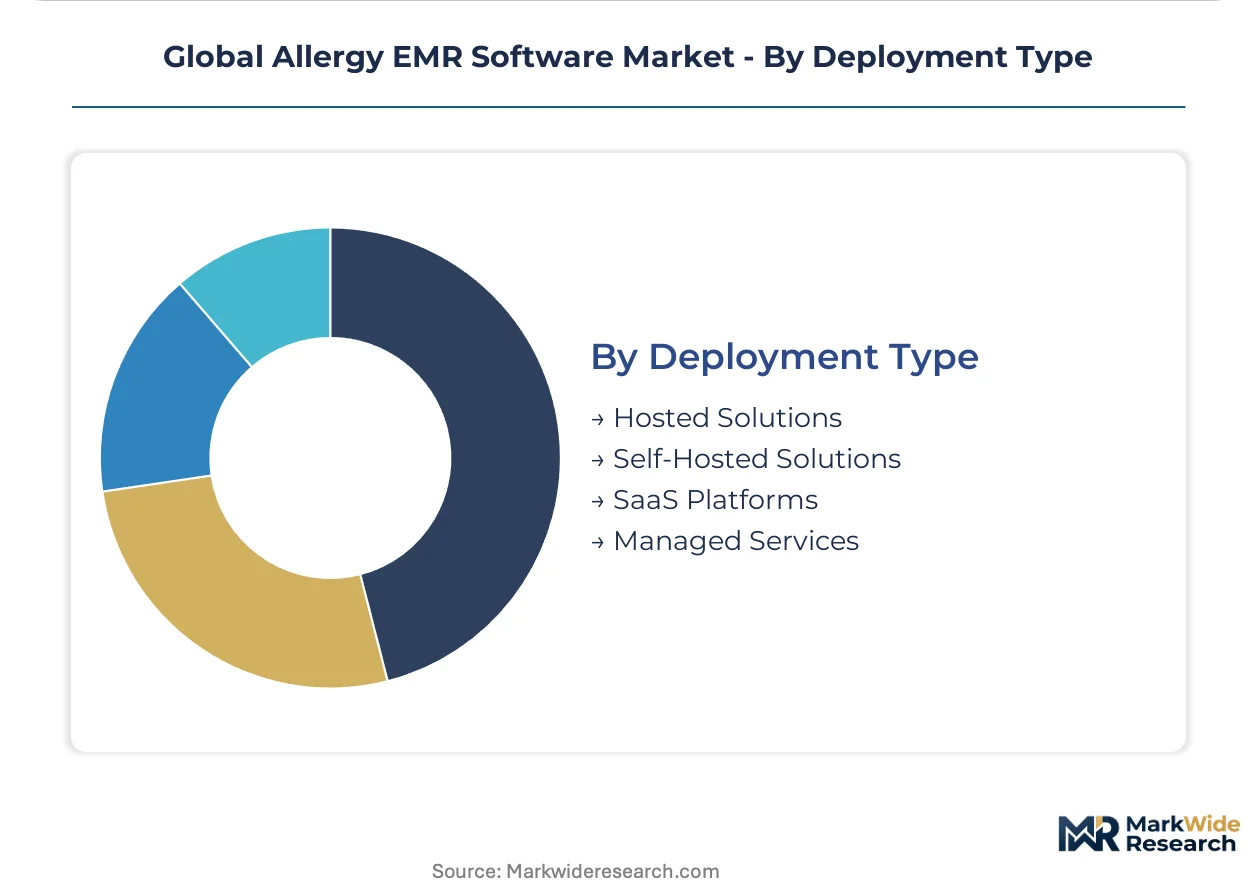
Deployment Type:
Margin structures diverge sharply between vendor-controlled infrastructure and customer-managed installations, with managed services capturing expanding recurring revenue pools.
- SaaS Platforms:Subscription-based multi-tenant delivery eliminates upfront licensing costs while embedding automatic security patch deployment. German and United States markets concentrate demand as practices prioritize predictable operational expenditure over capital deployment.
- Managed Services:Outsourced infrastructure oversight with dedicated support personnel addresses cybersecurity competency gaps among smaller specialty practices. These arrangements expand as HIPAA breach liability concerns intensify.
- Hosted Solutions:Single-tenant cloud deployments with vendor-managed infrastructure.
- Self-Hosted Solutions:Customer-operated installations with full infrastructure control.
SaaS platforms absorb the bulk of installed capacity; managed services are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley's cloud infrastructure anchors North American EMR deployment, while German healthcare networks drive European standardization for allergy documentation protocols.
United States
Independent allergy clinics in Texas and Florida are abandoning on-premise servers for multi-tenant SaaS architectures under HIPAA information-blocking enforcement. The 21st Century Cures Act mandates HL7 FHIR exchange with hospital networks, accelerating procurement of interoperable platforms. Boston's Longwood Medical Area hosts concentrated pilot programs for immunotherapy tracking modules.
Germany
Integrated care networks in Bavaria and North Rhine-Westphalia prioritize structured allergy testing documentation for cross-provider coordination. EU MDR classifications now govern clinical decision support modules within EMR systems, requiring separate certification pathways. Berlin's Charité hospital network drives interoperability standards adoption across outpatient specialty clinics.
United Kingdom
NHS England's digital transformation programs are expanding allergy service digitization in London and Manchester secondary care trusts. GDPR compliance frameworks shape patient data exchange architectures between private allergy clinics and NHS referral networks. The Cambridge-Oxford health tech corridor incubates FHIR-native platform development for immunology workflows.
Japan
Metropolitan Tokyo allergy clinics are adopting cloud-based patient management to address seasonal cedar pollen surge volumes. PMDA oversight of software-as-medical-device classifications influences vendor product roadmaps for clinical decision support. Osaka's Kansai region concentrates demand for pediatric allergy specialization modules with family portal integration.
India
Telemedicine providers in Bangalore and Hyderabad are deploying lightweight allergy documentation tools for remote consultation expansion. CDSCO guidance on digital health platforms shapes vendor compliance investments for clinical data capture. Mumbai's private hospital networks drive demand for billing-integrated EMR systems serving cash-pay allergy patients.
Global Allergy EMR Software Market Competitive Landscape
Global majors compete with regional champions across cloud infrastructure maturity, creating a tiered structure where multi-tenant SaaS vendors capture premium valuations against legacy client-server incumbents. The vendor base clusters around three strategic archetypes: cloud-native specialists with serverless architectures, generalist EMR platforms with allergy modules, and billing-centric solutions for smaller practices. Dominant competitive moves include API-first ecosystem partnerships and modular subscription unbundling that fragments traditional all-inclusive contracts.
Among cloud-native specialists, AdvancedMD exemplifies the vertically integrated platform approach, while DrChrono EHR occupies a position within mobile-first documentation archetypes. Kareo Clinical EHR represents the billing-integrated tier targeting independent specialty practices with streamlined revenue cycle management. These three anchors illustrate how vendor positioning diverges across infrastructure architecture, interface design philosophy, and financial workflow depth.
| Leading Market Players |
|---|
| AdvancedMD |
| DrChrono EHR |
| Kareo Clinical EHR |
| PrognoCIS by Bizmatics |
| Practice Fusion |
| CareCloud |
| MDConnection |
| Intergy by Greenway Health |
| Allscripts Healthcare Solutions |
| Others |
Supply & Pricing Matrix
Independent allergy clinics in Texas and Florida concentrate procurement authority, anchoring subscription-based SaaS pricing as the dominant commercial model across the United States market. Their capital constraints and HIPAA compliance pressures compress vendor pricing power while favoring predictable operational expenditure over upfront licensing.
Pricing Analysis
Service bundling separates premium tiers with dedicated implementation support and FHIR compliance consulting from stripped-down entry packages lacking immunotherapy tracking modules. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with ONC-certified platforms commanding sustained premiums. Cost compression in the economy tier intensifies because smaller practices select standalone documentation tools over comprehensive suites. Cash-pay allergy clinics exhibit highest price sensitivity; German integrated care networks with dedicated IT budgets show lowest sensitivity.
Supply Chain Analysis
Regional distribution centers in Silicon Valley, Berlin, and Bangalore anchor cloud infrastructure deployment for allergy EMR platforms serving their respective markets. Software development draws from engineering talent pools in the United States, Germany, and India, with serverless architecture components sourced from hyperscaler ecosystems. Single-source vulnerability concentrates in FHIR implementation expertise, where qualified developer scarcity constrains vendor roadmap velocity. Distribution runs through direct vendor sales teams for enterprise accounts and channel partners for independent clinic segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Engineering capacity for HL7 FHIR compliance functions as the binding constraint propping vendor pricing power. Scarce developer talent limits platform expansion velocity, sustaining margin structures for certified incumbents.
For Market Incumbents: Deepen backward integration into clinical decision support algorithm development to differentiate premium tiers against generalist EMR platforms. Expand capacity addition in German integrated care networks where data sovereignty requirements erect competitive moats. Certification investment in EU MDR pathways secures defensible positioning against SaaS-native challengers.
For New Entrants and Emerging Players: Capture pediatric allergy specialization as the most penetrable segment, where family portal workflows and guardian consent modules remain underdeveloped by incumbent platforms. Target cash-pay telemedicine providers in the United States seeking lightweight, API-first documentation tools. A modular go-to-market angle unbundling immunotherapy tracking from comprehensive suites bypasses entrenched vendor relationships.
For Investors and Strategic Acquirers: The window for entry favors cloud-native specialists with serverless architectures and established FHIR engineering teams over legacy client-server incumbents. Long-term viability hinges on regulatory certification durability rather than feature velocity alone. Watch ONC certification requirement evolution as the critical inflection signal determining market access eligibility shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| FHIR-Native Platform Development | ONC certification mandates in the United States and Germany accelerate engineering investment in interoperability-first architectures. |
| Pediatric Specialization Module Launch | Family portal workflows and guardian consent features address underpenetrated demand in Tokyo and Osaka metropolitan clinics. |
| Strategic Partnership with Diagnostic Laboratories | Bidirectional result exchange with centralized testing facilities tightens referral network integration for specialty clinics. |
| Acquisition of AI Decision Support Specialist | Machine learning integration for predictive immunotherapy protocols differentiates premium platform tiers against billing-centric competitors. |
| Geographic Expansion into German Integrated Care Networks | EU MDR compliance requirements and data sovereignty preferences favor localized infrastructure deployment in Bavaria and North Rhine-Westphalia. |
Research Methodology
Multi-period observation of vendor certification timelines, subscription pricing trajectories, and clinic procurement patterns anchored the trend analysis, supplemented by interviews with allergy clinic practice administrators, EMR platform product managers, FHIR implementation specialists, and hospital IT procurement officers. Secondary validation drew from ONC certification databases, FDA software-as-medical-device guidance documents, HIPAA enforcement action records, and hyperscaler infrastructure deployment disclosures. Bottom-up clinic adoption modeling and top-down market sizing triangulated volume estimates.
Segment-weighting across deployment modalities, application modules, and end-user categories structured the analytical framework throughout the projection horizon. CAGRs were derived from fitted adoption curves reflecting regulatory mandate acceleration and cloud migration velocity. Forecast inputs incorporated FHIR proficiency scarcity indices and German integrated care network expansion rates alongside United States independent clinic formation trends.
The model holds under stable ONC certification requirements and continued HIPAA information-blocking enforcement; deviation in regulatory timeline acceleration or cybersecurity liability expansion would shift vendor competitive positioning. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Information Systems
US Healthcare ERP Market
Medical Information Systems
Medical Saas System Market
Medical Information Systems
Medical Talent Management IT Market
Medical Information Systems
Global Clinical Information System Market
Medical Information Systems
US Medical Coding Market
Medical Information Systems
Global Pharmacy Information System Market
Medical Information Systems
Post-Marketing Pharmacovigilance and Medical Information Market
Medical Information Systems
India EMR (Electronic Medical Records) Market
Medical Information Systems
Global Clinical EHR Systems Market
Medical Information Systems
Critical Care Information Systems Market
Medical Information Systems
Medical Coding Market
Medical Information Systems
Global Healthcare Information Systems Market
Medical Information Systems
Ambulatory Software Market
Medical Information Systems
AI in Medical Billing Market
Medical Information Systems
Ophthalmology EMR Software Market
Medical Information Systems
Global Medical Scheduling Software Market