
 Global Medical Scheduling Software Market | 2026-2036
Global Medical Scheduling Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Medical Scheduling Software Market Foresight
The capital-intensity divergence between cloud-native specialists and legacy platform incumbents is redrawing competitive boundaries in medical scheduling software. Epic Systems Corporation anchors enterprise hospital deployments through deep EHR integration and captive infrastructure control. QGenda differentiates via anesthesia and specialty physician scheduling optimization. Kyruus leverages provider search and access orchestration to compete for health system digital front-door contracts.
Medical scheduling software comprises digital platforms that automate appointment allocation, resource sequencing, and patient-provider matching through algorithmic optimization and real-time calendar synchronization. These systems integrate HL7 FHIR protocols and REST APIs to exchange availability data with electronic health records, practice management systems, and patient engagement portals. Cloud-Based Software captures the dominant deployment share as health systems prioritize scalable infrastructure and remote accessibility over capital-heavy on-premise installations. Appointment Booking remains the foundational application segment, though Telehealth Coordination represents the fastest-expanding use case as virtual visit volumes reshape capacity planning requirements. Hospitals constitute the largest end-user category by installed base, while Ambulatory Surgical Centers generate disproportionate growth due to procedural volume expansion and block-time optimization needs.
FDA oversight of software-as-a-medical-device intersects with HIPAA security rule enforcement from the Office for Civil Rights to shape product development priorities and liability exposure for scheduling vendors. The EU AI Act and GDPR data localization requirements impose additional compliance architecture on platforms serving European health systems. Stakeholders must monitor evolving interoperability mandates from the Office of the National Coordinator for Health IT and assess whether their data governance frameworks satisfy cross-border patient privacy obligations as health system footprints expand internationally.
Market Dynamics
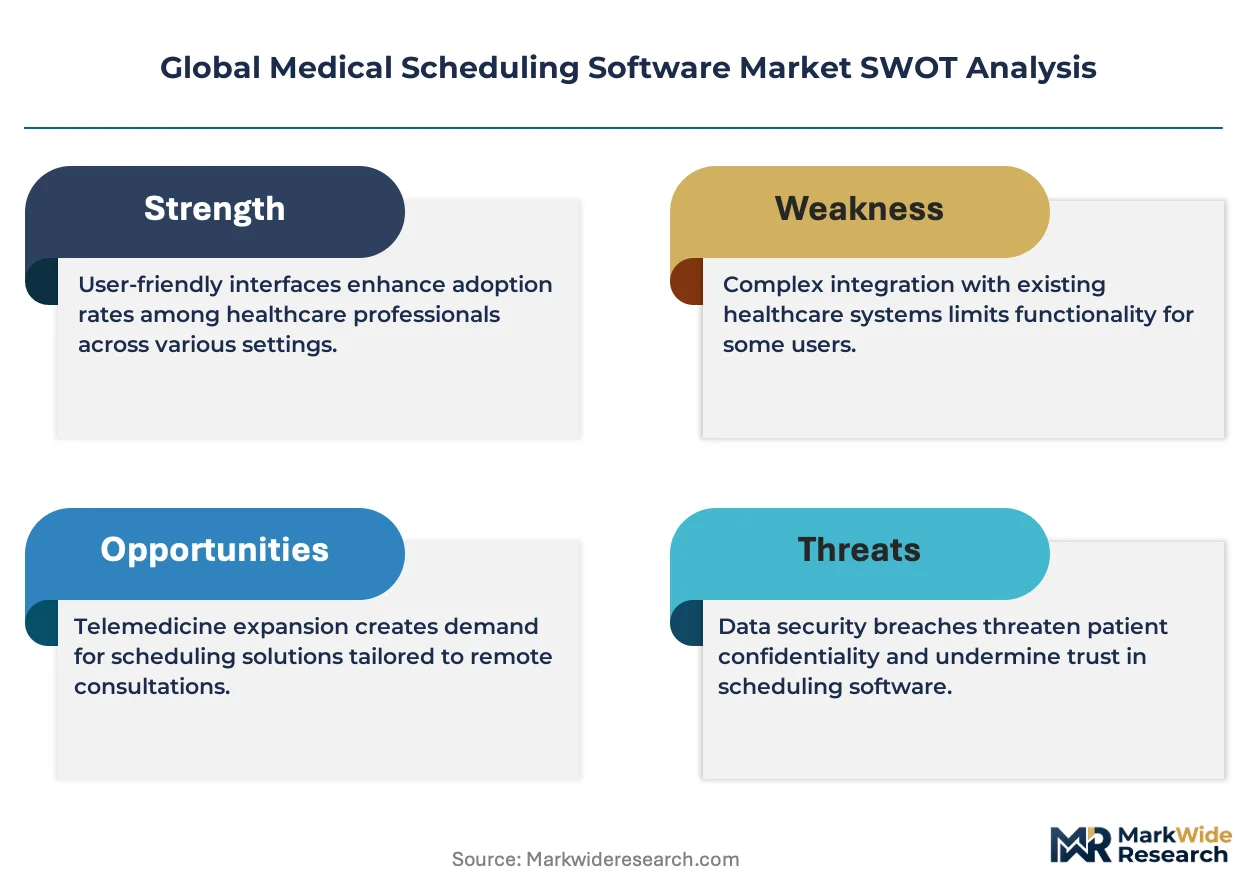
Cloud migration mandates under HIPAA interoperability rules are forcing health systems to retire legacy on-premise scheduling systems, compressing replacement cycles and redistributing procurement power toward cloud-native vendors with modern FHIR-native architectures.
Growth Catalysts
- HIPAA Interoperability Mandates:The Office of the National Coordinator for Health IT's 21st Century Cures Act enforcement compels health systems to replace siloed scheduling tools with API-first platforms that exchange real-time availability data across EHR ecosystems.
- Ambulatory Surgical Center Expansion:Procedural volume growth at ASCs drives demand for block-time optimization algorithms that maximize OR utilization and reduce idle capacity in high-throughput environments.
- Telehealth Coordination:Virtual visit platforms require intelligent scheduling engines that synchronize asynchronous and synchronous care modalities, creating new software procurement categories beyond traditional appointment booking.
Market Restraints
- Data Localization Requirements:GDPR and emerging national privacy frameworks in Germany, France, and India fragment cloud deployment architectures, forcing vendors to maintain region-specific infrastructure that elevates operational complexity.
- Legacy System Entrenchment:Epic Systems and Oracle Cerner's captive infrastructure control across large integrated delivery networks creates switching friction that slows competitive displacement and extends sales cycles.
- Technical Debt Accumulation:Health systems' decades-old HL7 v2 interfaces require expensive middleware layers to bridge modern REST APIs, inflating total cost of ownership for scheduling modernization projects.
Strategic Opportunities
- AI-Driven Predictive Scheduling:Machine learning models that forecast no-show probabilities and optimal appointment durations are penetrating mid-market health systems that lack in-house data science capabilities.
- Latin American Market Penetration:Brazil's ANVISA digital health acceleration and Mexico's expanding private hospital networks present underdeveloped demand for cloud scheduling platforms with Spanish-Portuguese localization.
- Patient Self-Scheduling:Digital front-door initiatives are elevating provider search and direct booking capabilities from administrative features to strategic patient acquisition channels.
Industry Challenges
- Interoperability Certification Delays:ONC's evolving certification criteria for scheduling modules creates timeline uncertainty for product roadmaps and complicates RFP response strategies.
- Cybersecurity Talent Scarcity:HIPAA security rule compliance and FDA software-as-a-medical-device oversight require specialized engineering expertise that vendors struggle to recruit at competitive compensation levels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Medical Scheduling Software Market |
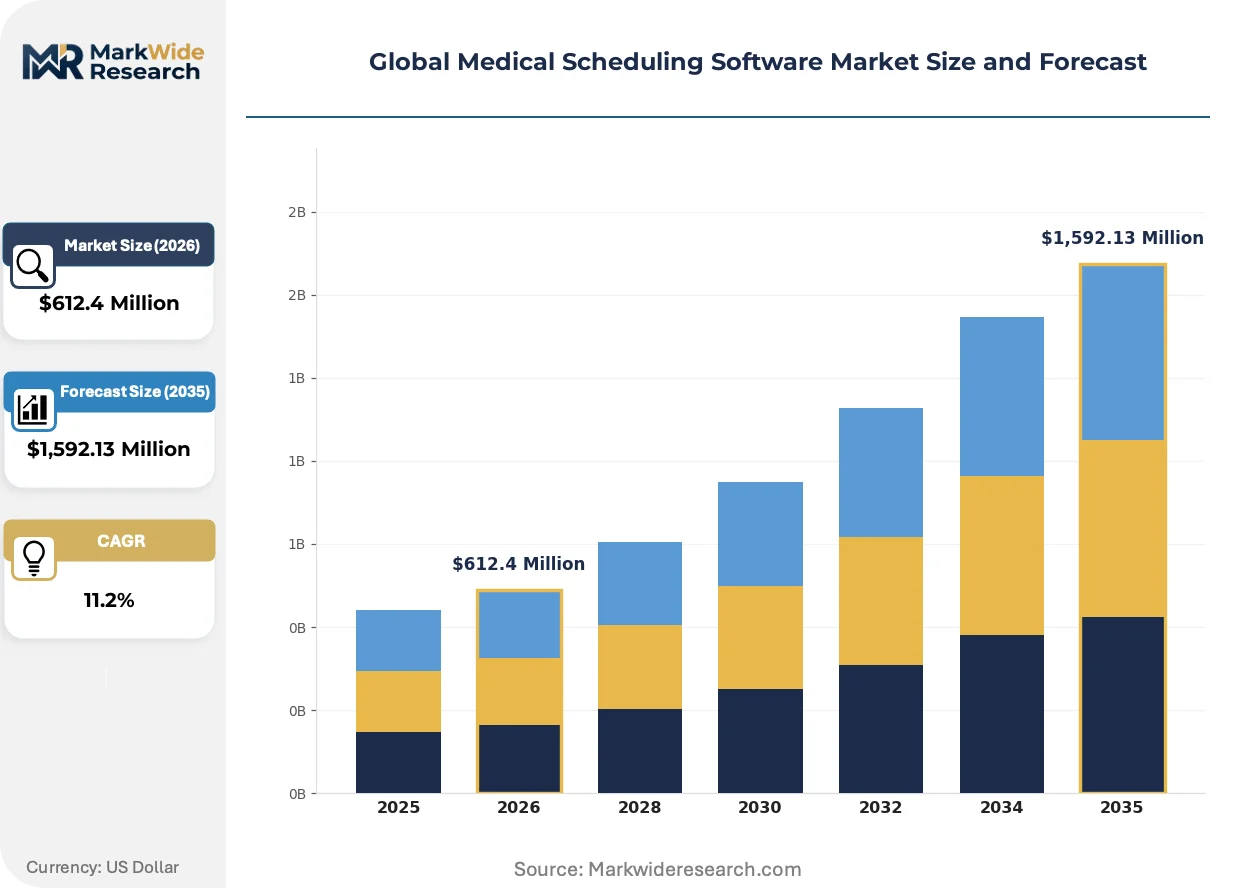
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,592.13 Million |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-Based Software, On-Premise Software, Hybrid Solutions, Mobile Applications Application: Appointment Booking, Resource Management, Patient Reminders, Staff Scheduling, Telehealth Coordination End User: Hospitals, Ambulatory Surgical Centers, Diagnostic Laboratories, Home Healthcare Providers, Rehabilitation Clinics Deployment Mode: Web-Based, Desktop, SaaS, API Integration |
| Companies Covered | Veradigm, CentralReach, AdvancedMD, Kyruus, QGenda, NextGen Healthcare Information Systems, Phreesia, Epic Systems Corporation, Oracle, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Medical Scheduling Software Market Shifts & Advancements
Algorithmic optimization is displacing rule-based scheduling logic across hospital and ambulatory environments, compressing the competitive window for vendors that lack native AI capabilities and elevating buyer expectations for predictive functionality.
Natural language processing for conversational appointment booking is fragmenting the traditional patient portal model. Health systems in the United States and United Kingdom are deploying voice-enabled and chatbot interfaces that bypass web-based scheduling forms. Epic Systems and niche vendors are diverging on whether to embed these capabilities natively or partner with specialized conversational AI platforms.
The EU AI Act's risk classification framework is reshaping product development priorities for scheduling vendors serving European health systems. High-risk algorithmic systems that determine patient access to care must meet conformity assessment requirements that extend deployment timelines. German and French hospitals are prioritizing vendors with established CE marking and explainable AI documentation over faster-to-deploy alternatives.
Subscription pricing for scheduling modules is displacing perpetual license models that dominated legacy procurement. Health system CFOs in Australia and Canada are demanding consumption-based contracts that tie fees to actual appointment volume rather than installed user counts. This shift compresses vendor revenue recognition and elevates the importance of patient retention analytics embedded within scheduling platforms.
Global Medical Scheduling Software Market Segmentation
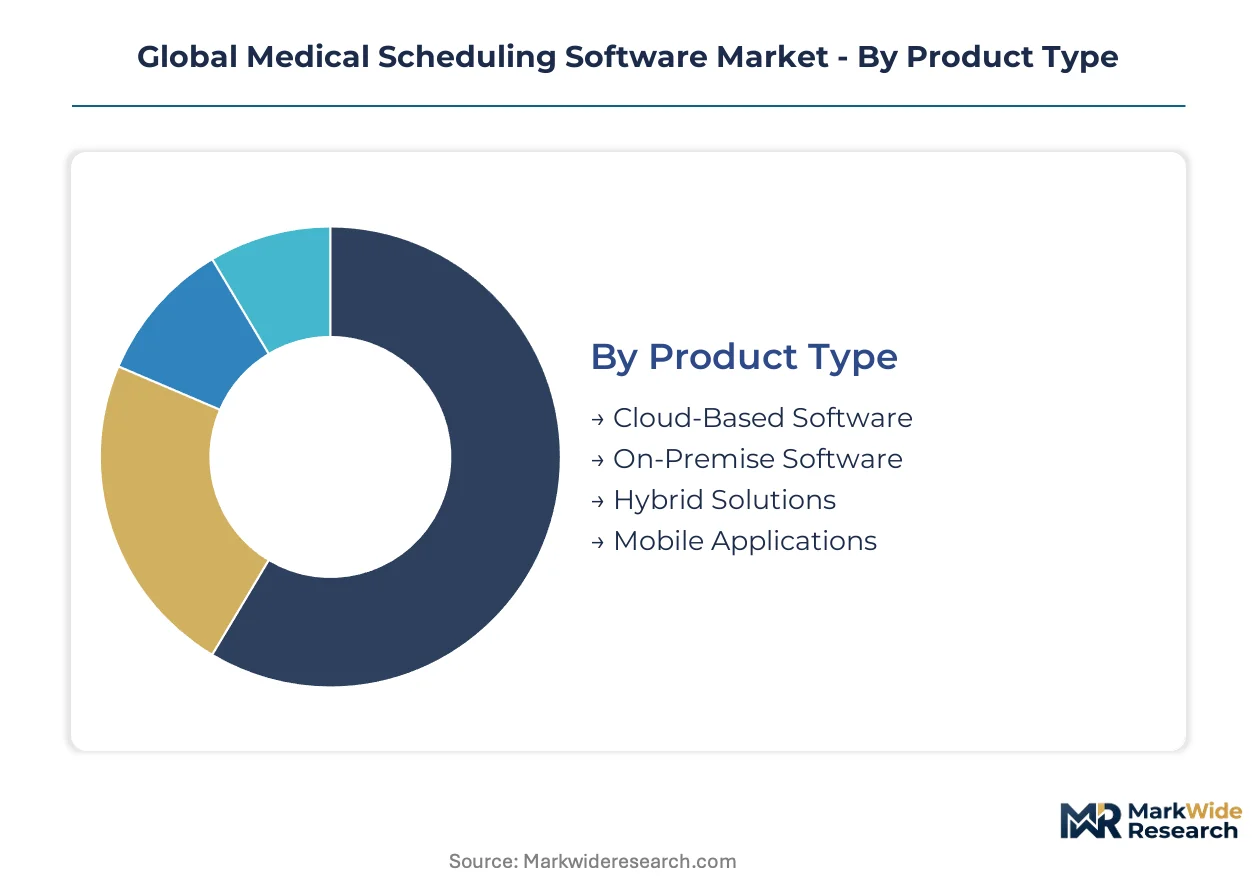
Medical scheduling software vendors architect product portfolios around distinct deployment economics and clinical workflows. Channel strategies diverge sharply between enterprise health systems demanding deep EHR integration and ambulatory operators prioritizing rapid implementation.
Product Type:
Cloud-native architectures dominate new procurement through health system IT departments and value-added resellers, while on-premise solutions persist in captive sales through legacy EHR vendors.
- Cloud-Based Software:Multi-tenant SaaS platforms with FHIR-native APIs enable real-time synchronization across distributed care networks. United States health systems and Australian hospital networks are consolidating procurement around these solutions to satisfy HIPAA interoperability mandates and reduce capital expenditure.
- On-Premise Software:Perpetual-license systems installed within hospital data centers offer maximum data sovereignty control. German and French hospitals favor these deployments under GDPR data localization requirements, though maintenance costs and upgrade friction constrain expansion.
- Hybrid Solutions:Architectures combining cloud orchestration layers with on-premise patient data repositories.
- Mobile Applications:Native iOS and Android scheduling clients for physician and patient self-service.
Cloud-Based Software dominates installed base. Hybrid Solutions are where expansion concentrates as privacy-conscious operators seek architectural compromise.
Application:
Functional modules map to operational cost tiers: core scheduling utilities anchor standard contracts, while predictive and coordination capabilities command premium pricing.
- Appointment Booking:Foundational calendar management with automated availability polling and waitlist optimization. Every health system deployment includes this module, though differentiation has collapsed toward commodity pricing in saturated markets.
- Telehealth Coordination:Engines synchronizing virtual visit queues with asynchronous messaging and remote monitoring workflows. United States integrated delivery networks and United Kingdom NHS trusts are expanding procurement fastest as virtual care volumes reshape capacity planning.
- Resource Management:OR block-time allocation and equipment sequencing algorithms.
- Patient Reminders:Automated SMS, voice, and email notification systems reducing no-show rates.
- Staff Scheduling:Physician and nurse roster optimization with credential matching and fatigue rule enforcement.
Appointment Booking generates the largest revenue pool. Telehealth Coordination is climbing the fastest as health systems rebuild around hybrid care models.
End User:
Customer-type segmentation reveals margin stratification: hospitals absorb implementation complexity for strategic control, while surgical centers and laboratories prioritize speed-to-value.
- Hospitals:Enterprise deployments spanning inpatient, outpatient, and emergency scheduling across multiple facilities. Epic Systems and Oracle Cerner anchor these relationships through EHR bundling, creating substantial switching costs for competitive displacement.
- Ambulatory Surgical Centers:High-throughput procedural environments requiring block-time optimization and rapid room turnover. Brazil's expanding private ASC networks and Mexico's surgical center chains are emerging as high-growth demand centers.
- Diagnostic Laboratories:Specimen collection scheduling and phlebotomy capacity management.
- Home Healthcare Providers:Mobile workforce coordination across geographically dispersed patient visits.
- Rehabilitation Clinics:Recurring therapy appointment sequencing with insurance authorization tracking.
Hospitals anchor vendor revenue stability. Ambulatory Surgical Centers are gaining share fastest as procedural volume migrates from inpatient settings.
Deployment Mode:
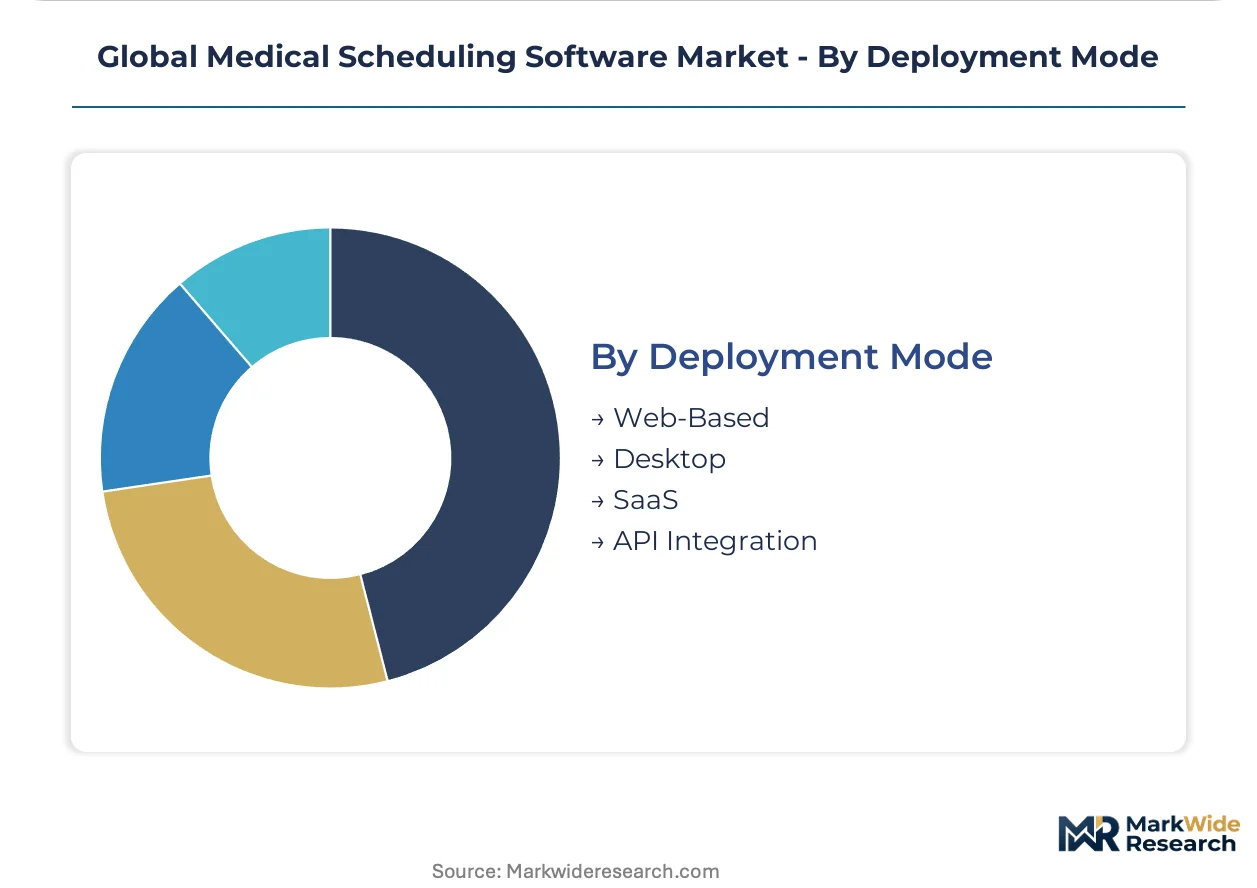
Technical delivery mechanisms determine integration depth and customer technical requirements, with API-first approaches displacing monolithic web portals.
- SaaS:Subscription-hosted platforms with automatic updates and shared infrastructure economics. Health system CFOs in Canada and Australia are mandating these contracts with consumption-based pricing tied to appointment volume.
- API Integration:Headless scheduling engines embedded within existing patient portals and EHR interfaces. United States digital health startups and NHS England transformation programs favor this deployment to preserve UX investments while modernizing backend logic.
- Web-Based:Browser-accessible scheduling portals requiring no local installation.
- Desktop:Thick-client applications for offline scheduling and legacy system compatibility.
SaaS captures the majority of new contract value. API Integration is where vendor R&D investment concentrates as composable architecture preferences harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Health system buyers in the United States absorb premium pricing for deep EHR integration, while procurement teams in Brazil and Mexico prioritize rapid deployment economics over customization depth.
United States
Integrated delivery networks drive enterprise scheduling deployments across multi-hospital footprints. HIPAA interoperability mandates from the Office of the National Coordinator for Health IT accelerate replacement of legacy systems. Epic Systems and Oracle Cerner dominate deployments in the Midwest and Southeast health system clusters.
Germany
University hospitals and statutory health insurance funds demand GDPR-compliant on-premise architectures with local data residency. The EU AI Act's high-risk system classification extends deployment timelines for algorithmic scheduling platforms. Berlin and Munich health networks concentrate vendor certification efforts around CE marking and explainable AI documentation.
United Kingdom
NHS England transformation programs prioritize API-first scheduling engines that embed within existing patient portals. NHS Digital interoperability standards compel FHIR-native platform adoption across acute trusts. London and Greater Manchester health systems lead procurement for digital front-door integration.
Brazil
Private hospital networks and ambulatory surgical centers expand cloud scheduling adoption amid ANVISA digital health acceleration. Portuguese-language localization and consumption-based pricing attract mid-market operators. São Paulo and Rio de Janeiro surgical center chains drive block-time optimization demand.
Australia
State health departments mandate SaaS contracts with appointment-volume pricing to reduce capital expenditure. The Australian Digital Health Agency's interoperability framework pushes FHIR adoption across public hospital networks. New South Wales and Victoria health systems consolidate procurement around cloud-native platforms.
Global Medical Scheduling Software Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes in medical scheduling software. Enterprise EHR incumbents anchor hospital deployments through captive infrastructure bundling, while cloud-native specialists capture ambulatory and surgical center growth. The market structure stratifies into three tiers: integrated platform giants, vertical workflow specialists, and API-first modular vendors. M&A activity concentrates on acquiring FHIR-native architectures and conversational AI capabilities, while geographic expansion targets Latin American and Asia-Pacific health system privatization.
Within the integrated platform tier, Epic Systems Corporation and Oracle exemplify archetypes that leverage EHR dominance to control scheduling module procurement. Kyruus and QGenda occupy positions as vertical specialists, with the former anchoring provider search and access orchestration and the latter exemplifying anesthesia and physician roster optimization. These three companies represent the competitive vectors—platform bundling versus workflow depth—that structure vendor selection criteria across health system segments.
| Leading Market Players |
|---|
| Veradigm |
| CentralReach |
| AdvancedMD |
| Kyruus |
| QGenda |
| NextGen Healthcare Information Systems |
| Phreesia |
| Epic Systems Corporation |
| Oracle |
| Others |
Supply & Pricing Matrix
Cloud-native SaaS architectures replacing legacy perpetual-license systems simultaneously redistribute vendor margins toward recurring revenue streams and concentrate procurement leverage within health system IT departments that negotiate enterprise-wide contracts. This substitution dynamic compresses upfront implementation fees while elongating customer lifetime value horizons across subscription renewal cycles.
Pricing Analysis
Implementation services and ongoing support contracts generate the dominant lifetime value tier for scheduling vendors, with professional fees often exceeding first-year subscription revenue in enterprise hospital deployments. Three-tier pricing structure across premium, standard, and economy levels segments by integration complexity and EHR ecosystem depth, with Epic Systems and Oracle Cerner commanding brand premiums through captive infrastructure bundling. Pricing pressure stems from mid-market health systems demanding consumption-based contracts tied to actual appointment volume rather than installed user counts. Ambulatory surgical centers exhibit highest price sensitivity due to capital constraints, while integrated delivery networks absorb premium pricing for deep interoperability.
Supply Chain Analysis
HIPAA compliance certification bottlenecks in the United States and GDPR data localization requirements in Germany and France constrain vendor expansion velocity and elevate regional infrastructure costs. Cloud hosting dependencies draw from Amazon Web Services, Microsoft Azure, and Google Cloud Platform data centers, with API middleware components sourced from specialized FHIR interoperability vendors. Single-source vulnerability concentrates in EHR integration layers controlled by Epic Systems and Oracle Cerner. Distribution runs through direct enterprise sales teams for hospital systems and value-added resellers for ambulatory operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through integrated delivery network consolidation, with multi-hospital systems extracting volume discounts that compress vendor margins and extend procurement cycles.
For Market Incumbents: Fortify EHR integration depth through expanded FHIR-native API portfolios that raise switching costs for hospital systems evaluating competitive displacement. Deepen vertical integration into conversational AI capabilities via acquisition or exclusive partnership to counter emerging chatbot-native entrants. Prioritize certification investment for EU AI Act conformity assessment to defend European market position against faster-to-deploy alternatives. For New Entrants and Emerging Players: Anchor in Latin American private hospital networks, where ANVISA digital health acceleration and Portuguese-Spanish localization gaps create penetrable white space absent dominant EHR incumbents. Target Brazil's ambulatory surgical center chains with block-time optimization modules priced on consumption metrics. Pursue API-first go-to-market positioning that embeds within existing patient portals rather than displacing core scheduling infrastructure. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed cloud-native scheduling specialists holding FHIR-native architectures but lacking geographic scale. Five-to-ten year viability hinges on successful expansion beyond United States health system clusters into underpenetrated European and Asia-Pacific markets. Monitor ONC certification timeline delays as inflection signal for vendor consolidation windows.| Strategic Initiative | Industry Significance |
|---|---|
| FHIR-Native Platform Integration | ONC interoperability mandates compel real-time EHR synchronization across Epic Systems and Oracle Cerner ecosystems. |
| Acquisition of Conversational AI Specialist | NHS England digital front-door programs prioritize voice-enabled booking interfaces over traditional web portals. |
| Geographic Expansion into Brazil | ANVISA regulatory acceleration and São Paulo surgical center privatization create deployable demand. |
| CE Marking Pathway Investment | German university hospitals prioritize explainable AI documentation under EU AI Act high-risk classification. |
| Consumption-Based Contracting Model | Australian state health departments mandate appointment-volume pricing to reduce capital expenditure. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with health system CIOs, EHR integration specialists, ambulatory surgery center operators, and GPO contracts managers; and secondary validation against FDA software-as-a-medical-device filings, ONC interoperability certification databases, hospital procurement records, and hyperscaler healthcare cloud revenue disclosures. Bottom-up sizing triangulated vendor-reported deployment metrics with top-down health system IT spending benchmarks.
Across the projection horizon, the analytical framework modeled deployment mode transitions, application functional expansion, and end-user segment migration patterns. Segmentation dimensions spanned cloud versus on-premise architecture, appointment booking versus telehealth coordination modules, and hospital versus ambulatory surgical center adoption intensity. CAGRs derived from fitted growth curves calibrated to HIPAA mandate enforcement timelines and EHR replacement cycle data.
Underlying assumptions cover sustained interoperability regulation enforcement and cloud migration continuity, with deviation risk concentrated in legacy system entrenchment extending replacement timelines beyond modeled windows. Practitioners should keep alternative scenarios live as EU AI Act implementation pace and ANVISA regulatory acceleration evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Information Systems
Healthcare ERP Market
Medical Information Systems
Global Clinical Information System Market
Medical Information Systems
Global Medical Transcription Software Market
Medical Information Systems
Global Laboratory Information Management System for Forensic Science Market
Medical Information Systems
OBGYN EHR Market
Medical Information Systems
Critical Care Information Systems Market
Medical Information Systems
Global Medical Decision Support Systems for Sepsis Market
Medical Information Systems
Anesthesia Information Management Systems Market
Medical Information Systems
AI in Medical Billing Market
Medical Information Systems
US Healthcare ERP Market
Medical Information Systems
AI Medical Service Market
Medical Information Systems
Mobile Medical Apps Market
Medical Information Systems
Global Allergy EMR Software Market
Medical Information Systems
India EMR (Electronic Medical Records) Market
Medical Information Systems
Medical Software Market
Medical Information Systems
Global Clinical Documentation Improvement Market