
 Global Healthcare Games and Simulation Market | 2026-2036
Global Healthcare Games and Simulation Market Size, Share, and Industry Trends Forecast 2026-2036
Global Healthcare Games and Simulation Market Intelligence
The shift toward subscription-based, cloud-hosted platforms from large capital expenditure models is reshaping competitive positioning. This allows smaller institutions to access advanced training tools previously limited to large hospitals. CAE Inc. leverages its aerospace simulation expertise to offer comprehensive healthcare training ecosystems. Surgical Science specializes in robotic and laparoscopic surgery simulators, while Laerdal Medical focuses on emergency care and resuscitation training.
Healthcare games and simulation encompass interactive digital tools that replicate clinical environments, procedures, and physiological responses. These systems often integrate haptic feedback and high-fidelity 3D visualization to create realistic training scenarios without patient risk. Virtual Reality Simulators for surgical planning represent a high-margin, rapidly expanding product category. Medical schools and research institutes continue to be the dominant end-user segment, procuring these tools for curriculum-based training.
Regulatory frameworks such as the US FDA's guidance on software as a medical device (SaMD) and the EU's Medical Device Regulation (MDR) govern product validation. Compliance with standards like ISO 13485 for quality management is also essential for market access in many countries. A key strategic decision for developers is whether to prioritize AI-driven adaptive learning pathways or focus on standardized, curriculum-aligned simulation modules.
Market Dynamics
The imperative for verifiable, objective skill validation is the central force shaping the healthcare simulation market. Regulatory mandates, particularly the EU's Medical Device Regulation, are compelling providers and manufacturers to adopt simulation for proficiency assessment beyond basic training.
Growth Catalysts
- Regulatory Proficiency Mandates:The European Union's MDR requires rigorous validation of a clinician's ability to use new medical devices, a process that simulation platforms are uniquely positioned to document and support, driving institutional procurement.
- Advancements in Immersive Technology:The integration of haptic feedback, high-fidelity 3D visualization, and VR/AR hardware creates hyper-realistic training scenarios, increasing clinical acceptance and adoption in surgical specialties like neurology and cardiology.
- Focus on Patient Safety:Medical schools and teaching hospitals are increasingly using simulation to provide risk-free training environments for complex procedures, reducing medical errors and improving patient outcomes without live-subject exposure.
Market Restraints
- High Initial Investment:The significant capital expenditure required for high-fidelity simulators, including hardware and facility setup, remains a substantial barrier for smaller hospitals, community clinics, and educational institutions in developing economies.
- Lack of Standardization:The absence of universally accepted metrics for performance and proficiency across different simulation platforms complicates curriculum integration and makes it difficult to compare skill assessments between institutions.
- Complex Validation Pathways:Products classified as Software as a Medical Device (SaMD) by regulators like the US FDA face lengthy and expensive validation processes, which can delay market entry and increase development costs.
Strategic Opportunities
- Expansion in Emerging Economies:Markets such as Brazil and India represent significant growth areas as their healthcare systems modernize and invest in advanced medical education tools to train a growing number of healthcare professionals.
- New Clinical Applications:Opportunities exist beyond surgical training in areas like mental health for virtual patient interaction, chronic disease patient education, and pharmaceutical team training for drug administration protocols.
- AI-Powered Personalization:Integrating artificial intelligence with simulation platforms allows for the development of adaptive learning systems that tailor training scenarios to an individual user's skill level, optimizing learning efficiency.
Industry Challenges
- Systems Integration Complexity:Integrating new simulation technologies with existing hospital information systems (HIS), electronic health records (EHR), and learning management systems (LMS) presents a significant technical and operational hurdle for IT departments.
- Specialized Content Creation:Developing medically accurate, high-fidelity simulation content requires a rare combination of clinical expertise, software engineering, and instructional design skills, creating a talent bottleneck and driving up costs.
- Curriculum Development Lag:The pace of developing and validating simulation-based curricula often lags behind technological advancements, limiting the immediate utility of new hardware and software features within formal education programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Healthcare Games and Simulation Market |
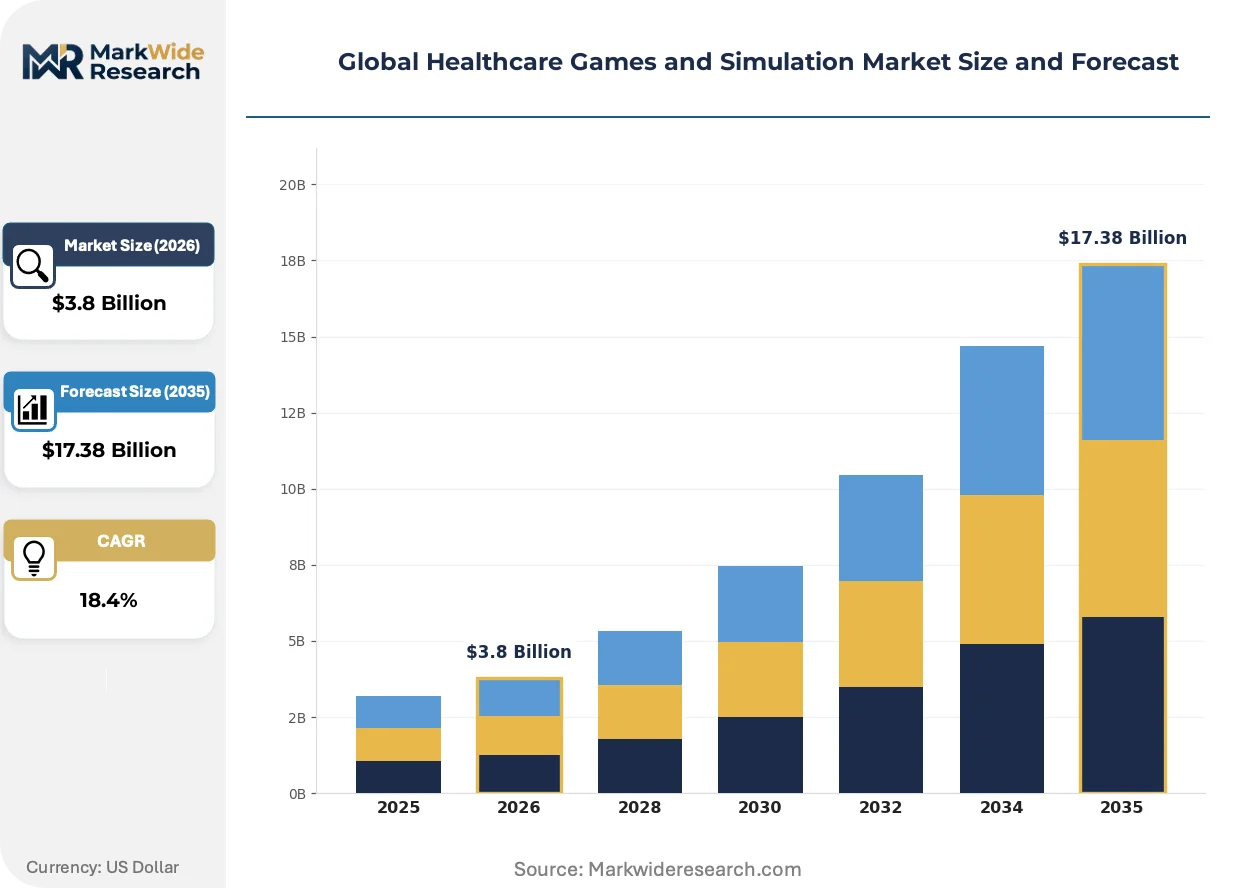
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.38 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Virtual Reality Simulators, Augmented Reality Trainers, Serious Games, 3D Visualization Tools Application: Medical Training, Surgical Planning, Patient Education, Rehabilitation Therapy End User: Medical Schools, Research Institutes, Physical Therapy Centers, Diagnostic Labs Deployment: Cloud-Based Platforms, On-Premise Solutions, Mobile Applications, Desktop Software |
| Companies Covered | Surgical Science, Simulab Corporation, CAE Inc., Kyoto Kagaku, Limbs & Things, Laerdal Medical, 3D Systems, Mentice, Gaumard Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Healthcare Games and Simulation Market Strategic Shifts & Innovations
A fundamental shift from static, one-size-fits-all training modules to dynamic, personalized learning experiences is underway. The convergence of artificial intelligence with immersive simulation technologies is creating platforms that can adapt to individual user performance in real time.
AI-driven adaptive learning engines are a pivotal product evolution. These systems analyze user performance during a simulated procedure to identify skill gaps and automatically adjust the difficulty or focus of subsequent scenarios. Medical schools and surgical residency programs are adopting this technology to accelerate the learning curve for trainees. This technology is hybridizing standardized training protocols with personalized, real-time feedback, creating a new model of dynamic skills assessment.
The European Union's Medical Device Regulation (MDR) is a significant policy driver. It imposes stringent requirements for clinical evidence and post-market surveillance, effectively mandating proof of user proficiency for complex devices. This regulation elevates simulation tools to a critical role for demonstrating and documenting clinician competency. Consequently, device manufacturers are increasingly bundling validated simulation training with their product rollouts, especially for robotic surgery systems.
A transition from large, one-time capital expenditures to subscription-based, cloud-hosted software-as-a-service (SaaS) models is gaining momentum. This shift in buying behavior lowers the financial barrier to entry, enabling smaller clinics and teaching hospitals to access advanced simulators. This trend is most visible in the United States and Western Europe, where mature cloud infrastructure and demand for scalable training solutions facilitate the adoption of subscription services.
Global Healthcare Games and Simulation Market Segmentation
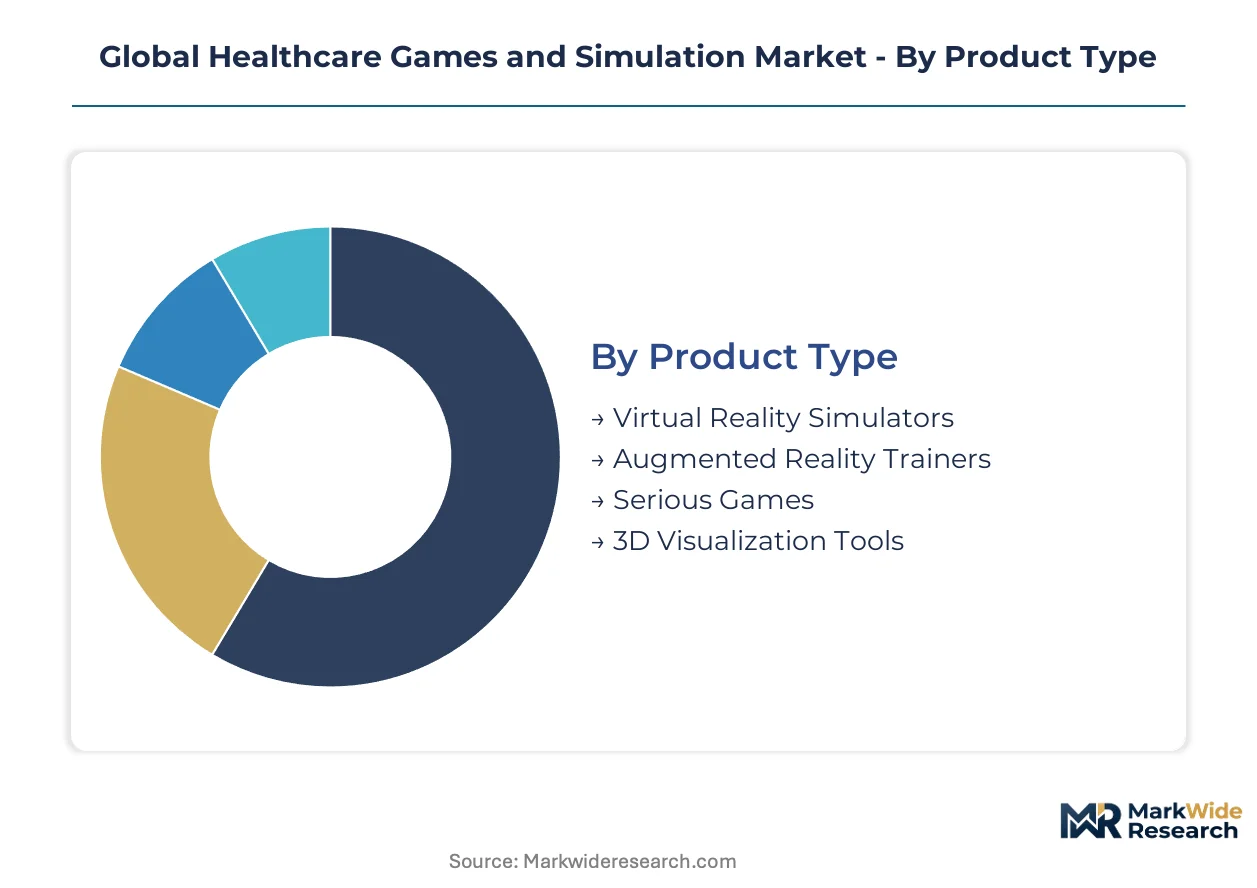
The market for healthcare games and simulation is diverse, structured by product type, application, end-user, and deployment models. Understanding these distinct segments reveals specific demand patterns and technological preferences. This granular analysis guides strategic development and market penetration efforts across various healthcare domains.
Product Type:
The product type segmentation delineates the range of interactive digital tools available, from highly immersive virtual environments to focused 3D anatomical models that replicate clinical scenarios.
- Virtual Reality Simulators:These systems replicate clinical environments with high fidelity, often integrating haptic feedback for realistic procedural training. Demand concentrates in surgical specialties within major academic medical centers in the United States, driven by the need for risk-free complex procedure practice.
- Augmented Reality Trainers:These tools overlay digital information onto the real world, enhancing procedural guidance or anatomical understanding in real-time. Adoption is gaining traction in medical device training and remote assistance scenarios, particularly for new product rollouts in Europe due to MDR requirements.
- Serious Games:Gamified learning experiences designed to educate users on medical concepts, patient care protocols, or disease management strategies.
- 3D Visualization Tools:These provide interactive anatomical models and procedural walkthroughs for foundational medical education and complex surgical planning.
Established volume favors Virtual Reality Simulators; emerging adoption favors Augmented Reality Trainers.
Application:
The application segmentation highlights the primary clinical and educational purposes for which these simulation technologies are deployed across the healthcare spectrum, addressing specific training and operational needs.
- Medical Training:This encompasses curriculum-based education for students and continuous professional development for practicing clinicians, covering a broad range of skills. This remains the largest application, with significant procurement by medical schools and residency programs globally, particularly in North America.
- Surgical Planning:This utilizes simulation to rehearse complex surgical procedures, visualize patient-specific anatomy, and optimize operative strategies before entering the operating room. This application is expanding rapidly in advanced surgical centers in Germany and Japan, driven by the increasing complexity of minimally invasive techniques.
- Patient Education:Engages patients through interactive simulations to explain conditions, treatment protocols, and self-management strategies for improved health literacy.
- Rehabilitation Therapy:Leverages games and simulations to provide engaging, repetitive exercises for physical and cognitive recovery in a controlled environment.
Medical Training holds the largest share, while Surgical Planning exhibits the steepest expansion trajectory.
End User:
The end-user segmentation identifies the primary institutional and organizational consumers driving demand for healthcare simulation platforms and tools, each with distinct procurement priorities and usage patterns.
- Medical Schools:These institutions integrate simulation into core curricula for preclinical and clinical training, emphasizing foundational skills and procedural competency. Medical schools represent a foundational demand base, particularly for high-fidelity simulators in the United States and Canada.
- Research Institutes:These entities employ simulation for developing new medical techniques, validating device efficacy, and conducting advanced physiological studies. Demand here is often tied to grant funding and specialized project requirements, particularly in European research hubs.
- Physical Therapy Centers:These centers adopt interactive systems for patient assessment, exercise guidance, and objective progress tracking in rehabilitation.
- Diagnostic Labs:These facilities utilize simulation for training technicians on complex equipment operation and interpretation of diagnostic results, ensuring accuracy.
Medical Schools are the traditional market anchor, with Research Institutes showing significant emerging potential.
Deployment:
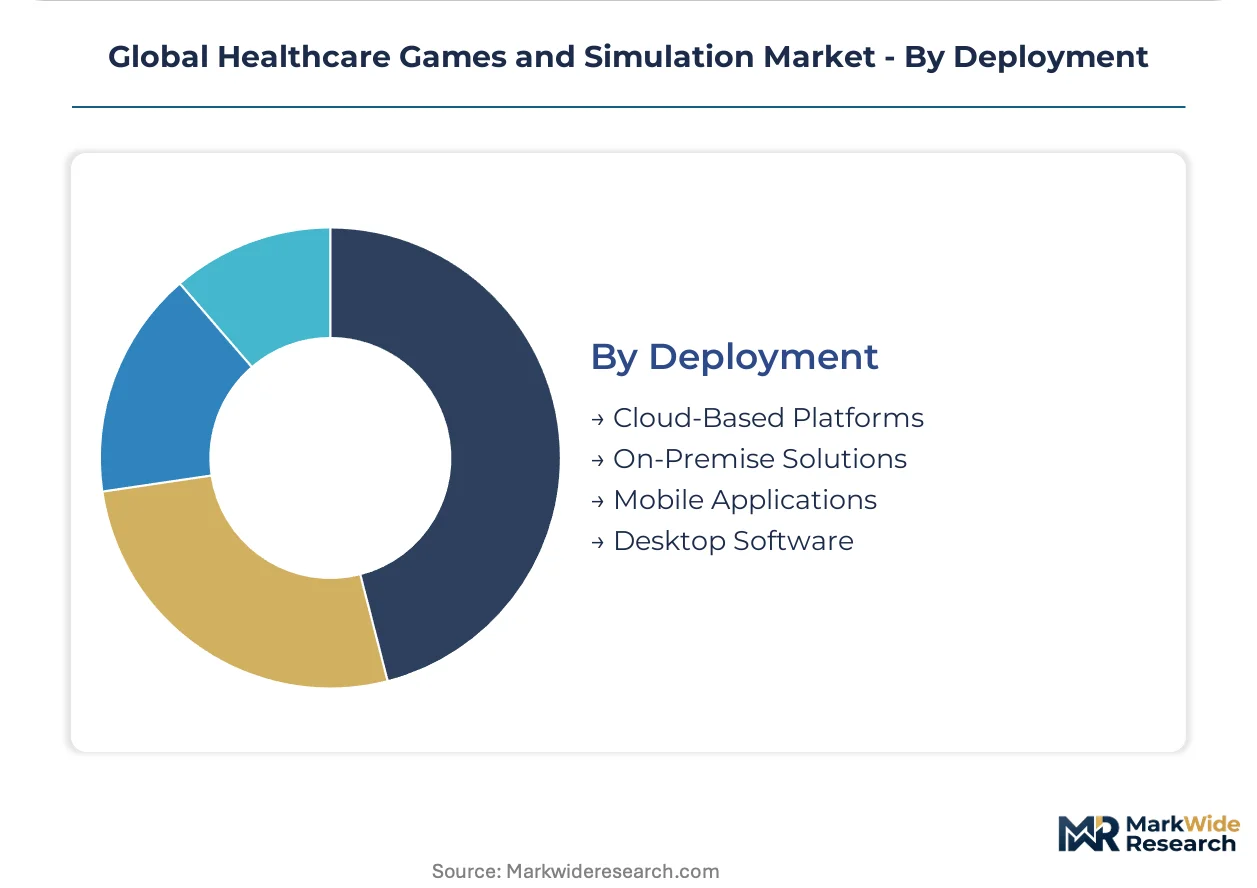
The deployment segmentation categorizes the architectural models through which healthcare simulation software and content are delivered and accessed by end-users, influencing cost structures and accessibility.
- Cloud-Based Platforms:These offer scalable, subscription-based access to simulation content and adaptive learning engines, reducing upfront capital expenditure for institutions. This model is gaining significant traction in Western Europe and the United States, driven by IT infrastructure maturity and remote access needs.
- On-Premise Solutions:These involve direct installation of software and hardware within an institution's own IT infrastructure, providing maximum control and data security. Large hospitals and specialized training centers with stringent data compliance requirements, such as those in Germany, often prefer this model.
- Mobile Applications:These provide accessible, portable simulation tools and learning modules for on-the-go education and quick reference for healthcare professionals.
- Desktop Software:These are traditional standalone applications installed on individual computers, suitable for specific tasks or offline training environments.
The shift towards Cloud-Based Platforms is reshaping procurement, while On-Premise Solutions maintain their niche.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory frameworks are significantly influencing the geographic distribution of healthcare simulation demand. The European Union's Medical Device Regulation (MDR) mandates advanced proficiency validation, accelerating adoption across member states. This regulatory imperative drives procurement in key European markets.
United States
Academic medical centers and research institutes drive substantial demand for healthcare simulation tools. The US FDA's guidance on software as a medical device (SaMD) influences product development and market access. Major academic medical centers in Boston and New York City lead procurement for advanced training and research applications.
Germany
Advanced surgical centers in Germany are rapidly expanding their adoption of simulation for complex minimally invasive techniques. The EU's Medical Device Regulation (MDR) necessitates rigorous validation of device proficiency for clinical use. Specialized training centers in Munich and Berlin prefer on-premise solutions for robust data security.
Japan
Advanced surgical centers in Japan exhibit high demand for simulation in complex minimally invasive procedures. The Pharmaceuticals and Medical Devices Agency (PMDA) regulates the validation and approval of medical devices, impacting simulation tools. Medical universities in Tokyo and Osaka are key adopters for curriculum-based training.
India
Modernizing healthcare systems and a growing professional workforce drive significant demand for medical education tools in India. The Central Drugs Standard Control Organization (CDSCO) regulates medical devices, influencing market entry for simulation platforms. Major medical institutions in Bangalore and Mumbai are expanding their simulation-based training programs.
Canada
Medical schools in Canada maintain foundational demand for high-fidelity simulation tools in core curricula. Health Canada provides regulatory oversight for medical devices, ensuring product safety and efficacy. University hospitals in Toronto and Montreal integrate advanced simulators for both student training and continuing professional development.
Global Healthcare Games and Simulation Market Key Industry Players
On the supply side, the industry is characterized by a blend of established technology firms and specialized medical simulation providers. The competitive landscape includes large entities leveraging broad engineering expertise, alongside niche innovators focusing on specific clinical areas. Strategic archetypes include comprehensive ecosystem providers, procedural specialists, and emerging cloud-native platforms. Companies are pursuing portfolio diversification and strategic partnerships to integrate advanced immersive technologies.
Specialists in procedural simulation include Surgical Science, which focuses on robotic and laparoscopic surgical training systems. CAE Inc. represents a comprehensive ecosystem provider, leveraging its extensive simulation heritage from other sectors to offer broad healthcare training platforms globally. Laerdal Medical occupies a position as a leading provider of emergency care and resuscitation training solutions, particularly for resuscitation and patient safety. These organizations exemplify the market's segmentation between broad platform offerings and highly focused clinical specializations, each addressing distinct user needs and evolving regulatory requirements.
| Leading Market Players |
|---|
| Surgical Science |
| Simulab Corporation |
| CAE Inc. |
| Kyoto Kagaku |
| Limbs & Things |
| Laerdal Medical |
| 3D Systems |
| Mentice |
| Gaumard Scientific |
| Others |
Cost & Logistics Intelligence
Underutilized simulation infrastructure, particularly in developing economies, drives aggressive pricing from providers and influences institutional procurement strategies. This also impacts the pace of new technology adoption across different healthcare segments.
Pricing Analysis
Certification level (FDA-grade, CE-marked) creates the primary spread across healthcare simulation pricing. Subscription-based, cloud-hosted SaaS models dominate, especially for advanced adaptive learning platforms. Quality grade of haptic feedback, fidelity of 3D visualization, and after-sales support significantly influence pricing. Pricing pressure stems from the increasing availability of lower-cost, cloud-based solutions. Smaller institutions and educational facilities are most price-sensitive, while major academic medical centers show lower sensitivity for high-fidelity surgical simulators.
Supply Chain Analysis
Specialized haptic components and high-resolution display panels form critical upstream feedstock for advanced simulation hardware. Component manufacturing concentrates in South Korea, Taiwan, and China. The market relies on specialized sensors, graphics processing units, and robust software development kits. Single-source vulnerability for niche haptic technologies presents a structural risk. Distribution runs through direct sales teams for large institutional contracts and online marketplaces for software licenses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires a robust substitution defense against traditional cadaver labs and low-fidelity training methods. Incumbents must navigate the threat of cheaper, less immersive digital alternatives gaining traction.
For Market Incumbents: Entrench market position through strategic partnerships with major medical device manufacturers. Develop bundled offerings that integrate simulation training with new device rollouts, especially for robotic surgery systems. Invest in advanced AI-driven adaptive learning pathways to differentiate from basic simulators. The threat of generic, unvalidated simulation software is real; R&D in haptic feedback and physiological modeling serves as a critical lever.
For New Entrants and Emerging Players: Build out niche expertise in underserved clinical applications like mental health virtual patient interactions. Target emerging economies such as India and Brazil, focusing on scalable, cloud-based solutions with lower initial investment. A direct-to-consumer or direct-to-small-clinic SaaS model offers a penetrable entry point. Focus on mobile applications for basic training modules.
For Investors and Strategic Acquirers: Long-term, this sits as a technology-enabled healthcare education play because regulatory mandates ensure sustained demand for proficiency validation. Target mid-sized specialists with strong intellectual property in AI-driven adaptive learning or high-fidelity haptic interfaces. The signal to watch is the expansion of MDR-like regulations globally. Focus on companies with robust cloud infrastructure.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop AI-Driven Adaptive Learning | Personalizes training, accelerates skill acquisition for clinicians, and optimizes learning efficiency. |
| Pursue Medical Device Manufacturer Partnerships | Bundles validated simulation training with new device rollouts, ensuring regulatory compliance and market access. |
| Expand Cloud-Based SaaS Offerings | Lowers financial barriers for smaller institutions and facilitates remote access to advanced training tools. |
| Invest in Haptic Feedback R&D | Enhances realism of procedural training, improving clinical acceptance, and reducing patient risk. |
| Target Emerging Market Expansion | Addresses modernization needs in healthcare systems and trains a growing professional workforce in regions like India. |
Research Approach
A standing panel of clinical educators, biomedical engineers, hospital procurement managers, and regulatory affairs specialists provided ongoing calibration for market assumptions. This approach combined in-depth primary interviews with rigorous secondary validation. Secondary data sources included regulatory body guidance (US FDA, EU MDR, PMDA), academic publications, and industry association reports. Bottom-up and top-down triangulation ensured data consistency and accuracy across all segments.
Scenario-bracketing across conservative, base, and aggressive growth trajectories informed the forecast framework over the projection horizon. The model segmented the market by product type (VR simulators, AR trainers), application (medical training, surgical planning), end-user (medical schools, research institutes), and deployment model (cloud-based, on-premise). Compound annual growth rates were derived through a proprietary regression analysis factoring in technology adoption curves. Key forecast inputs included regulatory mandate timelines and immersive technology hardware costs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by large tech conglomerates or specialized medical device firms would shift outcomes. Forecasts reflect assumptions regarding technological advancements and regulatory stability. Unforeseen geopolitical events or rapid shifts in healthcare funding represent risk factors. Cross-checking against institutional procurement budgets is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Simulation and Training
Military Simulation Software Market
Simulation and Training
Simulators Market
Simulation and Training
Live Laser-Based Training and Simulation Platforms Market
Simulation and Training
Civil Aerospace Simulation and Training Market
Simulation and Training
Military Vehicles and Aircraft Simulations Market
Simulation and Training
Flight Simulator Market
Simulation and Training
RADAR Simulator Market
Simulation and Training
Military Simulation Virtual Training Market
Simulation and Training
Global Military Airborne Simulation and Training Market
Simulation and Training
Dynamic Flight Training Compartments Market
Simulation and Training
Military Aerospace Simulation and Training Market
Simulation and Training
Flight Simulation Training Device Market
Simulation and Training
Drone Simulator Market
Simulation and Training
Asia-Pacific Ship Bridge Simulators Market
Simulation and Training
Military Simulation and Training Market
Simulation and Training
UAV Flight Training and Simulation Market