
 RADAR Simulator Market | 2026-2036
RADAR Simulator Market Size, Share, and Industry Trends Forecast 2026-2036
RADAR Simulator Market Analysis
Pricing for high-fidelity threat emulation systems is decoupling from entry-level training modules as defense customers demand sovereign-source code and classified waveform libraries. L3Harris Technologies leverages its classified signal intelligence portfolio to anchor premium contract positions. Keysight Technologies competes through instrumentation-grade calibration chains that sustain metrological credibility across military test ranges. BAE Systems dominates UK and Australian sovereign programs through security-cleared engineering workforces.
A RADAR Simulator is a test and training apparatus that replicates electromagnetic propagation, target returns, and environmental clutter across frequency bands from L-band to W-band, enabling repeatable validation of sensor performance without live flight operations. The hardware segment retains the largest revenue pool due to radio-frequency front-end costs and thermal management subsystems, though software segments are expanding fastest as customers virtualize signal processing chains on commercial cloud infrastructure. FMCW technology leads in automotive and short-range defense applications, while pulsed architectures anchor long-range air surveillance training programs.
FAA certification requirements for flight simulator qualification shape commercial aerospace demand, while the US Department of Defense mandates Joint Simulation Environment interoperability for next-generation training procurement. EASA and national military airworthiness boards in France, Germany, and Italy enforce parallel standards that fragment vendor qualification pathways across European defense markets. Stakeholders must monitor whether software-only simulator vendors achieve equivalent accreditation status against hardware-in-the-loop baselines as procurement authorities revise technical acceptance criteria.
Market Dynamics
The migration toward software-defined radio architectures is compressing hardware procurement cycles while elevating sovereign-source code requirements as the primary vendor selection criterion across NATO defense agencies.
Growth Catalysts
- Joint Simulation Environment Mandate:The US Department of Defense requires interoperability certification for all next-generation training procurement, forcing modernization of legacy threat replication systems.
- Synthetic Training Environments:Distributed mission training protocols are expanding simulator deployment beyond traditional flight schools into forward-deployed operational units.
- Electronic Warfare Readiness:NATO member states are accelerating pilot training for contested electromagnetic spectrum operations, driving demand for advanced radar threat libraries.
Market Restraints
- Radio-Frequency Front-End Costs:Gallium nitride power amplifiers and precision timing subsystems account for disproportionate hardware expenditure, constraining budget-constrained procurement programs.
- Security-Cleared Workforce Scarcity:Engineering talent with both RF design expertise and national security clearance is concentrated in the United States and United Kingdom, limiting vendor expansion.
- EASA Fragmentation:Parallel military airworthiness standards across France, Germany, and Italy create redundant qualification pathways that extend vendor time-to-revenue.
Strategic Opportunities
- Cloud-Native Signal Processing:Virtualized radar emulation on commercial cloud infrastructure opens sovereign training programs to software-only vendors previously excluded from hardware-in-the-loop contracts.
- Automotive FMCW Adjacency:Frequency-modulated continuous-wave expertise developed for defense simulators transfers directly into autonomous vehicle sensor validation, creating dual-use revenue streams.
- Australian Sovereign Programs:The AUKUS security pact is accelerating domestic radar simulation capability building, offering first-mover positioning for vendors establishing security-cleared local engineering presence.
Industry Challenges
- Classified Waveform Licensing:Negotiating access to national signal intelligence libraries involves multi-year bilateral agreements between defense agencies and vendors, delaying product development timelines.
- Legacy Hardware Integration:Hybrid environments combining 1990s-era simulator racks with modern software-defined architectures create protocol mismatch and calibration drift during extended training exercises.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | RADAR Simulator Market |
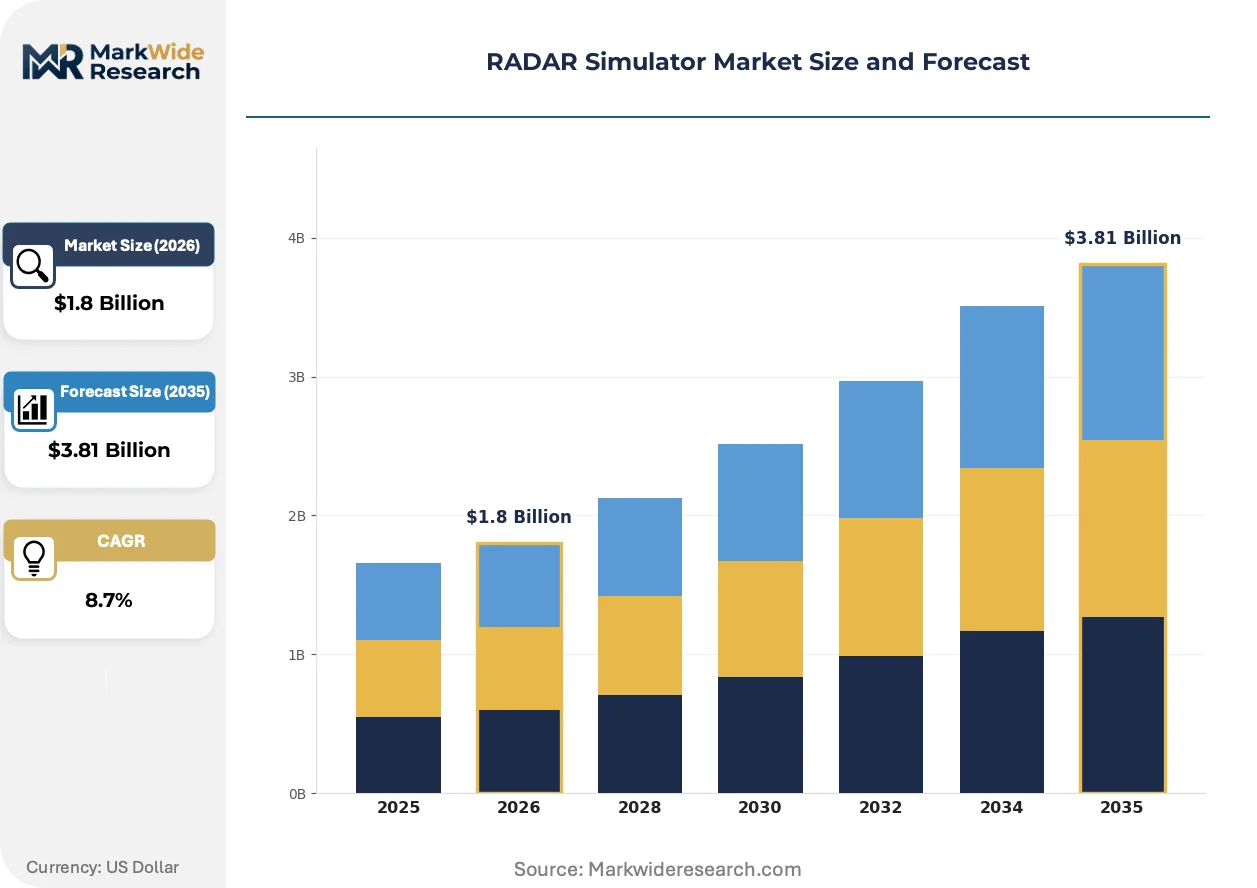
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Hardware, Hybrid, Add-on End User: Aerospace, Defense, Automotive, Research Institutions Technology: FMCW, Pulsed, Doppler, MIMO Application: Training, Testing, Development, Prototyping |
| Companies Covered | L3Harris Technologies, Inc., Keysight Technologies, Adacel Technologies Limited, Rockwell Collins, Inc., BAE Systems, Mercury Systems, Inc., CAE Inc., Textron Systems, RTX Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
RADAR Simulator Market Emerging Trajectories
Synthetic environments are displacing live-flight validation across military and commercial aviation, compressing the acceptable fidelity gap between simulated and operational radar returns.
Software-defined radio is decentralizing signal generation from centralized hardware racks to distributed computing nodes. Defense procurement agencies in the United States and United Kingdom are piloting containerized radar emulation workloads on tactical edge servers. This architecture is decentralizing threat simulation deployment from fixed training centers to expeditionary operational environments.
The EU AI Act's risk classification framework is extending to autonomous systems validation tools, including radar simulators used in unmanned platform development. Manufacturers must now document algorithmic transparency in target classification modules. European aerospace certification bodies are requiring explainable AI attestations for simulator-qualified flight training devices.
Defense customers are unbundling hardware acquisition from perpetual software maintenance, compressing contract renewal cycles from ten-year platforms to annual capability subscriptions. Original equipment manufacturers face margin compression as sovereign code requirements push military customers toward open-architecture middleware. This pattern is most visible in US Navy distributed training contracts, where modular software procurement now outpaces integrated system awards.
RADAR Simulator Market Segmentation
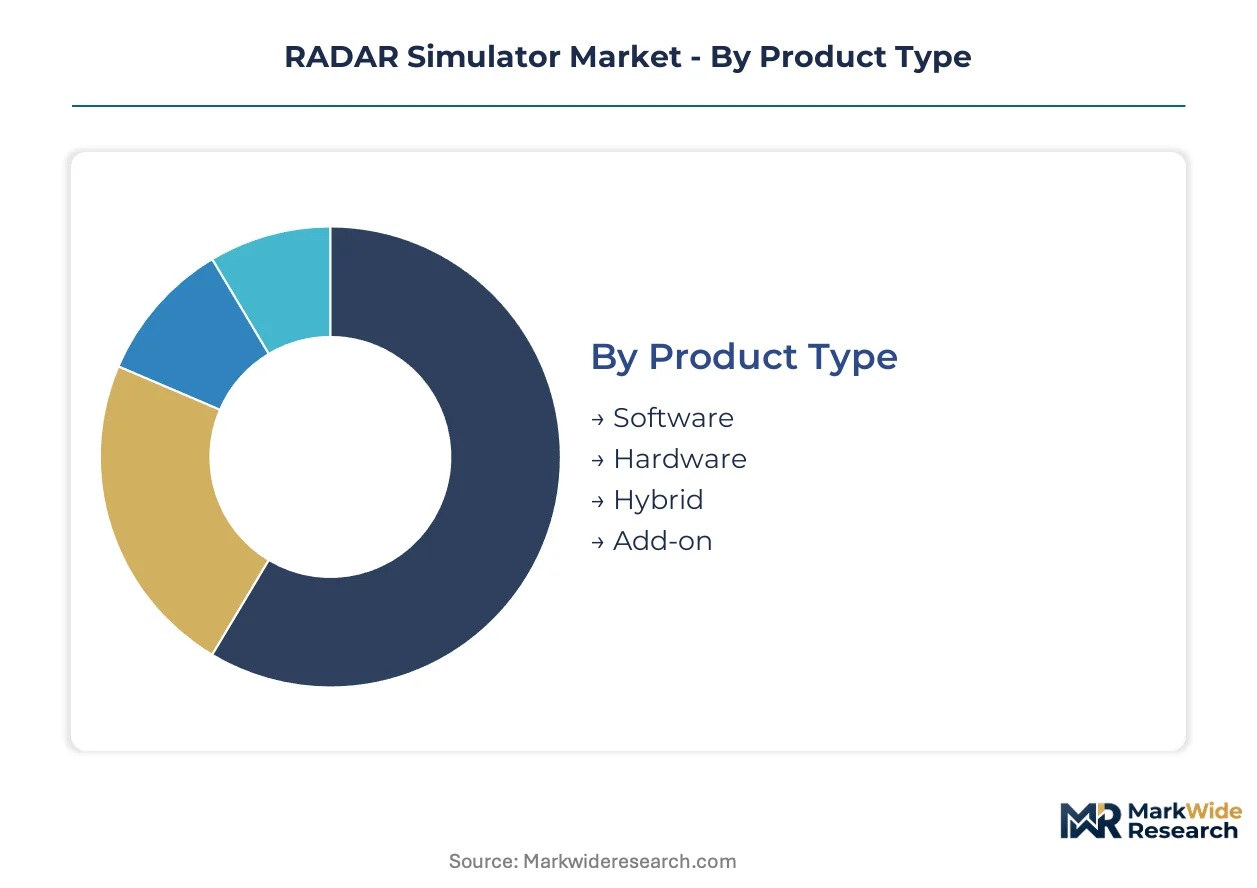
Segmentation in the RADAR Simulator Market reveals divergent capital requirements and procurement rhythms across product architectures. Defense agencies prioritize sovereign-code software investments, while commercial aerospace customers anchor demand in hardware-in-the-loop fidelity.
Product Type:
Hardware configurations demand the heaviest upfront capital deployment due to gallium nitride power amplifiers and precision thermal management subsystems.
- Hardware:Radio-frequency front-end assemblies with L-band to W-band coverage require specialized foundry capacity and extended calibration protocols. US Department of Defense distributed mission training programs absorb the majority of procurement volume, though gallium nitride component shortages constrain delivery timelines.
- Software:Containerized signal processing chains virtualize threat emulation on commercial cloud infrastructure. NATO member states are accelerating sovereign-source code mandates, elevating vendors with classified waveform libraries into premium contract positions.
- Hybrid:Combines legacy rack-mounted RF generation with modern software-defined radio interfaces for protocol bridging.
- Add-on:Modular waveform libraries and environmental clutter databases extend existing simulator baselines without full system replacement.
Hardware absorbs the bulk of installed capacity; software is expanding most quickly.
End User:
Defense procurement operates on classified security clearance requirements that filter vendor participation, while automotive validation follows commercial automotive safety integrity levels.
- Defense:Electronic warfare readiness programs across NATO alliance members drive demand for contested spectrum training. Joint Simulation Environment interoperability mandates from the US Department of Defense force modernization of legacy threat replication systems.
- Aerospace:FAA certification requirements for flight simulator qualification shape commercial demand, with EASA and national military airworthiness boards enforcing parallel standards that fragment vendor pathways.
- Automotive:Autonomous vehicle sensor validation transfers FMCW expertise from defense applications into commercial roadworthiness testing.
- Research Institutions:Academic and government laboratory procurement focuses on instrumentation-grade calibration chains for peer-reviewed sensor performance studies.
Defense commands the largest committed procurement budgets; automotive is climbing the fastest as ADAS deployment accelerates.
Technology:
Pulse repetition frequency and waveform agility differentiate competitive positioning across range-resolution tradeoffs.
- FMCW:Frequency-modulated continuous-wave architectures dominate short-range applications with superior range resolution and lower peak power requirements. Automotive ADAS validation and close-in defense training programs concentrate demand.
- Pulsed:Long-range air surveillance training relies on high peak power and coherent integration intervals. BAE Systems anchors UK and Australian sovereign programs through security-cleared engineering workforces.
- Doppler:Velocity measurement precision supports moving target indication and weather radar training protocols.
- MIMO:Multiple-input multiple-output configurations enable angle-of-arrival estimation for phased array calibration.
Pulsed systems retain the deepest installed base; FMCW is gaining share fastest on automotive adjacency.
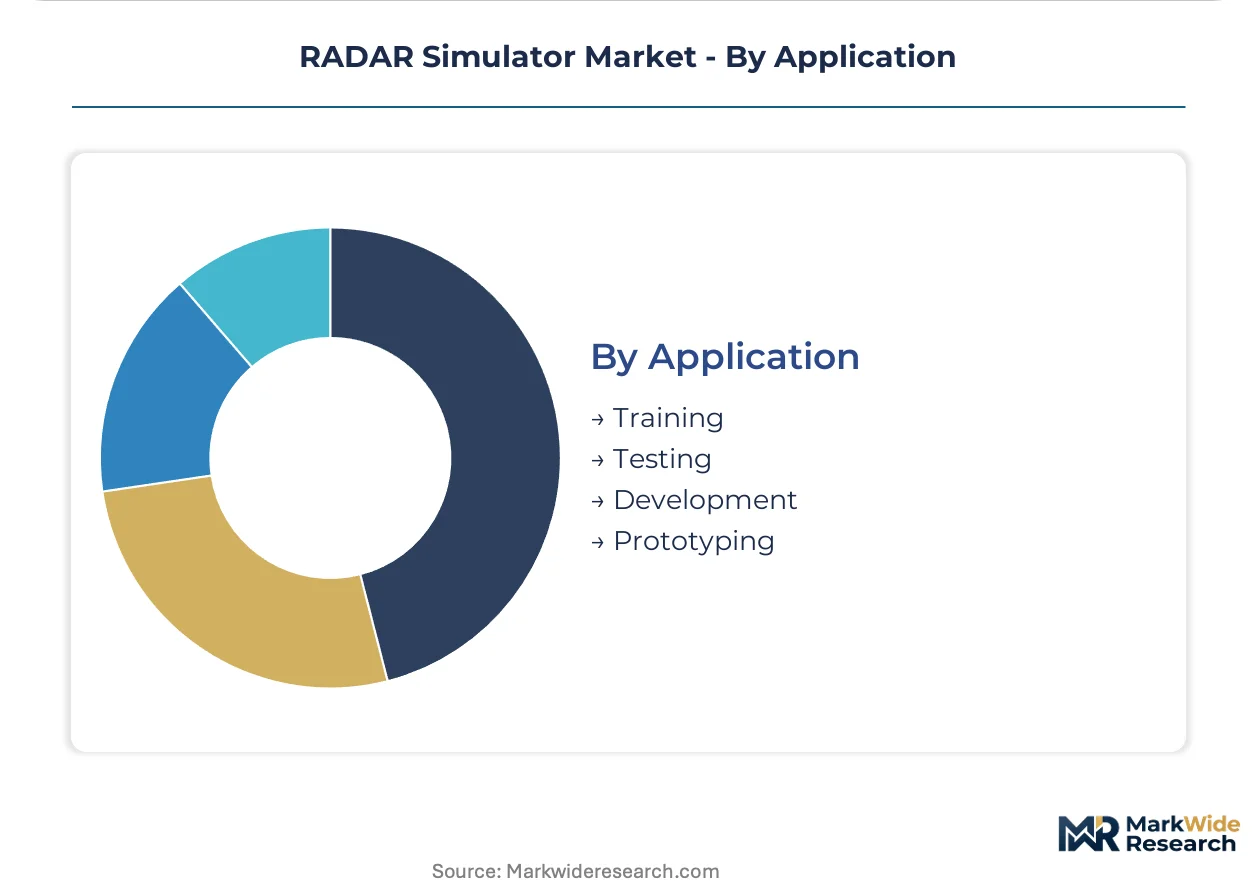
Application:
Training applications demand real-time human-in-the-loop fidelity, while testing and development prioritize measurement repeatability and automation interfaces.
- Training:Pilot and operator proficiency programs require low-latency visual and motion cueing synchronized with radar returns. The US Navy distributes simulator deployments from fixed flight schools into forward-deployed operational units.
- Testing:Metrological credibility across military test ranges depends on instrumentation-grade calibration chains. Keysight Technologies competes through traceable measurement uncertainty budgets.
- Development:Algorithmic target classification modules for autonomous platforms now require explainable AI attestations under EU AI Act risk classification frameworks.
- Prototyping:Rapid iteration on radar signal processing architectures favors software-defined radio reconfigurability over fixed hardware baselines.
Training captures the majority of defense procurement cycles; development is expanding most quickly on unmanned platform program growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Washington-Baltimore corridor anchors North American defense technology concentration, hosting classified engineering facilities that supply Joint Simulation Environment-certified systems to the Department of Defense and allied NATO procurement agencies.
United States
The Department of Defense mandates Joint Simulation Environment interoperability for all next-generation training procurement, accelerating modernization of legacy threat replication systems. FAA certification requirements for flight simulator qualification shape parallel commercial aerospace demand. The Pentagon's distributed mission training protocols are expanding simulator deployment from fixed flight schools into forward-deployed operational units across multiple service branches.
United Kingdom
Security-cleared engineering workforces concentrate around Farnborough and the Bristol aerospace cluster, anchoring sovereign radar simulation capability for Royal Air Force electronic warfare readiness programs. The UK Ministry of Defence enforces national military airworthiness standards that run parallel to EASA frameworks, creating specialized vendor qualification pathways. BAE Systems dominates domestic procurement through cleared personnel access to classified waveform libraries.
Germany
The Bundeswehr accelerates pilot training for contested electromagnetic spectrum operations, driving demand for advanced radar threat libraries compatible with NATO interoperability standards. The KBA and national military airworthiness boards enforce technical acceptance criteria that fragment vendor qualification pathways across European defense markets. Munich and the Bavarian aerospace corridor host engineering centers developing synthetic training environments for Eurofighter Typhoon programs.
Australia
The AUKUS security pact accelerates domestic radar simulation capability building, offering first-mover positioning for vendors establishing security-cleared local engineering presence. The country's defense procurement agency prioritizes sovereign-source code requirements in alignment with Five Eyes intelligence sharing protocols. Adelaide and the Woomera Test Range host concentrated development of autonomous platform validation systems requiring explainable AI attestations.
France
ANSM and national military airworthiness standards enforce parallel certification pathways that extend vendor time-to-revenue for radar simulator qualification. The Direction Générale de l'Armement prioritizes electronic warfare readiness programs requiring classified signal intelligence access for threat library development. Toulouse and the Paris-Saclay cluster concentrate aerospace engineering talent developing synthetic environments for Rafale fighter training protocols.
RADAR Simulator Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across divergent procurement models. The market structure consolidates around defense primes with classified clearance access and instrumentation specialists with metrological credibility. Three archetypes dominate: sovereign-code software vendors, hardware-in-the-loop integrators, and dual-use automotive-defense specialists. Strategic moves center on security-cleared workforce acquisition and cloud-native architecture partnerships that bypass traditional RF front-end procurement cycles.
Within the defense prime tier, L3Harris Technologies and BAE Systems occupy positions anchored by classified signal intelligence portfolios and security-cleared engineering workforces. Keysight Technologies exemplifies the instrumentation-grade specialist archetype, competing through traceable calibration chains that sustain metrological credibility across military test ranges. These three companies represent distinct competitive vectors: sovereign-code dominance, cleared-personnel scale, and measurement science credibility.
| Leading Market Players |
|---|
| L3Harris Technologies, Inc. |
| Keysight Technologies |
| Adacel Technologies Limited |
| Rockwell Collins, Inc. |
| BAE Systems |
| Mercury Systems, Inc. |
| CAE Inc. |
| Textron Systems |
| RTX Corporation |
| Others |
Supply Flow & Price Mechanics
Sovereign-backed defense primes and private-equity-rolled-up RF component specialists anchor supply-side concentration, translating gallium nitride foundry scarcity into sustained pricing power for threat emulation systems while compressing margins for software-only entrants lacking classified waveform portfolios.
Pricing Analysis
Value-based pricing tied to Joint Simulation Environment certification outcomes anchors contract structures, with three-tier pricing stratification across sovereign-code premium, instrumentation-grade standard, and entry-level training economy levels. Price differentiation hinges on security clearance depth and FAA/EASA dual-certification status. Cost compression in the economy tier intensifies as open-architecture middleware commoditizes basic threat libraries. Defense procurement agencies show lowest price sensitivity; commercial aerospace flight schools exhibit highest.
Supply Chain Analysis
Direct-to-defense-agency channels handle classified system integration, while tiered distributor networks serve commercial aerospace validation programs. Gallium nitride wafer supply concentrates in the United States, Japan, and Germany; precision timing subsystems draw from Swiss and US sources. Radio-frequency front-end assemblies rest on ceramic substrate and thermal management component flows. Single-source vulnerability in ITAR-controlled semiconductor foundries creates supply chain risk. Distribution runs through cleared-systems integrators with national security facility accreditation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The RADAR Simulator Market functions as a cost-of-compliance story where EU AI Act explainable AI attestations and FAA Joint Simulation Environment mandates erect regulatory moats favoring incumbents with pre-positioned certification infrastructure.
For Market Incumbents: Anchor classified waveform library depth against cloud-native software entrants by accelerating sovereign-source code partnerships with Five Eyes signal intelligence agencies. Expand security-cleared engineering presence in Australia under AUKUS protocols to preempt AUKUS-aligned procurement localization. Vertical integration into gallium nitride RF front-end supply buffers foundry allocation risk. For New Entrants and Emerging Players: Capture automotive FMCW validation adjacency where defense simulator expertise transfers into autonomous vehicle sensor roadworthiness testing without classified clearance barriers. Target Germany's Eurofighter Typhoon synthetic training upgrade cycle as the most penetrable European defense segment. Pursue software-only containerized deployment models that bypass hardware-in-the-loop qualification timelines. For Investors and Strategic Acquirers: Distressed-cycle entries favor instrumentation-grade calibration specialists with metrological credibility and recurring service revenue in the United States and United Kingdom. Long-term viability centers on dual-use defense-autonomous vehicle positioning with explainable AI compliance infrastructure. Monitor Joint Simulation Environment interoperability mandate acceleration as inflection signal for consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign-Code Partnership | Five Eyes signal intelligence access locks in premium defense contract positioning against open-architecture competitors. |
| Cloud-Native Architecture Migration | Containerized radar emulation on tactical edge servers displaces fixed training center hardware procurement cycles. |
| Security-Cleared Workforce Expansion | AUKUS-aligned Australian engineering presence captures AUKUS sovereign capability building procurement preference. |
| Automotive FMCW Adjacency | Defense simulator expertise transfers into autonomous vehicle ADAS validation under commercial automotive safety integrity levels. |
| EU AI Act Compliance Infrastructure | Explainable AI attestations for target classification modules preempt European unmanned platform development contract eligibility. |
Methodological Framework
Multi-period observation of Joint Simulation Environment certification timelines, gallium nitride component delivery schedules, and sovereign-source code procurement patterns anchored the trend analysis, supplemented by interviews with defense procurement officers, flight simulator qualification engineers, RF subsystem program managers, and electronic warfare training directors. Secondary validation drew from FAA flight simulator qualification databases, Department of Defense contract award disclosures, EASA certification registries, and customs records of gallium nitride semiconductor trade flows. Bottom-up segment sizing triangulated against top-down defense training budget appropriations.
Input-output matrices modeled hardware, software, hybrid, and add-on product types against defense, aerospace, automotive, and research institution end users across pulsed, FMCW, Doppler, and MIMO technology configurations. CAGRs derived from segment-level growth rate reconciliation across training, testing, development, and prototyping applications. Forecast inputs incorporated Joint Simulation Environment interoperability mandate implementation velocity and EU AI Act risk classification enforcement progression.
The model holds under steady defense procurement appropriation and gallium nitride foundry capacity expansion; deviation in ITAR restriction tightening or AUKUS localization acceleration would shift segment growth trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Simulation and Training
Global Military Airborne Simulation and Training Market
Simulation and Training
Drone Simulator Market
Simulation and Training
Police and Military Simulation Training Market
Simulation and Training
Military Training Aircraft Market
Simulation and Training
Helicopter Simulator Market
Simulation and Training
Asia-Pacific Civil Aviation Simulators Market
Simulation and Training
Europe Flight Training and Simulation Market
Simulation and Training
Satellite Simulator Market
Simulation and Training
Middle East Civil Aviation Flight Training and Simulation Market
Simulation and Training
Civil Aviation Simulator Market
Simulation and Training
Pilot Training Market
Simulation and Training
Flight Simulation Training Device Market
Simulation and Training
Middle East and Africa Ship Bridge Simulators Market
Simulation and Training
North America Simulator Windows and Simulator Skylights Market
Simulation and Training
Live Laser-Based Training and Simulation Platforms Market
Simulation and Training
Military Vehicles and Aircraft Simulations Market