
 Dynamic Flight Training Compartments Market | 2026-2036
Dynamic Flight Training Compartments Market Size, Share, and Industry Trends Forecast 2026-2036
Dynamic Flight Training Compartments Market Insights
Software-defined scenario generation is repositioning how training value gets captured, shifting revenue from hardware sales toward recurring content and fleet-specific curriculum updates. CAE Inc. leverages its installed base of full-flight simulators to lock in long-term service contracts across airline customers. L3Harris Technologies anchors military aviation training through its dominance in high-G cockpit systems for defense end users. Thales Group differentiates via integrated mission rehearsal platforms that combine live, virtual, and constructive training architectures.
Dynamic flight training compartments are enclosed, motion-capable synthetic environments that replicate aircraft cockpit dynamics, visual fields, and control loading with fidelity sufficient for regulatory credit toward type ratings and recurrent proficiency checks. These systems employ hexapod motion bases, collimated visual displays, and computational aerodynamic models to induce pilot spatial disorientation and procedural muscle memory without airborne risk. Full flight simulators command the largest revenue share due to their Level D certification status and mandatory role in airline qualification pathways, while virtual reality trainers represent the fastest-expanding segment as hardware costs drop and regulatory acceptance of virtual reality training devices broadens. Artificial intelligence integration within motion cueing algorithms is concentrating margin pools among vendors capable of real-time aerodynamic parameter adjustment.
FAA Part 60 standards and EASA CS-FSTD regulations govern simulator qualification levels, directly determining which training hours count toward commercial and military certification and thus which hardware configurations airlines and defense buyers can justify. The EU AI Act and emerging FAA guidance on machine learning in flight training systems are beginning to shape algorithm transparency requirements for adaptive training scenarios. Stakeholders must monitor how rapidly regulators extend credit toward mixed-reality platforms versus traditional full-flight devices, as this boundary will determine capital allocation between established simulator fleets and emerging virtual reality trainer deployments.
Market Dynamics
Regulatory credit allocation between full-flight simulators and emerging virtual reality training devices is restructuring capital deployment across airline and defense training budgets, compressing hardware replacement cycles while elevating software and content monetization.
Growth Catalysts
- FAA Part 60 Level D mandates:Airlines must complete type rating and recurrent checks in certified full-flight simulators, locking in replacement demand for aging hexapod platforms across US carrier fleets.
- EASA CS-FSTD regulatory harmonization:Cross-border training credit recognition enables European low-cost carriers to centralize simulator resources in Poland and Spain, reducing per-pilot training costs.
- Artificial intelligence motion cueing:Real-time aerodynamic parameter adjustment improves spatial disorientation fidelity, allowing shorter training sessions to achieve equivalent proficiency outcomes.
Market Restraints
- Motion base actuator supply concentration:German and Italian electromechanical component suppliers control hexapod servo valve production, creating input bottlenecks for simulator OEMs.
- Visual display collimation complexity:Laser phosphor and LED dome systems require precision optical alignment that extends manufacturing lead times and elevates field service costs.
- EU AI Act algorithm transparency requirements:Adaptive training scenarios using machine learning must document decision pathways, adding compliance overhead to software development cycles.
Strategic Opportunities
- India DGCA regulatory pathway expansion:The country's national aviation regulator is evaluating virtual reality training device credits for ab initio pilot programs, opening hardware deployment at flight schools.
- Live-virtual-constructive mission rehearsal convergence:Defense end users demand integrated platforms combining physical cockpits with synthetic battlespace networks, unifying procurement across training and operational units.
- Cloud-based scenario distribution:Airlines seek fleet-specific curriculum updates delivered over secure networks, shifting revenue from capital equipment toward recurring content subscriptions.
Industry Challenges
- Level D certification timeline compression:Hardware qualification cycles under FAA and EASA now require extended documentation of software version control, delaying revenue recognition for new simulator deliveries.
- Electromechanical technician scarcity:Maintenance of hexapod motion bases demands specialized hydraulic and servo control expertise that aviation training centers struggle to retain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dynamic Flight Training Compartments Market |
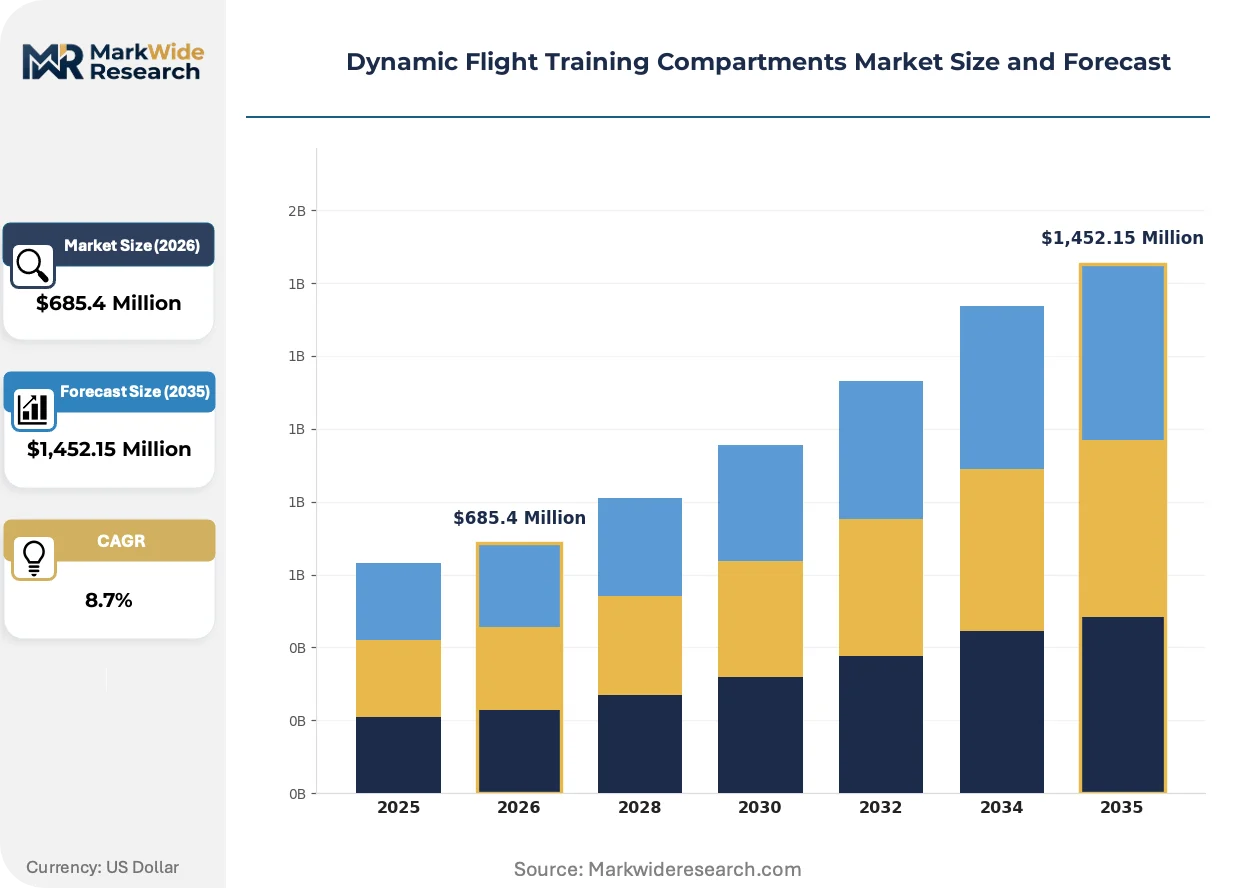
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,452.15 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Full Flight Simulators, Flight Part Task Trainers, Virtual Reality Trainers, Fixed Base Simulators Technology: Augmented Reality, Motion Cueing, Haptic Feedback, Artificial Intelligence Application: Commercial Pilot Training, Military Aviation Training, Helicopter Training, Drone Operation Training End User: Flight Schools, Defense Organizations, Unmanned Vehicle Operators, Pilot Training Centers |
| Companies Covered | CAE Inc., FlightSafety International, TRU Simulation + Training, L3Harris Technologies, Thales Group, Lockheed Martin, Northrop Grumman, Leonardo S.p.A., Textron Aviation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dynamic Flight Training Compartments Market Trends and Innovations
Software-defined architectures are displacing fixed-function hardware across training platforms, enabling rapid scenario reconfiguration and collapsing the boundary between simulator categories previously treated as distinct capital assets.
Extended reality headsets with inside-out tracking and varifocal displays are unifying visual and instrument panel fidelity previously split between dome projection and physical cockpit builds. Regional airlines in Australia and Scandinavia are piloting mixed-reality recurrent training to reduce travel to centralized simulator centers. This convergence is compressing the addressable market for mid-tier flight training devices by enabling single-platform flexibility across rating types.
The EU AI Act's risk classification framework for machine learning in safety-critical systems is mandating algorithmic audit trails for adaptive training scenarios. Simulator OEMs must now document how AI-driven difficulty adjustment modifies aerodynamic parameters in real time. Military aviation training programs across NATO member states are most affected, requiring retroactive compliance documentation for existing virtual mission rehearsal installations.
Airline procurement departments are unbundling after-sales service contracts from initial hardware purchases, negotiating separate agreements for motion base maintenance, visual system upgrades, and scenario content licensing. This disaggregation is most visible among US legacy carriers modernizing aging simulator fleets, where finance teams seek operational expenditure treatment for training infrastructure rather than capital deployment. Third-party service providers are capturing margin pools previously held by original equipment manufacturers through specialized maintenance contracts.
Dynamic Flight Training Compartments Market Segmentation
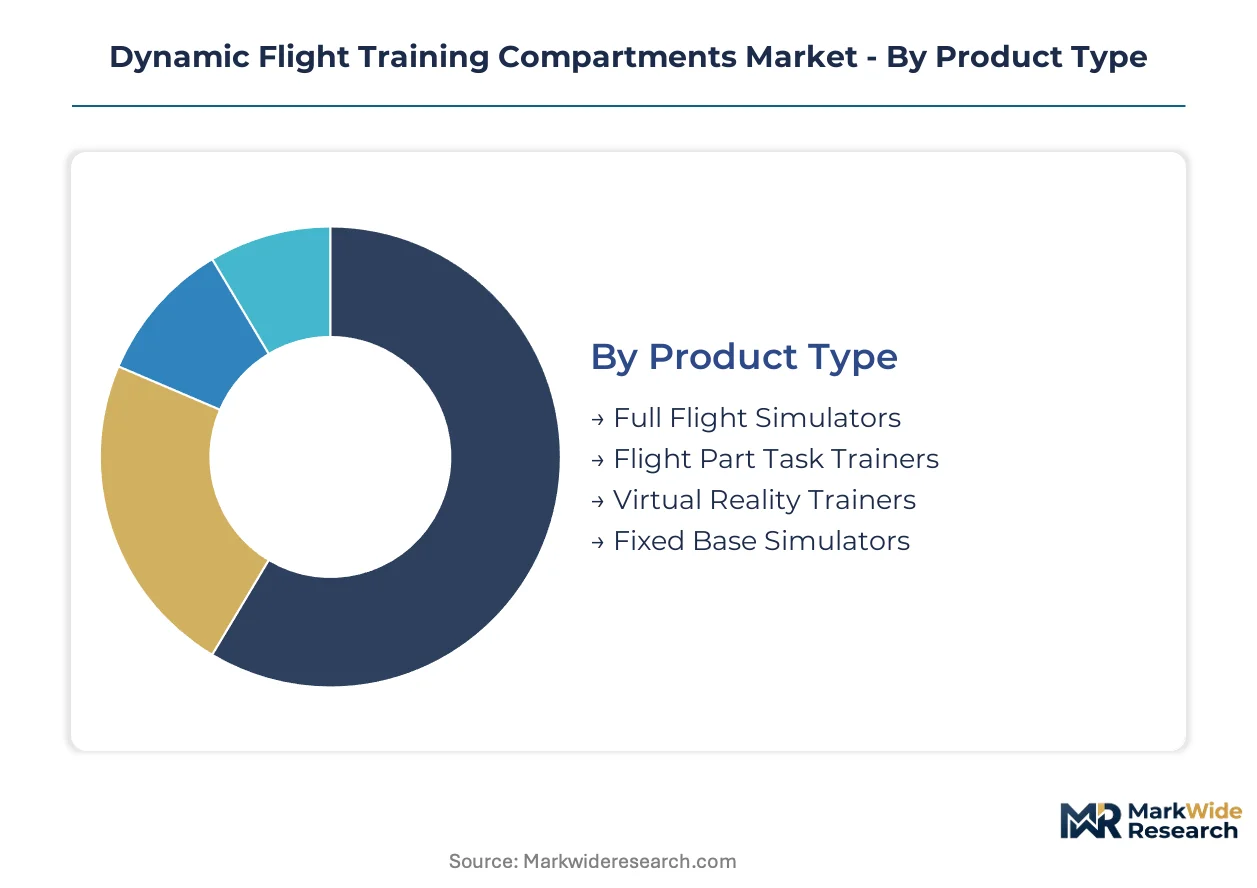
Training device segmentation determines regulatory credit eligibility and capital allocation across aviation education infrastructure. Procurement committees weigh certification level against throughput capacity when matching hardware categories to pilot throughput requirements.
Product Type:
Capital intensity and FAA certification tier drive airline procurement committees toward specific hardware configurations.
- Full Flight Simulators:Hexapod motion bases with Level D FAA Part 60 certification replicate complete aircraft flight envelopes for type rating qualification. United States legacy carriers concentrate replacement demand here as aging platforms approach obsolescence.
- Virtual Reality Trainers:Head-mounted displays with inside-out tracking deliver instrument procedural training at fraction of full-flight hardware cost. Flight schools in India and Australia are expanding these deployments fastest as DGCA and CASA extend regulatory credit recognition.
- Flight Part Task Trainers:Cockpit section replicas focusing on specific flight phases or emergency procedures.
- Fixed Base Simulators:Non-motion platforms for systems familiarization and procedural rehearsal.
Full Flight Simulators lead on scale; Virtual Reality Trainers lead on momentum.
Technology:
Software capabilities increasingly differentiate vendor offerings beyond mechanical specifications.
- Artificial Intelligence:Adaptive difficulty algorithms adjust aerodynamic parameters in real time based on trainee performance metrics. EASA CS-FSTD compliance documentation now requires algorithmic audit trails under EU AI Act risk classification frameworks.
- Motion Cueing:Real-time washout filters and acceleration onset cueing replicate spatial disorientation without inducing simulator sickness. German electromechanical component suppliers control critical servo valve production for hexapod platforms.
- Augmented Reality:Overlay systems blending physical cockpit panels with synthetic visual environments.
- Haptic Feedback:Force-reflecting control loading systems for control surface fidelity.
Motion Cueing dominates installed base; Artificial Intelligence commands premium pricing.
Application:
End-use certification requirements fragment hardware specifications across operational domains.
- Commercial Pilot Training:Airline transport pilot license pathways mandate recurrent proficiency checks in certified synthetic environments. United States regional carriers drive demand for narrow-body simulator configurations as fleet renewal accelerates.
- Military Aviation Training:High-G cockpit systems and integrated mission rehearsal platforms serve defense end users. NATO member states concentrate procurement through L3Harris and Thales for live-virtual-constructive architectures.
- Helicopter Training:Vertical flight dynamics require specialized motion cueing for rotorcraft instability regimes.
- Drone Operation Training:Remote pilot certificate programs for unmanned aircraft systems.
Commercial Pilot Training anchors volume; Drone Operation Training climbs the fastest.
End User:
Funding mechanisms and procurement flexibility separate institutional buyers.
- Flight Schools:Ab initio pilot programs require cost-efficient training hour accumulation. Poland and Spain host European low-cost carrier centralized training resources.
- Defense Organizations:Military aviation commands multi-year procurement cycles with classified scenario requirements. United States Department of Defense contracts specify integrated live-virtual-constructive network compatibility.
- Pilot Training Centers:Third-party providers serving airline outsourcing contracts.
- Unmanned Vehicle Operators:Commercial drone fleet operators and government surveillance programs.
Defense Organizations concentrate capital deployment; Flight Schools expand device count fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States simulator procurement cycles outpace German replacement demand by roughly three years, while India's regulatory pathway expansion attracts hardware deployment at flight schools faster than any other jurisdiction.
United States
FAA Part 60 Level D mandates lock in replacement demand for aging hexapod platforms across legacy carrier fleets. The FAA's extended documentation requirements for software version control now delay revenue recognition for new simulator deliveries. Dallas-Fort Worth and Atlanta host concentrated training infrastructure where regional airlines modernize narrow-body configurations.
Germany
German electromechanical component suppliers control critical hexapod servo valve production, creating input bottlenecks for simulator OEMs worldwide. EASA CS-FSTD regulatory harmonization enables cross-border training credit recognition that centralizes European resources. Munich and Hamburg anchor precision optical alignment facilities for laser phosphor dome systems.
India
DGCA evaluation of virtual reality training device credits for ab initio pilot programs opens hardware deployment at flight schools. The country's national aviation regulator follows CASA precedent in broadening synthetic environment recognition. Bangalore and Hyderabad concentrate emerging mixed-reality training pilots for regional airline partnerships.
United Kingdom
Royal Air Force integrated live-virtual-constructive network compatibility specifications drive defense procurement consolidation. Military aviation training commands multi-year cycles with classified scenario requirements that favor established platform vendors. BAE Systems partnerships in Lancashire and Bristol sustain mission rehearsal development clusters.
Australia
CASA regulatory credit recognition for virtual reality trainers enables regional airlines to pilot mixed-reality recurrent training outside centralized simulator centers. Geographic dispersion of pilot bases makes travel reduction economically compelling. Sydney and Melbourne host third-party training providers unbundling after-sales service from hardware purchases.
Dynamic Flight Training Compartments Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with full-flight simulator OEMs commanding premium pricing through certification-locked installed bases while virtual reality hardware vendors compete on unit cost and deployment speed. The vendor base concentrates around three tiers: integrated aerospace conglomerates with defense anchors, pure-play training specialists leveraging recurring service contracts, and emerging mixed-reality technology suppliers. Dominant competitive moves include strategic partnerships for cloud-based scenario distribution and geographic expansion into India's flight school market.
Within the integrated aerospace tier, CAE Inc. and L3Harris Technologies occupy positions that exemplify divergent end-market anchoring—CAE leveraging long-term airline service contracts across its full-flight simulator installed base, L3Harris anchoring military aviation through high-G cockpit systems for defense end users. Thales Group represents the mission rehearsal convergence archetype, combining live, virtual, and constructive training architectures for NATO member state procurement.
| Leading Market Players |
|---|
| CAE Inc. |
| FlightSafety International |
| TRU Simulation + Training |
| L3Harris Technologies |
| Thales Group |
| Lockheed Martin |
| Northrop Grumman |
| Leonardo S.p.A. |
| Textron Aviation |
| Others |
Pricing and Supply Chain Analysis
Software-defined scenario generation is compressing hardware margins while elevating recurring content economics, simultaneously fragmenting procurement power across airline finance departments and concentrating component supply among German electromechanical specialists. FAA Part 60 certification tiers create pricing stratification that rewards Level D platform vendors with decade-long service lock-in against emerging virtual reality hardware commoditization.
Pricing Analysis
Capacity additions in India's flight school sector are reshaping price floors for entry-level training devices as DGCA regulatory evaluation progresses. Three-tier pricing structure across Level D full-flight platforms, mid-tier part-task trainers, and virtual reality headsets reflects certification grade and after-sales bundling intensity. Cost compression in virtual reality hardware tiers is intensifying because display component costs are dropping faster than motion base economics. Regional airlines exhibit highest price sensitivity due to travel-burdened training budgets; defense organizations show lowest sensitivity given classified mission rehearsal requirements.
Supply Chain Analysis
Domestic-content mandates in India's aviation infrastructure push are reshaping sourcing patterns for cockpit replica assemblies and visual display domes. Component manufacturing concentrates in Germany, Italy, and the United States, with hexapod servo valve production anchored in German precision engineering clusters. Raw material and component dependencies span electromechanical actuators, laser phosphor projection engines, and computational aerodynamic modeling software. Single-source vulnerability in German electromechanical component supply creates procurement risk for simulator OEMs facing extended qualification timelines. Distribution runs through direct OEM sales to airline procurement departments and defense acquisition channels, with third-party service providers capturing aftermarket maintenance contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds value through regulatory credit allocation, with FAA Part 60 Level D mandates sustaining replacement demand regardless of economic cycles.
For Market Incumbents: Deploy installed base leverage to capture cloud-based scenario distribution contracts before virtual reality hardware commoditization accelerates. Secure long-term motion base maintenance agreements with regional airlines seeking operational expenditure treatment. Counter emerging mixed-reality entrants by accelerating EASA CS-FSTD compliance documentation for adaptive AI training scenarios. For New Entrants and Emerging Players: Enter via India's DGCA regulatory pathway expansion for virtual reality training device credits at flight schools. Target Australian and Scandinavian regional airlines piloting mixed-reality recurrent training to reduce centralized simulator travel. Pursue white-label visual system integration partnerships with established platform OEMs lacking in-house LED dome engineering. For Investors and Strategic Acquirers: Valuations sit cheapest among pure-play virtual reality hardware vendors lacking recurring content revenue streams. Long-term viability favors vendors with regulatory certification moats and airline service contract backlogs. Monitor EASA and FAA guidance velocity on machine learning transparency requirements as the inflection signal for AI-integrated platform premium capture.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Based Scenario Distribution | Shifts revenue from capital equipment toward recurring content subscriptions for airline fleet-specific curriculum. |
| AI Motion Cueing Integration | Concentrates margin pools among vendors capable of real-time aerodynamic parameter adjustment under EU AI Act audit requirements. |
| India Flight School Expansion | Captures DGCA regulatory pathway opening for virtual reality training device credits in ab initio pilot programs. |
| Live-Virtual-Constructive Convergence | Unifies defense procurement across training and operational units through integrated mission rehearsal platforms. |
| After-Sales Service Unbundling | Enables third-party providers to capture margin pools through specialized motion base maintenance contracts. |
Research Methodology
Direct dialogue with simulator OEM engineering directors, airline training center operations managers, defense procurement officers, and regulatory affairs specialists at FAA and EASA grounded qualitative assessments. Secondary validation drew from FAA Part 60 certification databases, EASA CS-FSTD qualification records, airline fleet modernization disclosures, and defense training budget appropriations documents. Bottom-up and top-down triangulation cross-checked hardware shipment estimates against training hour requirements and pilot pipeline projections.
Bottom-up modeling aggregated individual training device categories across product type, technology, application, and end-user segments over the projection horizon. Top-down analysis calibrated aggregate market sizing against aviation industry training expenditure patterns and regulatory mandate implementation timelines. CAGRs were derived from regression analysis of historical replacement cycles and projected fleet expansion rates, incorporating AI integration adoption curves and virtual reality regulatory credit velocity as industry-specific inputs.
Inputs from EASA certification databases and airline procurement disclosures were available through the study window; gaps in classified defense training program specifications introduce uncertainty bands around military segment projections. Forecasts reflect assumptions regarding regulatory harmonization pace and hardware cost reduction trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Simulation and Training
Military Training Aircraft Market
Simulation and Training
Europe Ship Bridge Simulators Market
Simulation and Training
North America Ship Bridge Simulators Market
Simulation and Training
Flight Simulator Market
Simulation and Training
Civil Aerospace Simulation and Training Market
Simulation and Training
Air Traffic Control Simulator and Training Market
Simulation and Training
Drone Simulator Market
Simulation and Training
Middle East and Africa Ship Bridge Simulators Market
Simulation and Training
Global Healthcare Games and Simulation Market
Simulation and Training
Helicopter Simulator Market
Simulation and Training
RADAR Simulator Market
Simulation and Training
Civil Aviation Simulator Market
Simulation and Training
GNSS Simulators Market
Simulation and Training
Global Military Airborne Simulation and Training Market
Simulation and Training
Global Ship Bridge Simulators Market
Simulation and Training
Europe Flight Training and Simulation Market