
 Civil Aerospace Simulation and Training Market | 2026-2036
Civil Aerospace Simulation and Training Market Size, Share, and Industry Trends Forecast 2026-2036
Civil Aerospace Simulation and Training Market Intelligence
FAA Level D qualification standards is restructuring the cost-of-entry calculus for simulator manufacturers, forcing multi-million dollar recertification investments that favor incumbents with established compliance infrastructure. CAE Inc. leverages its integrated training network across six continents to sustain recurring revenue from airline long-term contracts. L3Harris Technologies anchors its position through proprietary motion platform technology that dominates the high-fidelity segment. Thales Group differentiates via avionics replication fidelity that matches Airbus and Boeing cockpit architectures.
Civil aerospace simulation and training encompasses synthetic environments that replicate aircraft systems, flight dynamics, and operational scenarios using six-axis electric motion platforms, collimated visual displays with 220-degree horizontal field-of-view, and computational fluid dynamics-based aerodynamic modeling to achieve zero flight time certification equivalence. Full Flight Simulators command the largest value share due to regulatory mandates for type-rating qualification, while Virtual Reality Simulators represent the fastest-expanding category as airlines adopt cost-effective familiarization tools for procedural training. Pilot Training absorbs the majority of delivered simulator hours, though Maintenance Training carries superior margins because of specialized hardware-in-the-loop requirements.
The FAA, EASA, and China's CAAC each enforce distinct qualification frameworks that dictate simulator architecture, data package validation, and instructor station functionality, creating region-specific product variants that complicate manufacturing scale. EASA's recent CS-FSTD amendments and CAAC's evolving Level C equivalency rules are tightening visual system latency tolerances below 150 milliseconds, accelerating hardware refresh cycles. Stakeholders must monitor regulatory divergence between Washington, Brussels, and Beijing to anticipate which certification investments will unlock fleet-specific training contracts.
Market Dynamics
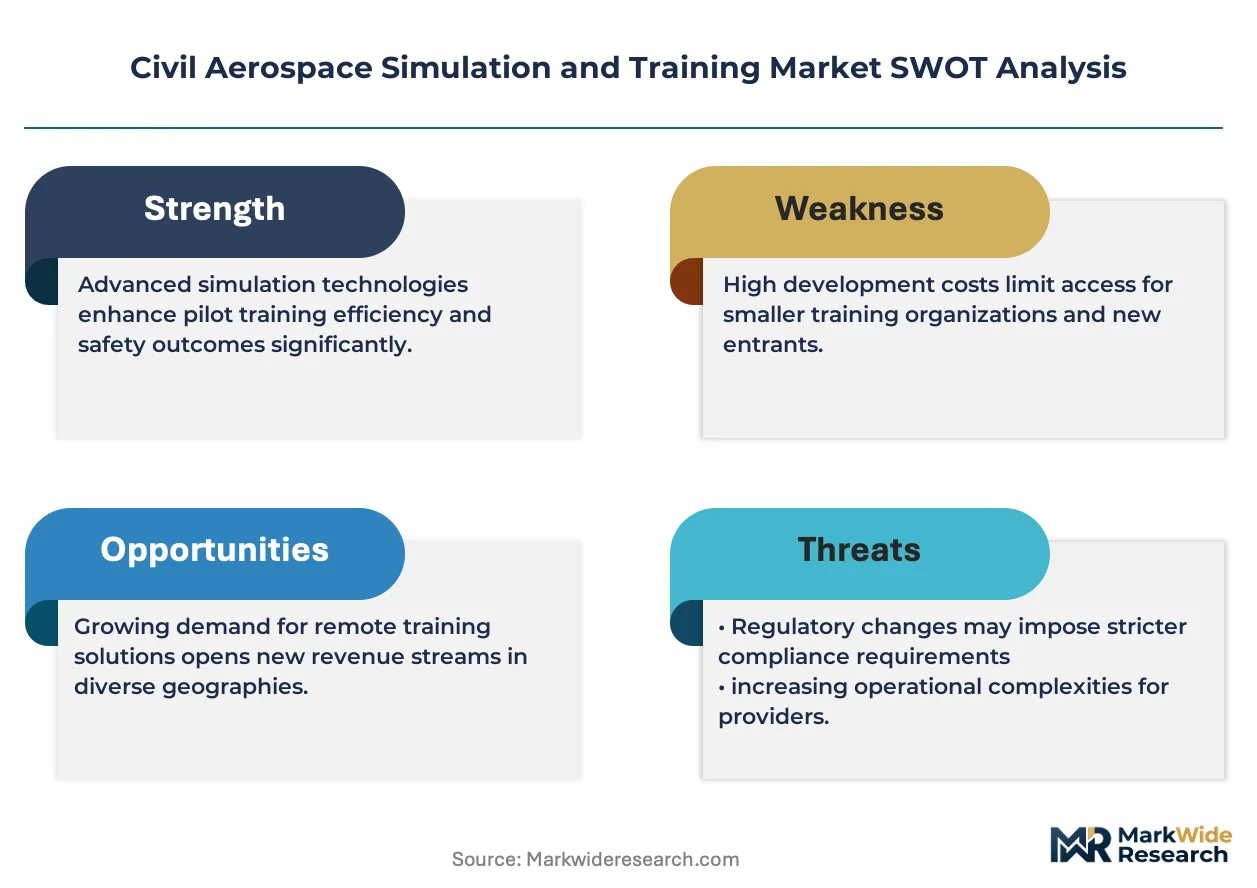
The FAA's updated Level D qualification standards are forcing multi-million dollar recertification investments across the installed base, consolidating competitive advantage around manufacturers with established compliance infrastructure and validated aerodynamic data packages.
Growth Catalysts
- FAA Level D Mandates:Airlines must achieve zero flight time certification equivalence through full flight simulators, expanding replacement demand across North American and European training centers.
- China's C919 Entry:COMAC's indigenous narrowbody program generates native simulator requirements that domestic and international manufacturers must address through CAAC-validated data packages.
- Electric Motion Platforms:Six-axis electric motion systems replace hydraulic actuators, reducing facility infrastructure costs and enabling simulator relocation to secondary training locations.
Market Restraints
- Visual System Latency Tolerances:EASA's CS-FSTD amendments tighten latency requirements below 150 milliseconds, forcing hardware refresh cycles that compress manufacturer margins on legacy installations.
- Aerodynamic Data Package Concentration:Boeing and Airbus control proprietary flight model validation data, creating gatekeeper dependencies for simulator manufacturers seeking type-specific certification.
- Regulatory Divergence:Distinct FAA, EASA, and CAAC qualification frameworks require region-specific product variants, fragmenting production scale and complicating inventory management.
Strategic Opportunities
- Virtual Reality Familiarization:Airlines adopt cost-effective VR tools for procedural training, opening a lower-price-tier segment distinct from regulatory-mandated full flight simulator hours.
- Maintenance Training Hardware:Specialized hardware-in-the-loop requirements for maintenance certification carry superior margins and less price sensitivity than pilot training contracts.
- Asia-Pacific Fleet Expansion:Chinese, Indian, and Southeast Asian carriers execute fleet renewal programs that outpace indigenous simulator manufacturing capacity, creating import-dependent demand windows.
Industry Challenges
- Computational Fluid Dynamics Expertise:Simulator manufacturers face acute shortages of aerodynamicists capable of translating aircraft manufacturer data into real-time flight models that satisfy regulatory validation protocols.
- Multi-Authority Certification Timelines:Simultaneous pursuit of FAA, EASA, and CAAC approvals extends time-to-revenue by 18-24 months, straining working capital for new platform introductions.
- Legacy Simulator Integration:Training centers operating 15-20 year old Level C devices encounter software architecture incompatibilities when attempting to incorporate modern visual system upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Civil Aerospace Simulation and Training Market |
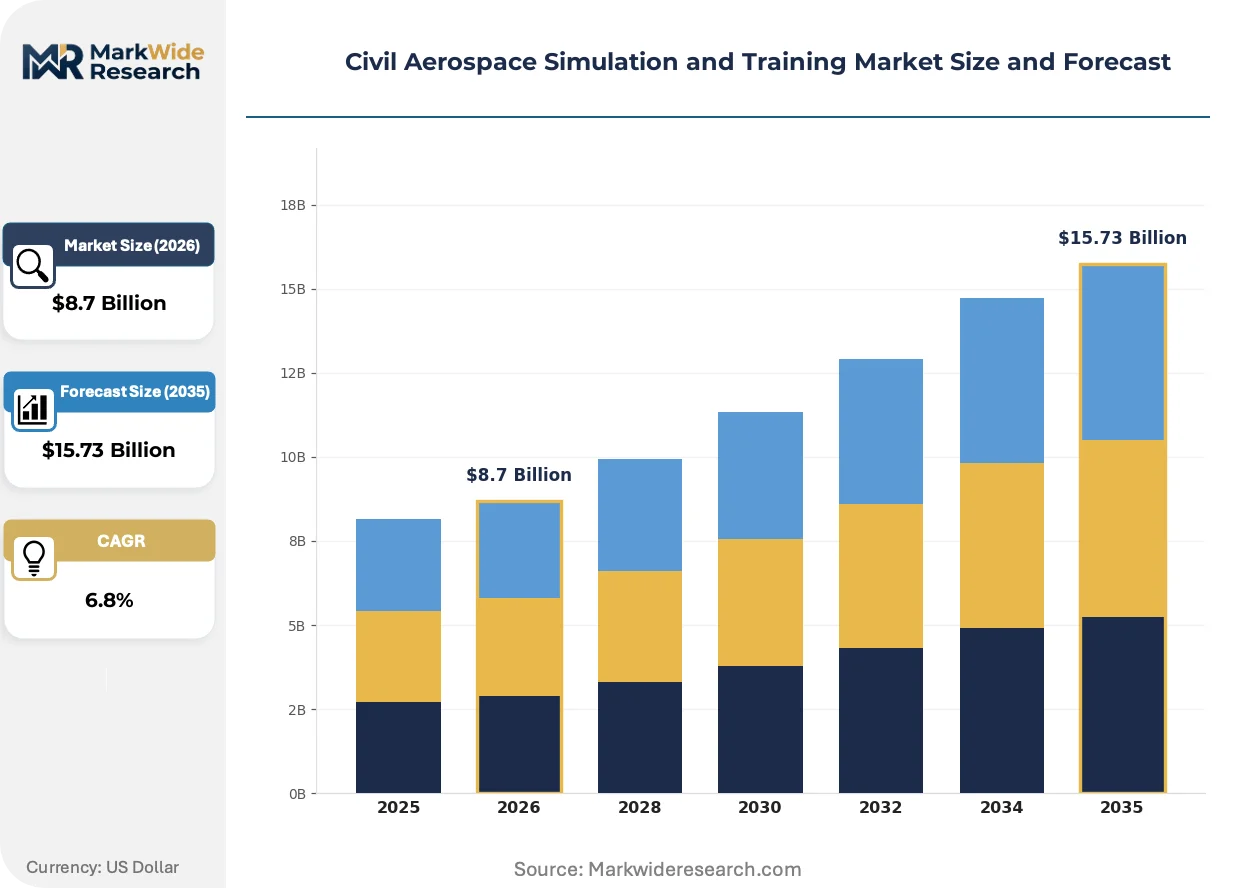
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Full Flight Simulator, Flight Training Device, Cockpit Procedures Trainer, Virtual Reality Simulator Application: Pilot Training, Cabin Crew Training, Ground Staff Training, Maintenance Training End User: Civil Aviation Authorities, Airlines, Flight Training Organizations, Military Delivery Mode: On-Premises, Cloud-Based, Blended Learning, Mobile Learning |
| Companies Covered | CAE Inc., FlightSafety International Inc., Thales Group, L3Harris Technologies, RTX Corporation, TRU Simulation + Training Inc., Elbit Systems Ltd., Indra Sistemas, ALSIM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Civil Aerospace Simulation and Training Market Strategic Shifts & Innovations
Computational advances and regulatory harmonization pressures are compressing development cycles while expanding the addressable training envelope beyond traditional type-rating qualification into familiarization and competency-based frameworks.
Artificial intelligence-driven adaptive learning algorithms are rewriting how simulator sessions personalize training intensity based on individual pilot performance metrics. Major carriers in the United States and Germany deploy these systems to reduce recurrent training hours while maintaining proficiency standards. The technology is compressing the traditional fixed-syllabus model into variable-duration sessions that optimize simulator utilization rates.
EASA's CS-FSTD amendments mandate sub-150 millisecond visual system latency tolerances and enhanced collimated display geometries for new Level D certifications. European training centers face accelerated obsolescence of installed visual systems that fail the revised standards. Manufacturers with next-generation display architectures capture replacement contracts ahead of the regulatory enforcement timeline.
Airlines unbundle after-sales training service contracts from initial simulator procurement, creating independent revenue streams for specialized training providers. Full-service carriers in the Asia-Pacific region lead this separation, contracting simulator hours through competitive tender rather than captive fleet arrangements. The shift concentrates purchasing power among airline procurement functions and pressures manufacturer margins on long-term service agreements.
Civil Aerospace Simulation and Training Market Segmentation
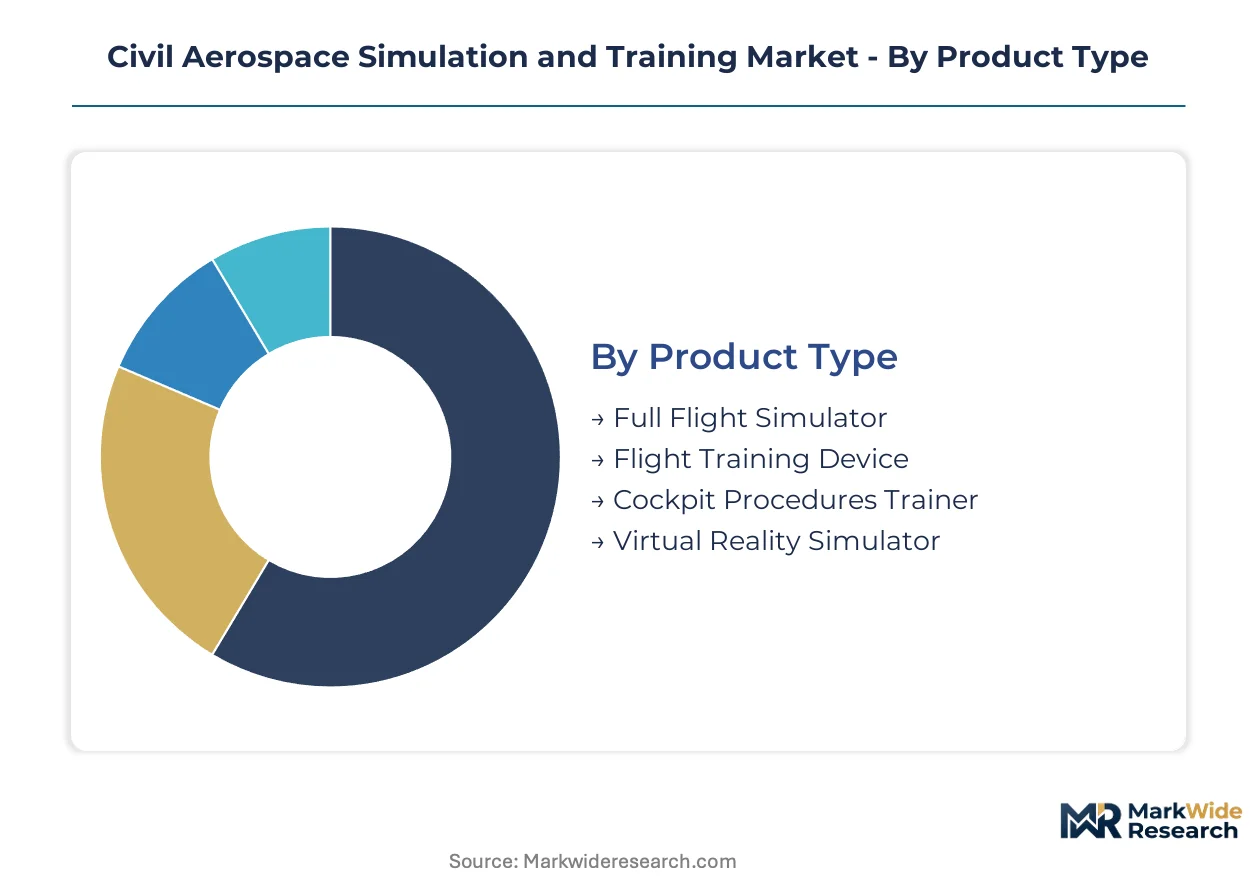
Simulator procurement patterns diverge sharply between regulatory-mandated type-rating certification and discretionary familiarization tools. Fleet renewal cycles and authority-specific qualification frameworks reshape how manufacturers configure motion platforms, visual systems, and instructor stations across each segment.
Product Type:
Standardization dominates at the high-fidelity end where FAA Level D mandates dictate architecture, while customization proliferates in emerging familiarization categories.
- Full Flight Simulator:Six-axis electric motion platforms with 220-degree collimated visual displays replicate aircraft flight dynamics for zero flight time certification. Airlines in China and the United States concentrate replacement demand as CAAC and FAA tighten qualification tolerances.
- Virtual Reality Simulator:Head-mounted displays with haptic feedback systems enable procedural training at one-tenth the capital cost of full-flight devices. Carriers in Germany and Singapore deploy these for cockpit familiarization ahead of type-rating qualification.
- Flight Training Device:Fixed-base platforms without motion systems address instrument proficiency and navigation procedures.
- Cockpit Procedures Trainer:Desktop or panel-mounted replicas focus on switchology and checklist execution for initial pilot screening.
Most installed capacity flows through Full Flight Simulator. Expansion is steepest in Virtual Reality Simulator.
Application:
Margin structures invert across this dimension, with specialized hardware requirements commanding premium pricing against volume-driven pilot instruction.
- Maintenance Training:Hardware-in-the-loop systems replicate aircraft systems at component-level fidelity for mechanic certification. MRO providers in France and Canada absorb these specialized installations where regulatory mandates exceed pilot training stringency.
- Pilot Training:Full-flight and flight training devices consume the majority of delivered simulator hours across recurrent and initial type-rating curricula. Fleet expansion at Chinese and Indian carriers concentrates demand for narrowbody-specific configurations.
- Cabin Crew Training:Door trainers, evacuation slides, and service mockups address safety and hospitality protocols.
- Ground Staff Training:Ramp operations and dispatch simulations target airline operational personnel outside the cockpit.
Maintenance Training captures the highest margin per installed seat. Pilot Training delivers the largest aggregate revenue pool.
End User:
Purchasing power concentrates among fleet operators with captive training networks, fragmenting across independent providers and regulatory bodies.
- Airlines:Full-service carriers in Asia-Pacific and North America operate proprietary training centers with long-term simulator procurement contracts. These operators unbundle after-sales service agreements to concentrate purchasing leverage.
- Flight Training Organizations:Independent academies in the United Kingdom and Australia serve ab-initio pilots and career-switchers through pay-per-hour access models.
- Civil Aviation Authorities:National regulators in China and the United States maintain examiner qualification facilities.
- Military:Air force and naval aviation programs access civil-certified platforms for transport and tanker training.
Airlines control the majority of capital deployment. Flight Training Organizations are expanding capacity fastest.
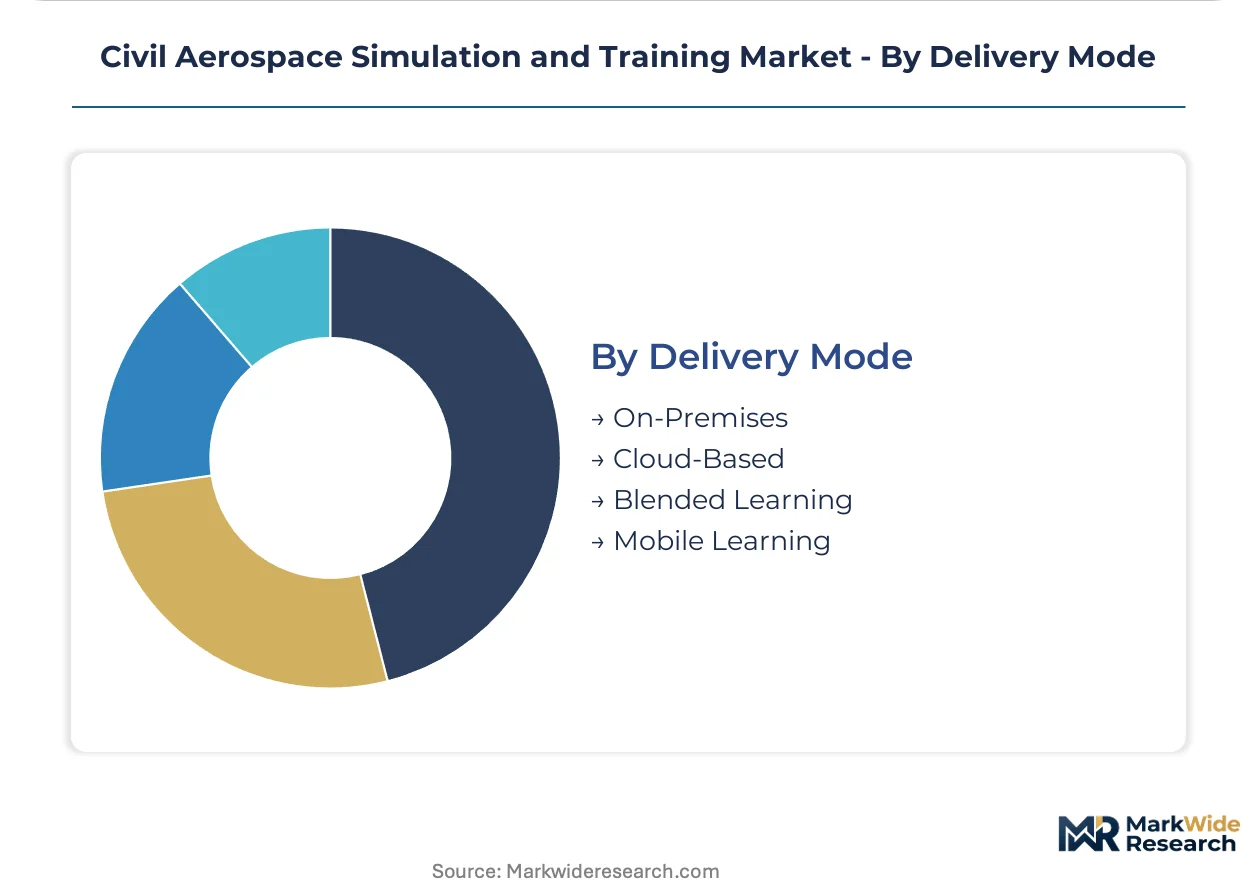
Delivery Mode:
Physical infrastructure requirements dominate high-fidelity segments, while digital modalities penetrate procedural and theoretical instruction.
- On-Premises:Full-flight simulators require dedicated buildings with reinforced foundations, climate control, and 15-meter visual domes. Training centers in Dubai and Frankfurt anchor regional hub strategies around these immovable assets.
- Cloud-Based:Browser-accessible platforms distribute theoretical knowledge and computer-based training without hardware dependency. Lufthansa and United Airlines deploy these for ground school and systems refresh.
- Blended Learning:Hybrid curricula combine simulator sessions with distance instruction.
- Mobile Learning:Tablet and smartphone applications support just-in-time reference and assessment.
On-Premises retains the highest revenue per learner. Cloud-Based is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Simulator engineering talent concentrates in Montreal, Toulouse, and Dallas-Fort Worth, anchoring the geographic distribution of civil aerospace training infrastructure. Fleet renewal cycles and regulatory tightening are redistributing procurement toward Asia-Pacific growth markets.
United States
Major carriers at Dallas-Fort Worth and Atlanta hubs drive simulator replacement demand as FAA Level D tolerances tighten. The FAA's updated qualification standards force recertification investments across legacy training centers. CAE Inc. and FlightSafety International anchor manufacturing and service operations in the Southeast and Southwest corridor.
China
COMAC's C919 entry-into-service generates native simulator requirements that outpace domestic manufacturing capacity. CAAC's evolving Level C equivalency rules are tightening visual system latency standards below 150 milliseconds. Training centers in Shanghai and Tianjin absorb import-dependent demand for narrowbody-specific configurations.
Germany
Lufthansa Group's unbundling of after-sales service contracts concentrates purchasing power among airline procurement functions. EASA's CS-FSTD amendments mandate sub-150 millisecond visual latency tolerances for new Level D certifications. Frankfurt anchors a regional hub strategy around immovable full-flight simulator infrastructure.
France
Airbus cockpit architecture replication requirements sustain demand for avionics-fidelity specialists in Toulouse and Paris-Saclay. EASA regulatory harmonization pressures compress development cycles for European qualification frameworks. Thales Group's integrated avionics heritage shapes regional competitive positioning in high-fidelity segments.
United Kingdom
Independent flight training academies in Oxford and Southampton serve ab-initio pilots through pay-per-hour access models. CAA alignment with EASA post-Brexit creates transitional certification complexity for cross-border training operations. L3Harris Technologies maintains engineering concentration in Southwest England for motion platform development.
Civil Aerospace Simulation and Training Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across a tiered structure where regulatory compliance infrastructure determines sustainable participation. Incumbents with validated aerodynamic data packages and multi-authority certification histories capture replacement demand from training centers facing obsolescence. Three archetypes dominate: integrated training network operators, proprietary motion platform technology holders, and avionics replication fidelity specialists. Consolidation through strategic partnerships and geographic licensing agreements is displacing organic capacity expansion as the primary expansion mode.
Within the integrated training network tier, CAE Inc. exemplifies the archetype of recurring revenue capture through long-term airline contracts. Thales Group and L3Harris Technologies occupy positions anchored in proprietary subsystem technology—avionics replication and motion platforms respectively. These three entities represent the compliance-heavy end of the competitive spectrum where regulatory validation histories serve as defensible positioning.
| Leading Market Players |
|---|
| CAE Inc. |
| FlightSafety International Inc. |
| Thales Group |
| L3Harris Technologies |
| RTX Corporation |
| TRU Simulation + Training Inc. |
| Elbit Systems Ltd. |
| Indra Sistemas |
| ALSIM |
| Others |
Cost & Logistics Intelligence
Rare earth magnet price indices cascade through electric motion platform manufacturing into three distinct pricing tiers for simulator procurement. Airlines unbundling after-sales service contracts from hardware acquisition concentrate purchasing leverage among procurement functions, compressing margins on long-term maintenance agreements while elevating capital equipment price transparency.
Pricing Analysis
The bundled-versus-unbundled service split now defines contract economics across the installed base. Three-tier pricing structure across premium, standard, and economy levels separates FAA Level D certified devices from Level C equivalents and non-certified familiarization tools. Price differentiation hinges on certification grade and after-sales service bundling, with EASA's sub-150 millisecond latency mandates intensifying cost compression in legacy visual system upgrades. Low-cost carriers in Southeast Asia exhibit highest price sensitivity; integrated training networks at legacy carriers demonstrate least.
Supply Chain Analysis
Direct-to-OEM channels handle fleet-operator demand for type-specific configurations, while distributor networks serve independent training organizations. Manufacturing concentrates in Canada, France, and the United States, with motion platform assembly anchored in Montreal and Toulouse engineering clusters. Supply chains draw from Taiwanese semiconductor foundries for visual processing units, German precision optics for collimated displays, and Chinese rare earth processors for electric actuator magnets. Single-source vulnerability around Boeing and Airbus aerodynamic data packages creates gatekeeper risk. Distribution runs through manufacturer-direct sales teams for full-flight simulators and specialized aviation distributors for lower-fidelity devices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as regulatory tightening toward FAA Level D and EASA CS-FSTD standards shifts procurement toward premium-certified configurations with validated compliance histories.
For Market Incumbents: Deploy certification infrastructure leverage to capture replacement demand from training centers facing 15-20 year device obsolescence. Deepen aerodynamic data partnerships with airframers to secure type-specific validation rights against emerging VR-based familiarization substitutes. Expand service contract reattachment programs to recover margins lost to unbundling trends among Asia-Pacific carriers. For New Entrants and Emerging Players: Launch via hardware-in-the-loop maintenance training specialization where regulatory stringency exceeds pilot training and price sensitivity remains lowest. Target unmet demand for COMAC C919-validated simulators where domestic Chinese capacity lags fleet entry-into-service requirements. Pursue cloud-based theoretical instruction partnerships with flight training organizations to establish brand presence ahead of capital-intensive full-flight device competition. For Investors and Strategic Acquirers: Asymmetric upside sits with motion platform technology specialists possessing proprietary six-axis electric architectures and established FAA-EASA dual certification histories. Long-term viability over a decade horizon favors entities with validated aerodynamic data packages and recurring revenue capture from integrated training networks. Monitor CAAC Level C equivalency rule finalization as inflection signal for China market access premium.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Authority Certification Investment | Dual FAA-EASA approvals unlock fleet-specific contracts at Lufthansa and United training centers. |
| Electric Motion Platform Migration | Six-axis electric systems reduce facility infrastructure costs and enable secondary location deployment. |
| Aerodynamic Data Partnership | Validated flight model agreements with Airbus and Boeing secure type-rating certification exclusivity. |
| VR Familiarization Product Launch | Head-mounted display systems address procedural training at one-tenth capital cost of full-flight devices. |
| Maintenance Training Specialization | Hardware-in-the-loop systems for mechanic certification capture superior margins versus pilot training. |
Research Approach
Bottom-up airline fleet modeling reconciled against top-down simulator manufacturing capacity tracking forms the analytical core of this study. Primary interviews with training center directors, airline procurement executives, regulatory certification engineers, and flight school operators combined with secondary validation from FAA certification databases, EASA CS-FSTD amendment filings, CAAC type validation records, and customs trade data for motion platform component flows. Top-down triangulation against OEM production schedules and fleet delivery forecasts ensures demand-side calibration.
Historical trendline analysis of simulator delivery patterns and training hour utilization rates informed projection framework construction across product type, application, and end-user dimensions. Modeled segmentation spans full-flight versus virtual reality device categories, pilot versus maintenance training applications, and airline versus independent training organization end-users. CAGRs derive from regression analysis of fleet renewal cycles and regulatory mandate implementation timelines, with electric motion platform adoption curves and VR penetration assumptions as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under regulatory divergence scenarios between Washington, Brussels, and Beijing. Periodic stress-testing of base assumptions is recommended, particularly around CAAC equivalency rule evolution and COMAC C919 delivery ramp schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Simulation and Training
Drone Simulator Market
Simulation and Training
Satellite Simulator Market
Simulation and Training
Europe Flight Training and Simulation Market
Simulation and Training
Flight Simulation Training Device Market
Simulation and Training
Global Healthcare Games and Simulation Market
Simulation and Training
Trainer Aircraft Market
Simulation and Training
Military Simulation and Training Market
Simulation and Training
Europe Ship Bridge Simulators Market
Simulation and Training
GNSS Simulators Market
Simulation and Training
North America Simulator Windows and Simulator Skylights Market
Simulation and Training
Military Training Aircraft Market
Simulation and Training
Military Aerospace Simulation and Training Market
Simulation and Training
Asia-Pacific Ship Bridge Simulators Market
Simulation and Training
Helicopter Simulator Market
Simulation and Training
North America Ship Bridge Simulators Market
Simulation and Training
Military Simulation Software Market