
 Military Simulation Software Market | 2026-2036
Military Simulation Software Market Size, Share, and Industry Trends Forecast 2026-2036
Military Simulation Software Market Insights
Defense procurement channels is fragmenting as sovereign nations build indigenous simulation capabilities alongside traditional vendor relationships. Lockheed Martin Corporation leverages its classified systems integration heritage to sustain prime-contractor positions across multiple NATO air forces. CAE Inc. anchors commercial aviation training expertise into military flight simulation, while Rheinmetall AG competes aggressively on European land-system simulation tenders through localized production footprints.
Military simulation software encompasses computer-generated environments, physics engines, and scenario authoring tools that replicate battlefield conditions for training, testing, and mission rehearsal without live asset exposure. These systems integrate real-time terrain databases, sensor emulation algorithms, and networked interoperability protocols conforming to HLA and DIS standards to enable distributed collective training across geographically separated units. Live simulation and virtual simulation command the largest installed bases, though mixed reality simulation captures expanding R&D allocation as optical waveguide and haptic feedback technologies mature. Cloud-based deployment grows fastest among segments, driven by elastic compute requirements for large-force exercises and reduced capital burden on defense ministries, while on-premise installations retain dominance in classified networks where air-gapped security mandates prevail.
ISO 9001 quality management and NATO STANAG 4609 video metadata standards shape product certification requirements for cross-border interoperability, while the U.S. DoD's Modular Open Systems Approach mandates vendor-agnostic software architectures to prevent proprietary lock-in. The U.S. Federal Aviation Administration and European Union Aviation Safety Agency impose overlapping certification burdens on simulation hardware with dual civil-military applications, complicating product roadmaps for suppliers serving both sectors. Stakeholders must monitor evolving cybersecurity mandates for cloud-hosted defense data, as national sovereignty requirements clash with multi-tenant infrastructure economics.
Market Dynamics
The U.S. DoD's Modular Open Systems Approach is forcing defense contractors to dismantle proprietary software architectures, reshaping how military simulation platforms integrate across NATO allied forces and opening prime-contractor positions to specialized subsystem vendors.
Growth Catalysts
- Synthetic Training Environment Mandates:The U.S. Department of Defense prioritizes virtual collective training for joint force readiness, accelerating procurement of networked simulation platforms that replicate multi-domain battlefields without live asset deployment.
- NATO STANAG 4609:Standardized video metadata protocols enable cross-border interoperability, allowing German, French, and Polish forces to exchange sensor-simulation data during coalition exercises.
- Optical Waveguide Maturation:Advances in photonic waveguide manufacturing reduce headset weight for mixed-reality pilot training, expanding addressable use cases beyond traditional dome-based flight simulators.
Market Restraints
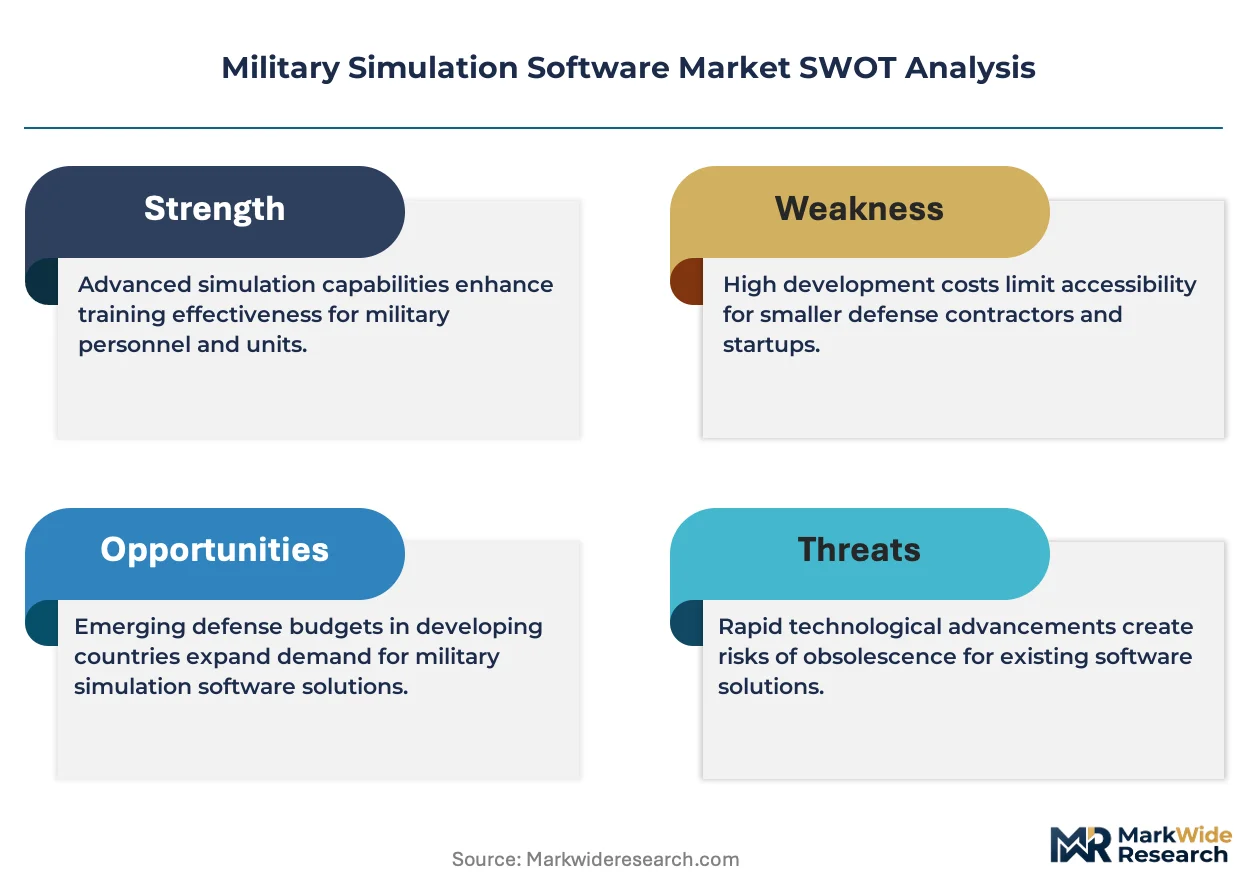
- Air-Gapped Security Mandates:Classified networks in intelligence and strategic command applications prohibit cloud connectivity, constraining elastic-compute adoption and perpetuating high fixed-cost on-premise infrastructure.
- Dual-Use Certification Overlap:The U.S. FAA and EASA impose conflicting airworthiness standards on hardware serving civil and military aviation, elongating product development timelines and raising compliance overhead.
- Specialized Talent Scarcity:Defense simulation engineering requires cleared personnel with expertise in HLA/DIS networking protocols, creating recruitment bottlenecks in the United States and United Kingdom.
Strategic Opportunities
- Poland and Baltic States:Frontline NATO members are building indigenous simulation centers for armored vehicle crew training, creating openings for land-system specialists with localized production capabilities.
- AI-Generated Scenario Authoring:Machine learning models trained on operational data automate red-force behavior scripting, compressing exercise preparation from weeks to days for operational test agencies.
- Cyber Range Convergence:Integration of kinetic and cyber battle simulation within single synthetic environments addresses joint force requirements for multi-domain operations training.
Industry Challenges
- Legacy System Integration:Decades-old simulation assets using proprietary data formats resist interoperability with modern open-architecture platforms, requiring costly middleware development.
- Security Clearance Throughput:Vendor personnel accessing classified program requirements face 12-18 month clearance timelines in the United States, delaying contract execution and milestone payments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Military Simulation Software Market |
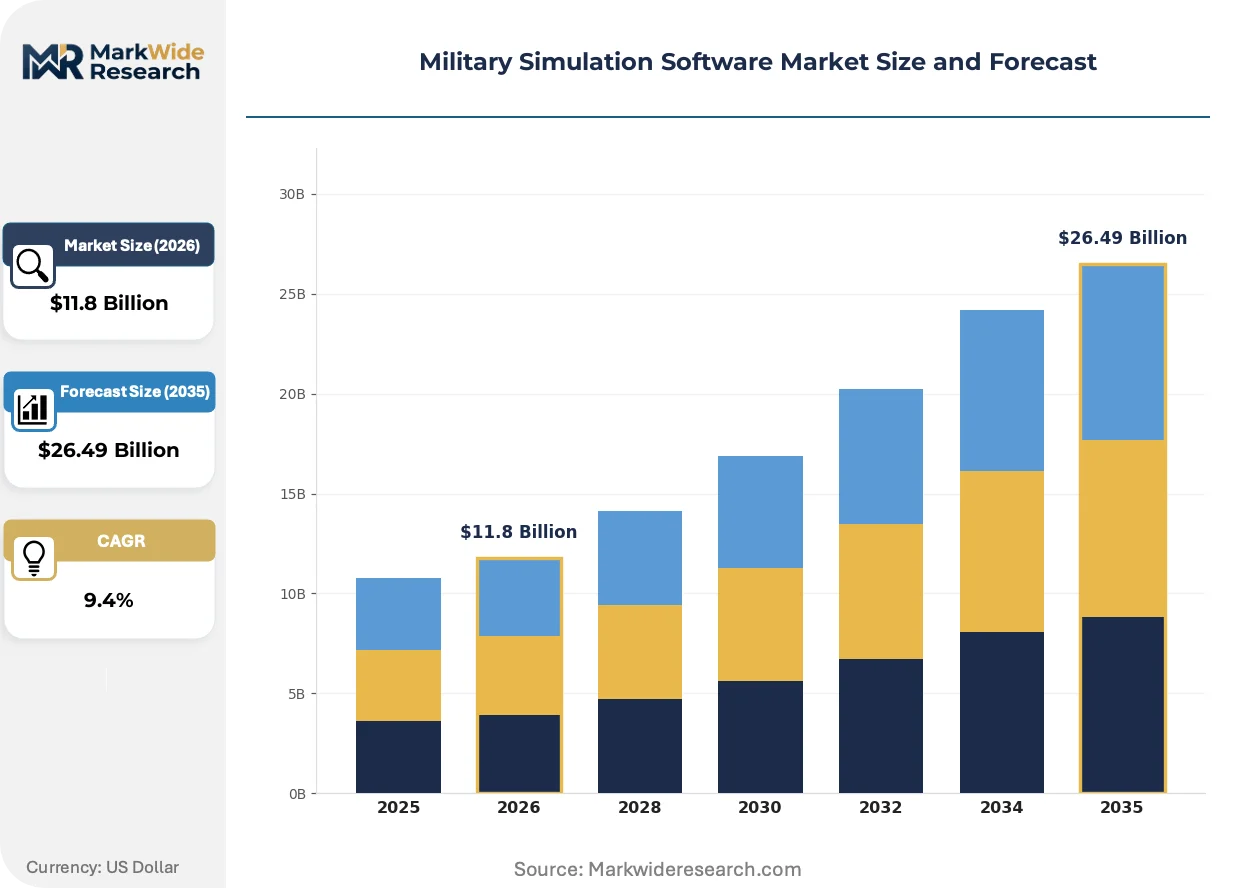
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $26.49 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Simulation Type: Live Simulation, Virtual Simulation, Constructive Simulation, Mixed Reality Simulation Deployment: On-Premise, Cloud-Based, Hybrid Cloud, Edge Computing Application: Combat Training, Tactical Planning, Weapon System Testing, Mission Rehearsal, Crisis Management End User: Defense Forces, Military Academies, Research Institutes, Training Contractors |
| Companies Covered | Lockheed Martin Corporation, CAE Inc., Northrop Grumman Corporation, BAE Systems, Thales Group, Raytheon Technologies, Collins Aerospace, Rheinmetall AG, L3Harris Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Military Simulation Software Market Trends and Innovations
Software-defined architectures are displacing hardware-dependent simulation systems, compressing upgrade cycles and enabling rapid reconfiguration of training scenarios without physical facility modification.
Digital twin technology is virtualizing physical weapon platforms for pre-mission rehearsal and operational testing. The U.S. Navy's Surface Warfare Centers deploy vessel-specific digital replicas to validate combat system software prior to at-sea trials. This approach compresses validation timelines while reducing wear on operational hulls and propulsion systems.
The EU AI Act establishes risk classification frameworks for autonomous systems deployed in defense applications, requiring conformity assessments for simulation environments that train algorithmic decision-making. European procurement agencies now mandate algorithmic audit trails for synthetic training data, affecting vendors supplying scenario generation tools to French and German forces.
Defense ministries are consolidating simulation procurement through framework agreements rather than discrete program acquisitions. The UK Ministry of Defence's Single Source Regulations Office standardizes pricing methodologies across training system contracts, compressing vendor margins while extending contract durations. This pattern is visible in Australia's Defence Simulation and Training Centre rationalization efforts.
Military Simulation Software Market Segmentation
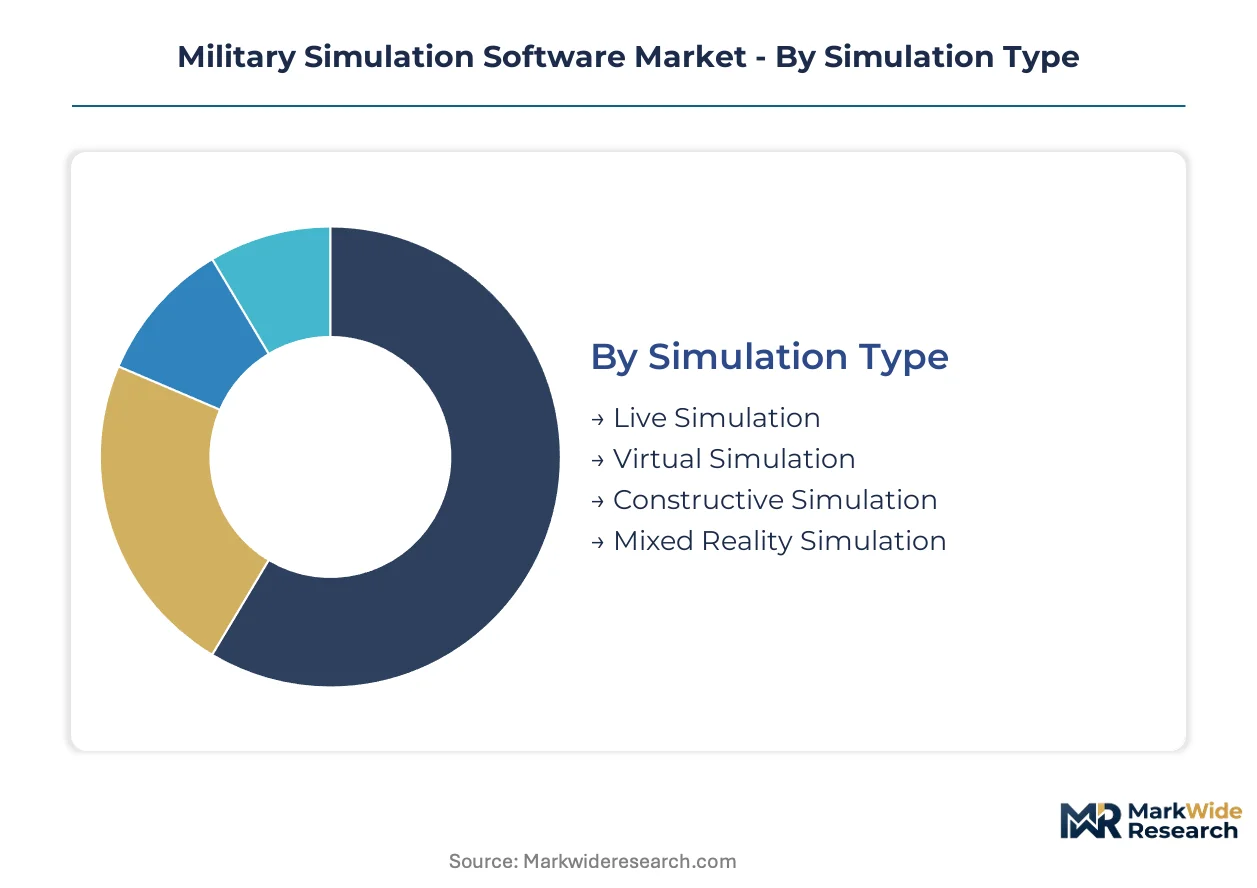
Segmentation reveals divergent procurement rhythms across military simulation software. Simulation type and deployment architecture exhibit starkly different replacement cycles, while application focus and end-user categories shape contract duration and margin structure.
Simulation Type:
Live simulation platforms turn over slowest due to physical infrastructure lock-in, while mixed reality simulation refreshes fastest as headset hardware generations compress.
- Live Simulation:Physical range instrumentation, target systems, and laser-based engagement adjudication require hardened facilities with decades-long amortization. The U.S. Army's National Training Center at Fort Irwin anchors demand for instrumented combined-arms training, though procurement cycles stretch across multiple Program Objective Memorandum cycles due to construction timelines.
- Virtual Simulation:Dome-based flight simulators and reconfigurable vehicle crew trainers dominate NATO air force and armored corps procurement. Germany's Air Force Flight Training Center at Holloman AFB drives concentrated demand for high-fidelity cockpit replication with motion platforms.
- Constructive Simulation:Computer-generated forces and aggregate-level wargaming models support command post exercises without human-in-the-loop participation. The U.S. Joint Staff J7 employs Joint Theater Level Simulation for global campaign analysis.
- Mixed Reality Simulation:Optical see-through headsets and haptic wearables enable dismounted infantry training with spatial computing. Polish Land Forces are procuring MR systems for urban combat preparation.
Virtual simulation dominates installed base. Mixed reality simulation is where expansion concentrates.
Deployment:
Cost tier stratification separates capital-intensive on-premise builds from operational-expense cloud models, with hybrid architectures capturing mid-budget programs seeking staged migration.
- On-Premise:Air-gapped classified networks in strategic command and intelligence applications mandate sovereign infrastructure with physical security controls. The U.S. National Security Agency's Commercial Solutions for Classified program certifies eligible hardware.
- Cloud-Based:Elastic compute pools support large-force exercise scaling without permanent capacity investment. The UK Defence Digital organization hosts synthetic training environments on Crown Hosting infrastructure.
- Hybrid Cloud:Sensitive scenario data remains on-premise while compute-intensive rendering shifts to commercial cloud. French Army simulation centers adopt this model for armored vehicle crew training.
- Edge Computing:Deployable nodes enable expeditionary simulation for forward-deployed units with intermittent connectivity. U.S. Marine Corps Force Design 2030 emphasizes distributed training at austere locations.
On-premise deployment retains revenue concentration. Cloud-based delivery is climbing the fastest.
Application:
Application segments align with distinct procurement authorities and budget line classifications, from operational force training accounts to research and engineering appropriations.
- Combat Training:Individual and collective live-virtual-constructive integration for maneuver units. The U.S. Army's Synthetic Training Environment program consolidates multiple legacy systems.
- Tactical Planning:Map-based rehearsal tools for mission commanders with terrain analysis and route planning. NATO Allied Command Operations employs these for operational planning.
- Weapon System Testing:Hardware-in-the-loop validation of fire control software prior to live-fire qualification. The U.S. Navy's Naval Air Warfare Center Weapons Division operates premier facilities.
- Mission Rehearsal:Unit-specific scenario preparation using classified intelligence feeds and actual mission parameters. UK Special Forces demand tailored environments with rapid scenario generation.
- Crisis Management:Interagency coordination simulation for national security council-level decision exercises. The U.S. Department of Homeland Security conducts these with state and local partners.
Combat training commands largest program-of-record spending. Mission rehearsal shows steepest expansion trajectory.
End User:
Customer type determines contracting vehicle complexity, from streamlined indefinite-delivery arrangements for defense forces to competitive grant mechanisms for research institutes.
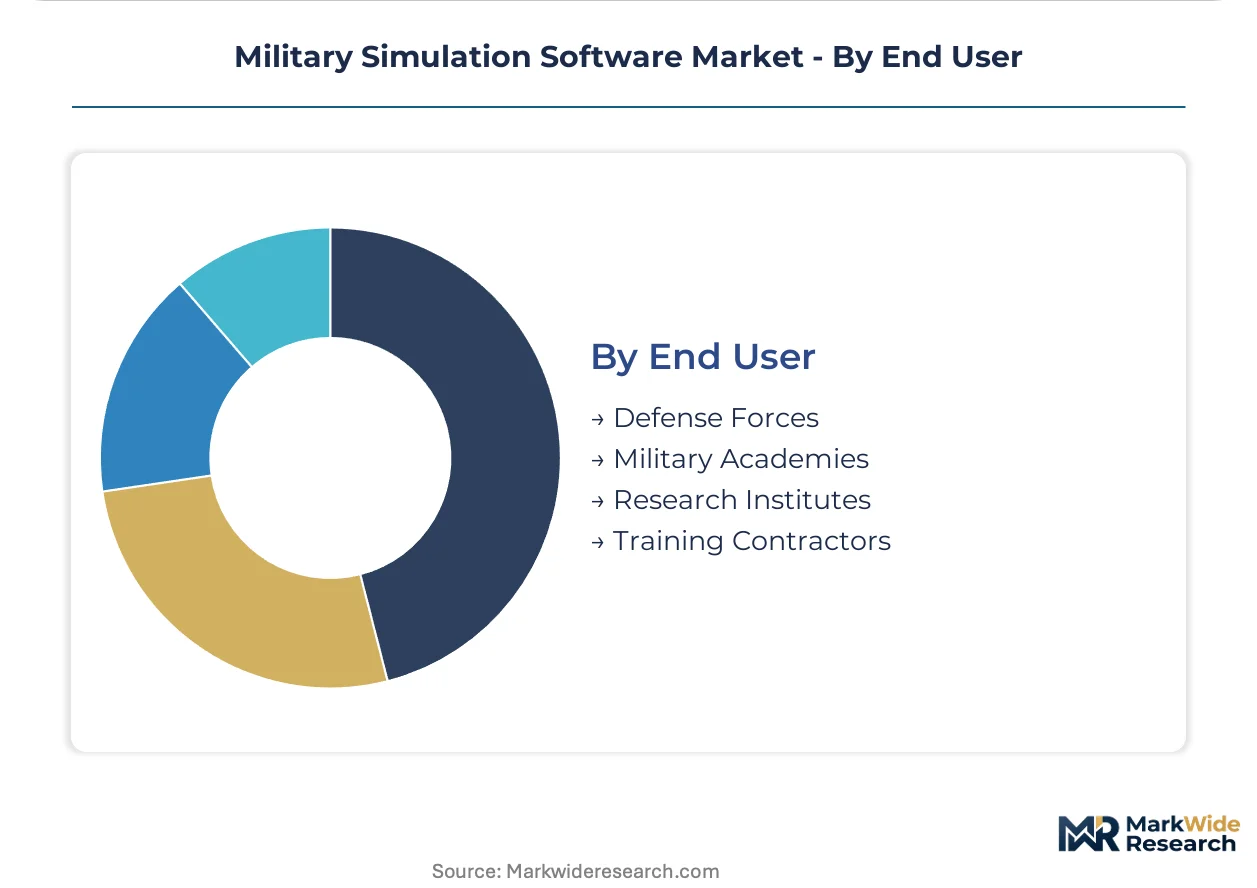
- Defense Forces:Operational military services with dedicated training commands and multi-year procurement authority. The U.S. Army Program Executive Office for Simulation, Training and Instrumentation manages these acquisitions.
- Military Academies:Officer commissioning institutions requiring foundational tactical education systems. The U.S. Military Academy at West Point operates the Digital Leader Development Center.
- Research Institutes:Federally funded research centers and university-affiliated laboratories with R&D mission orientation. The U.S. Naval Postgraduate School's MOVES Institute specializes in modeling and simulation research.
- Training Contractors:Private sector entities delivering contracted instruction services to defense ministries. CAE USA supports U.S. Air Force pilot training under Contractor Operated and Maintained Base Supply arrangements.
Defense forces dominate installed base. Research institutes are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement incentives are reshaping geographic demand patterns as sovereign nations prioritize indigenous simulation capabilities alongside allied interoperability frameworks. National security budgets in NATO member states explicitly fund synthetic training infrastructure, while non-aligned countries pursue localized development to reduce foreign dependency.
United States
The Department of Defense's Synthetic Training Environment program drives concentrated demand for joint-force simulation platforms across all service branches. The Modular Open Systems Approach mandates vendor-agnostic architectures for cross-platform compatibility. Orlando, Florida anchors the domestic simulation industrial cluster, where the Army's Program Executive Office for Simulation, Training and Instrumentation coordinates acquisition with private sector developers.
Germany
Bundeswehr modernization initiatives prioritize networked land-system simulation for armored corps readiness alongside NATO interoperability commitments. The EU AI Act imposes conformity assessments on autonomous systems training environments, affecting scenario generation tool procurement. Bavaria hosts concentrated simulation engineering capacity, with the Air Force Flight Training Center at Holloman AFB sustaining transatlantic pilot training operations.
United Kingdom
The Ministry of Defence's Single Source Regulations Office standardizes pricing methodologies across training system contracts, compressing vendor margins while extending engagement durations. Crown Commercial Service framework agreements consolidate procurement authority under Defence Digital. South West England clusters simulation development activity, where the Defence Simulation and Training Centre rationalizes legacy system portfolios.
Poland
Frontline NATO positioning accelerates indigenous simulation center construction for armored vehicle crew training and urban combat preparation. National sovereignty requirements clash with multi-tenant cloud infrastructure economics, mandating hybrid deployment architectures. Warsaw and the Baltic corridor concentrate defense technology investment, with Polish Land Forces procuring mixed-reality systems for dismounted infantry readiness.
Australia
The Defence Simulation and Training Centre consolidates procurement through framework agreements rather than discrete program acquisitions, mirroring UK rationalization patterns. Sovereign industrial capability priorities mandate local content thresholds for major simulation contracts. Canberra anchors federal defense decision-making, while Victoria and New South Wales host specialized training system integration facilities supporting regional joint exercises.
Military Simulation Software Market Competitive Landscape
On the supply side, the industry is consolidating around systems integrators with classified program heritage and specialized subsystem vendors with domain-specific expertise. Prime contractors occupy enduring positions through long-term service relationships and security-cleared workforces, while mid-tier specialists capture niche opportunities in emerging technology segments. Two strategic archetypes dominate: aerospace-derived platforms leveraging flight simulation legacy, and land-system specialists with armored vehicle training expertise. Competitive moves center on strategic partnerships for technology access and geographic expansion through localized production footprints.
Within the prime-contractor tier, Lockheed Martin Corporation and Northrop Grumman Corporation exemplify classified systems integration heritage sustaining multi-service positions across NATO air forces. CAE Inc. occupies a distinct archetype bridging commercial aviation training expertise into military flight simulation markets. Rheinmetall AG anchors European land-system specialization, competing aggressively on localized production capabilities for armored vehicle crew training tenders in Poland and Baltic states.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| CAE Inc. |
| Northrop Grumman Corporation |
| BAE Systems |
| Thales Group |
| Raytheon Technologies |
| Collins Aerospace |
| Rheinmetall AG |
| L3Harris Technologies |
| Others |
Pricing and Supply Chain Analysis
Rotterdam-Orlando maritime freight corridors carry specialized motion-platform components and optical waveguide assemblies, with container cost volatility compressing margins for European land-system suppliers while amplifying price spreads between NATO-certified and non-certified simulation platforms.
Pricing Analysis
Certification level (NATO STANAG 4609-compliant versus national-standard) creates the primary spread between premium and standard tiers. Project-based licensing with annual maintenance renewals dominates contract structures. Price differentiation stems from security-cleared engineering labor and sovereign data-hosting requirements. Cost compression in cloud-deployed segments is intensifying because defense ministries consolidate procurement through framework agreements. Training contractors exhibit highest price sensitivity due to fixed-fee contract structures, while intelligence agencies accept premium pricing for air-gapped infrastructure.
Supply Chain Analysis
Extended payment terms from prime contractors now stretch 90-120 days for subsystem vendors, with supply-chain finance facilities emerging as working capital bridges. Manufacturing concentrates in the United States, Germany, and Poland. Production draws from gallium nitride semiconductors, precision motion actuators, and classified terrain database sources. Single-source vulnerability persists in photonic waveguide fabrication. Distribution runs through defense procurement offices and Crown Commercial Service frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Security-cleared software engineers with HLA/DIS protocol expertise represent the critical bottleneck constraining vendor expansion, with recruitment timelines extending 12-18 months in the United States and United Kingdom.
For Market Incumbents: Entrench prime-contractor positions through captive cleared-labor pipelines and long-term service relationships with Program Executive Office for Simulation, Training and Instrumentation. Deepen backward integration into optical waveguide manufacturing to reduce headset hardware dependency. Counter emerging subsystem specialists by pre-empting Modular Open Systems Approach compliance certification. For New Entrants and Emerging Players: Establish a beachhead in Polish and Baltic state land-system simulation centers where indigenous capability gaps persist. Target mixed-reality infantry training as the most penetrable segment given headset hardware refresh cycles. Pursue rapid NATO STANAG 4609 certification as the primary go-to-market credential. For Investors and Strategic Acquirers: Specialist AI scenario-authoring firms with operational data partnerships represent the priority acquisition archetype. Long-term viability hinges on algorithmic audit trail capabilities mandated by the EU AI Act. Watch for defense ministry framework agreement consolidation as the inflection signal for margin compression timing.| Strategic Initiative | Industry Significance |
|---|---|
| Security Clearance Pipeline Investment | Cleared personnel access unlocks classified program participation at PEO STRI and NATO equivalents. |
| Modular Open Systems Approach Certification | Vendor-agnostic architecture compliance prevents proprietary lock-in exclusion from U.S. DoD procurement. |
| AI-Generated Scenario Authoring Capability | Machine learning compression of red-force scripting addresses Joint Staff J7 exercise preparation timelines. |
| Localized Production Footprint in Poland | Indigenous manufacturing satisfies Polish Land Forces sovereignty requirements for armored crew trainers. |
| Cyber-Kinetic Convergence Platform Development | Integrated multi-domain environments align with U.S. Army Synthetic Training Environment joint force mandates. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with simulation program managers at defense ministries, procurement officers at training commands, and engineering directors at platform developers; and secondary validation against NATO STANAG documentation, U.S. DoD budget justification materials, and EU AI Act regulatory filings. Bottom-up segment sizing triangulated against top-down defense expenditure allocation models.
Forecast inputs encompassed simulation type replacement cycles, deployment architecture migration rates, and cloud elasticity adoption curves across the projection horizon. Segmentation dimensions modeled include simulation fidelity tier, deployment security classification, and end-user procurement authority. CAGRs derived from program-of-record spending trajectories and R&D allocation patterns, with cross-reference to synthetic training environment procurement schedules.
Stress conditions across security clearance throughput, cloud sovereignty mandate intensity, and optical waveguide supply continuity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding NATO interoperability commitment durability and Modular Open Systems Approach enforcement consistency. Macroeconomic defense budget contraction, regulatory fragmentation in cross-border data hosting, or breakthrough advances in generative AI scenario generation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Simulation and Training
Military Simulation and Training Market
Simulation and Training
Trainer Aircraft Market
Simulation and Training
Military Training Aircraft Market
Simulation and Training
North America Ship Bridge Simulators Market
Simulation and Training
Flight Simulation Training Device Market
Simulation and Training
Asia-Pacific Civil Aviation Simulators Market
Simulation and Training
Global Military Airborne Simulation and Training Market
Simulation and Training
GNSS Simulators Market
Simulation and Training
Flight Simulator Market
Simulation and Training
Europe Flight Training and Simulation Market
Simulation and Training
Drone Simulator Market
Simulation and Training
Middle East Civil Aviation Flight Training and Simulation Market
Simulation and Training
Military Simulation Virtual Training Market
Simulation and Training
Middle East and Africa Ship Bridge Simulators Market
Simulation and Training
Satellite Simulator Market
Simulation and Training
Dynamic Flight Training Compartments Market