
 Military Simulation Virtual Training Market | 2026-2036
Military Simulation Virtual Training Market Size, Share, and Industry Trends Forecast 2026-2036
Military Simulation Virtual Training Market Intelligence
The shift towards simulation-as-a-service procurement models is reshaping competitive positioning among vendors. CAE Inc. leverages its extensive experience in civil aviation training to offer integrated service packages to defense clients. Lockheed Martin Corporation sustains its market leadership through large-scale, integrated programs for air and land combat training systems. Thales Group specializes in developing networked and interoperable training solutions for multinational coalition forces.
Military simulation virtual training employs computer-generated synthetic environments to replicate combat scenarios for personnel development. These systems utilize real-time physics engines and often adhere to interoperability standards like High-Level Architecture (HLA) to link disparate simulators. Within the technology segment, Virtual Reality and Augmented Reality are seeing accelerated use for immersive individual training. Collective Training and Mission Rehearsal formats continue to attract the largest investment from defense forces globally.
Procurement and export are heavily governed by national defense regulations, such as the United States' ITAR framework, which controls technology transfer. NATO Standardization Agreements (STANAGs) dictate interoperability requirements for systems used in joint operations among member countries. Balancing the demand for hyper-realistic fidelity against budget constraints and cybersecurity vulnerabilities remains a central strategic challenge for developers and procurers.
Market Dynamics
The convergence of artificial intelligence with demands for complex, unpredictable training is the central force defining the market. Defense forces require adaptive adversaries that challenge personnel beyond scripted scenarios, driving investment in next-generation simulation engines.
Growth Catalysts
- Military Modernization:Military modernization programs in nations like India and Poland create sustained demand for advanced flight, vehicle, and infantry simulators.
- AI Integration:The integration of artificial intelligence for dynamic adversary behavior allows for more realistic and challenging counter-terrorism or peer-competitor training.
- Paramilitary Adoption:Broadening adoption by paramilitary and border security agencies for non-conventional threat rehearsals expands the customer base beyond traditional military.
Market Restraints
- Export Controls:Stringent technology transfer regulations, particularly the United States' ITAR framework, restrict sales and collaboration opportunities in key international markets.
- Development Costs:The high upfront capital investment required for developing hyper-realistic, physics-based simulation engines creates a significant barrier to entry for new suppliers.
- Interoperability Standards:Persistent difficulty achieving seamless interoperability between disparate systems, despite standards like HLA, limits large-scale, multi-vendor exercises.
Strategic Opportunities
- Simulation-as-a-Service:Expanding simulation-as-a-service (SaaS) procurement models offers a path to serve smaller nations or agencies lacking large capital budgets.
- Haptic Integration:The integration of advanced haptic feedback and sensory immersion technologies presents a white-space opportunity for creating more effective dismounted soldier training.
- Emerging Geographies:Underpenetrated defense markets in Southeast Asia and South America represent new growth frontiers as they begin significant military modernization cycles.
Industry Challenges
- Talent Scarcity:A critical shortage of software engineers with dual expertise in military doctrine and advanced AI development constrains the pace of innovation.
- Cybersecurity Risks:Ensuring the cybersecurity of networked training systems against espionage or disruption of classified scenarios is a paramount operational hurdle.
- Legacy System Integration:Integrating modern virtual training platforms with existing, often decades-old, command and control (C2) systems presents significant technical and financial challenges.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Military Simulation Virtual Training Market |
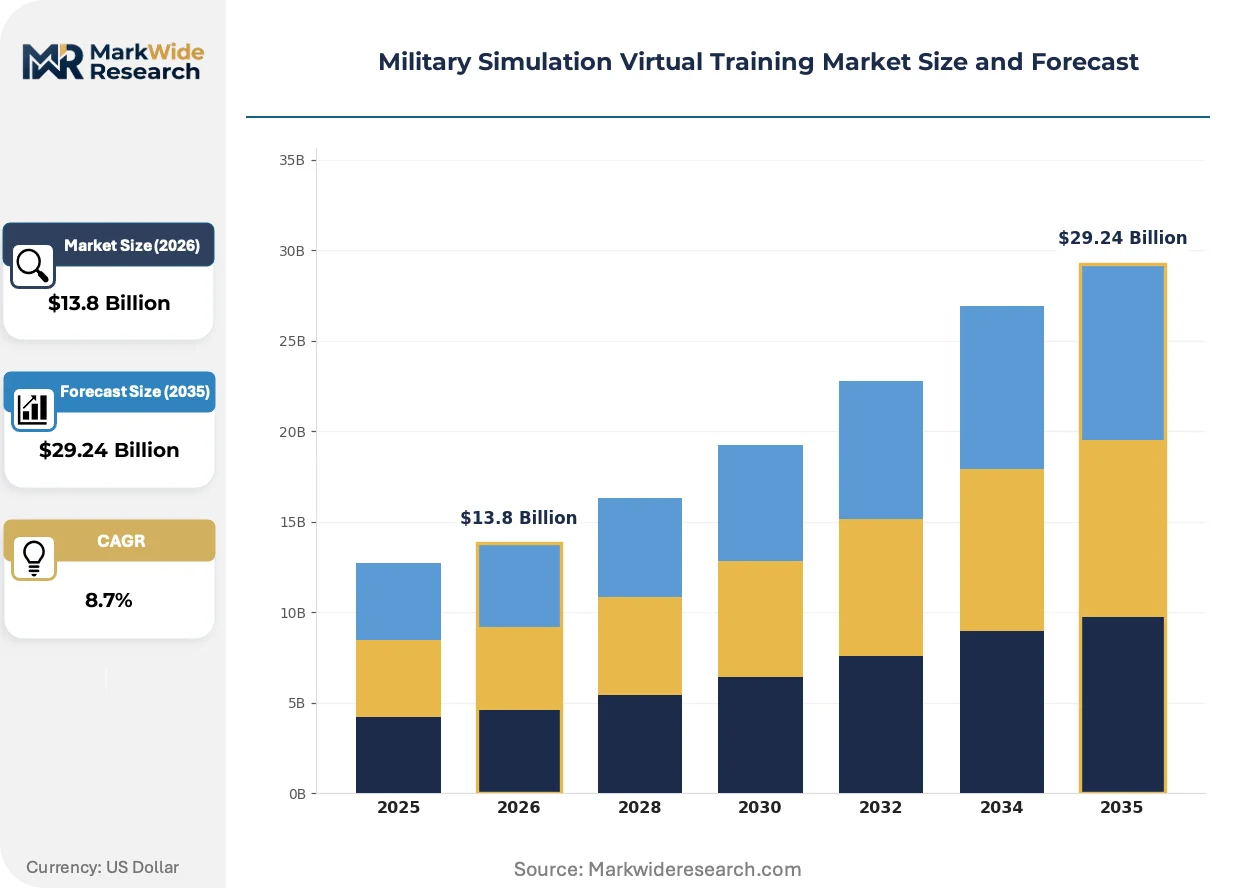
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $29.24 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Simulation Type: Live Simulation, Virtual Simulation, Constructive Simulation, Hybrid Simulation Training Format: Individual Training, Collective Training, Mission Rehearsal, Tactical Scenario Training, Command Training Technology: Augmented Reality, Virtual Reality, Mixed Reality, Artificial Intelligence, Machine Learning End User: Defense Forces, Paramilitary Units, Security Agencies, Intelligence Organizations |
| Companies Covered | CAE Inc., Lockheed Martin Corporation, Northrop Grumman Corporation, L3Harris Technologies, Inc., BAE Systems, Thales Group, Cubic Corporation, Collins Aerospace, Raytheon Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Military Simulation Virtual Training Market Strategic Shifts & Innovations
Technological advancements and evolving procurement philosophies are altering how military training is developed, delivered, and consumed. The focus shifts from standalone hardware to flexible, networked training ecosystems accessible on demand.
Cloud-based simulation platforms deliver complex scenarios on demand, reducing reliance on specialized hardware. Defense forces adopt this model for training geographically dispersed personnel without travel to central facilities. This approach is collapsing the traditional divide between individual skill-building and collective mission rehearsal.
NATO Standardization Agreements (STANAGs) increasingly mandate interoperability for systems used in joint operations. This pushes developers to build on open standards like the High-Level Architecture (HLA) over proprietary ecosystems. Air and land combat training segments are most impacted, requiring seamless data exchange for coalition exercises.
Subscription-based service models are gaining traction over traditional one-time capital equipment purchases. This shift transforms the vendor-client dynamic into an ongoing partnership focused on content updates, maintenance, and performance outcomes. The trend is most prominent within North American and European air forces for pilot training.
Military Simulation Virtual Training Market Segmentation
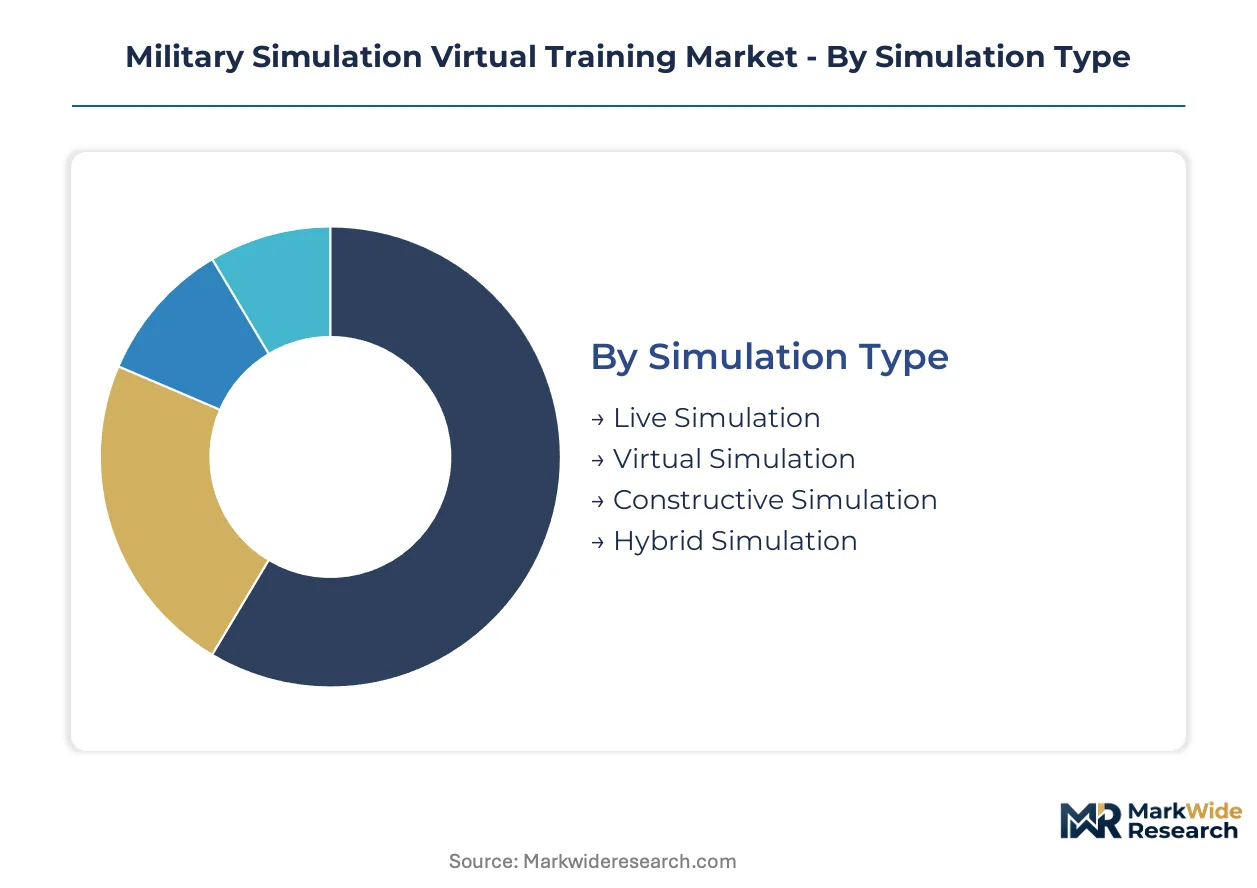
Understanding the Military Simulation Virtual Training Market through segmentation provides clarity on demand drivers and technological adoption across diverse applications. This granular analysis highlights specific areas of investment and operational focus for defense organizations.
Simulation Type:
The after-sales-service intensity varies significantly across simulation types, directly influencing long-term operational costs and vendor support requirements for complex systems.
- Virtual Simulation:This segment involves computer-generated environments for immersive training, often using head-mounted displays or large screen projections. Demand concentrates in North America and Europe for pilot and vehicle crew training, driven by the need for high-fidelity, repeatable scenarios.
- Constructive Simulation:These simulations model military operations at a command and control level, allowing staff to train on decision-making without individual participant interaction. India and Poland are increasing adoption for strategic planning and large-scale force deployment exercises, supporting military modernization.
- Live Simulation:Live simulation integrates real personnel and equipment with simulated effects, often using laser-based engagement systems. This type supports field exercises for infantry and armored units.
- Hybrid Simulation:Hybrid systems combine elements of live, virtual, and constructive simulations to create comprehensive training environments. They facilitate complex multi-echelon exercises.
By volume, Virtual Simulation leads. By growth pace, Hybrid Simulation is ahead.
Training Format:
Application diversity defines the training format segment, catering to distinct operational readiness requirements from individual skill development to large-scale mission execution.
- Collective Training:This format focuses on developing teamwork and coordination among multiple personnel or units within a simulated environment. Defense forces globally prioritize collective training for unit cohesion and operational effectiveness.
- Mission Rehearsal:Mission rehearsal prepares specific units for upcoming operations by simulating actual mission parameters and potential adversary responses. This format attracts significant investment from special operations forces in the United States and the United Kingdom.
- Individual Training:Individual training focuses on developing specific skills for single operators, such as marksmanship or vehicle operation. It builds foundational competencies for military personnel.
- Tactical Scenario Training:This format involves replicating specific tactical situations to test decision-making and response protocols. It is crucial for preparing units for diverse combat environments.
- Command Training:Command training exercises leadership and strategic decision-making skills for officers and senior staff. It develops capabilities for managing complex operations.
Investment in Collective Training and Mission Rehearsal remains strategically important for global defense forces.
Technology:
The maturity of various technologies dictates their current market penetration and future growth trajectories, with advanced solutions rapidly gaining traction.
- Artificial Intelligence:AI integration provides adaptive and unpredictable adversaries within simulation environments, enhancing training realism. Investment is accelerating in nations like the United States and Israel for advanced counter-terrorism and peer-competitor training.
- Virtual Reality:VR systems create immersive synthetic environments for individual training, offering high fidelity and cost-effectiveness compared to physical training. Accelerated use is evident across air forces for pilot training in North America and Europe.
- Augmented Reality:AR overlays digital information onto the real world, enhancing situational awareness during live exercises. It supports maintenance and operational guidance.
- Mixed Reality:MR blends virtual and real-world elements, allowing interaction with both physical and digital objects simultaneously. This technology offers advanced interactive training scenarios.
- Machine Learning:ML algorithms analyze trainee performance and adapt simulation parameters in real-time, personalizing the learning experience. It underpins dynamic adversary behavior.
Artificial Intelligence and Virtual Reality are receiving substantial development focus for next-generation training systems.
End User:
Customer type influences procurement cycles and the specific requirements for simulation fidelity and scale, driving tailored solution development.
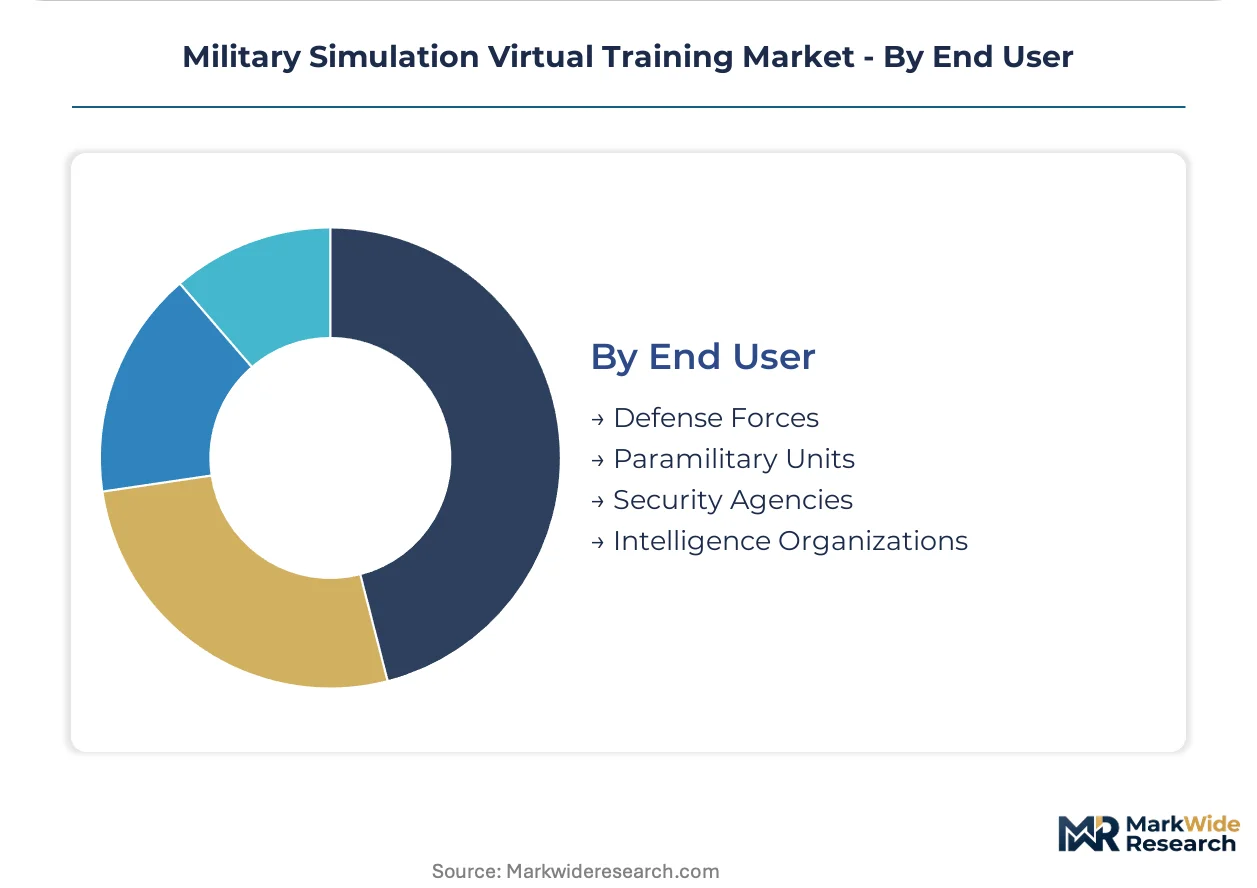
- Defense Forces:This segment includes national armies, navies, and air forces, representing the largest proportion of military simulation virtual training procurement. Modernization programs in India and Poland are driving substantial demand.
- Paramilitary Units:Paramilitary forces, including border security and internal security agencies, adopt virtual training for counter-terrorism and non-conventional threat rehearsals. Broadening adoption expands the customer base beyond traditional military applications.
- Security Agencies:These agencies utilize simulations for intelligence analysis training and critical infrastructure protection scenarios. They require secure and often classified training environments.
- Intelligence Organizations:Intelligence organizations employ virtual training for data analysis, scenario planning, and operational readiness for covert missions. Their needs often involve highly specialized and secure platforms.
The expanding customer base to Paramilitary Units indicates a diversification of market demand beyond core Defense Forces.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The extensive military infrastructure across global regions underwrites the diverse demand for simulation virtual training. National defense strategies and evolving threat landscapes shape procurement priorities in various geographies. Modernization programs and technological integration efforts are driving significant investment in advanced training systems worldwide.
United States
Demand for advanced training systems in the United States is driven by special operations forces investment and AI/VR technology integration. The ITAR framework strictly controls technology transfer, impacting export opportunities. Silicon Valley and other tech hubs concentrate expertise in AI and virtual reality development for defense applications.
India
India's significant military modernization programs create sustained demand for advanced flight, vehicle, and infantry simulators. The PLI scheme supports domestic defense manufacturing and technology adoption. Bengaluru and Hyderabad serve as key centers for defense R&D and simulation software development.
Poland
Poland's ongoing military modernization initiatives increase adoption of constructive simulation for strategic planning. NATO Standardization Agreements (STANAGs) dictate interoperability requirements for systems used in joint operations. Warsaw and other defense industry hubs are expanding capabilities in networked training solutions.
United Kingdom
Investment in mission rehearsal formats by special operations forces drives demand for highly realistic virtual training systems in the United Kingdom. The UK export control regulations govern military technology sales. London and Farnborough are central to aerospace and defense innovation, fostering simulation technology.
Israel
Israel's focus on advanced counter-terrorism and peer-competitor training accelerates AI integration into simulation environments. The country's defense export controls manage sensitive technology dissemination. Tel Aviv's tech ecosystem is a significant hub for developing cutting-edge AI and simulation capabilities.
Military Simulation Virtual Training Market Key Industry Players
On the supply side, the industry is characterized by a mix of large, diversified defense contractors and specialized simulation technology providers. Strategic archetypes include integrated system providers, software-centric developers, and service-oriented trainers. Companies pursue competitive positioning through strategic partnerships to enhance interoperability and by investing in advanced R&D for AI and immersive technologies. Geographic expansion into emerging defense markets also represents a key competitive move for several vendors.
Among established defense contractors, Lockheed Martin Corporation and Northrop Grumman Corporation exemplify companies offering large-scale, integrated programs for air and land combat training systems. CAE Inc. represents a specialized entity leveraging extensive experience from civil aviation to offer integrated service packages to defense clients, emphasizing simulation-as-a-service models. These entities focus on expanding their service offerings and integrating advanced technologies like AI and immersive VR/AR to meet evolving military demands for complex, unpredictable training scenarios.
| Leading Market Players |
|---|
| CAE Inc. |
| Lockheed Martin Corporation |
| Northrop Grumman Corporation |
| L3Harris Technologies, Inc. |
| BAE Systems |
| Thales Group |
| Cubic Corporation |
| Collins Aerospace |
| Raytheon Technologies |
Cost & Logistics Intelligence
Undercapacity in specialized AI development talent across defense contractors influences both supplier behavior and the pricing posture for advanced simulation systems. This scarcity drives up development costs and encourages vendors to offer long-term service contracts to secure expertise.
Pricing Analysis
Volume-discount tiering structures often apply to large-scale procurements, incentivizing defense ministries to consolidate orders for simulation systems. Subscription-based service models are gaining traction, providing access to updated content and software licenses rather than outright purchases. Price differentiation stems from the level of customization required for specific military doctrines and the extent of after-sales service and support. Pricing pressure arises from national defense budget constraints, especially for smaller nations or paramilitary units. Special operations forces generally exhibit lower price sensitivity for hyper-realistic, mission-critical rehearsal systems.
Supply Chain Analysis
Contract manufacturing capacity for high-fidelity simulation hardware primarily resides with established defense contractors in the United States, Europe, and Israel. The supply chain draws from specialized components, including high-performance computing hardware, advanced optical systems for VR/AR displays, and sophisticated physics engines. A key structural risk involves stringent export controls, such as the United States' ITAR framework, which limits technology transfer and international collaboration. Distribution runs predominantly through direct sales channels to defense ministries, often involving multi-year procurement contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The military simulation virtual training market faces a critical shortage of software engineers possessing dual expertise in military doctrine and advanced AI development. This capability gap necessitates strategic talent acquisition and specialized training programs.
For Market Incumbents:
Insulate market share by deepening integration with core defense clients through long-term, performance-based service contracts, leveraging existing trust and infrastructure. Invest heavily in advanced AI research and development to stay ahead of emerging technology firms, particularly in dynamic adversary generation. Form strategic partnerships with AI ethics and cybersecurity specialists to mitigate risks associated with networked training systems. Focus on secure cloud-based delivery models to enhance accessibility and reduce hardware dependency for clients.
For New Entrants and Emerging Players:
Underpenetration in Southeast Asian and South American defense markets represents a significant growth frontier for agile new players. Target paramilitary units and border security agencies with specialized, cost-effective VR/AR solutions for individual dismounted soldier training. A go-to-market angle focusing on simulation-as-a-service models can serve smaller nations lacking large capital budgets for upfront system purchases. Develop modular, open-standard platforms to facilitate easier integration with existing legacy systems, addressing a key industry challenge.
For Investors and Strategic Acquirers:
Long-term, this sits as a strategic infrastructure play because global military modernization programs and the imperative for realistic, complex training scenarios will persist. Identify acquisition targets that are software-centric developers specializing in AI/ML for dynamic adversary generation or advanced haptic feedback systems. A key signal to watch is the increasing allocation of defense spending specifically toward virtual training and simulation platforms in emerging markets. Focus on companies with strong intellectual property in immersive technologies and secure cloud delivery.
| Strategic Initiative | Industry Significance |
|---|---|
| Launch Cloud-based Simulation Platform | Reduces hardware dependency and expands accessibility for geographically dispersed personnel. |
| Form Strategic Partnership for AI Ethics Research | Mitigates cybersecurity risks and ensures responsible development of adaptive adversaries. |
| Acquire Haptic Technology Developer | Enhances sensory immersion for dismounted soldier training, improving realism. |
| Expand into Southeast Asian Defense Markets | Captures new growth from nations undergoing military modernization cycles. |
| Integrate with Legacy Command & Control Systems | Addresses technical challenges and financial hurdles for defense forces with existing infrastructure. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with industry stakeholders and secondary validation from defense publications. We engaged with military procurement officers, simulation engineers, defense contractors, and policy analysts to gather firsthand perspectives. Secondary data sources included defense ministry reports, NATO standardization documents, aerospace and defense industry journals, and technology patent databases. This approach enabled bottom-up market sizing and top-down validation for comprehensive market understanding.
Forecast inputs considered military modernization budgets, AI integration roadmaps, and evolving threat landscapes across the analysis window. The analytical framework modeled segmentation dimensions including simulation type, training format, technology, end-user, and regional defense spending. Compound Annual Growth Rates were derived from historical data trends and projected technological adoption curves. Key industry-specific forecast inputs included defense force personnel numbers and interoperability standard adoption rates.
The forecast holds incumbent behavior within observed patterns; aggressive moves by major defense contractors or disruptive tech startups would shift outcomes. The analysis reflects assumptions regarding sustained defense spending and continued technological advancements. Quarterly review of defense procurement announcements and R&D investment trends is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Simulation and Training
Air Traffic Control Simulation and Training Market
Simulation and Training
Pilot Training Market
Simulation and Training
Civil Aviation Simulator Market
Simulation and Training
Middle East and Africa Ship Bridge Simulators Market
Simulation and Training
Simulators Market
Simulation and Training
Military Simulation and Training Market
Simulation and Training
Asia-Pacific Civil Aviation Simulators Market
Simulation and Training
RADAR Simulator Market
Simulation and Training
North America Ship Bridge Simulators Market
Simulation and Training
Air Traffic Control Simulator and Training Market
Simulation and Training
Asia-Pacific Ship Bridge Simulators Market
Simulation and Training
Military Vehicles and Aircraft Simulations Market
Simulation and Training
UAV Flight Training and Simulation Market
Simulation and Training
Global Military Airborne Simulation and Training Market
Simulation and Training
Flight Simulation Training Device Market
Simulation and Training
Military Simulation Software Market