
 Flight Simulator Market | 2026-2036
Flight Simulator Market Size, Share, and Industry Trends Forecast 2026-2036
Flight Simulator Market Intelligence
The commercial airlines segment is consolidating its position as the primary end-user, outpacing defense organizations in simulator procurement volume. CAE Inc. leverages its extensive network of training centers to serve this commercial demand. Thales Group specializes in high-fidelity simulators for both civil and military platforms. FlightSafety International dominates the business and general aviation training sectors.
A flight simulator is a device that artificially re-creates aircraft flight and the environment in which it flies. These systems integrate a motion cueing platform with a high-resolution visual scene generator to provide realistic kinesthetic and visual feedback. Full Flight Simulators represent the largest product type, essential for final certification training. The adoption of Artificial Intelligence is enhancing the realism of emergency response drills.
Regulatory bodies including the US Federal Aviation Administration (FAA) and the European Union Aviation Safety Agency (EASA) dictate certification standards for simulators used in pilot licensing. These standards, such as Level D for Full Flight Simulators, ensure training hours are transferable to actual flight time. The key decision for operators is how to invest in simulator upgrades to meet new aircraft technologies and evolving cybersecurity requirements.
Market Dynamics
The central structural force shaping the flight simulator market is the direct linkage between escalating regulatory requirements and a persistent global pilot shortage. Mandates from the FAA and EASA for recurrent, competency-based training create non-discretionary demand for simulator hours.
Growth Catalysts
- Regulatory Mandates:Directives from the European Union Aviation Safety Agency (EASA) and the US Federal Aviation Administration (FAA) require continuous proficiency checks and type-rating training, making simulator use a mandatory operational cost for airlines.
- Airline Fleet Expansion:Rapid expansion of commercial airline fleets, particularly in China and India, generates a direct and proportional need for new pilots, which in turn requires a significant increase in simulator-based training capacity.
- New Aircraft Introductions:The entry of new aircraft models into service necessitates the development and procurement of corresponding full flight simulators for pilot certification and transition training, as seen with modern narrow-body and wide-body jets.
Market Restraints
- High Capital Expenditure:The procurement cost for a single Level D Full Flight Simulator, including its motion and visual systems, represents a significant capital investment, limiting accessibility for smaller airlines and training organizations.
- Component Supply Bottlenecks:The supply chain for specialized components, such as high-performance projectors for visual systems and actuators for motion platforms, is highly concentrated, creating risks of production delays and price volatility.
- Technical Replication Limits:Simulators still face limitations in perfectly recreating certain complex flight conditions, such as severe icing, specific aerodynamic stalls, or unusual aircraft-ground interactions, which remain a technical barrier.
Strategic Opportunities
- Urban Air Mobility Training:The development of electric vertical take-off and landing (eVTOL) aircraft for urban air mobility presents a new frontier for simulator manufacturers to design novel training devices for an entirely new class of pilots.
- AI and VR Integration:Combining Artificial Intelligence for adaptive scenarios with lower-cost Virtual Reality hardware offers an opportunity to deliver customized, high-repetition procedural training outside of expensive full flight simulators.
- Emerging Market Training Centers:Establishing new pilot training infrastructure in underserved but fast-growing aviation regions, such as Southeast Asia and Africa, can capture demand from nascent national and regional airlines.
Industry Challenges
- Simulator Technician Scarcity:A critical shortage of qualified engineers and technicians capable of maintaining, repairing, and upgrading these highly complex devices creates operational bottlenecks and increases downtime for training centers.
- Cybersecurity Vulnerabilities:As simulators become more networked for remote diagnostics and data exchange, they become increasingly vulnerable to cyberattacks that could compromise training integrity or steal sensitive flight data.
- Certification Cycle Times:The lengthy and rigorous process to achieve and maintain certification from aviation authorities like the FAA for simulator upgrades or new models can delay the deployment of training for new aircraft types.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flight Simulator Market |
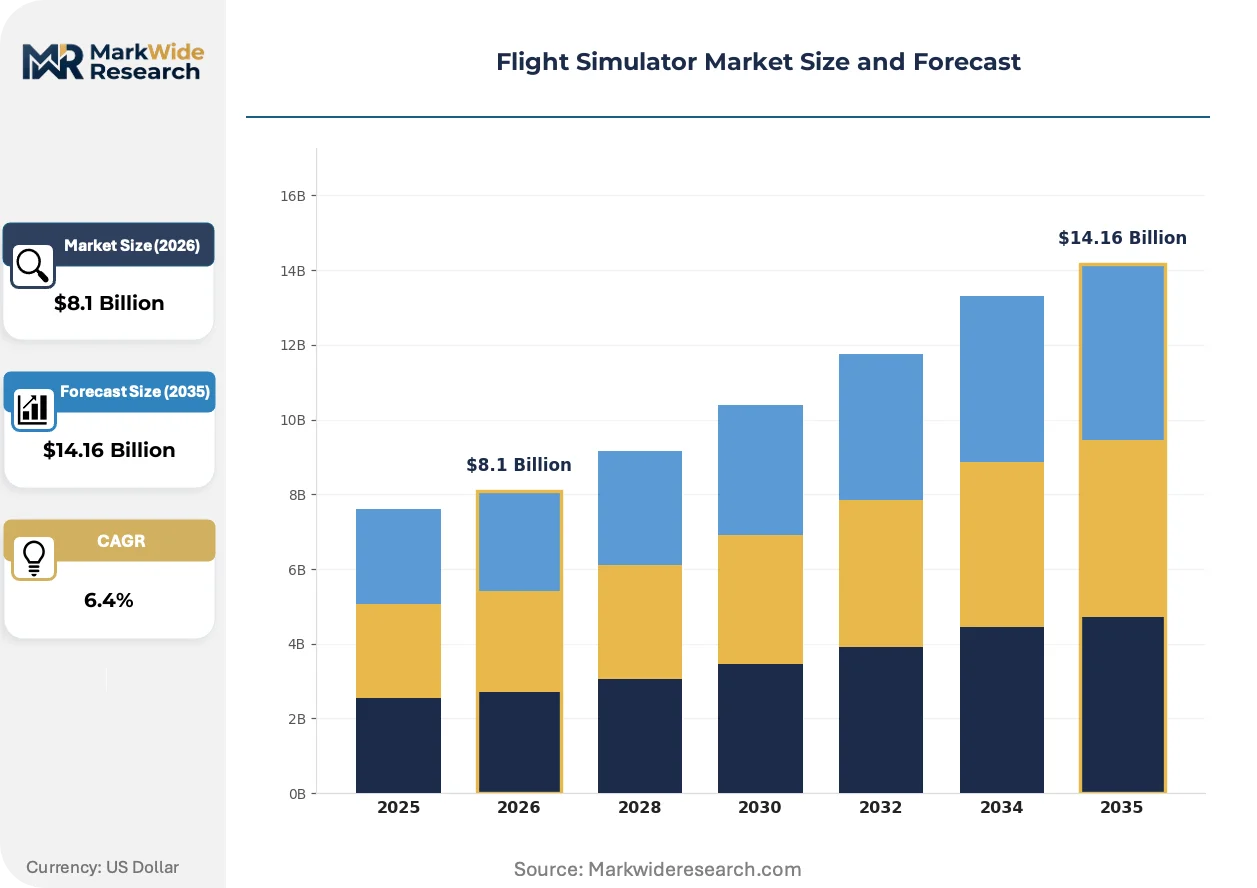
| Market Size in 2026 | $8.1 Billion |
| Market Size in 2035 | $14.16 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Full Flight Simulator, Fixed Base Simulator, Procedure Trainer, Desktop Simulator, Virtual Reality Simulator Technology: Augmented Reality, Motion Cueing, Visual Scene Generator, Haptic Feedback, Artificial Intelligence Application: Pilot Training, Air Traffic Control, Military Defense, Aircraft Design Validation, Emergency Response Drills End User: Flight Schools, Defense Organizations, Commercial Airlines, Aviation Research Centers, Charter Operators |
| Companies Covered | Thales Group, Lockheed Martin Corporation, CAE Inc., Airbus, Collins Aerospace, L3Harris Technologies, Boeing, Leonardo S.p.A., FlightSafety International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flight Simulator Market Strategic Shifts & Innovations
The market is advancing toward data-driven, hyper-realistic training environments. This evolution prioritizes the development of cognitive skills and decision-making under pressure over the simple repetition of standardized maneuvers, enabled by new technologies and training philosophies.
Artificial Intelligence Artificial intelligence is being integrated to create adaptive and dynamic training scenarios. Commercial airlines and military flight schools are adopting AI to improve pilot decision-making and stress response. This data-driven approach is overtaking static, pre-scripted emergency drills by providing more realistic and unpredictable training environments that better prepare pilots for unforeseen events.
Regulatory Frameworks Regulatory mandates for Evidence-Based Training (EBT), promoted by ICAO and adopted by the FAA and EASA, are altering curricula. This philosophy shifts training from rote maneuver repetition to developing core competencies identified through operational flight data. Commercial airline training programs are most affected, forcing investment in data analytics and the adaptation of simulator sessions to target specific, data-proven pilot weaknesses.
Service-Based Models A shift toward "power-by-the-hour" and subscription-based service contracts is altering equipment procurement. This model gives smaller airlines and business aviation operators access to high-end simulator devices without the prohibitive upfront capital expenditure, disrupting the traditional direct sales channel. This trend is most prominent among general aviation fleets and low-cost carriers in Europe seeking flexible operating expenses.
Flight Simulator Market Segmentation
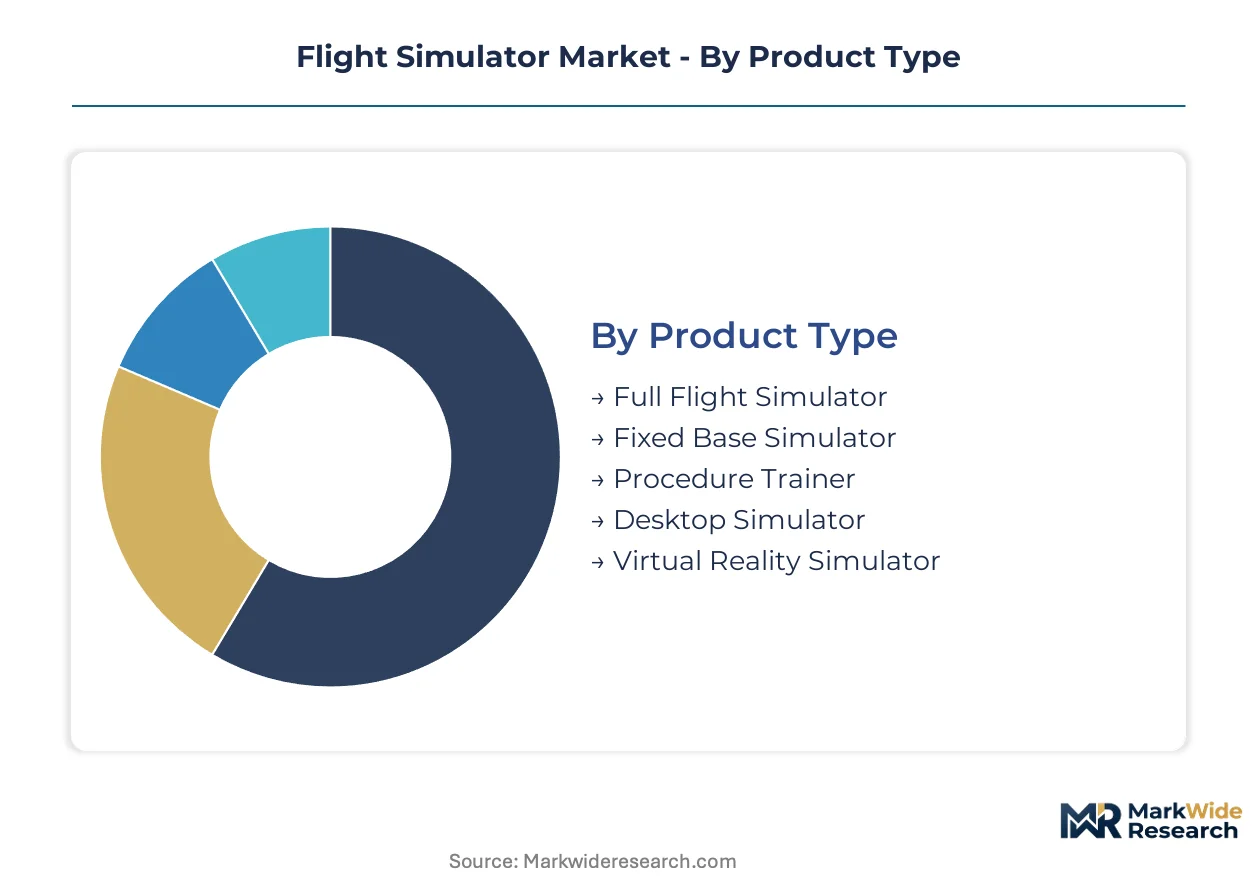
The Flight Simulator Market segmentation provides a granular view of device types, underlying technologies, diverse applications, and primary end-users. Understanding these divisions reveals specific demand pockets and technological evolution driving industry growth. This analysis highlights areas of concentrated investment and emerging opportunities.
Product Type:
The market's product type segmentation highlights the varying levels of fidelity and complexity offered by different simulator systems.
- Full Flight Simulator:Full Flight Simulators precisely replicate aircraft cockpits and flight dynamics with full motion systems. Demand concentrates among commercial airlines globally, driven by stringent regulatory mandates for pilot certification and recurrent training.
- Virtual Reality Simulator:Virtual Reality Simulators utilize VR headsets and haptic feedback to create immersive training environments at a lower cost. Pilot training organizations in Europe are increasingly adopting these for procedural and basic flight instruction, offering scalable solutions.
- Fixed Base Simulator:Fixed Base Simulators offer realistic cockpit environments without full motion, suitable for procedural and instrument flight training.
- Procedure Trainer:Procedure Trainers focus on specific aircraft systems and operational procedures, enhancing pilot proficiency in complex tasks.
- Desktop Simulator:Desktop Simulators provide basic flight simulation on personal computers, used for preliminary pilot familiarization and hobbyist use.
Full Flight Simulators lead on scale; Virtual Reality Simulators represent the fastest-growing trajectory.
Technology:
Segmentation by technology reveals the core innovations enhancing simulator realism and training effectiveness.
- Artificial Intelligence:Artificial Intelligence integration creates adaptive and dynamic training scenarios, improving pilot decision-making under pressure. Military flight schools and commercial airlines in the US are adopting AI for realistic emergency response drills, moving beyond static scripts.
- Motion Cueing:Motion Cueing systems provide physical sensations of acceleration, vibration, and turbulence, crucial for immersive flight experiences. High-fidelity simulators for new aircraft models depend on advanced motion cueing to meet certification standards.
- Visual Scene Generator:Visual Scene Generators render high-resolution external views, critical for realistic environmental and airport depictions.
- Haptic Feedback:Haptic Feedback systems simulate tactile sensations for controls and switches, enhancing realism for pilot interaction.
- Augmented Reality:Augmented Reality overlays digital information onto real-world views, offering new possibilities for maintenance and procedural training.
Artificial Intelligence is increasingly foundational for advanced training; Motion Cueing remains a cornerstone for high-fidelity devices.
Application:
The application landscape demonstrates the diverse operational contexts where flight simulators provide critical value.
- Pilot Training:Pilot Training is the primary application, covering initial certification, type ratings, and recurrent proficiency checks for all aviation sectors. Commercial airlines in China are heavily investing in simulators for pilot training to meet fleet expansion demands.
- Emergency Response Drills:Emergency Response Drills utilize simulators to practice critical procedures for unforeseen events, enhancing crew coordination and decision-making. Regulatory bodies like EASA mandate these drills, driving simulator use for safety compliance.
- Air Traffic Control:Air Traffic Control simulators train controllers in managing airspace, handling complex traffic scenarios, and emergency procedures.
- Military Defense:Military Defense applications include tactical flight training, mission rehearsal, and weapon system familiarization for defense personnel.
- Aircraft Design Validation:Aircraft Design Validation employs simulators to test new aircraft prototypes and systems before physical construction or flight.
Pilot Training drives the largest volume; Emergency Response Drills exhibit significant regulatory-driven expansion.
End User:
End-user segmentation clarifies the primary consumer groups driving demand and investment in flight simulation technology.
- Commercial Airlines:Commercial Airlines represent the largest end-user segment, procuring simulators for extensive pilot training and regulatory compliance. Fleet expansion and continuous proficiency requirements from the FAA sustain high demand in this sector.
- Defense Organizations:Defense Organizations utilize simulators for military pilot training, mission rehearsal, and tactical development across various platforms. Global defense spending increases and complex mission profiles necessitate advanced simulation capabilities.
- Flight Schools:Flight Schools offer initial pilot training and advanced ratings, relying on simulators for cost-effective instruction.
- Aviation Research Centers:Aviation Research Centers use simulators for human factors studies, new technology integration, and aerodynamic research.
- Charter Operators:Charter Operators require simulators for pilot recurrent training and type ratings to maintain operational readiness and safety standards.
Commercial Airlines command the highest procurement; Aviation Research Centers demonstrate specialized, high-fidelity needs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage influences flight simulator market dynamics, as regions with less stringent certification processes or lower operational costs attract certain training investments. However, the critical need for high-fidelity training, driven by global aviation safety standards, often necessitates investment in advanced systems regardless of immediate cost differentials. This creates a complex interplay between regulatory compliance and economic efficiency across major aviation hubs.
United States
Demand for flight simulators in the United States stems from extensive commercial airline pilot training and military defense programs. The US Federal Aviation Administration (FAA) mandates rigorous proficiency checks and type-rating training, directly sustaining simulator demand. Major aviation training centers in Florida and Arizona are expanding capacity to meet both domestic and international pilot training quotas.
China
China's rapid commercial airline fleet expansion drives significant procurement of new flight simulators for pilot training. The Civil Aviation Administration of China (CAAC) enforces strict pilot certification requirements, necessitating substantial simulator investment. Aviation training academies in cities like Beijing and Shanghai are becoming central to the country's ambitious pilot workforce development.
Germany
European demand for flight simulators, particularly in Germany, arises from continuous pilot competency assessments for commercial and cargo carriers. The European Union Aviation Safety Agency (EASA) sets the certification standards for Level D Full Flight Simulators, ensuring training hours are transferable. Training facilities near Frankfurt and Munich serve as key hubs for advanced pilot and maintenance crew instruction.
India
India experiences a surge in flight simulator demand due to its expanding domestic airline fleets and associated pilot shortage. The Directorate General of Civil Aviation (DGCA) mandates specific simulator hours for pilot licensing and recurrent training. Aviation training organizations in Bangalore and Hyderabad are rapidly increasing their simulator infrastructure to support new pilot cohorts.
United Kingdom
The United Kingdom's flight simulator market benefits from established aerospace industries and significant defense spending. UK Civil Aviation Authority (CAA) regulations align with EASA standards, requiring continuous professional development for pilots. Training centers around London and the aerospace cluster in Bristol are pivotal for both commercial airline and military flight simulation.
Flight Simulator Market Key Industry Players
Capacity expansion dominates the current landscape, driven by escalating pilot training quotas and the introduction of new aircraft models. The market exhibits a tiered structure, with a few large, integrated players alongside numerous specialized technology providers. Strategic archetypes include full-service training organizations offering end-to-end solutions, dedicated high-fidelity simulator manufacturers, and software integrators focusing on advanced simulation technologies. Key competitive moves involve strategic partnerships to broaden service offerings and portfolio diversification into emerging areas like urban air mobility.
Among the established aerospace and defense conglomerates, Thales Group exemplifies a major player providing high-fidelity simulators for both civil and military platforms. CAE Inc., a Canadian corporation, occupies a position as a leading global provider of training solutions, leveraging its extensive network of training centers for commercial airlines. FlightSafety International, an Inc. company, anchors the business and general aviation training sectors, representing a specialized full-service training provider. These entities collectively demonstrate the diverse approaches to market penetration, from broad defense and civil aviation portfolios to highly focused general aviation training.
| Leading Market Players |
|---|
| Thales Group |
| Lockheed Martin Corporation |
| CAE Inc. |
| Airbus |
| Collins Aerospace |
| L3Harris Technologies |
| Boeing |
| Leonardo S.p.A. |
| FlightSafety International |
| Others |
Cost & Logistics Intelligence
Specialized simulator manufacturers, often backed by private equity or large aerospace conglomerates, dictate both supply behavior and pricing discipline across the flight simulator market. This ownership structure enables significant control over high-fidelity component sourcing and intellectual property.
Pricing Analysis
Direct-to-OEM discount structures are prevalent for large commercial airline and defense contracts, reflecting long-term purchasing agreements. The dominant pricing model is project-based, tailored for each simulator unit or training center setup, often including extensive after-sales service bundles. Price differentiation stems from the simulator's Level D certification grade and the specific aircraft type replication. Pricing softness reflects intense competition for major commercial airline contracts, particularly in rapidly expanding Asian markets. Commercial airlines are generally less price-sensitive for Level D Full Flight Simulators due to regulatory mandates, while smaller flight schools exhibit higher price sensitivity.
Supply Chain Analysis
Visual scene generator supply rests heavily on specialized optical component manufacturers in Germany and Japan, alongside high-performance computing hardware from the United States. Key raw material dependencies include specialized alloys for motion platforms and advanced composites for cockpit replicas. A structural supply chain risk is the highly concentrated market for high-fidelity projector systems, creating single-source vulnerabilities. Distribution typically runs through direct sales channels from simulator manufacturers to airlines, defense organizations, and large flight training academies, often bundled with installation and maintenance contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The flight simulator market represents a margin-expansion story, driven by the shift towards service-based models and the premium associated with advanced AI-integrated training solutions.
For Market Incumbents: Cement market leadership by investing in next-generation simulator technologies, particularly advanced AI for adaptive training scenarios. This defends against emerging threats from lower-cost VR solutions and ensures compliance with evolving regulatory standards like Evidence-Based Training. Control over critical component supply chains through strategic partnerships or backward integration serves as a key lever to mitigate component bottlenecks.
For New Entrants and Emerging Players: EASA and FAA regulatory directives for competency-based training open a window for specialized software developers focusing on AI-driven adaptive learning modules. Target the underserved business and general aviation sectors with cost-effective, VR-integrated procedural trainers. A go-to-market angle emphasizing rapid customization and flexible subscription models can bypass the high capital expenditure barrier of full flight simulators.
For Investors and Strategic Acquirers: Valuations sit cheapest among legacy fixed-base simulator manufacturers lacking significant software or AI integration capabilities. Long-term viability hinges on companies demonstrating a clear path to integrate AI and VR for scalable, data-driven training solutions. A signal to watch is the increasing adoption rate of Evidence-Based Training methodologies by major airlines, indicating a readiness for advanced simulation platforms.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop AI-Powered Adaptive Training Modules | This initiative enhances realism and personalization, improving pilot decision-making under pressure for commercial airlines. |
| Expand Training Center Network in Southeast Asia | This action captures demand from nascent national and regional airlines, addressing the pilot shortage in fast-growing aviation regions. |
| Offer Subscription-Based Simulator Access | This model lowers upfront costs for smaller operators, democratizing access to high-fidelity training devices. |
| Invest in eVTOL Simulation R&D | This move positions manufacturers to capture the emerging urban air mobility market, designing novel training devices. |
| Strengthen Cybersecurity for Simulator Networks | This protects training integrity and sensitive flight data, addressing a critical vulnerability for defense organizations. |
Research Approach
Direct dialogue with commercial airline training heads, defense procurement officers, flight school instructors, and simulator engineers formed the qualitative grounding for this analysis. These primary insights were rigorously validated against secondary data from aviation authority reports, aircraft manufacturer technical specifications, and aerospace industry publications. The research employed both bottom-up and top-down triangulation to ensure comprehensive data coverage and accuracy.
Volume and value outputs were derived from a multi-factor analytical framework, projecting growth across the analysis window. The model segmented the market by product type, technology, application, end-user, and key geographic regions, with simulator utilization rates serving as a critical input. CAGRs were calculated by assessing historical growth trends and applying forward-looking projections based on fleet expansion plans and regulatory changes.
Revisions become necessary when significant shifts in global aviation regulations, major aircraft program delays, or unexpected economic downturns materialize. Forecasts reflect assumptions regarding pilot training quotas and technology adoption rates for new simulator platforms. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Simulation and Training
Drone Simulator Market
Simulation and Training
Middle East and Africa Ship Bridge Simulators Market
Simulation and Training
Military Aerospace Simulation and Training Market
Simulation and Training
Civil Aviation Simulator Market
Simulation and Training
Police and Military Simulation Training Market
Simulation and Training
Pilot Training Market
Simulation and Training
Europe Ship Bridge Simulators Market
Simulation and Training
Middle East Civil Aviation Flight Training and Simulation Market
Simulation and Training
Military Simulation and Training Market
Simulation and Training
North America Simulator Windows and Simulator Skylights Market
Simulation and Training
Asia-Pacific Ship Bridge Simulators Market
Simulation and Training
Helicopter Simulator Market
Simulation and Training
Global Healthcare Games and Simulation Market
Simulation and Training
Military Simulation Software Market
Simulation and Training
Asia-Pacific Civil Aviation Simulators Market
Simulation and Training
Global Military Airborne Simulation and Training Market