
 Simulators Market | 2026-2036
Simulators Market Size, Share, and Industry Trends Forecast 2026-2036
Simulators Market Analysis
Defense forces and automotive manufacturers are bifurcating the buyer landscape, with military end users gaining share through multi-domain training mandates. CAE Inc. dominates commercial aviation simulation through captive supply of full-flight simulators and integrated training services. Thales Group leverages its European installed base to sustain defense simulation contracts across NATO member states. L3Harris Technologies, Inc. competes in military flight training systems with hardware-software architectures tailored to fifth-generation fighter platforms.
Simulators are engineered systems that replicate operational environments through motion platforms, visual databases, and computational physics models achieving six-degrees-of-freedom articulation and sub-20-millisecond latency for vestibular fidelity. Their primary purpose is to transfer procedural competence and decision-making reflexes to operators without exposing personnel or equipment to live-environment risks. Aerospace application leads in value terms due to regulatory-mandated recurrent training and the capital intensity of Level D full-flight devices. Virtual Reality technology is displacing legacy projection dome architectures in medical training and driving segments where portability and scenario density outweigh motion cueing requirements. Cloud-based deployment is expanding fastest among educational institutions seeking distributed access to simulation content without on-site infrastructure investment.
FAA Part 60 and EASA CS-FSTD regulations govern flight simulator qualification levels, directly determining market access for device manufacturers and operator training center certification. FDA guidance on medical device validation and ISO 13485 quality management shape healthcare simulation product development pathways in the United States and European markets. MEE dual carbon goals and MIIT industrial standards in China are redirecting domestic simulator procurement toward energy-efficient motion systems and indigenous visual rendering engines. Stakeholders must monitor evolving certification reciprocity agreements between national aviation authorities and assess whether cloud-streamed simulation hours will achieve regulatory equivalence with physical device time.
Market Dynamics
Regulatory mandates for training fidelity are compressing replacement cycles across aviation and defense sectors, forcing simulator manufacturers to prioritize motion platform latency reduction and visual system resolution upgrades over incremental hardware refreshes.
Growth Catalysts
- FAA Part 60 Recertification Mandates:United States flight training centers must upgrade legacy devices to meet revised qualification standards, accelerating capital deployment into Level D full-flight simulators with enhanced motion cueing.
- Live-Virtual-Constructive Architectures:NATO defense procurement offices are integrating synthetic training environments with live range operations, requiring interoperable simulation protocols across joint force exercises.
- Cloud-Streamed Simulation:Educational institutions in Germany and Australia are adopting browser-accessible training modules, eliminating on-site infrastructure while expanding scenario libraries for distributed learner cohorts.
Market Restraints
- Motion Platform Supply Concentration:Electro-hydraulic actuator production clusters in Japan and Germany create single-source dependencies for six-degrees-of-freedom systems, amplifying lead time volatility.
- Visual Database Development Costs:Photorealistic terrain rendering for military training requires satellite imagery licensing and geospatial data rights that consume 35-45% of program budgets.
- EASA CS-FSTD Reciprocity Gaps:Divergent national aviation authority interpretations of cross-border simulator hour recognition fragment training center certification pathways.
Strategic Opportunities
- Saudi Arabia Defense Modernization:GAMI localization targets are redirecting fighter pilot training procurement toward in-country simulation centers with indigenous maintenance capabilities.
- Extended Reality Convergence:Mixed reality headsets combined with haptic gloves are creating portable medical procedure trainers for emergency medicine residents in India and Brazil.
- EU Green Deal Motion Efficiency:Electric motion platforms consuming 60% less energy than hydraulic alternatives qualify for EIB sustainable infrastructure financing in Netherlands and Denmark training facilities.
Industry Challenges
- Embedded Software Engineer Scarcity:Real-time physics modeling and rendering pipeline optimization require specialized talent pools concentrated in Montreal, Toulouse, and Bangalore aerospace clusters.
- Level D Certification Timelines:FAA and EASA joint qualification reviews for new full-flight simulators extend 18-24 months, compressing revenue recognition windows for device manufacturers.
- Interoperability Protocol Fragmentation:DIS, HLA, and emerging open simulation architecture standards create integration complexity for defense contractors assembling multi-vendor training systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Simulators Market |
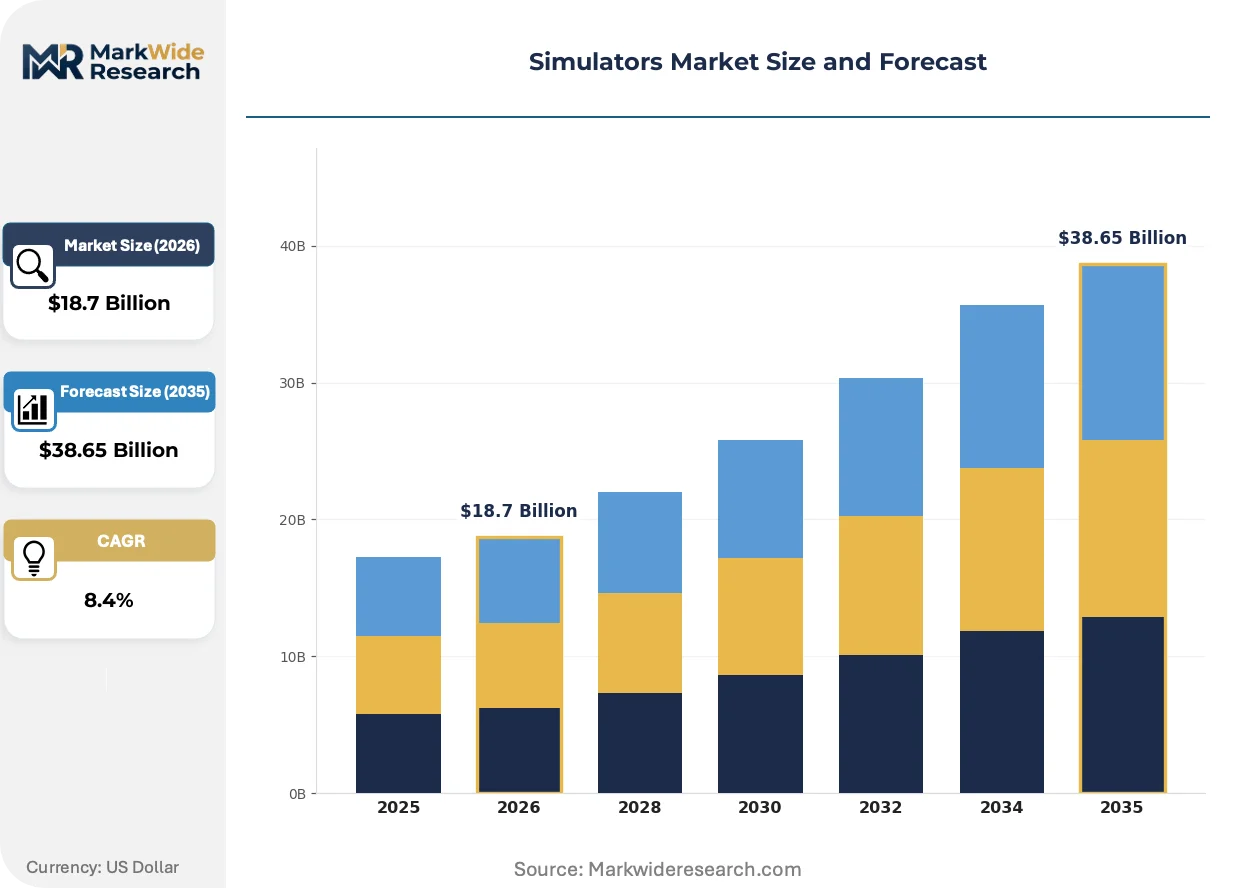
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application Type: Aerospace, Medical Training, Driving, Military Technology: Virtual Reality, Augmented Reality, Motion Simulation, 3D Graphics End User: Healthcare Providers, Educational Institutions, Defense Forces, Automotive Manufacturers Deployment Model: Cloud-based, On-premises, Hybrid, Standalone |
| Companies Covered | CAE Inc., Thales Group, L3Harris Technologies, Inc., FlightSafety International Inc., Rheinmetall AG, RTX Corporation (Collins Aerospace), Saab AB, Boeing Company, Lockheed Martin Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Simulators Market Emerging Trajectories
Computational advances in real-time ray tracing and physics engines are redefining fidelity benchmarks across civilian and military simulation, compressing the performance gap between synthetic and live training environments.
Virtual reality headsets with sub-10-millisecond motion-to-photon latency are displacing projection dome architectures in medical training and automotive design review applications. Surgical residency programs in South Korea and the United Kingdom are deploying VR-based laparoscopic simulators at triple the pace of conventional box-trainer installations. This displacement is collapsing the addressable market for mid-tier projection systems while expanding software licensing revenue for scenario authoring platforms.
EASA CS-FSTD regulations now mandate specific visual system field-of-view and resolution thresholds for initial type rating qualification, forcing European training centers to retire 1990s-era dome installations ahead of depreciation schedules. Device manufacturers must submit updated qualification test guides for each visual upgrade, creating compliance documentation burdens that favor established suppliers with regulatory affairs infrastructure. Flight schools in France and Spain are consolidating simulator hours at centralized facilities rather than maintaining distributed legacy devices.
Defense procurement offices are unbundling simulator hardware purchases from long-term service contracts, separating capital appropriations from recurring training support. This purchasing pattern shift pressures original equipment manufacturers to compete on maintenance pricing transparency rather than captive service lock-in. United States Navy and Royal Australian Air Force training commands are piloting performance-based logistics agreements where contractor payments tie to simulator availability rates rather than scheduled maintenance visits.
Simulators Market Segmentation
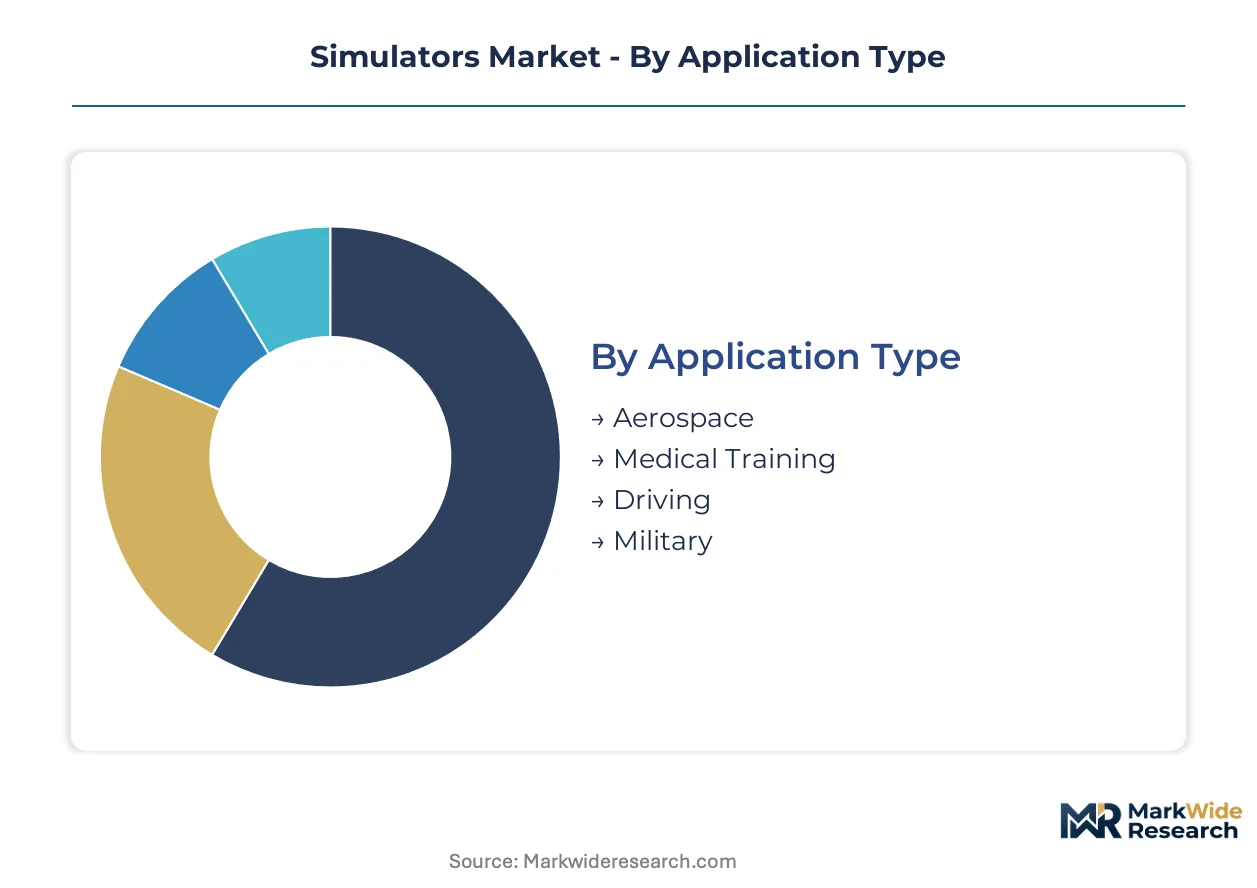
Segmentation reveals how procurement priorities diverge across military, civilian aviation, and healthcare domains. Each dimension exposes distinct technology requirements, certification pathways, and customer concentration patterns that reshape competitive positioning.
Application Type:
Geographic concentration varies sharply: aerospace and military segments cluster in defense procurement hubs, while medical training spreads through hospital accreditation networks.
- Aerospace:Full-flight simulators replicate cockpit environments with Level D certification under FAA Part 60 and EASA CS-FSTD. Demand concentrates in United States and European training centers facing recertification mandates for enhanced motion cueing and visual resolution thresholds.
- Medical Training:Surgical procedure trainers and patient simulators deploy across residency programs seeking accreditation compliance. South Korean and United Kingdom hospital networks are expanding VR-based laparoscopic installations threefold over conventional box-trainers.
- Driving:Automotive design review and driver training systems serve manufacturer R&D facilities and commercial fleet operators.
- Military:Live-virtual-constructive architectures integrate synthetic environments with live range operations across NATO joint force exercises.
Aerospace holds the largest share; momentum sits with medical training as VR displacement accelerates.
Technology:
Cost tiers separate capital-intensive motion platforms from software-centric immersive solutions.
- Virtual Reality:Head-mounted displays with sub-10-millisecond motion-to-photon latency displace projection domes in medical and automotive applications. German and Australian educational institutions adopt browser-accessible modules, eliminating on-site infrastructure investment.
- Motion Simulation:Six-degrees-of-freedom platforms with electro-hydraulic actuators achieve vestibular fidelity for pilot training. Japan and Germany host concentrated production clusters, creating single-source dependencies and lead time volatility.
- Augmented Reality:Overlay systems blend synthetic imagery with physical environments for maintenance training and battlefield situational awareness.
- 3D Graphics:Real-time ray tracing and physics engines compress the fidelity gap between synthetic and live environments across civilian and military simulation.
Motion simulation commands premium pricing; VR is climbing the fastest as scenario density requirements outpace motion cueing priorities.
End User:
Customer type determines procurement scale, with defense forces and automotive manufacturers driving largest contract values.
- Defense Forces:NATO procurement offices mandate interoperable simulation protocols for multi-domain training. United States Navy and Royal Australian Air Force pilot performance-based logistics agreements tying contractor payments to simulator availability rates.
- Healthcare Providers:Hospital networks and residency programs seek accreditation-compliant training devices. FDA guidance on medical device validation and ISO 13485 quality management shape product development pathways.
- Educational Institutions:Universities and technical colleges adopt cloud-streamed simulation for distributed learner access without capital infrastructure.
- Automotive Manufacturers:Design review and autonomous system validation drive demand for driving simulators with high-fidelity vehicle dynamics modeling.
Defense forces hold the largest share; healthcare providers are gaining share fastest through VR-based surgical training expansion.
Deployment Model:
Maturity stages separate established on-premises installations from emerging cloud-native architectures.
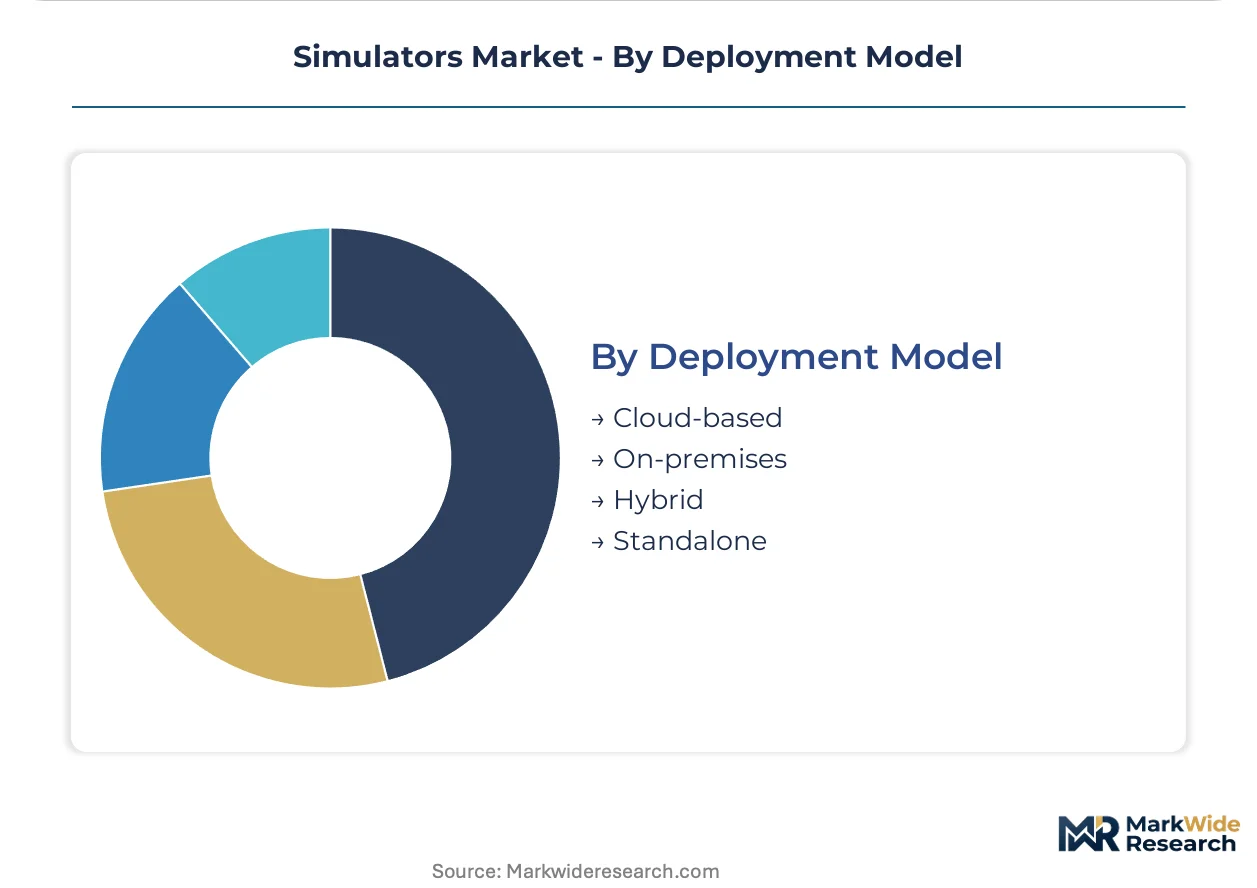
- Cloud-based:Browser-accessible training modules eliminate on-site infrastructure while expanding scenario libraries. German and Australian educational institutions lead adoption, though regulatory equivalence with physical device hours remains unresolved.
- On-premises:Dedicated facilities house Level D full-flight simulators and high-fidelity medical procedure trainers requiring controlled environmental conditions.
- Hybrid:Combinations of local processing for latency-critical functions with cloud-hosted scenario content and analytics.
- Standalone:Self-contained units deploy in field conditions or distributed locations lacking reliable network connectivity.
On-premises retains the largest installed base; cloud-based deployment shows steepest expansion trajectory as infrastructure constraints ease.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement offices and commercial aviation training centers concentrate simulator demand in specific national markets where regulatory mandates and military modernization programs intersect. Buyer archetypes split between NATO defense commands seeking live-virtual-constructive architectures and FAA-governed flight schools facing recertification deadlines.
United States
FAA Part 60 recertification mandates are compressing replacement cycles for Level D full-flight simulators at training centers in Florida and Texas. The Department of Defense is expanding procurement of integrated training environments for fifth-generation fighter platforms. Montreal-based suppliers maintain captive service relationships with US carriers through long-term training support contracts.
Germany
EASA CS-FSTD visual system thresholds are forcing retirement of 1990s-era dome installations at Lufthansa training facilities ahead of depreciation schedules. The country's national aviation regulator is tightening cross-border simulator hour recognition protocols. Stuttgart and Munich clusters host electro-hydraulic actuator production for six-degrees-of-freedom motion platforms serving European defense contracts.
Saudi Arabia
GAMI localization targets are redirecting fighter pilot training procurement toward in-country simulation centers with indigenous maintenance capabilities. The national military industries regulator is mandating technology transfer clauses in defense simulation contracts. Riyadh and Eastern Province facilities are expanding capacity for joint force training exercises with Gulf Cooperation Council partners.
United Kingdom
Royal Air Force training commands are piloting performance-based logistics agreements tying contractor payments to simulator availability rates. The national aviation authority is harmonizing qualification standards with EASA frameworks post-Brexit. BAE Systems facilities in Lancashire anchor domestic production of tactical training systems for NATO interoperability exercises.
South Korea
Surgical residency programs are deploying VR-based laparoscopic simulators at triple the pace of conventional box-trainer installations. The national food and drug regulator is aligning medical device validation guidance with FDA frameworks for healthcare simulation products. Seoul hospital networks are consolidating accreditation-compliant training device procurement through centralized purchasing cooperatives.
Simulators Market Vendor Landscape
Player mix skews toward integrated systems houses with captive regulatory affairs infrastructure. Consolidation pressures favor established suppliers with FAA and EASA qualification test guide submission capabilities. Three archetypes dominate: Canadian training service integrators, European defense-electronics conglomerates, and US aerospace primes with hardware-software architectures. Competitive moves center on unbundling hardware purchases from long-term service contracts and expanding performance-based logistics agreements.
Within the integrated systems tier, CAE Inc. and Thales Group exemplify divergent geographic anchoring strategies. CAE represents the North American training service model with captive full-flight simulator supply. Thales occupies a position leveraging European installed base density for NATO defense simulation contracts. L3Harris Technologies, Inc. anchors the US defense prime archetype with architectures tailored to military flight training requirements.
| Leading Market Players |
|---|
| CAE Inc. |
| Thales Group |
| L3Harris Technologies, Inc. |
| FlightSafety International Inc. |
| Rheinmetall AG |
| RTX Corporation (Collins Aerospace) |
| Saab AB |
| Boeing Company |
| Lockheed Martin Corporation |
| Others |
Supply Flow & Price Mechanics
Scale economies in motion platform manufacturing concentrate production in Stuttgart and Montreal clusters, compressing price floors for six-degrees-of-freedom systems while elevating barriers for second-tier suppliers lacking captive actuator foundries. This concentration amplifies pricing power for integrated systems houses that bundle hardware with long-term service contracts, forcing buyers into cost-plus arrangements with limited leverage.
Pricing Analysis
Cost-plus contracts with raw-material indexation dominate procurement for Level D full-flight simulators, tying final pricing to electro-hydraulic actuator and high-resolution display panel costs. Three-tier pricing structure across FAA/EASA-certified, military-qualified, and educational-grade devices separates premium motion fidelity from standard visual systems and economy VR-based trainers. Cost compression in the educational tier is intensifying because cloud-streamed modules eliminate on-site infrastructure requirements. Flight training centers exhibit highest price sensitivity due to recertification mandate timing pressures, while defense procurement offices prioritize availability guarantees over unit cost.
Supply Chain Analysis
Strategic stockpiling of electro-hydraulic actuators and precision motion control systems characterizes inventory strategy among tier-one manufacturers, mitigating lead time volatility from Japanese and German production clusters. Supply draws from concentrated actuator fabrication in Japan, visual rendering engine development in Germany, and software engineering talent pools in Montreal and Bangalore. Single-source vulnerability in six-degrees-of-freedom motion platforms creates exposure to geopolitical disruption or capacity constraints. Distribution runs through direct OEM relationships with defense procurement offices and commercial aviation training centers, supplemented by regional service hubs for maintenance and recertification support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Embedded software engineering talent for real-time physics modeling and rendering pipeline optimization represents the critical capability gap, with demand outstripping supply in Montreal, Toulouse, and Bangalore aerospace clusters. This scarcity constrains expansion velocity for device manufacturers and elevates acquisition premiums for teams with FAA and EASA qualification test guide submission experience.
For Market Incumbents: Secure captive regulatory affairs infrastructure by acquiring specialist firms with FAA Part 60 and EASA CS-FSTD qualification expertise, compressing 18-24 month certification timelines that currently delay revenue recognition. Expand backward integration into electro-hydraulic actuator production or establish dual-source agreements with Japanese and German foundries to mitigate single-source vulnerability threatening availability commitments. For New Entrants and Emerging Players: Anchor in cloud-streamed simulation for educational institutions, where browser-accessible modules eliminate capital infrastructure barriers and regulatory equivalence with physical device hours remains unresolved. Target German and Australian university networks with distributed learner cohorts seeking scenario density without motion platform investment. Pursue white-label partnerships with established device manufacturers to bypass qualification test guide submission requirements. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated training service providers with long-term operator contracts, outperforming pure hardware manufacturers exposed to cyclical defense procurement. Prioritize acquisition targets with performance-based logistics agreements tying payments to simulator availability rates. Watch for EASA-FAA reciprocity agreement progress as inflection indicator for cross-border training center consolidation opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Qualification Test Guide Submission | FAA and EASA joint reviews compress market access timelines for device manufacturers. |
| Performance-Based Logistics Agreement | United States Navy and Royal Australian Air Force pilot availability-tied payments reshape contractor economics. |
| Cloud-Streamed Module Deployment | German and Australian educational institutions eliminate on-site infrastructure while expanding scenario libraries. |
| Electro-Hydraulic Actuator Dual-Sourcing | Japanese and German production cluster dependencies create vulnerability mitigation opportunities. |
| VR-Based Medical Training Platform | South Korean and United Kingdom surgical residency programs triple installation pace over conventional systems. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with flight training center directors, defense procurement officers, simulator device manufacturers, regulatory affairs specialists, and healthcare simulation product managers. Secondary validation drew from FAA Part 60 qualification test guide databases, EASA CS-FSTD certification records, defense procurement contract disclosures, hospital accreditation standards, and ISO 13485 quality management filings. Bottom-up segment sizing across aerospace, medical, military, and educational applications triangulated with top-down market boundary analysis.
Across the analysis window, volume and value outputs reflect modeled projections for application type, technology tier, end-user category, and deployment model segmentation. CAGRs were derived from regression analysis of historical replacement cycle data, regulatory mandate implementation timelines, and defense modernization program appropriations. Industry-specific forecast inputs include FAA and EASA recertification deadline schedules, GAMI localization target progress, and cloud-streamed simulation regulatory equivalence developments.
Decision-makers should treat outputs as directional under assumptions of continued FAA-EASA certification reciprocity stability and sustained defense procurement prioritization of live-virtual-constructive architectures; material deviation would warrant model refresh. Specific risk factors include electro-hydraulic actuator supply disruptions, divergent national aviation authority hour recognition interpretations, and embedded software engineer talent pool constraints. Revision becomes warranted when cloud-streamed simulation achieves regulatory equivalence with physical device training hours.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Simulation and Training
Middle East and Africa Ship Bridge Simulators Market
Simulation and Training
Europe Flight Training and Simulation Market
Simulation and Training
Live Laser-Based Training and Simulation Platforms Market
Simulation and Training
Global Military Airborne Simulation and Training Market
Simulation and Training
Europe Ship Bridge Simulators Market
Simulation and Training
Civil Aerospace Simulation and Training Market
Simulation and Training
UAV Flight Training and Simulation Market
Simulation and Training
Asia-Pacific Ship Bridge Simulators Market
Simulation and Training
Military Simulation Software Market
Simulation and Training
Military Vehicles and Aircraft Simulations Market
Simulation and Training
Global Ship Bridge Simulators Market
Simulation and Training
North America Ship Bridge Simulators Market
Simulation and Training
Military Simulation and Training Market
Simulation and Training
GNSS Simulators Market
Simulation and Training
Middle East Civil Aviation Flight Training and Simulation Market
Simulation and Training
Flight Simulator Market