
 Drone Simulator Market | 2026-2036
Drone Simulator Market Size, Share, and Industry Trends Forecast 2026-2036
Drone Simulator Market Intelligence
The fragmentation of the end-user base, with a rapid influx of new commercial operators in logistics and agriculture, is restructuring the competitive landscape. CAE Inc. leverages its extensive civil and military aviation training heritage to offer integrated platforms. Thales Group specializes in high-fidelity systems for complex defense applications, while Lockheed Martin Corporation focuses on mission-specific environments for military end-users.
A drone simulator is a software or hardware-in-the-loop system designed to replicate the flight characteristics of an unmanned aerial vehicle. These systems use physics-based flight models and sensor emulations for safe pilot training and mission rehearsal. While military training constitutes the largest application segment, commercial piloting for logistics and inspection is expanding rapidly. Virtual Reality (VR) and Augmented Reality (AR) technologies are gaining share over traditional PC-based platforms due to superior immersion.
Regulatory frameworks from the U.S. Federal Aviation Administration (FAA) and the European Union Aviation Safety Agency (EASA) are standardizing pilot certification requirements. These mandates, often including minimum simulator hours for licensing, directly shape demand for certified training solutions. Success for vendors hinges on achieving platform compliance and approval from these key national and regional aviation authorities.
Market Dynamics
The primary structural force shaping the drone simulator market is the formalization of pilot competency requirements by aviation authorities. Mandates from regulators like the FAA and EASA are transforming simulators from optional training aids into mandatory certification tools for commercial and military operators.
Growth Catalysts
- Regulatory Mandates:Stricter pilot certification frameworks from the U.S. Federal Aviation Administration and European Union Aviation Safety Agency, which include minimum simulator training hours, create direct, non-discretionary demand for certified systems.
- Commercial End-Use Expansion:The growth of urban air mobility and last-mile logistics sectors creates a new class of commercial pilots who require extensive training for complex operations in dense environments.
- Payload Complexity:Increasing use of sophisticated sensor payloads, such as LiDAR and multispectral cameras for inspection and agriculture, necessitates advanced mission rehearsal simulation beyond basic flight mechanics.
Market Restraints
- High Initial Investment:The significant upfront cost of high-fidelity, certified hardware-in-the-loop (HIL) simulators presents a substantial barrier to entry for smaller commercial operators, startups, and training academies.
- Environmental Modeling Fidelity:Accurately replicating complex and unpredictable real-world physics, such as urban wind shear, signal interference, or GPS-denied navigation, remains a significant technical limitation for software-based systems.
- Substitution from Low-End Systems:The availability of inexpensive, consumer-grade PC simulators and the use of low-cost drones for real-world basic flight training can divert budget away from professional, certified simulation platforms.
Strategic Opportunities
- Specialized Application Modules:Developing simulator modules for niche but growing applications like agricultural precision spraying or public safety search-and-rescue offers a path for market differentiation and value-added services.
- AI-Driven Scenario Generation:Integrating artificial intelligence with VR and AR platforms to create adaptive training scenarios that dynamically respond to pilot errors can create a new tier of premium, high-efficacy training tools.
- Emerging Market Infrastructure:Targeting markets in South America and Southeast Asia, where commercial drone adoption is accelerating but certified training infrastructure is underdeveloped, presents a significant geographic expansion opportunity.
Industry Challenges
- Interoperability and Standardization:A lack of universal standards for simulator fidelity, sensor emulation, and data logging makes it difficult for operators to compare systems and for regulators to approve platforms consistently across jurisdictions.
- Instructional Talent Scarcity:A shortage of qualified instructors proficient in both advanced drone operations and simulator-based pedagogy limits the scalability and effectiveness of training programs at commercial flight schools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drone Simulator Market |
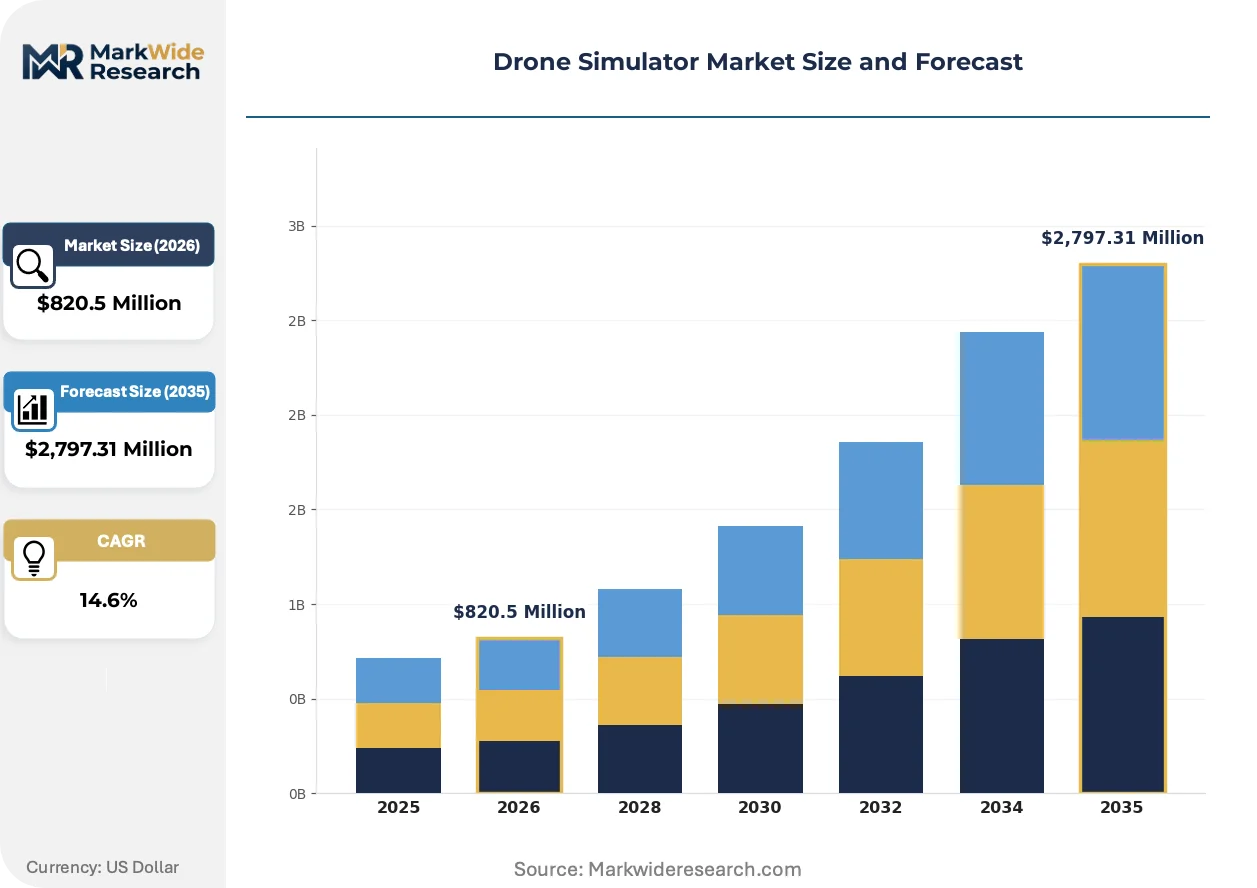
| Market Size in 2026 | $820.5 Million |
| Market Size in 2035 | $2,797.31 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Platform Type: PC-Based, Mobile-Based, Web-Based, Console-Based Application: Military Training, Commercial Piloting, Agricultural Monitoring, Search and Rescue, Cinematography Technology: Virtual Reality, Augmented Reality, Mixed Reality, 3D Modeling End User: Defense Agencies, Civil Aviation Authorities, Research Institutes, Private Operators |
| Companies Covered | Zen Technologies, General Atomics Aeronautical Systems Inc, CAE Inc., Thales Group, Leonardo S.p.A., Northrop Grumman Corporation, SILKAN, Lockheed Martin Corporation, L3Harris Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drone Simulator Market Strategic Shifts & Innovations
A fundamental transition from basic flight proficiency training to complex, high-fidelity mission rehearsal defines the market's evolution. Technology and regulatory pressures are compelling end-users to seek simulators that replicate entire operational workflows, not just aircraft physics.
Virtual Reality and Augmented Reality platforms provide immersive, first-person training environments that replicate the pilot’s physical cockpit or field perspective. Commercial training organizations and defense agencies are rapidly adopting these systems for advanced skill development. For critical tasks requiring spatial awareness in cluttered environments, the immersion offered by VR/AR is overtaking the utility of traditional monitor-based displays.
The European Union Aviation Safety Agency's framework for specific operational risk assessment (SORA) is a significant policy driver. It compels operators to prove pilot competency and risk mitigation for flights over populated areas, creating a strong incentive for simulator use. Commercial operators in Europe pursuing beyond-visual-line-of-sight (BVLOS) waivers are most affected, integrating simulator logs into their safety cases.
End-users are shifting from one-time capital expenditures on software to subscription-based Simulator-as-a-Service (SaaS) models. This change makes advanced simulation accessible to smaller operators by replacing large upfront costs with predictable recurring fees for updated content. The trend is most pronounced among freelance pilots and small enterprises in sectors like construction monitoring and media production in North America.
Drone Simulator Market Segmentation
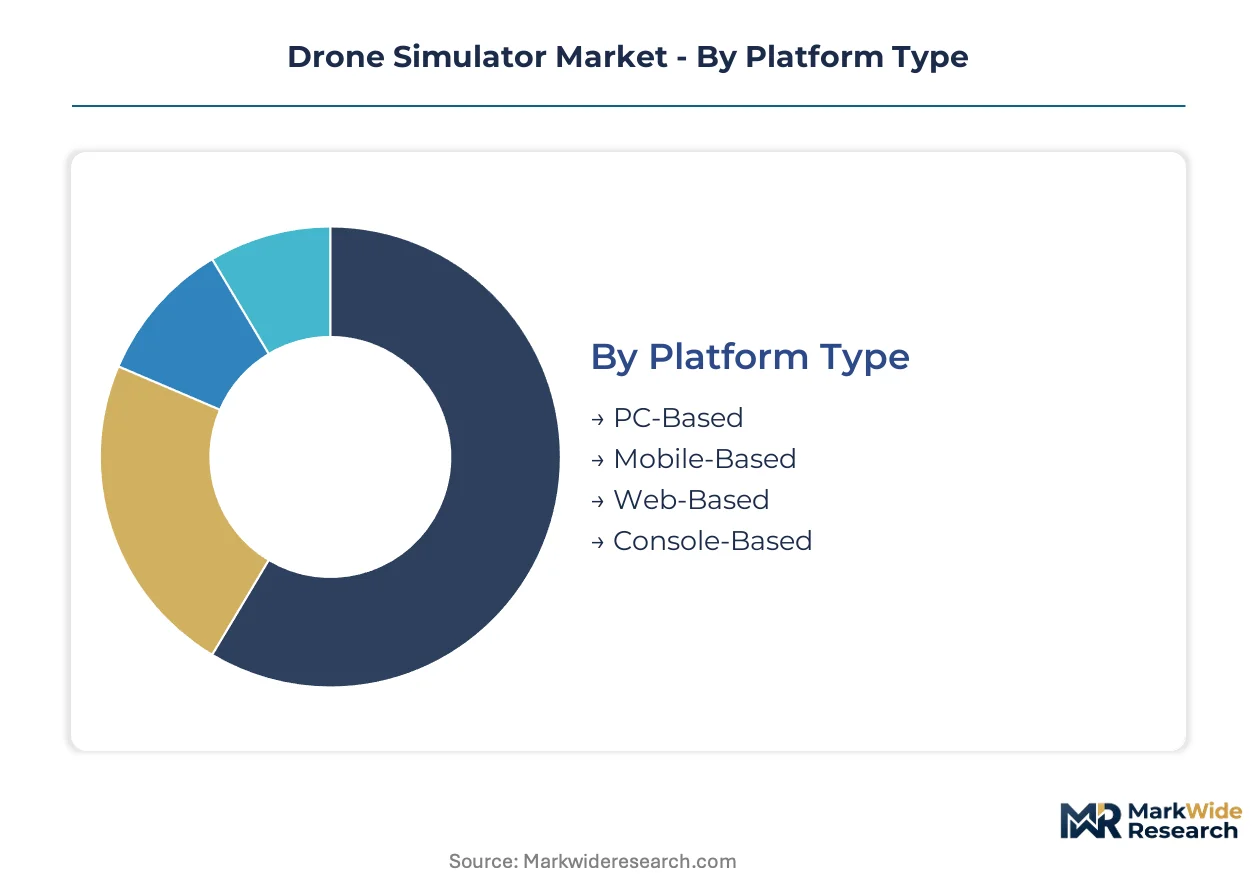
The drone simulator market's segmentation reflects the diverse operational needs and technological advancements driving its expansion. Analyzing these segments provides a clear understanding of where investment is flowing and which user groups are shaping product development and service offerings across the industry.
Platform Type:
The distinction between high-volume, accessible platforms and premium, specialized systems defines the competitive dynamics in this category.
- PC-Based:These simulators run on personal computers, offering a balance of fidelity and accessibility for both professional training and hobbyist use. Demand concentrates in training academies and commercial enterprises in North America, driven by the need for cost-effective, scalable solutions for new pilot certifications.
- Web-Based:Delivered via a browser, these platforms offer convenience and reduce hardware requirements for users, supporting subscription-based SaaS models. Their adoption is gaining traction among freelance pilots and small commercial operators in Europe seeking flexible access to training content without significant upfront investment.
- Mobile-Based:Designed for smartphones and tablets, these simulators provide basic flight mechanics and introductory training scenarios. These systems cater to entry-level users and hobbyists, primarily in emerging markets where mobile device penetration is high.
- Console-Based:These platforms leverage gaming consoles to offer more immersive experiences than mobile, often targeting consumer-grade entertainment and basic flight practice. Their utility for professional certification is limited, serving a niche market of drone enthusiasts.
Today's leader: PC-Based. Tomorrow's challenger: Web-Based.
Application:
The varied applications of drone simulators highlight the critical role they play in preparing operators for specific mission profiles and regulatory environments.
- Military Training:This segment involves high-fidelity simulators for tactical reconnaissance, target acquisition, and complex combat scenarios, often integrating into broader defense exercises. The U.S. defense sector represents a significant portion of this application, mandating advanced simulation for pilot and payload operator proficiency.
- Commercial Piloting:Simulators in this category prepare pilots for diverse commercial operations such as logistics, inspection, and urban air mobility, focusing on regulatory compliance and operational safety. Growth in this segment is particularly strong in Europe, driven by evolving EASA certification requirements for BVLOS operations.
- Agricultural Monitoring:These simulators train pilots to operate drones equipped with specialized sensors for precision farming tasks, including crop health analysis and intelligent spraying. Demand for these modules is expanding in regions like Brazil and India, where large-scale agriculture benefits from drone-based insights.
- Search and Rescue:Simulators for this application focus on training pilots for emergency response missions, including navigating challenging terrains and locating targets in adverse conditions. Public safety agencies in countries such as Australia are increasingly incorporating these tools into their operational readiness programs.
- Cinematography:This application involves training pilots in precise flight maneuvers and camera control for aerial film and photography, emphasizing smooth motion and complex shot execution. Media production companies and independent videographers utilize these systems to hone their craft.
The largest volume of demand originates from Military Training, while Commercial Piloting exhibits the steepest expansion trajectory.
Technology:
Technological innovation is enhancing the realism and effectiveness of drone simulation, pushing the boundaries of what training environments can offer.
- Virtual Reality:VR platforms provide fully immersive, computer-generated environments that replicate the pilot's perspective, essential for spatial awareness and critical decision-making. Commercial training organizations and defense agencies are rapidly adopting VR systems for advanced skill development in complex scenarios.
- Augmented Reality:AR technology overlays digital information onto the real-world view, offering context-rich training that blends virtual elements with physical surroundings. This approach is gaining share for maintenance training and on-site mission rehearsal, particularly in industrial inspection applications.
- Mixed Reality:MR systems combine elements of both VR and AR, allowing for interaction with virtual objects within a real-world setting, creating highly interactive training scenarios. This advanced technology finds application in high-stakes defense and specialized industrial training.
- 3D Modeling:This foundational technology provides the visual and environmental assets for all simulation platforms, creating realistic terrains, buildings, and drone models. Its continuous refinement supports the increasing fidelity demanded by modern simulators across all applications.
Virtual Reality and Augmented Reality technologies are rapidly displacing traditional monitor-based displays due to their superior immersion.
End User:
The end-user base for drone simulators is diversifying, reflecting the broad utility of unmanned aerial systems across various sectors.
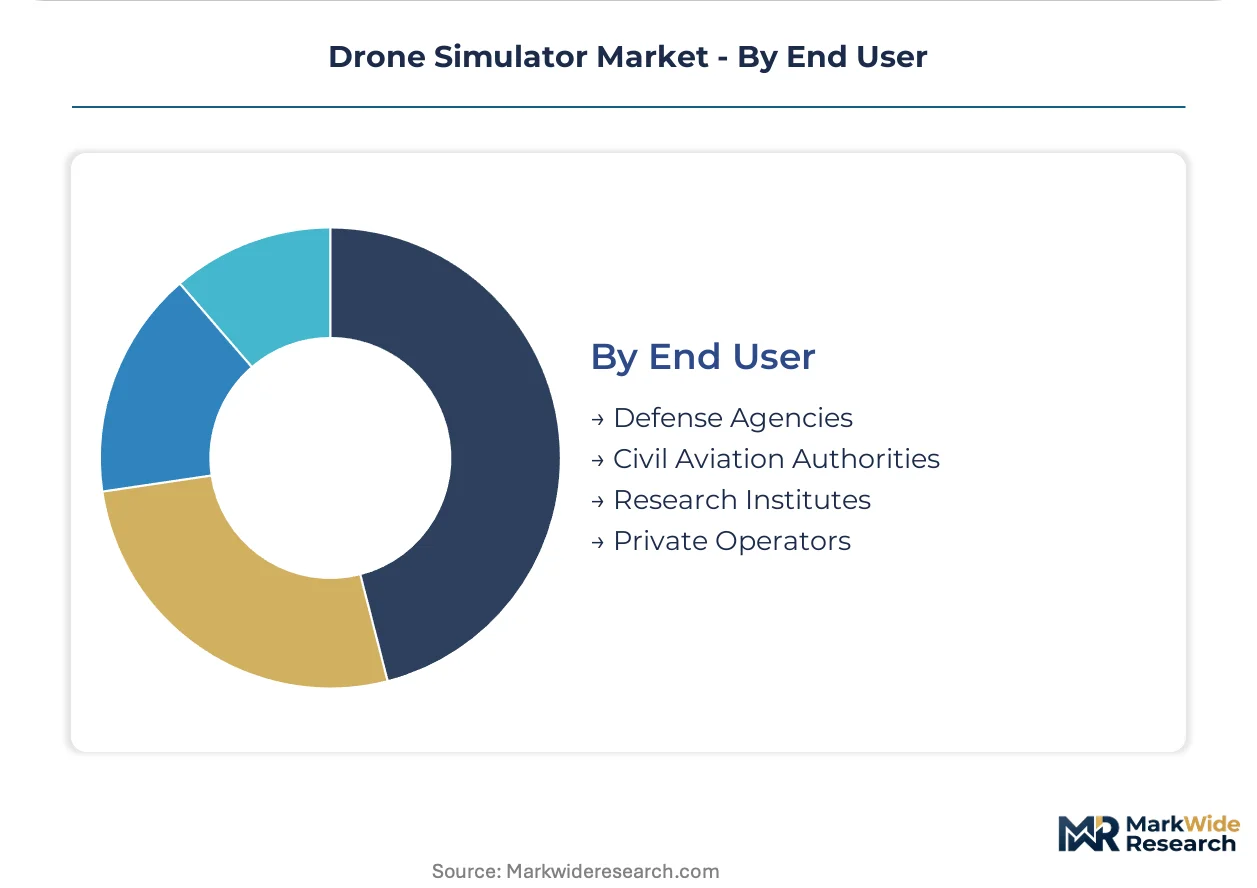
- Defense Agencies:These organizations procure high-fidelity, mission-specific simulators for training military personnel in reconnaissance, surveillance, and tactical operations. The United States and European defense sectors are major consumers, driven by continuous demands for advanced tactical readiness.
- Private Operators:This segment includes commercial enterprises, freelance pilots, and small businesses utilizing drones for services like logistics, inspection, and media production. The rapid influx of new commercial entities in urban air mobility and agriculture is fueling demand from this expanding end-user group.
- Civil Aviation Authorities:Regulatory bodies and their certified training partners use simulators to assess pilot competency and enforce certification standards for commercial drone operations. The FAA and EASA mandates for simulator hours directly shape procurement in this category.
- Research Institutes:Academic and private research entities use drone simulators for developing new flight algorithms, testing sensor payloads, and studying human-drone interaction. Universities in countries such as Germany and Japan are actively engaged in this research.
Defense Agencies represent the largest established end-user segment, with Private Operators experiencing the most significant expansion in demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States leads in defense-related drone simulator demand, while European nations like Germany are rapidly expanding commercial piloting applications. This divergence reflects distinct regulatory and operational priorities across major economic blocs. Emerging markets in Asia and Latin America are also demonstrating significant potential for specialized agricultural and public safety training systems.
United States
Demand for drone simulators in the United States centers on military readiness and civilian pilot certification. The U.S. Federal Aviation Administration (FAA) mandates specific simulator hours for commercial drone pilot licensing, directly driving market activity. Aerospace and defense clusters in states like California and Florida are actively integrating advanced simulation technologies for tactical training.
Germany
Germany exhibits strong demand for high-fidelity drone simulators, particularly for commercial and research applications. The European Union Aviation Safety Agency (EASA) frameworks compel operators to use certified simulators for advanced operational approvals, including BVLOS. Research institutes and automotive engineering hubs in Bavaria are developing sophisticated simulation environments for urban air mobility.
China
China's drone simulator market is expanding rapidly, driven by domestic defense modernization and widespread commercial drone adoption. Government initiatives support the development of advanced simulation for military training and industrial inspection. Technology parks in Shenzhen and Beijing are fostering innovation in VR/AR-based simulation platforms for various end-users.
India
India is witnessing growth in drone simulator procurement, particularly for agricultural and public safety applications. The Directorate General of Civil Aviation (DGCA) has introduced regulations for drone pilot training, including simulator requirements. Major agricultural regions and smart city initiatives are creating demand for localized training solutions.
Australia
Australia's market for drone simulators is characterized by strong demand from public safety agencies and the mining sector. The Civil Aviation Safety Authority (CASA) sets stringent competency standards for drone operators, encouraging simulator use. Remote operations centers in Western Australia are utilizing simulation for training pilots in complex logistics and surveillance missions.
Drone Simulator Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists, creating a multi-tiered competitive environment. The market structure features established aerospace and defense contractors alongside agile software developers. Strategic partnerships and technology licensing agreements are prevalent, as companies seek to expand their product portfolios and access new customer segments.
Specialists in high-fidelity defense systems, such as Lockheed Martin Corporation, exemplify mission-specific simulation expertise for military end-users. CAE Inc. represents a global leader in integrated training solutions, leveraging extensive civil and military aviation heritage. Thales Group occupies a position in complex defense applications, providing advanced simulation systems across various platforms.
| Leading Market Players |
|---|
| Zen Technologies |
| General Atomics Aeronautical Systems Inc |
| CAE Inc. |
| Thales Group |
| Leonardo S.p.A. |
| Northrop Grumman Corporation |
| SILKAN |
| Lockheed Martin Corporation |
| L3Harris Technologies |
| Others |
Cost & Logistics Intelligence
Advanced display panel prices, particularly for VR/AR hardware, cascade through the drone simulator supply chain, influencing the final pricing tiers for certified training systems. These component costs directly impact the affordability and feature sets of diverse simulation platforms.
Pricing Analysis
Capacity additions in East Asian manufacturing hubs are reshaping price floors for core simulator components like VR headsets and high-resolution displays. The dominant pricing model is a hybrid of subscription-based SaaS for software and per-unit transactional sales for hardware. Price differentiation stems from certification level, such as FAA or EASA approval, and the degree of mission-specific customization. Pricing softness in the commercial segment stems from the availability of low-cost PC-based alternatives, making smaller commercial operators highly price-sensitive.
Supply Chain Analysis
Dual-sourcing requirements for critical components are becoming more prevalent, driven by defense procurement standards. The supply chain for drone simulators concentrates in East Asia for hardware manufacturing, primarily China and Taiwan, and in North America and Europe for specialized software development. Key dependencies include high-performance GPUs, specialized sensor emulators, and physics-based flight model libraries, creating a structural risk from single-source reliance for proprietary software. Distribution typically runs through direct sales channels for defense contracts and value-added resellers for commercial clients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The drone simulator market represents a late-cycle quality story, as regulatory pressures and operational complexity drive a demand-shift toward premium, certified simulation platforms. End-users now prioritize high-fidelity mission rehearsal capabilities over basic flight proficiency.
For Market Incumbents:Deploy certification investment into new regulatory frameworks, securing early approval from bodies like EASA and the FAA. Form strategic partnerships with VR/AR hardware manufacturers to counter the threat from agile software developers offering immersive, but uncertified, solutions. Deepen vertical integration into specialized physics-based modeling and sensor emulation to maintain fidelity leadership. Consolidate smaller software providers to expand application module portfolios.
For New Entrants and Emerging Players:Online SaaS platforms offer a direct digital channel to penetrate underserved commercial segments like agricultural precision spraying in Brazil. Target emerging markets in Southeast Asia where certified training infrastructure remains underdeveloped. Focus on developing specialized application modules for niche public safety search-and-rescue operations. A freemium model for basic flight mechanics, upgrading to subscription for advanced mission scenarios, provides an effective go-to-market angle.
For Investors and Strategic Acquirers:Asymmetric upside sits with specialized software developers focused on AI-driven scenario generation and high-fidelity environmental modeling. The market demonstrates long-term viability over the next 5-10 years, driven by continuous regulatory evolution and commercial drone expansion. Seek acquisition targets with strong intellectual property in VR/AR integration for defense and urban air mobility. The signal to watch is the widespread adoption of BVLOS waivers by commercial operators, indicating maturity in advanced training requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in EASA SORA Compliance Modules | Ensures European commercial operators meet stringent risk assessment requirements for advanced operations. |
| Develop AI-Driven Adaptive Scenario Generation | Creates premium training tools that dynamically respond to pilot performance, enhancing efficacy for defense agencies. |
| Expand Subscription-Based SaaS Offerings | Lowers entry barriers for small commercial operators, expanding market access beyond capital expenditures. |
| Target Emerging Market Training Infrastructure | Captures early market share in regions like Southeast Asia where commercial drone adoption is accelerating. |
| Form Partnerships with VR/AR Hardware Providers | Integrates cutting-edge immersive technologies, displacing traditional PC-based platforms for advanced training. |
Research Approach
Multiple input streams — primary interviews, proprietary databases, and industry reports — were reconciled to construct a robust market view. This involved extensive conversations with drone pilots, training academy directors, defense procurement officers, and regulatory compliance specialists. Secondary data sources included FAA and EASA publications, aerospace industry journals, and company financial filings. A rigorous bottom-up and top-down triangulation process validated all quantitative and qualitative findings.
Historical market performance was cross-referenced against expert panel input to establish the forecast framework across the analysis window. The market was segmented by platform type, application, technology, and end-user, alongside an industry-specific dimension of regulatory compliance level. Compound Annual Growth Rates were derived from an iterative process of supply-side capacity projections and demand-side adoption curves. Key inputs included projected pilot certification rates and defense spending allocations.
The model assumes a particular technology adoption path; alternative pathways for mixed reality or advanced haptic feedback would alter the outlook. Forecasts reflect current regulatory trajectories and geopolitical stability. Deviation in aviation authority mandates or defense budget shifts would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Simulation and Training
Flight Simulator Market
Simulation and Training
Civil Aviation Simulator Market
Simulation and Training
Helicopter Simulator Market
Simulation and Training
Air Traffic Control Simulator and Training Market
Simulation and Training
Europe Flight Training and Simulation Market
Simulation and Training
Civil Aerospace Simulation and Training Market
Simulation and Training
Asia-Pacific Civil Aviation Simulators Market
Simulation and Training
Simulators Market
Simulation and Training
Global Military Airborne Simulation and Training Market
Simulation and Training
Police and Military Simulation Training Market
Simulation and Training
Asia-Pacific Ship Bridge Simulators Market
Simulation and Training
Middle East Civil Aviation Flight Training and Simulation Market
Simulation and Training
Air Traffic Control Simulation and Training Market
Simulation and Training
Global Ship Bridge Simulators Market
Simulation and Training
Live Laser-Based Training and Simulation Platforms Market
Simulation and Training
Pilot Training Market