
 Global Military Airborne Simulation and Training Market | 2026-2036
Global Military Airborne Simulation and Training Market Size, Share, and Industry Trends Forecast 2026-2036
Global Military Airborne Simulation and Training Market Foresight
Carbon fiber-reinforced polymer is expanding its share in motion platform construction, displacing steel in high-G centrifuge bases to cut weight and extend actuator life. CAE Inc. leverages captive composites manufacturing to control platform delivery timelines for NATO customers. Lockheed Martin Corporation anchors its training portfolio on F-35 synthetic ecosystem integration, while Rheinmetall AG competes through Eurofighter-specific mission rehearsal suites.
Military airborne simulation and training encompasses synthetic environments replicating cockpit dynamics, aerial maneuver physics, and electromagnetic threat landscapes for pilot skill development without operational aircraft exposure. These systems integrate six-degree-of-freedom motion bases, spherical laser projection domes exceeding 240 degrees horizontal field-of-view, and computational fluid dynamics engines processing real-time atmospheric disturbance models. Full mission simulation captures the dominant share of procurement budgets as air forces prioritize end-to-end mission rehearsal over discrete skill drills. Virtual reality systems represent the fastest-expanding segment, driven by headset resolution advances and reduced hardware footprints for deployed training nodes. Networked simulators concentrate margin pools where vendors bundle classified threat libraries with secure datalink architectures.
The US FAA and European Union Aviation Safety Agency jointly shape device qualification pathways, while NATO's Aircrew Training and Reconnaissance Support program standardizes interoperability protocols across allied forces. The US Federal Aviation Administration mandates recurrent qualification testing that compresses replacement cycles for visual display systems. China's Civil Aviation Administration and the country's national defense regulator are advancing indigenous GB standards for synthetic training equipment, altering vendor access patterns. Stakeholders must weigh sovereign content requirements against interoperability commitments when selecting platform architectures for multinational training coalitions.
Market Dynamics
Live-flight hour reduction mandates across NATO air forces are compressing simulator certification timelines and forcing hardware refresh cycles that favor modular, software-defined architectures over fixed-base legacy systems.
Growth Catalysts
- FAA Synthetic Training Device Qualification:Updated standards from the US Federal Aviation Administration accelerate visual display replacement cycles among defense contractors maintaining training fleets.
- Carbon Emission Reduction Protocols:NATO member states impose binding emission targets on military aviation, redirecting pilot certification budgets toward simulator-based programs that eliminate fuel burn.
- Multi-Domain Simulation Convergence:Networked platforms integrating air, space, and electromagnetic spectrum replication attract procurement priority over single-domain trainers.
Market Restraints
- Specialized Motion Base Supply Concentration:High-G centrifuge actuator manufacturing concentrates among a limited set of European and North American precision engineering suppliers, creating delivery bottlenecks.
- Classified Threat Library Access Controls: National security restrictions on electromagnetic warfare scenario data prevent seamless simulator interoperability across allied training coalitions.
- Computational Fluid Dynamics Licensing Costs:Real-time atmospheric modeling engines require recurring payments to specialized physics software vendors, elevating total cost of ownership.
Strategic Opportunities
- Australia Pacific Rebalance:Royal Australian Air Force modernization programs seek deployable, containerized simulation nodes for distributed training across northern bases.
- Virtual Reality Headset Resolution Thresholds:Consumer electronics advances in micro-OLED displays enable military-grade visual fidelity at reduced hardware footprints for expeditionary units.
- EU Green Deal Defense Procurement Incentives:European Union sustainability criteria award evaluation preference to training platforms demonstrating measurable carbon reduction against live-flight benchmarks.
Industry Challenges
- Software-Defined Radio Integration Complexity:Simulator datalink architectures must reconcile proprietary military waveforms with commercial Ethernet backbones, extending system integration timelines.
- Computational Hardware Obsolescence Cycles:Graphics processing unit refresh rates in visual rendering subsystems outlast qualification testing periods, creating capability gaps during certification windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Military Airborne Simulation and Training Market |
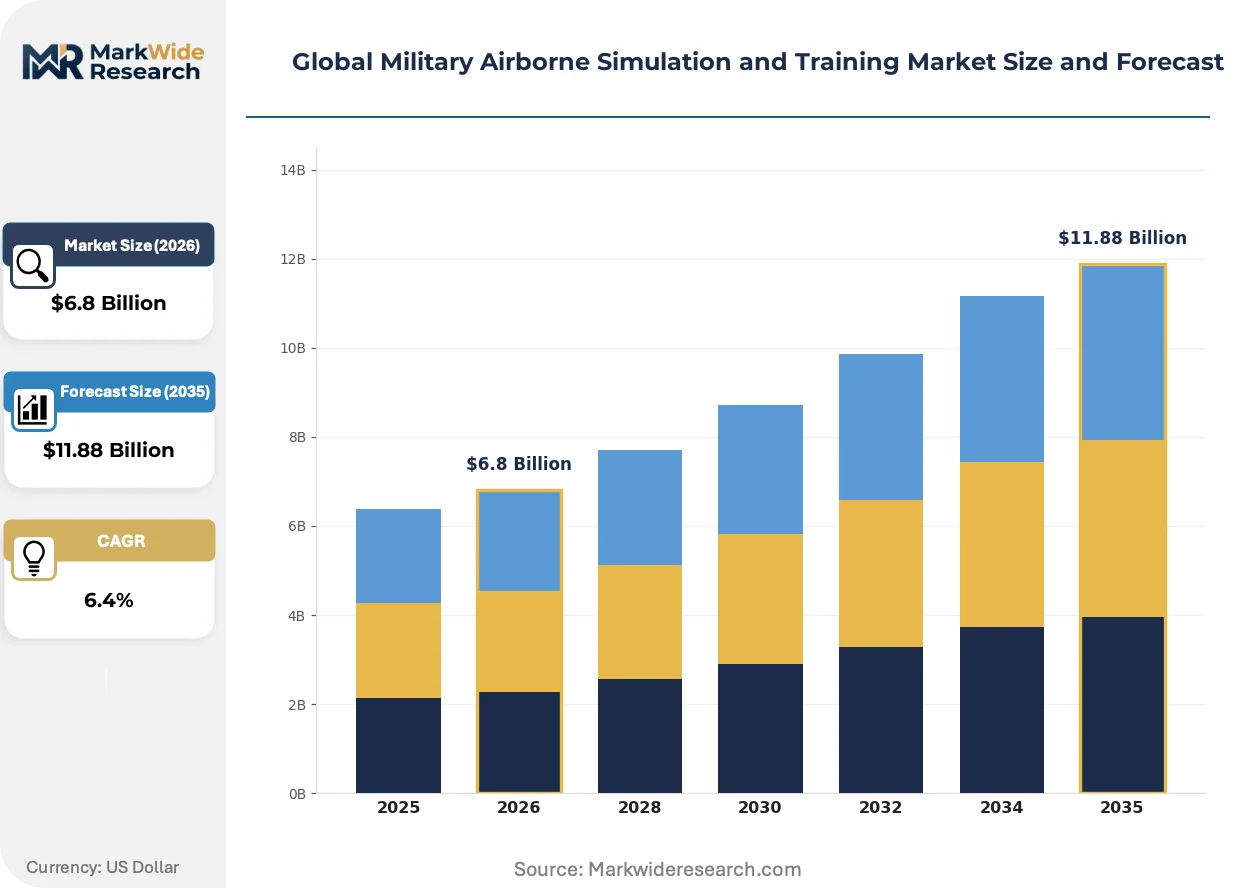
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Full Mission Simulation, Part Task Trainers, Virtual Reality Systems, Desktop Trainers Training Type: Flight Training, Mission Rehearsal, Combat Readiness, Survival Skills End User: Air Force Squadrons, Defense Academies, Pilot Training Schools, Aviation Research Centers Technology: Augmented Reality, Networked Simulators, Motion Platforms, Visual Display Systems |
| Companies Covered | FlightSafety International Inc., Rheinmetall AG, CAE Inc., Northrop Grumman Corporation, BAE Systems PLC, Lockheed Martin Corporation, Collins Aerospace, L3Harris Technologies, THALES, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Military Airborne Simulation and Training Market Shifts & Advancements
Digital engineering workflows are collapsing hardware prototyping cycles while artificial intelligence injects adaptive adversary behaviors into synthetic training scenarios previously scripted by human instructors.
Carbon fiber-reinforced polymer is overtaking steel in high-G centrifuge motion base construction. Air forces in Germany and the United States specify composite platforms to reduce foundation loads and extend actuator service intervals. This materials transition is overtaking traditional metallurgical approaches across NATO procurement specifications for next-generation pilot training centers.
European Union Aviation Safety Agency coordination with the US Federal Aviation Administration on mutual recognition of synthetic training device qualifications is harmonizing certification pathways. This regulatory convergence reduces duplicate testing burdens for vendors serving both markets. Full mission simulator manufacturers are consolidating qualification documentation to exploit this bilateral alignment.
Air force procurement offices are unbundling simulator hardware purchases from long-term service agreements. Buyers in Australia and Germany now separately tender visual system upgrades, motion platform refurbishment, and scenario content development. This contract fragmentation favors specialized subsystem vendors and compresses incumbent full-stack supplier margins.
Global Military Airborne Simulation and Training Market Segmentation
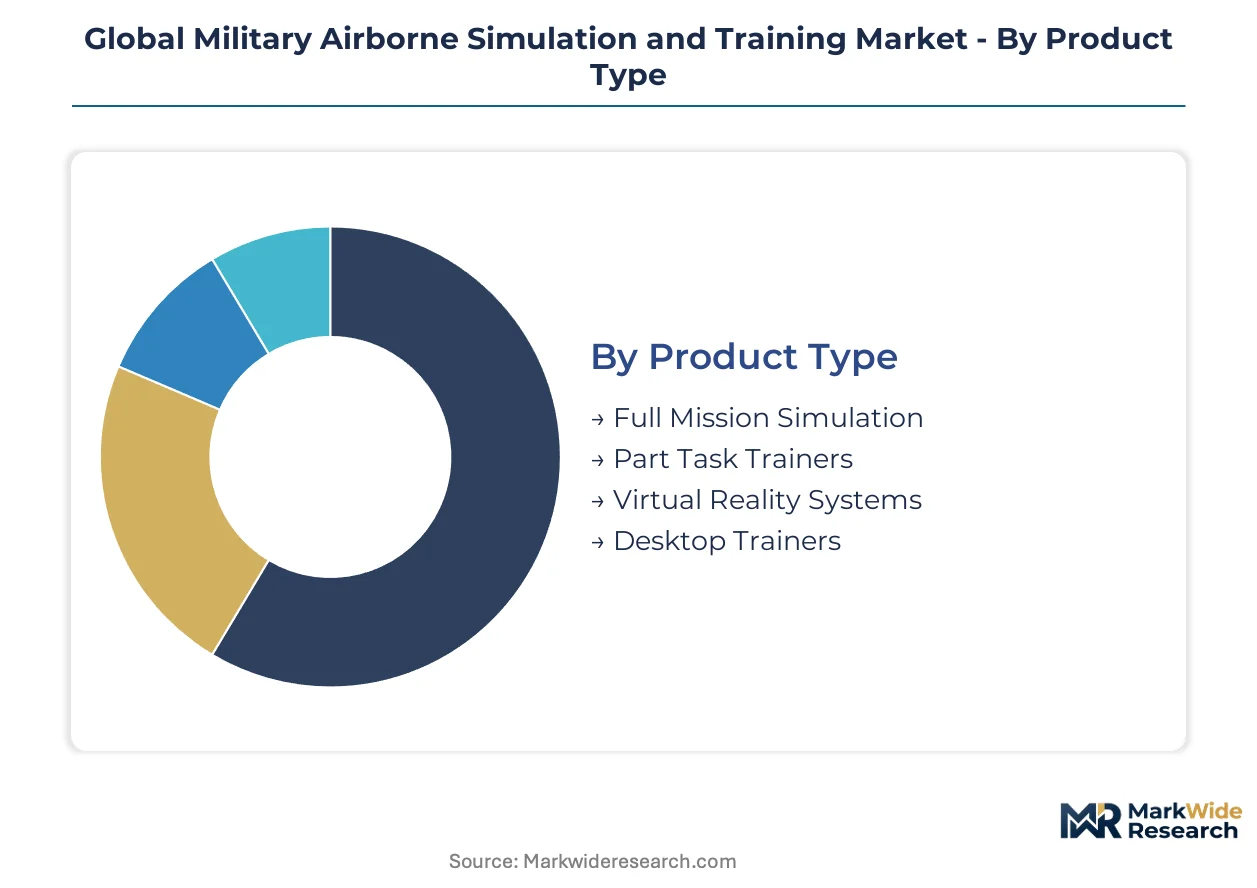
Segmentation in military airborne simulation reveals how procurement budgets fragment across fidelity tiers and operational readiness objectives. Air forces balance capital-intensive full-mission installations against deployable, software-scalable alternatives for distributed training architectures.
Product Type:
Carbon fiber-reinforced motion bases and spherical laser projection domes define the hardware specification axis across fidelity tiers.
- Full Mission Simulation:Six-degree-of-freedom motion platforms with 240-degree horizontal field-of-view laser projection replicate complete cockpit environments for end-to-end mission rehearsal. The US Air Force and Royal Australian Air Force concentrate procurement here as NATO emission reduction protocols compress live-flight certification timelines.
- Virtual Reality Systems:Micro-OLED headsets delivering military-grade visual fidelity at reduced hardware footprints enable expeditionary training nodes without fixed infrastructure. Micro-OLED resolution advances are accelerating hardware refresh cycles among defense contractors maintaining deployable fleets.
- Part Task Trainers:Discrete skill modules targeting instrument procedures or emergency protocols occupy intermediate budget tiers between desktop and full-mission systems.
- Desktop Trainers:Screen-based procedural trainers support initial qualification phases before pilots advance to motion-based platforms.
Full Mission Simulation leads on scale; Virtual Reality Systems lead on momentum.
Training Type:
Procurement patterns track how air forces allocate simulator hours across certification phases versus operational rehearsal.
- Flight Training:Core pilot certification programs covering takeoff, navigation, and landing procedures in synthetic environments. Germany and Australia redirect budgets here as carbon emission reduction protocols eliminate fuel burn from baseline qualification.
- Mission Rehearsal:End-to-end tactical scenario replication integrating electromagnetic threat landscapes and multi-domain coordination. NATO's Aircrew Training and Reconnaissance Support program standardizes interoperability protocols for these systems across allied forces.
- Combat Readiness:High-G centrifuge training and adversary engagement scenarios maintaining operational tempo between deployments.
- Survival Skills:Ejection protocol and hostile environment preparation modules occupying specialized training center allocations.
Flight Training dominates procurement volume; Mission Rehearsal commands the steepest expansion trajectory.
End User:
Customer concentration patterns reflect sovereign defense budgets and multinational training coalition structures.
- Air Force Squadrons:Operational units procuring networked, multi-domain platforms for unit-level mission rehearsal. The United States, Germany, and Australia anchor demand as these nations modernize legacy training infrastructure.
- Defense Academies:Institutional pilot pipelines specifying full-mission simulators for initial qualification and advanced tactical training.
- Pilot Training Schools:Civil-military hybrid facilities serving contract training requirements for allied force personnel exchange programs.
- Aviation Research Centers:Experimental flight dynamics and human factors research facilities requiring configurable, non-standard platform architectures.
Air Force Squadrons concentrate margin pools; Defense Academies sustain replacement cycle visibility.
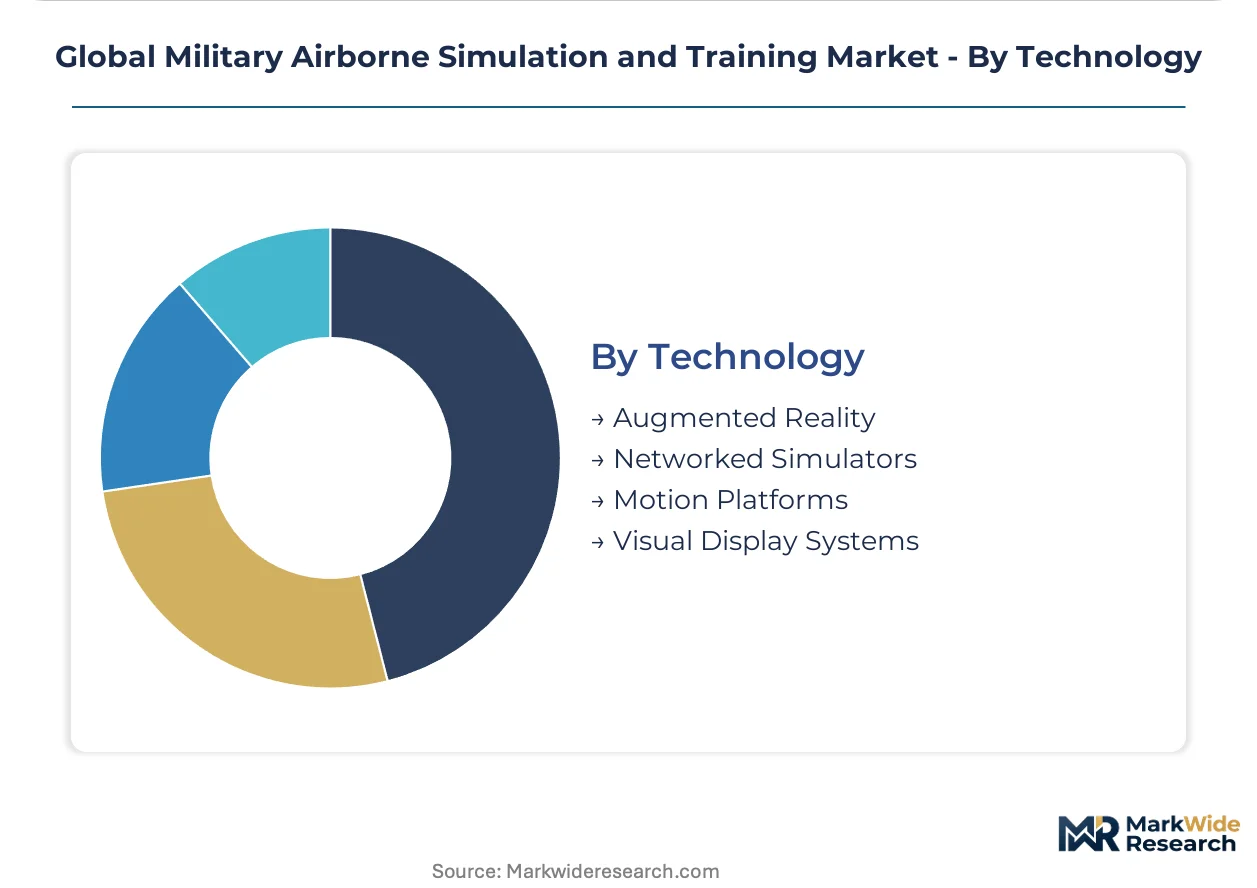
Technology:
Subsystem specialization determines vendor positioning across visual, motion, and datalink integration layers.
- Networked Simulators:Secure datalink architectures bundling classified threat libraries with multi-domain scenario distribution. Procurement offices in Australia and Germany unbundle these from hardware purchases, favoring specialized subsystem vendors.
- Motion Platforms:High-G centrifuge bases with carbon fiber-reinforced polymer construction reducing foundation loads and extending actuator service intervals. CAE Inc. leverages captive composites manufacturing to control delivery timelines for NATO customers.
- Visual Display Systems:Spherical laser projection domes and micro-OLED headsets subject to recurrent FAA qualification testing that compresses replacement cycles.
- Augmented Reality:Overlay systems blending synthetic terrain with physical cockpit elements for mixed-fidelity training applications.
Networked Simulators capture interoperability premiums; Motion Platforms concentrate supply-side engineering scarcity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States anchors the military airborne simulation and training landscape through its concentration of defense primes and FAA regulatory leadership. German engineering clusters and Australian Pacific repositioning programs generate secondary demand poles. Sovereign procurement patterns diverge based on NATO interoperability requirements versus indigenous capability development priorities.
United States
The US Air Force and Navy drive procurement through F-35 synthetic ecosystem integration and networked multi-domain platforms. FAA synthetic training device qualification standards compress visual display replacement cycles among defense contractors. Greater Orlando and Dallas-Fort Worth metro areas concentrate simulation engineering talent pools supporting prime contractor delivery timelines.
Germany
The Luftwaffe redirects pilot certification budgets toward simulator-based programs under binding NATO emission reduction protocols. EASA coordination with FAA on mutual recognition of device qualifications reduces duplicate testing burdens for vendors. Bavaria's Munich-Stuttgart corridor hosts precision engineering suppliers manufacturing carbon fiber-reinforced motion base components for centrifuge platforms.
Australia
The Royal Australian Air Force seeks deployable containerized simulation nodes for distributed training across northern bases under Pacific rebalance strategies. National defense procurement guidelines prioritize expeditionary capability over fixed infrastructure investments. Queensland and Northern Territory airbase clusters host pilot training schools serving multinational coalition personnel exchange programs.
United Kingdom
The Royal Air Force modernizes legacy training infrastructure through Eurofighter-specific mission rehearsal suites and networked threat library integration. UK Ministry of Defence procurement offices unbundle hardware purchases from long-term service agreements, favoring specialized subsystem vendors. BAE Systems' Lancashire engineering facilities anchor domestic simulation platform assembly capacity.
France
The Armée de l'Air et de l'Espace prioritizes full-mission simulation procurement for Rafale pilot certification under EU Green Deal defense procurement incentives. DGA procurement specifications award evaluation preference to platforms demonstrating measurable carbon reduction against live-flight benchmarks. Toulouse aerospace cluster hosts visual display system integration facilities serving NATO customer requirements.
Global Military Airborne Simulation and Training Market Competitive Landscape
Global majors compete with regional champions across certification standards and sovereign content requirements. The vendor base stratifies between full-stack platform integrators and specialized subsystem suppliers serving unbundled procurement contracts. Three archetypes dominate: defense primes bundling hardware with classified threat libraries, precision engineering houses controlling motion base actuator supply, and visual system specialists subject to recurrent FAA qualification testing. Competitive moves concentrate on portfolio diversification into multi-domain simulation convergence and strategic partnerships securing access to electromagnetic warfare scenario data.
Within the defense prime tier, Lockheed Martin Corporation and Northrop Grumman Corporation occupy positions anchoring training portfolio development on fighter-specific synthetic ecosystem integration. CAE Inc. exemplifies the precision engineering archetype through captive composites manufacturing capabilities controlling platform delivery timelines. Rheinmetall AG represents the regional champion model competing through Eurofighter-specific mission rehearsal suites tailored to European air force requirements.
| Leading Market Players |
|---|
| FlightSafety International Inc. |
| Rheinmetall AG |
| CAE Inc. |
| Northrop Grumman Corporation |
| BAE Systems PLC |
| Lockheed Martin Corporation |
| Collins Aerospace |
| L3Harris Technologies |
| THALES |
| Others |
Supply & Pricing Matrix
NATO air force unbundling of simulator hardware from long-term service agreements is forcing subsystem suppliers to absorb qualification documentation costs while compressing full-stack integrator margins. This procurement fragmentation reshapes how motion base manufacturers and visual system specialists negotiate contract structures across allied training programs.
Pricing Analysis
Input-cost pass-through from carbon fiber-reinforced polymer and precision actuator manufacturing concentrates pricing power among European and North American engineering houses. Three-tier pricing structure across full-mission, part-task, and desktop training systems differentiates by fidelity grade and FAA qualification tier. Pricing pressure stems from defense procurement offices demanding modular, software-scalable architectures over fixed-base legacy platforms. Air force squadrons exhibit highest price sensitivity for deployable training nodes, while defense academies absorb premium positioning for networked multi-domain installations.
Supply Chain Analysis
Single-source vulnerability sits with German and Italian precision engineering clusters manufacturing high-G centrifuge actuators. Geographic supply concentration centers on Germany, the United States, and Canada for motion platform composites and laser projection dome assemblies. Raw material dependencies rest on aerospace-grade carbon fiber prepregs, rare-earth magnets for servo motors, and gallium nitride substrates for RF components. Supply chain risk hinges on national security restrictions blocking electromagnetic warfare scenario data transfer across allied training coalitions. Distribution runs through prime contractor integration facilities serving NATO Aircrew Training and Reconnaissance Support program specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as air forces redirect certification budgets toward simulator-based programs with measurable carbon reduction credentials against live-flight benchmarks.
For Market Incumbents: To counter contract unbundling eroding full-stack margins, anchor position through captive composites manufacturing controlling carbon fiber-reinforced motion base delivery timelines. Deepen software-defined radio integration capabilities reconciling proprietary military waveforms with commercial Ethernet backbones to extend system integration service contracts. For New Entrants and Emerging Players: Begin with deployable containerized simulation nodes for Royal Australian Air Force Pacific rebalance programs, where expeditionary capability requirements outstrip incumbent fixed-infrastructure portfolios. Target micro-OLED headset subsystem supply for expeditionary training nodes as consumer electronics resolution advances enable military-grade visual fidelity at reduced hardware footprints. For Investors and Strategic Acquirers: Asymmetric upside sits with precision engineering specialists controlling high-G centrifuge actuator manufacturing amid NATO emission reduction protocol acceleration. Long-term viability favors vendors with backward integration into carbon fiber composites and classified threat library access through national security clearance structures. Watch FAA-EASA mutual recognition pathway expansion as inflection signal for qualification documentation consolidation plays.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Fiber Composites Integration | CAE Inc. leverages captive manufacturing to control platform delivery timelines for NATO customers. |
| F-35 Synthetic Ecosystem Development | Lockheed Martin Corporation anchors training portfolios on fighter-specific multi-domain scenario integration. |
| Eurofighter Mission Rehearsal Suites | Rheinmetall AG competes through European air force-specific threat library bundling. |
| Deployable Containerized Nodes | Royal Australian Air Force modernization programs seek distributed training across northern bases. |
| Micro-OLED Headset Subsystem Supply | Consumer electronics advances enable military-grade visual fidelity for expeditionary units. |
Research Methodology
Direct dialogue with flight training center directors, defense procurement officers, simulator platform engineers, and electromagnetic warfare scenario developers grounded qualitative insights. Secondary validation drew from FAA synthetic training device qualification standards, NATO Aircrew Training and Reconnaissance Support program documentation, EASA mutual recognition pathway filings, and defense contractor SEC disclosures. Bottom-up and top-down triangulation reconciled subsystem vendor capacity data with air force procurement budget allocations.
Bottom-up modeling aggregated individual platform installations across full-mission, virtual reality, part-task, and desktop fidelity tiers. Segmentation dimensions spanned product type, training phase, end-user archetype, and technology layer including networked simulators, motion platforms, and visual display systems. CAGRs derived from hardware refresh cycle compression under FAA recurrent qualification mandates and NATO emission reduction protocol adoption curves. Industry-specific inputs incorporated carbon fiber composite cost trajectories and classified threat library access control evolution.
Several conditions sit outside the modeled scope, including sovereign content requirement shifts altering multinational training coalition vendor access, and unforeseen electromagnetic spectrum allocation changes affecting software-defined radio integration complexity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Simulation and Training
Satellite Simulator Market
Simulation and Training
GNSS Simulators Market
Simulation and Training
Military Aerospace Simulation and Training Market
Simulation and Training
Military Vehicles and Aircraft Simulations Market
Simulation and Training
Military Simulation and Training Market
Simulation and Training
Civil Aerospace Simulation and Training Market
Simulation and Training
Europe Flight Training and Simulation Market
Simulation and Training
Helicopter Simulator Market
Simulation and Training
Military Training Aircraft Market
Simulation and Training
North America Ship Bridge Simulators Market
Simulation and Training
Trainer Aircraft Market
Simulation and Training
Asia-Pacific Civil Aviation Simulators Market
Simulation and Training
Europe Ship Bridge Simulators Market
Simulation and Training
Military Simulation Software Market
Simulation and Training
UAV Flight Training and Simulation Market
Simulation and Training
Dynamic Flight Training Compartments Market