
 UAV Flight Training and Simulation Market | 2026-2036
UAV Flight Training and Simulation Market Size, Share, and Industry Trends Forecast 2026-2036
UAV Flight Training and Simulation Market Intelligence
Defense sector investment is recalibrating the end-use vertical mix, with military agencies now commanding the dominant share of advanced simulation procurement. CAE Inc. leverages its installed base of full-flight simulators to extend into UAV-specific training systems for allied air forces. L3Harris Technologies Inc. anchors its position through integrated mission rehearsal platforms that combine synthetic environments with live data feeds. Zen Technologies Limited competes on cost-optimized ground control station trainers tailored for emerging military operators in Asia and the Middle East.
UAV flight training and simulation encompasses hardware and software systems that replicate aircraft dynamics, sensor payloads, and mission scenarios without airborne risk, typically operating at frame rates exceeding 60 Hz with six-degrees-of-freedom motion bases for high-fidelity applications. The primary purpose spans operator certification, mission rehearsal, and emergency procedure drilling across both military and civilian contexts. Virtual Reality technology leads current procurement for immersive cockpit environments, while Cloud-Based delivery mode represents the fastest-expanding structural segment as defense organizations migrate training networks to distributed architectures. Pilot Training application retains the largest revenue pool, though Tactical Simulation commands premium pricing due to classified scenario libraries and real-time threat modeling requirements.
The FAA regulates commercial UAV operator certification under Part 107, with recurrent knowledge testing creating sustained demand for accredited training modules. EASA's U-space framework and specific category operational authorizations are pushing European operators toward standardized simulation-based competency demonstrations. Military procurement across NATO members references STANAG 4586 interoperability standards, which mandate common interfaces between national simulation assets. Stakeholders must monitor how emerging detect-and-avoid mandates reshape simulator fidelity requirements and whether defense budget reallocations toward autonomous systems dilute human operator training investment.
Market Dynamics
The migration toward live-virtual-constructive training architectures is compressing procurement cycles for high-fidelity simulators as defense agencies consolidate vendor relationships and demand interoperable systems.
Growth Catalysts
- FAA Part 107 recurrent mandates:Commercial operators must complete periodic knowledge testing, creating sustained demand for accredited training modules and simulator-based competency demonstrations.
- Beyond Visual Line of Sight rulemaking:Evolving FAA frameworks for BVLOS operations are tightening certification requirements and expanding the addressable market for advanced simulation systems.
- STANAG 4586 interoperability standards:NATO procurement references mandate common interfaces between national simulation assets, driving standardization and cross-border training network integration.
Market Restraints
- Motion base hardware costs:Six-degrees-of-freedom platforms with 60 Hz frame rates require precision electromechanical components that concentrate supply among specialized German and Japanese component suppliers.
- Classified scenario library limitations:Tactical simulation content with real-time threat modeling faces export control restrictions that fragment addressable markets for premium-tier systems.
- Cloud security certification delays:Defense organizations migrating training networks to distributed architectures encounter prolonged authority-to-operate timelines for classified data environments.
Strategic Opportunities
- EASA U-space framework expansion:European specific-category operational authorizations are pushing operators toward standardized simulation-based competency demonstrations, opening procurement channels.
- Virtual Reality cockpit immersion:Head-mounted display systems are converging with haptic feedback interfaces to reduce physical simulator footprint and enable portable training deployments.
- India defense modernization:Cost-optimized ground control station trainers face limited domestic competition and align with procurement budgets of emerging military operators across Asia.
Industry Challenges
- Detect-and-avoid algorithm validation:Simulator fidelity requirements for autonomous sense-and-avoid systems lack standardized test criteria, complicating certification timelines for next-generation platforms.
- Legacy system integration friction:Existing full-flight simulator installed bases require substantial software architecture modifications to accommodate UAV-specific dynamics and sensor payload replication.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAV Flight Training and Simulation Market |
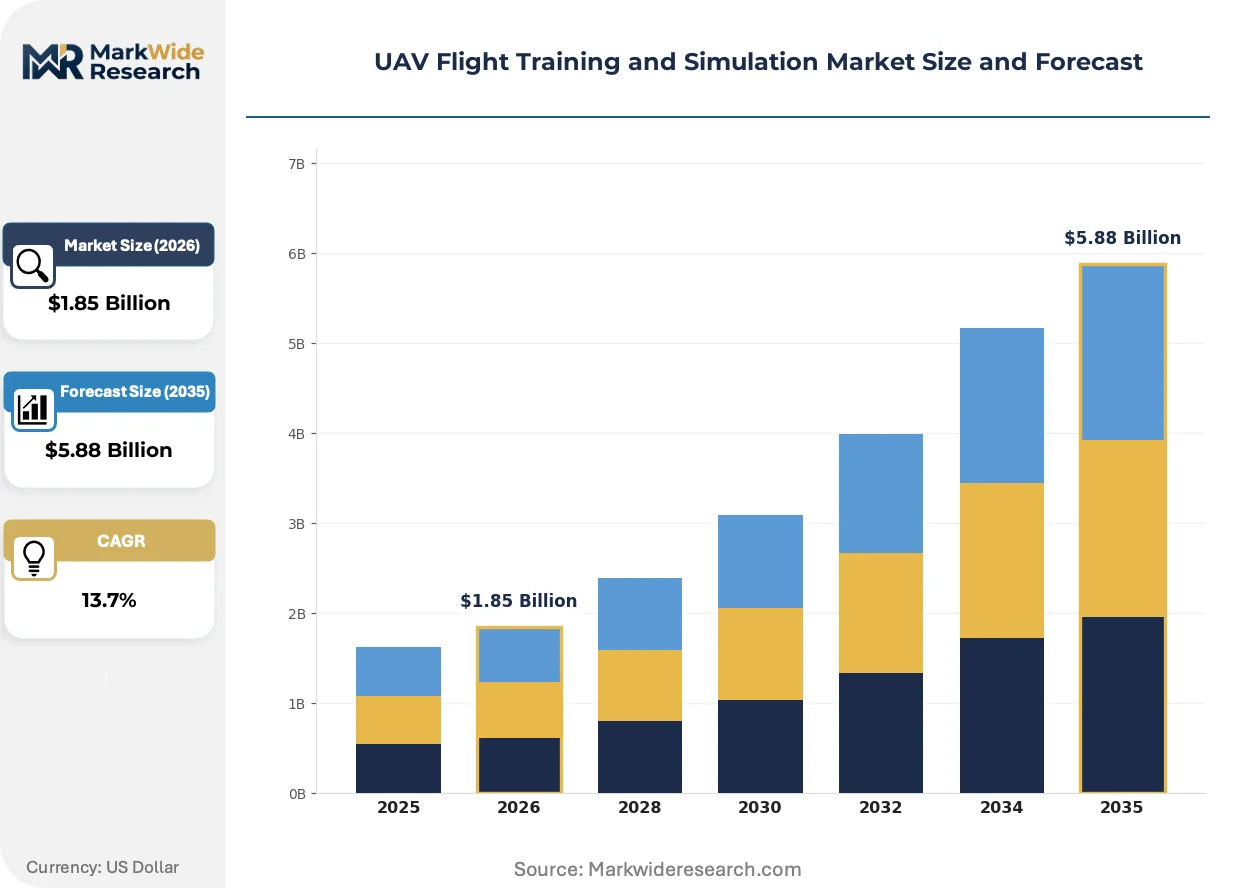
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $5.88 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Virtual Reality, Augmented Reality, Synthetic Environment, Real-Time Simulation End User: Military, Commercial, Educational Institutions, Private Pilots Delivery Mode: Cloud-Based, On-Premise, Hybrid, Mobile Applications Application: Pilot Training, Mission Planning, Tactical Simulation, Course Development |
| Companies Covered | CAE Inc., Israel Aerospace Industries, L3Harris Technologies Inc., Textron Systems, Northrop Grumman Corporation, BAE Systems, Thales Training and Simulation, Zen Technologies Limited, Simlat, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAV Flight Training and Simulation Market Strategic Shifts & Innovations
Training delivery models are fragmenting as defense organizations abandon centralized simulator facilities in favor of distributed architectures that reduce travel burdens and increase training frequency.
Cloud-based simulation delivery is decentralizing access to high-fidelity training environments by enabling secure remote connectivity to centralized scenario libraries. Allied air forces are adopting this architecture fastest, driven by coalition exercise requirements and budget pressure to maximize simulator utilization rates. This shift is decentralizing vendor power away from hardware-centric suppliers toward platform-agnostic software providers capable of managing distributed training networks.
EASA's U-space framework is mandating standardized competency demonstrations for specific-category operations, forcing European operators to document simulator-based training hours for operational authorizations. The regulation compresses approval timelines for certified training providers while excluding non-accredited vendors from commercial drone service procurement. Commercial operators in Germany and France are responding by consolidating vendor relationships with simulation houses holding recognized design organization approvals.
Buyer concentration among defense primes is compressing payment terms and demanding outcome-based training effectiveness metrics rather than equipment specifications. Traditional simulator manufacturers face margin pressure as procurement teams unbundle hardware from scenario content and after-sales support. This behavioral shift is most visible in United States Department of Defense contracts, where indefinite-delivery indefinite-quantity vehicles favor vendors demonstrating measurable pilot proficiency improvements.
UAV Flight Training and Simulation Market Segmentation
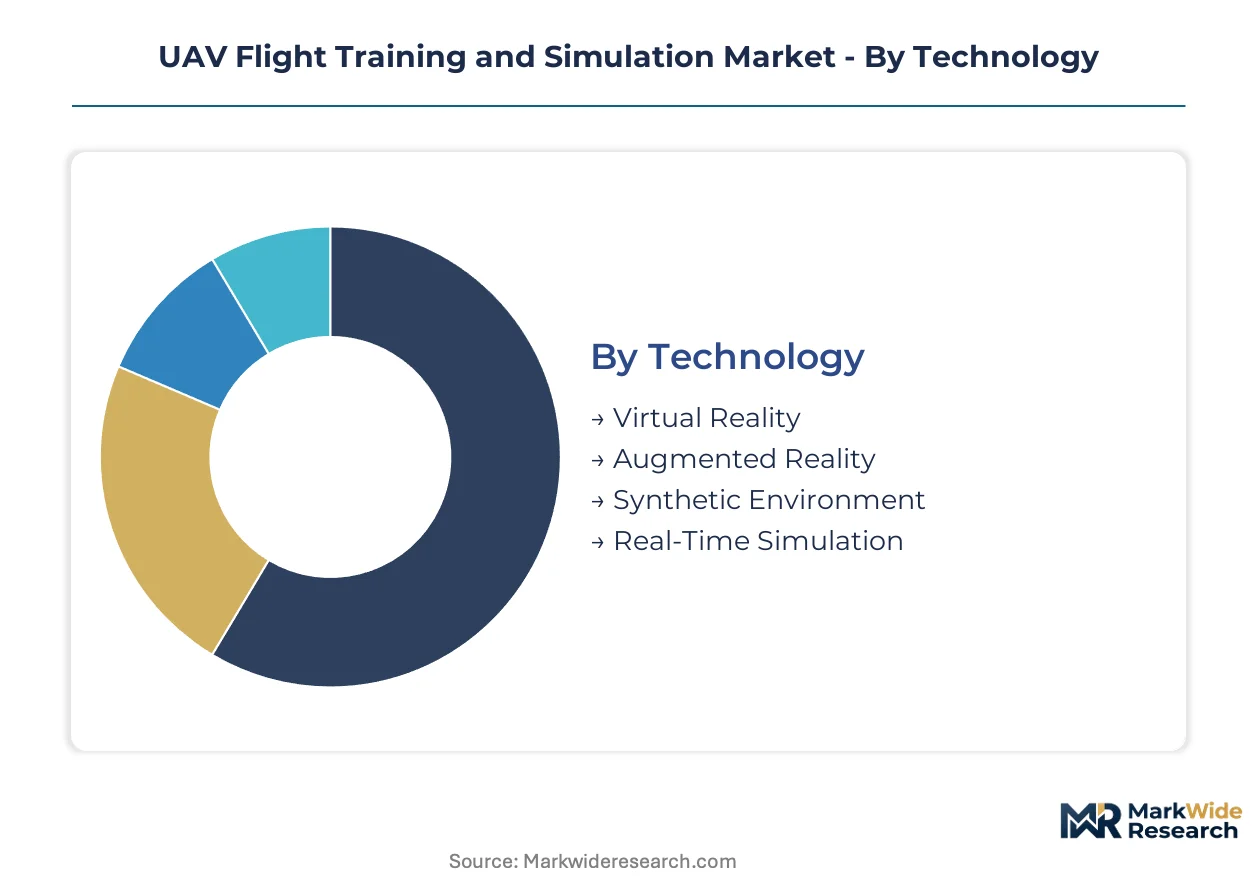
Procurement patterns in UAV flight training diverge sharply across technology maturity, operational security requirements, and infrastructure constraints. Segment boundaries are blurring as defense agencies demand interoperable systems while commercial operators prioritize cost-efficient, scalable delivery models.
Technology:
Upgrade cycles compress as military end-users replace legacy projection-based systems with immersive head-mounted displays and haptic feedback interfaces.
- Virtual Reality:Head-mounted display systems generate fully immersive cockpit environments with 90-degree field-of-view rendering at sub-20ms motion-to-photon latency. Demand concentrates in United States Air Force pilot training pipelines, driven by portability requirements for deployed operations and reduced physical simulator footprint.
- Synthetic Environment:Physics-based scenario engines replicate terrain, weather, and electromagnetic spectrum conditions with geospecific database accuracy. NATO coalition exercises in Germany and Poland are accelerating procurement of interoperable synthetic environments that federate across national training networks.
- Augmented Reality:Overlay systems blend physical cockpit hardware with computer-generated symbology for mixed-reality training scenarios.
- Real-Time Simulation:Deterministic frame-locked architectures maintain temporal consistency for hardware-in-the-loop testing of flight control systems.
Virtual Reality sits at the top of the volume ranking, with Synthetic Environment climbing the fastest.
End User:
Customer procurement authority shapes contract structures, with military agencies favoring indefinite-delivery vehicles while commercial operators seek subscription-based access models.
- Military:Defense agencies command premium-tier systems with classified threat libraries, six-degrees-of-freedom motion bases, and STANAG 4586 interoperability mandates. Procurement in the United States, United Kingdom, and Australia favors integrated live-virtual-constructive architectures that network simulators across dispersed bases.
- Commercial:Drone service providers and enterprise operators require Part 107-compliant training modules with recurrent knowledge testing support. United States-based commercial operators are consolidating vendor relationships with FAA-recognized training providers to secure operational authorizations for beyond-visual-line-of-sight missions.
- Educational Institutions:University flight programs and technical colleges procure entry-level desktop simulators for foundational UAS curriculum delivery.
- Private Pilots:Individual recreational operators access consumer-grade simulation software through direct digital distribution channels.
Military end-users dominate absolute spending, with Commercial expanding most quickly as FAA regulatory tightening broadens the addressable market.
Delivery Mode:
Infrastructure maturity determines deployment feasibility, with classified environments requiring air-gapped on-premise systems while unclassified training migrates toward distributed cloud architectures.
- Cloud-Based:Centralized scenario libraries with secure remote access enable distributed training networks and coalition exercise participation. Allied air forces in Norway and the Netherlands are adopting this architecture fastest, driven by budget pressure to maximize simulator utilization across multiple operating locations.
- On-Premise:Air-gapped installations with localized hardware maintain operational security for classified mission rehearsal and tactical simulation content. Demand persists in United States Special Operations Command and United Kingdom Defence Science and Technology Laboratory facilities where data sovereignty requirements prohibit external network connectivity.
- Hybrid:Architectures partition unclassified pre-mission planning in cloud environments from classified execution phases in secure facilities.
- Mobile Applications:Tablet and smartphone-based training modules deliver portable knowledge assessment and emergency procedure review.
On-Premise retains the largest installed base, with Cloud-Based gaining share fastest as authority-to-operate timelines compress for classified cloud environments.
Application:
Training outcome requirements dictate fidelity investments, with pilot certification demanding repetitive procedure drilling while tactical simulation requires dynamic threat response adaptation.
- Pilot Training:Operator certification programs emphasize stick-and-rudder proficiency, instrument interpretation, and emergency procedure execution under time pressure. FAA Part 107 recurrent mandates in the United States sustain demand for accredited modules that document simulator hours toward operational currency.
- Tactical Simulation:Mission rehearsal systems integrate real-time intelligence feeds with synthetic threat environments for operational planning. United States Indo-Pacific Command and United Kingdom Strategic Command procure these systems for contested environment preparation, with premium pricing reflecting classified scenario development costs.
- Mission Planning:Pre-flight route optimization and payload configuration tools leverage high-fidelity terrain databases.
- Course Development:Authoring environments enable military and civilian instructors to construct customized training scenarios.
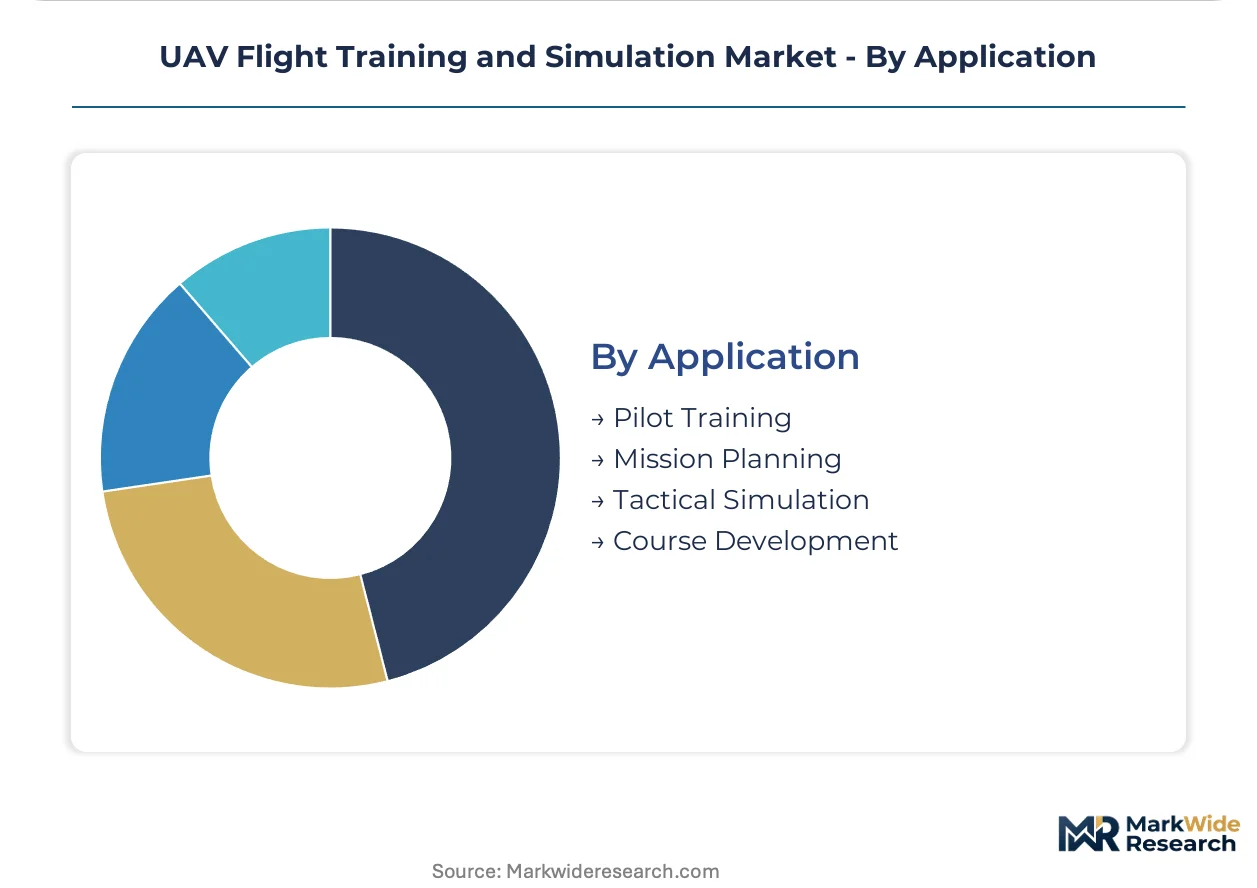
Pilot Training commands the largest revenue pool, with Tactical Simulation exhibiting the steepest expansion trajectory as great-power competition intensifies investment in contested environment preparation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping procurement flows as defense agencies migrate simulation investments toward jurisdictions with streamlined certification pathways and favorable export control frameworks. Cost-of-compliance gaps between national security review processes are concentrating advanced system development in specific allied markets.
United States
The FAA's Part 107 recurrent training mandates and evolving BVLOS rulemaking are tightening operational certification requirements for commercial operators. Military procurement budgets across NATO members are expanding live-virtual-constructive training architectures. Demand concentrates in the United States, where defense primes and emerging commercial drone service providers jointly drive simulator procurement in the Washington D.C. corridor and California aerospace clusters.
Germany
NATO coalition exercises in Germany and Poland are accelerating procurement of interoperable synthetic environments that federate across national training networks. EASA's U-space framework and specific category operational authorizations are pushing European operators toward standardized simulation-based competency demonstrations. The country's national aerospace regulator works closely with military procurement offices in Bavaria and Baden-Württemberg to align STANAG 4586 interoperability standards with domestic certification requirements.
United Kingdom
United Kingdom Strategic Command procures tactical simulation systems for contested environment preparation, with premium pricing reflecting classified scenario development costs. The country's defense science and technology facilities maintain air-gapped installations where data sovereignty requirements prohibit external network connectivity. London and the Southeast region host integrated mission rehearsal platform providers serving allied air force training networks.
India
Cost-optimized ground control station trainers face limited domestic competition and align with procurement budgets of emerging military operators across Asia. Zen Technologies Limited competes on cost-optimized ground control station trainers tailored for emerging military operators in Asia and the Middle East. Maharashtra and Karnataka states are developing domestic simulation capabilities to reduce import dependency for UAV operator training infrastructure.
Australia
United States Indo-Pacific Command procurement patterns are influencing allied investment in contested environment preparation capabilities. The country's defense organization encounters prolonged authority-to-operate timelines for classified data environments in cloud migration initiatives. Queensland and New South Wales host distributed training network nodes connecting to coalition synthetic exercise architectures.
UAV Flight Training and Simulation Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with defense primes commanding premium-tier procurement through integrated platform offerings while regional specialists capture cost-sensitive emerging market demand. The vendor base concentrates around three strategic archetypes: full-flight simulator incumbents extending into UAV-specific systems, integrated mission rehearsal platform providers, and cost-optimized ground control station specialists. Dominant competitive moves include portfolio diversification into adjacent training technologies and strategic partnerships to achieve STANAG 4586 interoperability certification.
Among North American defense primes, CAE Inc. and L3Harris Technologies Inc. exemplify contrasting positioning archetypes. CAE Inc. leverages its installed base to extend into UAV-specific training systems for allied air forces, representing the full-flight simulator incumbent pathway. L3Harris Technologies Inc. anchors its position through integrated mission rehearsal platforms that combine synthetic environments with live data feeds. Zen Technologies Limited occupies a distinct tier as a cost-optimized specialist targeting emerging military operators in Asia and the Middle East.
| Leading Market Players |
|---|
| CAE Inc. |
| Israel Aerospace Industries |
| L3Harris Technologies Inc. |
| Textron Systems |
| Northrop Grumman Corporation |
| BAE Systems |
| Thales Training and Simulation |
| Zen Technologies Limited |
| Simlat |
| Others |
Cost & Logistics Intelligence
Rare earth magnet price indices cascade through motion base manufacturing into three-tier pricing structures across premium, standard, and economy simulator tiers. Defense primes absorb electromechanical component volatility through long-term offtake agreements with Japanese and German suppliers, while commercial operators face spot-market exposure in VR headset procurement.
Pricing Analysis
Distributor margins compress as defense agencies consolidate vendor relationships and demand direct-to-OEM procurement channels. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and motion base fidelity, with STANAG 4586-compliant systems commanding substantial premiums over commercial-grade alternatives. Cost compression in the commercial tier intensifies because FAA-recognized training providers compete on recurrent knowledge testing volume. Drone service providers exhibit highest price sensitivity, while United States Special Operations Command demonstrates lowest sensitivity due to classified scenario library requirements.
Supply Chain Analysis
Single-source vulnerability sits with precision electromechanical component suppliers concentrated in Germany and Japan. Motion base hardware draws from specialized German servo motor manufacturers and Japanese encoder suppliers, with haptic feedback interfaces resting on Taiwanese semiconductor fabrication. Tariff exposure threatens cost-optimized ground control station trainers sourced through Asian assembly networks. Distribution runs through defense prime integrators for military procurement and direct SaaS platforms for commercial operator access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UAV flight training and simulation market functions as a regulatory compounder, with FAA Part 107 recurrent mandates and evolving BVLOS rulemaking generating sustained demand for accredited training infrastructure.
For Market Incumbents: Deepen backward integration into motion base electromechanical components to defend margins against German and Japanese supplier concentration. Lock in STANAG 4586 interoperability certification investments to forestall emerging platform-agnostic software providers threatening hardware-centric revenue streams.
For New Entrants and Emerging Players: Defense prime channel partners represent the most viable entry vector for cost-optimized ground control station trainers targeting India's defense modernization. White-space concentrates in EASA U-space framework compliance services for European commercial operators lacking simulator-based competency demonstration infrastructure. Pursue recognized design organization approvals to access procurement channels excluding non-accredited vendors.
For Investors and Strategic Acquirers: Consolidation pressure builds where cloud security certification delays fragment defense training network procurement. Long-term viability centers on platform-agnostic software providers capable of managing distributed architectures across allied air forces. Target acquisition profiles emphasize scenario content libraries with real-time threat modeling capabilities. Watch for authority-to-operate timeline compression in classified cloud environments as the inflection signal accelerating cloud-based delivery mode adoption.
| Strategic Initiative | Industry Significance |
|---|---|
| STANAG 4586 Interoperability Certification | Unlocks NATO coalition exercise procurement and cross-border training network integration. |
| Cloud Security Authority-to-Operate | Enables distributed training architectures for Norwegian and Netherlands air forces. |
| VR-Haptic Convergence Development | Reduces physical simulator footprint for United States Air Force deployed operations. |
| Classified Scenario Library Expansion | Commands premium pricing from United States Indo-Pacific Command mission rehearsal procurement. |
| EASA Recognized Design Organization Approval | Secures operational authorization channels for German and French commercial drone services. |
Research Approach
Bottom-up military and commercial operator modeling reconciled against top-down simulator hardware and software supply tracking forms the analytical core of this study. Primary interviews with flight training program directors, defense procurement officers, regulatory affairs specialists at aviation authorities, and simulation technology R&D heads combined with secondary validation against FAA regulatory filings, EASA U-space framework documentation, NATO STANAG standards, and defense budget appropriation records. Triangulation between end-use demand signals and supply-side production capacity ensures cross-verified market sizing.
Input-output matrices map technology adoption curves against regulatory milestone timing across the projection horizon. Segmentation dimensions span technology maturity, end-user procurement authority, delivery mode infrastructure constraints, and application fidelity requirements. CAGRs derive from scenario-weighted regression analysis incorporating detect-and-avoid mandate progression, defense budget reallocation patterns toward autonomous systems, and cloud security certification velocity as UAV-specific forecast inputs.
Revisions become necessary when BVLOS rulemaking timelines shift, defense budget reallocations dilute human operator training investment, or detect-and-avoid algorithm validation standards crystallize differently than modeled. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Simulation and Training
Flight Simulation Training Device Market
Simulation and Training
Satellite Simulator Market
Simulation and Training
Global Military Airborne Simulation and Training Market
Simulation and Training
Police and Military Simulation Training Market
Simulation and Training
Asia-Pacific Ship Bridge Simulators Market
Simulation and Training
Civil Aviation Simulator Market
Simulation and Training
Military Vehicles and Aircraft Simulations Market
Simulation and Training
Civil Aerospace Simulation and Training Market
Simulation and Training
Military Simulation and Training Market
Simulation and Training
Global Healthcare Games and Simulation Market
Simulation and Training
Europe Ship Bridge Simulators Market
Simulation and Training
Military Simulation Virtual Training Market
Simulation and Training
Middle East and Africa Ship Bridge Simulators Market
Simulation and Training
Military Training Aircraft Market
Simulation and Training
Air Traffic Control Simulation and Training Market
Simulation and Training
Flight Simulator Market