
 Military Vehicles and Aircraft Simulations Market | 2026-2036
Military Vehicles and Aircraft Simulations Market Size, Share, and Industry Trends Forecast 2026-2036
Military Vehicles and Aircraft Simulations Market Outlook
Market Context with Strategic Players
Defense leasing and performance-based contracting is reconfiguring capital deployment across the simulation sector, allowing mid-tier contractors to access high-fidelity platforms without full ownership burdens. Lockheed Martin Corporation dominates through captive integration of hardware-software stacks across multiple domains. CAE Inc. leverages its geographic footprint to sustain training-as-a-service contracts with allied militaries. Rheinmetall AG anchors European ground-vehicle simulation demand through specialized armored-platform trainers.
Technical Definition and Structural Segments
Military vehicles and aircraft simulations encompass computer-generated environments, motion-base platforms, and software algorithms that replicate vehicle dynamics, weapons systems, and tactical scenarios for operator training and mission rehearsal, typically incorporating six-degrees-of-freedom motion cues and real-time physics engines operating at sub-50-millisecond latency. These systems reduce live-training costs, mitigate operational risk, and enable repetition of rare or dangerous conditions impossible to reproduce in physical exercises. Airborne Systems leads product-type revenue due to jet-trainer procurement cycles, while Simulation Software captures expanding margin pools as defense ministries shift toward modular, updateable architectures. Hybrid Systems technology is gaining share as forces blend live assets with constructive digital environments for joint-force exercises.
Regulatory Frame and Forward-Looking Close
The FAA governs certain civil-military crossover simulation standards in the United States, while the EU AI Act imposes algorithmic transparency requirements on autonomous-targeting trainers in Europe. NATO Standardization Office protocols shape interoperability mandates that determine market access for cross-border training contracts. Stakeholders must monitor how emerging cybersecurity certification frameworks for classified synthetic environments reshape procurement eligibility and vendor qualification pathways.
Market Dynamics
Defense ministries are compressing live-training budgets while demanding higher-fidelity synthetic environments, forcing simulation vendors to absorb hardware costs through leasing structures and performance-based contracting models.
Growth Catalysts
- EU AI Act compliance mandates:European defense procurement now requires algorithmic transparency in autonomous-targeting trainers, creating upgrade cycles for legacy platforms across NATO allied forces.
- Jet-trainer procurement cycles:Air forces in the United States, Germany, and Australia are replacing aging fleets with integrated simulation suites that reduce per-pilot training costs.
- Hybrid constructive-live architectures:Joint-force exercises blending physical assets with digital environments are expanding simulator utilization rates beyond traditional single-platform training.
Market Restraints
- Motion-base hardware cost volatility:Electromechanical actuators and precision hydraulics concentrate supply among Japanese and German component specialists, exposing integrators to input price swings.
- Classified-environment cybersecurity certification:National security frameworks for synthetic training sites impose multi-year approval timelines that delay contract execution.
- Live-flight hour substitution limits:Regulatory minimums for actual cockpit time in military aviation certification standards cap the addressable market for full simulation replacement.
Strategic Opportunities
- Underpenetrated Australian ground-vehicle segment:The Australian Army's armored platform modernization is creating demand for specialized crew trainers that European vendors currently underserve.
- 5G-enabled distributed training networks:Low-latency cellular infrastructure allows geographically dispersed squadrons to conduct synchronized virtual exercises without co-located hardware.
- Modular software architectures:Defense ministries are mandating updateable, open-standard simulation cores that shift margin pools from hardware sales to recurring software licenses.
Industry Challenges
- Sub-50-millisecond latency engineering talent:Real-time physics engine optimization requires specialized computational fluid dynamics expertise that defense contractors compete for against commercial gaming studios.
- Legacy platform integration complexity:Decades-old simulator networks in active service resist seamless connection to modern constructive environments without expensive middleware development.
- NATO interoperability certification timelines:Cross-border training contracts require vendor qualification through Standardization Office protocols that extend sales cycles by twelve to eighteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Military Vehicles and Aircraft Simulations Market |
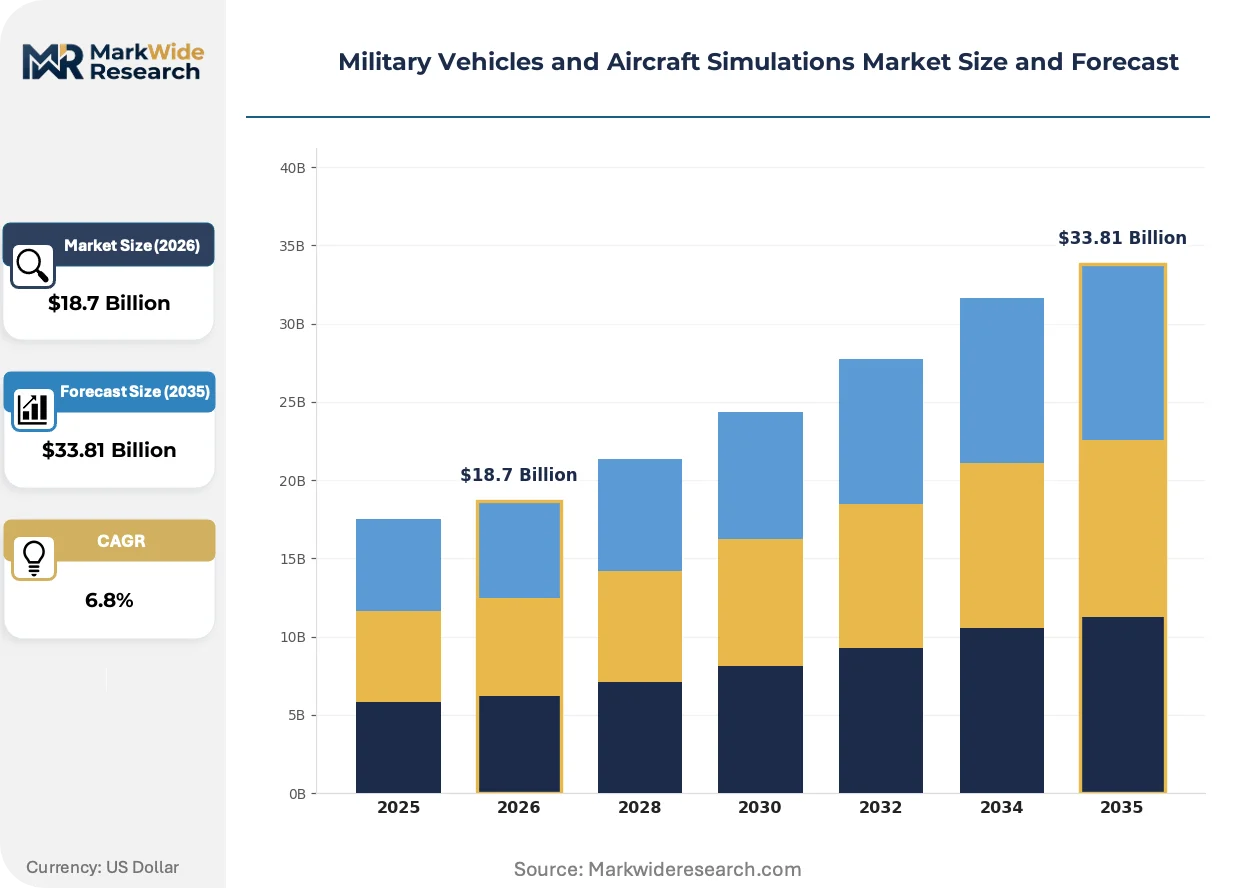
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ground Vehicles, Airborne Systems, Naval Platforms, Simulation Software End User: Government Agencies, Defense Contractors, Military Academies, Training Facilities Technology: Virtual Reality, Augmented Reality, Live Simulation, Hybrid Systems Application: Training, Mission Planning, Combat Simulation, Maintenance Training |
| Companies Covered | Lockheed Martin Corporation, CAE Inc., Thales Group, Rheinmetall AG, FlightSafety International, L3Harris Technologies, Collins Aerospace, BAE Systems, Saab AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Military Vehicles and Aircraft Simulations Market Strategic Shifts
Artificial intelligence inference at the network edge is compressing scenario-generation timelines while regulatory pressure on algorithmic decision-making is reshaping how autonomous-targeting systems receive training validation.
Neural-network-based adaptive scenario engines are rendering obsolete static, script-driven mission libraries that required manual content updates. The United States Air Force is deploying these systems across distributed pilot-training nodes, compressing curriculum development from months to days and forcing legacy simulator vendors to restructure software roadmaps or lose platform refresh contracts.
The EU AI Act imposes mandatory explainability requirements on synthetic environments used for lethal-autonomy training. European defense integrators must now document decision-pathway transparency in targeting algorithms, affecting simulation software architectures and driving demand for interpretable machine-learning frameworks over black-box neural networks in NATO procurement specifications.
Training-as-a-service contracts are displacing capital-heavy simulator purchases in allied military procurement. The Royal Australian Air Force now contracts flight-hour equivalents rather than owning motion-base platforms, shifting vendor revenue toward recurring operational expenditure models and concentrating market access among integrators with sustained logistics footprints in the Asia-Pacific theater.
Military Vehicles and Aircraft Simulations Market Segmentation
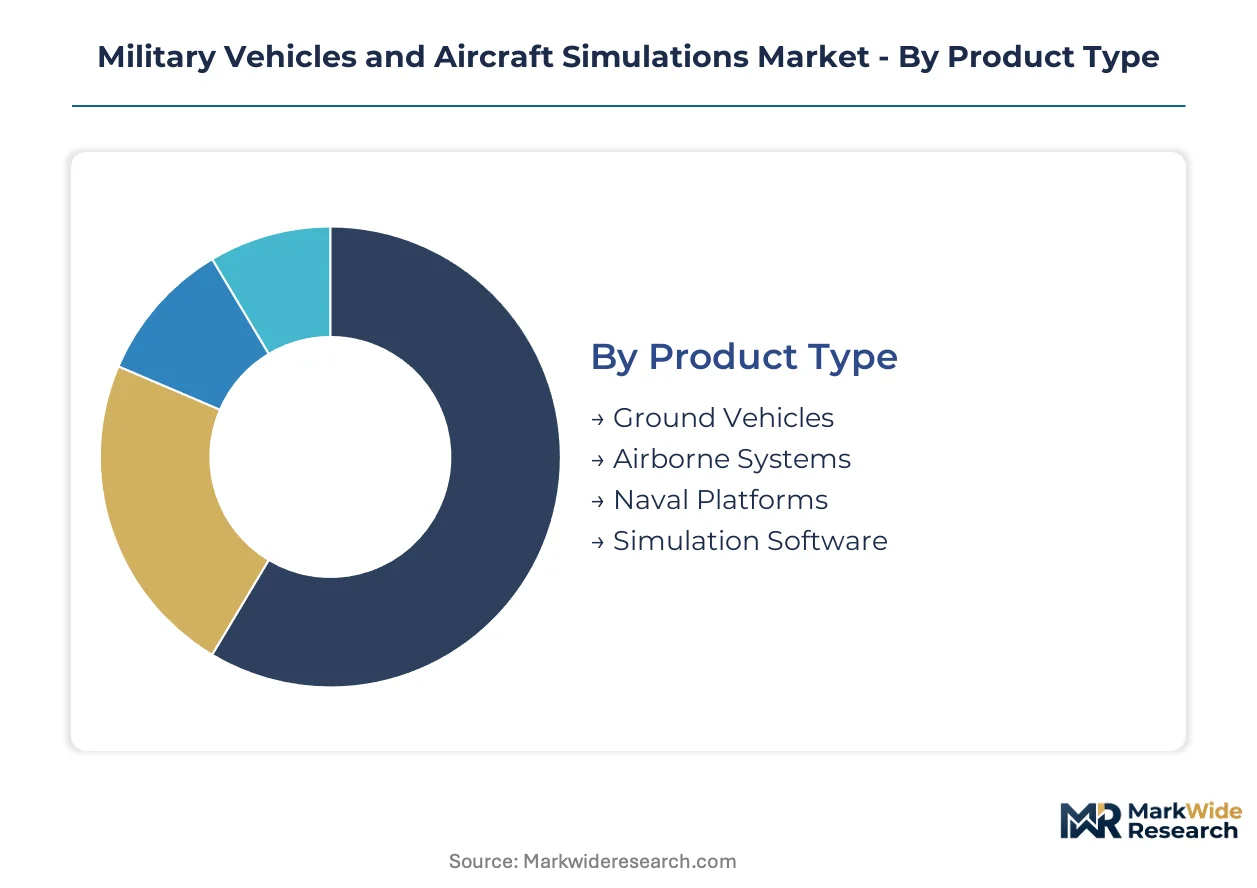
Segmentation in military simulation reveals how procurement cycles, certification requirements, and technology refresh rates create divergent investment timelines across hardware and software categories. Understanding these rhythms helps vendors align R&D spending with contract windows and anticipate upgrade waves before budget cycles lock.
Product Type:
Hardware platforms operate on decade-long replacement cycles tied to airframe and vehicle fleet modernization, while software layers turn over every three to five years as threat libraries and physics engines require updates.
- Airborne Systems:Jet-trainer procurement cycles in the United States, Germany, and Australia drive demand for high-fidelity cockpit replicas with six-degrees-of-freedom motion bases. Defense ministries prioritize these systems to reduce per-pilot training costs while maintaining FAA-equivalent certification standards for synthetic flight hours.
- Simulation Software:Modular, updateable architectures are capturing expanding margin pools as forces shift from capital purchases to recurring license models. The EU AI Act mandates algorithmic transparency in autonomous-targeting trainers, forcing European defense integrators toward interpretable machine-learning frameworks.
- Ground Vehicles:Specialized armored-platform trainers serve crew coordination for mechanized infantry and tank units, with Rheinmetall AG anchoring European demand through Bundeswehr modernization contracts.
- Naval Platforms:Submarine and surface-vessel bridge simulators concentrate procurement among nuclear deterrent operators and coastal defense forces with limited live-exercise access.
Airborne Systems dominates installed base. Simulation Software is where expansion concentrates.
End User:
Procurement authority and budget scale vary sharply across buyer types, with government agencies controlling sovereign training infrastructure while contractors seek flexible, exportable platforms for allied foreign military sales.
- Government Agencies:National defense ministries in the United States, Germany, and Australia direct capital allocation toward sovereign training sites, with NATO Standardization Office protocols shaping interoperability mandates that determine cross-border contract eligibility.
- Defense Contractors:Lockheed Martin Corporation and CAE Inc. integrate simulation suites into broader platform sales, using training-as-a-service contracts to sustain long-term revenue from allied militaries.
- Military Academies:Officer training institutions require foundational flight and vehicle simulators with curriculum-aligned scenario libraries and instructor-led debrief capabilities.
- Training Facilities:Dedicated simulation centers in the Asia-Pacific theater are adopting 5G-enabled distributed networks to synchronize exercises across geographically dispersed squadrons without co-located hardware.
Government Agencies command the largest absolute spend. Defense Contractors are gaining the fastest as performance-based contracting displaces direct procurement.
Technology:
Immersion depth and latency tolerance define technology selection, with virtual reality platforms advancing fastest in pilot training while hybrid architectures gain traction for joint-force exercises.
- Virtual Reality:Head-mounted displays and spatial audio systems reduce hardware footprint for deployed training nodes, though motion sickness susceptibility limits session duration for some operator profiles.
- Hybrid Systems:Blending live assets with constructive digital environments expands utilization rates beyond single-platform training, with the United States Air Force deploying these architectures across distributed pilot-training nodes.
- Augmented Reality:Overlay systems for maintenance training and cockpit familiarization are gaining share as aircraft complexity outpaces traditional technical manual formats.
- Live Simulation:Instrumented ranges with laser-based engagement systems remain essential for force-on-force validation despite higher per-exercise costs than synthetic alternatives.
Live Simulation retains the deepest installed base. Hybrid Systems are climbing the fastest as joint-force exercise requirements intensify.
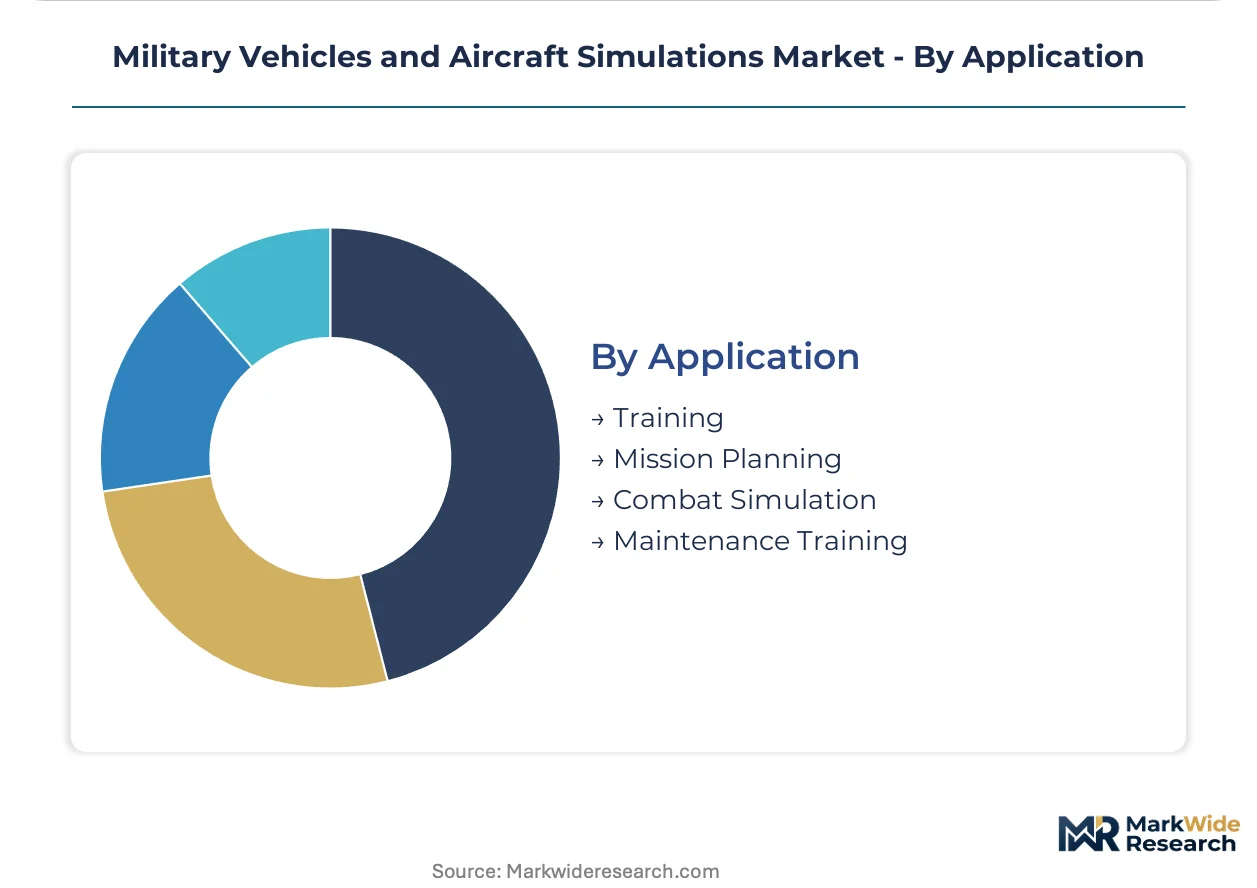
Application:
Training intensity and scenario complexity determine platform specification, with combat simulation demanding the highest fidelity while maintenance training prioritizes repeatable, low-cost access.
- Training:Pilot and vehicle operator readiness programs account for the majority of simulator utilization hours, with curriculum development compressing from months to days through neural-network-based adaptive scenario engines.
- Combat Simulation:High-stress tactical rehearsal requires real-time physics engines operating at sub-50-millisecond latency, with specialized computational fluid dynamics expertise concentrated among defense contractors competing against commercial gaming studios.
- Mission Planning:Pre-deployment rehearsal systems integrate satellite imagery and intelligence feeds to model operational environments before physical asset commitment.
- Maintenance Training:Virtual component interaction and fault isolation procedures reduce aircraft downtime by accelerating technician certification without risking operational platforms.
Training captures the highest volume of installed hours. Combat Simulation is gaining share fastest as threat complexity demands more sophisticated rehearsal environments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FAA certification standards for synthetic flight hours and NATO Standardization Office interoperability protocols are reshaping procurement eligibility across defense ministries, with cost-per-pilot training economics driving simulator adoption in allied air forces.
United States
The United States Air Force is deploying neural-network-based adaptive scenario engines across distributed pilot-training nodes, compressing curriculum development timelines. FAA-equivalent certification standards govern synthetic flight hour accreditation for military aviators. Lockheed Martin Corporation anchors demand through captive integration of hardware-software stacks at training facilities in Florida and Texas.
Germany
Bundeswehr modernization contracts for armored-platform trainers are expanding ground-vehicle simulation procurement. The EU AI Act mandates algorithmic transparency in autonomous-targeting trainers, forcing upgrade cycles for legacy platforms. Rheinmetall AG concentrates European demand through specialized crew trainers manufactured in North Rhine-Westphalia.
Australia
The Royal Australian Air Force contracts flight-hour equivalents through training-as-a-service models rather than owning motion-base platforms. The Australian Army's armored platform modernization is creating demand for specialized crew trainers. CAE Inc. sustains long-term revenue through logistics footprints in the Asia-Pacific theater centered on Victoria and Queensland training facilities.
United Kingdom
BAE Systems integrates simulation suites into broader platform sales for the Royal Air Force's jet-trainer replacement programs. NATO Standardization Office protocols determine cross-border training contract eligibility for British forces. Greater London and the Midlands host concentrated defense contractor engineering clusters supporting synthetic environment development.
France
Thales Group leverages its domestic position to supply virtual reality platforms for French Air and Space Force pilot readiness programs. The EU AI Act's explainability requirements affect simulation software architectures for lethal-autonomy training. The Provence-Alpes-Côte d'Azur region contains specialized computational fluid dynamics expertise competing against commercial gaming studios.
Military Vehicles and Aircraft Simulations Market Competitive Environment
Channel-controlling players compete with product-specialist players across a consolidated vendor base where captive hardware-software integration determines platform refresh contract outcomes. Tier-one integrators dominate through sustained logistics footprints and performance-based contracting models that displace capital-heavy purchases. Three strategic archetypes prevail: full-stack platform integrators, modular software specialists, and motion-base hardware fabricators. Competitive moves concentrate on strategic partnerships for NATO interoperability certification and technology licensing for 5G-enabled distributed training networks.
Among North American full-stack integrators, Lockheed Martin Corporation and CAE Inc. exemplify the channel-controlling archetype through training-as-a-service contracts that shift revenue toward recurring operational expenditure models. Rheinmetall AG occupies a distinct position as a European product specialist anchoring ground-vehicle demand through Bundeswehr modernization programs. These three entities represent the dominant competitive positioning vectors in allied military procurement.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| CAE Inc. |
| Thales Group |
| Rheinmetall AG |
| FlightSafety International |
| L3Harris Technologies |
| Collins Aerospace |
| BAE Systems |
| Saab AB |
| Others |
Value Chain & Pricing Dynamics
The Trans-Pacific shipping corridor from Yokohama to Long Beach shapes cost dynamics for Japanese electromechanical actuator suppliers, concentrating pricing power among German and Japanese component specialists while downstream integrators absorb hardware volatility through leasing structures that differentiate subscription tiers by motion fidelity and certification grade.
Pricing Analysis
Certification level creates the primary spread across NATO Standardization Office-compliant platforms versus non-interoperable trainers. Pricing stratifies across FAA-equivalent, CE-marked, and national-grade tiers, with algorithmic transparency mandates under the EU AI Act compressing margins on legacy black-box systems. Cost absorption through performance-based contracting intensifies as defense ministries shift capital expenditure to operational budgets. Government agencies exhibit lowest price sensitivity due to sovereign training mandates, while training facilities face acute pressure from 5G infrastructure deployment costs.
Supply Chain Analysis
Precision hydraulics and electromechanical actuators draw from concentrated manufacturing footprints in Japan, Germany, and the United States. Raw material dependencies center on rare-earth magnet supply for servo motors, high-grade aluminum for motion-base structures, and specialized semiconductors for real-time physics processing. Single-source vulnerability in Japanese actuator components exposes integrators to logistics chokepoint risk. Distribution runs through defense contractor captive networks and authorized service partnerships with sustained logistics footprints in allied territories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment through NATO interoperability certification creates structural barriers that extend sales cycles and concentrate market access among established integrators.
For Market Incumbents: Build switching-cost moats through captive integration of hardware-software stacks and sustained logistics footprints in allied territories. Deepen backward integration into motion-base component supply to mitigate Japanese actuator price volatility. Prioritize EU AI Act compliance investments to capture European upgrade cycles as legacy platforms face algorithmic transparency mandates. For New Entrants and Emerging Players: Establish a beachhead in the Australian ground-vehicle segment where European vendors currently underserve armored platform modernization demand. Target 5G-enabled distributed training networks as the most penetrable technology layer, leveraging low-latency cellular infrastructure to bypass co-located hardware requirements. Pursue modular software specialist positioning with open-standard architectures that defense ministries now mandate. For Investors and Strategic Acquirers: Carve-out targets emerge from defense conglomerates divesting non-core simulation assets amid portfolio rationalization. Long-term viability hinges on recurring revenue exposure through training-as-a-service contracts rather than capital-heavy platform sales. Monitor NATO Standardization Office protocol adoption rates as the critical inflection signal for cross-border contract eligibility expansion.| Strategic Initiative | Industry Significance |
|---|---|
| NATO Interoperability Certification Investment | Standardization Office protocol compliance unlocks cross-border training contracts with allied ministries. |
| Backward Integration into Motion-Base Components | German and Japanese actuator supply concentration creates margin vulnerability for hardware-dependent integrators. |
| EU AI Act Compliance Roadmap | Algorithmic transparency mandates force upgrade cycles for legacy autonomous-targeting trainers across European forces. |
| 5G-Enabled Distributed Network Deployment | Low-latency cellular infrastructure allows geographically dispersed squadrons to synchronize without co-located hardware. |
| Training-as-a-Service Contract Conversion | Royal Australian Air Force flight-hour equivalent models demonstrate recurring revenue potential displacing capital purchases. |
Study Parameters
Initial hypotheses were tested against primary input from defense procurement officers, simulation platform engineers, NATO Standardization Office certification specialists, and training-as-a-service contract managers, then refined through secondary validation against FAA certification databases, EU AI Act regulatory filings, defense ministry budget appropriations, and customs records for motion-base component trade flows. Bottom-up installed base estimates and top-down defense expenditure allocations were triangulated to reconcile volume and value outputs.
Demand-supply balance modeling across the projection horizon incorporated segmentation dimensions spanning product type, end-user procurement authority, technology immersion depth, and application intensity. CAGRs were derived from contract award velocity analysis and fleet modernization cycle timing. Industry-specific forecast inputs included jet-trainer replacement schedules and EU AI Act implementation timelines affecting software upgrade mandates.
Sensitivities concentrate around cybersecurity certification timeline delays for classified synthetic environments and live-flight hour minimum regulatory adjustments. Cross-checking against defense ministry budget execution reports and NATO training exercise frequency data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Simulation and Training
RADAR Simulator Market
Simulation and Training
Global Healthcare Games and Simulation Market
Simulation and Training
Middle East and Africa Ship Bridge Simulators Market
Simulation and Training
Pilot Training Market
Simulation and Training
Military Training Aircraft Market
Simulation and Training
Middle East Civil Aviation Flight Training and Simulation Market
Simulation and Training
Global Ship Bridge Simulators Market
Simulation and Training
Europe Flight Training and Simulation Market
Simulation and Training
Live Laser-Based Training and Simulation Platforms Market
Simulation and Training
Simulators Market
Simulation and Training
Military Simulation Software Market
Simulation and Training
Drone Simulator Market
Simulation and Training
Helicopter Simulator Market
Simulation and Training
North America Ship Bridge Simulators Market
Simulation and Training
Air Traffic Control Simulation and Training Market
Simulation and Training
Satellite Simulator Market