
 GNSS Simulators Market | 2026-2036
GNSS Simulators Market Size, Share, and Industry Trends Forecast 2026-2036
GNSS Simulators Market Analysis
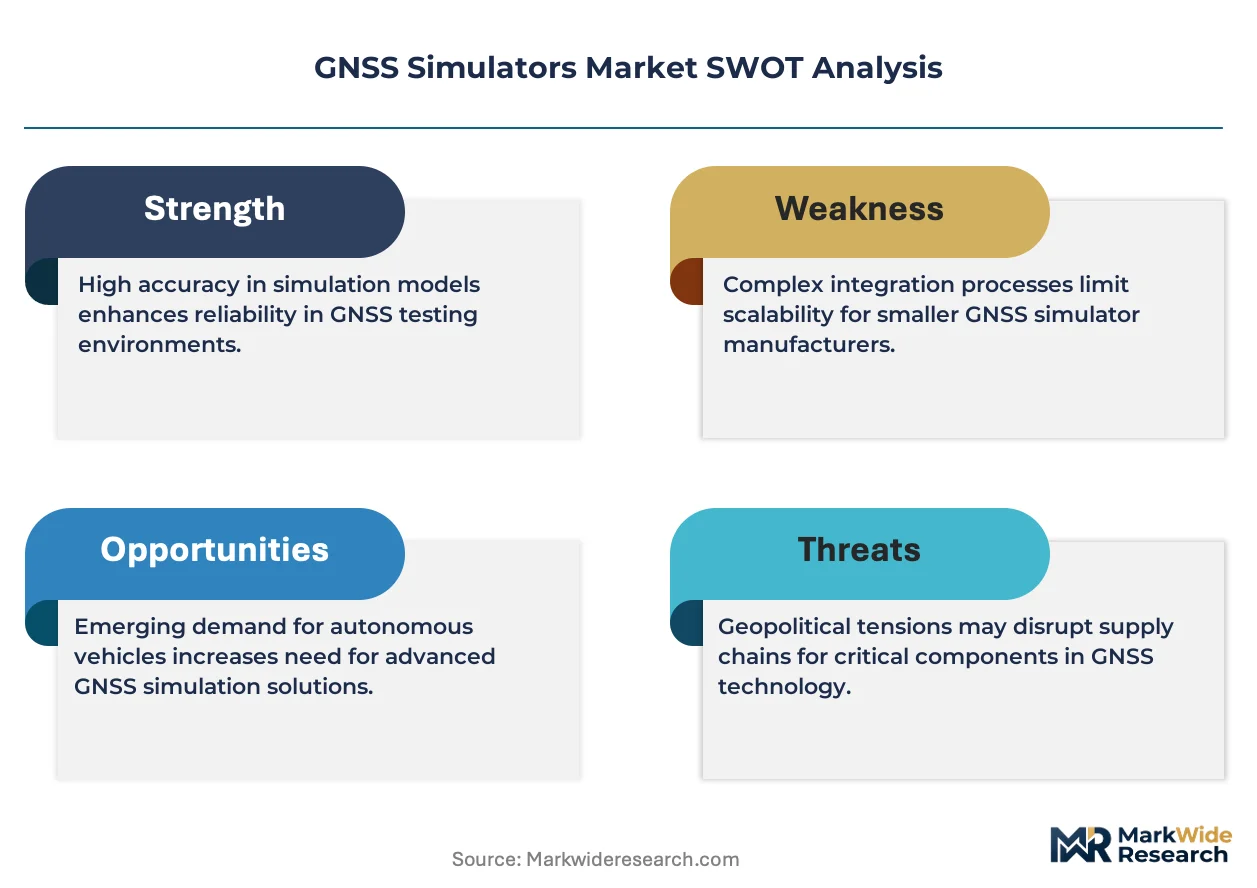
The EU Radio Equipment Directive is decoupling low-cost simulator imports from European defense and automotive supply chains by mandating traceable calibration to ETSI standards. Spirent Communications leverages deep vertical integration in signal generation hardware to sustain premium positioning across NATO-aligned test labs. Rohde & Schwarz anchors European market share through accredited calibration networks that competitors cannot replicate without years of accreditation investment. Hexagon AB differentiates by bundling simulator hardware with its native positioning software, creating sticky integrated workflows for autonomous vehicle developers.
GNSS simulators are precision instruments that synthesize radio frequency signals from satellite constellations including GPS, GLONASS, Galileo, and BeiDou, enabling controlled replication of atmospheric interference, multipath effects, and constellation geometry for receiver validation without live-sky dependency. Multi-channel architectures command the dominant share of procurement budgets because modern receivers must simultaneously track four or more constellations with centimeter-level accuracy. Software-based simulation is displacing legacy hardware-only systems as automotive developers demand rapid scenario iteration for autonomous navigation validation. Cloud-based deployment remains nascent but attracts research institutions seeking elastic compute for large-scale Monte Carlo testing of receiver fault modes.
EMA, FCC, and ETSI frameworks collectively shape product certification pathways, with ETSI EN 303 413 setting baseline signal fidelity for European automotive homologation while FCC Part 15 governs unintentional radiator compliance for simulators sold into U.S. defense programs. The divergence between European accreditation-heavy procurement and U.S. program-specific waivers creates dual-track product development burdens that favor established vendors with regulatory affairs scale. Stakeholders must monitor whether India's TEC certification expansion into GNSS test equipment creates a third compliance jurisdiction that fragments product portfolios or consolidates advantage among vendors already operating multi-standard platforms.
Market Dynamics
The GNSS simulators market is experiencing a structural compression between hardware-centric legacy architectures and software-defined alternatives, as automotive OEMs demand faster iteration cycles for autonomous navigation validation while defense programs maintain rigid hardware certification requirements.
Growth Catalysts
- Multi-constellation mandates:ETSI EN 303 413 and FCC equipment authorization rules now require validation against four or more satellite systems, forcing receiver manufacturers to expand simulator procurement budgets.
- Automotive homologation:Germany's KBA and similar transport authorities in France and Italy now mandate simulated interference scenarios for Level 3+ autonomous vehicle certification.
- Munich-Stuttgart testing clusters:Dense geographic concentration of aerospace and automotive R&D facilities in southern Germany generates localized demand spikes for high-channel-count systems.
Market Restraints
- RF front-end component concentration:Specialized signal generation hardware relies on a limited supplier base in Japan and the United States, creating input bottlenecks during capacity expansions.
- Accreditation moats:ETSI-traceable calibration networks require multi-year investment that locks out new entrants from European defense and automotive supply chains.
- Software emulation limits:Real-time kinematic and precise point positioning applications still require hardware-in-the-loop validation that cloud-based alternatives cannot replicate.
Strategic Opportunities
- India's TEC certification expansion:The Telecommunication Engineering Centre's emerging GNSS test equipment standards could consolidate demand among vendors with existing multi-standard platforms.
- 5G-NTN convergence:Integration of non-terrestrial network positioning with traditional GNSS creates new validation requirements for hybrid receiver architectures.
- Cloud-based Monte Carlo testing:Research institutions in the United Kingdom and Netherlands are piloting elastic compute models for large-scale receiver fault mode analysis.
Industry Challenges
- Dual-track product development:Divergence between European accreditation-heavy procurement and U.S. program-specific waivers forces vendors to maintain parallel certification pathways.
- Signal fidelity engineering talent:Scarcity of RF engineers capable of synthesizing atmospheric interference models with centimeter-level accuracy constrains R&D throughput.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GNSS Simulators Market |
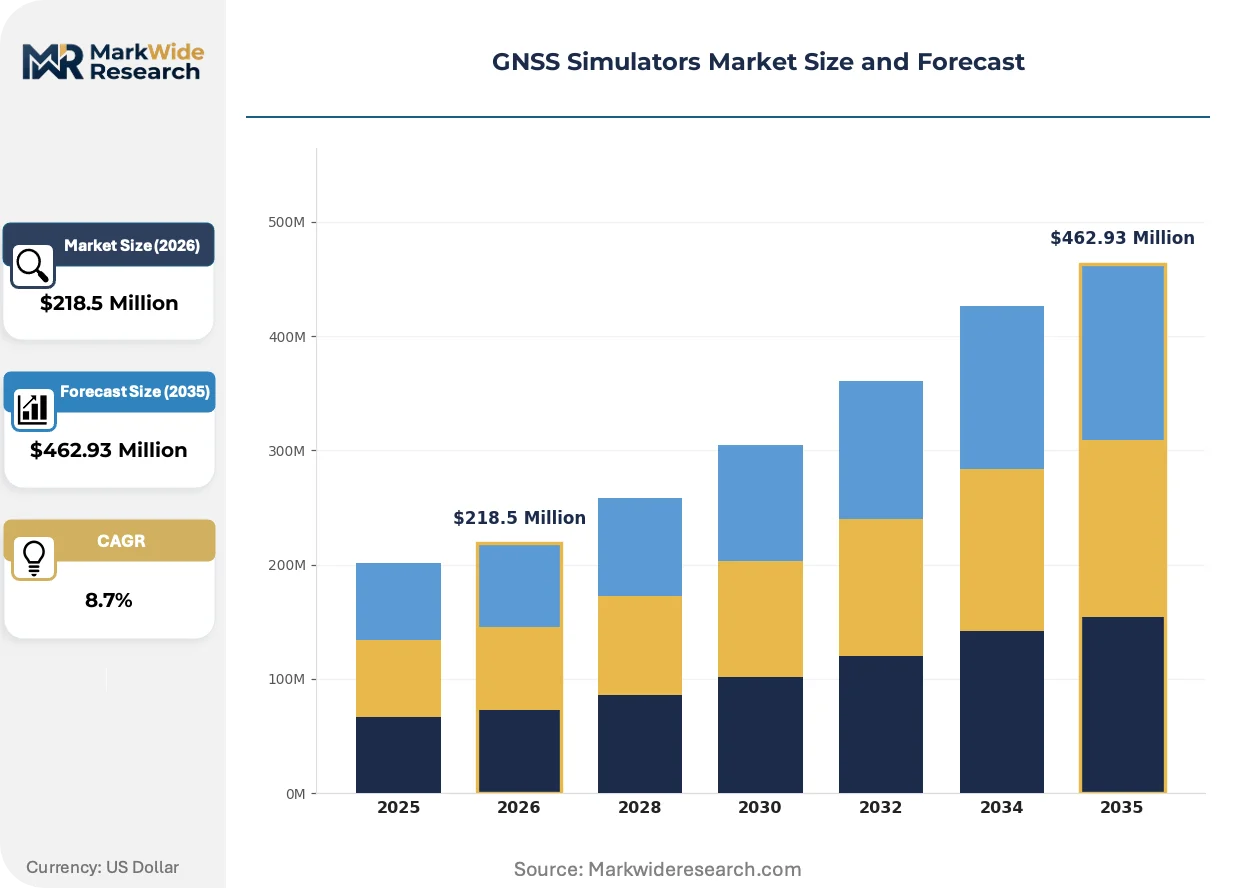
| Market Size in 2026 | $218.5 Million |
| Market Size in 2035 | $462.93 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Channel, Multi-Channel, GNSS Constellations, Integrated Solutions End User: Aerospace, Defense, Transportation, Research Institutions Technology: Software-Based, Hardware-In-the-Loop, Real-Time Simulation, Cloud-Based Application: Testing, Development, Training, Integration |
| Companies Covered | Spirent Communications, Rohde & Schwarz, Hexagon AB, Keysight Technologies, Orolia, VIAVI Solutions, CAST Navigation, Accord Software & Systems Private Limited, IFEN GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GNSS Simulators Market Emerging Trajectories
Software-defined architectures are actively displacing fixed-function hardware across automotive validation workflows, compressing scenario development cycles from weeks to hours while creating new competitive axes around API flexibility and cloud orchestration.
Software-based simulation is expanding into automotive development pipelines by enabling rapid constellation geometry manipulation and multipath scenario iteration without hardware recalibration. Tier 1 suppliers in Germany and Japan are adopting these platforms for daily regression testing of navigation firmware. This expansion is compressing the traditional hardware refresh cycle and forcing incumbent vendors to unbundle signal generation hardware from scenario authoring tools.
ETSI EN 303 413 signal fidelity requirements are tightening calibration traceability standards for European automotive homologation, decoupling low-cost imports from certified supply chains. The directive mandates documented uncertainty budgets for synthesized pseudorange errors. Automotive OEMs in Germany, France, and Italy are responding by consolidating procurement around vendors with accredited European calibration networks.
Buyer concentration among autonomous vehicle developers is fragmenting traditional simulator procurement into modular component purchases. Tier 1 navigation suppliers now acquire signal generation hardware separately from scenario libraries and validation software. This unbundling is most visible in California and Bavaria, where specialized software vendors are capturing margin previously retained by integrated hardware providers.
GNSS Simulators Market Segmentation
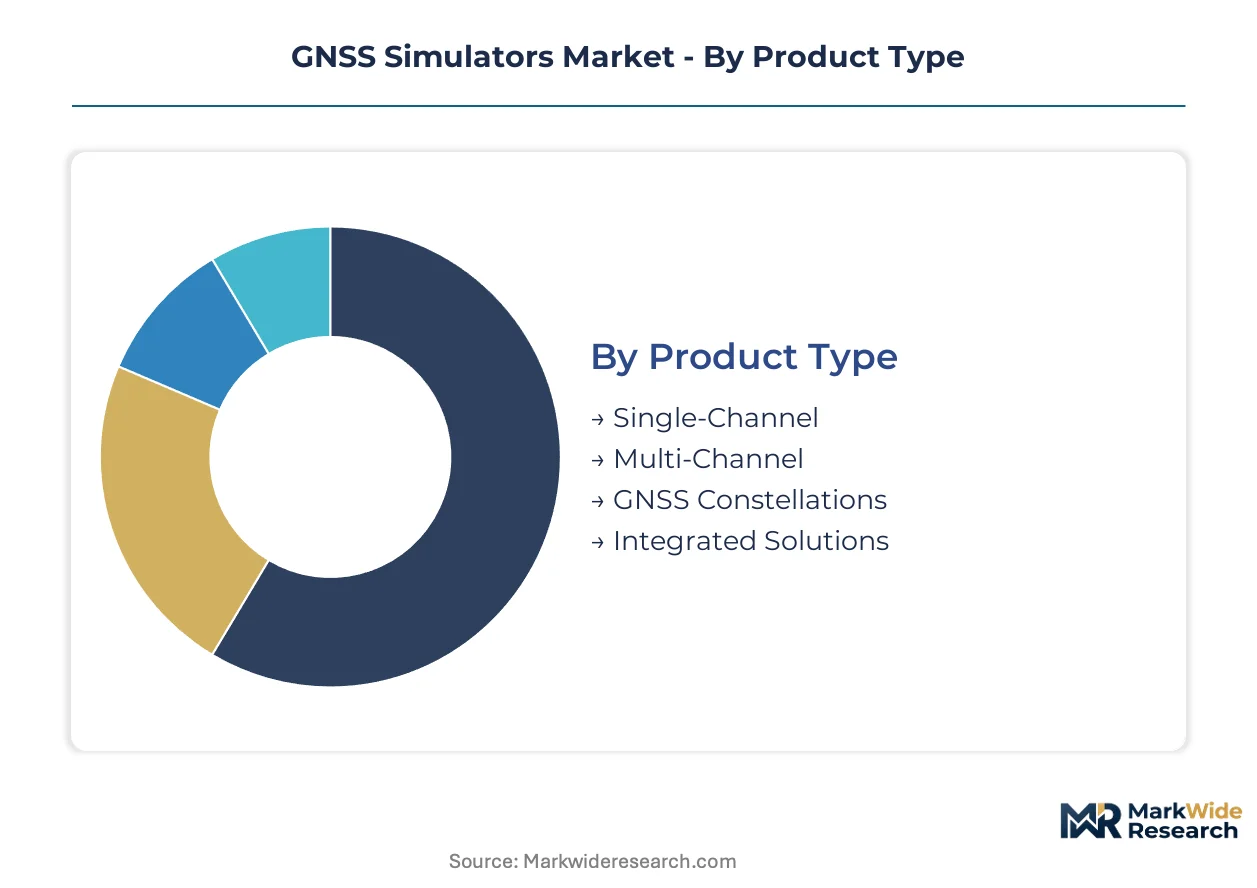
GNSS simulator procurement patterns diverge sharply across hardware generations and software maturity levels. Automotive OEMs and defense contractors operate on fundamentally different replacement timelines, creating tiered demand structures that vendors must navigate simultaneously.
Product Type:
Upgrade cycles compress as receiver architectures evolve from single-constellation to multi-frequency designs.
- Multi-Channel:Architectures supporting 64+ simultaneous signal paths dominate aerospace and autonomous vehicle validation. German automotive clusters around Munich and Stuttgart concentrate procurement of 128-channel systems for Level 3+ homologation under KBA mandates.
- Integrated Solutions:Bundled hardware-software platforms embed scenario libraries and automated test sequences. European defense programs favor these configurations for NATO interoperability certification, accepting premium pricing to reduce integration overhead.
- Single-Channel:Entry-level units serve educational markets and basic receiver firmware debugging.
- GNSS Constellations:Constellation-specific generators address legacy GPS-only equipment refresh in budget-constrained applications.
Multi-Channel sits at the top of the volume ranking, with Integrated Solutions climbing the fastest.
End User:
Customer procurement authority determines margin capture and contract duration.
- Defense:National programs in the United States, Germany, and Japan mandate hardware-in-the-loop validation for weapon system integration. FCC Part 15 and ETSI EN 303 413 compliance requirements lock procurement to accredited vendors with established calibration networks.
- Aerospace:Commercial aircraft and UAV manufacturers validate multi-constellation receivers against FAA and EASA certification baselines. Boeing and Airbus supplier ecosystems drive standardization around specific simulator interface protocols.
- Transportation:Automotive OEMs and Tier 1 suppliers adopt software-defined platforms for daily regression testing.
- Research Institutions:Universities and national laboratories pilot cloud-based Monte Carlo methods for receiver fault analysis.
Defense commands the highest contract values, while Transportation expands most quickly.
Technology:
Software maturity determines scenario iteration speed and total cost of ownership.
- Software-Based:Pure software signal generation runs on commercial computing infrastructure, enabling rapid constellation geometry manipulation. Japanese Tier 1 suppliers deploy these platforms for navigation firmware regression testing, compressing development cycles from weeks to hours.
- Hardware-In-the-Loop:Physical RF signal generation remains mandatory for real-time kinematic and precise point positioning validation. Centimeter-level accuracy requirements in surveying and precision agriculture sustain demand despite higher capital expenditure.
- Real-Time Simulation:Deterministic latency control supports closed-loop testing of receiver tracking loops.
- Cloud-Based:Elastic compute models attract research institutions in the United Kingdom and Netherlands for large-scale fault mode analysis.
Hardware-In-the-Loop retains the largest installed base, with Software-Based gaining share fastest.
Application:
Workflow integration depth separates commodity purchases from strategic vendor relationships.
- Testing:Formal validation protocols for receiver certification against regulatory baselines. ETSI EN 303 413 signal fidelity requirements in Europe and FCC equipment authorization in the United States mandate documented uncertainty budgets.
- Development:Iterative scenario creation for navigation algorithm refinement. California and Bavaria-based autonomous vehicle developers unbundle signal generation hardware from scenario libraries, fragmenting traditional integrated procurement.
- Training:Operator familiarization for military and commercial aviation applications.
- Integration:System-level validation of GNSS within broader navigation sensor fusion architectures.
Testing generates the most recurring revenue, with Development showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
RF signal fidelity engineering talent concentrates in southern Germany, where automotive and aerospace validation clusters generate sustained procurement of high-channel-count systems. Calibration accreditation networks in France and the United Kingdom anchor European supply chains. Japanese precision hardware manufacturers and United States defense contractors complete the tripolar demand structure.
Germany
KBA mandates for Level 3+ autonomous vehicle certification drive multi-constellation simulator procurement by BMW, Mercedes-Benz, and Continental. ETSI EN 303 413 traceability requirements lock automotive OEMs into accredited European calibration networks. Munich and Stuttgart testing clusters concentrate 128-channel system deployments for daily regression testing of navigation firmware.
United States
FCC Part 15 equipment authorization rules and FAA certification baselines sustain defense and commercial aerospace demand. Boeing and Lockheed Martin supplier ecosystems standardize around specific hardware-in-the-loop interface protocols. California autonomous vehicle developers fragment traditional procurement by unbundling signal generation hardware from scenario software libraries.
Japan
METI-funded positioning technology programs support Tier 1 suppliers adopting software-defined platforms for rapid constellation geometry manipulation. JIS standards alignment with ETSI frameworks enables dual-market product certification. Tokyo and Nagoya automotive R&D facilities compress development cycles from weeks to hours through daily firmware regression testing.
United Kingdom
Research institutions in Cambridge and Oxford pilot cloud-based Monte Carlo methods for large-scale receiver fault mode analysis. UK Space Agency funding for multi-constellation receiver validation creates demand elasticity outside traditional defense procurement. London-based autonomous navigation startups unbundle hardware purchases from software scenario libraries.
France
ANSM regulatory alignment with ETSI standards supports Thales and Safran aerospace supplier validation requirements. CNES space programs generate specialized demand for Galileo constellation simulation. Toulouse and Paris aerospace clusters concentrate hardware-in-the-loop procurement for commercial aircraft receiver certification.
GNSS Simulators Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across hardware generation and software maturity tiers. Market structure concentrates around established vendors with multi-year calibration network investments that lock out new entrants from European defense and automotive supply chains. Three archetypes dominate: integrated hardware-software bundlers, signal generation hardware specialists, and software-defined platform disruptors. Strategic moves center on backward integration into RF front-end component supply and geographic expansion through accredited calibration facility establishment.
Within the integrated solutions tier, Spirent Communications and Rohde & Schwarz exemplify vendors sustaining premium positioning through ETSI-traceable calibration networks that competitors cannot replicate without years of accreditation investment. Hexagon AB occupies a distinct position bundling simulator hardware with native positioning software to create sticky integrated workflows for autonomous vehicle developers. These three anchors represent the competitive fault line between hardware-centric legacy architectures and software-defined alternatives reshaping procurement patterns in automotive validation.
| Leading Market Players |
|---|
| Spirent Communications |
| Rohde & Schwarz |
| Hexagon AB |
| Keysight Technologies |
| Orolia |
| VIAVI Solutions |
| CAST Navigation |
| Accord Software & Systems Private Limited |
| IFEN GmbH |
| Others |
Supply Flow & Price Mechanics
Automotive OEM procurement clusters in southern Germany anchor a bifurcated pricing model where accredited calibration networks command substantial premiums over unbundled hardware imports. Defense programs sustain long-term contract structures, while software-defined alternatives compress capital expenditure timelines for autonomous vehicle developers.
Pricing Analysis
Bundled hardware-software configurations retain premium positioning against unbundled component sourcing. Pricing stratifies across ETSI-traceable calibration tiers, volume procurement scales, and after-sales service bundling. Cost compression in entry-level channels intensifies as software-defined platforms displace fixed-function hardware. Tier 1 automotive suppliers exhibit highest price sensitivity, whereas NATO-aligned defense programs prioritize accreditation compliance over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with specialized RF front-end component suppliers concentrated in Japan and the United States. Signal generation hardware draws from precision oscillator foundries in Japan, FPGA fabricators in the United States, and specialized RF assembly facilities in Germany. Tariff exposure on semiconductor inputs creates margin volatility for European system integrators. Distribution runs through accredited calibration facilities in Germany, France, and the United Kingdom serving defense and automotive validation clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where ETSI accreditation investment costs in Europe diverge sharply from FCC program-waiver flexibility in the United States, creating dual-track product development burdens that favor vendors with regulatory affairs scale across both jurisdictions.
For Market Incumbents: Deepen backward integration into RF front-end component supply to insulate margins from semiconductor input volatility. Expand accredited calibration facility footprints in France and the United Kingdom to reinforce ETSI-traceable network moats against emerging multi-standard platform competitors. Software-defined platform entrants threaten premium positioning in automotive segments. For New Entrants and Emerging Players: Capture cloud-based Monte Carlo testing demand from research institutions in the United Kingdom and Netherlands where elastic compute models circumvent capital-intensive hardware procurement barriers. India's TEC certification expansion offers the most penetrable regulatory entry point for vendors with existing multi-standard platforms. Position around API flexibility and scenario orchestration tools rather than signal generation hardware. For Investors and Strategic Acquirers: Aerospace and defense conglomerates are the most active acquirer in this space, targeting software-defined platform specialists to complement legacy hardware portfolios. Long-term viability hinges on regulatory accreditation density rather than unit volume scale. Monitor India's TEC certification implementation timeline as an inflection indicator for geographic demand consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Accredited Calibration Network Expansion | ETSI-traceable facilities in Germany and France lock out unaccredited competitors from automotive supply chains. |
| Software-Defined Platform Development | API-first architectures enable rapid scenario iteration for BMW and Mercedes-Benz autonomous navigation teams. |
| Multi-Standard Regulatory Certification | Dual ETSI-FCC compliance reduces product portfolio fragmentation for vendors serving NATO defense programs. |
| Cloud-Based Monte Carlo Testing Pilot | Elastic compute models at Cambridge and Oxford research institutions validate receiver fault modes at scale. |
| RF Front-End Component Backward Integration | In-house oscillator and FPGA sourcing insulates margins from Japanese and United States supplier concentration. |
Methodological Framework
Multiple input streams — primary interviews with simulator procurement managers at automotive OEMs, RF engineering directors at Tier 1 suppliers, and calibration laboratory accreditation officers — were reconciled against secondary validation from ETSI framework documentation, FCC equipment authorization filings, and KBA homologation records. Bottom-up channel checks with signal generation hardware distributors anchored volume estimates, while top-down aerospace and defense budget allocations cross-validated value projections.
Data-stream reconciliation across hardware generation tiers, software maturity levels, and end-use verticals structured the analytical framework throughout the projection horizon. Segmentation dimensions modeled encompassed constellation support breadth, channel count architecture, deployment technology, and geographic regulatory cluster. CAGRs were derived from replacement cycle compression rates and procurement budget elasticity observed across German automotive clusters and United States defense programs.
Regulatory timeline delays, semiconductor input cost volatility, and autonomous vehicle certification standard revisions are the dominant revision risks to modeled outputs. Forecasts reflect assumptions about ETSI EN 303 413 enforcement consistency and TEC certification expansion pace. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Simulation and Training
Live Laser-Based Training and Simulation Platforms Market
Simulation and Training
UAV Flight Training and Simulation Market
Simulation and Training
Europe Flight Training and Simulation Market
Simulation and Training
Asia-Pacific Civil Aviation Simulators Market
Simulation and Training
Air Traffic Control Simulator and Training Market
Simulation and Training
Military Aerospace Simulation and Training Market
Simulation and Training
Asia-Pacific Ship Bridge Simulators Market
Simulation and Training
Military Simulation Virtual Training Market
Simulation and Training
Military Simulation Software Market
Simulation and Training
Simulators Market
Simulation and Training
Global Healthcare Games and Simulation Market
Simulation and Training
Flight Simulation Training Device Market
Simulation and Training
Global Ship Bridge Simulators Market
Simulation and Training
Military Simulation and Training Market
Simulation and Training
Civil Aviation Simulator Market
Simulation and Training
North America Ship Bridge Simulators Market