
 Flight Simulation Training Device Market | 2026-2036
Flight Simulation Training Device Market Size, Share, and Industry Trends Forecast 2026-2036
Flight Simulation Training Device Market Insights
EASA CS-FSTD certification is reorganizing competitive access across the Flight Simulation Training Device landscape. CAE Inc. leverages integrated training center networks spanning multiple continents. FlightSafety International sustains proprietary curriculum tied to manufacturer-specific type ratings. L3Harris Technologies anchors military simulation portfolios through defense procurement channels.
Flight Simulation Training Devices replicate aircraft cockpit environments with six-degree-of-freedom motion platforms, collimated visual displays exceeding 220-degree horizontal field of view, and real-time aerodynamic modeling accurate to flight test data. Full Flight Simulators command the highest qualification tiers and associated margin pools, while UAV Operator Training represents the fastest-expanding application segment as remotely piloted aircraft systems proliferate across civil and defense sectors.
FAA Part 60 and EASA CS-FSTD frameworks govern device qualification levels, directly determining market access for manufacturers seeking airline and training center contracts. China's CAAC certification requirements and NMPA oversight of aviation equipment imports add regulatory complexity for foreign suppliers. Stakeholders must monitor evolving Level D fidelity standards and emerging sovereign certification regimes as fleet diversification accelerates.
Market Dynamics
FAA Part 60 and EASA CS-FSTD qualification standards are tightening fidelity requirements for Level D full flight simulators, compressing certification timelines while elevating capital barriers for device manufacturers seeking airline contracts.
Growth Catalysts
- COMAC Fleet Expansion:China's indigenous narrowbody production is generating procurement demand for CAAC-certified training devices tailored to C919 and ARJ21 cockpits.
- UAV Operator Training Mandates:Civil aviation authorities across multiple jurisdictions are imposing simulator-based certification for remotely piloted aircraft systems pilots.
- EASA CS-FSTD Reorganization:The consolidated certification framework is streamlining cross-border qualification recognition, reducing redundant validation costs for multinational training center operators.
Market Restraints
- Motion Platform Input Costs:Hydraulic actuator systems and precision electric drive components face supply concentration in German and Japanese precision manufacturing clusters.
- Visual System Latency:Collimated display technology requires sub-20-millisecond image generation pipelines that strain real-time computing architectures.
- CAAC Import Oversight:China's NMPA equipment import protocols impose extended validation periods on foreign-sourced Level C and Level D devices.
Strategic Opportunities
- India Training Infrastructure:The country's DGCA is expanding approved training organization capacity, creating demand for FTD Level 5 and Level 6 devices at regional aviation hubs.
- XR Convergence:Mixed reality headsets combined with physical cockpit panels are enabling lower-cost intermediate qualification tiers between FTDs and full flight simulators.
- Military-Civil Crossover:Defense procurement channels for tactical aircrew training systems are opening secondary revenue streams for device manufacturers with dual-use certifications.
Industry Challenges
- Flight Test Data Access:Aerodynamic modeling fidelity depends on proprietary aircraft manufacturer datasets that simulator builders must license under restrictive terms.
- Software Configuration Control:FAA Part 60 continuing qualification requirements demand rigorous version management across visual, motion, and avionics software loads.
- Electrical System Integration:Next-generation aircraft with fly-by-wire architectures require simulator electrical load simulations that exceed legacy host computer throughput.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flight Simulation Training Device Market |
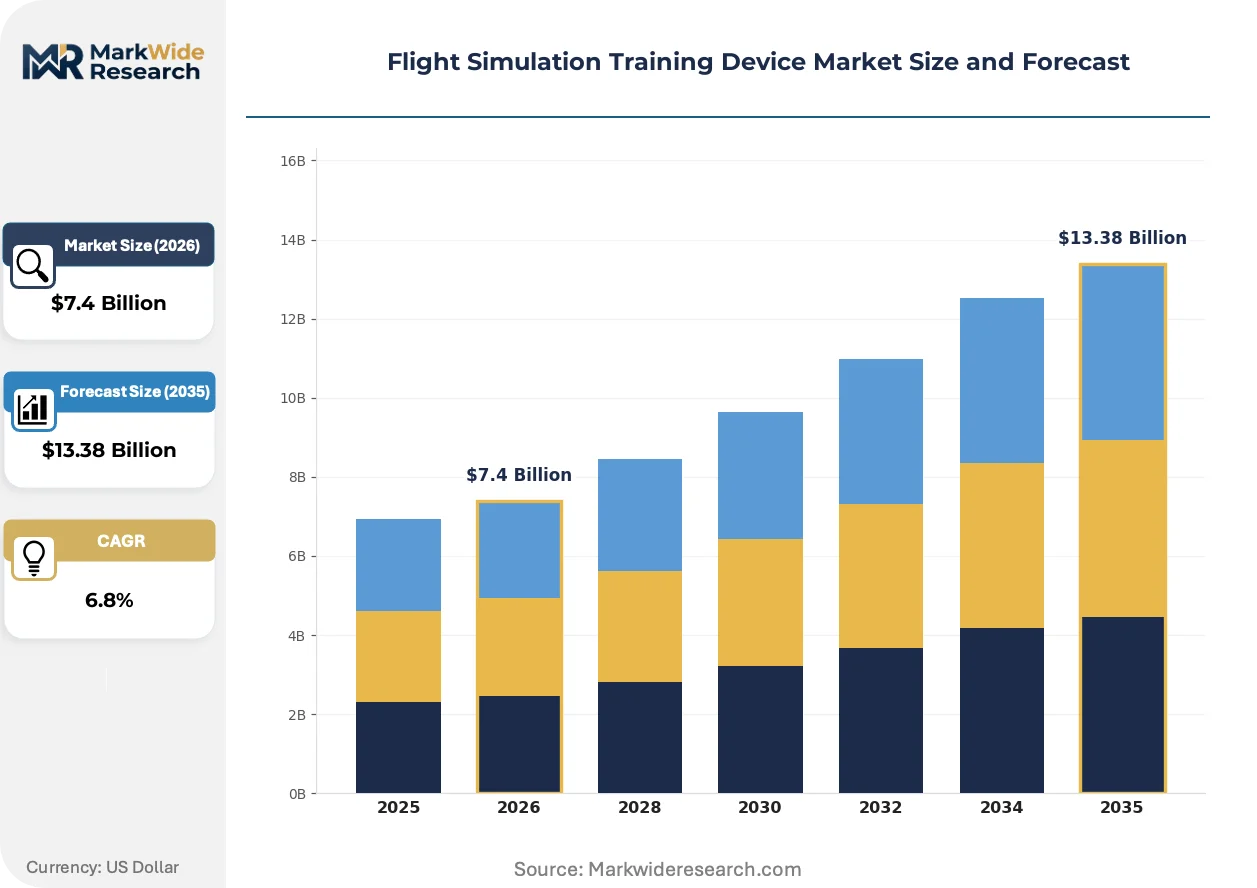
| Market Size in 2026 | $7.4 Billion |
| Market Size in 2035 | $13.38 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Full Flight Simulator, Flight Procedures Trainer, Fixed Base Simulator, Cockpit Procedures Trainer, Flight Training Device Technology: Visual Display System, Motion Platform, Audio System, Control Loading, Simulation Software Application: Military Pilot Training, Civil Aviation Training, UAV Operator Training, Corporate Pilot Training, Emergency Response Training End User: Airlines, Aviation Training Centers, Defense Forces, Commercial Operators, Private Flight Schools |
| Companies Covered | CAE Inc., FlightSafety International, L3Harris Technologies, Thales Group, TRU Simulation + Training, Collins Aerospace, Boeing, Rheinmetall AG, Lockheed Martin Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flight Simulation Training Device Market Trends and Innovations
Computational architectures and display technologies are restructuring how flight simulation devices achieve regulatory fidelity. Manufacturers are rethinking hardware-software boundaries to compress qualification cycles.
Image generation systems built on commercial gaming engines are decomposing the traditional visual database pipeline. Airlines in Southeast Asia are piloting these architectures for recurrent training modules. The shift is compressing visual system procurement costs while forcing legacy IG suppliers toward software licensing models.
EASA's CS-FSTD Amendment 2023 introduces updated objective testing protocols for stall model validation and ground effect modeling. Device manufacturers must recertify existing Level D inventories against revised handling quality matrices. European training centers are prioritizing retrofit contracts that address aerodynamic model gaps without full platform replacement.
Airlines are unbundling simulator capacity from long-term training center leases. Carriers in the Middle East are contracting block-hour arrangements with third-party providers rather than captive facility investments. The model concentrates demand at multi-fleet training hubs in Dubai and Singapore while marginalizing single-aircraft-type regional centers.
Flight Simulation Training Device Market Segmentation
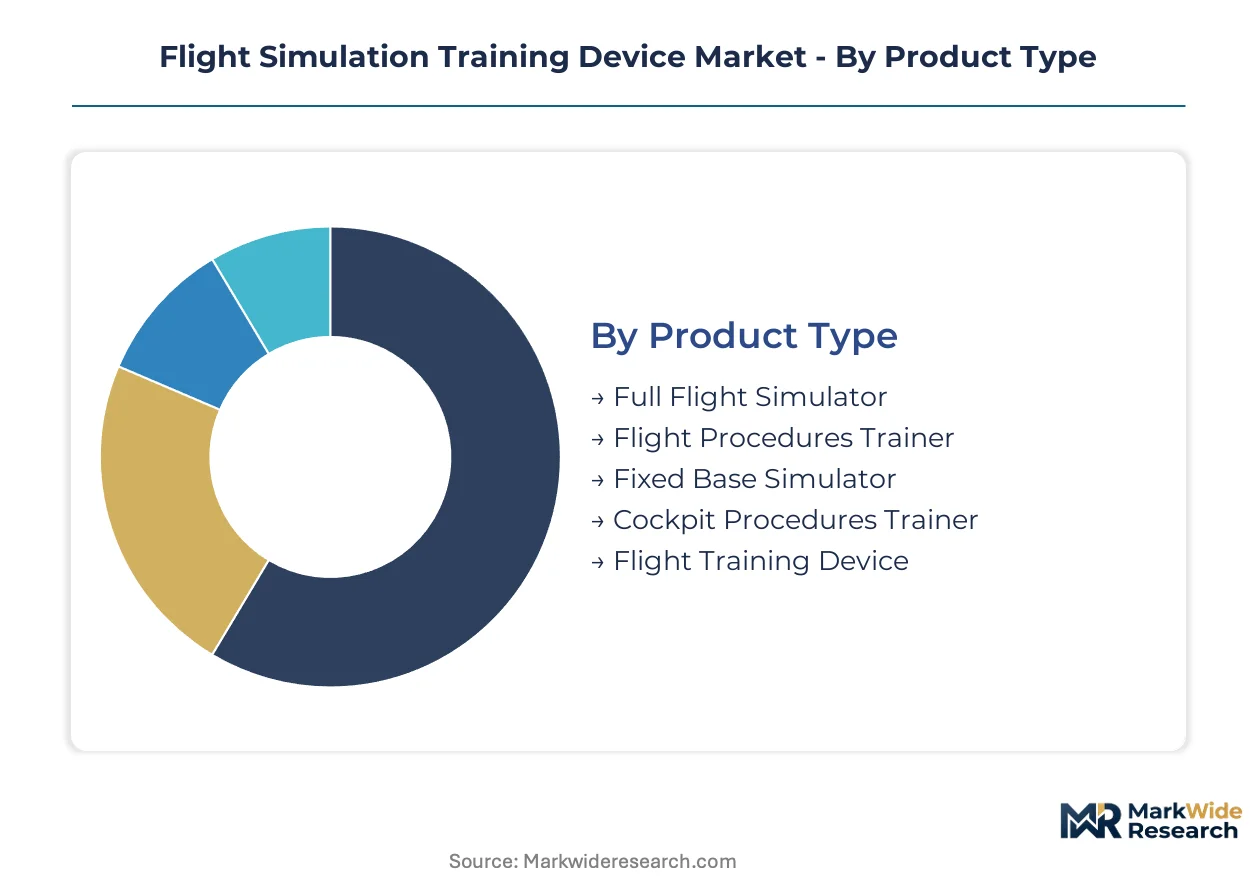
Segmentation in flight simulation training devices reflects how regulatory qualification tiers, hardware architectures, and end-user procurement models create distinct commercial pools. Each dimension carries different margin profiles, certification barriers, and technology refresh cycles that shape manufacturer positioning.
Product Type:
FAA Part 60 and EASA CS-FSTD qualification levels stratify device categories by motion fidelity, visual field of view, and aerodynamic model validation rigor.
- Full Flight Simulator:Six-degree-of-freedom hydraulic or electric motion platforms combine with 220-degree collimated visual systems and validated flight test data models. Airlines in China concentrate procurement here for CAAC Level D certification tied to COMAC fleet entry-into-service requirements.
- Flight Training Device:Fixed-base configurations without motion platforms address instrument procedure training and systems familiarization at lower capital intensity. Aviation training centers in India favor FTD Level 5 and Level 6 devices under DGCA expanding approved training organization mandates.
- Flight Procedures Trainer:Desktop or console-based units replicate avionics suites for procedural drills without external visual immersion.
- Fixed Base Simulator:Cockpit mockups with integrated visual channels but absent motion cueing occupy intermediate qualification tiers.
- Cockpit Procedures Trainer:Panel-specific devices isolate emergency checklist training and abnormal scenario rehearsal.
Established volume favors Full Flight Simulator; emerging adoption favors Flight Training Device.
Technology:
Cost tier differentiation separates premium motion and visual subsystems from commoditized audio and software layers.
- Visual Display System:Collimated dome or cross-cockpit displays demand sub-20-millisecond latency pipelines and proprietary image generation databases. German and Japanese precision optics manufacturers concentrate supply of high-fidelity projection components.
- Motion Platform:Electric drive systems displace legacy hydraulic actuators for reduced maintenance intervals and improved energy efficiency. Southeast Asian training centers specify electric platforms for new-build Level D installations.
- Audio System:Spatial sound reproduction engines replicate engine noise, weather, and cockpit alerts with directional accuracy.
- Control Loading:Force-feedback yokes and rudder pedals simulate aerodynamic resistance across flight envelopes.
- Simulation Software:Aerodynamic modeling, avionics emulation, and instructor operating station code constitute recurring license revenue streams.
Capital intensity concentrates in Visual Display System and Motion Platform; software margins expand fastest in Simulation Software.
Application:
Customer type and procurement channel divergence creates four distinct demand profiles with varying contract duration and specification rigor.
- UAV Operator Training:Remotely piloted aircraft system simulators replicate ground control station interfaces and beyond-visual-line-of-sight communication latency. Civil aviation authorities in multiple jurisdictions now mandate simulator-based certification for commercial drone pilots.
- Military Pilot Training:Tactical mission rehearsal, weapons systems integration, and multi-ship coordination drive specialized visual database and threat simulation requirements. Defense procurement channels in the United States and Saudi Arabia sustain long-term platform refresh programs.
- Civil Aviation Training:Airline recurrent training and type rating certification dominate device utilization rates at major training hubs.
- Corporate Pilot Training:Business aircraft operators contract block-hour arrangements at third-party facilities rather than captive simulator investments.
- Emergency Response Training:Cabin crew and maintenance personnel use lower-fidelity devices for procedural familiarization.
Defense budget stability anchors Military Pilot Training; regulatory mandate expansion is accelerating UAV Operator Training most steeply.
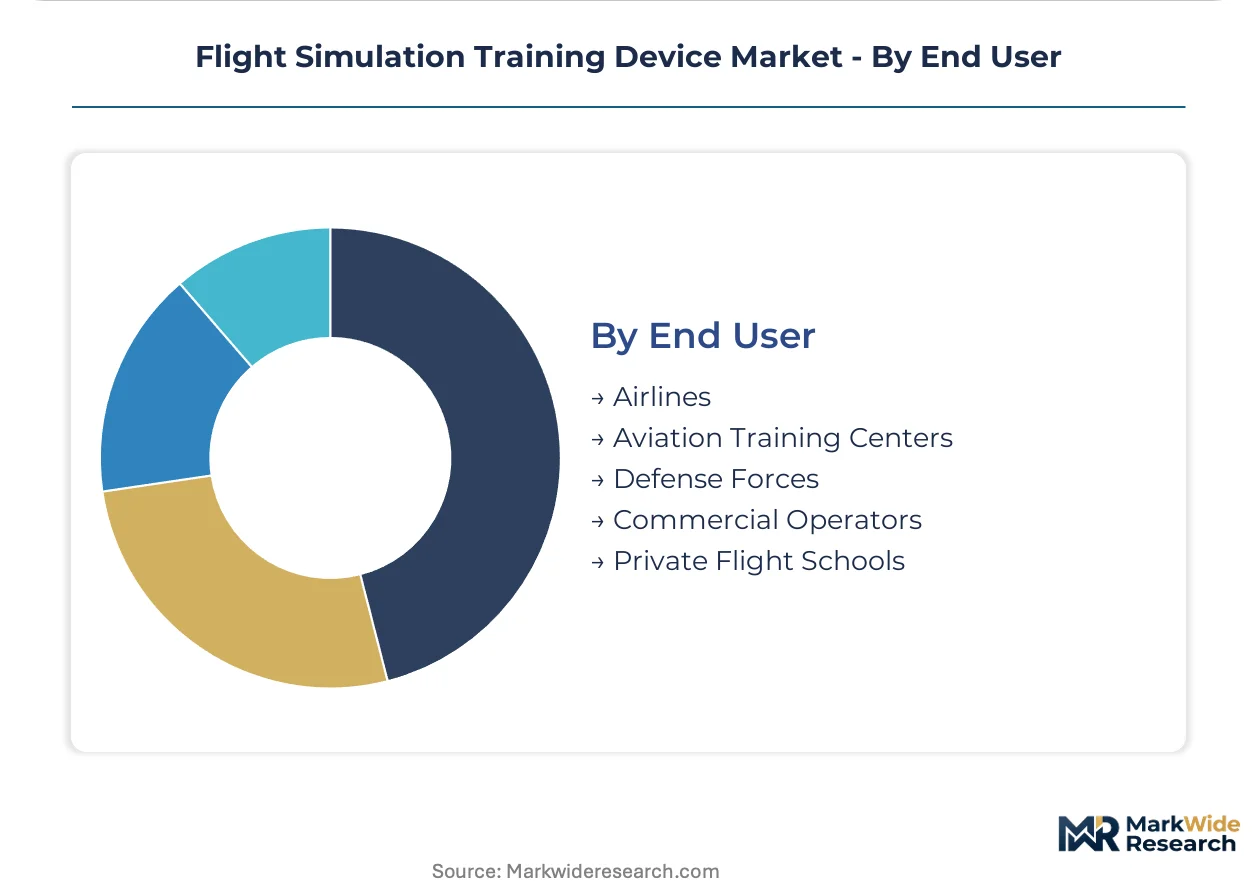
End User:
Procurement concentration and contract structure vary sharply between fleet-integrated operators and independent training service providers.
- Airlines:Major carriers in the Middle East unbundle simulator capacity from long-term training center leases, preferring block-hour contracts with multi-fleet hubs in Dubai and Singapore over captive facility ownership.
- Aviation Training Centers:Independent providers aggregate demand across multiple airline customers, requiring device configurations that accommodate rapid fleet-type reconfiguration.
- Defense Forces:Military services specify proprietary curriculum and security-cleared software loads with extended support horizons.
- Commercial Operators:Cargo and charter fleets prioritize cost-efficient recurrent training access over initial type rating infrastructure.
- Private Flight Schools:Part 61 and Part 141 certificated schools in the United States procure entry-level FTDs for instrument rating preparation.
Volume concentration sits with Airlines; outsourcing momentum favors Aviation Training Centers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FAA Part 60 qualification standards and CAAC fleet mandates are redirecting procurement flows toward certified training infrastructure in specific national markets. EASA CS-FSTD harmonization is compressing cross-border validation timelines for multinational operators. Sovereign certification regimes in Asia-Pacific and Middle East training hubs are elevating local content requirements.
United States
Defense procurement channels sustain platform refresh programs for tactical aircrew training systems at military installations across the country. FAA Part 60 governs device qualification levels for commercial airline contracts, with recurrent training demand concentrating at multi-fleet hubs in Dallas-Fort Worth and Atlanta. Boeing and Lockheed Martin anchor domestic manufacturing capacity through defense-integrated supply chains.
China
COMAC C919 and ARJ21 fleet entry-into-service is generating procurement demand for CAAC Level D certified devices tailored to indigenous cockpit configurations. NMPA import oversight extends validation periods on foreign-sourced equipment, favoring domestic assembly partnerships. Training center construction concentrates in Shanghai and Beijing where CAE and local joint ventures address sovereign certification requirements.
Germany
EASA CS-FSTD Amendment 2023 recertification mandates are driving retrofit contracts at European training centers for stall model validation upgrades. Precision manufacturing clusters in Bavaria and Baden-Württemberg concentrate supply of electric motion platform actuators and collimated optical components. Rheinmetall AG leverages defense procurement relationships across Bundeswehr facilities.
United Arab Emirates
Airlines in Dubai and Abu Dhabi are unbundling simulator capacity from long-term leases, preferring block-hour arrangements with third-party providers. Multi-fleet training hubs at Dubai South and Al Ain aggregate demand from Gulf carriers seeking type rating efficiency. EASA qualification recognition streamlines device certification for European-registered aircraft operated by UAE-based airlines.
Singapore
Aviation training centers at Seletar Aerospace Park specify rapid fleet-type reconfiguration capabilities to serve low-cost carriers across Southeast Asia. EASA CS-FSTD cross-border qualification recognition reduces redundant validation costs for multinational operators basing recurrent training programs there. Electric motion platform specifications dominate new-build Level D installations as regional carriers prioritize energy efficiency.
Flight Simulation Training Device Market Competitive Landscape
Listed leaders compete with private specialists across integrated training center networks and proprietary curriculum development. The vendor base stratifies between full-platform manufacturers and subsystem specialists supplying motion, visual, or software components. Two archetypes dominate: aerospace conglomerates with defense-civil crossover portfolios, and pure-play simulation houses with manufacturer-agnostic device configurations. Competitive moves concentrate on strategic partnerships for flight test data licensing and geographic expansion through training center joint ventures.
Among North American integrated providers, CAE Inc., FlightSafety International, and L3Harris Technologies exemplify contrasting market positions. CAE Inc. represents the global training center network archetype spanning multiple continents with consolidated qualification management. FlightSafety International occupies a position tied to manufacturer-specific type rating curricula and proprietary instructional systems. L3Harris Technologies anchors the defense-dominant portfolio archetype through military procurement channels with secondary civil aviation exposure.
| Leading Market Players |
|---|
| CAE Inc. |
| FlightSafety International |
| L3Harris Technologies |
| Thales Group |
| TRU Simulation + Training |
| Collins Aerospace |
| Boeing |
| Rheinmetall AG |
| Lockheed Martin Corporation |
| Others |
Pricing and Supply Chain Analysis
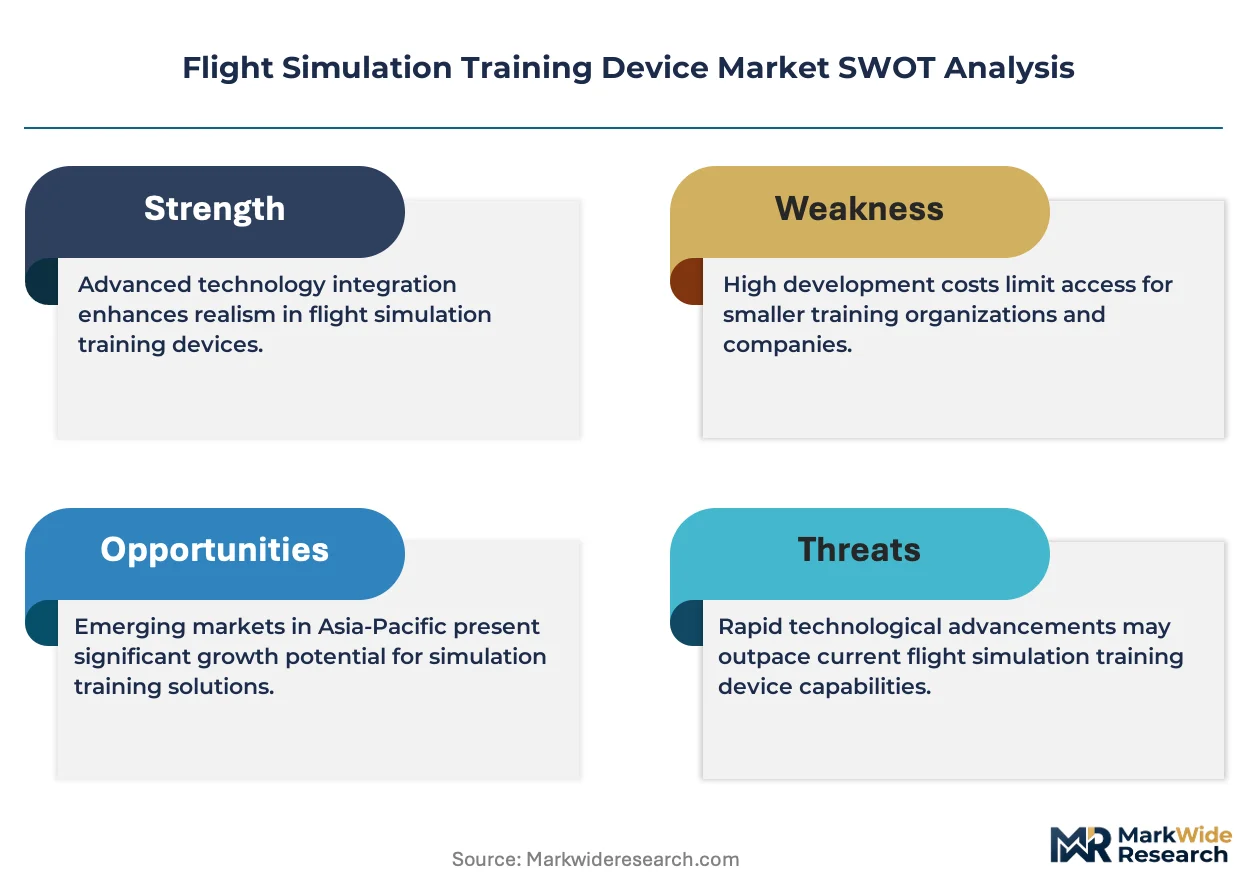
EASA CS-FSTD and FAA Part 60 qualification tiers gate both manufacturer market access and price differentiation across device categories simultaneously. Certification level creates parallel supply qualification barriers and pricing power stratification, with Level D full flight simulators commanding premium positioning against lower-tier fixed-base alternatives.
Pricing Analysis
Certification level creates the primary spread between device tiers, with CAAC Level D qualification for COMAC cockpits extracting substantial premiums over FTD Level 5 configurations. Three-tier pricing structure across Level D full flight simulators, intermediate fixed-base devices, and entry-level procedural trainers reflects fidelity-grade stratification. Cost compression in FTD segments is intensifying because gaming-engine visual architectures are commoditizing image generation pipelines. Regional aviation training centers in India exhibit highest price sensitivity, while Middle Eastern airlines contracting block-hour arrangements at multi-fleet hubs demonstrate lowest sensitivity to capital expenditure timing.
Supply Chain Analysis
Germany and Japan anchor precision manufacturing clusters for electric motion platform actuators and collimated optical projection components. Hydraulic actuator systems and high-fidelity display assemblies draw from Bavarian precision engineering and Japanese mechatronics specialists. Single-source vulnerability concentrates in sub-20-millisecond image generation chipsets sourced from Taiwanese semiconductor foundries. Distribution runs through defense procurement channels and civil aviation training center operators with divergent specification requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Device qualification fragmentation across FAA, EASA, and CAAC regimes creates specialist niches for modular platform architectures. UAV operator training mandates represent the most penetrable demand expansion vector for non-incumbent positioning.
For Market Incumbents: Consolidate flight test data licensing relationships with COMAC and established airframe manufacturers before indigenous Chinese simulator builders achieve vertical integration into aerodynamic modeling. Lock in long-term service contracts at Singapore and Dubai multi-fleet training hubs to preempt block-hour provider switching. Electric motion platform maintenance capabilities represent the priority capability anchor against emerging electric-drive specialists. For New Entrants and Emerging Players: CAAC fast-track certification partnerships with domestic Chinese joint venture structures open procurement access to C919 and ARJ21 training device contracts. Target India's DGCA expanding approved training organization capacity with FTD Level 6 offerings priced below European incumbent benchmarks. Go-to-market positioning as XR-convergence specialists for intermediate qualification tiers between legacy FTDs and full flight simulators bypasses capital intensity barriers. For Investors and Strategic Acquirers: EASA CS-FSTD Amendment 2023 recertification mandates reshape the acquisition landscape toward retrofit-capable software houses with aerodynamic model upgrade expertise. Long-term viability centers on dual-use defense-civil certification portfolios with recurring simulation software license revenue. Watch for CAAC indigenous content requirements tightening as signal for foreign joint venture restructuring necessity.| Strategic Initiative | Industry Significance |
|---|---|
| CAAC Joint Venture Formation | Local assembly partnerships bypass NMPA import validation delays for Level D devices. |
| Flight Test Data Licensing Agreement | Proprietary aerodynamic datasets from COMAC or Boeing lock in model fidelity differentiation. |
| XR Convergence Platform Development | Mixed reality architectures reduce capital barriers for intermediate qualification tier entry. |
| Electric Motion Platform Manufacturing Scale-Up | Energy-efficient actuators displace hydraulic systems at Southeast Asian training centers. |
| Multi-Fleet Training Hub Partnership | Block-hour contracts with Dubai or Singapore operators concentrate utilization across airline customers. |
Research Methodology
A spread of perspectives from simulator manufacturer engineering directors, airline training center procurement managers, civil aviation authority certification leads, and defense program officers converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against FAA Part 60 qualification databases, EASA CS-FSTD amendment documentation, CAAC equipment import protocols, and customs records for motion platform component trade flows. Bottom-up device shipment tallies triangulated against top-down training center capacity expansion announcements.
Segmentation dimensions modeled span qualification tier, motion platform technology, visual system architecture, application category, and end-user procurement structure across the analysis window. CAGRs derived from installed base replacement cycles, fleet expansion trajectories, and regulatory mandate implementation timelines. Forecast inputs incorporated COMAC delivery schedules, DGCA approved training organization licensing velocity, and civil UAV operator certification mandate adoption curves.
Underlying assumptions cover EASA-FAA qualification harmonization progress, CAAC indigenous content policy stability, and electric motion platform component supply continuity, with deviation risk concentrated in sovereign certification regime fragmentation and flight test data access restriction tightening. Recalibration cycles align with material shifts in regulatory amendment schedules and fleet entry-into-service milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Simulation and Training
Military Simulation Virtual Training Market
Simulation and Training
Pilot Training Market
Simulation and Training
Flight Simulator Market
Simulation and Training
Simulators Market
Simulation and Training
UAV Flight Training and Simulation Market
Simulation and Training
Global Military Airborne Simulation and Training Market
Simulation and Training
Air Traffic Control Simulation and Training Market
Simulation and Training
Global Ship Bridge Simulators Market
Simulation and Training
Asia-Pacific Civil Aviation Simulators Market
Simulation and Training
GNSS Simulators Market
Simulation and Training
Helicopter Simulator Market
Simulation and Training
Middle East and Africa Ship Bridge Simulators Market
Simulation and Training
Europe Flight Training and Simulation Market
Simulation and Training
Military Training Aircraft Market
Simulation and Training
RADAR Simulator Market
Simulation and Training
Military Vehicles and Aircraft Simulations Market