
 Ventilated Seats Market | 2026-2036
Ventilated Seats Market Size, Share, and Industry Trends Forecast 2026-2036
Ventilated Seats Market Analytics
Premium ventilated seating is decoupling from commodity fan-based systems in both engineering architecture and pricing architecture. Gentherm leverages its thermoelectric expertise to sustain technology leadership in active cooling modules. Magna International anchors North American supply through integrated seat structure manufacturing.
Ventilated seats employ forced-air distribution systems that draw cabin air through perforated upholstery and foam substrates, typically operating at flow rates between 10 and 25 cubic feet per minute to maintain surface temperatures below ambient levels. The primary commercial purpose is occupant thermal comfort management, reducing perspiration and extending perceived comfort duration during extended drives. Leather material configurations command the widest margin pools in OEM channels, while mesh variants represent the fastest-growing category in aftermarket retrofit applications. Cooling functionality dominates unit volumes, though massage-integrated systems are gaining share in luxury and sports car segments where feature bundling drives average selling prices upward.
NHTSA cabin safety protocols and Euro NCAP occupant comfort scoring frameworks are elevating baseline performance requirements for thermal management systems. EPA fuel economy standards indirectly shape demand by pressuring OEMs to adopt electrically efficient blower designs that minimize auxiliary power draw. Stakeholders must monitor evolving EU Green Deal material sustainability mandates and their downstream impact on foam and synthetic textile sourcing decisions across seating supply chains.
Market Dynamics
Thermal management electrification is compressing the engineering cycle for ventilated seating systems as automakers integrate climate control with battery thermal architecture. NHTSA cabin environment assessments and Euro NCAP occupant comfort scoring are forcing simultaneous compliance with safety and efficiency mandates.
Growth Catalysts
- EPA fuel economy standards:Pressure on auxiliary power draw is accelerating adoption of efficient blower designs in Detroit Three lineups. Electrically optimized fan modules reduce parasitic load on hybrid powertrains.
- Japan:METI vehicle electrification targets are expanding ventilated seat penetration across Toyota and Honda SUV platforms as thermal comfort becomes a competitive differentiator in humid climates.
- Perforated leather substrates:Premium upholstery material innovation is enabling higher airflow rates without durability degradation, satisfying luxury OEM specification tightening.
Market Restraints
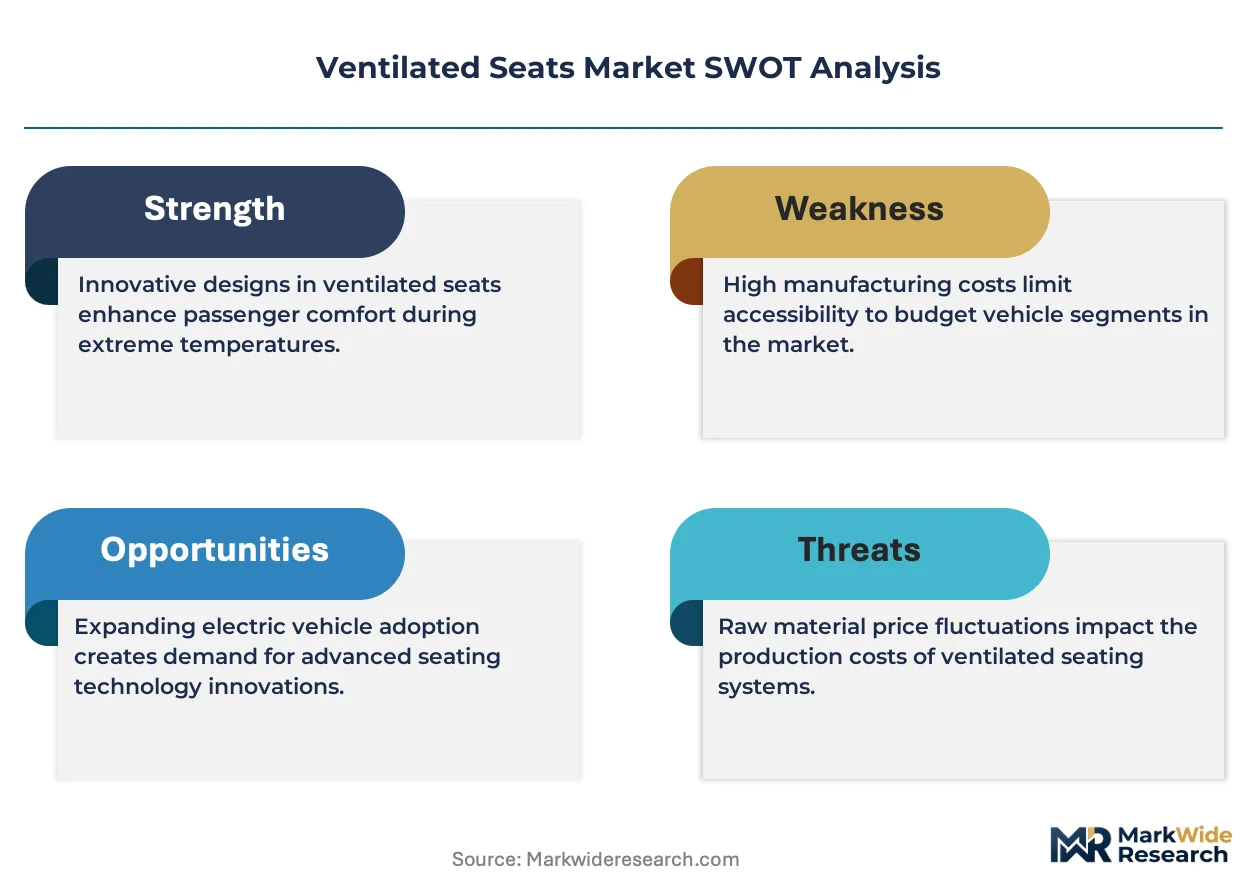
- Copper and rare-earth magnet costs:Blower motor input volatility compresses margin on mid-tier seat assemblies. Suppliers face pass-through limitations in annual OEM pricing negotiations.
- Concentrated foam substrate supply:Three German chemical producers control specialized open-cell polyurethane formulations for automotive seating, creating single-source vulnerability.
- EU Green Deal material mandates:Sustainability traceability requirements for synthetic textiles are extending qualification timelines by 8-14 months for new seat programs.
Strategic Opportunities
- India:PLI scheme automotive component incentives are attracting seat system localization for Maruti Suzuki and Hyundai Motor India expansion. Climate-controlled seating remains underpenetrated in sub-25 lakh vehicle segments.
- Massage-ventilation convergence:Integrated actuator and pneumatic systems are opening white space in sports car and ultra-luxury categories where feature bundling commands pricing premiums.
- Aftermarket retrofit channels:Mesh variant seat covers with clip-on fan modules are bypassing OEM distribution through e-commerce direct-to-consumer platforms in Texas and Florida.
Industry Challenges
- Thermoelectric module integration:Active cooling semiconductor assembly requires cleanroom-grade manufacturing capability scarce in tier-two seat suppliers. Gentherm and Japanese competitors hold captive process knowledge.
- Dual certification timelines:Simultaneous NHTSA FMVSS 302 flammability and Euro NCAP whiplash testing extends program validation by 4-6 months, compressing launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ventilated Seats Market |
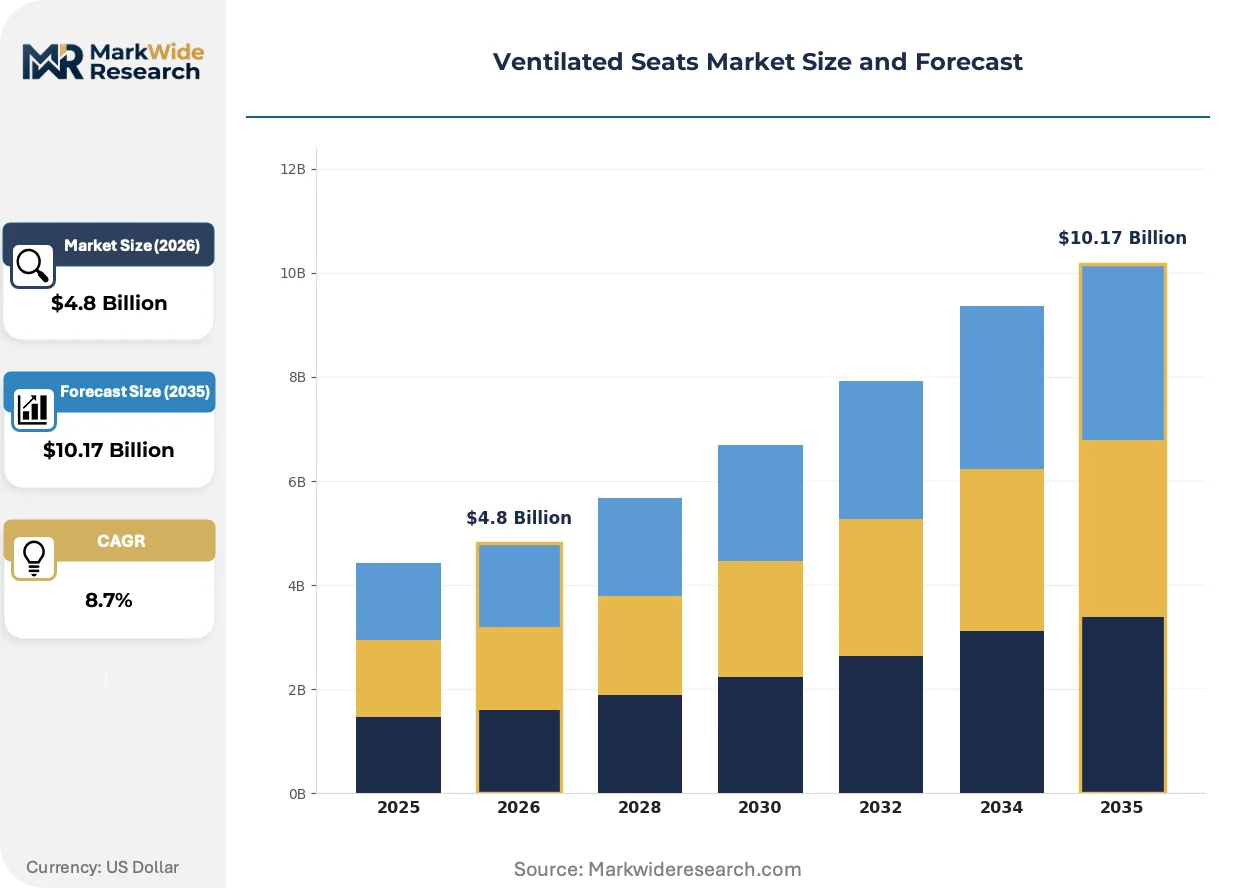
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Luxury Cars, SUVs, Commercial Vehicles, Sports Cars Feature: Cooling, Heating, Massage, Adjustable Lumbar Support Material: Leather, Fabric, Synthetic, Mesh End User: OEMs, Aftermarket Retailers, Fleet Operators, Vehicle Customization Companies |
| Companies Covered | Magna International, TS Tech, Adient, Hyundai Transys, Gentherm, Lear Corporation, Toyota Boshoku Corporation, Continental AG, Faurecia, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ventilated Seats Market Evolving Landscape
Climate-controlled seating is absorbing adjacent wellness and safety functions as automakers reposition interior environments as competitive battlegrounds. Technology convergence, regulatory layering, and procurement model evolution are simultaneously reshaping supplier relationships and product architecture.
Thermoelectric cooling modules are absorbing compressor-based refrigeration functions in premium electric vehicle platforms. BMW and Mercedes-Benz integrate these solid-state systems into seat structures to eliminate belt-driven HVAC components. This absorption is compressing the addressable market for conventional blower-based systems above the 75,000 dollar vehicle price point.
Euro NCAP cabin environment assessment protocols are mandating thermal comfort scoring alongside traditional crashworthiness metrics. OEMs must now document surface temperature uniformity and humidity management in type approval submissions. German and Swedish manufacturers are responding with multi-zone seat climate controls that segment cushion and backrest airflow independently.
Fleet procurement of climate-controlled seating is fragmenting across direct OEM, tier-one integrator, and aftermarket retrofit channels. Rental car operators in Arizona and Nevada are sourcing refurbished ventilated seat assemblies through specialized automotive recyclers rather than new equipment programs. This channel rotation is compressing residual value capture for original seat system manufacturers in high-heat geographies.
Ventilated Seats Market Segmentation
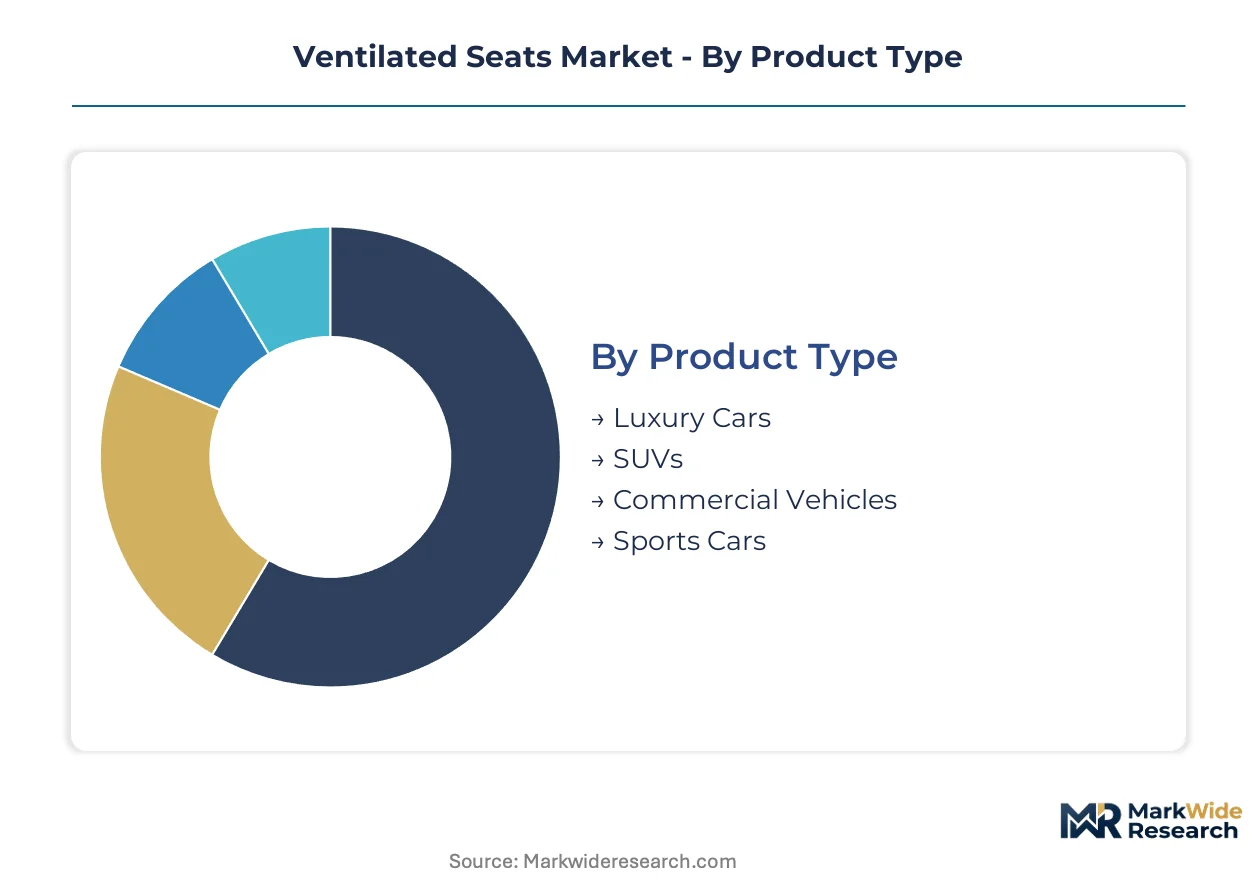
Ventilated seat segmentation reveals how thermal comfort technology diffuses across vehicle price tiers and use cases. Upgrade cycles vary dramatically between luxury OEM fitment and aftermarket retrofit channels, reshaping supplier priorities.
Product Type:
Replacement-cycle timing diverges sharply across vehicle categories, with fleet operators refreshing commercial seating every 4-6 years while luxury personal vehicles extend to 8-10 year cycles.
- Luxury Cars:German manufacturers specify multi-zone climate controls with independent cushion and backrest airflow zones. NHTSA cabin environment assessments and Euro NCAP thermal comfort scoring drive specification tightening in the United States and Germany.
- SUVs:Three-row configurations command the highest ventilated seat penetration rates as second and third-row occupants gain thermal comfort priority. Toyota and Honda platforms in Japan are expanding adoption across humid-climate SUV lineups under METI electrification targets.
- Commercial Vehicles:Long-haul truck operators in Texas and Florida prioritize driver retention through thermal comfort spec.
- Sports Cars:Limited production volumes constrain supplier scale economies despite premium pricing.
SUVs sit at the top of the volume ranking, with luxury cars climbing the fastest.
Feature:
Cost tier stratification separates base cooling modules from integrated wellness systems, with massage-ventilation bundles commanding 3-4x unit economics in ultra-luxury applications.
- Cooling:Forced-air distribution systems draw cabin air through perforated foam substrates at 10-25 cubic feet per minute. EPA fuel economy standards pressure Detroit Three lineups toward electrically efficient blower designs that minimize auxiliary power draw on hybrid powertrains.
- Massage:Pneumatic actuator integration with climate modules opens white space in sports car segments where feature bundling drives average selling prices upward. Gentherm thermoelectric expertise anchors technology leadership in active cooling modules for this convergence.
- Heating:Resistive element systems remain standard fitment in cold-climate markets.
- Adjustable Lumbar Support:Mechanical and pneumatic variants increasingly pair with climate functions.
Cooling dominates absolute unit shipments, with massage functionality gaining share fastest.
Material:
Supply concentration for specialized open-cell polyurethane formulations creates margin pressure, with three German chemical producers controlling critical foam substrate supply.
- Leather:Perforated premium upholstery enables higher airflow rates without durability degradation. Luxury OEM specification tightening in Germany and Japan sustains the widest margin pools in OEM channels.
- Mesh:Synthetic textile variants bypass OEM distribution through e-commerce direct-to-consumer platforms in Texas and Florida. EU Green Deal material sustainability mandates extend qualification timelines by 8-14 months for new seat programs using synthetic substrates.
- Fabric:Woven textile configurations serve economy and mid-tier vehicle segments.
- Synthetic:Polyurethane and vinyl alternatives address cost-sensitive fleet procurement.
Leather commands the highest value concentration, with mesh expanding most quickly in aftermarket channels.
End User:
Procurement fragmentation across direct OEM, tier-one integrator, and aftermarket channels compresses residual value capture for original manufacturers in high-heat geographies.
- OEMs:Integrated seat structure manufacturing anchors North American supply through tier-one suppliers. Simultaneous NHTSA FMVSS 302 flammability and Euro NCAP whiplash testing extends program validation by 4-6 months, compressing launch windows.
- Aftermarket Retailers:Clip-on fan modules with mesh seat covers target humid-climate vehicle owners in Texas and Florida through e-commerce platforms. Rental car operators in Arizona and Nevada source refurbished assemblies through specialized automotive recyclers.
- Fleet Operators:High-utilization commercial fleets in Arizona and Nevada prioritize thermal comfort for driver retention.
- Vehicle Customization Companies:Specialty upfitters serve enthusiast segments with bespoke climate-controlled seating.
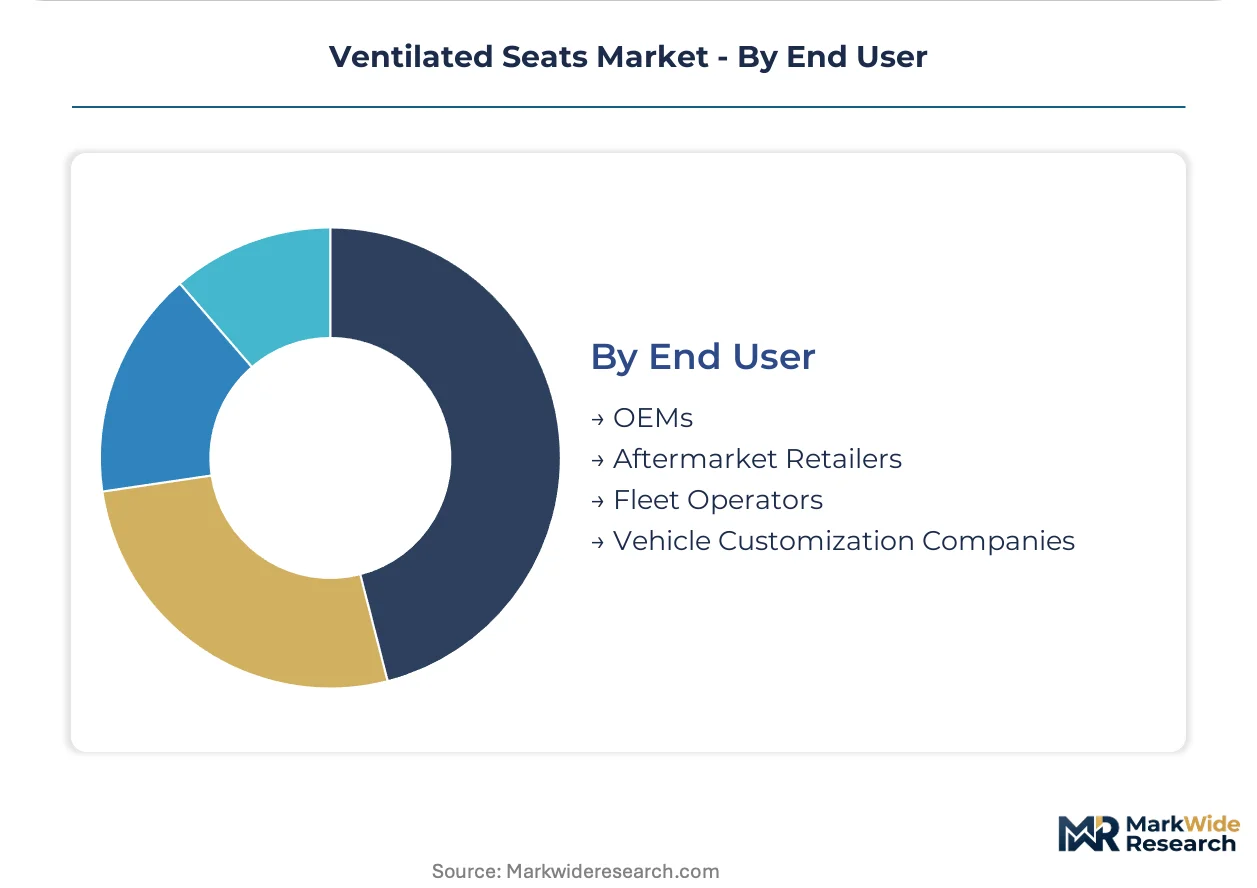
OEMs anchor volume leadership, with aftermarket retailers climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent pools in Stuttgart, Detroit, and Nagoya anchor ventilated seat development. These clusters concentrate thermoelectric specialists and HVAC integration engineers. Regulatory pressure from NHTSA and Euro NCAP is synchronizing design standards across these manufacturing hubs.
United States
Detroit Three OEMs specify climate-controlled seating as standard in premium SUVs and trucks. NHTSA cabin environment assessments tighten thermal comfort benchmarks for type approval. Michigan-based tier-one suppliers integrate seat structures with advanced blower modules for domestic production.
Germany
Luxury automakers in Stuttgart and Munich specify multi-zone climate controls with independent cushion and backrest airflow. Euro NCAP occupant comfort scoring mandates surface temperature uniformity documentation. Bavarian chemical producers control specialized open-cell polyurethane foam formulations for seating substrates.
Japan
Toyota and Honda expand ventilated seat penetration across humid-climate SUV platforms. METI vehicle electrification targets accelerate thermal comfort differentiation in domestic lineups. Nagoya-area suppliers anchor thermoelectric module assembly for premium electric vehicle programs.
India
Maruti Suzuki and Hyundai Motor India localize seat system production under PLI scheme automotive component incentives. BIS safety standards align with emerging thermal comfort specifications for domestic vehicles. Tamil Nadu manufacturing clusters attract tier-one seating suppliers for export-oriented assembly.
South Korea
Hyundai Motor Group integrates climate-controlled seating across Genesis luxury and electric vehicle portfolios. MFDS automotive component guidelines influence domestic safety qualification timelines. Seoul Capital Area suppliers specialize in mesh textile variants for cost-optimized seat programs.
Ventilated Seats Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the ventilated seat value chain. Integrated seat structure manufacturers anchor North American and European supply through captive foam and blower assembly. Three strategic archetypes dominate: thermoelectric specialists, full-system integrators, and component-focused suppliers. Competitive moves concentrate on backward integration into foam substrate production and strategic partnerships with luxury OEMs for multi-zone climate programs.
Among North American full-system integrators, Magna International and Lear Corporation exemplify scale-driven manufacturing archetypes. Gentherm occupies a position within the thermoelectric specialist tier, leveraging semiconductor cooling expertise for active climate modules. TS Tech represents the Japanese integrated supplier model, anchoring seating production for domestic OEM export programs. These three companies collectively illustrate how geographic clustering and technology specialization stratify competitive positioning across premium and mass-market vehicle segments.
| Leading Market Players |
|---|
| Magna International |
| TS Tech |
| Adient |
| Hyundai Transys |
| Gentherm |
| Lear Corporation |
| Toyota Boshoku Corporation |
| Continental AG |
| Faurecia |
| Others |
Value Network & Pricing Analysis
EPA fuel economy standards pressuring electrically efficient blower designs force tier-one suppliers toward higher-cost magnet materials and cleanroom-grade thermoelectric assembly, compressing margins on mid-tier seat programs and widening the premium-economy price gap.
Pricing Analysis
Bundled massage-ventilation systems versus unbundled cooling-only modules create a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on certification grade for NHTSA FMVSS 302 flammability compliance and Euro NCAP thermal comfort scoring, plus volume scale in OEM fleet contracts. Cost compression in mid-tier assemblies intensifies because copper and rare-earth magnet input volatility limits annual pricing pass-through. Fleet operators in Arizona and Nevada exhibit highest price sensitivity through refurbished assembly procurement, while German luxury OEMs show lowest sensitivity for multi-zone climate programs.
Supply Chain Analysis
Specialized open-cell polyurethane foam formulations rest on three German chemical producers controlling critical substrate supply. Blower motor rare-earth magnets draw from Chinese and Japanese magnet processors, while perforated leather finishing clusters in Italian and Mexican tanning operations. Single-source vulnerability in German foam chemistry creates qualification timeline risk as EU Green Deal sustainability mandates extend new program approvals. Distribution runs through tier-one integrator channels to OEM assembly plants, with aftermarket mesh variants bypassing this structure through direct-to-consumer e-commerce.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where PLI scheme incentives in India offset the 8-14 month qualification penalties from EU Green Deal material mandates, creating cost-advantaged sourcing for export-oriented seat assembly.
For Market Incumbents: Hedge thermoelectric module supply exposure by securing captive cleanroom capacity or partnership terms with Nagoya-area semiconductor assemblers before Gentherm and Japanese competitors tighten process knowledge control. Defend margin position in North American SUV platforms through backward integration into foam substrate production, countering the three-German-producer supply concentration that constrains tier-two competitors. For New Entrants and Emerging Players: Thermoelectric cooling convergence with compressor-based HVAC elimination offers a technology-first wedge into BMW and Mercedes-Benz electric vehicle programs above the 75,000 dollar vehicle price point. Target India's sub-25 lakh vehicle segments where climate-controlled seating remains underpenetrated despite Maruti Suzuki and Hyundai Motor India expansion, using PLI localization incentives as the go-to-market anchor. For Investors and Strategic Acquirers: Asymmetric upside sits with tier-two seat suppliers possessing foam formulation relationships but lacking thermoelectric assembly capability, as acquisition and capability grafting could reposition them for premium electric vehicle programs. Long-term viability over the 5-10 year window hinges on multi-zone climate control adoption rates in German and Japanese luxury lineups. Watch NHTSA thermal comfort guideline expansion as the inflection signal that would force mid-tier OEM specification upgrades and expand addressable market.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Foam Substrate Production | Counters single-source vulnerability from three German chemical producers controlling open-cell polyurethane supply. |
| Thermoelectric Module Assembly Partnership | Secures cleanroom-grade capability scarce outside Gentherm and Nagoya-area competitors for premium electric vehicle programs. |
| PLI Scheme Localization in India | Captures automotive component incentives for Maruti Suzuki and Hyundai Motor India seat system expansion. |
| Multi-Zone Climate Control Certification Investment | Meets Euro NCAP occupant comfort scoring mandates for surface temperature uniformity documentation in German OEM submissions. |
| Aftermarket Mesh Variant E-Commerce Launch | Bypasses OEM distribution through direct-to-consumer platforms targeting Texas and Florida humid-climate vehicle owners. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and dealership operations managers with secondary validation from vehicle production databases, IHS Markit registration data, SEC filings, and customs records. Bottom-up segment sizing and top-down market reconciliation triangulated volume and value estimates.
Segment-weighting approaches modeled vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster dimensions across the analysis window. CAGRs derived from production volume trajectories and content-per-vehicle scaling assumptions, incorporating EPA fuel economy standard compliance costs and NHTSA thermal comfort guideline evolution as automotive-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to rare-earth magnet price volatility, EU Green Deal material mandate expansion, and NHTSA cabin environment assessment protocol adoption. Forecasts reflect documented assumptions about OEM specification timing and tier-one supplier capacity expansion. A small set of named triggers—thermoelectric module cost curves, PLI scheme incentive renewal, and Euro NCAP thermal comfort scoring weighting—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
India Automotive Adaptive Lighting System Market
Automotive Interior & Exterior
Automotive Glove Box Market
Automotive Interior & Exterior
Automotive Liftgate Market
Automotive Interior & Exterior
Rear-View Mirror Market
Automotive Interior & Exterior
Automotive Interior Trims Market
Automotive Interior & Exterior
Automotive in-Cabin Air Quality Improvement Solutions Market
Automotive Interior & Exterior
Automotive Energy Absorption (EA) Pads Market
Automotive Interior & Exterior
Germany Automotive Adaptive Lighting System Market
Automotive Interior & Exterior
Automotive Door Impact Bars Market
Automotive Interior & Exterior
Reflective Air Bags Market
Automotive Interior & Exterior
Zero Gravity Seat Market
Automotive Interior & Exterior
Automotive Front Windshield Market
Automotive Interior & Exterior
Automotive Flock Market
Automotive Interior & Exterior
Global Automotive Intelligent Seats Market
Automotive Interior & Exterior
Automotive Intelligent Lighting System Market
Automotive Interior & Exterior
Automotive Smart Seating Systems Market