
 Windscreen Washer System Market | 2026-2036
Windscreen Washer System Market Size, Share, and Industry Trends Forecast 2026-2036
Windscreen Washer System Market Insights
Fleet operators are redrawing procurement priorities for windscreen washer systems as automotive OEMs shift specifications toward integrated sensor-cleaning modules. Robert Bosch GmbH leverages its electromechanical pump portfolio to anchor supply relationships with European premium brands. Continental AG sustains R&D intensity in heated nozzle technologies that clear ice without driver intervention. Valeo competes through geographic dominance in Asian assembly plant proximity, reducing logistics costs for just-in-sequence delivery.
A windscreen washer system comprises fluid reservoirs, delivery pumps, tubing, and spray nozzles engineered to maintain optical clarity on vehicle glazing surfaces, typically operating at fluid pressures between 40 and 80 psi depending on nozzle configuration and spray pattern requirements. The assembly serves critical safety functions by removing debris, precipitation, and road film from windscreens under varying speed and temperature conditions. Electric pump configurations lead unit shipments across passenger vehicle applications, while ultrasonic nozzle technologies represent the fastest-growing segment as OEMs integrate camera and lidar cleaning functions into advanced driver-assistance architectures. Aftermarket Suppliers capture margin pools through proprietary fluid formulations and retrofit heated reservoir kits for cold-climate operators.
NHTSA visibility standards in the United States, ECE R43 glazing regulations in Europe, and China's GB standards for motor vehicle safety equipment collectively shape product certification requirements and market access conditions for washer system manufacturers. EMA and EPA frameworks increasingly influence fluid chemistry restrictions, limiting volatile organic compound content in concentrated washer solutions. Stakeholders must monitor regulatory divergence between jurisdictions to determine whether platform standardization or regional customization offers superior capital efficiency for production footprints.
Market Dynamics
Fleet operators and automotive OEMs are redrawing procurement priorities as sensor-cleaning integration becomes mandatory for advanced driver-assistance architectures, compressing supplier margins while elevating technical certification barriers.
Growth Catalysts
- NHTSA visibility regulations:Mandated minimum fluid delivery rates for heavy-duty platforms in the United States force fleet-wide system upgrades, expanding addressable demand for high-capacity pump assemblies.
- Heated nozzle technology:German automotive OEMs now specify integrated heated nozzle assemblies for premium passenger vehicles, creating specification pull-through across adjacent vehicle classes.
- Ultrasonic cleaning modules:Camera and lidar sensor proliferation in advanced driver-assistance systems requires precision cleaning hardware, opening new content-per-vehicle opportunities.
Market Restraints
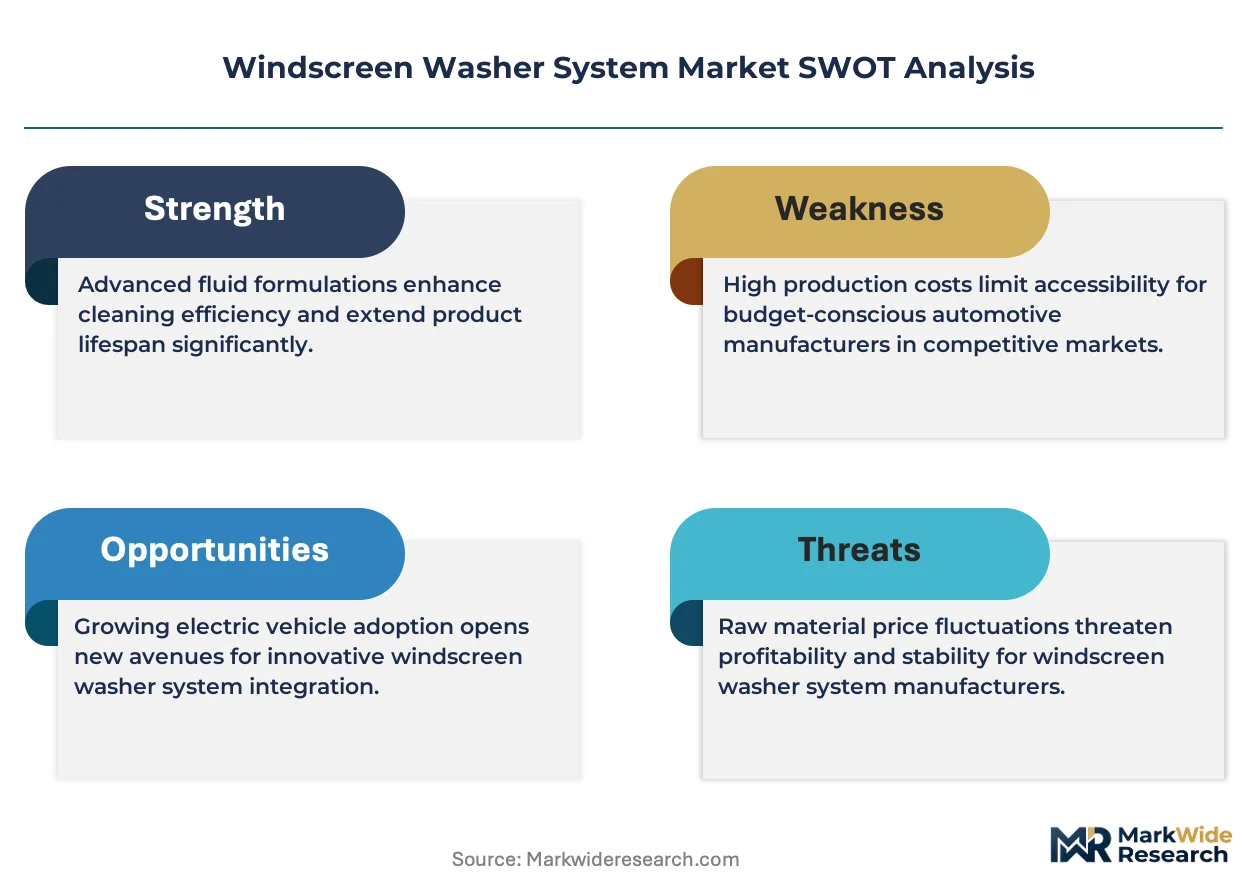
- Polymer resin cost volatility:Fluid reservoir and tubing production depends on engineered polymer feedstocks subject to petrochemical price swings, compressing molded component margins.
- European supply concentration:Electromechanical pump manufacturing clusters in Germany and Czech Republic create geographic risk exposure for just-in-sequence delivery commitments.
- REACH chemical restrictions:ECHA frameworks limit volatile organic compound content in concentrated washer solutions, forcing reformulation investments and regional SKU proliferation.
Strategic Opportunities
- Indian commercial vehicle fleet:Underpenetrated heavy-duty platform base and tightening BIS safety equipment standards create first-mover positioning for integrated washer system suppliers.
- Sensor-cleaning convergence:Ultrasonic nozzle technology merging with camera housing designs enables tier-one suppliers to capture adjacent content in ADAS architectures.
- Aftermarket retrofit channels:Cold-climate operators in Nordic countries and Canada seek heated reservoir kits through independent service networks, bypassing OEM captive supply.
Industry Challenges
- Multi-jurisdiction certification timelines:Simultaneous NHTSA, ECE R43, and GB standard compliance stretches engineering resources and delays platform launches.
- Legacy vehicle integration complexity:Retrofitting sensor-cleaning hardware onto existing electrical architectures requires custom harness engineering and dealer technician retraining.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Windscreen Washer System Market |
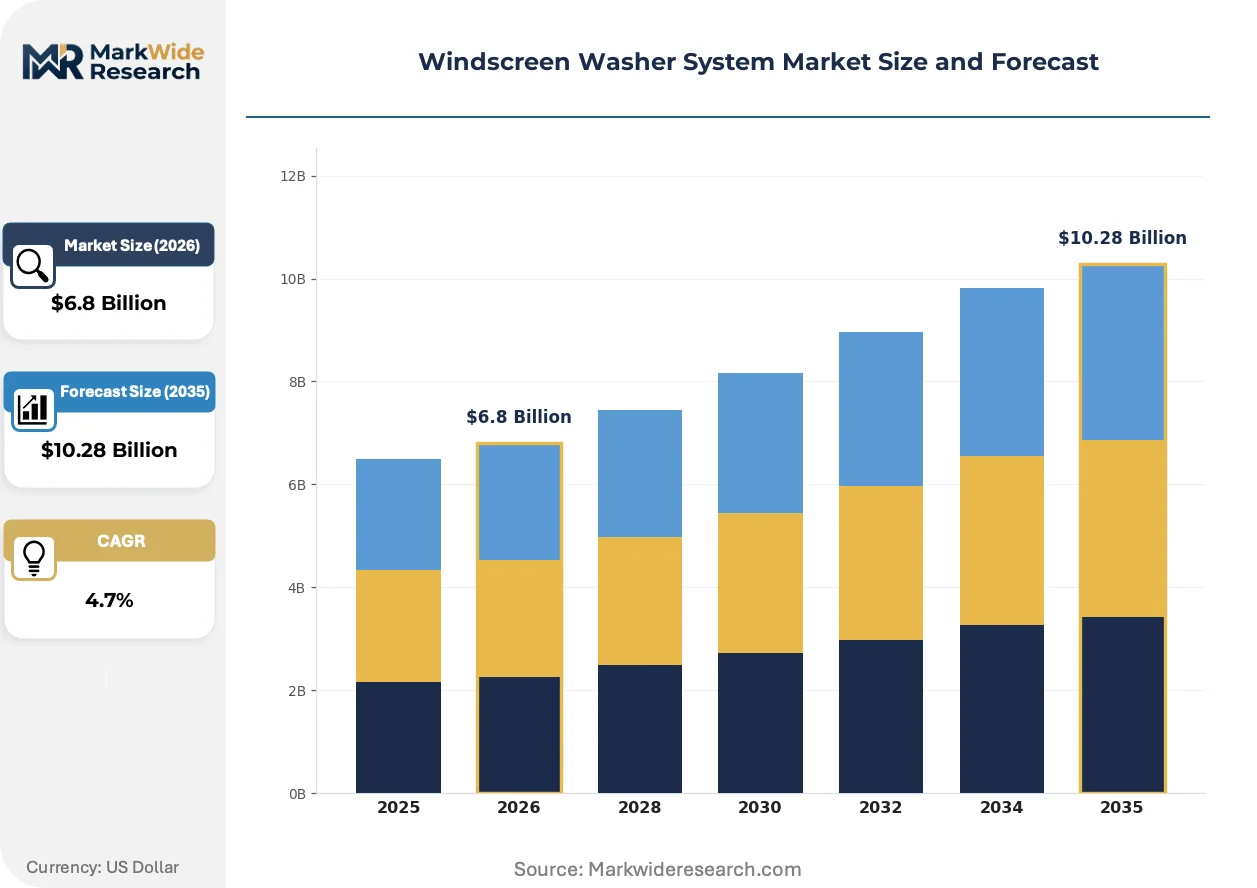
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Pumps, Manual Pumps, Fluid Reservoirs, Nozzles Technology: Electromechanical, Pneumatic, Hydraulic, Ultrasonic End User: Automotive OEMs, Aftermarket Suppliers, Service Centers, Fleet Operators Application: Passenger Vehicles, Commercial Vehicles, Heavy Machinery, Specialty Vehicles |
| Companies Covered | DENSO Corporation, Continental AG, HELLA GmbH & Co. KGaA, Robert Bosch GmbH, Valeo, Mitsuba Corp., 3M, dlhBOWLES, DOGA Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Windscreen Washer System Market Trends and Innovations
Electrification of auxiliary systems and sensor proliferation are compressing traditional component boundaries, forcing washer system suppliers to embed intelligence and thermal management into previously passive hardware.
Ultrasonic nozzle technology is displacing conventional pressure-based spray systems in premium vehicle architectures. Automotive OEMs specify piezoelectric actuators for camera and lidar cleaning functions where precision droplet control prevents sensor damage. This displacement is compressing the addressable market for standard solenoid-driven nozzles while elevating electronics content requirements for incumbent pump suppliers.
EMA chemical frameworks are tightening volatile organic compound limits in concentrated washer solutions, forcing fluid manufacturers to reformulate methanol-based concentrates. The industrial consequence is SKU fragmentation between jurisdictions and accelerated R&D spending on bio-based surfactant alternatives. European aftermarket distributors are responding by consolidating supplier relationships to manage compliance complexity.
Fleet procurement departments are unbundling after-sales service contracts from initial hardware purchases, shifting toward usage-based fluid supply agreements. This behavioral change disrupts traditional tier-one supplier margins in North American commercial vehicle channels. Long-haul operators in the United States now specify bulk fluid delivery programs tied to mileage intervals rather than packaged concentrate purchases.
Windscreen Washer System Market Segmentation
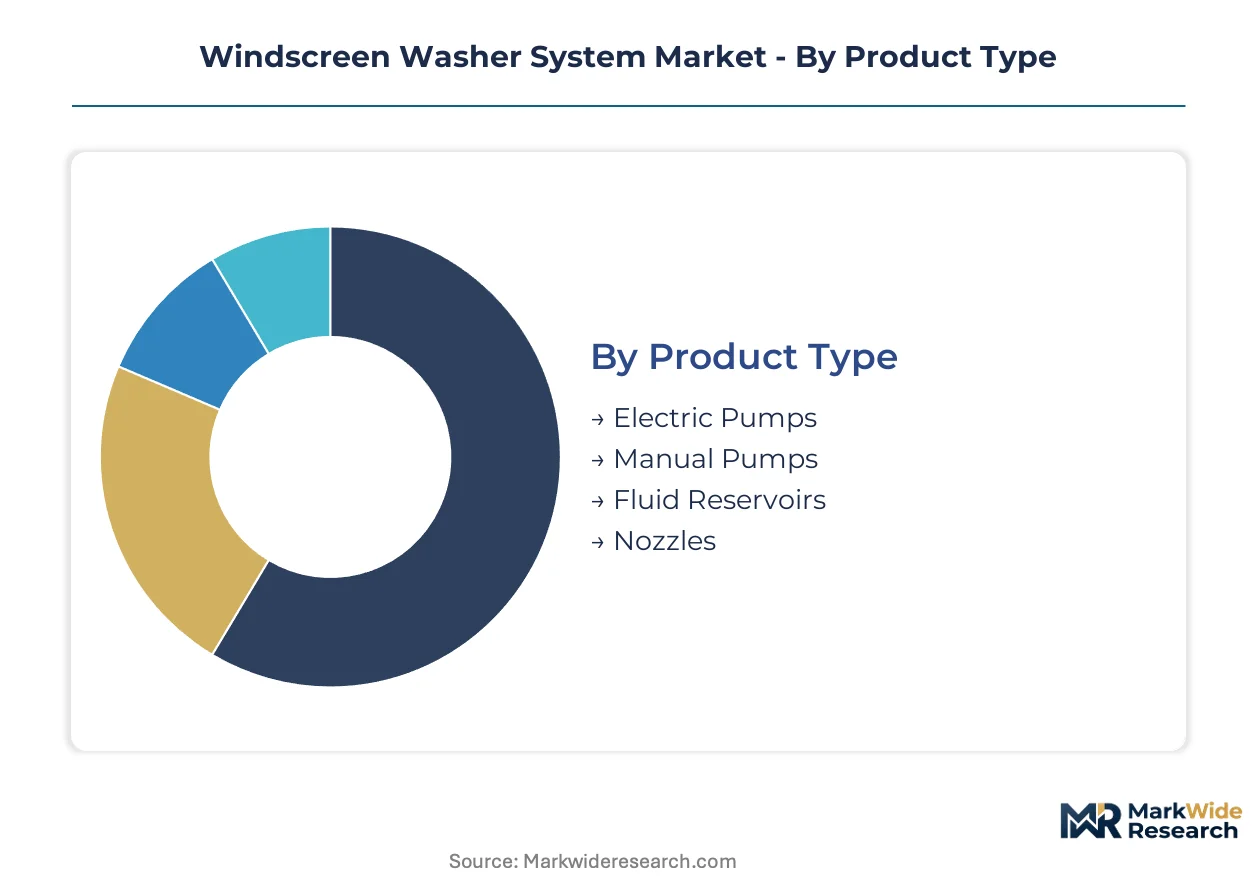
Windscreen washer system procurement diverges sharply across customer types and platform specifications, with sensor-cleaning integration forcing technology transitions that fragment traditional component categories. Component suppliers must align production footprints with distinct certification requirements and fluid chemistry standards governing each segment.
Product Type:
Electric pumps face intensifying substitution pressure from ultrasonic cleaning modules in premium architectures, while manual pump demand concentrates in cost-sensitive emerging market segments where electrical system complexity remains limited.
- Electric Pumps:Centrifugal and diaphragm pump configurations deliver pressurized fluid at 40-80 psi for standard spray nozzle operation. Passenger vehicle OEMs in Germany and the United States specify brushless DC motor variants for noise reduction and extended duty cycles. NHTSA visibility mandates for heavy-duty platforms are accelerating procurement of high-capacity electric pump assemblies by fleet operators.
- Fluid Reservoirs:Blow-molded polyethylene or polypropylene tanks with integrated level sensors dominate original equipment fitment. REACH chemical restrictions in Europe are forcing reservoir redesigns to accommodate reformulated washer fluids with reduced methanol content, increasing engineering validation costs for suppliers serving multiple jurisdictions.
- Manual Pumps:Hand-actuated piston mechanisms persist in aftermarket retrofit applications and legacy commercial vehicle platforms across India and Southeast Asia.
- Nozzles:Fixed and adjustable spray nozzles in acetal or nylon compounds handle standard windshield cleaning duties; heated variants command specification pull-through in Nordic markets.
Electric pumps anchor the volume base while ultrasonic-enabled nozzle systems gain share at the steepest rate.
Technology:
Technology selection tracks directly with platform electrification level and ADAS sensor density, creating tiered cost structures that separate commodity hardware from precision cleaning systems.
- Electromechanical:Solenoid-actuated valves and motor-driven pumps constitute the dominant installed base across mass-market passenger vehicles. Robert Bosch GmbH and Continental AG maintain manufacturing concentration in Germany and the Czech Republic, creating geographic risk for just-in-sequence delivery commitments to European assembly plants.
- Ultrasonic:Piezoelectric transducers generate high-frequency mechanical vibration for precision droplet control in camera and lidar cleaning applications. Premium OEMs specify ultrasonic modules where sensor damage prevention justifies elevated hardware costs.
- Pneumatic:Compressed air-driven systems serve heavy machinery and mining equipment where electrical system reliability cannot be guaranteed.
- Hydraulic:Pressure-multiplication circuits appear in specialty agricultural and construction vehicles with existing hydraulic infrastructure.
Electromechanical systems capture the largest installed base though ultrasonic technology is expanding most quickly in premium segments.
End User:
Procurement authority fragmentation between captive OEM supply and independent aftermarket channels creates divergent margin structures and technical certification pathways.
- Automotive OEMs:Tier-one suppliers negotiate multi-year supply agreements with integrated sensor-cleaning specifications. German premium brands now mandate heated nozzle assemblies as standard equipment, transmitting specification requirements through platform-sharing agreements to volume manufacturers.
- Fleet Operators:Commercial vehicle fleet managers in the United States are unbundling after-sales service contracts from initial hardware purchases, shifting toward usage-based fluid supply agreements tied to mileage intervals. NHTSA visibility regulations mandate minimum fluid delivery rates for heavy-duty platforms, forcing system upgrades across aging fleet assets.
- Aftermarket Suppliers:Independent distributors capture margin pools through proprietary fluid formulations and retrofit heated reservoir kits for cold-climate operators in Canada and Nordic countries.
- Service Centers:Dealer and independent repair facilities handle warranty replacements and collision repair volume, with sensor-cleaning hardware retrofits requiring custom harness engineering.
Automotive OEMs dominate value capture while fleet operators are driving the fastest procurement pattern transformation.
Application:
Platform duty cycles and operating environment severity determine hardware durability specifications and fluid consumption rates across vehicle categories.
- Passenger Vehicles:Light-duty platforms specify compact pump assemblies with integrated reservoirs for packaging efficiency. Asian assembly plant proximity advantages enable Valeo to reduce logistics costs for just-in-sequence delivery to regional OEMs.
- Commercial Vehicles:Heavy-duty trucks and buses require expanded reservoir capacity and redundant pump configurations for continuous operation. Indian commercial vehicle fleets present underpenetrated opportunity as BIS safety equipment standards tighten.
- Heavy Machinery:Construction and mining equipment demands corrosion-resistant materials and sealed electrical connections for contaminant-heavy operating environments.
- Specialty Vehicles:Emergency response and military platforms specify hardened systems with extended temperature range performance.
Passenger vehicles generate the highest unit volumes while commercial vehicles offer the strongest content-per-vehicle expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial fleet operators in the United States anchor procurement volumes for heavy-duty washer systems, while German automotive OEMs drive specification premiums through heated nozzle mandates. Asian assembly plants concentrate sensor-cleaning module demand as ADAS penetration accelerates across export platforms.
United States
Fleet operators at long-haul trucking companies are upgrading aging assets to meet NHTSA visibility regulations mandating minimum fluid delivery rates. The EPA influences washer fluid chemistry through volatile organic compound limits affecting concentrated methanol formulations. Manufacturing clusters in Michigan and Ohio supply electromechanical pump assemblies to domestic commercial vehicle builders.
Germany
Premium automotive OEMs specify integrated heated nozzle assemblies as standard equipment across passenger vehicle platforms. REACH chemical restrictions enforced by ECHA force reservoir redesigns accommodating reformulated washer fluids with reduced methanol content. Stuttgart and Munich anchor electromechanical pump manufacturing concentration serving European just-in-sequence delivery commitments.
China
Domestic OEMs integrate ultrasonic cleaning modules for camera and lidar sensors as GB standards for motor vehicle safety equipment tighten. MIIT guidelines shape auxiliary system electrification requirements affecting pump motor specifications. Yangtze River Delta assembly plants drive procurement volume for compact reservoir-pump integrated units.
India
Commercial vehicle fleet operators present underpenetrated demand as BIS safety equipment standards tighten for heavy-duty platforms. The PLI scheme incentivizes domestic manufacturing of automotive components including washer system hardware. Tamil Nadu and Maharashtra host emerging supplier clusters targeting cost-sensitive manual pump configurations.
Japan
Automotive OEMs specify precision ultrasonic nozzle systems for advanced driver-assistance architectures in premium export vehicles. METI frameworks guide chemical content restrictions affecting washer fluid concentrate formulations. Kanto region manufacturing concentration supports just-in-sequence delivery to domestic assembly plants.
Windscreen Washer System Market Competitive Landscape
Player mix skews toward diversified automotive component conglomerates with electromechanical system portfolios. The vendor base clusters around three strategic archetypes: integrated tier-one suppliers with full-system capabilities, specialized nozzle technology developers, and regional pump fabricators serving cost-sensitive markets. Dominant competitive moves include sensor-cleaning convergence through ultrasonic module development and geographic repositioning toward Asian assembly plant proximity.
Within the diversified conglomerate tier, Robert Bosch GmbH and Continental AG exemplify integrated supply positions anchoring European premium brand relationships. Valeo occupies a position representing Asian market proximity advantages through reduced logistics costs for just-in-sequence delivery. DENSO Corporation sits within the precision electromechanical specialist archetype, reflecting Japanese manufacturing concentration in compact auxiliary systems.
| Leading Market Players |
|---|
| DENSO Corporation |
| Continental AG |
| HELLA GmbH & Co. KGaA |
| Robert Bosch GmbH |
| Valeo |
| Mitsuba Corp. |
| 3M |
| dlhBOWLES |
| DOGA Inc. |
| Others |
Pricing and Supply Chain Analysis
NHTSA visibility regulations in the United States gate both supplier qualification and price differentiation simultaneously, forcing fleet operators to pay certification premiums for heavy-duty pump assemblies while compressing margins on standard passenger vehicle hardware. This regulatory bifurcation concentrates pricing power with electromechanical pump manufacturers holding multi-jurisdiction certifications.
Pricing Analysis
Cost-plus contracts with polymer resin indexation dominate procurement agreements between tier-one suppliers and automotive OEMs. Three-tier pricing structure across premium, standard, and economy levels separates ultrasonic sensor-cleaning modules from heated nozzle assemblies and basic fixed-nozzle configurations. Cost compression in standard electromechanical pumps is intensifying because REACH chemical restrictions force fluid reservoir redesigns. Fleet operators in North America exhibit the highest price sensitivity due to unbundled after-sales service contracts, while German premium brands remain least sensitive given platform-sharing specification mandates.
Supply Chain Analysis
Port congestion on Asia-Europe trade lanes elevates inbound logistics costs for just-in-sequence delivery commitments to German assembly plants. Electromechanical pump manufacturing concentrates in Germany, the Czech Republic, and China, drawing from engineered polymer feedstocks, piezoelectric ceramics, and brushless DC motor components. Single-source vulnerability in heated nozzle valve actuators creates supply chain risk exposure. Distribution runs through tier-one supplier direct-to-OEM channels with aftermarket fluid formulations bypassing captive supply via independent service networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized capability in ultrasonic cleaning module integration remains scarce relative to accelerating ADAS sensor proliferation, creating asymmetric returns for suppliers mastering piezoelectric precision engineering.
For Market Incumbents: Shield core pump assembly margins by securing backward integration into brushless DC motor production and acquiring regional certification assets for Indian BIS compliance. Ultrasonic nozzle substitution threatens traditional solenoid-driven hardware. Capacity addition in Tamil Nadu manufacturing clusters offers defensive geographic diversification against European supply concentration. For New Entrants and Emerging Players: GB standards fast-track certification for camera-cleaning modules unlocks white-space positioning in Chinese domestic OEM supply chains. Indian commercial vehicle fleets present the most penetrable segment given underpenetrated heavy-duty platform bases. A go-to-market angle anchored to usage-based fluid supply agreements bypasses entrenched tier-one supplier relationships. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mid-cap nozzle technology developers holding ADAS platform design-ins but lacking full-system integration capabilities. Long-term viability hinges on convergence toward intelligent cleaning architectures with thermal management functions. Acquisition targets should demonstrate embedded software competencies and sensor housing integration expertise. Watch for NHTSA rulemaking expansion to light-duty platforms as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Ultrasonic Module Development | Piezoelectric actuator integration captures camera-cleaning content in ADAS architectures. |
| Heated Nozzle Assembly Expansion | German OEM specification mandates transmit pull-through across adjacent vehicle classes. |
| Indian Manufacturing Footprint | PLI scheme incentives support cost-competitive manual pump production for commercial fleets. |
| Fluid Chemistry Reformulation | Bio-based surfactant R&D addresses REACH volatile organic compound restrictions. |
| Sensor-Cleaning Convergence | Ultrasonic nozzle merging with camera housing enables tier-one adjacent content capture. |
Research Methodology
A spread of perspectives from tier-one supplier procurement officers, OEM platform engineers, aftermarket distributors, and fleet operations managers converged on the working assumptions. Primary interviews combined with secondary validation from NHTSA regulatory filings, EPA chemical framework documents, vehicle production databases, and customs trade records. Bottom-up unit shipment estimates triangulated against top-down value projections.
Segmentation dimensions modeled span vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster across the analysis window. CAGRs derived from historical shipment trajectories adjusted for regulatory mandate timelines and sensor proliferation curves. Forecast inputs incorporate fluid consumption rates by platform duty cycle and heated nozzle specification penetration by climate zone.
Decision-makers should treat outputs as directional under stable polymer resin pricing and sustained NHTSA enforcement intensity; material deviation would warrant model refresh. Forecasts reflect assumptions of continued ADAS sensor density growth and REACH chemical restriction stability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Laser Headlight Market
Automotive Interior & Exterior
Automotive Convertible Top Market
Automotive Interior & Exterior
Global Smart Tailgate Market
Automotive Interior & Exterior
Automotive Interior Leather Market
Automotive Interior & Exterior
Automotive Door Seal Market
Automotive Interior & Exterior
Automotive Cabin Insulation Market
Automotive Interior & Exterior
Automotive Cowl Screen Market
Automotive Interior & Exterior
Glass for Electric Vehicle Glass Roof Market
Automotive Interior & Exterior
Automotive Door Handles Market
Automotive Interior & Exterior
China Automotive Seats Market
Automotive Interior & Exterior
Automotive Energy Absorption (EA) Pads Market
Automotive Interior & Exterior
Car Organizer Market
Automotive Interior & Exterior
Bonnet Lock Plate and Latch Market
Automotive Interior & Exterior
Automotive Multi-Layer Display Market
Automotive Interior & Exterior
Global Automotive Window Power Sunshade Market
Automotive Interior & Exterior
All Plastic Front End Module Market