
 Automotive Grab Handle Market | 2026-2036
Automotive Grab Handle Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Grab Handle Market Analysis
Aftermarket service revenue for grab handle replacement and refurbishment is reconfiguring margin pools away from pure component supply toward lifecycle service contracts. Grupo Antolin leverages its vertical integration into plastic injection molding to control cost structures across interior handle programs. Magna International anchors North American production through dedicated seating and interiors plants in Michigan and Ontario. Lear Corporation competes on platform modularity, supplying standardized grab handle architectures across multiple OEM vehicle programs.
An automotive grab handle is a mechanically fixed or retractable handhold installed on vehicle pillars, headliners, or door frames, typically engineered from glass-filled polypropylene or zinc-coated steel to withstand cyclic loads exceeding 500 Newtons, and designed primarily to stabilize occupants during acceleration, braking, and off-road maneuvers. Interior handles and assist handles lead volume demand as cabin ergonomics become a competitive differentiator in premium vehicle segments, while composite materials represent the fastest-growing material category as manufacturers pursue mass reduction targets without sacrificing structural integrity. Plastic formulations still occupy the largest share of unit economics due to their compatibility with high-speed injection molding and color-matching capabilities.
The US NHTSA Federal Motor Vehicle Safety Standards govern occupant protection and interior component retention, while China's SAMR enforces GB standards for automotive interior part durability, and the EU's REACH regulation restricts hazardous substances in polymer formulations used for cabin touchpoints. These frameworks collectively elevate testing and certification costs for new market entrants while reinforcing established suppliers with in-house compliance infrastructure. Stakeholders must monitor evolving material disclosure requirements and anticipate whether recycled content mandates will reshape raw material sourcing strategies before the next product platform cycles.
Market Dynamics
OEM procurement of integrated interior assist systems is accelerating as cabin ergonomics become a competitive differentiator in premium vehicle segments, forcing suppliers to expand from discrete component manufacturing toward full subsystem integration.
Growth Catalysts
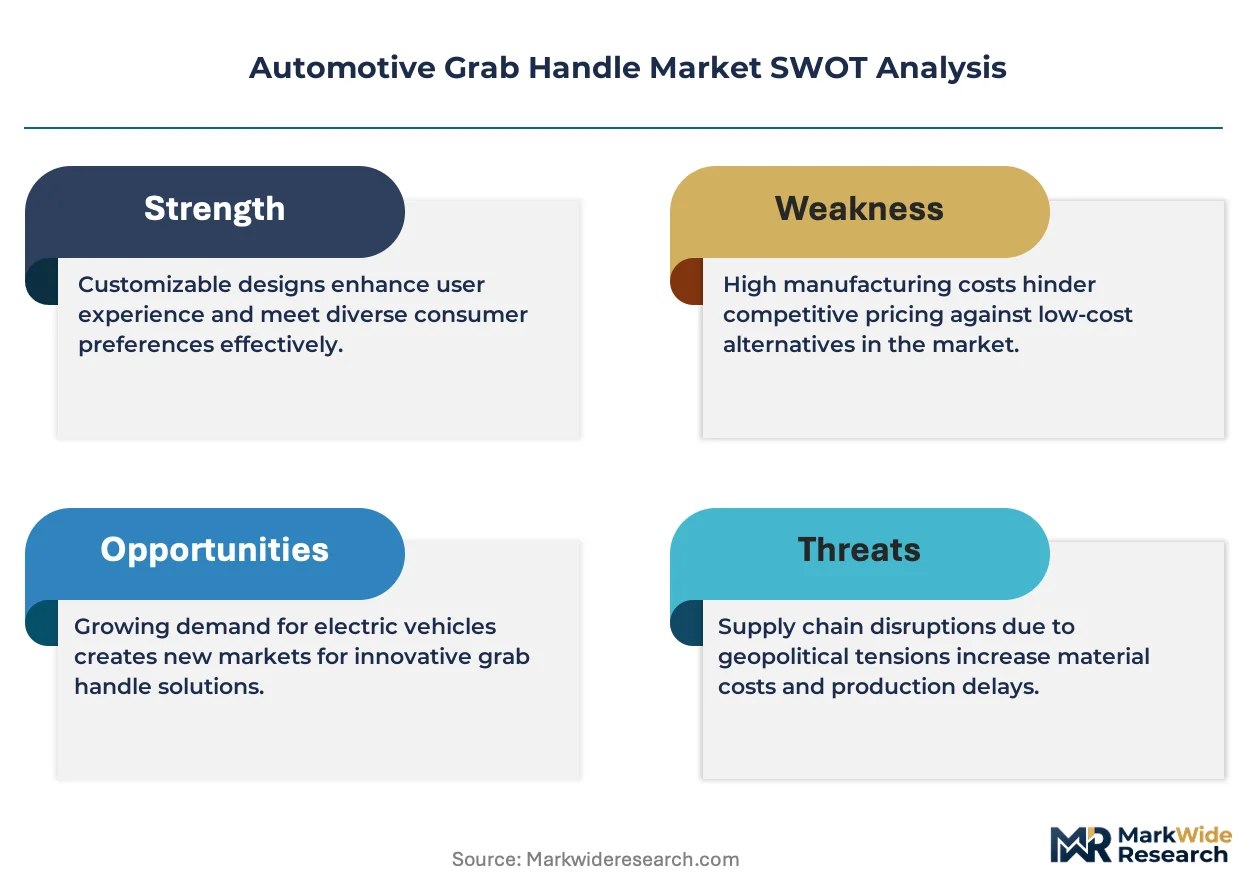
- GB Standards Compliance:China's tightening material and load-bearing requirements under SAMR enforcement are elevating quality benchmarks across the supply base, favoring suppliers with in-house testing infrastructure.
- Glass-Filled Polypropylene Adoption:Advanced plastic formulations compatible with high-speed injection molding are displacing metal alternatives in volume passenger car programs, reducing per-unit mass while maintaining cyclic load tolerance.
- Stuttgart-Munich Manufacturing Corridor:Concentrated premium passenger car production in southern Germany is generating sustained demand for ergonomic interior hardware with customized finish specifications.
Market Restraints
- REACH Substance Restrictions:The EU's hazardous substance limitations in polymer formulations are increasing raw material qualification timelines and narrowing the approved supplier base for cabin touchpoint materials.
- Zinc-Coated Steel Volatility:Input cost fluctuations for metal substrate variants are compressing margins on hybrid material handles and discouraging long-term fixed-price contracts.
- Supplier Concentration in Injection Molding:Captive plastic processing capabilities at tier-one interior specialists are creating barriers for independent component manufacturers seeking direct OEM relationships.
Strategic Opportunities
- Recycled Content Mandates:Anticipated EU regulatory requirements for post-consumer material incorporation in automotive interiors are positioning early movers with validated recycling partnerships for preferred supplier status.
- Lifecycle Service Contracts:Aftermarket refurbishment and replacement programs are opening recurring revenue streams beyond initial equipment supply, particularly in commercial vehicle fleets with extended duty cycles.
- Composite Material Convergence:Hybrid fiber-reinforced formulations combining thermoplastic matrices with natural fiber fillers are creating mass reduction pathways for electric vehicle platforms prioritizing range optimization.
Industry Challenges
- Cross-Material Certification Timelines:Validation protocols spanning glass-filled polymers, zinc-coated steels, and emerging composites are extending product development cycles and delaying platform integration milestones.
- Ergonomic Testing Capability Scarcity:Specialized occupant biomechanics expertise required for integrated assist system design is concentrated at a limited number of engineering service providers, constraining supplier expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Grab Handle Market |
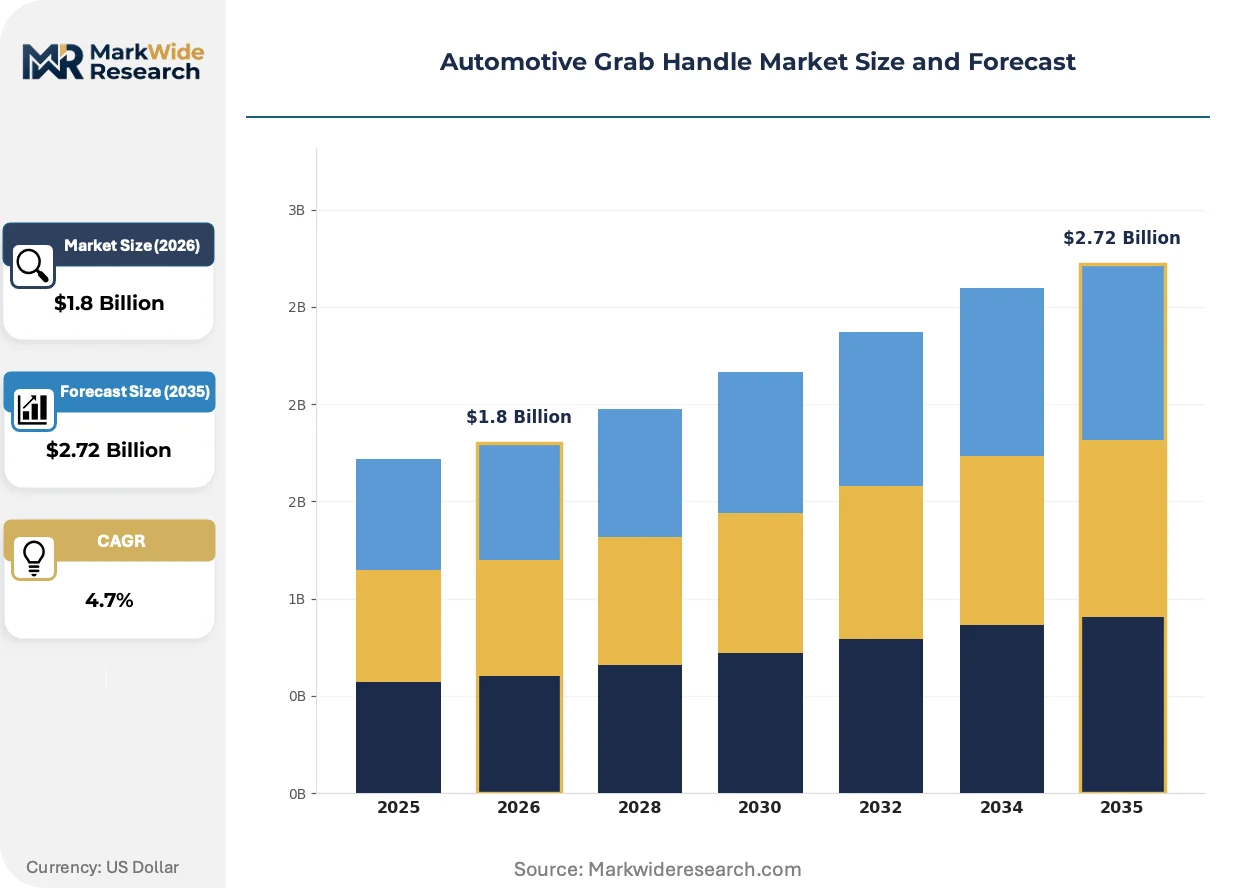
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Interior Handles, Assist Handles, Exterior Handles, Door Handles Material: Plastic, Metal, Composite, Rubber Vehicle Type: Passenger Cars, Commercial Vehicles, SUVs, Motorcycles Functionality: Safety, Convenience, Aesthetic, Ergonomic |
| Companies Covered | Grupo Antolin, BASF, Dura Automotive Systems, Magna International, Lear Corporation, Adient, AGM Automotive, Rugged Ridge, Smittybilt, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Grab Handle Market Emerging Trajectories
Sensor-integrated handle architectures are transforming passive mechanical components into active cabin interfaces, creating new functional requirements for wiring integration and software validation that extend supplier competence boundaries beyond traditional metal and polymer processing.
Capacitive sensing technology embedded in overhead assist handles is digitizing occupant detection and gesture recognition functions previously handled by discrete switches or camera systems. Luxury electric vehicle manufacturers in Germany and China are adopting these modules at accelerated cadences for hands-free cabin control activation. This convergence is compressing the traditional separation between interior hardware suppliers and electronic subsystem integrators, forcing handle specialists to develop firmware competencies or cede value capture to tier-one electronics suppliers.
REACH regulation amendments targeting endocrine-disrupting chemicals in polymer additives are compelling reformulation of glass-filled polypropylene compounds used in cabin touchpoints. Compounders serving the automotive sector are investing in alternative flame-retardant and UV-stabilizer packages to maintain performance specifications while achieving substance compliance. Interior handle programs destined for EU markets face the most stringent qualification burdens, with some OEMs extending these material standards globally to simplify supply chain complexity.
Fleet operators and vehicle leasing companies are unbundling grab handle replacement from comprehensive maintenance agreements, creating standalone procurement channels for aftermarket service providers. This behavioral shift is fragmenting demand across discrete component supply and installation service contracts, particularly visible in North American commercial vehicle and ride-hail fleet segments where interior wear rates exceed private passenger vehicle averages. Suppliers with dedicated service networks are capturing margin pools previously retained by dealership parts operations.
Automotive Grab Handle Market Segmentation
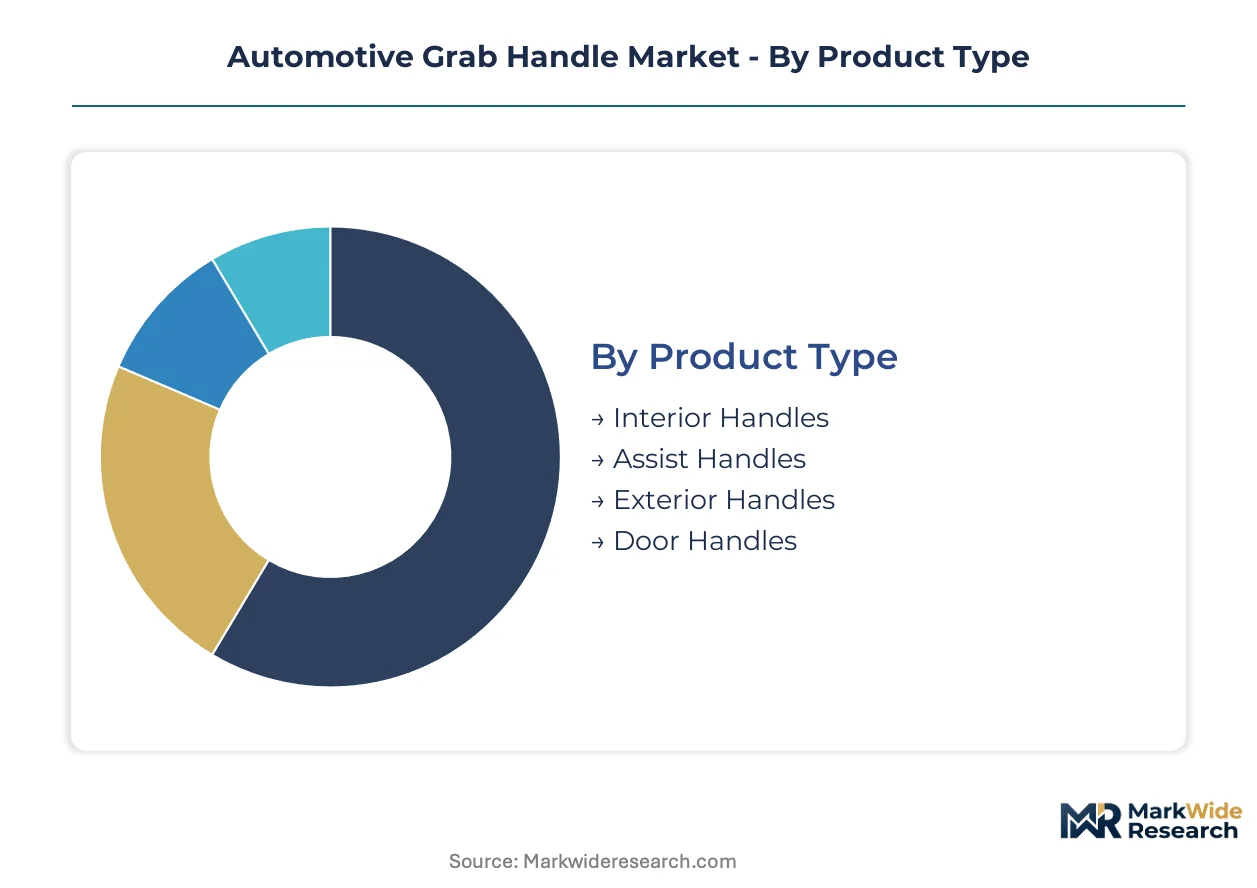
Grab handle procurement patterns diverge sharply across vehicle programs, with premium passenger car manufacturers prioritizing integrated assist systems while commercial fleet operators optimize for replacement cycle economics. Material selection and functionality requirements reshape supplier qualification criteria and margin structures differently across each segment boundary.
Product Type:
After-sales service intensity varies dramatically by handle mounting location and integration depth, with pillar-mounted systems requiring more complex refurbishment protocols than discrete overhead units.
- Interior Handles:These mechanically fixed handholds installed on A-pillars, B-pillars, and headliners typically employ glass-filled polypropylene formulations rated for cyclic loads exceeding 500 Newtons. German premium manufacturers around Stuttgart specify customized finish coatings that extend replacement intervals in high-wear fleet applications.
- Assist Handles:Overhead retractable handholds with integrated return mechanisms dominate ergonomic-focused vehicle programs. Chinese OEMs adopting GB standards compliance are accelerating procurement of these units for domestic electric vehicle platforms targeting occupant comfort differentiation.
- Exterior Handles:Weather-resistant variants with sealed bearing assemblies serve commercial vehicle access applications.
- Door Handles:Integrated pull mechanisms combining entry and stabilization functions consolidate component counts in cost-optimized vehicle architectures.
Interior handles hold the largest share; momentum sits with assist handles as cabin ergonomics become a competitive differentiator.
Material:
Raw material qualification timelines and substance compliance burdens concentrate differently across polymer, metal, and hybrid formulations, with REACH-regulated additives creating asymmetric barriers to compounder approval.
- Plastic:Glass-filled polypropylene compounds compatible with high-speed injection molding occupy the dominant unit economics position. Color-matching capabilities and mass reduction potential position these formulations favorably with OEMs pursuing platform standardization across multiple vehicle programs.
- Metal:Zinc-coated steel substrates deliver maximum cyclic load tolerance for heavy-duty commercial vehicle applications. Input cost volatility for zinc and steel sheet compresses margins on hybrid material handles and discourages long-term fixed-price contracting.
- Composite:Hybrid fiber-reinforced thermoplastic matrices with natural fiber fillers are climbing the fastest as electric vehicle manufacturers prioritize range optimization through cabin component mass reduction.
- Rubber:Elastomeric overmold variants provide tactile grip surfaces and vibration dampening in premium vehicle specifications.
Plastic formulations dominate unit volumes; composites are gaining share fastest on mass reduction imperatives.
Vehicle Type:
Production volume concentration and platform sharing intensity determine whether handle programs justify dedicated tooling investment or modular component supply arrangements.
- Passenger Cars:High-volume sedan and hatchback programs drive standardization of grab handle architectures across multiple OEM brands. The Stuttgart-Munich manufacturing corridor generates sustained demand for ergonomic interior hardware with customized finish specifications.
- SUVs:Elevated cabin architectures and off-road duty cycles require reinforced load-bearing specifications. Chinese domestic manufacturers are expanding SUV grab handle procurement as the segment captures growing domestic market share.
- Commercial Vehicles:Extended duty cycles and higher occupant ingress-egress frequency accelerate wear rates and expand aftermarket replacement revenue pools.
- Motorcycles:Compact form factors and weather exposure dictate specialized sealing and corrosion resistance requirements.
Passenger cars anchor volume demand; SUVs exhibit the steepest expansion trajectory on platform proliferation.
Functionality:
Sensor integration and digitization are reclassifying handle value propositions from passive mechanical components toward active cabin interface nodes with embedded electronic functionality.
- Safety:Load-certified retention systems engineered for occupant stabilization during collision events or severe maneuvering. NHTSA Federal Motor Vehicle Safety Standards govern retention force requirements for these critical applications.
- Convenience:Capacitive sensing technology embedded in overhead assist handles enables hands-free cabin control activation. Luxury electric vehicle manufacturers in Germany and China are digitizing occupant detection through these modules.
- Aesthetic:Finish-matched surface treatments and illumination integration serve premium cabin design specifications.
- Ergonomic:Biomechanically optimized grip geometries and deployment forces address occupant accessibility requirements.
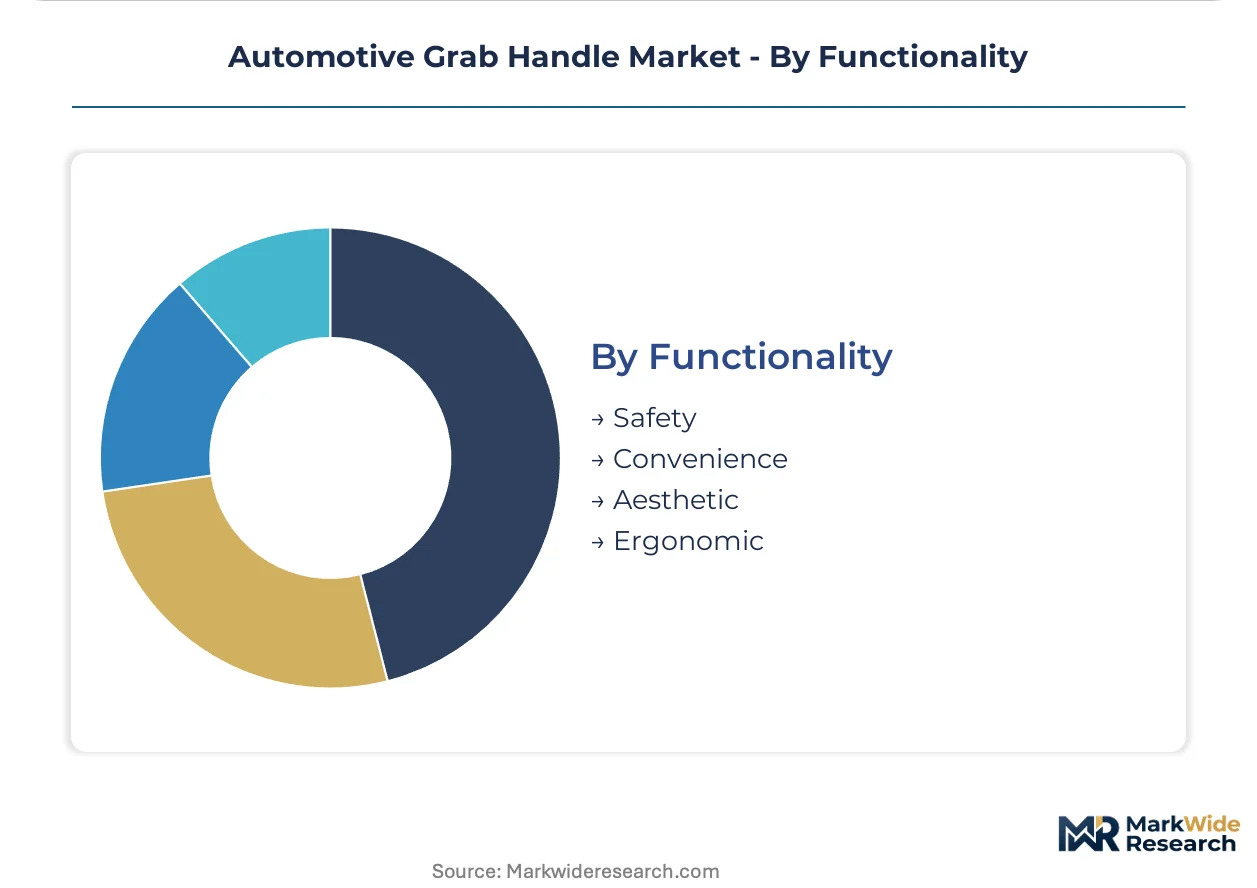
Safety functionality retains the largest procurement share; convenience features are expanding most quickly on sensor convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet operators in North America exhibit the highest price sensitivity for aftermarket replacement cycles, while German premium manufacturers absorb cost premiums for customized ergonomic specifications without volume elasticity effects.
United States
Commercial vehicle fleet operators unbundle grab handle replacement from comprehensive maintenance agreements, creating standalone procurement channels for aftermarket service providers. NHTSA Federal Motor Vehicle Safety Standards govern occupant protection and interior component retention requirements. The Midwest manufacturing belt around Michigan anchors North American production through dedicated seating and interiors plants serving Detroit-based OEMs.
Germany
Luxury electric vehicle manufacturers accelerate procurement of capacitive-sensing assist handles for hands-free cabin control activation. REACH regulation amendments targeting endocrine-disrupting chemicals in polymer additives compel reformulation of glass-filled polypropylene compounds. The Stuttgart-Munich manufacturing corridor generates sustained demand for ergonomic interior hardware with customized finish specifications and extended replacement intervals.
China
Domestic SUV manufacturers expand grab handle procurement as the segment captures growing domestic market share and prioritizes occupant comfort differentiation. SAMR enforces GB standards for automotive interior part durability and load-bearing requirements under tightening material specifications. Yangtze River Delta electric vehicle platforms drive standardization of assist handle architectures across multiple domestic brands.
Japan
Premium passenger car programs emphasize biomechanically optimized grip geometries addressing aging demographic accessibility requirements. METI industrial standards influence material qualification timelines for cabin touchpoint components. Kanto region automotive clusters concentrate ergonomic testing capabilities with specialized occupant biomechanics expertise.
South Korea
Electric vehicle manufacturers prioritize composite material convergence for mass reduction pathways supporting range optimization targets. MFDS-equivalent automotive material disclosure requirements shape raw material sourcing strategies for interior component suppliers. Seoul Capital Area production facilities integrate sensor-embedded handle architectures transforming passive mechanical components into active cabin interfaces.
Automotive Grab Handle Market Vendor Landscape
Capability concentration sits with integrated interior specialists possessing captive injection molding infrastructure; scale advantage sits with diversified tier-one suppliers operating across multiple vehicle programs. The supply base organizes around three archetypes: full-system integrators with ergonomic testing capabilities, material compounders with validated recycling partnerships, and discrete component manufacturers seeking direct OEM relationships. Dominant competitive moves include backward integration into plastic processing assets and strategic positioning for anticipated recycled content mandates.
Among North American diversified suppliers, Magna International and Lear Corporation exemplify scale-driven platform modularity approaches. Grupo Antolin represents the vertically integrated archetype with in-house production capabilities spanning material compounding through finished component supply. These three entities anchor competitive positioning across distinct capability vectors without overlapping strategic emphasis.
| Leading Market Players |
|---|
| Grupo Antolin |
| BASF |
| Dura Automotive Systems |
| Magna International |
| Lear Corporation |
| Adient |
| AGM Automotive |
| Rugged Ridge |
| Smittybilt |
| Others |
Supply Flow & Price Mechanics
Commodity volatility in zinc-coated steel feedstocks determines both tiered margin compression across premium and economy handle specifications and the geographic reconfiguration of captive injection molding investments toward tariff-advantaged production zones. This dual feedback loop rewards suppliers with backward integration into polymer compounding while squeezing independent metal-forming specialists dependent on spot-market steel procurement.
Pricing Analysis
Aftermarket service contracts now drive lifetime value capture beyond initial equipment supply. Three-tier pricing structure across premium, standard, and economy levels differentiates on certification grade and finish customization. Cost compression in economy-tier plastic handles is intensifying because OEMs are pushing platform standardization across multiple vehicle programs. Fleet operators exhibit the highest price sensitivity, while German premium manufacturers absorb cost premiums for ergonomic specifications without volume elasticity effects.
Supply Chain Analysis
Tariff exposure between China and North America dominates strategic sourcing decisions for glass-filled polypropylene compounds. Supply concentrates in Germany, China, and Mexico for both polymer compounding and finished component assembly. Raw material dependencies rest on polypropylene resin, zinc-coated steel sheet, and natural fiber fillers for emerging composite formulations. Single-source vulnerability in specialized ergonomic testing capabilities constrains supplier expansion. Distribution runs through tier-one interior specialists with direct OEM relationships rather than independent aftermarket channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sensor-integrated handle architectures are transforming this market into a platform-economics inflection point where hardware suppliers must develop firmware competencies or cede value capture to electronics integrators. Interoperability requirements for capacitive sensing modules are reshaping supplier qualification criteria.
For Market Incumbents: Pre-empt electronics tier-one encroachment by acquiring embedded systems capabilities or partnering with sensor module specialists. Secure backward integration into recycled-content polymer compounding before EU mandates harden. Defend against emerging composite specialists by locking in long-term natural fiber supply agreements with agricultural processors. For New Entrants and Emerging Players: Build out ergonomic testing capabilities as a service offering to tier-two component manufacturers lacking in-house biomechanics expertise. Target the North American commercial vehicle aftermarket where fleet operators unbundle replacement from comprehensive maintenance agreements. Pursue a direct-to-fleet go-to-market angle bypassing dealership parts operations. For Investors and Strategic Acquirers: REACH regulation amendments reshaping polymer additive requirements recalibrate the acquisition landscape toward compounders with validated alternative flame-retardant packages. Long-term viability hinges on positioning for recycled content mandates and sensor convergence. Signal to watch: OEM platform standardization announcements that would commoditize discrete handle supply.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | OEM consolidation of handle architectures across multiple vehicle programs reduces tooling amortization for qualified suppliers. |
| Sensor Module Partnership | Capacitive sensing integration transforms passive hardware into active cabin interfaces with recurring software validation revenue. |
| Recycled Content Validation | Early compliance with anticipated EU post-consumer material mandates secures preferred supplier status in platform sourcing. |
| Ergonomic Testing Acquisition | Specialized biomechanics capabilities command scarcity rents as integrated assist system complexity escalates. |
| Aftermarket Service Network | Standalone fleet replacement contracts capture margin pools previously retained by dealership parts operations. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with tier-one supplier procurement officers, OEM platform engineers, aftermarket distributors, and dealership operations managers; and secondary validation against vehicle production databases, IHS Markit registration data, customs records, and SEC filings from interior component suppliers. Bottom-up segment sizing triangulated against top-down production volume estimates.
Forecast inputs considered vehicle class, propulsion architecture, content per vehicle, and regional production cluster across the analysis window. CAGRs were derived from production volume trajectories and material substitution elasticities. Industry-specific inputs included GB standards compliance timelines and REACH substance restriction phase-in schedules.
Stress conditions across zinc price volatility, polymer feedstock availability, and regulatory enforcement intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Body-In-White Market
Automotive Interior & Exterior
Automotive Lighting Market
Automotive Interior & Exterior
All Plastic Front End Module Market
Automotive Interior & Exterior
Automotive Dashboard Market
Automotive Interior & Exterior
Automotive Clear Coat Paint Market
Automotive Interior & Exterior
Automotive Electrically Adjustable Outside Rear View Mirror (ORVM) Market
Automotive Interior & Exterior
India Automotive Adaptive Lighting System Market
Automotive Interior & Exterior
Automotive Exterior Smart Lighting Market
Automotive Interior & Exterior
Automotive Seat Climate Systems Market
Automotive Interior & Exterior
Car Covers Market
Automotive Interior & Exterior
Railway Interior Lighting Market
Automotive Interior & Exterior
Automotive Door Handles Market
Automotive Interior & Exterior
Europe Automotive Interiors Market
Automotive Interior & Exterior
Seat Comfort and Lumbar Actuator Systems Market
Automotive Interior & Exterior
Bonnet Lock Plate and Latch Market
Automotive Interior & Exterior
United States Car Bumper Guard Market