
 Automotive Portable Refrigerator Market | 2026-2036
Automotive Portable Refrigerator Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Portable Refrigerator Market Analytics
The EU Green Deal is repositioning automotive portable refrigerator demand toward low-GWP refrigerant systems and energy-efficient designs. Dometic Group AB leverages its European manufacturing footprint to sustain compliance leadership across CE-marked product lines. Engel Distribution Pty Ltd. anchors its position through compressor technology specialization in ruggedized outdoor applications. ARB USA competes by controlling distribution through dedicated 4x4 and overlanding retail channels.
An automotive portable refrigerator is a thermally insulated, mobile cooling device engineered for DC power operation, typically maintaining temperatures between minus 18 degrees Celsius and plus 10 degrees Celsius via compressor, absorption, or thermoelectric mechanisms. These units serve commercial and recreational vehicle operators requiring food preservation and beverage chilling during transit or remote stops. Compressor refrigerators command the dominant value share due to superior cooling efficiency and freezing capability in ambient temperatures exceeding 40 degrees Celsius. Thermoelectric coolers occupy the entry-price tier with lighter weight and simpler semiconductor-based operation, though their performance degrades substantially in high-heat environments. Absorption refrigerators retain niche positioning among off-grid users prioritizing silent operation and multi-fuel flexibility.
The EPA regulates refrigerant emissions under Section 608 of the Clean Air Act, compelling manufacturers toward R600a and other low-global-warming-potential alternatives in US-bound products. ECHA enforces REACH and RoHS compliance for substances in electrical components sold across European markets, raising material certification costs for exporters. China's SAMR implements GB standards for energy efficiency labeling that affect import eligibility and domestic product positioning. Stakeholders must monitor diverging refrigerant phase-down schedules and efficiency test protocols across these jurisdictions to preserve market access and avoid stranded inventory.
Market Dynamics
China's dual carbon goals are compressing the product development cycle for mobile cooling equipment, forcing manufacturers to redesign compressor systems and insulation materials ahead of tightened GB energy-efficiency standards.
Growth Catalysts
- Overlanding vehicle retrofit demand:Western US vanlife communities are expanding the addressable base for DC-powered refrigeration, with dedicated 4x4 accessory channels scaling distribution capacity.
- EU F-Gas Regulation phase-down:The 2024-2030 refrigerant quota reduction is accelerating R600a and hydrocarbon adoption in CE-marked product lines, creating compliance-driven replacement cycles.
- Silent absorption technology:Off-grid camping and wildlife photography segments are pulling multi-fuel refrigerators into premium positioning, displacing compressor noise in remote-use scenarios.
Market Restraints
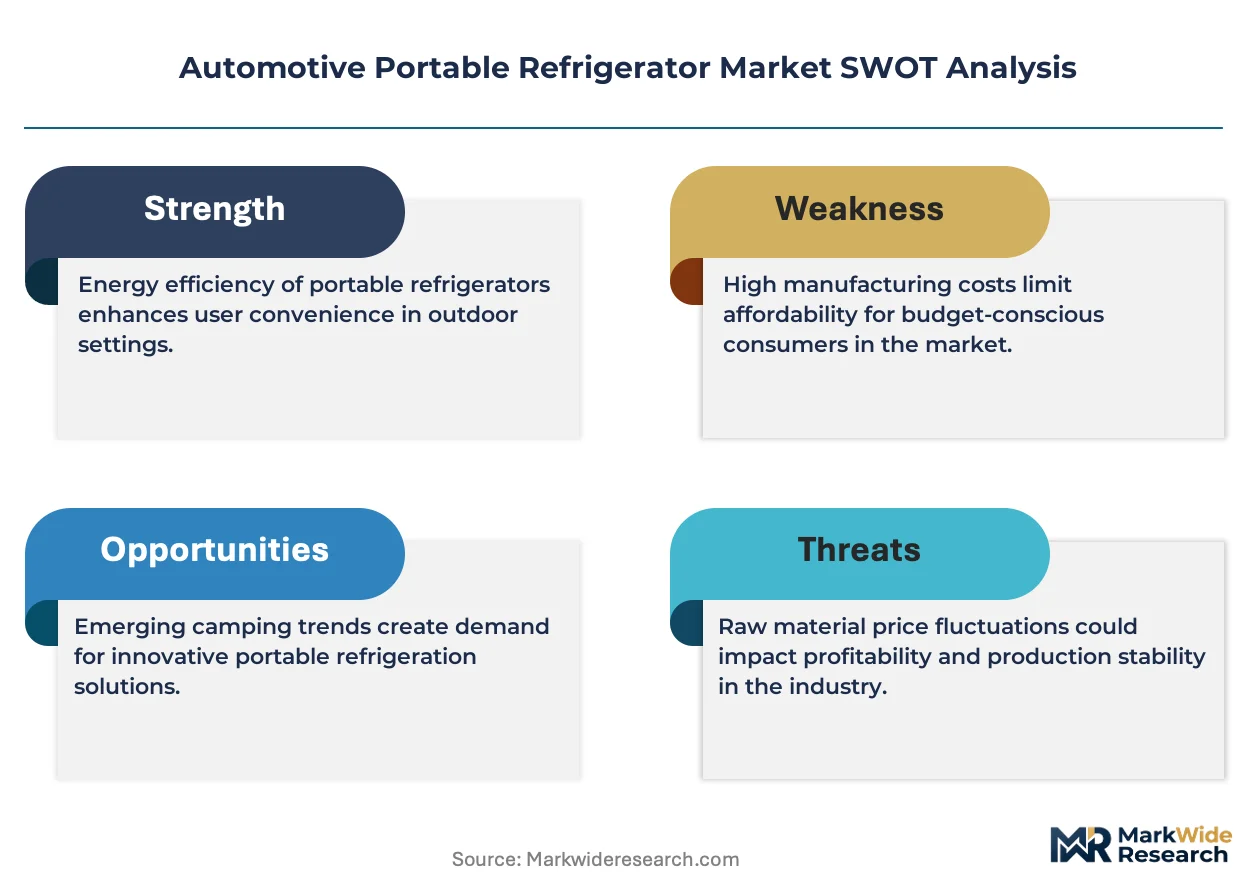
- Copper and aluminum input volatility:Compressor heat exchangers and casing materials expose margins to London Metal Exchange price swings, complicating long-term contract pricing.
- Thermoelectric performance ceiling:Peltier systems degrade above 35 degrees Celsius ambient, limiting addressable hours in desert overlanding corridors and tropical logistics routes.
- REACH substance certification costs:ECHA compliance for electrical insulation and solder materials adds 8-12 week pre-shipment timelines for Asian exporters serving European retail.
Strategic Opportunities
- India outdoor recreation emergence:Ladakh and Spiti Valley overlanding routes are creating first-mover openings for ruggedized DC refrigeration as domestic 4x4 ownership expands.
- Vehicle-integrated power systems:Convergence of lithium iron phosphate house batteries and smart DC-DC charging is enabling whole-cabin energy management bundling.
- Australia caravan park electrification:National campground infrastructure upgrades are creating plug-and-play rental markets for seasonal refrigerator deployment.
Industry Challenges
- Refrigeration technician scarcity:Hydrocarbon handling certification requirements are narrowing the service network for warranty repairs in remote deployment zones.
- Multi-jurisdiction test protocol divergence:EPA SNAP approval timelines, GB energy-labeling procedures, and CE conformity assessment routes create parallel development tracks.
- Integration complexity with CAN bus systems:Smart refrigerator load management requires vehicle-specific protocol adaptation, fragmenting firmware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Portable Refrigerator Market |
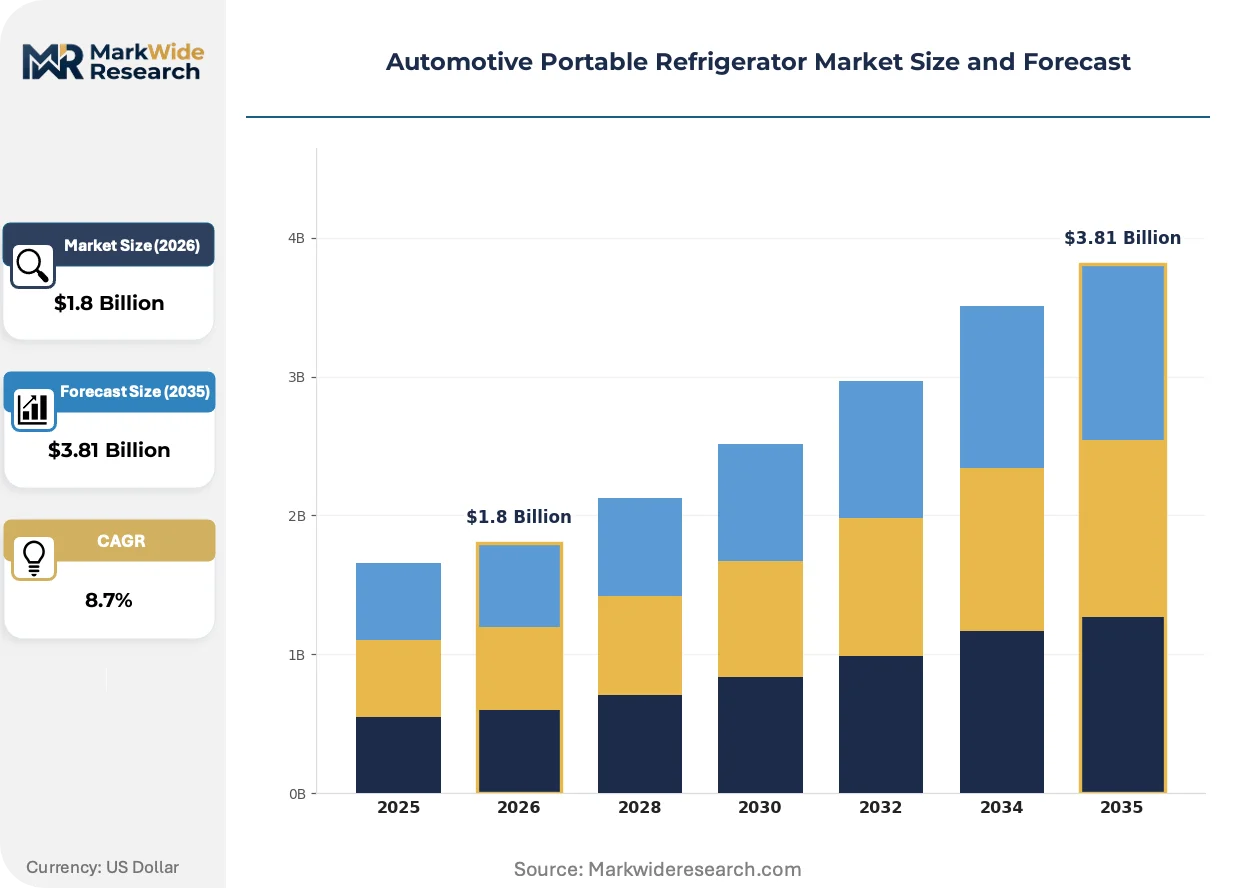
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
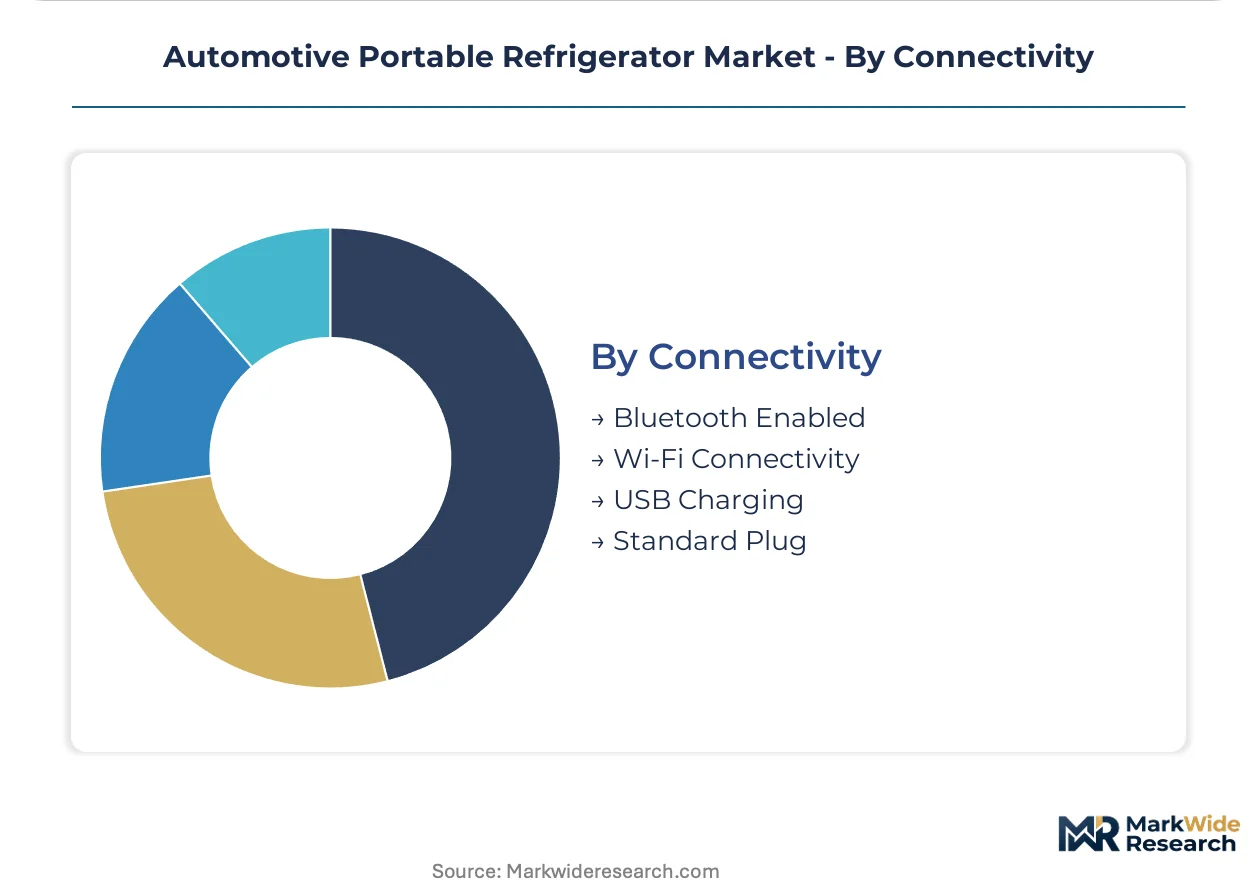
| Segmentation | Product Type: Absorption Refrigerators, Compressor Refrigerators, Thermoelectric Coolers, Mini Fridges End User: Outdoor Enthusiasts, Road Travelers, Camping Users, Commercial Vehicles Power Rating: 12V, 24V, 110V, Dual Voltage Connectivity: Bluetooth Enabled, Wi-Fi Connectivity, USB Charging, Standard Plug |
| Companies Covered | Dometic Group AB, Engel Distribution Pty Ltd., ARB USA, Whynter LLC, Koolatron Corporation, Indel B S.p.A., Alpicool, Mobicool, Igloo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Portable Refrigerator Market Evolving Landscape
Variable-speed compressor control is rewriting thermal management economics, while regulatory refrigerant phase-downs and direct-to-consumer channel expansion are compressing legacy go-to-market structures.
Brushless DC compressor technology with integrated inverter drives is rewriting efficiency benchmarks for mobile refrigeration. Overlanding equipment buyers in Australia and the Western United States are specifying these units for solar-dominated power budgets. The technology is compressing battery capacity requirements and enabling smaller lithium pack configurations.
The EU F-Gas Regulation's 2024 quota cut is forcing refrigerant formulation changes across CE-marked product lines. Manufacturers are redesigning capillary tube lengths and compressor displacement to maintain cooling duty with lower-GWP hydrocarbons. Small-capacity units under 40 liters are experiencing the fastest redesign cycles as they face earlier compliance deadlines.
Direct-to-consumer video commerce is displacing traditional outdoor retail for initial product discovery. Chinese manufacturers are building owned-media presences on short-form platforms, bypassing distributor margin stacks. This channel rotation is most visible in Southeast Asian markets where mobile-first purchasing dominates camping accessory procurement.
Automotive Portable Refrigerator Market Segmentation
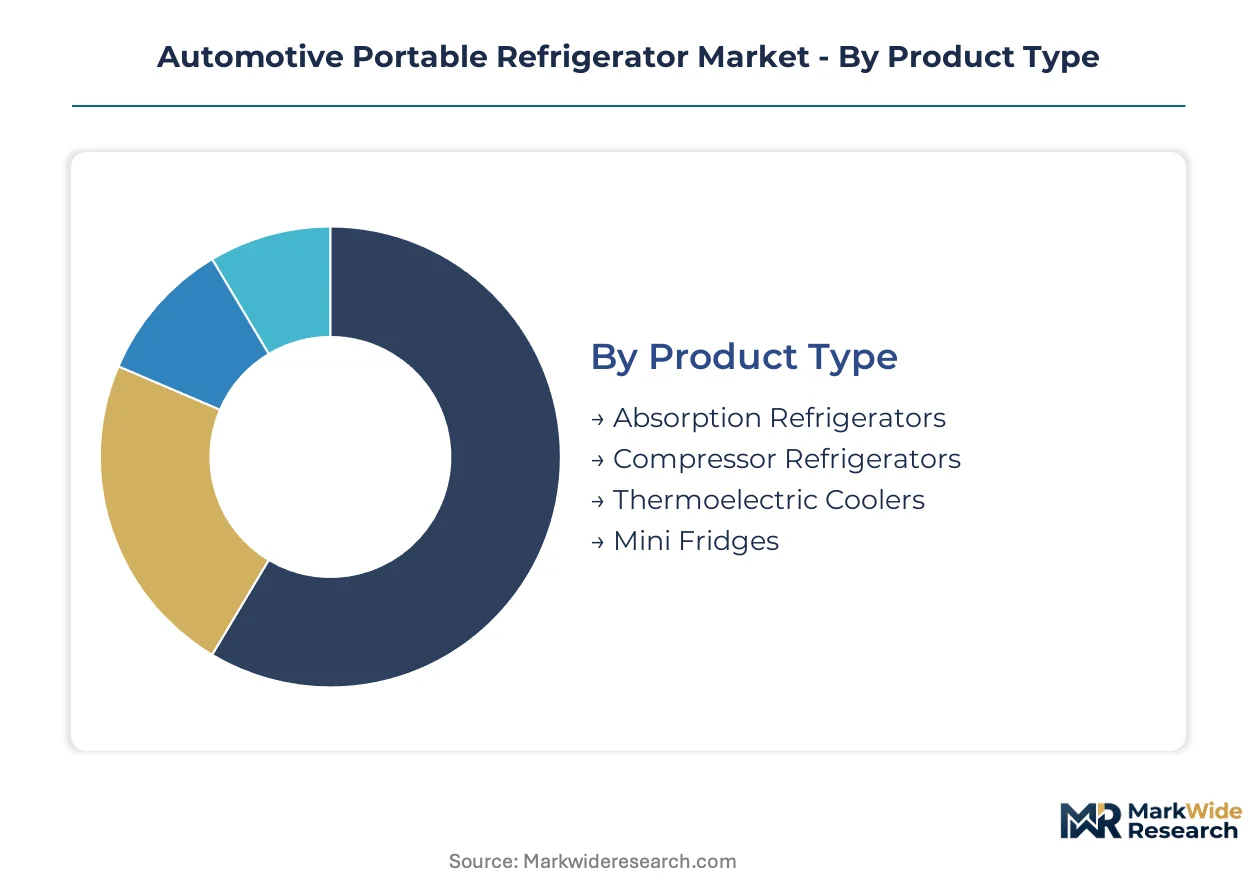
Automotive portable refrigerator segmentation reveals how capital deployment, technical requirements, and user behavior fragment manufacturing priorities. Product architecture and power integration choices determine which suppliers capture margin in DC-dominant vehicle applications.
Product Type:
Compressor systems demand the highest upfront tooling investment for sealed unit assembly and refrigerant handling infrastructure.
- Compressor Refrigerators:Sealed reciprocating or rotary compressors with inverter drives deliver minus 18 degrees Celsius freezing from 12V DC inputs. Overlanding retrofitters in the Western United States specify these for solar-dominated power budgets where efficiency preserves battery capacity.
- Thermoelectric Coolers:Semiconductor Peltier junctions transfer heat without moving parts, enabling sub-$150 price points and sub-5-kilogram portability. Road travelers in temperate climates accept the 20-degree-Celsius below-ambient limitation for beverage chilling during highway stops.
- Absorption Refrigerators:Ammonia-hydrogen absorption cycles operate silently on propane, 12V, or 120V, suiting wildlife photographers and off-grid campers prioritizing acoustic discretion over cooling speed.
- Mini Fridges:Thermoelectric or compressor variants under 20 liters address console and seatback installations where cabin space constraints dominate specification.
Compressor refrigerators absorb the bulk of installed capacity; thermoelectric coolers are expanding most quickly in entry-price Asian markets.
End User:
Application intensity determines duty cycle expectations and warranty claim frequency across the installed base.
- Outdoor Enthusiasts:Backpackers, anglers, and hunters operating beyond grid access for 72-plus hours demand multi-fuel flexibility and sub-40-decibel operation. Australia's caravan park electrification programs are pulling absorption units into seasonal rental pools.
- Commercial Vehicles:Long-haul trucking fleets and last-mile delivery vans require food safety compliance and temperature logging for regulatory documentation. The segment commands the highest average selling prices due to telematics integration and hardened chassis mounting.
- Road Travelers:Interstate motorists and weekend excursionists prioritize plug-and-play simplicity from 12V accessory sockets, accepting thermoelectric performance trade-offs for sub-$200 acquisition costs.
- Camping Users:Tent and RV campers split between budget thermoelectric units for overnight trips and compressor systems for extended basecamp operations.
Commercial vehicles concentrate the highest revenue per unit; outdoor enthusiasts are climbing the fastest as vanlife participation broadens.
Power Rating:
Voltage architecture determines battery compatibility and cross-border sales eligibility in regulated vehicle markets.
- 12V:The baseline automotive standard dominates North American and Japanese light-vehicle accessory sockets. Manufacturers optimize compressor displacement and evaporator sizing around 8-amp draw limits.
- 24V:Heavy-duty trucking and European commercial vehicle specifications enable higher compressor capacity without exceeding current limits. The segment carries premium positioning due to lower volume and specialized distribution.
- 110V:Shore power compatibility for RV park hookups and garage pre-cooling expands addressable hours but requires inverter or dual-power architecture.
- Dual Voltage:Automatic switching between 12V/24V vehicle and 110V/240V shore supplies commands price premiums in overlanding and marine crossover segments.
12V systems anchor the installed base; dual voltage configurations are gaining share fastest in premium overlanding equipment.
Connectivity:
Smart feature integration separates premium positioning from commodity replacement cycles in mature markets.
- Bluetooth Enabled:Smartphone temperature monitoring and compressor cycling control via manufacturer apps. The Western United States overlanding community specifies these for remote diagnostics in dispersed camping scenarios.
- Wi-Fi Connectivity:Cloud-linked units enable fleet managers and commercial operators to monitor temperature compliance across distributed vehicle pools. Higher hardware costs and subscription dependencies limit penetration to enterprise procurement.
- USB Charging:Auxiliary 5V outputs for phone and tablet charging add negligible cost but feature prominently in consumer-facing marketing materials.
- Standard Plug:Non-connected units without digital interfaces retain majority volume in price-sensitive Asian and Latin American markets where smartphone penetration does not translate to appliance connectivity demand.
Standard plug configurations retain the largest shipment volumes; Bluetooth-enabled units are expanding most quickly in Australian and North American direct-to-consumer channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity clusters in China and Southeast Asia while consumption concentrates in North American and European outdoor recreation markets. This production-consumption divide shapes trade flows and compliance requirements across jurisdictions.
United States
Western states overlanding communities in Colorado, Utah, and California drive DC-powered refrigerator retrofit demand through dedicated 4x4 accessory channels. EPA Section 608 refrigerant regulations compel R600a adoption in US-bound product lines. Texas and Arizona desert corridor logistics operators specify compressor units for temperature-sensitive cargo in extreme ambient conditions.
China
Domestic vanlife participation and outdoor recreation infrastructure expansion are pulling portable cooling equipment into consumer retail. SAMR GB energy-efficiency standards and dual carbon goals are compressing product development cycles for compressor redesign. Guangdong and Zhejiang manufacturing clusters house sealed unit assembly infrastructure serving export markets.
Germany
Caravan and motorhome OEM integration creates specification pull for dual-voltage refrigerator systems in European recreational vehicle builds. ECHA REACH and RoHS compliance requirements elevate material certification costs for electrical component sourcing. Baden-Württemberg automotive supplier networks are adapting compressor technology for mobile cooling applications.
Australia
Remote-area tourism and mining logistics sustain demand for ruggedized multi-fuel absorption units in off-grid deployment scenarios. National caravan park electrification programs are creating seasonal rental markets for plug-and-play refrigerator deployment. Queensland and Western Australia overlanding route operators specify brushless DC compressor systems for solar-dominated power budgets.
Japan
Kei van and compact RV aftermarket channels support thermoelectric and mini-fridge segments for weekend excursionists. METI energy-efficiency labeling requirements influence import product positioning and domestic manufacturer R&D priorities. Nagoya-area automotive component suppliers are developing vehicle-integrated power management systems for DC appliance loads.
Automotive Portable Refrigerator Market Competitive Landscape
The competitive structure tilts toward specialized compressor technology providers and diversified outdoor equipment conglomerates. Mid-scale specialists with dedicated distribution through overlanding retail channels occupy defensible positions against mass-market entrants. Three archetypes dominate: European manufacturing incumbents with regulatory compliance leadership, Asia-Pacific volume producers with direct-to-consumer channel control, and regional distribution specialists with 4x4 accessory market lock-in. Competitive moves center on refrigerant platform redesign cycles and lithium power system bundling partnerships.
Among European manufacturing incumbents, Dometic Group AB exemplifies compliance-driven product line architecture across CE-marked jurisdictions. Engel Distribution Pty Ltd. and ARB USA anchor the regional distribution specialist archetype through dedicated 4x4 and overlanding retail channel control. These three occupy positions that resist pure price competition by coupling product specification with installation support and warranty service networks in remote deployment zones.
| Leading Market Players |
|---|
| Dometic Group AB |
| Engel Distribution Pty Ltd. |
| ARB USA |
| Whynter LLC |
| Koolatron Corporation |
| Indel B S.p.A. |
| Alpicool |
| Mobicool |
| Igloo |
| Others |
Value Network & Pricing Analysis
Compressor-thermoelectric performance divergence separates premium brushless DC systems from commodity Peltier units, and this bifurcation manifests in both acquisition cost spreads and sourcing concentration across Guangdong manufacturing clusters versus distributed Southeast Asian assembly for entry-price tiers.
Pricing Analysis
Margin tightening in thermoelectric entry tiers reflects copper heat exchanger cost volatility and semiconductor junction pricing pressure from consumer electronics demand competition. Three-tier pricing structure across premium brushless DC, standard fixed-speed compressor, and economy thermoelectric levels anchors the market. Price differentiation traces to GB energy-efficiency certification tiers and lithium power system bundling. Fleet procurement managers show lowest price sensitivity; weekend road travelers exhibit highest.
Supply Chain Analysis
Skilled refrigeration technician scarcity in Guangdong and Zhejiang sealed-unit assembly corridors is compressing capacity expansion timelines for hydrocarbon-handling certification requirements. Manufacturing gravity centers on China, South Korea, and Germany for compressor technology. Raw material dependencies span copper heat exchangers, aluminum casing alloys, and lithium iron phosphate cells. Single-source vulnerability concentrates in brushless DC inverter controller chipsets. Distribution runs through dedicated 4x4 accessory channels and direct-to-consumer video commerce platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU F-Gas refrigerant phase-down deadlines and China's tightened GB energy-efficiency standards are forcing simultaneous product redesign cycles that weaker capitalized players cannot fund, consolidating share toward compliance-leaders with European manufacturing footprints.
For Market Incumbents: Deepen backward integration into sealed compressor unit assembly to capture margin from hydrocarbon refrigerant handling certification requirements. Fortify warranty service networks in Western US overlanding corridors and Australian remote-area deployment zones against emerging Chinese direct-to-consumer entrants with video commerce channel control. For New Entrants and Emerging Players: Capture India's Ladakh and Spiti Valley overlanding route openings before domestic 4x4 ownership saturation hardens distribution access. Target Australia's seasonal caravan park rental pools through plug-and-play refrigerator deployment partnerships with national campground electrification programs. For Investors and Strategic Acquirers: Re-rating potential sits with European manufacturing incumbents possessing CE-marked product line compliance leadership given EU F-Gas quota reduction enforcement acceleration. Five-to-ten year viability favors compressor technology specialists with vehicle-integrated lithium power system bundling capabilities. Watch hydrocarbon refrigerant handling technician certification expansion rates as inflection signal for service network scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Platform Redesign | R600a hydrocarbon adoption satisfies EU F-Gas Regulation phase-down timelines for CE-marked product lines. |
| Lithium Power System Bundling | Vehicle-integrated LiFePO4 house battery partnerships enable whole-cabin energy management cross-selling. |
| Direct-to-Consumer Channel Expansion | Owned-media presences on short-form video platforms bypass distributor margin stacks in Southeast Asian markets. |
| Silent Absorption Technology Premium Positioning | Multi-fuel flexibility captures wildlife photography and off-grid camping segments prioritizing acoustic discretion. |
| Brushless DC Compressor Capacity Addition | Inverter-driven sealed units rewrite efficiency benchmarks for solar-dominated overlanding power budgets. |
Research Methodology
Independent corroboration across compressor technology suppliers, 4x4 accessory channel distributors, and commercial vehicle fleet procurement managers underwrites the qualitative findings. Primary fieldwork engaged sealed unit assembly plant engineers, overlanding equipment retail buyers, and lithium battery system integrators. Secondary validation drew from EPA Section 608 enforcement records, ECHA REACH substance restriction updates, SAMR GB standard issuance notices, and vehicle production registration databases. Bottom-up shipment estimates triangulated against top-down recreational vehicle and commercial fleet penetration assumptions.
Comparable-period anchoring matched historical reference intervals against projection horizon segmentation across compressor, thermoelectric, and absorption product architectures; 12V, 24V, and dual voltage power ratings; and outdoor enthusiast, commercial vehicle, and road traveler end-use applications. CAGRs derived from installed base replacement cycles, regulatory compliance-driven upgrade waves, and channel shift velocity. Industry-specific inputs incorporated refrigerant phase-down schedules and lithium iron phosphate cell cost curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to copper and aluminum London Metal Exchange volatility, hydrocarbon refrigerant technician certification network expansion rates, and multi-jurisdiction test protocol divergence timelines. Forecasts reflect documented assumptions around EU F-Gas quota enforcement, China's dual carbon goal implementation pace, and Western US overlanding participation growth. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Sound Proofing Material Market
Automotive Interior & Exterior
Automotive Interior Leather Market
Automotive Interior & Exterior
Automotive Smart Dashboard Display Market
Automotive Interior & Exterior
Automotive Door Seal Market
Automotive Interior & Exterior
China Automotive Sunroof Market
Automotive Interior & Exterior
Automotive Door Impact Bars Market
Automotive Interior & Exterior
Global Automotive Rear Window Blinds Market
Automotive Interior & Exterior
Automotive Front Windshield Market
Automotive Interior & Exterior
Seat Comfort and Lumbar Actuator Systems Market
Automotive Interior & Exterior
Automotive in-Cabin Air Quality Improvement Solutions Market
Automotive Interior & Exterior
Mexico Automotive Sunroof Market
Automotive Interior & Exterior
Automotive Active Spoiler Market
Automotive Interior & Exterior
Automotive Mudguards Market
Automotive Interior & Exterior
Automotive Upholstery Market
Automotive Interior & Exterior
Automotive Grill Guard Market
Automotive Interior & Exterior
Automotive Window and Exterior Sealing Systems Market