
 Automotive Intelligent Lighting System Market | 2026-2036
Automotive Intelligent Lighting System Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Intelligent Lighting System Market Analysis
The capital-intensity divergence between full-stack lighting integrators and component specialists is unwinding competitive dynamics across the supply base. Koito Manufacturing Co., Ltd. leverages captive LED chip sourcing and in-house optical design to sustain margin structures in matrix beam production. Valeo SA anchors European OEM relationships through integrated smart beam control software and hardware bundles. HELLA GmbH & Co. KGaA competes on modular platform architectures that reduce variant complexity for automakers.
Automotive intelligent lighting systems comprise electronically controlled front and rear illumination assemblies that adjust beam patterns, intensity, and distribution through sensor fusion and real-time processing, typically operating at color temperatures between 4,000K and 6,000K for LED configurations and achieving luminous efficacies exceeding 130 lumens per watt in premium designs. Their primary purpose is to enhance driver visibility while reducing glare for oncoming traffic through adaptive cut-off algorithms and predictive road illumination. LED Systems occupy the dominant value position due to economies of scale in chip manufacturing and universal fitment across vehicle classes. Matrix Beams represent the fastest-expanding product category as pixel-level control enables compliance with stringent anti-dazzle regulations. Electric Vehicles application demand concentrates margin pools, where lighting integration with battery thermal management and aerodynamic optimization creates bundled specification requirements.
NHTSA Federal Motor Vehicle Safety Standard 108 shapes US market access through headlight photometric performance and glare containment thresholds. ECE R48 and EU General Safety Regulation mandate automatic levelling and adaptive functionality for new vehicle types, while China's GB standards administered by SAMR enforce domestic electromagnetic compatibility and environmental durability testing. Stakeholders must monitor divergence between UN harmonized technical prescriptions and national implementation timelines to avoid redundant homologation costs.
Market Dynamics
Matrix beam pixel density wars between Tier 1 integrators and semiconductor suppliers are compressing development cycles and forcing simultaneous hardware-software co-design investments across the supply base.
Growth Catalysts
- NHTSA FMVSS 108 modernization:Proposed glare containment thresholds for adaptive driving beams are accelerating OEM migration from static halogen architectures to electronically controlled LED-matrix platforms in the United States.
- EU General Safety Regulation mandates:Automatic levelling and adaptive functionality requirements for new vehicle types are creating compliance-driven specification floors that eliminate conventional headlamp options from European product planning.
- EV aerodynamic integration:Battery electric vehicle platforms in China are bundling slim-profile intelligent lighting with thermal management hardware, generating consolidated procurement volumes that justify dedicated production lines.
Market Restraints
- LED chip supply concentration:Epitaxial wafer production clusters in East Asia create single-source vulnerability for matrix beam pixel drivers during demand surges.
- Homologation cost escalation:Divergence between UN ECE harmonized technical prescriptions and SAMR GB standards implementation timelines forces redundant electromagnetic compatibility testing for China-bound products.
- Software complexity premiums:Real-time sensor fusion algorithms for predictive road illumination require specialized optical engineering talent that concentrates in Stuttgart, Munich, and Nagoya metro areas.
Strategic Opportunities
- India PLI scheme alignment:Domestic component manufacturing incentives for automotive electronics are opening cost-optimized production pathways for mid-tier adaptive headlamp modules serving emerging market OEMs.
- V2X communication convergence:Integration of vehicle-to-infrastructure signaling with intelligent lighting control creates new specification layers for smart city deployment corridors in Germany and South Korea.
- Aftermarket retrofit channels:Regulatory clarity on LED conversion kit compliance in select US states is enabling certified upgrade pathways for aging vehicle fleets.
Industry Challenges
- Optomechanical talent scarcity:The intersection of precision lens design and thermal simulation expertise remains underdeveloped in engineering programs outside Japan and Germany.
- Legacy CAN bus integration:Real-time beam pattern adjustment requires protocol translation layers that add latency and validation burden when interfacing with decade-old vehicle electrical architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Intelligent Lighting System Market |
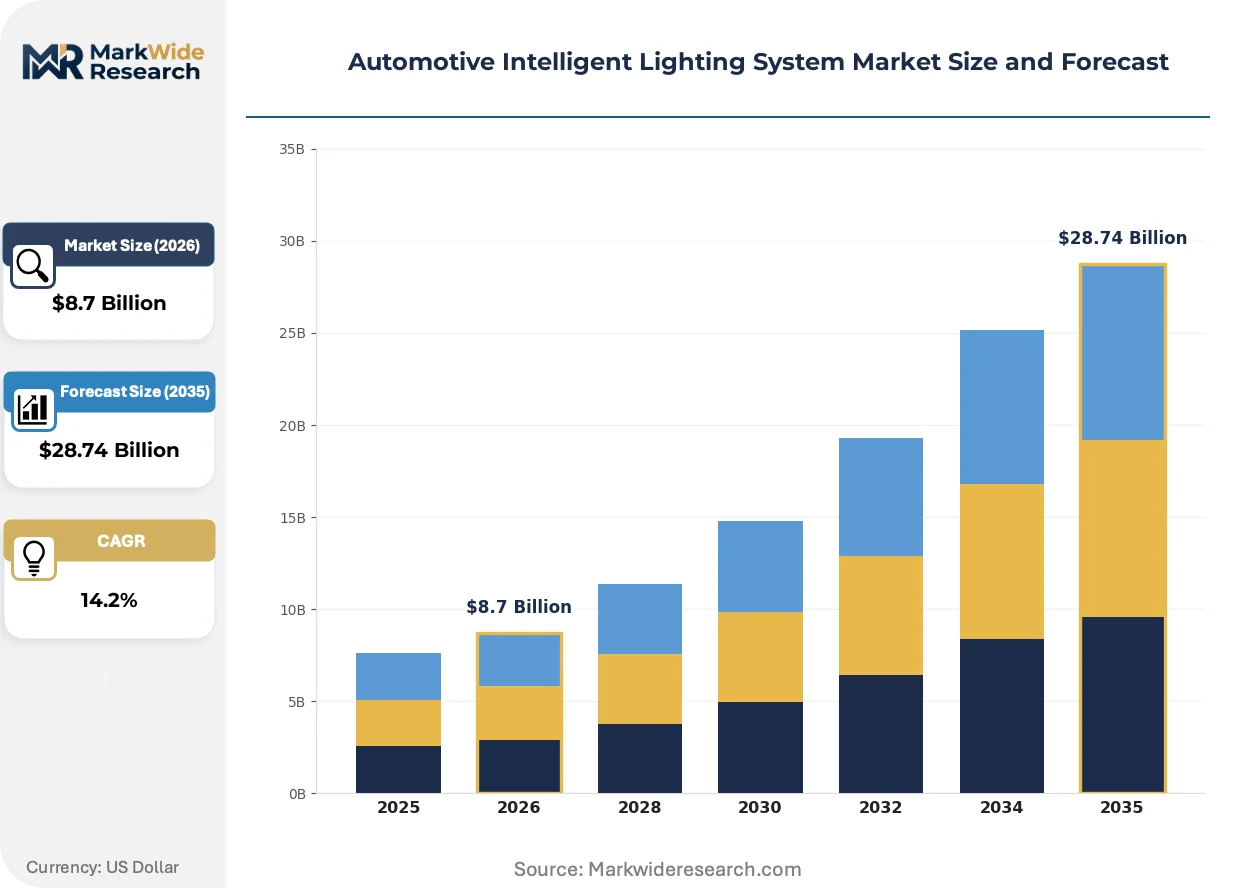
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Adaptive Headlights, LED Systems, Laser Lights, Matrix Beams Technology: Smart Beam Control, Networked Lighting, IoT Integration, Vision Sensors End User: Automakers, Original Equipment Manufacturers, Aftermarket Providers, Vehicle Assemblers Application: Passenger Vehicles, Commercial Trucks, Two-Wheelers, Electric Vehicles |
| Companies Covered | Koito Manufacturing Co., Ltd., Valeo SA, HELLA GmbH & Co. KGaA, Marelli Holdings Co., Ltd., Stanley Electric Co., Ltd., ZKW Group, OSRAM GmbH, Hyundai Mobis, Aptiv PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Intelligent Lighting System Market Emerging Trajectories
Silicon-carbide power electronics and solid-state lidar fusion are rewriting the performance envelope for adaptive beam control, compressing the gap between premium and mass-market feature availability.
Micro-LED pixel arrays are fragmenting the incumbent matrix beam supplier landscape by enabling 25,000+ individually addressable light points per headlamp. Chinese EV startups are adopting these architectures faster than legacy European OEMs, collapsing the traditional five-year technology diffusion cycle into eighteen-month product refresh windows. The resulting supply base compression is forcing incumbent lighting integrators to acquire fabless semiconductor design capabilities or surrender specification control to chip vendors.
REACH substance restrictions on halogenated flame retardants in automotive electronics are accelerating substrate material transitions for LED driver modules. Tier 2 suppliers must requalify printed circuit board laminates and potting compounds under shortened compliance deadlines, with German KBA type-approval processes currently experiencing six-month backlog extensions. The regulatory friction disproportionately affects mid-volume lighting specialists lacking dedicated homologation teams.
Fleet procurement managers are unbundling lighting system warranties from vehicle powertrain coverage, creating standalone service contract markets. Commercial vehicle operators in North American long-haul segments now negotiate separate predictive maintenance agreements for adaptive headlamp calibration and pixel replacement. This consumption pattern shift concentrates margin capture with authorized service networks possessing optical alignment equipment, displacing independent repair shops from high-value lighting service revenue.
Automotive Intelligent Lighting System Market Segmentation
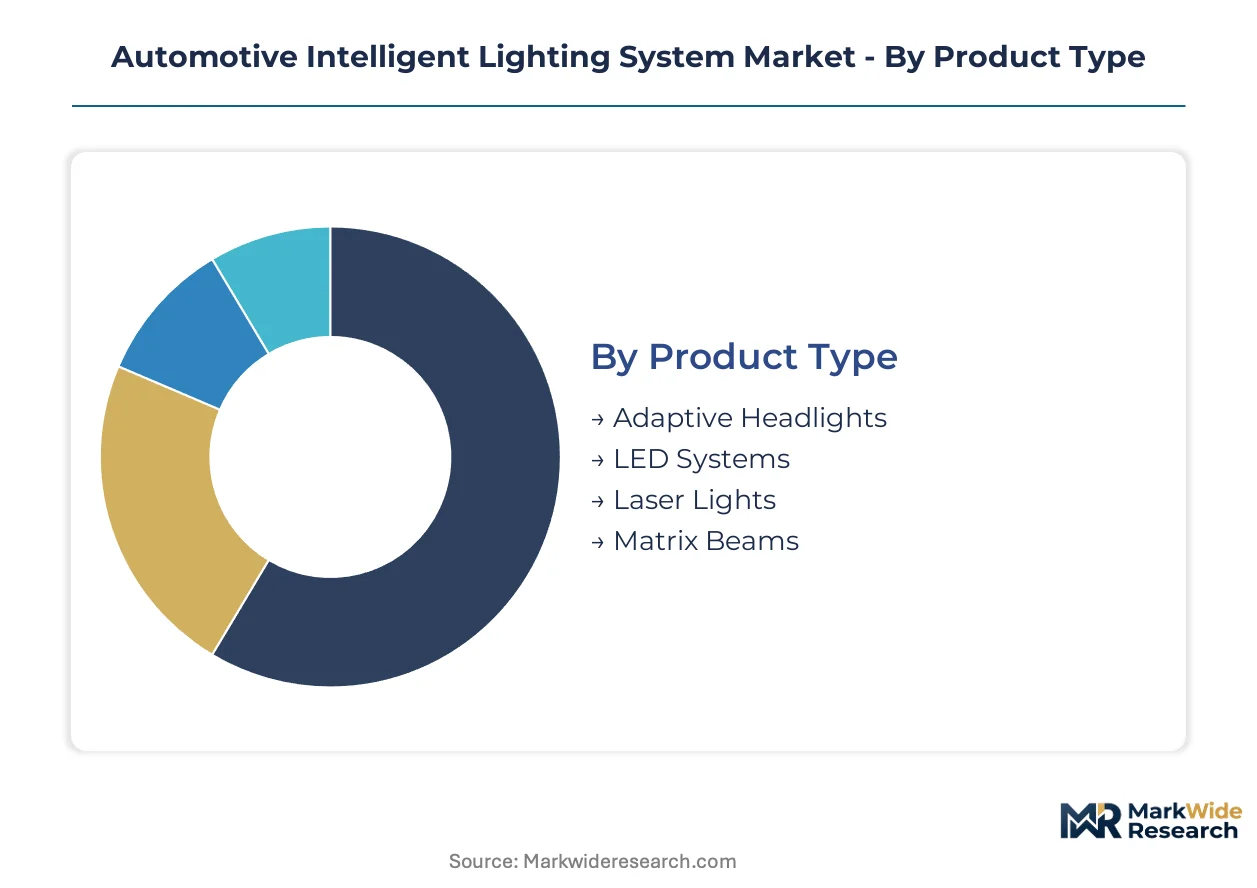
Intelligent lighting procurement patterns diverge sharply across vehicle electrification tiers and regulatory compliance thresholds. Segment-specific specification requirements determine whether suppliers compete on semiconductor integration depth or modular hardware economics.
Product Type:
Halogen-to-LED substitution pressure concentrates most intensely in entry-luxury vehicle classes where matrix beam availability now defines competitive parity.
- LED Systems:These assemblies leverage chip-on-board architectures and standardized driver electronics to achieve luminous efficacies above 130 lumens per watt. Procurement from German and Chinese EV platforms dominates volume, with NHTSA FMVSS 108 modernization accelerating US fleet conversions from static halogen units.
- Matrix Beams:Pixel-level beam control enables compliance with EU General Safety Regulation anti-dazzle mandates through 25,000+ individually addressable light points. Chinese EV startups adopt these architectures on 18-month refresh cycles, compressing traditional five-year technology diffusion timelines.
- Adaptive Headlights:Mechanically actuated modules with servo-driven levelling dominate mid-tier vehicle specifications.
- Laser Lights:High-luminance supplemental sources extend visibility range on premium German autobahn-configured vehicles.
LED Systems retain volume leadership; Matrix Beams hold the steepest expansion curve.
Technology:
Cost tier stratification separates vision-sensor fusion platforms from basic CAN-bus relay architectures.
- Smart Beam Control:Real-time sensor fusion algorithms process camera and radar inputs to predict road curvature and oncoming traffic position. Stuttgart and Nagoya engineering clusters concentrate specialized optical talent for these software-intensive implementations.
- IoT Integration:Cloud-connected lighting modules enable over-the-air calibration updates and predictive maintenance scheduling. Fleet operators in North American long-haul segments negotiate standalone service contracts for these capabilities.
- Networked Lighting:V2X communication protocols synchronize vehicle illumination with smart city infrastructure in German and South Korean deployment corridors.
- Vision Sensors:Solid-state lidar fusion with silicon-carbide power electronics rewrites performance envelopes for adaptive beam response latency.
Smart Beam Control commands premium pricing; IoT Integration is climbing the fastest.
End User:
Customer-type concentration favors captive Tier 1 integrators serving volume OEMs over independent aftermarket channels.
- Automakers:Premium passenger vehicle OEMs in Germany and the United States specify matrix beam and adaptive configurations as standard equipment. Bundled procurement with battery thermal management hardware creates consolidated production line economics.
- Original Equipment Manufacturers:Full-stack lighting integrators compete through in-house LED chip sourcing and optical design capabilities.
- Aftermarket Providers:Regulatory clarity on LED conversion kit compliance in select US states enables certified upgrade pathways for aging vehicle fleets.
- Vehicle Assemblers:Contract manufacturers serving emerging market OEMs seek cost-optimized adaptive headlamp modules under India's PLI scheme incentives.
Automakers drive specification intensity; Aftermarket Providers face the most regulatory fragmentation.
Application:
Application-level margin pools concentrate where aerodynamic integration creates bundled specification requirements.
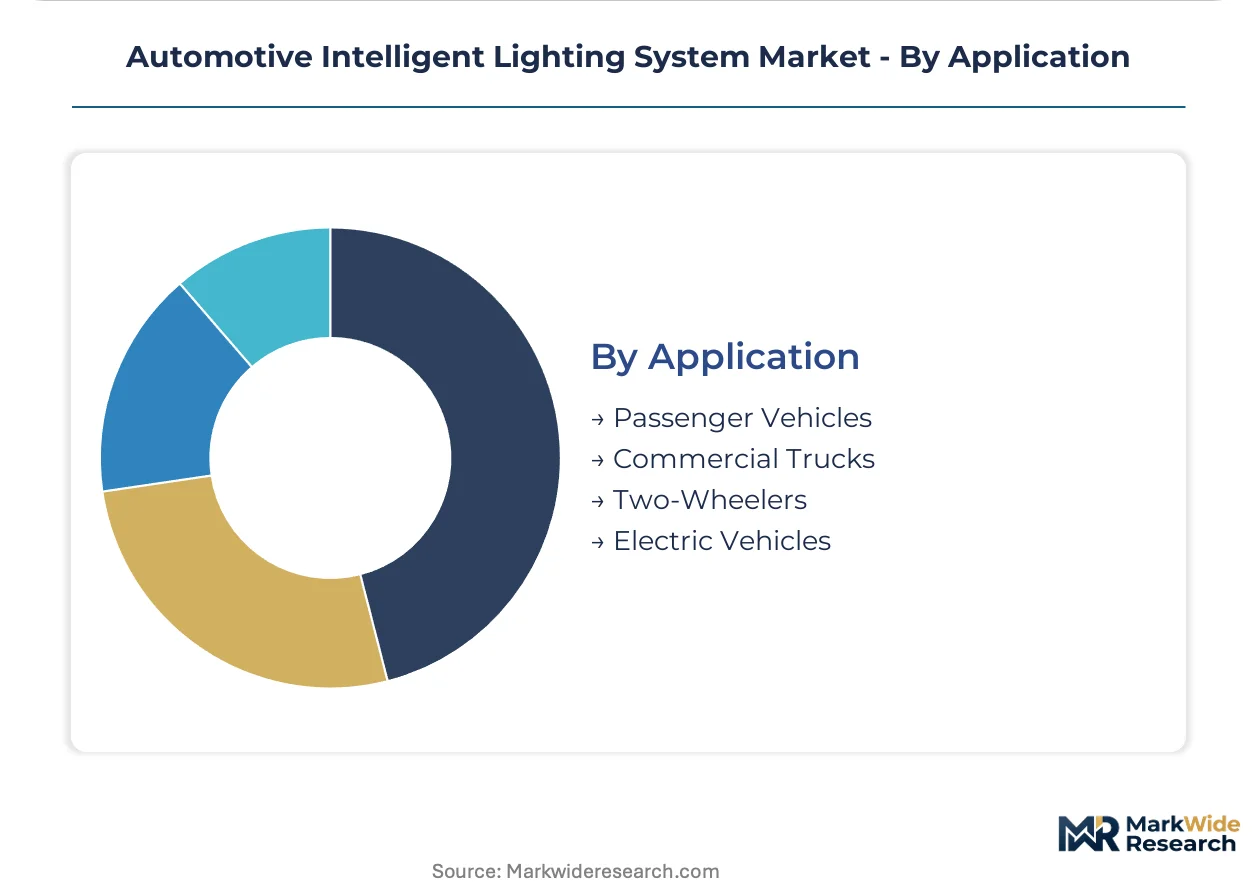
- Electric Vehicles:Battery platforms in China bundle slim-profile intelligent lighting with thermal management hardware. Dedicated production lines justify procurement volumes that mid-tier internal combustion vehicle programs cannot match.
- Passenger Vehicles:Premium configurations lead matrix beam adoption, with EU General Safety Regulation mandates eliminating conventional headlamp options from European product planning.
- Commercial Trucks:Fleet procurement managers unbundle lighting warranties from powertrain coverage, creating standalone predictive maintenance contract markets.
- Two-Wheelers:Cost-optimized LED modules serve high-volume emerging market production with simplified beam adjustment mechanisms.
Electric Vehicles capture the margin concentration; Passenger Vehicles maintain the installed base depth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics for automotive intelligent lighting systems tilt toward net importing positions in North American and European assembly markets, while East Asian production clusters generate surplus capacity directed at overseas OEM programs.
China
Domestic EV production scales drive procurement concentration for matrix beam modules in the Yangtze River Delta and Pearl River Delta corridors. SAMR-administered GB standards enforce electromagnetic compatibility testing that extends homologation timelines for foreign suppliers. Shenzhen and Shanghai host the densest clusters of LED driver module fabricators serving BYD, NIO, and XPeng vehicle programs.
Germany
Premium passenger vehicle OEMs specify adaptive headlight configurations as standard equipment across BMW, Mercedes-Benz, and Audi nameplates. KBA type-approval processes currently experience six-month backlog extensions for substrate material requalification under REACH substance restrictions. Stuttgart and Munich engineering clusters concentrate specialized optical talent for smart beam control algorithm development.
United States
NHTSA FMVSS 108 modernization proposals accelerate fleet migration from static halogen architectures to electronically controlled LED-matrix platforms. Michigan and Ohio assembly corridors generate concentrated demand for aftermarket retrofit channels serving aging commercial vehicle fleets. Detroit-area Tier 1 engineering centers coordinate specification alignment with domestic OEM product planning cycles.
Japan
Koito Manufacturing and Stanley Electric anchor captive supply relationships with Toyota, Honda, and Nissan vehicle programs. METI industrial policy supports domestic LED chip packaging capacity for matrix beam pixel driver production. Nagoya metro area engineering clusters specialize in precision lens design and thermal simulation expertise.
South Korea
Hyundai Mobis and Samsung LED affiliates supply integrated lighting-thermal management bundles for Hyundai-Kia EV platforms. MFDS regulatory alignment with UN ECE harmonized technical prescriptions reduces redundant homologation burdens for export-bound production. Busan-Ulsan industrial corridors concentrate module assembly capacity directed at North American and European markets.
Automotive Intelligent Lighting System Market Vendor Landscape
Concentration sits with full-stack lighting integrators possessing captive LED chip sourcing and in-house optical design capabilities. The vendor base stratifies across three tiers: semiconductor-backed integrators commanding premium matrix beam specifications, modular platform specialists reducing variant complexity for volume OEMs, and component suppliers feeding standardized LED driver electronics. Dominant competitive moves include backward integration into epitaxial wafer supply and technology licensing partnerships for pixel driver architectures.
Among Japanese- and European-based integrators, Koito Manufacturing Co., Ltd., Valeo SA, and HELLA GmbH & Co. KGaA exemplify contrasting strategic archetypes. Koito Manufacturing represents the captive supply model with integrated chip sourcing. Valeo SA anchors European OEM relationships through bundled software-hardware offerings. HELLA GmbH & Co. KGaA occupies the modular platform tier, competing on architecture flexibility that reduces automaker variant management burdens.
| Leading Market Players |
|---|
| Koito Manufacturing Co., Ltd. |
| Valeo SA |
| HELLA GmbH & Co. KGaA |
| Marelli Holdings Co., Ltd. |
| Stanley Electric Co., Ltd. |
| ZKW Group |
| OSRAM GmbH |
| Hyundai Mobis |
| Aptiv PLC |
| Others |
Supply Flow & Price Mechanics
NHTSA FMVSS 108 compliance thresholds gate both supplier qualification and price differentiation simultaneously. OEMs seeking adaptive driving beam certification face dual cost burdens: pixel driver hardware premiums and validation testing expenses that stratify procurement tiers. Matrix beam integrators leverage captive LED chip sourcing to defend margin structures against commoditization pressure from standardized LED module suppliers.
Pricing Analysis
Configured-to-order pricing for matrix beam modules commands substantial premiums over standard LED assemblies due to pixel-level calibration requirements and software customization. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale effects. Cost compression in mid-tier adaptive headlamp segments is intensifying because Chinese EV startups compress product refresh cycles. Fleet procurement managers demonstrate highest price sensitivity through unbundled warranty negotiations, while premium German OEMs show lowest sensitivity due to bundled thermal management specifications.
Supply Chain Analysis
Just-in-time inventory strategies dominate LED driver module fabrication, though strategic stockpiling of epitaxial wafers persists among matrix beam specialists managing East Asian supply concentration. Production clusters in China, Japan, and South Korea supply pixel driver semiconductors and optical components. Raw material dependencies include gallium nitride substrates, silicone potting compounds, and halogen-free PCB laminates. Single-source vulnerability for epitaxial wafer production creates structural risk during demand surges. Distribution runs through captive Tier 1 integrator channels serving OEM assembly corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive intelligent lighting demand tracks vehicle production cycles, with EV platform ramp-ups in China and Germany driving current recovery momentum. OEM specification intensity for matrix beam compliance creates countercyclical investment opportunities in semiconductor-backed lighting integrators.
For Market Incumbents: Fortify specification control through backward integration into fabless semiconductor design capabilities or risk surrendering pixel driver architecture decisions to chip vendors. Acquire specialized optical engineering talent concentrated in Stuttgart and Nagoya metro areas to defend algorithm development margins against software-centric entrants. Prioritize certification investment in SAMR GB standards compliance to reduce redundant homologation costs for China-bound production lines. For New Entrants and Emerging Players: Aftermarket retrofit certification gaps in select US states present white-space targets where legacy suppliers under-serve aging commercial vehicle fleets. India's PLI scheme incentives for domestic automotive electronics manufacturing offer the most penetrable geography for cost-optimized adaptive headlamp module production. Pursue direct fleet procurement relationships with predictive maintenance service contracts as the primary go-to-market angle. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across matrix beam semiconductor integration, favoring asset-light fabless designers over captive foundry operators. Long-term viability over the next decade rests on software-defined vehicle convergence and V2X infrastructure deployment. Target acquisition archetypes include fabless pixel driver specialists with automotive qualification and modular platform architects serving volume OEM variant reduction programs. Watch NHTSA FMVSS 108 final rule publication timing as the critical inflection signal for US market access premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into LED Chip Sourcing | Koito Manufacturing leverages captive supply to sustain matrix beam margin structures against commoditization. |
| Software-Hardware Bundle Development | Valeo SA anchors BMW and Mercedes-Benz relationships through integrated smart beam control platforms. |
| Modular Platform Architecture Investment | HELLA GmbH reduces automaker variant complexity through flexible hardware configurations across vehicle classes. |
| Fabless Semiconductor Design Acquisition | Incumbent integrators acquire pixel driver capabilities to retain specification control from chip vendors. |
| India PLI Scheme Manufacturing Alignment | Cost-optimized production pathways emerge for mid-tier adaptive headlamp modules serving emerging market OEMs. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of regulatory filings, vehicle production databases, and trade flow records. Primary interviews engaged Tier 1 supplier procurement directors, OEM platform engineers, aftermarket distributors, and semiconductor packaging specialists. Secondary validation drew from NHTSA rulemaking dockets, SAMR GB standard publications, KBA type-approval registers, and IHS Markit vehicle registration data. Bottom-up segment sizing triangulated against top-down macroeconomic demand indicators.
Segmentation dimensions modeled span product type, technology tier, end-user category, and application across vehicle propulsion architectures. Value projections incorporate content-per-vehicle trajectories for LED and matrix beam configurations. CAGRs derive from regression analysis of historical specification penetration rates and regulatory mandate implementation timelines. Forecast inputs include OEM platform launch schedules and EV production scaling assumptions across the analysis window.
Forecasts assume regulatory continuity in NHTSA FMVSS 108 modernization, EU General Safety Regulation enforcement, and SAMR GB standards administration; material policy shifts would require re-modeling. Technology substitution risks from micro-LED architectures and solid-state lidar fusion may accelerate diffusion timelines beyond baseline assumptions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Decorative Exterior Trim Market
Automotive Interior & Exterior
Auto Ventilated Seats Market
Automotive Interior & Exterior
Mexico Automotive Sunroof Market
Automotive Interior & Exterior
Automotive Panoramic Sunroof Market
Automotive Interior & Exterior
Automotive Automatic Liftgate Market
Automotive Interior & Exterior
Blind Spot Mirror Market
Automotive Interior & Exterior
Europe Automotive Interior Materials Market
Automotive Interior & Exterior
Automotive Air Purifier Market
Automotive Interior & Exterior
Capacitive Touch Switch Panels for Vehicle Interiors Market
Automotive Interior & Exterior
Automotive Sunroof Market
Automotive Interior & Exterior
Automotive Outside Rearview Mirrors (ORVM) Market
Automotive Interior & Exterior
Automotive Synthetic Leather Market
Automotive Interior & Exterior
Japan Automotive Flooring Market
Automotive Interior & Exterior
Automotive Air Suspension System Market
Automotive Interior & Exterior
Asia Pacific Automotive Interiors Market
Automotive Interior & Exterior
Automotive OEM Interior Coatings Market