
 Global Hazardous Location Motor Starters Market | 2026-2036
Global Hazardous Location Motor Starters Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hazardous Location Motor Starters Market Analysis
A shift from single-source to multi-source procurement for explosion-proof components is hardening across downstream project engineering. Siemens leverages its IECEx-certified manufacturing footprint in Europe to sustain long-term supply agreements with integrated oil majors. WEG competes aggressively on cost-engineered soft starters for Latin American mining conglomerates, while Rockwell Automation differentiates through digital integration of its motor protection platforms into plant-wide control architectures.
Hazardous location motor starters are electromechanical switching devices rated for Class I Division 1 or Zone 0/1 environments, typically housed in cast aluminum or stainless steel enclosures with flame-path designs that contain internal explosions without igniting surrounding atmospheres. Their primary purpose is to safely start, stop, and protect induction motors in facilities where flammable gases, vapors, or combustible dusts persist. Soft starters command premium positioning in oil and gas applications where torque control limits mechanical stress on downhole pumps and compressor trains. Variable frequency drives represent the fastest-expanding technology segment as operators retrofit fixed-speed installations for energy recovery in offshore platforms and refineries.
The IECEx scheme administered through the IEC governs international equipment certification for explosive atmospheres, while the EU ATEX Directive 2014/34/EU mandates conformity assessment procedures for products sold within European member states; China's GB 3836 standards enforced by the national standardization authority impose additional testing protocols for imports into its chemical processing zones. In the United States, OSHA's hazardous location classifications under 29 CFR 1910.307 and NEMA enclosure type specifications shape procurement criteria for domestic petrochemical and pharmaceutical facilities. Stakeholders must monitor divergence between regional certification reciprocity agreements and emerging digital protocol requirements as smart motor starters gain hazardous area deployment.
Market Dynamics
Explosion-proof motor starters face intensifying specification pressure as IECEx and ATEX certification reciprocity fragments across regional enforcement regimes, forcing manufacturers to maintain parallel testing protocols for identical equipment classes.
Growth Catalysts
- Upstream Oil and Gas Expansion:Offshore platform electrification and shale processing facility upgrades in the United States and China require Zone 1-rated soft starters for compressor and pump motor control.
- ATEX Directive Harmonization:EU member states are tightening conformity assessment timelines, compelling petrochemical operators to accelerate replacement cycles for legacy motor protection equipment.
- Variable Frequency Drive Retrofit Cycles:Energy recovery mandates in German refineries and Chinese chemical processing zones are accelerating fixed-speed to variable-speed conversions in hazardous areas.
Market Restraints
- Cast Aluminum Input Volatility:Flame-path enclosure manufacturing depends on specialized aluminum alloys whose pricing fluctuates with primary metal commodity markets and foundry capacity constraints.
- Certification Body Concentration:IECEx testing laboratory capacity concentrates in Western Europe, creating bottlenecks for Asian manufacturers seeking international market access.
- Variable Frequency Drive Substitution:Integrated VFD packages with built-in motor protection are capturing share in Zone 2 applications where full explosion-proof starter enclosures represent over-engineering.
Strategic Opportunities
- Indian Chemical Processing Corridor:Gujarat and Maharashtra industrial zones under BIS enforcement are expanding specialty chemical capacity with limited indigenous hazardous location equipment supply.
- Digital Protocol Convergence:Integration of Ethernet-APL physical layer with traditional motor protection relays enables predictive maintenance in Saudi Aramco and ADNOC processing facilities.
- EU Green Deal Industrial Funding:Carbon border adjustment mechanism preparatory investments are channeling capital into energy-efficient motor system retrofits across Rotterdam and Antwerp refining clusters.
Industry Challenges
- IECEx Scheme Interpretation Variance:National differences in explosive atmosphere classification between IEC Zone systems and North American Class/Division frameworks complicate unified product platform strategies.
- Legacy Control System Integration:Brownfield petrochemical sites in the US Gulf Coast and German Ruhr region operate 4-20mA analog infrastructure that resists seamless adoption of smart starter digital architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hazardous Location Motor Starters Market |
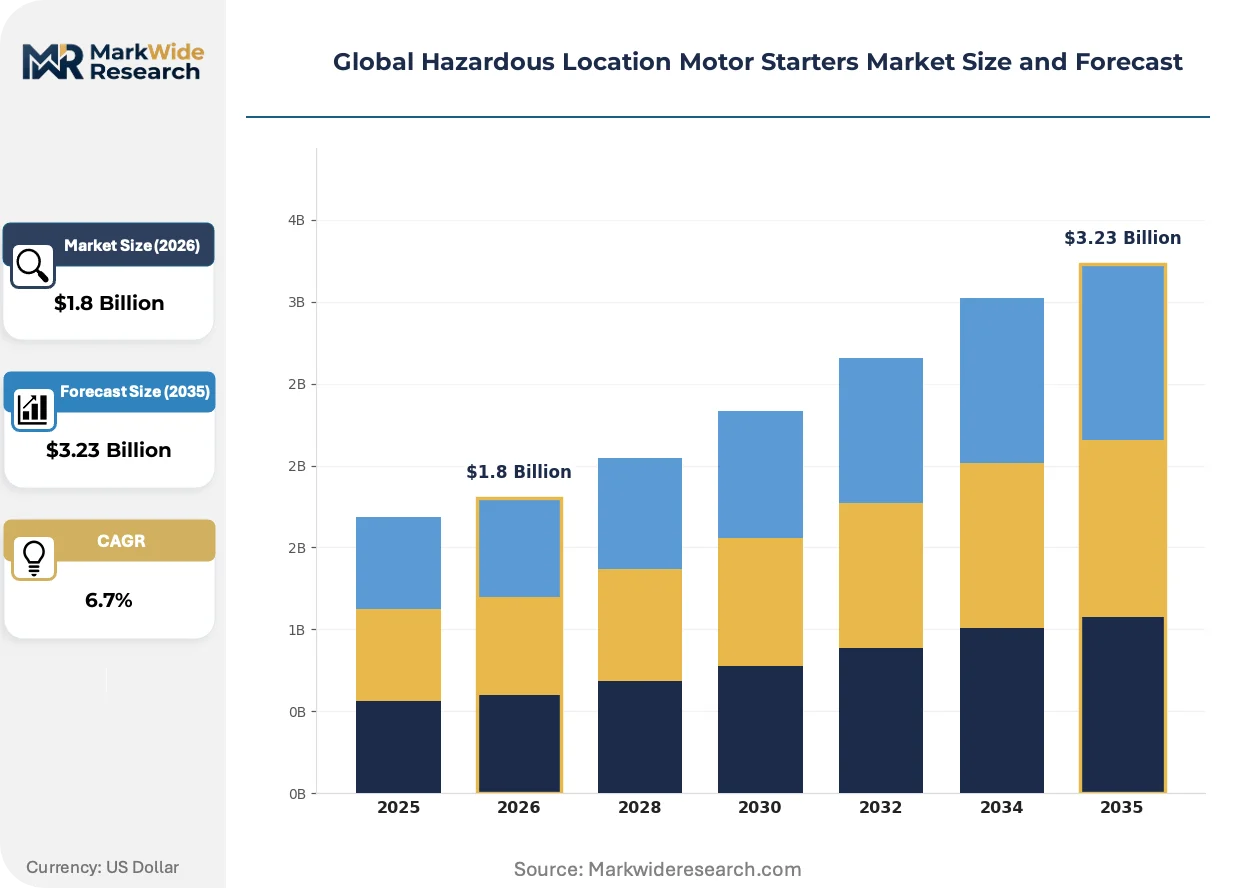
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soft Starters, Direct-On-Line Starters, Variable Frequency Drives, Motor Protection Starters End User: Oil & Gas, Chemical, Mining, Pharmaceuticals Installation: Indoor, Outdoor, Ex Hazardous Areas, Non-Hazardous Areas Technology: Electromechanical, Digital, Smart Control, Analog |
| Companies Covered | ABB, Schneider Electric, Siemens, Eaton Corporation, Rockwell Automation, WEG, Emerson Electric, Mitsubishi Electric, General Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hazardous Location Motor Starters Market Emerging Trajectories
Digital integration of motor protection functions with plant-wide control architectures is compressing the traditional boundary between discrete starters and distributed control systems, reshaping supplier value capture models.
Silicon carbide power semiconductors are absorbing thermal management burdens in explosion-proof enclosures where traditional IGBT modules require excessive heat-sinking volume. Offshore platform operators in the North Sea and Gulf of Mexico are piloting these devices for subsea pump control. The technology is absorbing space constraints that previously limited starter ratings in compact flame-path housings.
China's GB 3836 standard revisions are mandating enhanced dust-ignition protection testing for Zone 21 applications, extending certification timelines for European and Japanese manufacturers. Chemical processing facilities in the Yangtze River Delta are delaying procurement decisions pending clarity on enforcement commencement. Mining operators in Shanxi Province face immediate compliance deadlines for underground coal handling equipment.
Asset-as-a-service contracting is displacing capital purchase models for large compressor train installations in Middle Eastern gas processing. Engineering procurement contractors in Abu Dhabi and Qatar are unbundling starter hardware from long-term maintenance and performance guarantees. This reconfiguration concentrates vendor risk in operational uptime commitments rather than equipment delivery.
Global Hazardous Location Motor Starters Market Segmentation
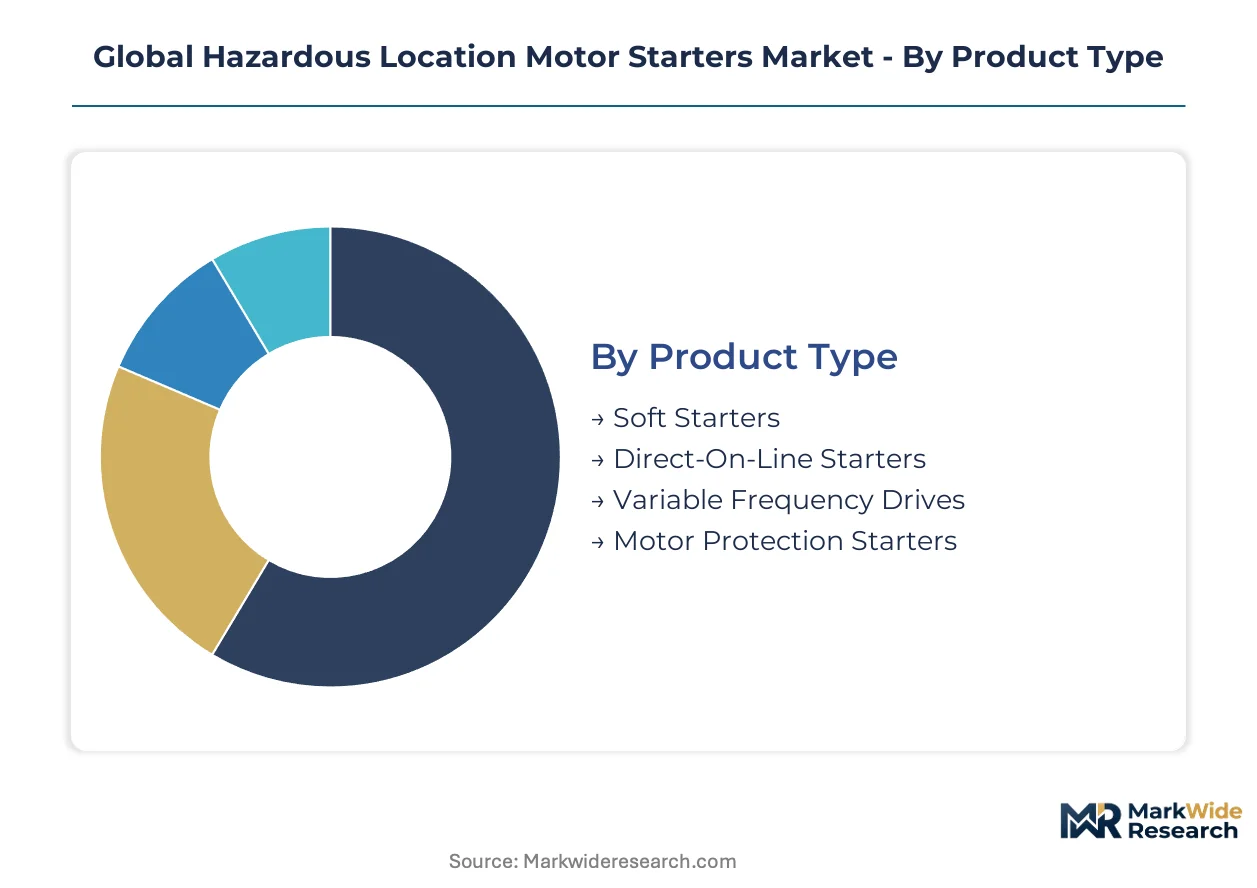
Segmentation in hazardous location motor starters reflects divergent certification requirements and operational constraints across explosive atmosphere classifications. Product specifications vary sharply between Zone 0/1 and Zone 2 deployments, while end-use economics drive technology selection between electromechanical reliability and digital predictive capabilities.
Product Type:
Technology specifications determine enclosure engineering, thermal management, and protection integration depth.
- Soft Starters:Solid-state devices using thyristor-based voltage ramping to limit inrush current and mechanical torque shock. Oil and gas operators in the United States deploy these for downhole pump protection where torque control extends equipment life in sour gas environments.
- Variable Frequency Drives:Power electronics platforms enabling precise motor speed control with integrated energy recovery. German refineries and Chinese chemical processing zones are retrofitting fixed-speed installations with VFD packages to meet carbon efficiency mandates.
- Direct-On-Line Starters:Simple electromechanical contactor assemblies providing full-voltage motor starting. Mining operations in Australia and South Africa favor these for conveyor belt drives where cost minimization outweighs energy optimization.
- Motor Protection Starters:Integrated overload and fault protection modules with thermal and electronic trip mechanisms. Pharmaceutical cleanrooms in Switzerland and Germany specify these for batch process reliability under cGMP protocols.
Soft starters lead on scale; variable frequency drives lead on momentum.
End User:
Application environments dictate certification tier, enclosure material, and maintenance access design.
- Oil & Gas:Upstream drilling platforms and midstream compression stations requiring Zone 1 explosion-proof ratings with stainless steel flame-path housings. Offshore operators in the Gulf of Mexico and North Sea prioritize corrosion resistance in salt-laden atmospheres.
- Chemical:Petrochemical crackers and specialty chemical reactors with flammable vapor exposure. Rotterdam and Antwerp refining clusters are accelerating starter replacement cycles under EU Green Deal industrial funding timelines.
- Mining:Underground coal handling and surface mineral processing with combustible dust hazards. Shanxi Province coal operators face immediate GB 3836 compliance deadlines for Zone 21 equipment certification.
- Pharmaceuticals:Solvent-handling suites and API manufacturing suites with hybrid cleanroom-explosion protection requirements. FDA-regulated facilities in New Jersey and Puerto Rico specify washdown-compatible enclosures.
Oil and gas commands the largest procurement volumes; chemical processing shows the steepest specification tightening.
Installation:
Physical deployment context shapes ingress protection ratings, thermal dissipation pathways, and accessibility for maintenance.
- Ex Hazardous Areas:Zone 0/1 and Zone 21 installations mandating flame-path or increased safety enclosures with IECEx/ATEX certification. Offshore platforms in Brazil and Norway concentrate procurement here due to permanent hydrocarbon vapor presence.
- Indoor:Climate-controlled electrical rooms with controlled atmosphere access. German automotive paint shops and Japanese semiconductor fabs specify these for solvent vapor zones with mechanical ventilation.
- Outdoor:Exposed installations requiring IP66+ ratings and UV-resistant gasketing. Middle Eastern gas processing facilities in Qatar and Saudi Arabia demand these for desert temperature cycling extremes.
- Non-Hazardous Areas:General purpose industrial environments without explosive atmosphere classification. These support auxiliary systems in integrated petrochemical complexes where hazardous and safe zones intermix.
Ex hazardous areas concentrate premium pricing; indoor installations dominate unit volumes.
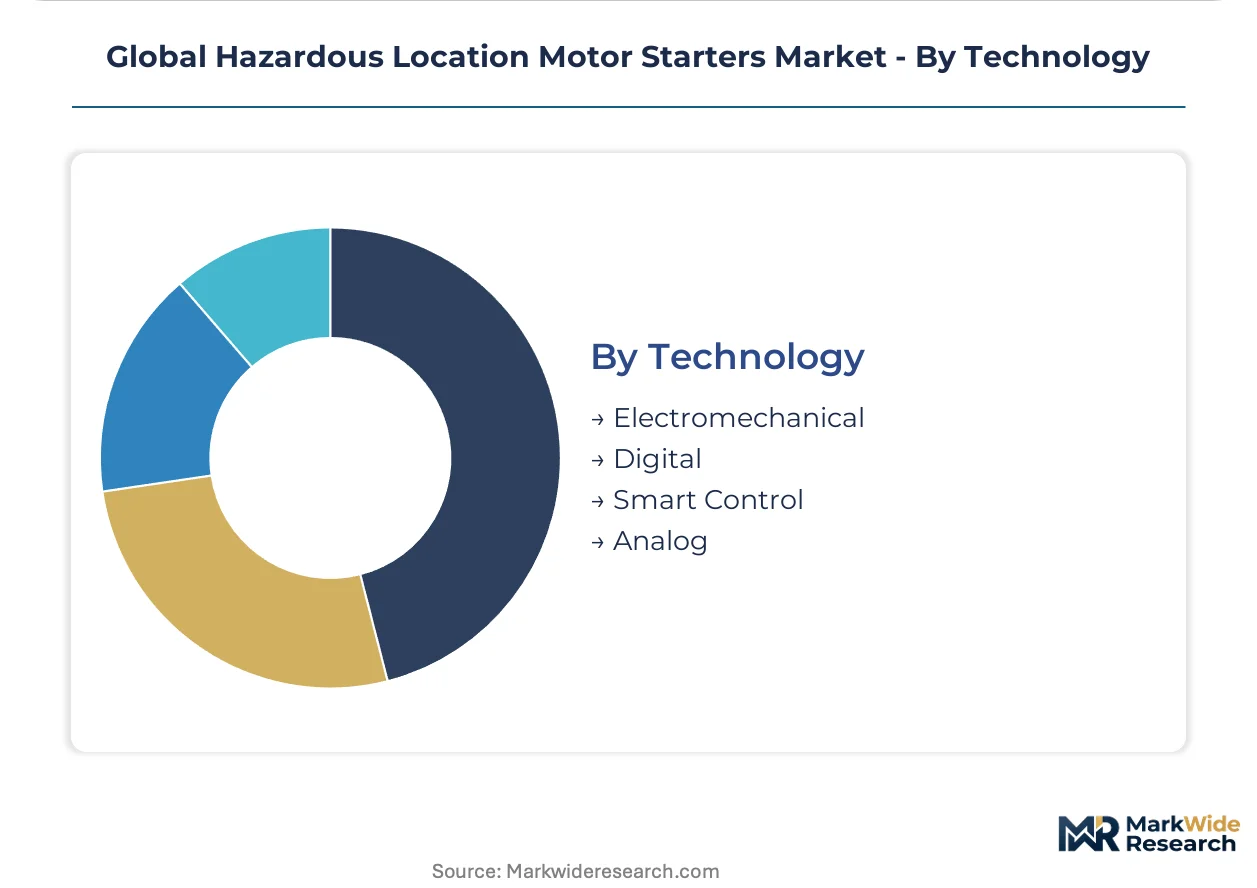
Technology:
Control architecture maturity determines integration depth with plant-wide automation and predictive maintenance capabilities.
- Electromechanical:Relay-based control circuits with discrete contactor logic and bimetallic overload protection. Legacy brownfield sites in the US Gulf Coast maintain these for compatibility with 4-20mA analog infrastructure.
- Smart Control:Ethernet-APL enabled platforms with embedded condition monitoring and cloud connectivity. Saudi Aramco and ADNOC processing facilities are piloting these for predictive maintenance in rotating equipment.
- Digital:Microprocessor-based protection relays with programmable trip curves and event logging. These bridge legacy and modern architectures in European refinery retrofit projects.
- Analog:Pneumatic or basic electronic control without digital communication protocols. Declining share except in cost-constrained mining operations in Latin America and Africa.
Electromechanical retains installed base dominance; smart control platforms are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Gulf Coast petrochemical corridor concentrates the largest procurement volumes for Zone 1 explosion-proof motor starters. German refining clusters and Chinese chemical processing zones are accelerating replacement cycles under tightening certification mandates.
United States
Offshore platform electrification in the Gulf of Mexico and Permian Basin shale processing facilities drive demand for stainless steel flame-path housings. OSHA's 29 CFR 1910.307 hazardous location classifications shape procurement criteria for domestic petrochemical operators. Houston and Beaumont refining clusters are retrofitting fixed-speed compressor installations with soft starter packages.
Germany
Rotterdam and Antwerp refining complexes channel EU Green Deal industrial funding into energy-efficient motor system retrofits. The EU ATEX Directive 2014/34/EU mandates accelerated conformity assessment timelines for legacy equipment replacement. Ruhr region brownfield sites resist seamless adoption of smart starter digital architectures due to 4-20mA analog infrastructure.
China
Yangtze River Delta chemical processing zones expand specialty chemical capacity with Zone 21 dust-ignition protection requirements. GB 3836 standard revisions enforced by the national standardization authority extend certification timelines for import equipment. Shanxi Province coal operators face immediate compliance deadlines for underground coal handling equipment.
Saudi Arabia
Abu Dhabi and Qatar gas processing facilities pilot Ethernet-APL enabled platforms for predictive maintenance in rotating equipment. Asset-as-a-service contracting displaces capital purchase models for large compressor train installations. Engineering procurement contractors unbundle starter hardware from long-term maintenance and performance guarantees.
Brazil
Offshore platform operators in the North Sea and Gulf of Mexico pilot silicon carbide power semiconductors for subsea pump control. Latin American mining conglomerates procure cost-engineered soft starters for surface mineral processing operations. Petrobras pre-salt development programs specify Zone 1-rated equipment for floating production facilities.
Global Hazardous Location Motor Starters Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue digital integration and predictive maintenance capabilities. The vendor base stratifies across three tiers: diversified electrical conglomerates with IECEx-certified manufacturing footprints, regional specialists competing on cost-engineered solutions, and automation platforms integrating motor protection into plant-wide control architectures. Strategic moves concentrate on certification body partnerships to bypass IECEx testing laboratory bottlenecks and on silicon carbide semiconductor sourcing for compact flame-path thermal management.
Within the diversified electrical tier, ABB and Schneider Electric occupy positions spanning electromechanical reliability and digital predictive capabilities. Siemens anchors the European manufacturing vector with long-term supply agreements tied to IECEx-certified production facilities. Rockwell Automation exemplifies the automation-integrated archetype, embedding motor protection platforms into distributed control system architectures for plant-wide visibility.
| Leading Market Players |
|---|
| ABB |
| Schneider Electric |
| Siemens |
| Eaton Corporation |
| Rockwell Automation |
| WEG |
| Emerson Electric |
| Mitsubishi Electric |
| General Electric |
| Others |
Supply Flow & Price Mechanics
Sovereign-backed producers in China and family-owned mid-caps in Germany anchor supply-side discipline, translating certification bottlenecks into sustained pricing power for IECEx-validated equipment while cost-engineered alternatives face margin compression from aluminum alloy volatility.
Pricing Analysis
Cast aluminum alloy pass-through from commodity markets shapes tiered pricing across certification grades. Premium IECEx/ATEX dual-certified units command substantial markups over single-certification equivalents, while standard-grade soft starters face price erosion from integrated VFD substitution in Zone 2 applications. Mining operators in Latin America exhibit highest price sensitivity, prioritizing cost-engineered direct-on-line starters over torque-controlled alternatives.
Supply Chain Analysis
Dual-sourcing requirements from integrated oil majors mandate parallel qualification of European and Asian manufacturers, fragmenting procurement concentration. Foundry capacity in Germany, China, and Italy feeds flame-path enclosure production, with specialized silicon carbide semiconductors sourcing from Japan and the United States. Tariff exposure on aluminum alloys creates margin vulnerability for cast-component suppliers. Distribution runs through engineering procurement contractors with bundled maintenance obligations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in digital-integrated premium tiers, where Ethernet-APL enabled platforms capture value from predictive maintenance contracts while electromechanical legacy segments face cost-down pressure from semiconductor thermal management advances.
For Market Incumbents: Anticipate VFD substitution threats by deepening certification moats around Zone 0/1 applications where flame-path enclosures remain non-negotiable. Prioritize IECEx testing laboratory partnerships to bypass capacity bottlenecks for Asian market access. Anchor long-term supply agreements with ADNOC and Saudi Aramco through asset-as-a-service contracting models that shift revenue toward operational uptime guarantees. For New Entrants and Emerging Players: Mid-tier chemical processors in Gujarat and Maharashtra industrial zones offer penetrable entry points with limited indigenous hazardous location equipment supply. Target BIS compliance pathways ahead of GB 3836 enforcement clarity to preempt European and Japanese incumbent certification delays. Lead with cost-engineered soft starter platforms for surface mining operations where Zone 21 dust-ignition requirements are newly mandated. For Investors and Strategic Acquirers: Valuations sit cheapest among electromechanical specialists with captive foundry capacity and dormant IECEx certification assets. Five-to-ten year viability favors vendors with backward integration into aluminum alloy sourcing and forward integration into digital protocol stacks. Monitor silicon carbide semiconductor sourcing agreements as inflection indicators for thermal management leadership in compact explosion-proof housings.| Strategic Initiative | Industry Significance |
|---|---|
| IECEx Testing Laboratory Partnership | Bypasses Western European capacity bottlenecks for Asian manufacturers seeking international market access. |
| Silicon Carbide Semiconductor Integration | Absorbs thermal management burdens in compact flame-path enclosures for subsea pump control applications. |
| Asset-as-a-Service Contracting | Concentrates vendor risk in operational uptime commitments for Abu Dhabi and Qatar gas processing facilities. |
| Ethernet-APL Protocol Convergence | Enables predictive maintenance integration in Saudi Aramco and ADNOC rotating equipment installations. |
| GB 3836 Compliance Prepositioning | Captures procurement delays from European and Japanese manufacturers facing extended Zone 21 certification timelines. |
Methodological Framework
Multiple input streams — primary interviews with plant engineers and maintenance directors, OEM procurement teams, and aftermarket service heads; secondary validation through customs/trade data, SEC filings, and IECEx certification registries; and technical documentation from NEMA and GB standards authorities — were reconciled through bottom-up and top-down triangulation to construct segment-level estimates.
Historical shipment patterns were cross-referenced against panel input from engineering procurement contractors to anchor growth trajectories across the projection horizon. Segmentation dimensions modeled include product type, explosive atmosphere classification tier, end-use industry, and regional certification reciprocity status. CAGRs were derived from slope analysis of replacement cycle intensities and retrofit penetration curves, with specific weighting applied to EU Green Deal funding disbursement timelines and China's dual carbon policy enforcement phases.
Underlying measurement precision varies by segment; electromechanical installed base estimates carry tighter precision than emerging smart control platform projections. Forecasts reflect assumptions about certification body capacity expansion, aluminum alloy price stability, and VFD substitution elasticity in Zone 2 applications. Deviation in IECEx scheme interpretation harmonization would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Power Equipment
Electrodialysis System Market
Electrical Power Equipment
Alternating Current (AC) Electric Drives Market
Electrical Power Equipment
Marine Switchboard Market
Electrical Power Equipment
Busbar Protection Market
Electrical Power Equipment
Middle East and Africa Hazardous Location Motor Starters Market
Electrical Power Equipment
Recloser Market
Electrical Power Equipment
HV Bushing Market
Electrical Power Equipment
North America Oil Filled Electric Heaters Market
Electrical Power Equipment
Instant Water Heater Market
Electrical Power Equipment
High Voltage Direct Current (HVDC) Cables Market
Electrical Power Equipment
Domestic Hot Water (DHW) Tanks Market
Electrical Power Equipment
Electric Substation Market
Electrical Power Equipment
North America Protective Relays Market
Electrical Power Equipment
India Instrument Transformer Market
Electrical Power Equipment
Unitary Heaters Market
Electrical Power Equipment
Electric Submersible Pump Cable Market