
 Unitary Heaters Market | 2026-2036
Unitary Heaters Market Size, Share, and Industry Trends Forecast 2026-2036
Unitary Heaters Market Analytics
Service-layer contracting for predictive maintenance and remote diagnostics is hardening into a core revenue stream alongside hardware sales. Carrier Global leverages its digital platform to anchor long-term customer relationships through performance-based service agreements. Johnson Controls International plc sustains R&D intensity in building automation integration, while Trane Technologies plc competes on geographic dominance across North American distribution channels.
Unitary heaters are self-contained heating systems integrating combustion or electric elements with blowers and controls in a single cabinet, typically rated between 5 kW and 150 kW output for direct space conditioning. Gas-fired configurations dominate commercial installations where natural gas infrastructure exists, while electric heaters occupy niches in emissions-restricted zones and smaller-footprint buildings. Heat pumps represent the fastest-growing product category as cold-climate performance thresholds improve, though hydronic heaters retain margin pools in industrial process applications. Infrared technology leads installation-type flexibility, with ceiling-mounted configurations gaining share in warehouse and agricultural end uses where floor space carries premium value.
EPA efficiency standards under the National Appliance Energy Conservation Act shape minimum performance thresholds for gas and electric units sold in the United States. DOE test procedures and ASHRAE 90.1 building code compliance determine market access for commercial-specification products. Stakeholders must monitor refrigerant transition timelines and cold-climate heat pump certification pathways as regulatory and technological cycles converge on replacement-driven procurement decisions.
Market Dynamics
The EPA's phasedown of hydrofluorocarbons under the AIM Act is compressing refrigerant transition timelines and forcing heat pump manufacturers to accelerate R&D cycles. Cold-chain logistics expansion and aging commercial HVAC replacement cycles in the United States are simultaneously pulling demand toward higher-efficiency unitary configurations.
Growth Catalysts
- Warehouse automation:Cold-storage facilities and distribution centers are expanding climate-controlled footprints, driving procurement of high-capacity gas-fired and infrared unitary systems for large-volume spaces.
- AIM Act compliance:The EPA's hydrofluorocarbon phasedown mandates refrigerant transitions that favor next-generation heat pump architectures with lower-GWP working fluids.
- Heat pump cold-climate performance:Advances in variable-speed compressors and defrost algorithms are extending operational range into northern US heating zones previously served by fossil-fuel equipment.
Market Restraints
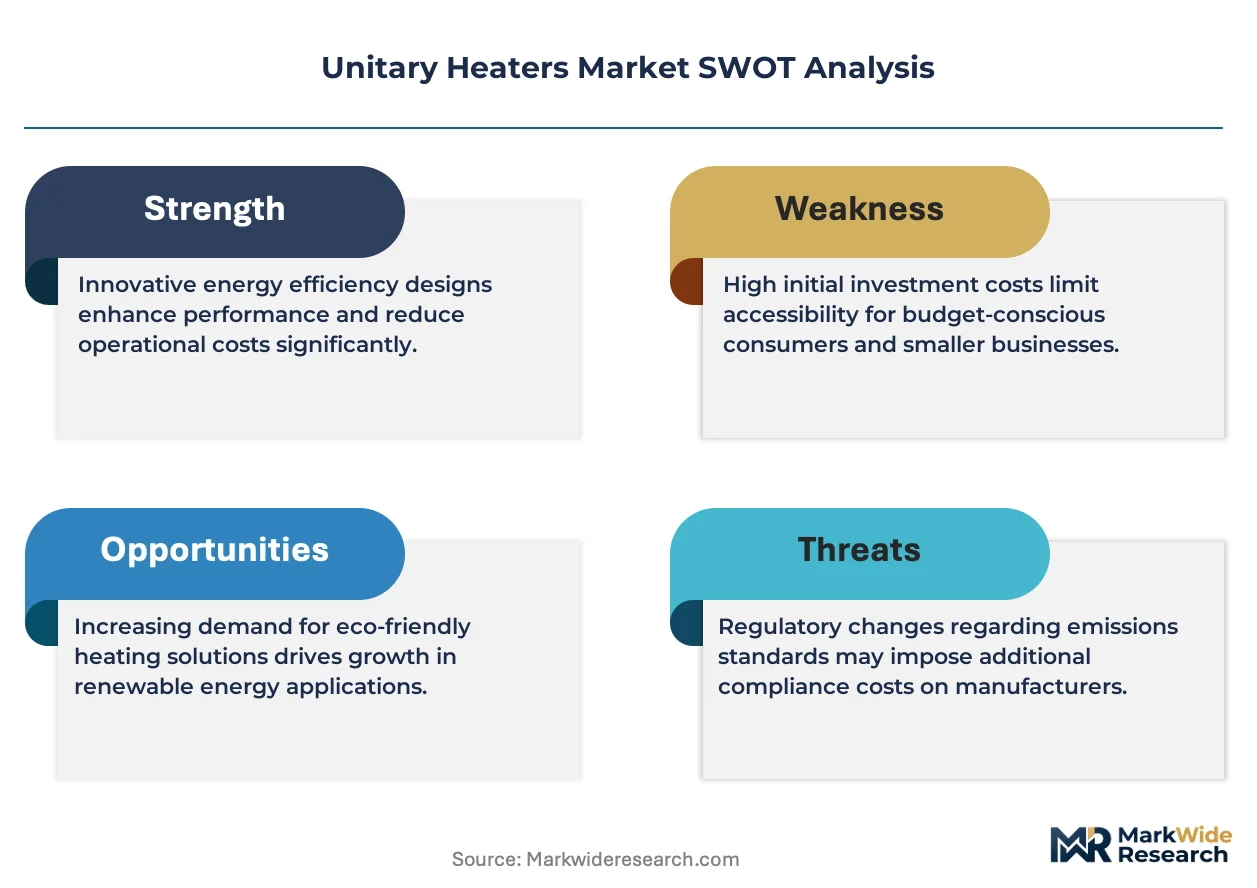
- Copper and steel input volatility:Raw material price swings in commodity metals compress margins for cabinet and heat exchanger fabrication, particularly affecting mid-tier manufacturers without captive supply.
- Natural gas infrastructure lock-in:Existing pipeline networks in the US Midwest and Northeast create switching costs that slow electrification transitions in commercial retrofit applications.
- Refrigerant supply concentration:Production of low-GWP alternatives concentrates among a limited set of chemical suppliers, creating bottleneck risk during scale-up phases.
Strategic Opportunities
- Service-layer digitization:Predictive maintenance platforms and remote diagnostics are opening recurring revenue streams that extend customer lifetime value beyond initial hardware sales.
- Agricultural climate control:Controlled-environment agriculture and vertical farming installations represent underpenetrated demand for infrared and hydronic unitary heaters in greenhouse and livestock applications.
- Building automation convergence:Integration with BACnet and IoT-enabled energy management systems creates specification advantages in smart building retrofits and new construction.
Industry Challenges
- Cold-climate heat pump certification:Northeast Energy Efficiency Partnership and DOE test procedure updates are compressing product validation timelines, requiring parallel engineering and regulatory submission tracks.
- Legacy control system interoperability:Retrofit installations must bridge proprietary protocols from incumbent HVAC brands, extending commissioning cycles and field service costs.
- Skilled technician scarcity:Refrigerant handling certification and combustion safety training gaps in the US contractor base are constraining installation capacity during peak replacement seasons.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Unitary Heaters Market |
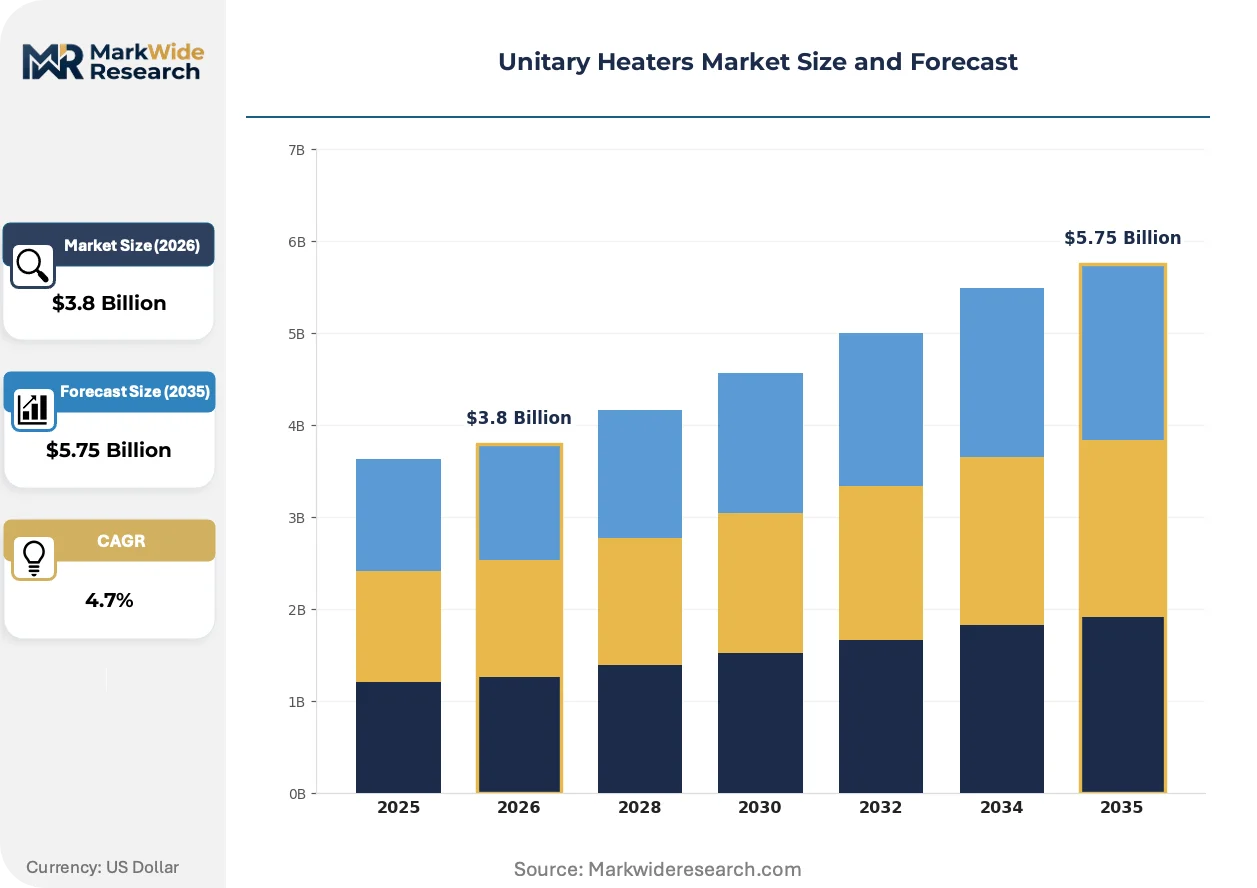
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Heaters, Gas Heaters, Hydronic Heaters, Heat Pumps Technology: Infrared, Convection, Radiant, Forced Air End User: Residential, Commercial, Industrial, Agricultural Installation Type: Wall-mounted, Ceiling-mounted, Portable, Window-mounted |
| Companies Covered | Trane Technologies plc, Carrier Global, Modine Manufacturing Company, Mestek Inc., Johnson Controls International plc, Reznor LLC, Sterling HVAC, Turbonics, Inc., Lennox International, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Unitary Heaters Market Evolving Landscape
Refrigerant chemistry, control system architecture, and procurement contracting models are converging to reshape competitive positioning. Equipment vendors are racing to align product roadmaps with regulatory deadlines while capturing value from connected service ecosystems.
Variable-capacity heat pumps with enhanced vapor injection are overtaking single-stage systems in commercial specification channels. Cold-climate performance thresholds now satisfy design conditions in Minneapolis, Denver, and Boston without auxiliary resistance heat. This capability compression is collapsing the historical geographic boundary between heat pump viability and fossil-fuel dominance in the US market.
The EPA's Technology Transitions Program under the AIM Act is mandating sector-specific GWP limits that phase down through 2028. Heat pump manufacturers must certify equipment with A2L refrigerants or natural alternatives to maintain market access. The transition imposes capital intensity disproportionately on smaller fabricators lacking in-house chemical engineering resources.
Performance-based service agreements are displacing transactional maintenance contracts in multi-site commercial portfolios. Facility managers at retail chains and logistics operators are bundling equipment, installation, and energy outcome guarantees into single-vendor relationships. This contracting evolution concentrates procurement authority with national account teams at the expense of regional distributor networks.
Unitary Heaters Market Segmentation

Unitary heater procurement patterns diverge sharply across thermal source, heat distribution method, and mounting configuration. Specification decisions cascade from building envelope constraints, fuel infrastructure availability, and occupancy thermal profiles rather than pure equipment cost.
Product Type:
Thermal source selection determines efficiency ceiling, emissions profile, and operational cost structure for facility managers.
- Electric Heaters:Resistance-element or electrode boilers packaged with air-handling components deliver precise zone control without combustion ventilation requirements. Demand clusters in California and New York metro areas where building electrification mandates and carbon pricing accelerate displacement of fossil-fuel equipment.
- Gas Heaters:Condensing and non-condensing configurations burning natural gas or propane dominate warehouse and big-box retail installations across Texas, Ohio, and Illinois where pipeline infrastructure minimizes fuel cost volatility. EPA furnace efficiency standards under NAECA shape minimum AFUE thresholds for commercial-specification units.
- Hydronic Heaters:Boilers paired with unitary air handlers serve industrial process loads and perimeter heating in legacy buildings with existing hot-water distribution.
- Heat Pumps:Vapor-compression systems with auxiliary resistance elements are climbing the fastest as cold-climate performance thresholds improve.
Mature deployment sits with Gas Heaters. Newer deployment is concentrated in Heat Pumps.
Technology:
Heat transfer mechanism selection trades installation flexibility against thermal comfort uniformity and energy recovery potential.
- Infrared:Gas-fired or electric radiant panels target occupants and surfaces directly without air-mixing energy losses. Ceiling-mounted configurations capture dominant share in Minnesota and Wisconsin dairy operations and Michigan automotive assembly plants where floor space carries premium value and air stratification is acceptable.
- Forced Air:Centrifugal blowers distribute conditioned air through ductwork with fastest response to thermostat setbacks. Commercial office buildings in Florida and Georgia specify variable-speed ECM motors to meet ASHRAE 90.1 fan power limitations.
- Convection:Passive or fan-assisted natural circulation suits small-footprint retail and residential applications with minimal ductwork.
- Radiant:Embedded tubing or panel systems deliver uniform surface temperatures for healthcare and educational facilities prioritizing acoustic comfort.
Mature deployment sits with Forced Air. Newer deployment is concentrated in Infrared.
End User:
Occupancy patterns and thermal load profiles dictate capacity sizing, control granularity, and redundancy requirements.
- Commercial:Multi-zone office buildings, retail chains, and hospitality properties drive specification of networked controls and demand-responsive sequences. Procurement concentrates in Sun Belt states where cooling-dominant climates extend heat pump operating hours.
- Industrial:Manufacturing floors and process facilities require explosion-rated enclosures and washdown-compatible finishes in food processing corridors.
- Agricultural:Greenhouse and livestock operations in Iowa and Nebraska are expanding infrared and hydronic installations for controlled-environment production.
- Residential:Single-family and multifamily dwellings specify compact cabinet dimensions and quiet operation for basement or attic mounting.
Mature deployment sits with Commercial. Newer deployment is concentrated in Agricultural.
Installation Type:
Mounting configuration resolves spatial constraints, maintenance access, and architectural integration priorities.
- Ceiling-mounted:Suspended gas-fired unit heaters and infrared radiant panels maximize floor clearance in distribution centers. Amazon and Walmart fulfillment networks in Pennsylvania and Indiana standardize on 30-foot mounting heights for forklift navigation.
- Wall-mounted:Through-the-wall packaged terminals serve hotel and senior living retrofits where central plant replacement is cost-prohibitive.
- Portable:Plug-in electric units address temporary construction heating and emergency redundancy.
- Window-mounted:Packaged terminal air conditioners with heat pump reversal occupy legacy multifamily stock with limited exterior wall penetration options.
Mature deployment sits with Wall-mounted. Newer deployment is concentrated in Ceiling-mounted.

Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity clusters in the United States and Germany while procurement demand spreads across North American logistics corridors and European retrofit markets. Production concentration in these hubs contrasts with consumption dispersion across warehouse districts and agricultural zones.
United States
Cold-chain logistics expansion in Pennsylvania and Indiana drives ceiling-mounted unitary procurement for fulfillment centers. The EPA's AIM Act refrigerant phasedown compresses heat pump certification timelines for 2028 compliance. Dallas-Fort Worth anchors gas-fired heater demand as warehouse construction accelerates across Texas.
Germany
Commercial building retrofit cycles in North Rhine-Westphalia pull demand for condensing gas and electric heat pump configurations. The EU F-Gas Regulation mandates low-GWP refrigerant transitions that reshape product portfolios. Bavarian industrial zones concentrate hydronic heater installations for process heating applications.
Canada
Cold-climate heat pump deployment spreads through Ontario and Quebec as performance thresholds satisfy sub-zero design conditions. Natural Resources Canada's energy efficiency regulations tighten minimum performance standards for commercial equipment. Toronto's commercial real estate sector shortens HVAC replacement cycles in aging office stock.
China
Manufacturing capacity for heat exchangers and compressor assemblies concentrates in Jiangsu and Zhejiang provinces. The MIIT energy efficiency labeling program drives domestic market consolidation around higher-AFUE products. Yangtze River Delta industrial parks expand unitary heater adoption for climate-controlled production facilities.
United Kingdom
Building electrification mandates in England accelerate displacement of fossil-fuel heating in commercial properties. The UK's Future Buildings Standard sets performance benchmarks that favor heat pump and high-efficiency electric configurations. Midlands logistics corridors expand infrared and gas-fired installations for distribution centers.
Unitary Heaters Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across differentiated technology layers. The vendor base organizes into three tiers: integrated HVAC conglomerates with captive distribution, specialized heating equipment fabricators, and regional assembly operations serving single-country markets. Dominant competitive moves include backward integration into heat exchanger manufacturing and strategic partnerships with building automation platforms.
Among US-based conglomerates, Trane Technologies plc and Carrier Global occupy positions emphasizing geographic coverage across North American distribution channels. Johnson Controls International plc represents the building automation integration archetype, anchoring specification influence through control system convergence. These three entities exemplify how scale-driven manufacturers defend margin pools through service-layer digitization and long-term performance contracting.
| Leading Market Players |
|---|
| Trane Technologies plc |
| Carrier Global |
| Modine Manufacturing Company |
| Mestek Inc. |
| Johnson Controls International plc |
| Reznor LLC |
| Sterling HVAC |
| Turbonics, Inc. |
| Lennox International, Inc. |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up specialists in commercial HVAC components enforce pricing discipline through captive heat exchanger fabrication and long-term service contract anchoring, compressing margin pools for asset-light assemblers dependent on spot-market metals procurement.
Pricing Analysis
Margin tightening in mid-tier equipment reflects copper and steel input volatility without captive supply hedging. Three-tier pricing structure across premium, standard, and economy levels separates UL-certified cold-climate heat pumps from baseline gas-fired units and unbranded imports. Price differentiation hinges on AFUE certification tier and after-sales service bundling. Price-sensitive buyers cluster in agricultural and small-footprint commercial segments where capital constraints dominate specification.
Supply Chain Analysis
Welding technician scarcity in Ohio and Indiana manufacturing corridors constrains cabinet and heat exchanger throughput for domestic fabricators. Production gravity centers on the United States, China, and Germany for compressor assemblies and control module integration. Raw material dependencies span copper tubing, cold-rolled steel, and A2L refrigerant formulations from concentrated chemical suppliers. Single-source vulnerability in low-GWP refrigerant production creates bottleneck risk during EPA-mandated transition phases. Distribution runs through national account teams at integrated HVAC conglomerates and regional distributor networks serving contractor installers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Unitary Heaters Market operates as a cost-of-compliance story where EPA AIM Act refrigerant mandates erect barrier-to-entry moats favoring capitalized incumbents with in-house chemical engineering and certification resources.
For Market Incumbents: Deepen backward integration into heat exchanger manufacturing to offset copper price volatility and compress mid-tier competitor margins. Anchor specification influence through BACnet-integrated control platforms that extend replacement-cycle lock-in. Threat substitution from cold-climate heat pumps accelerates as variable-speed compressor performance thresholds improve, demanding parallel R&D investment in fossil-fuel efficiency to defend installed base. For New Entrants and Emerging Players: Launch via direct-to-facility-manager digital channels bypassing incumbent distributor relationships in agricultural climate control and controlled-environment agriculture verticals. White-space concentration sits with infrared and hydronic configurations for greenhouse and livestock operations in Iowa and Nebraska where specification authority fragments across independent growers. Go-to-market positioning emphasizes rapid commissioning and modular capacity scaling against legacy centralized systems. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional assembly operations with EPA refrigerant certification progress and established contractor installer relationships in Sun Belt warehouse construction corridors. Long-term viability hinges on service-layer digitization platforms capturing recurring revenue beyond transactional equipment sales. Signal to watch: Northeast Energy Efficiency Partnership cold-climate heat pump certification velocity as inflection indicator for electrification transition pace.| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Transition Certification | EPA AIM Act compliance secures market access against 2028 GWP limits. |
| Service-Layer Digitization | Predictive maintenance platforms extend customer lifetime value at Carrier Global and Trane Technologies. |
| Cold-Climate Heat Pump R&D | Variable-speed compressor advances collapse geographic boundaries for heat pump viability in Minneapolis and Boston. |
| Backward Integration | In-house heat exchanger production buffers copper volatility for Modine Manufacturing and Mestek. |
| Agricultural Segment Expansion | Infrared and hydronic configurations capture controlled-environment agriculture demand in Iowa dairy operations. |
Research Methodology
Document review covered EPA regulatory filings, DOE efficiency standard updates, and ASHRAE 90.1 code documentation, complemented by interviews with commercial HVAC contractors, facility maintenance directors, and distributor procurement leads. Secondary validation drew from SEC 10-K disclosures, utility rebate program databases, and refrigeration industry trade publications. Bottom-up equipment shipment analysis triangulated against top-down building stock replacement modeling.
Cross-referencing historical AFUE efficiency adoption curves with panel input from OEM product managers and energy efficiency program administrators shaped projection parameters. Segmentation modeling spanned thermal source, heat distribution technology, mounting configuration, and end-use application across the analysis window. CAGR derivation incorporated equipment replacement cycle compression, refrigerant transition timelines, and cold-climate performance threshold improvements.
Refrigerant supply disruption, copper price volatility spikes, and skilled technician training bottlenecks are the dominant revision risks to shipment and revenue trajectories. Forecasts embed assumptions around EPA enforcement consistency and utility rebate program continuity. Material deviation in named triggers warrants pause and re-evaluation of capacity expansion and certification investment timing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Power Equipment
Residential Air Insulated Power Distribution Component Market
Electrical Power Equipment
HVDC Converter Station Market
Electrical Power Equipment
Electric Radiators Market
Electrical Power Equipment
South America Gas Insulated Switchgear Market
Electrical Power Equipment
Global Lightning Arrester Market
Electrical Power Equipment
India Instrument Transformer Market
Electrical Power Equipment
Global Electric Power Substation Automation Market
Electrical Power Equipment
Solar Combiner Boxes Market
Electrical Power Equipment
Global Duct Heaters Market
Electrical Power Equipment
Asia Pacific Gas Insulated Switchgear Market
Electrical Power Equipment
Subsea Cables Equipment Market
Electrical Power Equipment
AV Power Conditioners Market
Electrical Power Equipment
Electrodialysis System Market
Electrical Power Equipment
Hollow Core Insulator Market
Electrical Power Equipment
Taiwan Electric Power Equipment Market
Electrical Power Equipment
Alternators Market