
 Latin America Hazardous Location Motor Starters Market | 2026-2036
Latin America Hazardous Location Motor Starters Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Hazardous Location Motor Starters Market Foresight
IECEx equipment certification is unwinding the competitive landscape across Latin America, forcing distributors and integrators to rebuild supplier portfolios around qualified sources. Siemens leverages its global testing infrastructure to sustain IECEx and INMETRO dual certifications for Brazilian offshore platforms. WEG anchors regional manufacturing through its captive motor and starter production in Jaraguá do Sul, competing on lead time against imported assemblies. Schneider Electric differentiates through digital starter architectures that integrate with EcoStruxure platforms deployed at Pemex refineries.
Hazardous location motor starters are electromechanical or solid-state switching devices engineered to contain internal arc faults and prevent ignition of explosive atmospheres in Class I Division 1 or Zone 1 environments, typically constructed with cast aluminum or stainless steel enclosures rated IP66 or higher and sealed to contain pressures during fault conditions. Their primary purpose is to safely initiate, protect, and control motor loads in hydrocarbon processing, underground mining, and chemical manufacturing where flammable gases or combustible dusts persist. Direct-On-Line Starters dominate volume in legacy oilfield infrastructure across Venezuela and Colombia, though Variable Frequency Drives capture margin pools as Mexican chemical processors retrofit for energy efficiency. Electromechanical technology still occupies the majority of installed base, but Digital starter adoption accelerates where remote diagnostics and predictive maintenance reduce downtime in offshore Brazilian production.
Brazil's INMETRO Ordinance 179 and Mexico's NOM-027-ENER constrain market access for uncertified equipment, while IECEx 02 equipment certification streamlines cross-border trade between Mercosur and Andean Community members. ANP technical regulations for offshore safety systems in Brazil and ASEA hydrocarbon sector standards in Mexico further tighten enclosure and sealing requirements for subsea and platform applications. Stakeholders must monitor convergence between INMETRO's emerging digital equipment certification pathway and IECEx's operational document revisions to anticipate qualification cost shifts.
Market Dynamics
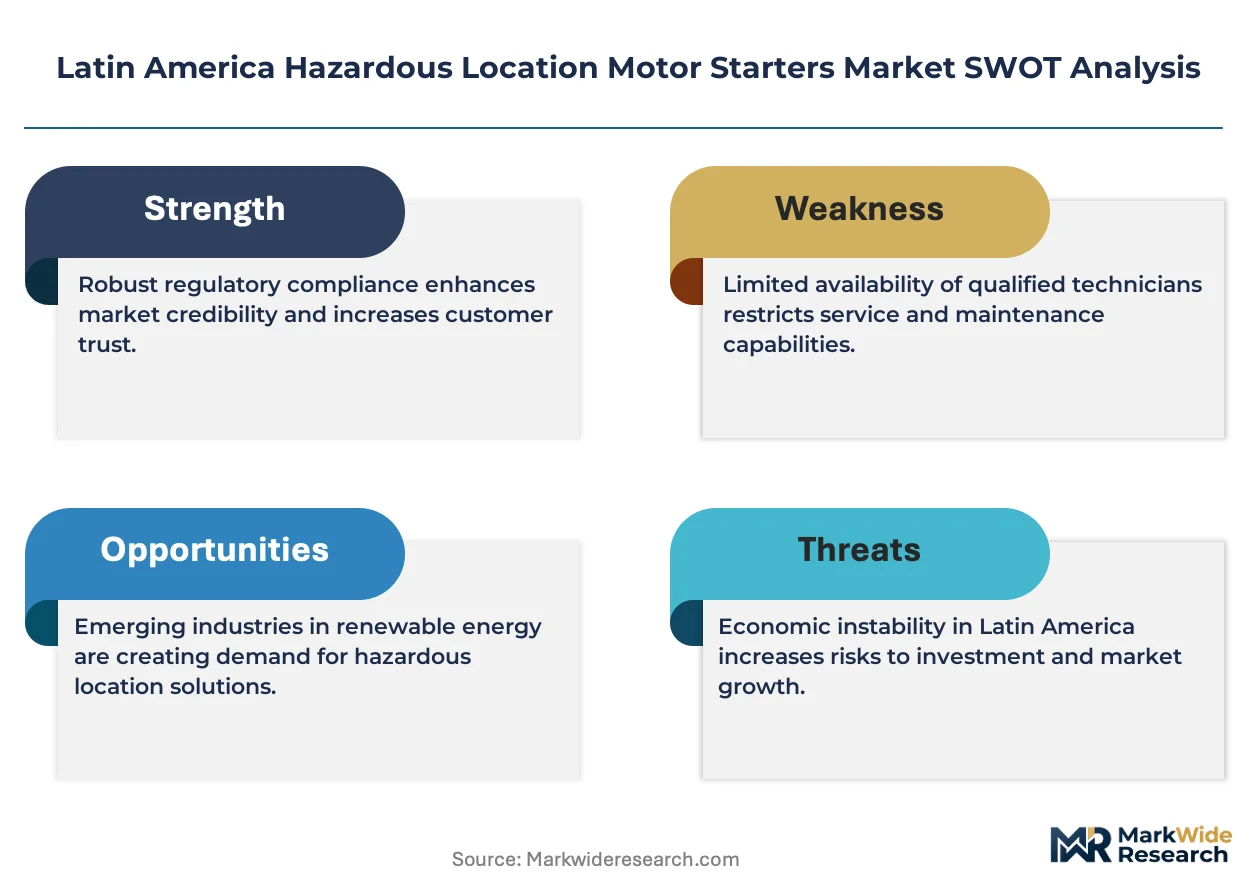
IECEx and INMETRO certification convergence is forcing equipment suppliers to rebuild qualification pipelines, compressing the supplier base while elevating compliance costs for distributors serving Brazil's offshore pre-salt developments and Mexico's petrochemical corridors.
Growth Catalysts
- Offshore pre-salt expansion:Brazil's ANP technical regulations mandate explosion-proof motor control systems for platform safety systems, sustaining procurement volumes from Petrobras and international operators drilling in the Santos Basin.
- Energy efficiency retrofit mandates:Mexico's NOM-027-ENER standards compel chemical processors to replace electromechanical starters with variable frequency drives, creating replacement demand across Pemex refining complexes.
- Digital predictive maintenance:Solid-state starters with integrated condition monitoring are penetrating offshore Brazilian production, where unplanned downtime costs justify premium equipment spend.
Market Restraints
- Cast aluminum enclosure volatility:Raw material price swings for explosion-rated housings compress margins for regional fabricators serving Andean mining operations.
- Dual certification burden:INMETRO Ordinance 179 and parallel IECEx 02 requirements force redundant testing cycles, extending time-to-market for new product introductions.
- Electromechanical installed base longevity:Legacy Direct-On-Line Starters in Venezuelan and Colombian oilfields exhibit operational lifespans exceeding twenty years, delaying replacement cycles.
Strategic Opportunities
- Underpenetrated Andean mining:Peruvian and Chilean underground copper operations present white space for Zone 1 certified starters as safety standards tighten.
- EcoStruxure platform integration:Digital starter architectures converging with industrial IoT backbones enable recurring software revenue streams from refinery automation upgrades.
- INMETRO digital certification pathway:Emerging regulatory frameworks for software-defined motor control create first-mover advantage for suppliers with embedded cybersecurity credentials.
Industry Challenges
- IECEx operational document revision lag:Evolving certification standards for functional safety create uncertainty in product roadmaps and qualification timelines.
- Subsea sealing expertise scarcity:Specialized engineering talent for IP66+ enclosure design concentrates in southern Brazil, constraining regional expansion capacity.
- Legacy electromechanical integration:Retrofitting digital starters into existing motor control centers requires custom adapter engineering, complicating project execution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Hazardous Location Motor Starters Market |
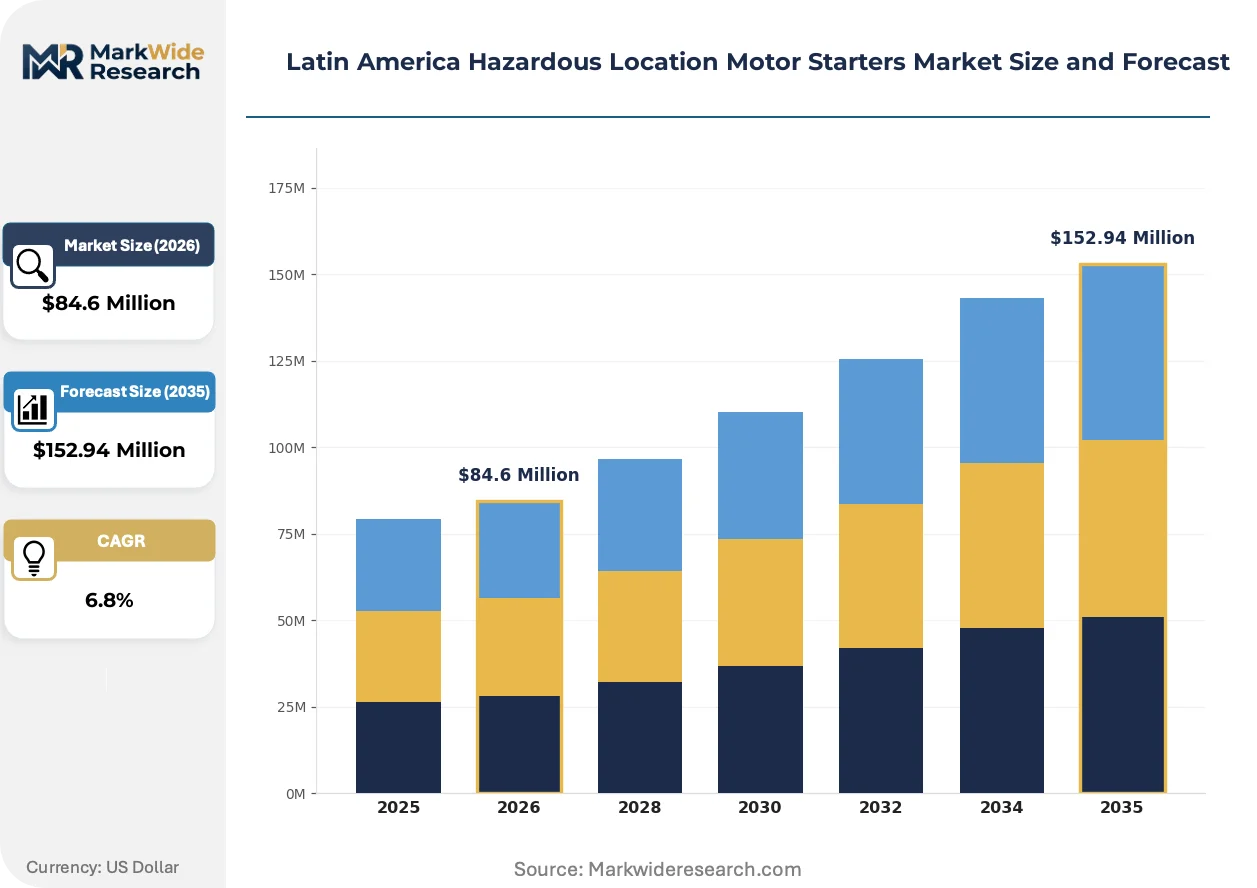
| Market Size in 2026 | $84.6 Million |
| Market Size in 2035 | $152.94 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Direct-On-Line Starters, Starters with Safety Features, Variable Frequency Drives, Soft Starters Technology: Electromechanical, Digital, Pneumatic, Hydraulic End User: Oil & Gas, Mining, Chemical Processing, Pharmaceutical Installation: Wall-Mounted, Rack-Mounted, Floor-Mounted, Portable |
| Companies Covered | Siemens, Hubbell, Schneider Electric, Crouse-Hinds, WEG, ABB, Rockwell Automation, GE Vernova, Eaton, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Hazardous Location Motor Starters Market Shifts & Advancements
Explosion-proof motor control is pivoting from passive containment to active intelligence, with solid-state switching and embedded diagnostics compressing equipment footprints while elevating functional safety performance in hydrocarbon processing environments.
Solid-state contactors employing silicon carbide power semiconductors are miniaturizing hazardous location starter enclosures, enabling higher power density in platform space-constrained electrical rooms. Brazilian offshore operators are specifying these compact units for subsea tieback projects where deck footprint carries premium cost. The technology is miniaturizing traditional cast aluminum housings by thirty percent while maintaining Zone 1 pressure containment ratings.
INMETRO's emerging digital equipment certification pathway is converging with IECEx operational document revisions, creating a unified qualification framework for software-enabled motor starters. This regulatory harmonization reduces redundant testing costs for suppliers serving both Brazilian and broader Mercosur markets. Mexican petrochemical operators are accelerating procurement of pre-certified digital architectures to preempt compliance deadlines.
Refinery maintenance departments are unbundling after-sales service contracts from equipment procurement, engaging third-party technical service providers for starter commissioning and predictive diagnostics. This channel shift disrupts traditional manufacturer-captive service models, particularly visible across Pemex refining complexes where budget constraints favor specialized local integrators. Brazilian platform operators are piloting similar unbundling for offshore electrical maintenance.
Latin America Hazardous Location Motor Starters Market Segmentation
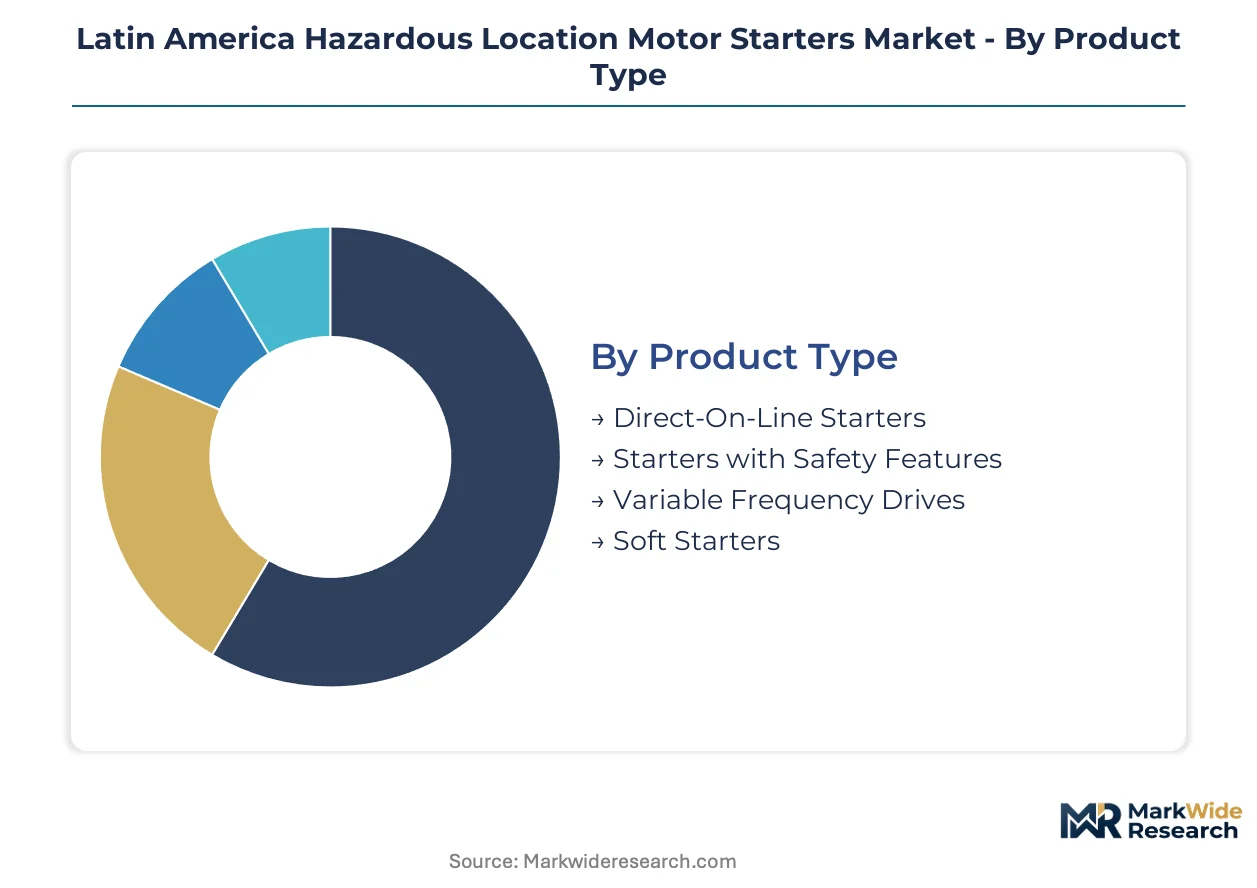
Segmentation in hazardous location motor starters reveals how certification requirements, enclosure specifications, and control architectures diverge across Latin American hydrocarbon and mining operations. Procurement patterns in Brazil's pre-salt basins and Mexico's petrochemical corridors concentrate demand in specific product configurations.
Product Type:
INMETRO Ordinance 179 and IECEx 02 certification tiers create distinct equipment qualification pathways, with explosion-proof ratings and pressure containment specifications determining market access for each starter category.
- Direct-On-Line Starters:Electromechanical switching devices with cast aluminum enclosures rated for Zone 1 pressure containment dominate legacy oilfield infrastructure across Venezuela and Colombia. Petrobras maintenance contracts sustain replacement volumes for these units in Brazilian offshore platforms where twenty-year operational lifespans delay technology refresh cycles.
- Variable Frequency Drives:Solid-state motor control with integrated power electronics enables energy efficiency compliance under Mexico's NOM-027-ENER standards. Pemex refining complexes are retrofitting electromechanical starters with these drives to meet mandated consumption reductions, creating concentrated demand in Veracruz and Tula corridors.
- Starters with Safety Features:Units incorporating emergency stop circuits and arc flash containment meet ANP technical regulations for offshore safety systems.
- Soft Starters:Reduced-voltage starting equipment minimizes mechanical stress on large induction motors in Chilean copper concentrators.
Direct-On-Line Starters handles the majority of throughput; Variable Frequency Drives is the fastest mover on share.
Technology:
Cost tiers separate mature electromechanical platforms from premium digital architectures, with pneumatic and hydraulic alternatives occupying specialized niches in underground and subsea applications.
- Electromechanical:Magnetic contactors and thermal overload relays constructed with silver-alloy contacts and bimetallic strips retain dominant installed base across Andean mining operations. Colombian coal processors continue specifying these units for their field-service simplicity and tolerance to voltage fluctuation in remote grid conditions.
- Digital:Microprocessor-controlled starters with embedded condition monitoring and Modbus connectivity command premium positioning in Brazilian offshore production. Solid-state switching with silicon carbide semiconductors enables predictive maintenance protocols that justify equipment spend against unplanned downtime costs in Santos Basin tieback projects.
- Pneumatic:Compressed-air actuated control systems operate in gassy underground environments where electrical spark ignition risks mandate intrinsic safety.
- Hydraulic:Fluid-power motor control serves subsea wellhead applications requiring pressure-compensated operation at depth.
Electromechanical retains the largest installed footprint; Digital is expanding most quickly as offshore operators prioritize remote diagnostics.
End User:
Application severity and safety regulation intensity concentrate procurement in hydrocarbon processing, with mining and chemical sectors following distinct specification patterns.
- Oil & Gas:Explosion-proof motor control for drilling rigs, production platforms, and pipeline compression stations constitutes the largest demand pool. Brazil's ANP regulations and Mexico's ASEA standards mandate IECEx-certified equipment for Class I Division 1 environments, with subsea and platform applications requiring IP66+ sealing and pressure-rated enclosures.
- Mining:Underground copper and coal operations in Peru, Chile, and Colombia specify Zone 1 certified starters for ventilation-limited headings. Dust ignition protection and flameproof enclosures dominate procurement as safety standards tighten across Andean Community members.
- Chemical Processing:Pemex petrochemical complexes and Brazilian fertilizer producers require corrosion-resistant enclosures for aggressive atmospheres.
- Pharmaceutical:Cleanroom-compatible hazardous location control occupies limited volume in Mexico City and São Paulo manufacturing clusters.
Oil & Gas commands the dominant procurement volume; Mining is gaining share fastest as Peruvian and Chilean safety enforcement intensifies.
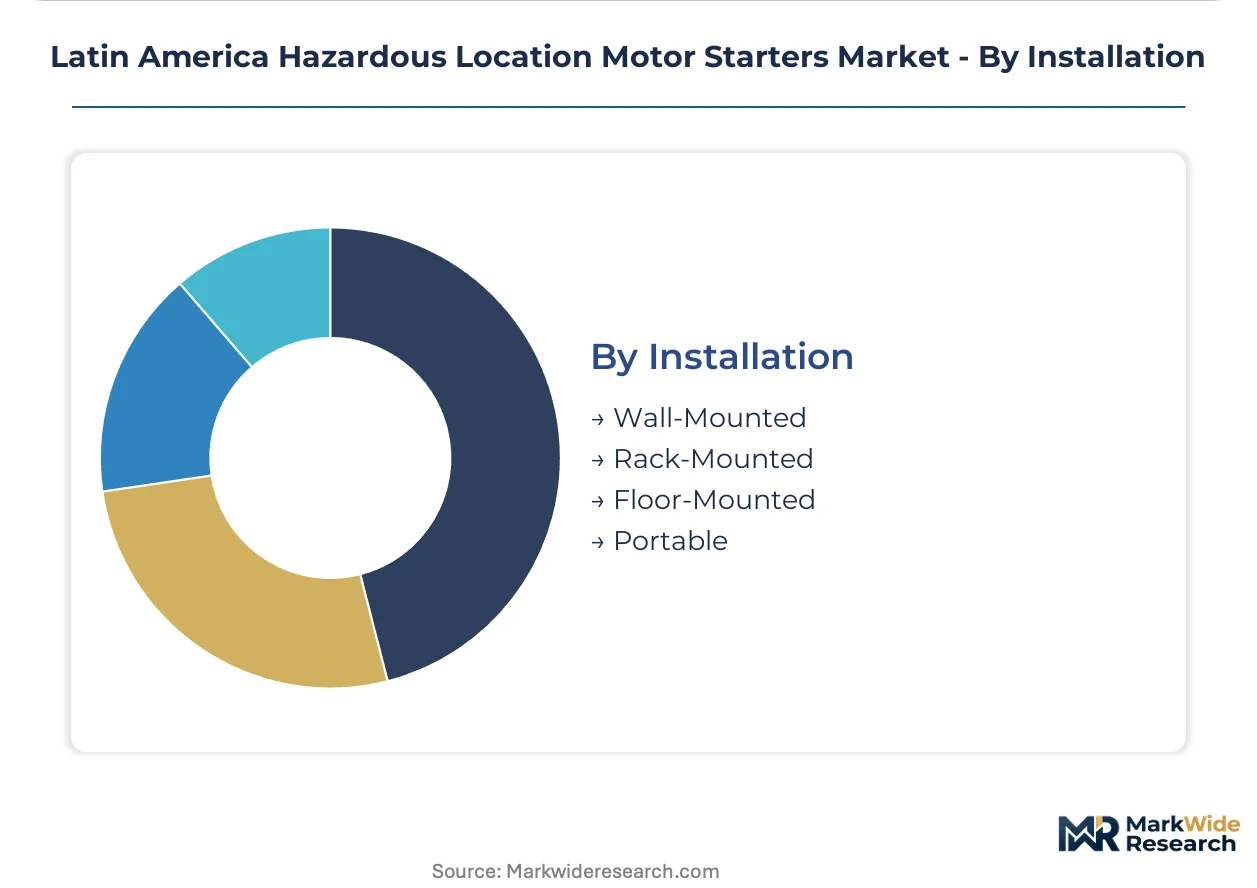
Installation:
Physical mounting configuration correlates with facility type and maintenance accessibility, with platform space constraints and underground mobility requirements driving specification divergence.
- Wall-Mounted:Enclosed motor control centers affixed to structural surfaces maximize floor space in congested electrical rooms. Brazilian offshore platforms specify these configurations for topside equipment shelters where deck loading limits constrain footprint.
- Floor-Mounted:Freestanding motor control centers with integrated isolation transformers serve large compressor stations in Mexico's Cantarell field infrastructure.
- Rack-Mounted:Standardized 19-inch chassis configurations enable modular expansion in centralized control buildings.
- Portable:Skid-mounted or wheeled units support temporary drilling operations and maintenance bypass scenarios.
Wall-Mounted carries the highest shipment volume; Floor-Mounted is climbing the fastest as onshore processing capacity expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
INMETRO Ordinance 179 and IECEx 02 certification convergence is redrawing equipment qualification boundaries across Latin America, compressing supplier access while elevating compliance investment thresholds for distributors serving high-risk hydrocarbon installations.
Brazil
Petrobras pre-salt platform construction sustains procurement volumes for explosion-proof motor control systems in the Santos Basin. ANP technical regulations mandate IECEx-certified equipment for offshore safety systems, tightening enclosure specifications for subsea applications. Jaraguá do Sul manufacturing clusters anchor captive motor and starter production, competing on lead time against imported assemblies for Brazilian offshore developments.
Mexico
Pemex refining complex retrofits drive replacement demand for variable frequency drives meeting NOM-027-ENER energy efficiency mandates. ASEA hydrocarbon sector standards enforce Class I Division 1 certification requirements across petrochemical corridors. Veracruz and Tula industrial concentrations concentrate procurement of corrosion-resistant enclosures for aggressive processing atmospheres.
Chile
Underground copper concentrators in the Atacama Desert specify soft starters to minimize mechanical stress on large induction motors. Tightening safety enforcement across Andean Community members accelerates Zone 1 certified equipment adoption in ventilation-limited headings. Santiago-based mining engineering clusters coordinate specification standards for dust ignition protection systems.
Colombia
Legacy oilfield infrastructure across the Llanos Basin sustains replacement cycles for Direct-On-Line Starters with twenty-year operational lifespans. Colombian coal processors continue specifying electromechanical units for field-service simplicity under remote grid voltage fluctuations. Bogotá procurement offices coordinate maintenance contracts for Andean mining operations.
Peru
Underground copper operations in the Andean highlands present white space for Zone 1 certified starters as safety standards tighten. Peruvian mining regulators are converging inspection protocols with Chilean and Colombian counterparts, harmonizing equipment qualification requirements. Lima-based engineering services clusters are developing specialized commissioning capabilities for hazardous location electrical systems.
Latin America Hazardous Location Motor Starters Market Competitive Landscape
Player mix skews toward diversified industrial conglomerates with captive certification infrastructure, compressing the addressable vendor base for distributors while elevating barriers for regional fabricators lacking dual IECEx-INMETRO qualification pipelines. Three strategic archetypes dominate: global testing infrastructure owners sustaining multi-jurisdiction certifications, regional manufacturers leveraging captive production for lead time advantages, and digital platform integrators capturing recurring software revenue from refinery automation upgrades. Competitive moves concentrate on strategic partnerships with offshore engineering contractors and portfolio diversification into predictive maintenance services.
Among Germany-based industrial conglomerates, Siemens occupies a position representing global certification infrastructure archetypes, leveraging testing networks for dual IECEx and INMETRO compliance. WEG, a Brazilian S.A., exemplifies regional manufacturing archetypes with captive production anchoring lead time competitiveness. Schneider Electric, a France-based multinational, represents digital platform integration archetypes converging starter architectures with industrial IoT backbones. These three companies illustrate how certification scale, regional production proximity, and software-enabled services define competitive positioning in Latin American hazardous location motor control procurement.
| Leading Market Players |
|---|
| Siemens |
| Hubbell |
| Schneider Electric |
| Crouse-Hinds |
| WEG |
| ABB |
| Rockwell Automation |
| GE Vernova |
| Eaton |
| Others |
Supply & Pricing Matrix
INMETRO Ordinance 179 and IECEx 02 certification tiers gate both supplier qualification and price differentiation simultaneously, compressing the vendor base while elevating compliance premiums for equipment serving Brazilian offshore platforms and Mexican petrochemical corridors. Buyers face bifurcated sourcing economics between dual-certified global suppliers and regional fabricators struggling with redundant testing cycles.
Pricing Analysis
Certification level (IECEx/INMETRO dual-grade) creates the primary spread between premium and standard tiers, with explosion-proof Zone 1 ratings commanding substantial premiums over Division 2 alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects enclosure material grade, with cast aluminum housings separating from stainless steel variants. Pricing pressure stems from raw material volatility in aluminum alloys, compressing margins for Andean mining suppliers. National oil companies exhibit lowest price sensitivity given safety-critical procurement mandates, while independent mining operators in Peru and Colombia drive hardest bargaining on electromechanical replacements.
Supply Chain Analysis
Port congestion at Santos and container availability constraints on Asia-Pacific trade lanes elevate inbound logistics costs for imported assemblies serving Brazilian offshore developments. Manufacturing concentrates in Brazil, Germany, and France, with Jaraguá do Sul anchoring regional captive production for lead time competitiveness. Raw material dependencies span cast aluminum alloys, silicon carbide semiconductors, and silver-alloy electrical contacts. Single-source vulnerability concentrates in specialized IP66+ sealing components from southern Brazilian engineering clusters. Distribution runs through certified distributor networks with integrator partnerships for offshore commissioning.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Solid-state digital architectures threaten electromechanical incumbents with substitution risk as offshore operators prioritize predictive maintenance capabilities over field-service simplicity. Defense of installed base requires proactive portfolio repositioning.
For Market Incumbents: Consolidate certification infrastructure around dual IECEx-INMETRO qualification pipelines to compress time-to-market for new product introductions. Deepen backward integration into cast aluminum enclosure fabrication to offset raw material volatility exposure. Anchor capacity in Jaraguá do Sul manufacturing clusters to defend lead time advantages against German and French imports. For New Entrants and Emerging Players: Aftermarket predictive diagnostics services present white space where incumbents under-serve with captive maintenance models. Peruvian underground copper operations offer the most penetrable geography as safety enforcement tightens. Commissioning and remote monitoring capabilities provide the strongest go-to-market angle against established equipment suppliers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed industrial electrical specialists holding regional certification portfolios but lacking digital platform integration. Long-term viability favors suppliers bridging electromechanical installed base with software-enabled service revenue. Watch for INMETRO digital certification pathway finalization as inflection signal for first-mover advantage in software-defined motor control.| Strategic Initiative | Industry Significance |
|---|---|
| Dual Certification Investment | IECEx-INMETRO convergence reduces redundant testing costs for Brazilian-Mercosur market access. |
| Digital Platform Integration | EcoStruxure-compatible architectures capture recurring software revenue from Pemex refinery upgrades. |
| Regional Manufacturing Expansion | Jaraguá do Sul capacity additions compress lead times against European imports for Santos Basin projects. |
| Predictive Diagnostics Capability | Condition monitoring services unbundle from equipment sales to serve third-party maintenance contracts. |
| Andean Mining Market Entry | Zone 1 certified soft starters address tightening safety enforcement in Chilean copper concentrators. |
Research Methodology
Operator-level perspectives from offshore platform electrical engineers, petrochemical maintenance directors, mining safety officers, and certified distributor technical sales anchored the qualitative base for this study. Primary interviews with these stakeholders combined with secondary validation from ANP regulatory filings, ASEA hydrocarbon sector standards, INMETRO certification databases, and customs trade records. Bottom-up equipment procurement tracking and top-down industrial investment flow analysis provided triangulation across data sources.
Sensitivity analysis around certification timeline delays and raw material cost scenarios framed the analytical approach across the projection horizon. Segmentation dimensions modeled include product type, technology architecture, end-use sector, and installation configuration, with regulatory framework intensity as an industry-specific overlay. CAGRs derived from equipment replacement cycle analysis and greenfield project pipeline assessment, incorporating energy efficiency mandate compliance rates and offshore platform construction schedules as key forecast inputs.
Underlying assumptions cover certification convergence timelines, aluminum alloy price stability, and offshore drilling activity persistence, with deviation risk concentrated in regulatory revision delays and mining safety enforcement variability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Power Equipment
Solar Combiner Boxes Market
Electrical Power Equipment
Global Electric Power Substation Automation Market
Electrical Power Equipment
Storage Water Heater Market
Electrical Power Equipment
Instrument Transformers Market
Electrical Power Equipment
Marine Switchboard Market
Electrical Power Equipment
Unitary Heaters Market
Electrical Power Equipment
Load Bank Market
Electrical Power Equipment
Low Voltage Protection Control Market
Electrical Power Equipment
Subsea Cables Equipment Market
Electrical Power Equipment
North America Protective Relays Market
Electrical Power Equipment
Electric Substation Market
Electrical Power Equipment
Electric Radiators Market
Electrical Power Equipment
Instant Water Heater Market
Electrical Power Equipment
High Voltage Oil Insulated Switchgear Market
Electrical Power Equipment
Utility Poles Market
Electrical Power Equipment
High Voltage Direct Current (HVDC) Cables Market