
 Horticulture Film Market | 2026-2036
Horticulture Film Market Size, Share, and Industry Trends Forecast 2026-2036
Horticulture Film Market Foresight
Market Overview
European polymer compounders is broadening specialized horticulture film capacity to serve controlled-environment agriculture expansion. BASF SE leverages its biodegradable polymer research pipeline to differentiate in mulch film applications. Dow Inc. anchors North American supply through integrated polyethylene production. Berry Global Group sustains competitive position via extensive converting infrastructure and direct channel control with large commercial growers.
Technical and Segment Analysis
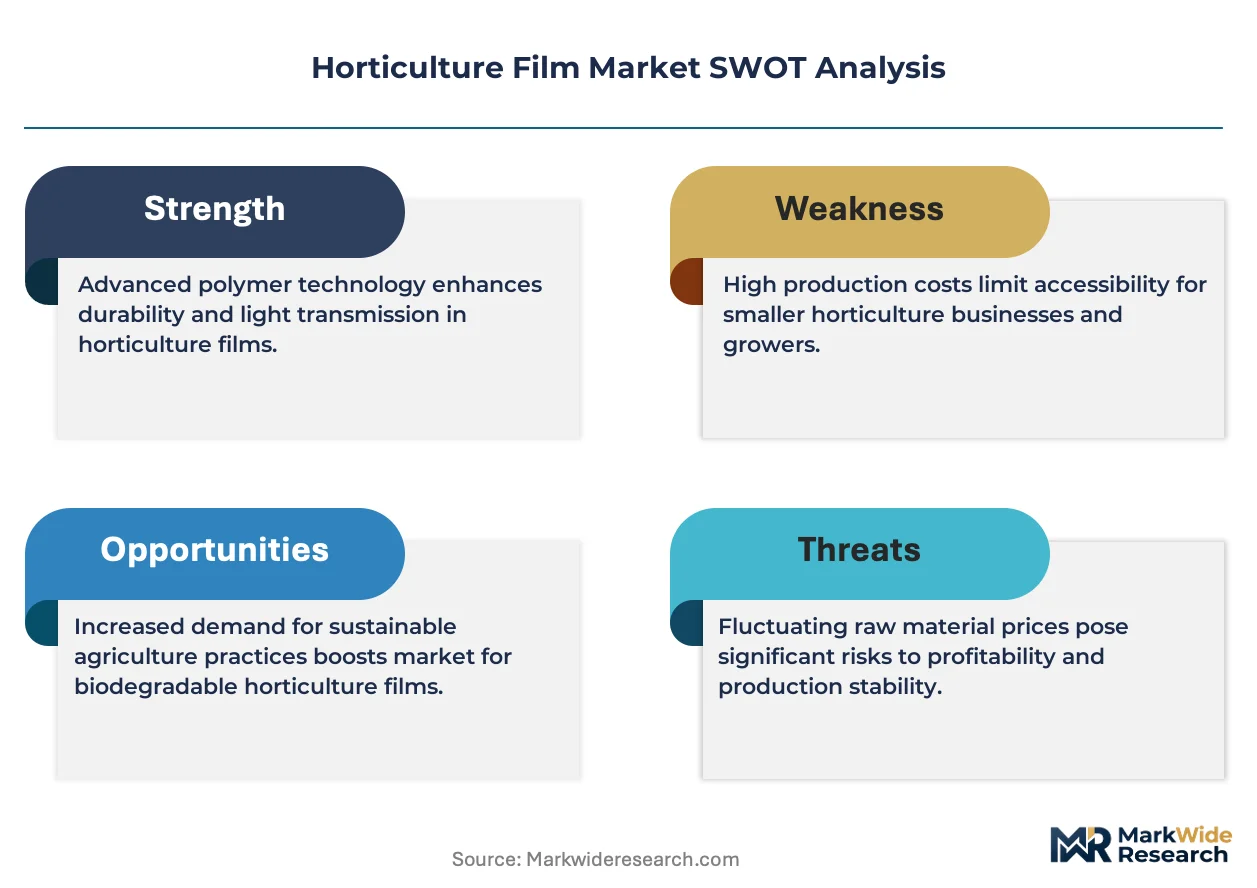
Horticulture film encompasses engineered polymer sheets and nets deployed for microclimate management, weed suppression, and soil moisture retention, typically manufactured through blown film extrusion with UV stabilizer packages rated for 1-4 season durability. Greenhouse film commands the largest value share due to high square-meter coverage requirements and replacement frequency in intensive systems, while biodegradable polymers represent the fastest-expanding material category as disposal regulations tighten. Mulch film carries concentrated margin pools where premium pricing attaches to photo- and bio-degradable grades that eliminate removal labor.
Regulatory Environment
REACH restrictions on persistent organic pollutants constrain conventional additive formulations across Europe, while EPA agricultural plastics guidelines influence US product development trajectories. The EU Green Deal's farm-to-fork strategy directly shapes film demand by penalizing non-recoverable mulch and rewarding soil-biodegradable alternatives. Stakeholders must monitor evolving compostability certification standards and polymer substitution timelines to align R&D portfolios with compliance-driven procurement shifts.
Market Dynamics
The EU Green Deal's plastics reduction mandates are compressing replacement timelines for conventional polyethylene mulch while redirecting R&D budgets toward soil-biodegradable polymer formulations. This regulatory pressure is restructuring supplier-buyer relationships across intensive greenhouse clusters.
Growth Catalysts
- EU Green Deal farm-to-fork strategy:Mandatory soil-biodegradable mulch requirements in member states are forcing rapid polymer substitution and opening premium pricing tiers for certified compostable films.
- Almería greenhouse cluster expansion:Spain's intensive horticulture zone drives continuous film replacement cycles as growers expand climate-controlled vegetable production under high-UV exposure conditions.
- Blown film extrusion with enhanced UV stabilizer packages:Four-season durability ratings reduce replacement frequency for commercial operators while improving total cost of ownership metrics.
Market Restraints
- Ethylene feedstock volatility:Crude oil price swings directly compress polyethylene film margins and destabilize long-term contract pricing for greenhouse operators.
- REACH persistent organic pollutant restrictions:ECHA constraints on conventional additive formulations force costly reformulation cycles and disqualify legacy product lines from EU markets.
- Mechanical removal labor economics:Non-degradable mulch films retain cost advantages in regions without disposal penalties, slowing biodegradable adoption in price-sensitive segments.
Strategic Opportunities
- Compostability certification standardization:Emerging ISO and EN standards for soil-biodegradability create first-mover advantages for compounders with validated test protocols.
- Controlled-environment agriculture in the Netherlands:High-tech greenhouse expansion around Westland and Venlo generates demand for optical-grade films with tailored light diffusion properties.
- Direct channel partnerships with commercial growers:Bypassing distributor networks enables customized film specifications and captures margin pools currently absorbed by converting intermediaries.
Industry Challenges
- Polymer science talent scarcity:Formulation chemists with biodegradable polymer expertise command premium compensation, constraining mid-tier compounder R&D expansion.
- Composting infrastructure certification timelines:Industrial composting facility validation for soil-biodegradable films extends go-to-market cycles by 18-24 months in key member states.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Horticulture Film Market |
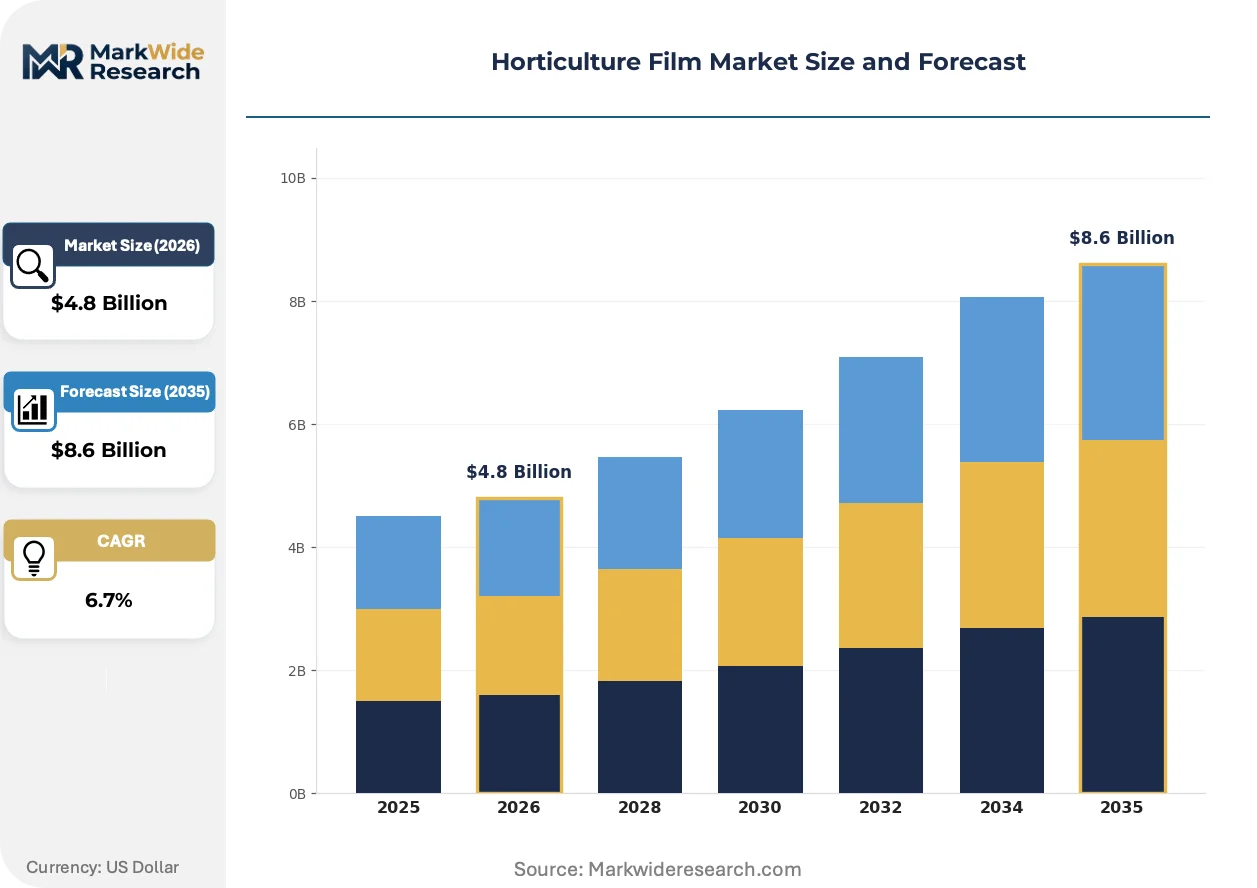
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Greenhouse Film, Mulch Film, Shade Netting, Plastic Sheet Material: Polyethylene, Polypropylene, Biodegradable Polymers, PVC Application: Crop Cultivation, Soil Protection, Greenhouse Covering, Weed Control End User: Commercial Growers, Organic Farmers, Garden Centers, Agricultural Co-operatives |
| Companies Covered | BASF SE, Dow Inc., Berry Global Group, Inc., RKW Group, Trioplast Industries AB, Armando Alvarez Group, Plastika Kritis S.A., Novamont S.p.A., Mondi Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Horticulture Film Market Shifts & Advancements
Automation and sensor integration are transforming film performance validation, while regulatory chemistry constraints and buyer consolidation are compressing traditional supply relationships. Three developments are restructuring competitive positioning.
Multilayer coextrusion with embedded spectral filters is automating light quality management for greenhouse operators. Large vegetable producers in Spain and Italy are adopting these films at accelerating rates to optimize photosynthetic photon flux density. This technology is automating climate control decisions that previously required manual shade curtain adjustments, reducing labor inputs while improving yield consistency.
REACH authorization requirements for UV stabilizer chemistries are forcing additive package redesigns across European compounders. ECHA's expanding candidate list of substances of very high concern now captures several hindered amine light stabilizers common in agricultural films. Greenhouse film manufacturers serving Germany and France are responding by accelerating bio-based stabilizer testing and securing alternative supply chains.
Consolidation among large-scale greenhouse operators is compressing procurement cycles and demanding volume-tiered pricing structures. Major vegetable producers in Almería and the Netherlands are consolidating purchasing through cooperative buying groups, displacing fragmented distributor relationships. This concentration is most visible in Spain's southeastern corridor, where three grower cooperatives now control over half of regional film procurement decisions.
Horticulture Film Market Segmentation
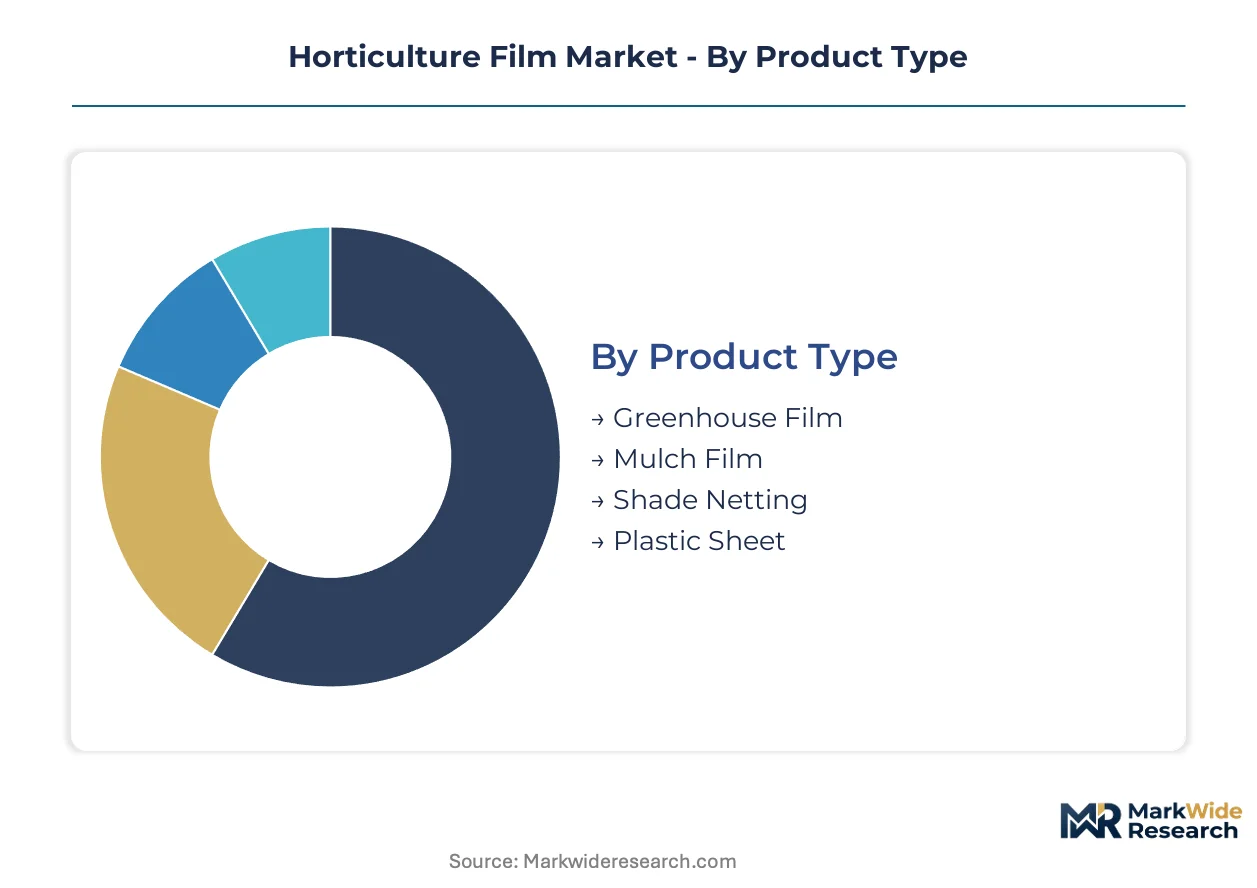
Segmentation in horticulture film reflects divergent certification burdens across polymer grades and end-use applications. Procurement specifications vary sharply between regulated greenhouse operations and price-sensitive open-field cultivation.
Product Type:
Certification requirements cluster around durability ratings and UV stabilizer compliance, with REACH-authorised additives mandatory for EU greenhouse applications while non-regulated markets permit legacy formulations.
- Greenhouse Film:Multilayer coextruded structures with embedded spectral filters manage photosynthetic photon flux density for climate-controlled vegetable production. Demand concentrates in Spain's Almería corridor and the Netherlands' Westland cluster, where four-season durability ratings reduce replacement frequency and improve total cost of ownership for intensive operators.
- Mulch Film:Soil-contact polymer sheets engineered for weed suppression and moisture retention, manufactured in both conventional polyethylene and certified soil-biodegradable grades. EU Green Deal farm-to-fork mandates are compressing replacement timelines for conventional grades in member states while opening premium pricing tiers for compostable alternatives in Germany and France.
- Shade Netting:Woven or knitted polymer meshes with calibrated light transmission coefficients for temperature and radiation management.
- Plastic Sheet:General-purpose polyethylene barriers for temporary ground cover and equipment protection in non-specialised applications.
Leading the category by volume: Greenhouse Film. Growing fastest: Mulch Film.
Material:
Cost tier stratification separates commodity polyethylene from specialty biodegradable formulations, with polymer substitution timelines driven by disposal penalty structures rather than intrinsic performance.
- Polyethylene:Blown film extrusion from high-density and linear low-density resins dominates installed base economics. Spain's agricultural co-operatives and Italian vegetable consortia anchor volume demand despite feedstock volatility compressing margins during crude oil price swings.
- Biodegradable Polymers:Polylactic acid and polyhydroxyalkanoate formulations certified to EN 13432 and ISO 17088 standards for soil biodegradability. Composting infrastructure validation timelines in key member states extend go-to-market cycles, constraining mid-tier compounder expansion despite regulatory pull.
- Polypropylene:Higher thermal stability suits applications requiring elevated temperature resistance in Mediterranean greenhouse environments.
- PVC:Rigid and semi-rigid formulations retain niche positioning for structural greenhouse components where flexibility is secondary to dimensional stability.
Volume leadership: Polyethylene. Steepest expansion trajectory: Biodegradable Polymers.
Application:
Customer type determines specification stringency, with commercial growers demanding optical-grade performance while organic farmers prioritise certified compostable materials for accreditation compliance.
- Crop Cultivation:Film systems optimised for yield maximisation in intensive vegetable and ornamental production. The Netherlands' high-tech greenhouse sector generates demand for tailored light diffusion properties, while Spanish commercial operators prioritise UV stabiliser package longevity under high-exposure conditions.
- Soil Protection:Barrier applications preventing erosion and contamination in exposed cultivation zones. Organic farmers in France and Germany drive adoption of soil-biodegradable alternatives to satisfy certification body requirements and avoid removal labour costs.
- Greenhouse Covering:Climate envelope management for controlled-environment agriculture infrastructure.
- Weed Control:Ground-cover films suppressing competitive vegetation without herbicide application.
Dominant by volume: Crop Cultivation. Gaining share fastest: Soil Protection.
End User:
Supply concentration varies across buyer scale, with large commercial growers consolidating procurement through cooperative structures while garden centres fragment across distributor networks.
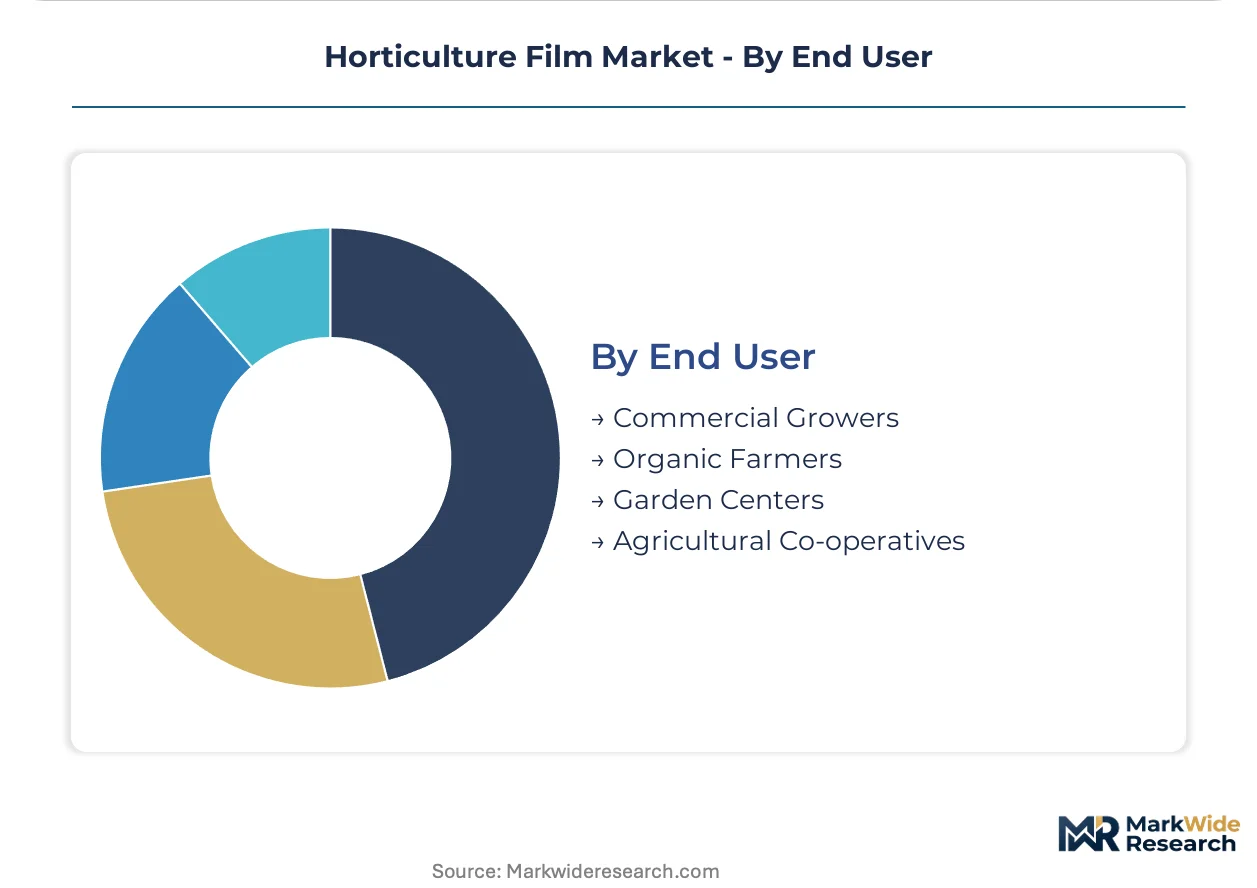
- Commercial Growers:Large-scale vegetable and ornamental producers operating climate-controlled facilities. Three grower co-operatives in Spain's southeastern corridor now control over half of regional film procurement, compressing pricing structures and demanding customised specifications direct from compounders.
- Agricultural Co-operatives:Pooled purchasing entities aggregating demand across member farms. Italian and Spanish consortia are displacing fragmented distributor relationships, enabling volume-tiered pricing and standardised quality protocols across greenhouse clusters.
- Organic Farmers:Certification-constrained operators requiring documented compostability for accreditation maintenance.
- Garden Centers:Retail-oriented outlets serving hobbyist and small-scale cultivation with standardised product ranges.
Volume concentration: Commercial Growers. Procurement consolidation accelerating fastest: Agricultural Co-operatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ethylene feedstock availability in the US Gulf Coast anchors polyethylene supply for North American horticulture film production. European compounders source naphtha-derived resins through Rotterdam and Antwerp refining clusters. Asian manufacturers rely on coal-to-olefins capacity concentrated in China's Shandong and Ningxia provinces.
Spain
Almería's greenhouse corridor drives Europe's highest film replacement velocity as intensive vegetable producers expand climate-controlled acreage. EU Green Deal farm-to-fork mandates compress timelines for conventional mulch adoption while accelerating soil-biodegradable procurement. Three grower cooperatives in the southeastern corridor now direct over half of regional purchasing decisions.
Netherlands
Westland and Venlo greenhouse clusters generate demand for optical-grade films with engineered light diffusion properties. REACH restrictions on hindered amine light stabilizers force additive package redesigns among Dutch compounders serving Germany and France. High-tech cultivation facilities prioritize four-season durability ratings to minimize replacement downtime.
United States
California's Central Valley and Florida's winter vegetable belt anchor commercial greenhouse expansion requiring UV-stabilized covering films. EPA agricultural plastics guidelines influence product development trajectories for mulch applications. Texas and Arizona growers drive demand for thermal management films in desert cultivation environments.
Italy
Po Valley vegetable consortia and Sicilian tomato producers sustain volume demand for conventional polyethylene despite feedstock volatility. ECHA constraints on persistent organic pollutants disqualify legacy additive formulations from EU market access. Agricultural cooperatives in Apulia and Campania are consolidating procurement through pooled purchasing entities.
China
Shandong Province's greenhouse vegetable belt generates massive square-meter coverage requirements for blown film extrusion. The country's dual carbon goals accelerate scrutiny of agricultural plastic waste streams. Ningxia and Xinjiang coal-to-olefins facilities supply feedstock to compounders serving domestic protected cultivation expansion.
Horticulture Film Market Competitive Landscape
Global majors compete with regional champions across polymer formulation and converting infrastructure. The vendor base organizes into three tiers: integrated petrochemical producers with captive resin supply, specialized compounders with biodegradable polymer expertise, and regional converters with direct grower relationships. Consolidation pressures intensify as large agricultural cooperatives consolidate procurement volumes. Capacity expansion and compostability certification represent the dominant competitive moves reshaping supplier positioning.
Within the integrated chemical producer tier, BASF SE and Dow Inc. exemplify divergent strategic anchors—BASF leverages biodegradable polymer research pipelines while Dow anchors North American supply through polyethylene production integration. Among specialized European compounders, Novamont S.p.A. occupies a position representing soil-biodegradable formulation leadership. These three entities illustrate how competitive positioning fragments across petrochemical scale, specialty polymer science, and sustainability certification vectors.
| Leading Market Players |
|---|
| BASF SE |
| Dow Inc. |
| Berry Global Group, Inc. |
| RKW Group |
| Trioplast Industries AB |
| Armando Alvarez Group |
| Plastika Kritis S.A. |
| Novamont S.p.A. |
| Mondi Group |
| Others |
Supply & Pricing Matrix
Multilayer coextrusion technology with embedded spectral filters is simultaneously elevating manufacturing complexity and concentrating production among compounders with advanced blown film capabilities. This capability shift rewards integrated producers who can amortize R&D costs across volume tiers while marginalizing converters dependent on commodity resin formulations.
Pricing Analysis
Warranty-backed durability commitments now separate premium greenhouse film tiers from unbundled commodity offerings. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale, with EU Green Deal compliance tiers commanding substantial premia over legacy polyethylene formulations. Cost compression in standard-grade mulch intensifies because feedstock volatility compresses polyethylene margins and agricultural cooperatives consolidate procurement volumes. Small-scale garden centers exhibit highest price sensitivity, while commercial growers in Spain's Almería corridor prioritize total cost of ownership over unit pricing.
Supply Chain Analysis
Workforce availability constraints in Germany and the Netherlands compound formulation chemist scarcity, forcing compounders to locate R&D functions near polymer science talent clusters. Geographic supply concentration centers on Germany, Spain, and China, with European compounders sourcing naphtha-derived resins through Rotterdam-Antwerp refining corridors and Asian manufacturers drawing from Shandong coal-to-olefins capacity. Raw material dependencies rest on ethylene feedstock, UV stabilizer additive packages, and biodegradable polymer resins. Single-source vulnerability in hindered amine light stabilizers creates exposure as ECHA expands its candidate list. Distribution runs through agricultural cooperative buying groups displacing fragmented distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating rapidly as EU regulatory compliance timelines force sub-scale compounders out of certified product segments. Procurement consolidation among agricultural cooperatives accelerates this attrition by concentrating volume with suppliers capable of validated compostability documentation.
For Market Incumbents: Deepen backward integration into biodegradable polymer resin production to secure supply chain control as polylactic acid and polyhydroxyalkanoate demand outpaces compounder capacity. Fortify direct channel partnerships with Spain's three dominant grower cooperatives before competitor compounders capture cooperative procurement consolidation. Prioritize EN 13432 and ISO 17088 certification investment to defend margin position against emerging specialty compounders.
For New Entrants and Emerging Players: Agricultural co-operative buying groups represent the most penetrable channel archetype, as these entities actively displace legacy distributor relationships and seek alternative suppliers for volume-tiered pricing. Target Italy's Po Valley vegetable consortia and Apulia-Campania cooperatives where procurement consolidation has lagged Spain's southeastern corridor. Pursue white-label manufacturing partnerships with established converters lacking in-house biodegradable formulation expertise.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated petrochemical majors seeking biodegradable polymer capabilities and specialty compounders pursuing geographic expansion. Long-term viability favors compounders with validated soil-biodegradability protocols and direct grower channel control rather than distributor-dependent converters. Watch composting infrastructure certification timelines in Germany and France as the critical inflection signal—accelerated validation would compress go-to-market cycles and reward early movers.
| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Polymer Capacity Expansion | Captures EU Green Deal procurement shifts as member states mandate soil-biodegradable mulch adoption. |
| Compostability Certification Investment | Secures first-mover positioning in Germany and France where industrial composting validation gates market access. |
| Direct Channel Partnership Development | Bypasses distributor margin absorption and captures volume-tiered pricing with Spain's consolidated grower cooperatives. |
| UV Stabilizer Additive Reformulation | Ensures REACH compliance as ECHA candidate list expansion disqualifies legacy hindered amine formulations. |
| Spectral Filter Technology Licensing | Monetizes multilayer coextrusion expertise for Netherlands high-tech greenhouse optical-grade film demand. |
Research Methodology
Document review covered ECHA regulatory filings, EU Commission farm-to-fork strategy documents, and SEC disclosures from integrated chemical producers, complemented by interviews with blown film extrusion plant managers, procurement leads at Spanish agricultural cooperatives, distribution channel partners, and technical R&D directors specializing in biodegradable polymer formulations. Secondary validation drew from customs and trade data, Cefic polymer industry reports, and compostability certification registry databases. Bottom-up demand modeling triangulated against top-down supply capacity assessments across European and Asian production clusters.
Segment-level value and volume trajectories across the analysis window reflect disaggregated modeling of greenhouse film, mulch film, shade netting, and plastic sheet categories with cross-dimensional analysis by polymer type, durability rating, and end-user scale. CAGRs were derived from fitted growth curves incorporating replacement cycle frequencies in Spain's Almería corridor, Netherlands Westland expansion rates, and regulatory-driven substitution timelines for conventional polyethylene. Key inputs included UV stabilizer package longevity assumptions, feedstock price elasticity coefficients, and agricultural cooperative procurement consolidation velocity.
Caveats apply where ECHA substance restrictions, composting infrastructure certification delays, or ethylene feedstock volatility could materially shift the outlook. Forecasts reflect assumptions about regulatory enforcement consistency and grower adoption rates for soil-biodegradable alternatives. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Fabrics
US Agro Textile Market
Agricultural Fabrics
Hay Bags Market
Agricultural Fabrics
Anti Wind Net Market
Agricultural Fabrics
North America Silo Bags Market
Agricultural Fabrics
Coco Coir Market
Agricultural Fabrics
Shade Net Market
Agricultural Fabrics
Agricultural Films and Bonding Market
Agricultural Fabrics
Silage Wrap Films Market
Agricultural Fabrics
Canopy Market
Agricultural Fabrics
Global Agricultural Films Market
Agricultural Fabrics
North America Agricultural Films Market
Agricultural Fabrics
Global Mulch Films Market
Agricultural Fabrics
Silage Bags Market
Agricultural Fabrics
Global Greenhouse Film Market
Agricultural Fabrics
Silo Bags Market
Agricultural Fabrics
Nonwoven Crop Cover Market