
 United Kingdom Commercial Greenhouse Market | 2026-2036
United Kingdom Commercial Greenhouse Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Commercial Greenhouse Market Insights
Horticultural supply chains through major supermarket produce procurement is reconfiguring as retailers demand traceable, domestic year-round vegetable supply. Growponics Ltd. leverages its hydroponic technology leadership to secure long-term produce contracts. Robinsons Greenhouses anchors the Midlands manufacturing corridor with decades of structural fabrication expertise. Elite Greenhouses Ltd. specializes in bespoke aluminum-framed glasshouses for premium estate and institutional clients.
A commercial greenhouse is an enclosed, climate-managed structure engineered with specified light transmission rates, thermal insulation values, and automated environmental controls to enable controlled cultivation of crops outside natural growing seasons. These facilities employ precision-engineered glazing systems, typically achieving 80-90% light transmission, combined with active ventilation and heating infrastructure to maintain optimal growing conditions. Glasshouses command the premium installation tier due to superior longevity and optical clarity for high-value crop production. Polycarbonate Structures are displacing traditional glazing in mid-scale operations where thermal efficiency and impact resistance outweigh capital intensity. Automated Systems within the Installation Type dimension represent the fastest-growing configuration as labor costs and precision requirements intensify.
The Environment Agency enforces water abstraction licensing and nitrate discharge rules that directly constrain expansion of soil-based intensive cultivation, redirecting investment toward closed-loop hydroponic infrastructure. BSI standards for structural wind loading and glazing safety shape product certification requirements for permanent installations. DEFRA's Sustainable Farming Incentive and evolving ELM scheme criteria determine capital grant eligibility for energy-efficient greenhouse upgrades. Stakeholders must monitor how post-Brexit phytosanitary border protocols reshape seed and propagation material sourcing economics against domestic production targets.
Market Dynamics
DEFRA's tightening water abstraction regulations are forcing a structural pivot from soil-based cultivation toward closed-loop hydroponic systems, concentrating investment in Kent and West Midlands glasshouse clusters where infrastructure permits compliance.
Growth Catalysts
- Retailer Traceability Mandates:Major supermarket produce procurement now requires verifiable domestic year-round vegetable supply chains. Glasshouse operators capture long-term contracts by meeting optical clarity and thermal performance specifications.
- Environment Agency Discharge Standards:Nitrate discharge rules constrain soil-intensive horticulture expansion. Closed-loop hydroponic infrastructure redirects capital toward automated environmental control installations.
- Glasshouse Cluster Economics:Kent and West Midlands concentration enables shared logistics, skilled labor pools, and proximity to distribution networks serving London retail terminals.
Market Restraints
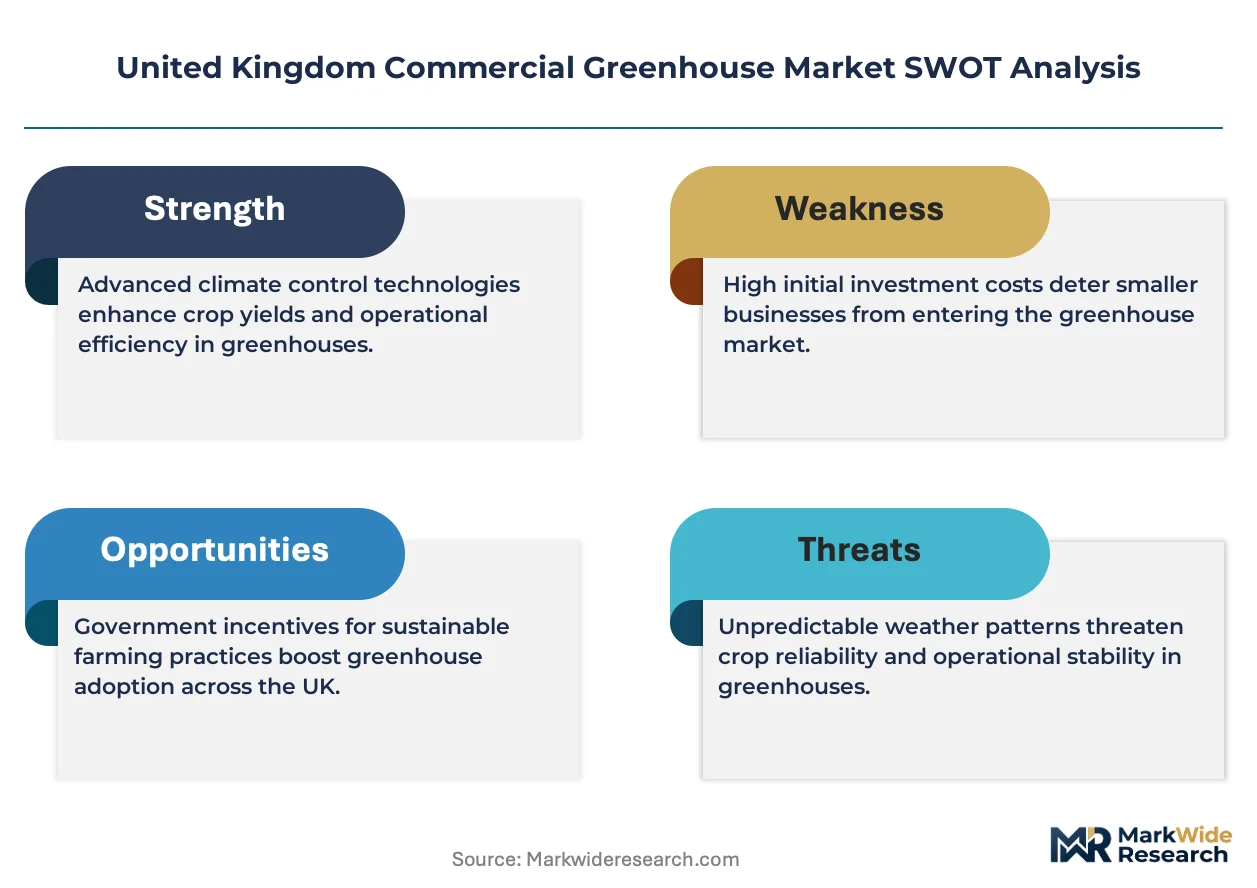
- Capital Intensity Thresholds:Automated glasshouse installations require substantial upfront expenditure on precision-engineered glazing and climate infrastructure, excluding smaller agricultural operators.
- Steel and Aluminum Input Volatility:Structural framing material costs fluctuate with global commodity markets, compressing fabrication margins for permanent installation manufacturers.
- Propagation Material Sourcing Friction:Post-Brexit phytosanitary border protocols complicate seed and cutting imports from EU suppliers, extending lead times for crop establishment.
Strategic Opportunities
- DEFRA Sustainable Farming Incentive:Capital grant eligibility for energy-efficient greenhouse upgrades creates funding pathways for thermal insulation retrofits and heating infrastructure modernization.
- Polycarbonate Structure Expansion:Mid-scale operations in Yorkshire and East Anglia adopt impact-resistant glazing where thermal efficiency outweighs glass longevity requirements.
- Automated System Integration:Convergence of sensor networks and precision irrigation technology enables labor cost reduction in high-value crop segments.
Industry Challenges
- Structural Wind Loading Certification:BSI standards for permanent installations require extensive engineering validation, extending product development timelines for regional manufacturers.
- Legacy Climate Control Integration:Retrofitting automated environmental systems into existing glasshouse infrastructure demands specialized electrical and mechanical coordination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Commercial Greenhouse Market |
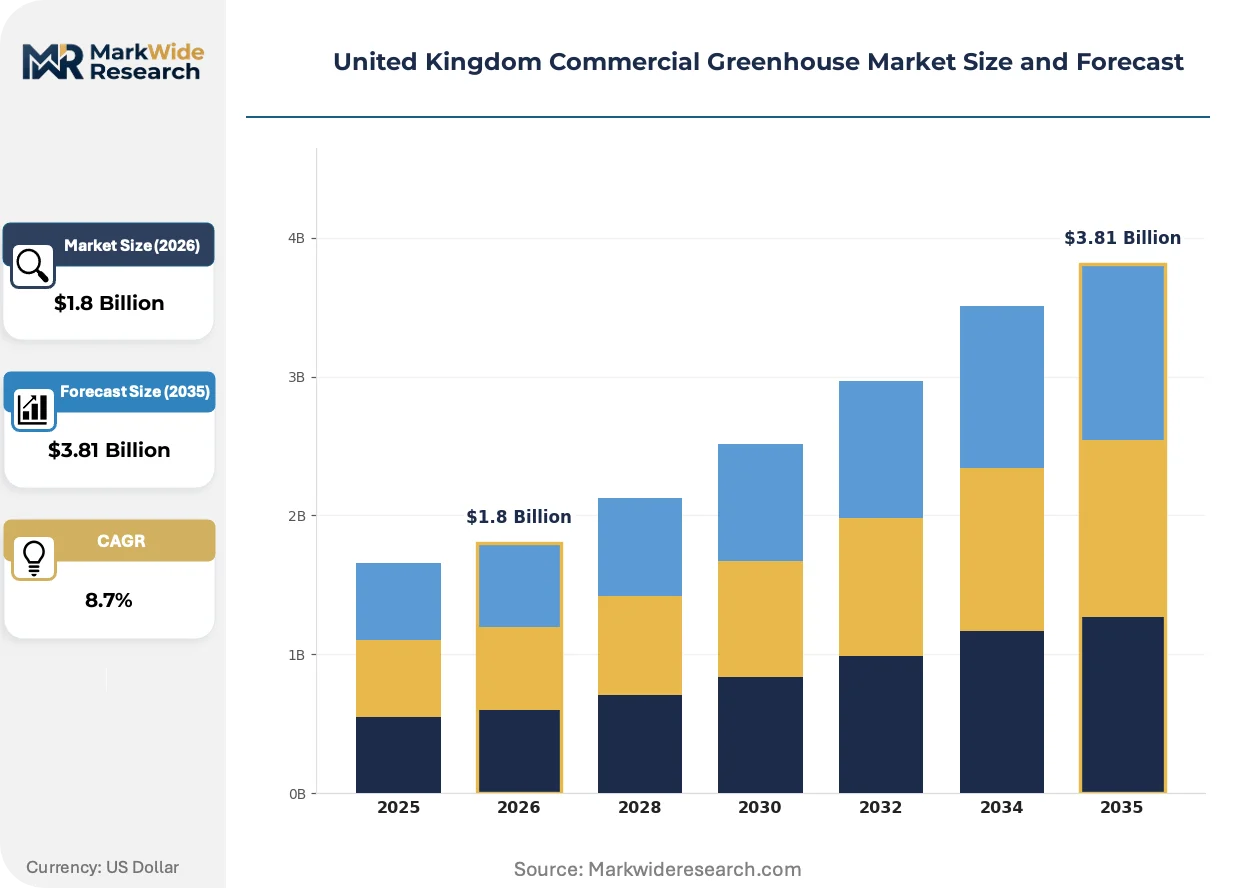
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydroponic Systems, Polycarbonate Structures, Glasshouses, Shade Houses Installation Type: Permanent Installations, Temporary Structures, Containerized Greenhouses, Automated Systems End User: Commercial Growers, Research Institutions, Educational Facilities, Agricultural Cooperatives Technology: Climate Control Systems, LED Grow Lights, Watering Solutions, Nutrient Management Technologies |
| Companies Covered | Growponics Ltd., NETAFIM, Robinsons Greenhouses, Elite Greenhouses Ltd., Cultivar Ltd., Palram Industries Ltd., KEDER GREENHOUSE, Griffin Glasshouses Limited, Alitex Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Commercial Greenhouse Market Trends and Innovations
Digital infrastructure and regulatory compliance technology are reshaping how UK glasshouse operators manage cultivation environments and document production traceability for retail buyers.
Sensor-integrated climate management platforms are digitizing growing environment optimization across Kent glasshouse clusters. Large-scale salad crop producers deploy networked temperature, humidity, and light monitoring to enable predictive ventilation adjustments. The technology is digitizing labor allocation patterns by automating routine environmental monitoring tasks previously requiring manual oversight.
DEFRA's evolving Environmental Land Management scheme criteria are restructuring capital investment priorities for horticultural operators. Grant eligibility thresholds now favor closed-loop water recirculation and renewable heating infrastructure over conventional systems. Premium vegetable producers in the West Midlands reconfigure expansion plans to align with ELM scheme certification requirements.
Supermarket produce buyers now mandate batch-level traceability documentation from glasshouse suppliers. Direct sourcing contracts with major retail chains displace traditional wholesale market channels for domestic tomato and cucumber producers. This procurement compression is most visible in Kent, where glasshouse operators invest in integrated inventory management systems to satisfy retailer audit protocols.
United Kingdom Commercial Greenhouse Market Segmentation
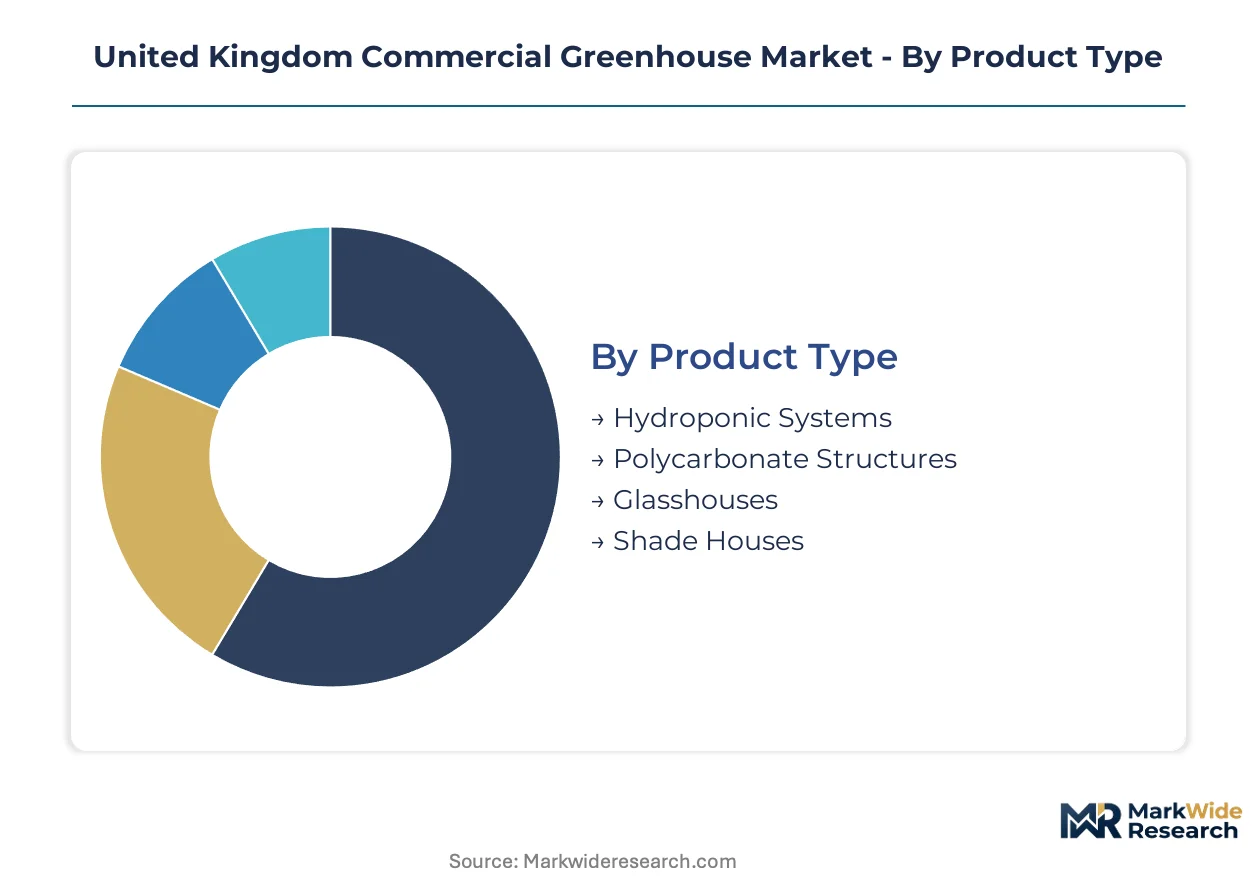
UK commercial greenhouse procurement patterns diverge sharply across structural materials, installation permanence, and automation intensity. Each segment tier carries distinct capital requirements, regulatory compliance obligations, and crop suitability profiles that determine operator selection criteria.
Product Type:
Mature glasshouse technology anchors premium installations while emerging materials reshape mid-scale economics.
- Glasshouses:Precision-engineered steel or aluminum frameworks support high-transmission glazing achieving 80-90% optical clarity. Kent salad producers and West Midlands tomato growers specify these structures for multi-decade operational lifespans where crop quality premiums justify capital intensity.
- Polycarbonate Structures:Twin-wall and multi-wall extruded panels deliver superior thermal insulation values alongside impact resistance. Yorkshire and East Anglia vegetable operations adopt these systems where heating cost reduction outweighs glass longevity requirements.
- Hydroponic Systems:Closed-loop nutrient delivery infrastructure enables soilless cultivation compliant with Environment Agency discharge regulations.
- Shade Houses:Structural frameworks with permeable shading fabrics protect nursery stock and propagation material from excessive solar loading.
Glasshouses retain volume leadership; Polycarbonate Structures hold the steepest expansion curve.
Installation Type:
Cost tier stratification separates capital-intensive permanent infrastructure from flexible temporary alternatives.
- Permanent Installations:Engineered foundations and fixed structural members require BSI wind loading certification and DEFRA grant alignment for capital support eligibility. These installations dominate Kent glasshouse cluster expansion where long-term land tenure secures investment returns.
- Automated Systems:Integrated sensor networks, precision irrigation, and climate control automation reduce labor dependence while tightening environmental parameter control. West Midlands salad producers deploy these configurations to satisfy supermarket traceability mandates and year-round contract specifications.
- Temporary Structures:Modular framing with ground anchoring supports seasonal production without permanent foundation investment.
- Containerized Greenhouses:Modified shipping containers with integrated climate systems enable rapid deployment for research or pilot-scale operations.
Permanent Installations retain volume leadership; Automated Systems hold the steepest expansion curve.
End User:
Customer type concentration varies across commercial production scale, institutional research priorities, and cooperative ownership structures.
- Commercial Growers:Large-scale salad, tomato, and cucumber producers operating under direct supermarket supply contracts. These operators drive demand for automated environmental control and batch-level traceability documentation systems.
- Research Institutions:University agricultural departments and crop science facilities requiring precisely replicable growing conditions for varietal development trials.
- Educational Facilities:Agricultural colleges and vocational training centers utilizing greenhouse infrastructure for practical horticulture instruction.
- Agricultural Cooperatives:Member-owned enterprises pooling capital for shared greenhouse infrastructure serving multiple small-scale producers.
Commercial Growers retain volume leadership; Research Institutions hold the steepest expansion curve.
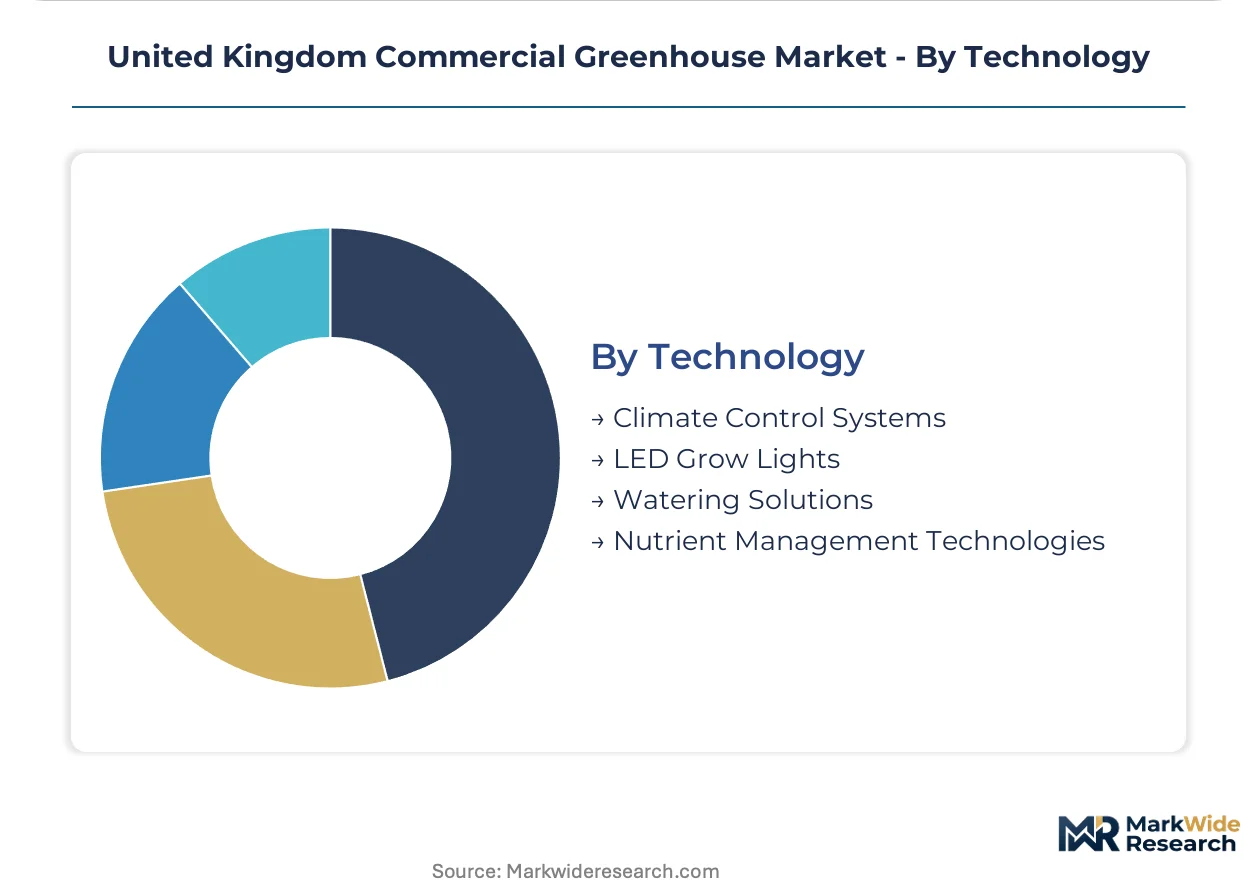
Technology:
Margin concentration follows the precision gradient from basic irrigation through integrated climate management platforms.
- Climate Control Systems:Networked temperature, humidity, and ventilation automation platforms enable predictive environmental adjustments. Kent glasshouse operators deploy these systems to digitize labor allocation and satisfy retailer audit protocols for year-round supply contracts.
- LED Grow Lights:Spectrally-tuned solid-state lighting supplements natural irradiance during winter months and enables multi-layer vertical cultivation configurations.
- Watering Solutions:Drip irrigation, ebb-and-flow benches, and misting systems deliver precise moisture control across diverse crop requirements.
- Nutrient Management Technologies:Automated dosing and recirculation systems maintain closed-loop hydroponic operation compliant with Environment Agency discharge standards.
Climate Control Systems retain volume leadership; LED Grow Lights hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Channel Tunnel rail link and Dover-Calais freight corridor position Kent as the UK's primary horticultural import-export node, while the M6 motorway corridor anchors West Midlands distribution networks serving London retail terminals.
Kent and the Southeast
Direct Eurotunnel freight access drives salad crop concentration for continental export markets. Environment Agency water abstraction licensing restricts soil-based expansion, redirecting capital toward closed-loop hydroponic glasshouses near Thanet and Ashford. Thanet Earth exemplifies cluster economics, hosting multiple automated tomato and cucumber producers under unified logistics infrastructure.
West Midlands
Proximity to Birmingham wholesale markets and M6 distribution spurs tomato and pepper greenhouse investment. DEFRA's Sustainable Farming Incentive capital grants fund thermal retrofitting across Worcestershire and Warwickshire installations. Evesham Vale retains historical glasshouse density while newer automated facilities concentrate near Redditch distribution hubs.
East Anglia
Flat agricultural land availability supports large-scale polycarbonate structure deployment for mid-market vegetable production. BSI wind loading certification requirements shape structural specifications across Norfolk and Suffolk exposed coastal plains. Lowestoft nursery clusters specialize in propagation material supply to Kent and Midlands finishing operations.
Yorkshire
Lower land costs relative to southern England enable experimental LED supplemental lighting installations for winter tomato production. Closed-loop hydroponic systems address Environment Agency nitrate discharge constraints in the Humber catchment. Doncaster area glasshouses serve Sheffield-Leeds retail corridors with reduced transport carbon intensity.
Scotland
Short growing seasons necessitate high thermal performance specifications and LED grow light integration for viable tomato and soft fruit production. Scottish Government capital grant schemes support renewable heating infrastructure in Clyde Valley and Aberdeenshire protected cropping facilities. Dundee-area research institutions pilot sensor-integrated climate platforms for northern latitude cultivation protocols.
United Kingdom Commercial Greenhouse Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in a fragmented supply base where structural fabricators, climate technology providers, and hydroponic equipment suppliers operate as distinct capability layers. Market structure shows moderate concentration among established glasshouse constructors, with entry barriers rising from BSI certification requirements and DEFRA grant alignment complexity. Three archetypes dominate: legacy structural fabricators with decades of UK installation heritage, hydroponic technology platforms securing long-term produce supply contracts, and polycarbonate glazing specialists serving cost-sensitive mid-scale operators. Competitive moves center on strategic partnerships with supermarket procurement divisions and vertical integration into automated environmental control systems.
Among UK-based fabricators, Robinsons Greenhouses anchors Midlands manufacturing heritage, while Elite Greenhouses Ltd. occupies the premium bespoke segment for estate and institutional clients. Growponics Ltd. exemplifies the technology-platform archetype, leveraging hydroponic system integration to secure direct retailer contracts. These three represent distinct positioning vectors: regional manufacturing scale, premium customization capability, and produce supply chain integration.
| Leading Market Players |
|---|
| Growponics Ltd. |
| NETAFIM |
| Robinsons Greenhouses |
| Elite Greenhouses Ltd. |
| Cultivar Ltd. |
| Palram Industries Ltd. |
| KEDER GREENHOUSE |
| Griffin Glasshouses Limited |
| Alitex Limited |
| Others |
Pricing and Supply Chain Analysis
Steel and aluminum input volatility determines both tier spreads and supply chain configuration across UK commercial greenhouse manufacturing. Commodity price swings compress fabrication margins and force structural fabricators toward volume-discount contracting with large-scale glasshouse operators.
Pricing Analysis
Volume-discount tiering separates bespoke aluminum-framed glasshouses from standard polycarbonate structures and modular temporary installations. Premium pricing attaches to BSI wind-loading certification and DEFRA grant eligibility alignment, while mid-tier operators compete on thermal efficiency metrics. Cost compression in polycarbonate segments intensifies as Yorkshire and East Anglia vegetable producers prioritize capital efficiency over optical clarity. Small agricultural cooperatives exhibit highest price sensitivity; institutional estate clients demonstrate lowest sensitivity due to customization requirements.
Supply Chain Analysis
Supplier-financing facilities from Dutch and Belgian glazing specialists extend payment terms for Kent glasshouse cluster expansions. Structural steel draws from UK and German mills; aluminum extrusions feed from Spanish and Italian fabricators. Single-source vulnerability concentrates in precision-engineered glazing supply from continental EU suppliers. Distribution runs through Midlands manufacturing corridors and direct-to-site project logistics serving Thanet Earth and Evesham Vale clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automated environmental control retrofits and recurring maintenance contracts expand faster than structural hardware sales. Service-attach revenue from sensor-integrated climate platforms offers margin expansion beyond one-time installation economics.
For Market Incumbents: Entrench position through captive supply of precision-engineered glazing and backward integration into automated control system manufacturing. Threat from hydroponic technology platforms securing direct supermarket contracts demands defensive certification investment in BSI structural standards. Channel control over Kent and West Midlands installation labor pools reinforces contract capture. For New Entrants and Emerging Players: Establish a beachhead in Yorkshire polycarbonate structure deployment where thermal efficiency requirements outpace glasshouse capital intensity. White-space exists in LED supplemental lighting integration for Scottish winter production and containerized greenhouse rapid deployment for research institutions. Go-to-market leverage rests on DEFRA Sustainable Farming Incentive grant navigation expertise. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors platform integrators with produce supply chain contracts over pure-play fabricators. Long-term viability across the projection horizon hinges on supermarket traceability mandate compliance and closed-loop hydroponic technology ownership. Signal to watch: direct sourcing contract awards from major retail chains displacing wholesale market channels.| Strategic Initiative | Industry Significance |
|---|---|
| Automated System Integration | Sensor-integrated climate platforms satisfy Environment Agency discharge compliance and retailer audit protocols. |
| Backward Integration into Glazing Supply | Captive precision-engineered glass production secures BSI certification timelines and margin control. |
| DEFRA Grant Alignment Investment | Capital grant eligibility unlocks funding pathways for thermal retrofit and renewable heating infrastructure. |
| Direct Retailer Contract Securement | Long-term produce supply agreements displace wholesale channels and anchor glasshouse utilization rates. |
| Regional Cluster Expansion | Proximity to Thanet Earth and Evesham Vale logistics infrastructure reduces distribution carbon intensity. |
Research Methodology
Initial hypotheses were tested against primary input from glasshouse operators, structural fabricators, supermarket procurement managers, and DEFRA policy officials and refined through secondary validation. Horticultural supply chain directors, climate technology engineers, and Environment Agency licensing officers contributed operational perspective. Secondary sources encompassed BSI standards documentation, DEFRA scheme criteria publications, Environment Agency discharge regulations, and customs data on aluminum and steel imports. Bottom-up installation demand estimates triangulated against top-down market sizing from capital expenditure tracking.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions spanned structural material tier, installation permanence, automation intensity, end-user scale, and regional regulatory cluster. CAGRs derived from installation volume trends, grant funding trajectories, and retailer contract expansion patterns. Forecast inputs incorporated Environment Agency licensing queue data and DEFRA ELM scheme evolution timelines.
Sensitivities concentrate around post-Brexit phytosanitary protocol friction, commodity input volatility, and supermarket procurement mandate acceleration. Forecasts reflect documented assumptions on grant eligibility continuity and retailer traceability requirement timelines. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Chaga Mushroom Market
Agriculture and Agri Products
LAMEA Rapeseed Oil Market
Agriculture and Agri Products
Tanzania Cashew Market
Agriculture and Agri Products
Africa Animal Protein Market
Agriculture and Agri Products
France Alfalfa Hay Market
Agriculture and Agri Products
North America Swine Feed Premix Market
Agriculture and Agri Products
Manufactured Garden Soil Market
Agriculture and Agri Products
Vietnam Floriculture Market
Agriculture and Agri Products
South Africa Compound Feed Market
Agriculture and Agri Products
Colombia Hemp Market
Agriculture and Agri Products
UAE Agriculture Market
Agriculture and Agri Products
South America Swine Feed Premix Market
Agriculture and Agri Products
American Ginseng Market
Agriculture and Agri Products
Dairy Cattle Feed Market
Agriculture and Agri Products
Alfalfa Hay Market
Agriculture and Agri Products
Netherlands Floriculture Market