
 Polysiloxane Coatings Market | 2026-2036
Polysiloxane Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Polysiloxane Coatings Market Outlook
ISO 12944 corrosion-protection certification is reorganizing competitive tiers among suppliers, as shipyards and offshore fabricators now mandate documented coating-system performance for C5-M and Im2 environments. PPG Industries leverages its marine-certification depth to sustain long-term supply agreements with Korean and Japanese shipbuilders. Akzo Nobel anchors its position through backward integration into silane intermediates, while Hempel A/S competes via specialized technical-service teams embedded at major European and Asian dry-dock facilities.
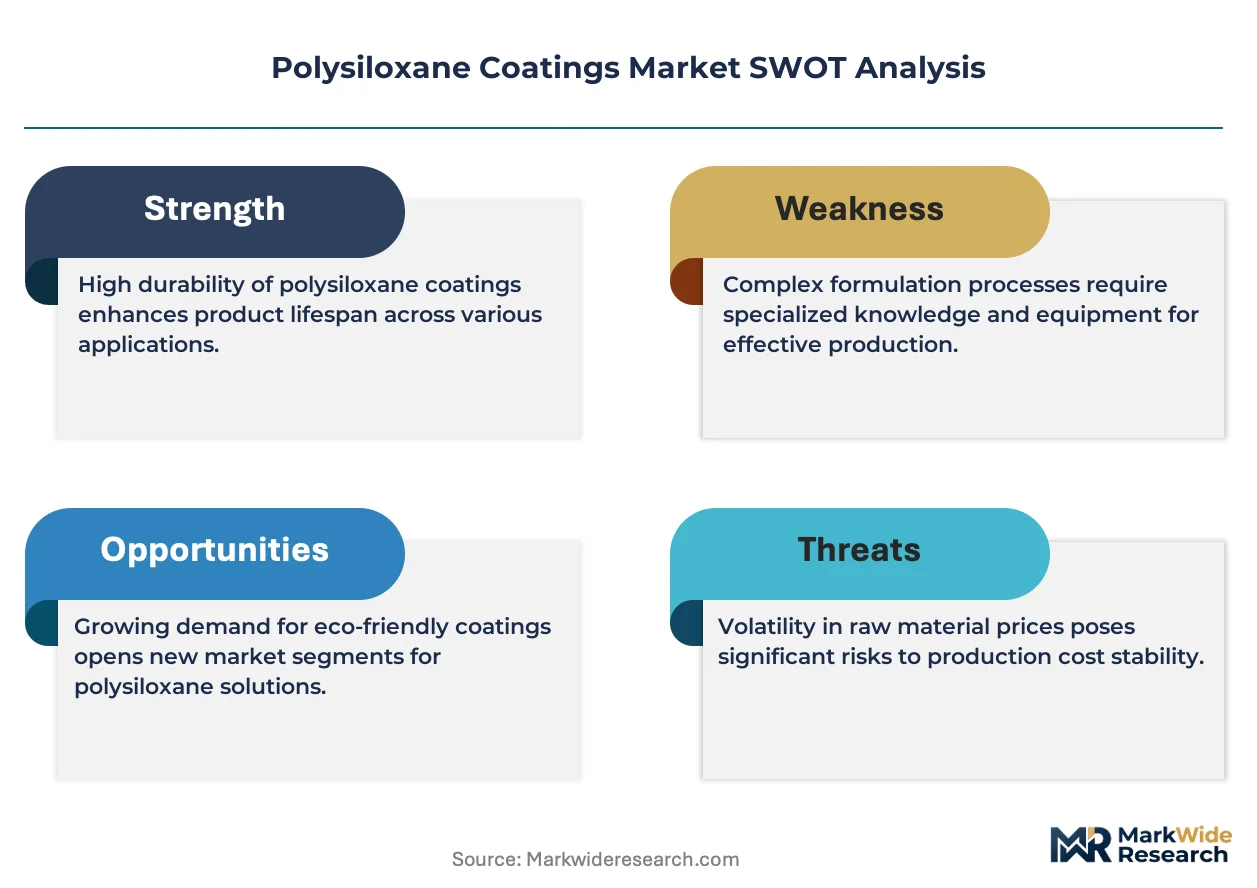
Polysiloxane coatings are organosilicon polymers formed through hydrolysis and condensation of silane precursors, typically featuring Si-O-Si backbone structures with organic side groups that confer UV stability, thermal resistance, and low surface energy; they cure at ambient or elevated temperatures to form dense, breathable films that protect steel, aluminum, and composite substrates from corrosion, fouling, and weathering in harsh industrial and marine exposures. Water-based formulations are gaining share as environmental compliance tightens, though solvent-based systems still dominate margin pools in aerospace and offshore applications where extreme chemical resistance remains non-negotiable. Protective coatings represent the largest application segment by volume, while automotive finishes command premium pricing due to color-match precision and scratch-recovery requirements.
EPA VOC regulations and the EU F-Gas Regulation are tightening permissible solvent content, forcing reformulation investments and testing-protocol updates across North American and European supply chains. China's MEE enforces GB standards on industrial coating emissions, creating parallel compliance tracks for multinational suppliers serving domestic and export markets. Stakeholders must monitor divergence between regional chemical-registration requirements and carbon-border adjustment mechanisms as they allocate R&D budgets and qualify alternative curing chemistries.
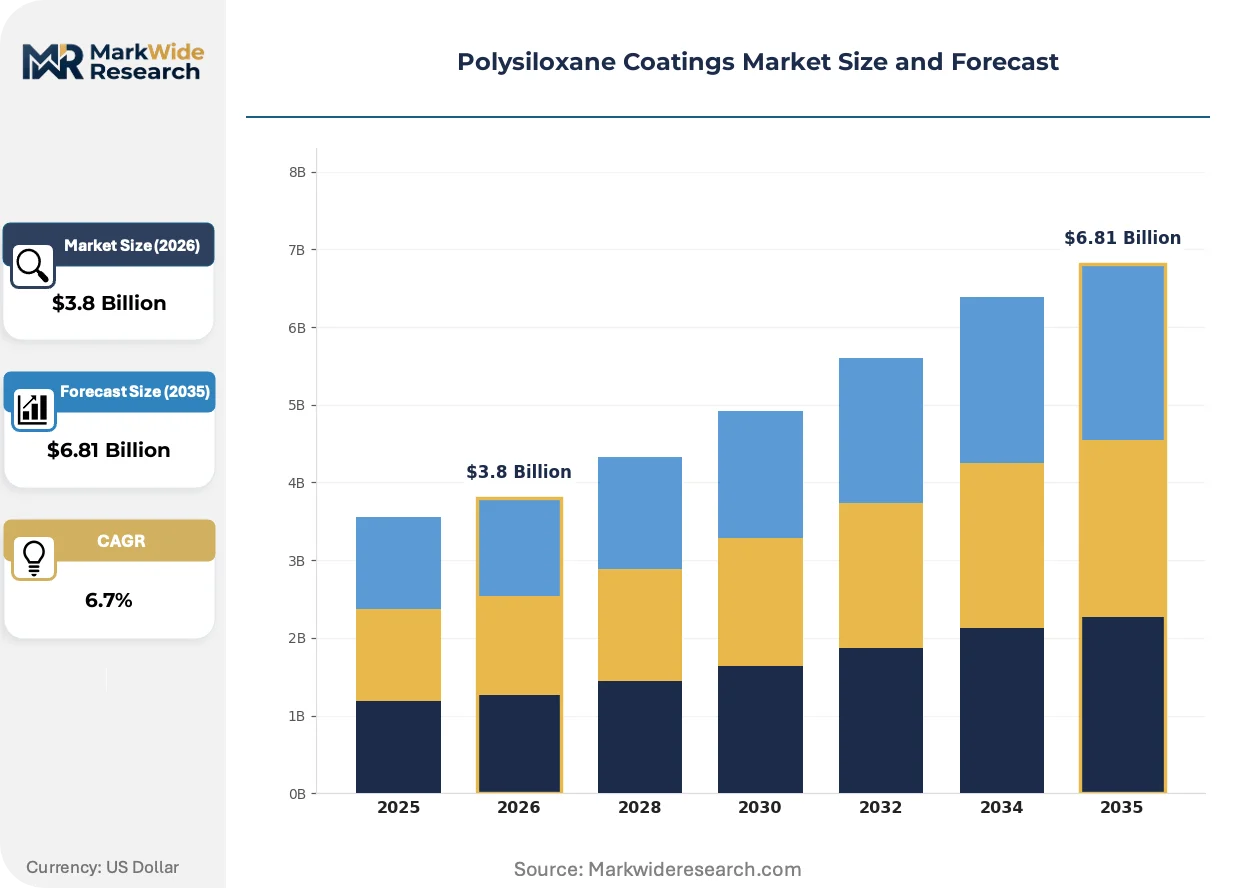
Market Dynamics
Marine fleet operators are compressing dry-dock maintenance intervals by 40% through polysiloxane topcoat adoption, forcing coating suppliers to restructure technical-service deployment around shipyard clusters in South Korea, China, and Japan.
Growth Catalysts
- EPA VOC Rule Tightening:US shipyards face phased solvent-content reductions that accelerate water-based polysiloxane qualification programs. Dry-dock operators in Gulf Coast and Pacific Northwest ports now specify compliant systems for newbuild contracts.
- East Asian Shipbuilding Concentration:South Korean and Chinese yards constructing LNG carriers and ultra-large container vessels drive specification-grade coating demand. These facilities require C5-M certified systems with documented 15-year performance warranties.
- Silane Precursor Chemistry:Advances in ambient-temperature curing formulations reduce energy-intensive bake cycles. This process innovation expands application windows for in-situ maintenance on operating vessels.
Market Restraints
- Petrochemical Feedstock Volatility:Silane monomer and silicone resin prices fluctuate with natural gas and methanol benchmarks. Coating manufacturers lack pricing power to pass through input spikes in long-term marine supply agreements.
- Specialized Applicator Scarcity:Proper film-build application requires trained spray technicians certified to ISO 12944 system specifications. Shipyards in secondary ports face 6-12 month queues for qualified contractor availability.
- Epoxy-Polyurethane Substitution:Lower-first-cost conventional systems retain share in non-certified maintenance segments. Budget-constrained fishing fleets and coastal cargo operators delay polysiloxane upgrades.
Strategic Opportunities
- Offshore Wind Installation Vessels:Im2 corrosion-category specifications for jack-up and heavy-lift ships create new specification-grade demand. European and East Asian fabricators require coating systems validated for splash-zone and atmospheric exposure.
- EU F-Gas Regulation Alignment:Low-solvent polysiloxane formulations qualify for carbon-border adjustment exemptions when exported to EU markets. Asian suppliers reformulating to REACH-compliant chemistries capture premium positioning.
- Digital Coating Specification Platforms:Shipowners and classification societies adopt cloud-based coating selection tools. These channels displace traditional distributor relationships and enable direct technical engagement between manufacturers and fleet technical managers.
Industry Challenges
- ISO 12944-9 Certification Timelines:Laboratory testing and field-exposure validation for new polysiloxane systems require 18-36 months. Suppliers face revenue gaps between formulation completion and shipyard qualification.
- Legacy Substrate Compatibility:In-situ application over aged epoxy or zinc-rich primers demands surface preparation protocols that extend dry-dock occupancy. Ship operators resist coating transitions that compress cargo-loading windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polysiloxane Coatings Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solvent-based, Water-based, UV-cured, Hybrid End Use Industry: Aerospace, Automotive, Marine, Construction Application: Protective Coatings, Decorative Coatings, Industrial Coatings, Automotive Finishes Technology: Spray Coating, Brush Coating, Roller Coating, Dip Coating |
| Companies Covered | Akzo Nobel N.V., PPG Industries, Inc., The Sherwin-Williams Company, Jotun, Hempel A/S, Wacker Chemie AG, Evonik Industries, Momentive Performance Materials, 3M, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polysiloxane Coatings Market Strategic Shifts
Formulation chemistry is bifurcating between ultra-low-VOC waterborne systems for regulatory-compliant newbuilds and high-solids solventborne grades for extreme-service offshore applications where chemical resistance thresholds remain non-negotiable.
Hybrid inorganic-organic polysiloxane-zinc chemistry is decomposing the traditional three-coat epoxy-polyurethane specification stack. Offshore platform operators in the North Sea and Gulf of Mexico specify these systems for reduced film-build requirements and extended maintenance cycles. The technology is compressing total applied cost structures while extending asset protection intervals.
REACH authorization requirements for certain siloxane intermediates are forcing European coating manufacturers to requalify supply chains. ECHA substance evaluation deadlines in 2026-2027 compress reformulation windows for products containing cyclic siloxanes. Marine coating divisions accelerate alternative precursor testing to maintain registration compliance.
Shipowner procurement departments are unbundling coating specification from general shipyard contracts. Major container lines and LNG operators now retain direct technical relationships with coating manufacturers, bypassing traditional shipyard material sourcing. This pattern concentrates most visibly among Japanese and South Korean fleet operators with centralized technical departments.
Polysiloxane Coatings Market Segmentation
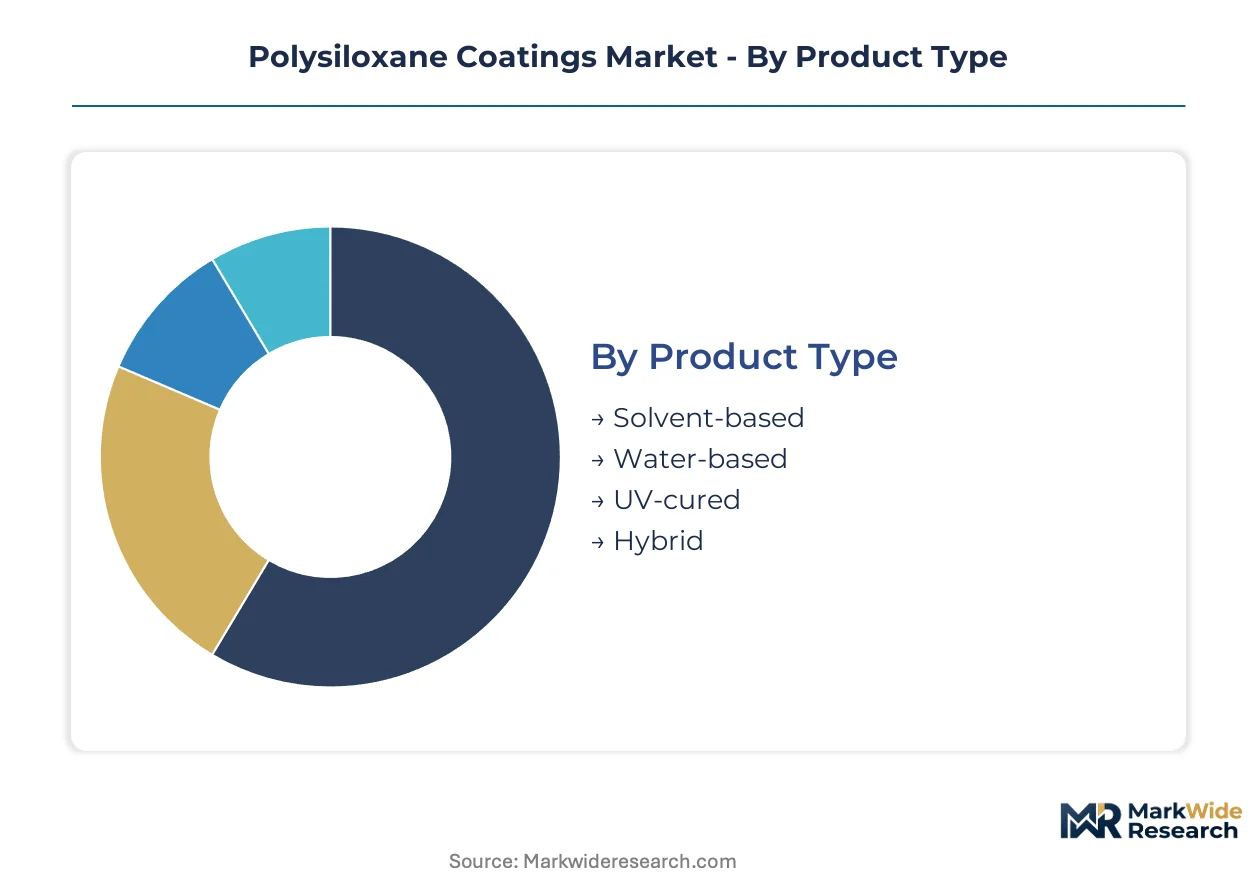
Polysiloxane coatings fragment across formulation chemistry, end-use severity, and application method. Each axis carries distinct regulatory thresholds and margin structures that reshape supplier priorities.
Product Type:
EPA VOC rules and REACH authorization timelines split formulation strategies between compliant waterborne systems and legacy solventborne grades.
- Solvent-based:High-solids formulations deliver chemical resistance for offshore platforms and aerospace maintenance where bake cycles are impractical. North Sea operators specify these systems for splash-zone protection despite tightening emissions caps.
- Water-based:Ultra-low-VOC emulsions now qualify for C5-M marine certifications previously reserved for solventborne grades. South Korean shipyards specify waterborne polysiloxanes for newbuild LNG carriers to meet EU import compliance.
- UV-cured:Rapid polymerization suits automated automotive production lines requiring scratch-resistant clearcoats.
- Hybrid:Polysiloxane-epoxy or polysiloxane-urethane combinations bridge performance gaps in industrial maintenance.
Established volume favors solvent-based; emerging adoption favors water-based.
End Use Industry:
Application severity determines specification grade and warranty duration.
- Marine:C5-M and Im2 corrosion categories demand 15-year performance warranties for LNG carriers and container vessels. South Korean and Chinese yards drive specification-grade volume through centralized procurement.
- Aerospace:Thermal stability and UV resistance command premium pricing for exterior airframe protection. FAA maintenance protocols favor polysiloxane topcoats for fuel efficiency gains.
- Automotive:Color-match precision and scratch-recovery properties differentiate OEM finishes.
- Construction:Weathering resistance protects steel infrastructure in coastal and industrial atmospheres.
Marine anchors procurement scale; aerospace sustains margin concentration.
Application:
Functional purpose separates protective from aesthetic performance requirements.
- Protective Coatings:Corrosion and fouling resistance for steel, aluminum, and composite substrates in chemical plants and offshore structures. ISO 12944 certification gates shipyard qualification.
- Automotive Finishes:Scratch-recovery and color stability command OEM specification. Japanese and German manufacturers specify polysiloxane clearcoats for premium vehicle segments.
- Industrial Coatings:Chemical resistance for processing equipment and storage tanks.
- Decorative Coatings:Weathering protection with aesthetic finish for architectural metalwork.
Protective coatings dominate tonnage; automotive finishes concentrate value.
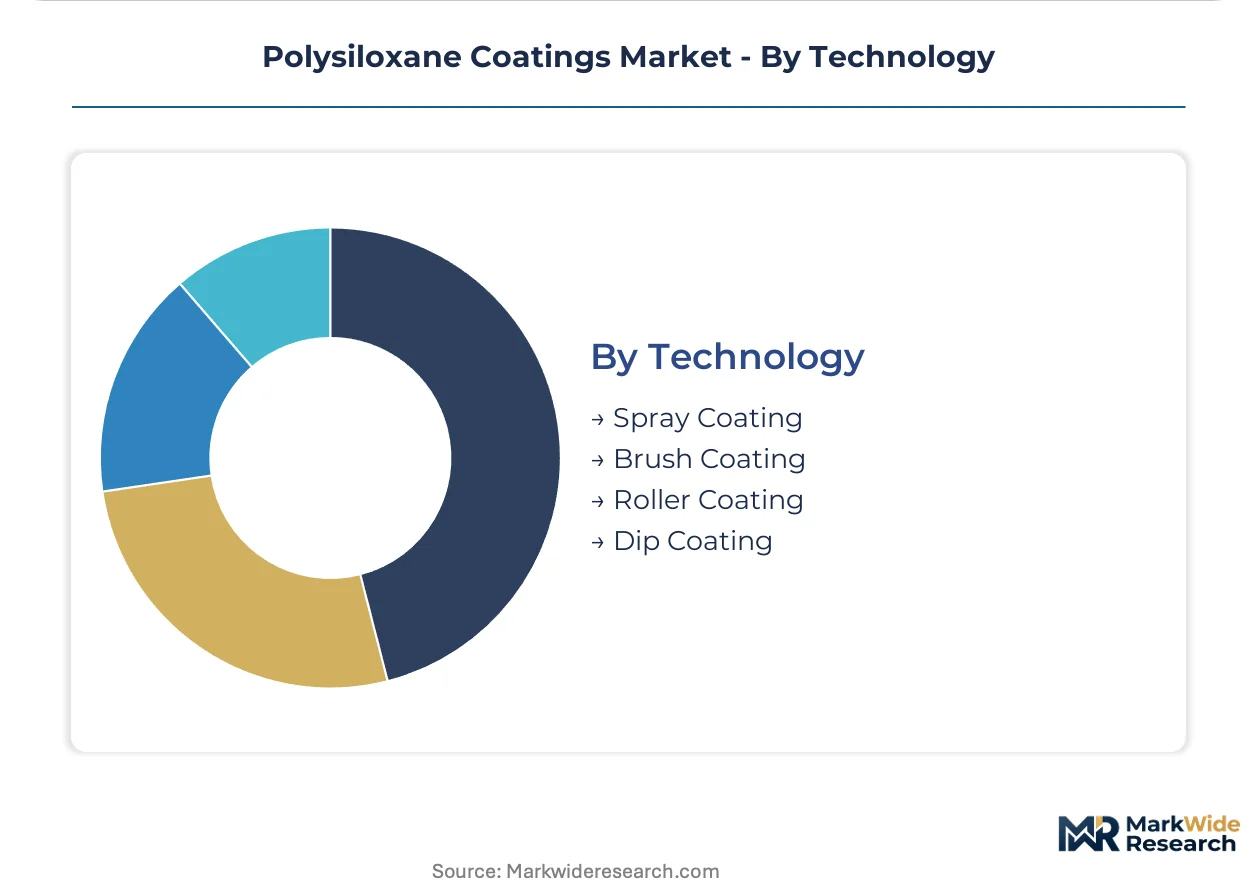
Technology:
Application method constrains film-build precision and labor certification requirements.
- Spray Coating:Airless and electrostatic systems achieve specified dry-film thickness for marine and aerospace substrates. Certified applicator scarcity extends shipyard dry-dock queues.
- Brush Coating:Touch-up and maintenance applications on operating vessels where spray containment is impractical.
- Roller Coating:Flat panel and coil applications in construction and industrial fabrication.
- Dip Coating:Uniform coverage for complex geometries in automotive component manufacturing.
Spray coating commands specification-grade volume; brush coating expands in-situ maintenance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Marine fleet operators and industrial asset managers concentrate procurement authority in East Asian shipbuilding clusters, European offshore fabrication centers, and North American aerospace maintenance hubs. These buyer archetypes drive specification-grade demand across distinct regulatory environments.
China
State-owned shipyards in Dalian and Shanghai construct LNG carriers and container vessels requiring C5-M certified coating systems. The MEE enforces GB standards on industrial coating emissions, creating dual compliance tracks for domestic and export markets. Yangtze River Delta fabrication clusters now specify waterborne polysiloxanes for newbuild contracts bound for EU ports.
South Korea
Hyundai Heavy Industries and Samsung Heavy Industries drive specification-grade volume through centralized technical procurement. KSA certification aligns with ISO 12944-9 testing protocols for 15-year performance warranties. Ulsan and Geoje shipbuilding complexes require embedded technical-service teams from coating suppliers during dry-dock application windows.
United States
Gulf Coast offshore platform operators and Pacific Northwest shipyards face phased EPA VOC content reductions. Dry-dock facilities in Houston and Seattle now mandate compliant systems for newbuild and maintenance contracts. FAA maintenance protocols favor polysiloxane topcoats for commercial airframe fuel efficiency programs.
Germany
Offshore wind installation vessel fabricators in Bremen and Hamburg require Im2 corrosion-category systems for jack-up and heavy-lift ships. ECHA substance evaluation deadlines for cyclic siloxanes compress reformulation windows through 2027. North Sea platform operators specify high-solids solventborne grades for splash-zone protection despite tightening emissions caps.
Japan
ClassNK certification requirements govern coating system selection for domestic and export vessel construction. METI industrial standards align with international maritime regulations for reduced maintenance-cycle coatings. Nagoya and Kobe shipbuilding clusters concentrate specification authority within centralized technical departments of major fleet operators.
Polysiloxane Coatings Market Competitive Environment
Player mix skews toward diversified chemical conglomerates with captive silane precursor supply and specialized marine coating divisions with embedded technical-service capabilities. The market structure concentrates around three to five integrated suppliers capable of ISO 12944-9 certification depth. Strategic archetypes include backward-integrated resin manufacturers, shipyard-embedded service specialists, and aerospace-certified finish suppliers. Dominant competitive moves center on silane intermediate supply security and technical-service deployment density around East Asian shipbuilding clusters.
Among diversified chemical conglomerates, Akzo Nobel N.V. and Wacker Chemie AG occupy positions anchored by upstream control over silane chemistry. PPG Industries, Inc. exemplifies the shipyard-embedded service archetype through marine-certification depth and long-term supply agreements. These three companies represent the tier capable of delivering documented 15-year performance warranties for C5-M and Im2 corrosion categories.
| Leading Market Players |
|---|
| Akzo Nobel N.V. |
| PPG Industries, Inc. |
| The Sherwin-Williams Company |
| Jotun |
| Hempel A/S |
| Wacker Chemie AG |
| Evonik Industries |
| Momentive Performance Materials |
| 3M |
| Others |
Value Chain & Pricing Dynamics
Silane precursor production scale in Germany and Japan anchors cost floors for specification-grade marine coatings, concentrating margin leverage among backward-integrated resin manufacturers while compressing pricing power for formulators lacking captive intermediate supply.
Pricing Analysis
Cost-plus contracts with methanol and natural gas indexation dominate long-term marine supply agreements between Korean shipyards and coating suppliers. Price differentiation separates ISO 12944-9 C5-M certified systems with 15-year warranties from uncertified maintenance grades lacking documented field exposure. Pricing pressure intensifies in solventborne segments as EPA VOC phasedowns accelerate waterborne qualification programs. Budget-constrained fishing fleets exhibit highest price sensitivity, while LNG carrier operators prioritize performance warranties over first cost.
Supply Chain Analysis
Strategic stockpiling of silane monomers and silicone resins characterizes procurement behavior among European coating manufacturers facing ECHA substance evaluation deadlines. Supply concentration centers on Germany, Japan, and China for silane precursor manufacturing. Raw material dependencies include methanol, chlorosilanes, and specialized silicone intermediates. Single-source vulnerability runs through cyclic siloxane registrations under REACH authorization timelines. Distribution runs through embedded technical-service teams at major East Asian shipbuilding clusters rather than traditional distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical-service deployment and certification-linked aftermarket programs represent faster-expanding revenue layers than base coating sales, as shipowners unbundle specification authority from shipyard contracts and seek direct manufacturer relationships for dry-dock maintenance cycles.
For Market Incumbents: Shield ISO 12944-9 certification depth through accelerated field-exposure validation programs before ECHA substance evaluation deadlines eliminate legacy cyclic siloxane formulations. Deepen backward integration into silane intermediates to offset methanol price volatility that erodes margin in long-term marine agreements. Prioritize embedded technical-service density at Ulsan and Geoje shipbuilding complexes where Hyundai and Samsung concentrate procurement authority. For New Entrants and Emerging Players: Differentiate on ambient-temperature curing chemistry that compresses dry-dock occupancy for in-situ maintenance on operating vessels. Target secondary ports in Southeast Asia facing 6-12 month queues for ISO-certified applicator availability. Pursue direct technical engagement with fleet technical managers through digital coating specification platforms displacing traditional distributor relationships. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors coating divisions with captive silane supply and established C5-M/Im2 certification depth over pure-play formulators exposed to feedstock volatility. Long-term viability hinges on REACH-compliant precursor transitions and waterborne qualification completion. The signal to watch is shipowner procurement unbundling velocity—acceleration indicates structural channel shift toward manufacturer-direct technical relationships.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silane Intermediates | Captive methanol-to-silane production insulates margin from petrochemical feedstock volatility. |
| ISO 12944-9 Certification Investment | Documented C5-M performance warranties gate qualification at Korean and Chinese LNG carrier yards. |
| Waterborne Formulation Transition | Ultra-low-VOC systems capture EU carbon-border adjustment exemptions for export-bound vessels. |
| Embedded Technical-Service Expansion | Shipyard-embedded teams at Ulsan and Geoje complexes secure long-term supply agreement renewals. |
| Digital Specification Platform Development | Cloud-based tools enable direct engagement with fleet technical managers bypassing distributor channels. |
Study Parameters
Cross-validation between primary interviews with marine coating technical directors, shipyard procurement managers, and classification society surveyors anchors the qualitative findings, while secondary validation draws from customs trade data, SEC 10-K filings of diversified chemical conglomerates, and ECHA substance registration databases. Bottom-up triangulation aggregates segment-level volume estimates from shipyard coating specification data; top-down validation cross-checks against silane precursor production capacity reported by major manufacturers.
Sensitivity analysis around methanol price trajectories and EPA VOC compliance timelines shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include formulation chemistry, corrosion protection category, end-use severity, and regional regulatory cluster. CAGRs derive from installed base growth in LNG carrier and container vessel fleets combined with maintenance-cycle compression factors. Industry-specific inputs encompass ISO 12944-9 certification adoption curves and shipowner procurement unbundling rates.
The analysis sits within stated boundaries; outcomes outside sustained East Asian shipbuilding output levels or accelerated REACH substance restrictions would require recalibration. Forecasts reflect assumptions regarding silane precursor supply continuity and classification society certification protocol stability. Revision becomes warranted when ECHA evaluation outcomes or EPA enforcement intensity cross thresholds that alter reformulation investment requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Wood Preservative Coatings Market
Coatings
Africa Automotive Refinish Coatings Market
Coatings
Self-Cleaning Coatings Market
Coatings
Global Polyaspartic Coatings Market
Coatings
South America Thermal Spray Market
Coatings
Global Hydrophobic Coating Market
Coatings
Leisure Boat Marine Coatings Market
Coatings
Perfluoroalkoxy (PFA) Coatings Market
Coatings
Germany Industrial Coatings Market
Coatings
Germany Protective Coatings Market
Coatings
North America Polyimide Coating Market
Coatings
Global Fluorinated Ethylene Propylene (FEP) Coatings Market
Coatings
France Protective Coatings Market
Coatings
Asia-Pacific Radiation Curable Coatings Market
Coatings
Hull Coatings Market
Coatings
US Industrial Coatings Market