
 Batters and Coatings Market | 2026-2036
Batters and Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Batters and Coatings Market Outlook
Asian flour-milling conglomerates is repositioning their wet-mix capacity toward gluten-free and rice-based batter formulations for Southeast Asian export markets. BASF leverages its emulsifier portfolio to supply modified starches that improve adhesion in high-humidity frying environments. PPG Industries anchors North American industrial coating applications with specialized barrier technologies for food-contact surfaces. SK ie technology competes in adjacent membrane-coating expertise that informs moisture-control innovations in edible film layers.
Batters and coatings comprise engineered starch-protein suspensions and particulate dredges applied to food substrates before thermal processing, typically achieving 8-15% pickup weight and forming moisture-sealing barriers at 160-190°C oil temperatures. Their primary commercial purpose is to deliver texture contrast, fat-barrier protection, and visual uniformity across fried, baked, and retorted food systems. Batter Mix and Tempura categories lead value capture in Asian food-service channels where hydration stability and cold-storage tolerance command premium positioning. Coating applications for Seafood and Snacks represent the fastest-expanding demand pools as retail brands seek shelf-life extension without phosphate-based moisture retention. Fried Foods maintains mature volume dominance but faces margin compression from oil-cost volatility and filtration-system capital requirements.
FDA GRAS notifications and USDA FSIS labeling standards govern ingredient safety and allergen disclosure for batters sold into U.S. food-service and retail channels, while EFSA additive authorizations and EU Green Deal farm-to-fork targets are accelerating clean-label reformulations across European supply chains. REACH chemical registrations and F-Gas Regulation compliance further constrain solvent-based coating chemistries, pushing investment toward water-dispersed and powder-coating alternatives. Stakeholders must monitor how dual carbon goals in China and emerging ASEAN national food-codex harmonization reshape raw-material sourcing qualifications and cross-border formulation approvals.
Market Dynamics
Clean-label reformulation mandates from EFSA and sodium reduction targets are compressing legacy additive portfolios while redirecting R&D budgets toward rice-based and gluten-free wet-batter systems for Southeast Asian export channels.
Growth Catalysts
- Quick-service restaurant expansion:Southeast Asian QSR chains are broadening coated protein menus to capture urban consumption growth, pulling batter volume through centralized commissary supply agreements.
- REACH chemical registration pressure:European solvent-based coating restrictions are accelerating water-dispersed and powder-coating alternatives, opening formulation service opportunities for compliant suppliers.
- Wet-batter hydration stability:Cold-storage tolerance improvements in tempura and batter-mix categories are commanding premium positioning in Asian food-service channels.
Market Restraints
- Palm oil price volatility:Input cost swings in frying media are compressing margins for fried-food processors and forcing capital allocation toward filtration-system upgrades.
- Modified starch supply concentration:Asian flour-milling conglomerates control critical wet-mix capacity, creating sourcing risk for European and North American coating formulators.
- Moisture-barrier technical ceiling:Phosphate-free shelf-life extension requirements for seafood coatings remain unmet at commercial scale, limiting clean-label penetration.
Strategic Opportunities
- Vietnam production hub scaling:Regional wet-batter capacity expansion for export markets offers co-manufacturing partnerships to brands seeking ASEAN cost bases.
- Retort-stable coating systems:Emerging demand for shelf-stable coated snacks in ambient retail channels rewards heat-resistant barrier technology development.
- EU Green Deal farm-to-fork alignment:Carbon footprint disclosure requirements favor regional sourcing networks and low-energy drying processes.
Industry Challenges
- Clean-label reformulation timelines:EFSA additive authorization delays and sodium mandate compliance are extending product development cycles by 12-18 months.
- Cross-border formulation harmonization:Divergent ASEAN national food-codex standards create regulatory fragmentation for multi-market batter suppliers.
- High-humidity frying adhesion:Tropical climate performance requirements demand specialized emulsifier systems that strain technical service capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Batters and Coatings Market |
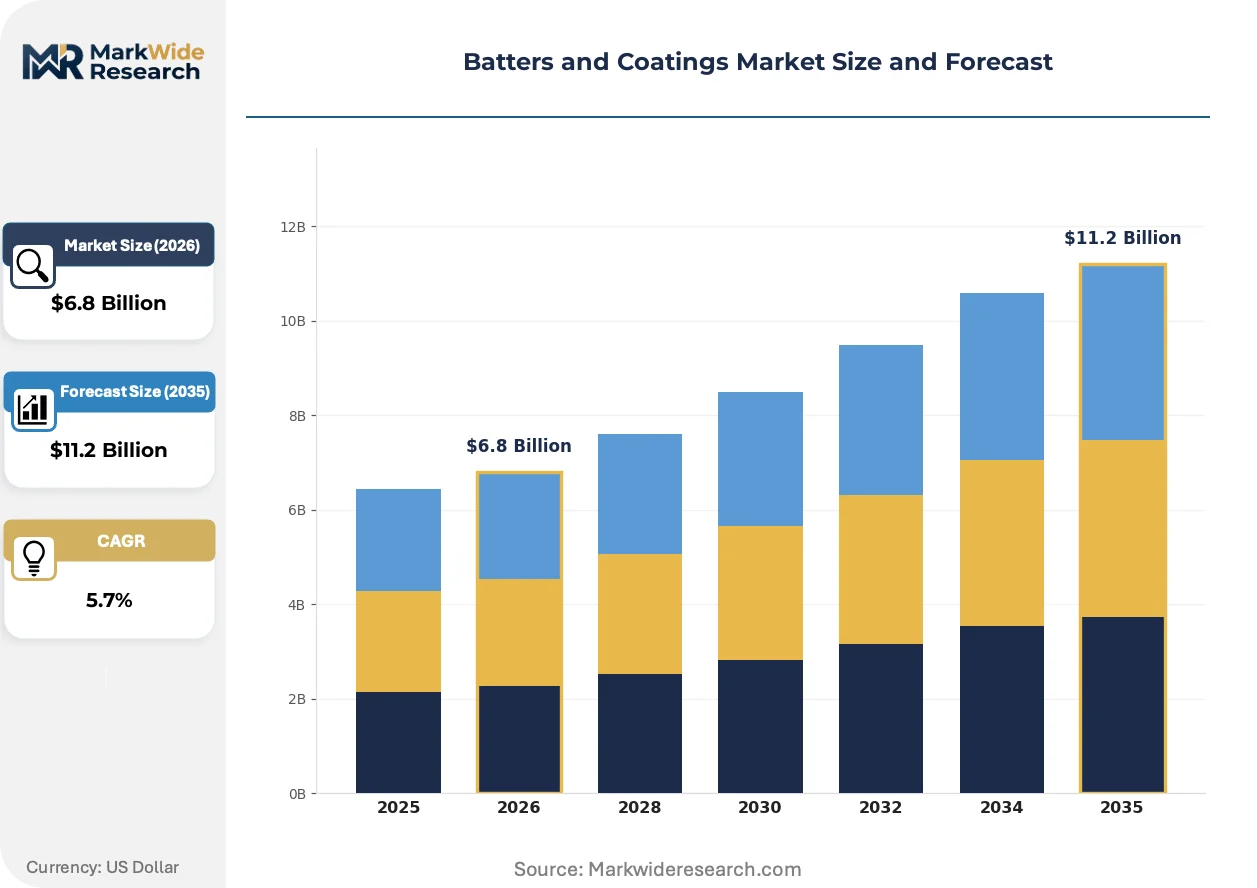
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Batter Mix, Breading, Tempura, Coating Application: Fried Foods, Baked Goods, Snacks, Seafood End User: Restaurants, Food Service, Home Cooking, Industrial Packaging Type: Bulk Packaging, Pouches, Boxes, Bags |
| Companies Covered | Sumitomo Chemical, Celgard, Asahi Kasei, BASF, UBE Corporation, Toray Industries, Mitsubishi Chemical, PPG Industries, SK ie technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Batters and Coatings Market Strategic Shifts
Formulation science and thermal processing control are converging to redefine texture engineering, barrier performance, and supply-chain transparency across fried, baked, and retorted food systems.
Engineered starch-protein suspension technology is modularizing batter system architecture. Food manufacturers are adopting component-based formulations that separate hydration, adhesion, and browning functions into interchangeable modules. This approach is compressing SKU proliferation while enabling rapid regional customization for humidity and oil-type variations.
EFSA clean-label mandates and EU Green Deal carbon accounting requirements are restructuring ingredient sourcing. Additive authorization restrictions are eliminating synthetic phosphate alternatives from seafood coating portfolios. European retail brands are responding with accelerated supplier audits and farm-level certification requirements that propagate through Southeast Asian raw-material networks.
Centralized commissary procurement is consolidating volume among fewer batter suppliers with full-service technical support. Asian QSR chains are displacing distributed local sourcing with regional production hub contracts that bundle formulation, logistics, and frying equipment calibration. Vietnam and Indonesia host the most visible concentration of these integrated supply agreements.
Batters and Coatings Market Segmentation
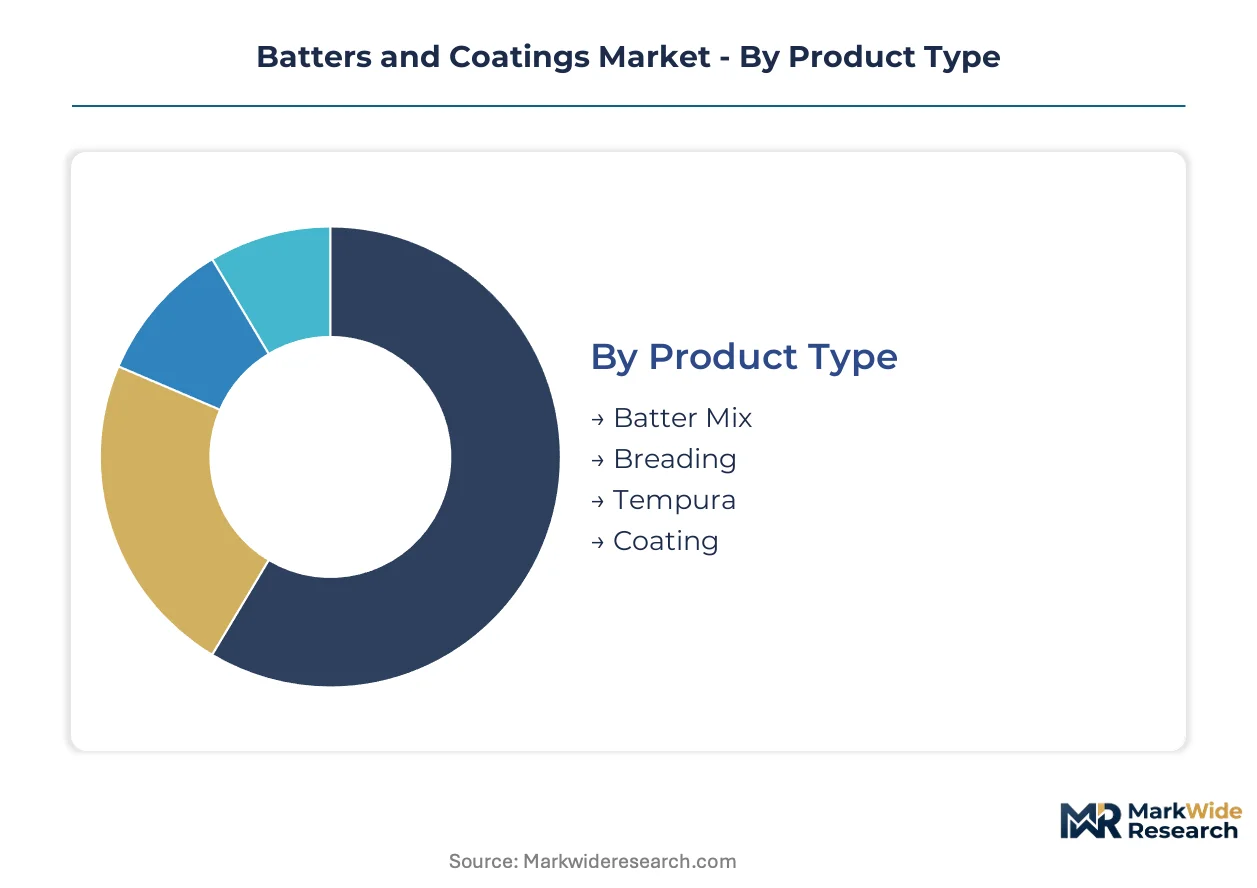
Segmentation in batters and coatings reveals distinct technical requirements across thermal processing methods and distribution channels. Formulators must balance hydration stability, adhesion performance, and clean-label compliance differently for each segment.
Product Type:
Volume concentration favors standardized dry-mix formats while premium positioning clusters around specialized wet-batter systems with extended cold-storage tolerance.
- Batter Mix:Engineered starch-protein suspensions designed for 8-15% pickup weight and moisture-sealing barrier formation at 160-190°C. Demand concentrates in Asian food-service channels where centralized commissary procurement rewards hydration stability and SKU consolidation.
- Tempura:Delicate, low-density coating systems requiring precise viscosity control and rapid dehydration for crispy texture retention. Vietnamese and Indonesian production hubs are scaling wet-batter capacity for export markets, pulling technical service investment toward tropical climate adhesion solutions.
- Breading:Particulate dredges applied as dry coatings before thermal processing, delivering textural contrast through particle size distribution engineering.
- Coating:Functional barrier layers including edible films and retort-stable systems for shelf-life extension without phosphate-based moisture retention.
Mature deployment sits with Batter Mix. Newer deployment is concentrated in Tempura.
Application:
Margin structure diverges sharply between high-volume fried formats and emerging clean-label categories facing technical ceilings.
- Fried Foods:Mature volume dominance across QSR and retail channels, though processors face margin compression from palm oil price volatility and mandatory filtration-system capital allocation. EFSA sodium reduction mandates are forcing reformulation of legacy additive portfolios.
- Seafood:Phosphate-free shelf-life extension requirements remain unmet at commercial scale, limiting clean-label penetration despite retail brand demand. This application is climbing the fastest as brands seek barrier performance without synthetic moisture retention.
- Snacks:Ambient retail shelf-stable formats driving heat-resistant coating development for retort processing compatibility.
- Baked Goods:Lower-temperature thermal processing requirements favor egg-based adhesion systems and reduced oil-barrier specifications.
Volume leadership resides with Fried Foods. Technical innovation investment flows toward Seafood.
End User:
Procurement concentration is displacing fragmented local sourcing as Asian QSR chains consolidate around regional hub contracts.
- Food Service:Centralized commissary supply agreements bundle formulation, logistics, and frying equipment calibration. Southeast Asian QSR expansion is pulling batter volume through technical support-intensive partnerships.
- Restaurants:Independent operator demand favors flexible pack sizes and simplified hydration protocols with minimal equipment requirements.
- Industrial:Large-scale processors require consistent pickup weight control and extended production run stability for automated coating lines.
- Home Cooking:Retail pouch formats emphasizing convenience and foolproof preparation instructions with limited technical support access.
Contract consolidation is reshaping Food Service. Fragmented demand persists in Restaurants.
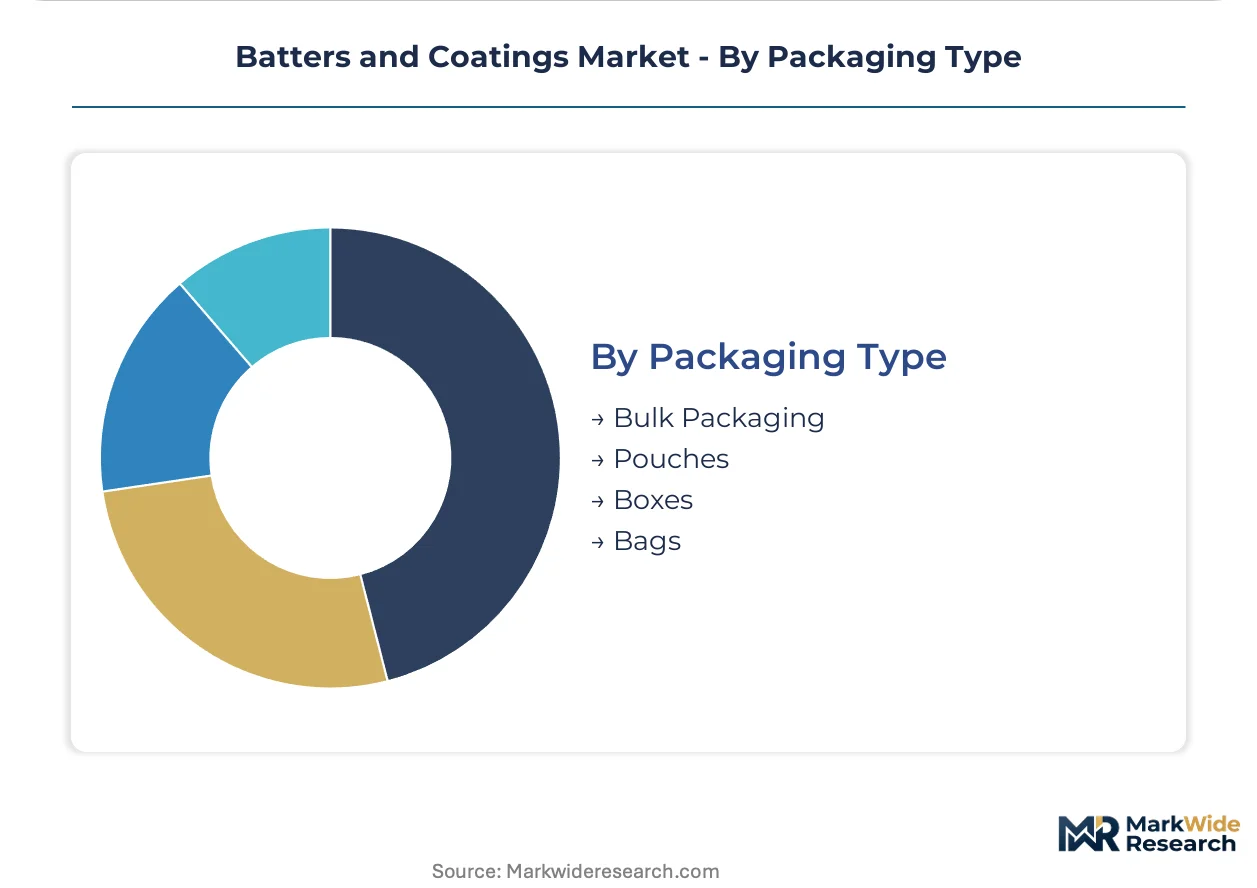
Packaging Type:
Distribution economics favor bulk formats for industrial scale while premium positioning attaches to portion-controlled retail configurations.
- Bulk Packaging:Tanker and tote formats for industrial processors and centralized commissaries with dedicated handling infrastructure and high-throughput requirements.
- Pouches:Single-use retail portions with moisture-barrier laminates preserving hydration stability for home cooking segments.
- Boxes:Food-service case packs optimized for stackability and warehouse efficiency in regional distribution centers.
- Bags:Flexible intermediate formats bridging institutional and retail channels with resealability features.
Cost efficiency anchors Bulk Packaging. Convenience premiums attach to Pouches.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rice flour milling in Vietnam's Mekong Delta and modified starch processing in Thailand's Chao Phraya basin anchor Southeast Asian wet-batter supply networks. EFSA sodium mandates and China's dual carbon goals are reshaping regional formulation standards.
United States
QSR chains and frozen food processors drive batter volume through centralized commissary contracts. FDA GRAS notifications and USDA FSIS labeling standards govern allergen disclosure requirements. Chicago and Atlanta host technical service hubs supporting regional coating formulators.
Germany
Industrial bakery and frozen food sectors demand clean-label coating systems with phosphate-free moisture retention. REACH chemical registrations and EU Green Deal farm-to-fork targets accelerate water-dispersed alternatives. Cologne-Düsseldorf corridor concentrates R&D facilities for barrier technology development.
China
Domestic QSR expansion and export-oriented seafood processing pull modified starch demand through Yangtze River Delta manufacturing clusters. SAMR food safety standards and dual carbon goals constrain solvent-based coating chemistries. Shanghai and Ningbo anchor wet-mix capacity for Asian export markets.
Vietnam
Regional production hub scaling attracts co-manufacturing partnerships for ASEAN cost bases. National food-codex harmonization efforts align with emerging ASEAN standards for cross-border formulation approvals. Ho Chi Minh City and Mekong Delta provinces concentrate rice-based batter capacity expansion.
Indonesia
Quick-service restaurant networks drive coated protein menu expansion across urban consumption centers. FSSAI-aligned import standards and domestic halal certification requirements shape ingredient sourcing. Jakarta and Surabaya host integrated supply agreements bundling formulation and logistics services.
Batters and Coatings Market Competitive Environment
Global majors compete with regional champions across emulsifier technology and wet-batter formulation capabilities. Market structure shows moderate consolidation around Asian flour-milling conglomerates controlling critical wet-mix capacity, with specialized coating chemical suppliers occupying distinct technology tiers. Three archetypes dominate: diversified chemical conglomerates with emulsifier portfolios, Asian flour-millers with captive starch processing, and industrial coating specialists with barrier technology expertise. Competitive moves concentrate on capacity expansion in Vietnam and Indonesia production hubs, and strategic partnerships linking formulation services with QSR commissary procurement.
Within the diversified chemical tier, BASF SE and Mitsubishi Chemical occupy positions spanning emulsifier supply and modified starch development. Among Asian industrial specialists, Sumitomo Chemical and UBE Corporation exemplify integrated chemical producers with adjacent coating material capabilities. Toray Industries and Asahi Kasei sit within the membrane and barrier technology archetype, with expertise informing moisture-control innovations. SK ie technology represents Korean industrial conglomerate positioning in coating-adjacent technologies.
| Leading Market Players |
|---|
| Sumitomo Chemical |
| Celgard |
| Asahi Kasei |
| BASF |
| UBE Corporation |
| Toray Industries |
| Mitsubishi Chemical |
| PPG Industries |
| SK ie technology |
| Others |
Value Chain & Pricing Dynamics
Palm oil futures benchmarks cascade through batter and coating supply chains, compressing margins at fried-food processors while amplifying pricing power for Asian flour-milling conglomerates with captive starch processing. This commodity volatility stratifies procurement costs across premium tempura formulations, standard batter-mix tiers, and economy breading grades.
Pricing Analysis
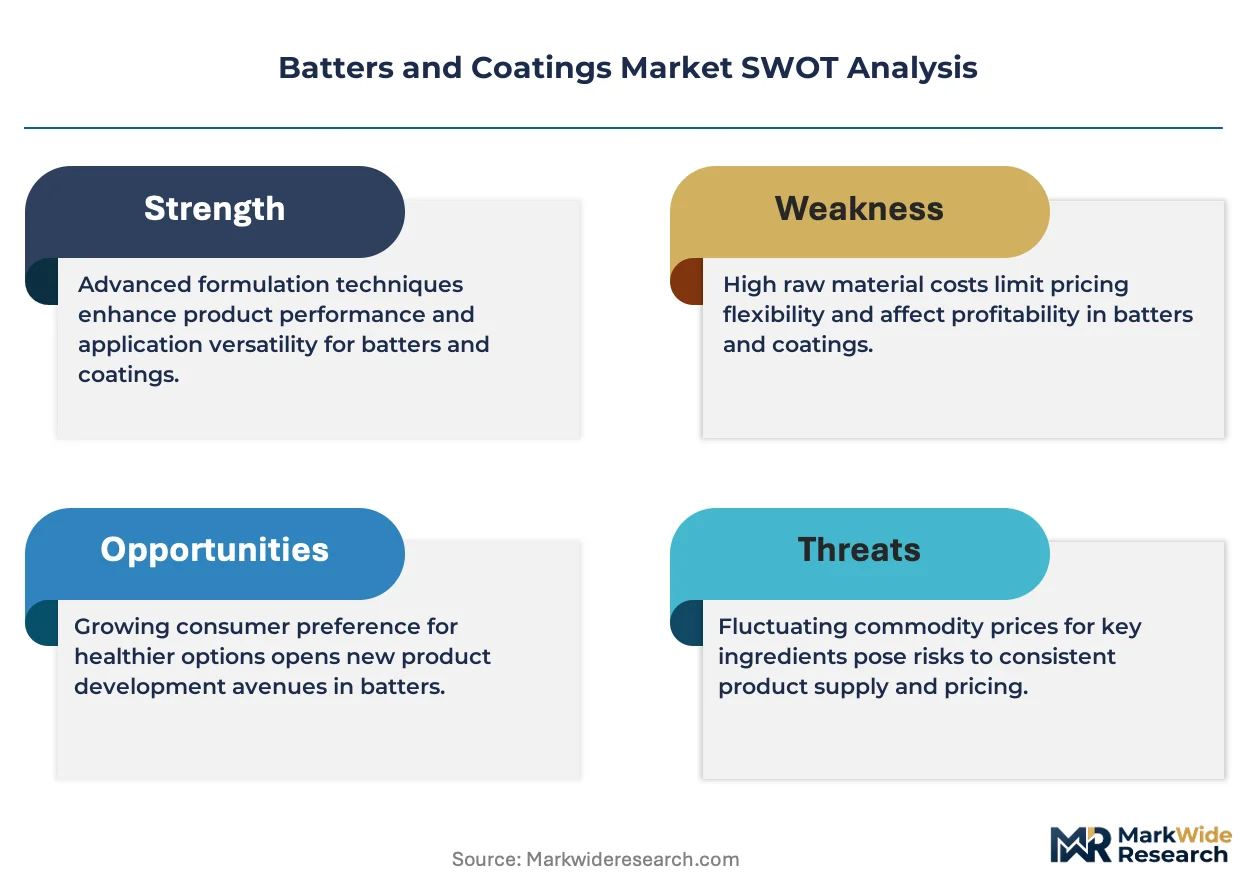
Technical service bundling separates premium positioning from unbundled commodity supply. Three-tier pricing structure across premium, standard, and economy levels reflects hydration stability specifications, EFSA clean-label certification tiers, and volume scale commitments. Cost compression in economy segments is intensifying because palm oil price volatility forces capital diversion toward filtration-system upgrades. Quick-service restaurant chains exhibit highest price sensitivity due to centralized commissary procurement consolidation, while industrial processors with automated coating lines absorb premiums for extended production run stability.
Supply Chain Analysis
Container freight rate fluctuations from Southeast Asian ports reshape landed cost economics for European and North American coating formulators. Supply concentrates in Vietnam, Indonesia, and Thailand, where rice flour milling and modified starch processing anchor wet-batter capacity. Formulation draws from palm oil derivatives, rice flour, and specialized emulsifier systems. Single-source vulnerability concentrates in Asian flour-milling conglomerates controlling critical wet-mix capacity. Distribution runs through regional production hub contracts bundling formulation, logistics, and frying equipment calibration services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Modified starch supply concentration in Asian flour-milling conglomerates props pricing power across premium wet-batter tiers, constraining volume growth for formulators without captive sourcing.
For Market Incumbents: Extend technical service capacity toward tropical climate adhesion solutions in Vietnam and Indonesia production hubs. Asian QSR commissary consolidation threatens margin capture for suppliers lacking integrated formulation-logistics-calibration bundles. Backward integration into rice flour milling secures input cost control against palm oil volatility. For New Entrants and Emerging Players: EU Green Deal farm-to-fork targets in Europe open a window for phosphate-free moisture retention technologies in seafood coatings. Clean-label reformulation gaps in retort-stable systems present the most penetrable white space. Target co-manufacturing partnerships with Vietnamese wet-batter capacity expansions as the fastest route to ASEAN cost-base positioning. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap coating chemical specialists with barrier technology expertise in Germany's Cologne-Düsseldorf corridor. Long-term viability hinges on water-dispersed formulation capabilities displacing solvent-based alternatives. Watch EFSA additive authorization timelines as the inflection signal for clean-label portfolio valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Vietnam | Ho Chi Minh City wet-batter scale-up captures ASEAN export demand through integrated supply agreements. |
| Backward Integration into Rice Flour | Mekong Delta milling control insulates margin compression from Asian conglomerate supply concentration. |
| Clean-Label Reformulation Partnership | EFSA-compliant phosphate-free systems unlock European retail seafood coating contracts. |
| Technical Service Hub Establishment | Jakarta calibration centers bundle frying equipment support with QSR commissary procurement. |
| Retort-Stable Coating Development | Heat-resistant barrier technology addresses ambient shelf-stable snack demand in Asian retail channels. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with coating formulators, QSR procurement directors, flour-milling plant managers, and EFSA regulatory affairs specialists combined with EFSA additive authorization databases, ASEAN food-codex harmonization documents, and palm oil futures market data. Bottom-up volume modeling triangulated against top-down market sizing across product type, application, and end-user segments.
Segment-level granularity modeled Batter Mix, Tempura, Breading, and Coating product types alongside Fried Foods, Seafood, Snacks, and Baked Goods applications across the projection horizon. End-user distinctions captured Food Service, Restaurants, Industrial, and Home Cooking procurement patterns. CAGRs derived from trend extrapolation of QSR expansion rates, clean-label reformulation adoption curves, and wet-batter capacity buildout timelines. Palm oil price volatility assumptions and EFSA authorization delay scenarios informed sensitivity testing.
The model assumes a particular technology adoption path; alternative pathways for phosphate-free moisture retention would alter the outlook for seafood coating penetration. Forecasts reflect assumptions about ASEAN food-codex harmonization progress and dual carbon goal implementation in China. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Global Mirror Coatings Market
Coatings
Clear Coatings Market
Coatings
Anti-Corrosion Nanocoatings Market
Coatings
Diamond-Like Carbon Coatings Market
Coatings
Spain Automotive OEM Coatings Market
Coatings
Technical Coil Coatings Market
Coatings
Europe Super Hydrophobic Coatings Market
Coatings
Japan Protective Coatings Market
Coatings
Superhydrophobic Coatings Market
Coatings
Powder Coating Booth Market
Coatings
Global Intumescent Coatings Market
Coatings
Global Conformal Coatings Market
Coatings
Energy Efficient Powder Coatings Market
Coatings
Global Floor Coatings Market
Coatings
Electrocoat Market
Coatings
Anti-Adhesion Coatings Market