
 Asia-Pacific Coil Coatings Market | 2026-2036
Asia-Pacific Coil Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Coil Coatings Market Outlook
Skilled polymer chemist availability across East Asia is bifurcating competitive capacity between multinational formulators and regional challengers. AkzoNobel leverages its integrated resin supply chain to secure formulation consistency across Chinese and Indian production hubs. BASF anchors its position through captive acrylic acid derivatives that feed directly into polyester coil coating lines. Nippon Paint Holdings Co., Ltd dominates Japan's domestic architectural metal segment while extending technical service networks into Vietnam and Indonesia.
Asia-Pacific coil coatings comprise factory-applied liquid or powder systems cured onto continuous metal strips, typically achieving dry film thicknesses of 15-25 micrometers to deliver corrosion resistance, color stability, and UV durability for exterior building envelopes and appliance housings. Polyester formulations occupy the volume lead across China's commercial construction sector due to cost-performance balance in humid subtropical climates. Liquid coating technology sustains the majority share in existing coil lines, though powder coating is gaining traction among Japanese and South Korean appliance manufacturers seeking zero-VOC compliance and thicker protective films.
China's MEE enforces progressively tighter VOC limits on industrial coatings, compelling reformulation investments from all market participants. Japan's METI energy-efficiency standards for commercial buildings elevate demand for solar-reflective coil coatings that reduce cooling loads. India's BIS certification requirements for construction materials create compliance barriers for unqualified imports while privileging established domestic producers. Stakeholders must monitor how carbon-border adjustment mechanisms and evolving green building codes across ASEAN reshape specification criteria and supplier qualification timelines.
Market Dynamics
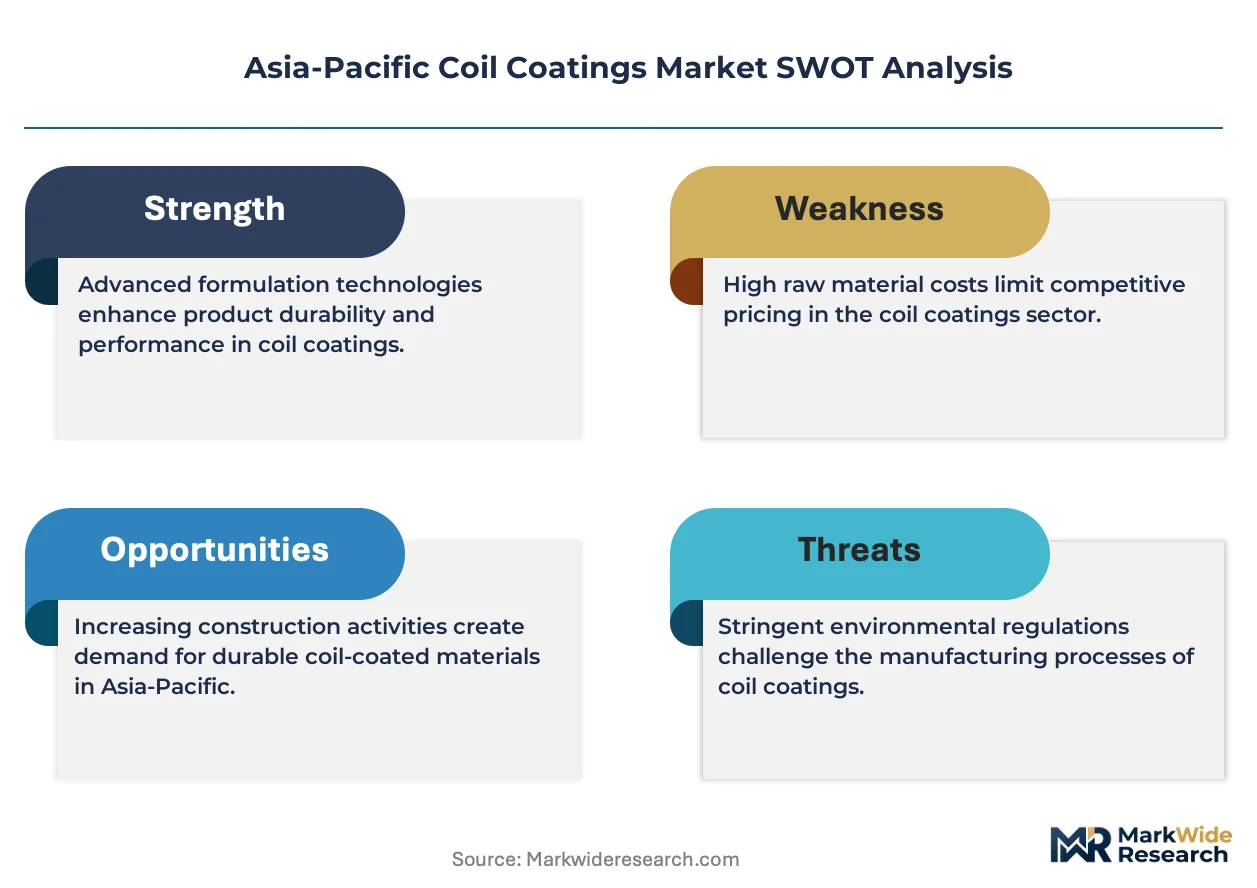
China's MEE VOC emission standards are forcing wholesale reformulation across polyester and fluoropolymer coating lines, compressing solvent-borne capacity while reallocating capital toward waterborne curing systems and high-solid alternatives.
Growth Catalysts
- Dual carbon goals:China's national carbon neutrality targets are accelerating factory-applied coating adoption over field-applied alternatives, reducing on-site solvent emissions across commercial construction projects.
- Pre-painted metal roofing:Southeast Asian commercial developments are specifying coil-coated cladding for accelerated build schedules and weather-resistant envelopes in humid subtropical conditions.
- MEE enforcement:Progressive tightening of industrial coating VOC limits is compelling coating line upgrades and reformulation investments from all market participants.
Market Restraints
- Titanium dioxide volatility:Pigment input cost swings compress margin predictability for polyester formulation specialists serving price-sensitive construction segments.
- Resin supply concentration:Captive acrylic acid derivative production at select multinational formulators limits independent access for regional challengers across Chinese and Indian production hubs.
- Curing temperature floors:Waterborne systems require elevated bake profiles incompatible with legacy coil lines, stranding capital-intensive infrastructure.
Strategic Opportunities
- Vietnam manufacturing expansion:Greenfield appliance and construction material facilities are creating first-mover advantage for technical service networks establishing local formulation support.
- Solar-reflective specifications:Japan's METI energy-efficiency standards for commercial buildings are elevating demand for infrared-reflective coil coatings that reduce cooling loads.
- Powder coating convergence:Zero-VOC compliance requirements and thicker protective film demands are driving Japanese and South Korean appliance manufacturers toward powder system trials.
Industry Challenges
- Polymer chemist scarcity:Skilled formulation talent bifurcation between multinational and regional players constrains rapid reformulation cycles for waterborne system migration.
- BIS certification timelines:India's construction material approval processes create qualification barriers for unqualified imports while privileging established domestic producers with existing laboratory relationships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Coil Coatings Market |
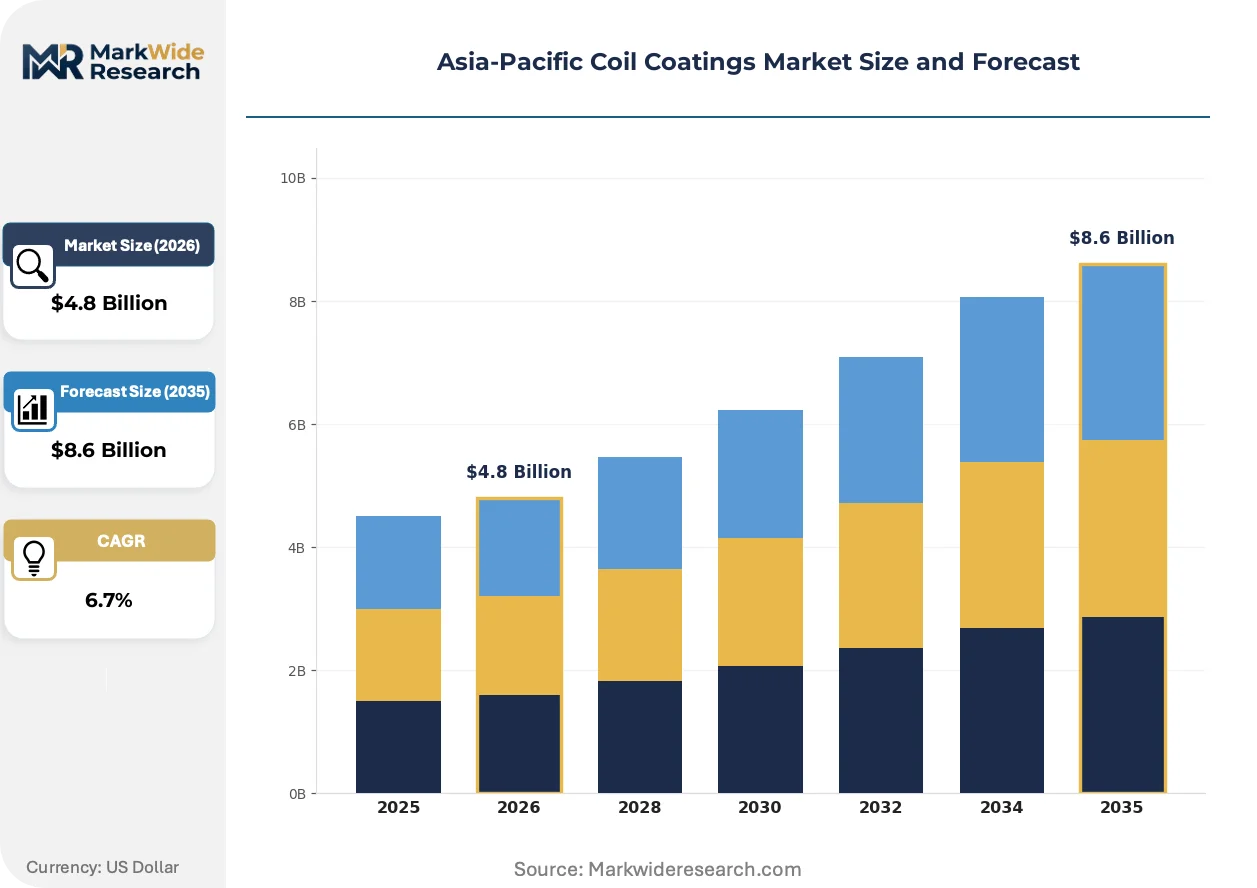
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
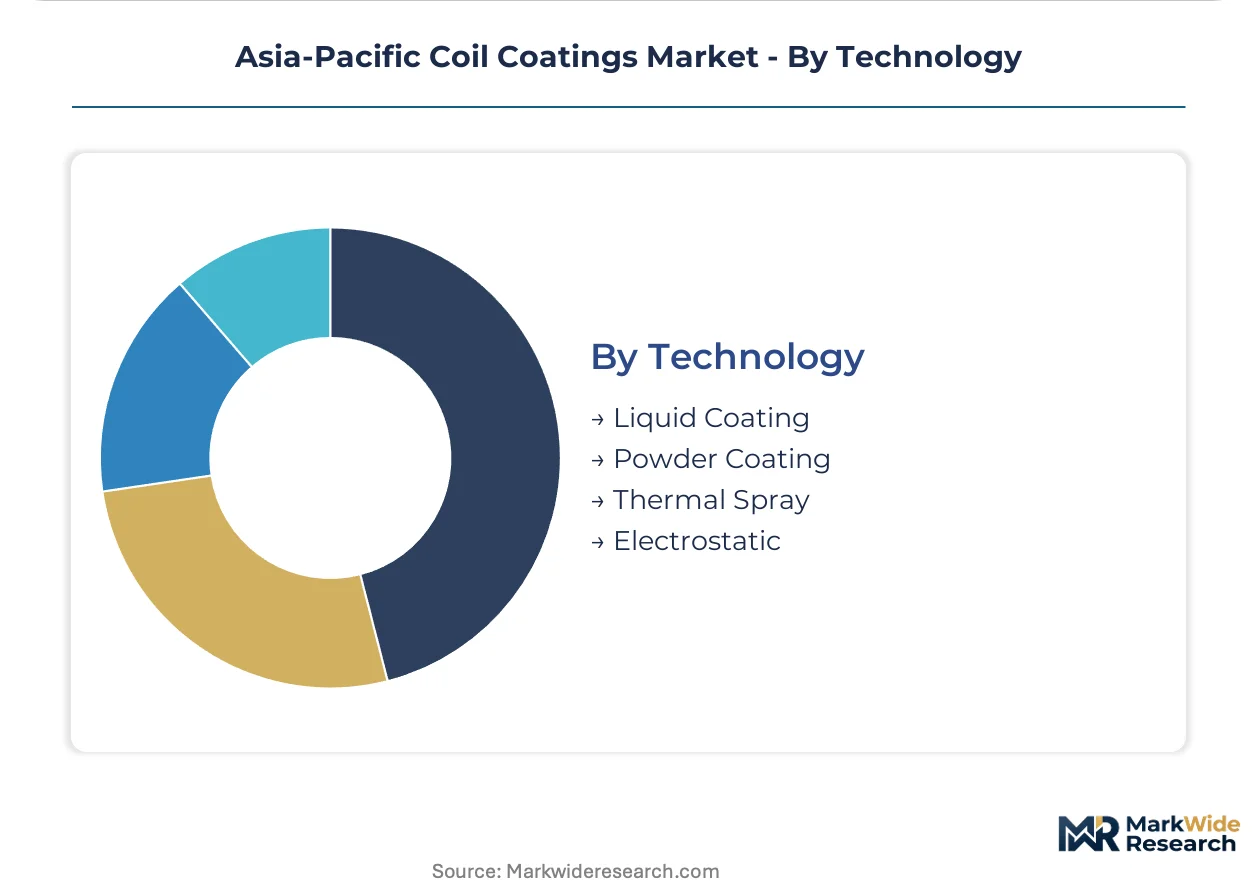
| Segmentation | Product Type: PVC, Polyester, Polyurethane, Plasmar® Application: Building & Construction, Appliances, Automotive, HVAC End User: Manufacturers, Installers, Distributors, Retailers Technology: Liquid Coating, Powder Coating, Thermal Spray, Electrostatic |
| Companies Covered | AkzoNobel, BASF, Nippon Paint Holdings Co., Ltd, Beckers Group, Jotun Group, Kansai Paint Co., Ltd, Sherwin-Williams Company, Guangzhou Willstrong New Material Holding Co. Ltd, PPG Industries, Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Coil Coatings Market Strategic Shifts
Active reformulation across resin chemistry, curing mechanisms, and pigment engineering is compressing legacy solvent-borne dominance while elevating performance specifications for corrosion resistance and solar reflectance.
Fluoropolymer topcoat technology is miniaturizing dry film thickness requirements while maintaining 20-year color retention warranties. Japanese architectural metal fabricators are adopting these systems for coastal and high-UV exposure projects. The technology is miniaturizing material throughput per coated area, reducing resin consumption rates and enabling thinner-gauge substrate compatibility.
China's GB standards for industrial coating VOC content are tightening maximum permissible solvent levels on a phased schedule through 2025. Coating line operators are responding with hybrid cure systems combining infrared and convection heating to reduce bake energy while maintaining film integrity. Polyester formulations for commercial construction face the steepest compliance pressure given their volume dominance.
Specification authority is migrating from general contractors to coating applicators and raw material suppliers as performance warranty terms lengthen. Japanese and South Korean appliance OEMs now require direct technical service relationships with formulators rather than distributor-mediated support. This channel compression is most visible in premium appliance segments where zero-defect film quality mandates direct formulation accountability.
Asia-Pacific Coil Coatings Market Segmentation
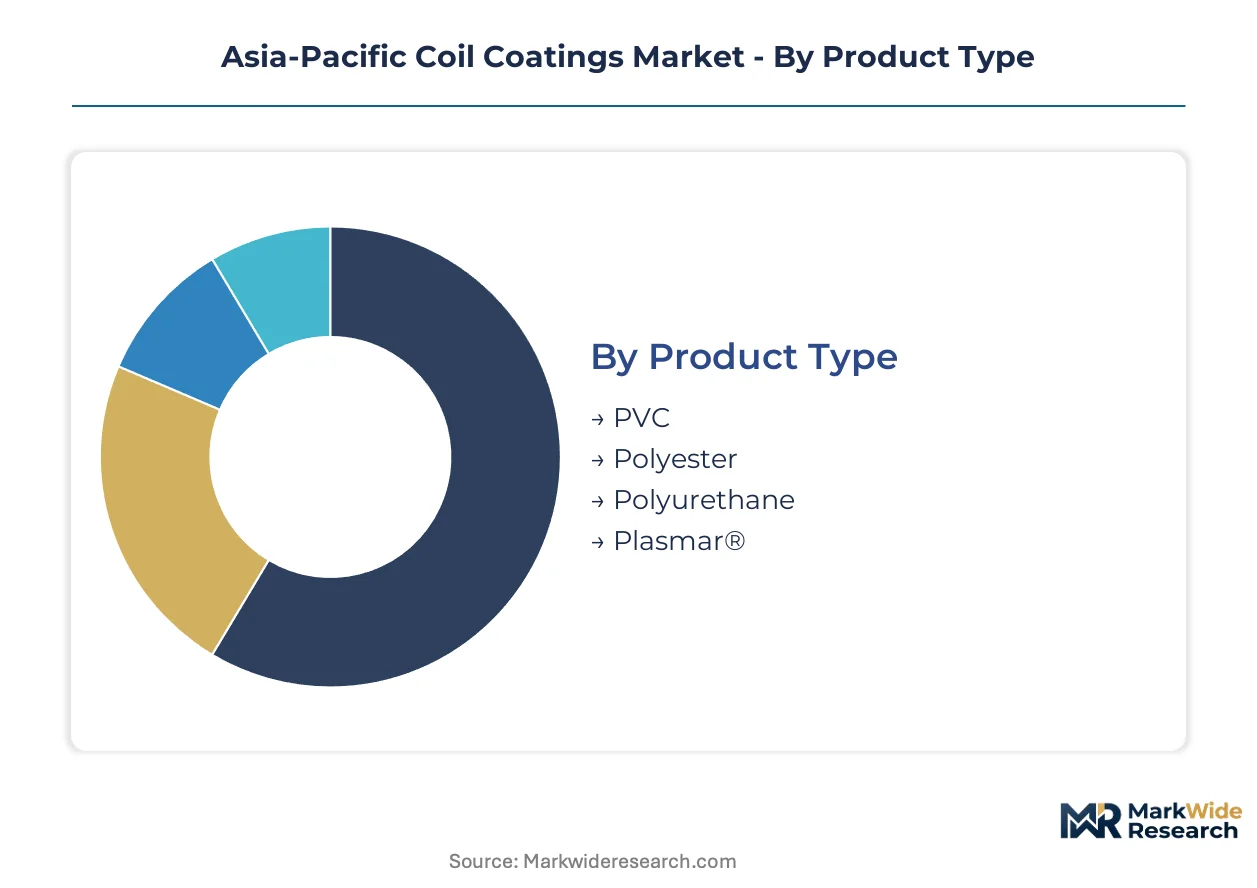
Coil coating procurement channels diverge sharply by product chemistry and end-use durability requirements. Specification authority sits with distinct stakeholder types across each segment boundary, reshaping how formulators configure technical service and inventory positioning.
Product Type:
Channel mix varies by resin chemistry: polyester and polyurethane flow through construction distributors and metal service centers, while specialized systems reach appliance OEMs through direct technical partnerships.
- Polyester:Alkyd-melamine or polyester-melamine thermoset formulations dominate commercial construction specifications across China's humid subtropical zones. Demand concentrates in pre-painted metal roofing and cladding for Southeast Asian logistics parks and manufacturing facilities, driven by cost-performance balance in high-UV exposure conditions.
- Polyurethane:Two-component systems deliver superior flexibility and abrasion resistance for appliance housings and premium architectural applications. Procurement clusters with Japanese and South Korean appliance manufacturers seeking zero-defect film quality, constrained by higher raw material costs and skilled applicator requirements.
- PVC:Organosol and plastisol variants serve specialty corrosion protection in coastal industrial environments.
- Plasmar®:Fluoropolymer-acrylic hybrid technology targets extended warranty architectural metal in Japan's coastal prefectures.
By volume, polyester leads. By growth pace, polyurethane is climbing the fastest.
Application:
Margin profiles separate construction volume plays from appliance precision coating, with automotive and HVAC occupying intermediate positions on specification intensity.
- Building & Construction:Pre-painted metal roofing, wall cladding, and structural profiles constitute the volume anchor. Procurement concentrates in India's western and southern states where greenfield manufacturing facilities and logistics parks are multiplying, driven by accelerated build schedules and weather-resistant envelope requirements.
- Appliances:Refrigerator panels, washing machine housings, and air conditioner cabinets demand exacting color consistency and zero-defect surface quality. Japanese and South Korean OEMs now require direct technical service relationships with formulators, displacing distributor-mediated support channels.
- Automotive:Interior trim components and exterior accent panels utilize coil-coated aluminum and steel substrates.
- HVAC:Heat exchanger fins and equipment housings balance thermal conductivity with corrosion protection.
Construction commands the revenue base. Appliance coatings are gaining share fastest on premium pricing and specification intensity.
End User:
Customer type determines technical service configuration and warranty accountability structures across the value chain.
- Manufacturers:Metal coil coaters and original equipment manufacturers hold specification authority for formulation selection and performance warranties. Procurement concentrates with established domestic producers in India leveraging existing BIS laboratory relationships, while multinational formulators serve Japanese appliance OEMs through captive technical networks.
- Installers:Roofing and cladding contractors influence brand selection through field performance feedback and warranty claim patterns.
- Distributors:Metal service centers and construction material wholesalers manage inventory positioning for standard color ranges.
- Retailers:Home improvement chains and building material outlets serve small-scale renovation and repair demand.
Manufacturers dominate procurement value. Installer influence is expanding through performance-based specification migration.
Technology:
Curing mechanism selection divides legacy infrastructure from compliance-ready capacity as VOC regulations tighten.
- Liquid Coating:Solvent-borne and waterborne systems sustain the majority share in existing coil lines across China and Southeast Asia. Demand concentrates in commercial construction polyester formulations, constrained by MEE VOC emission standards compelling wholesale reformulation toward waterborne curing systems.
- Powder Coating:Thermoset powder systems deliver zero-VOC compliance and thicker protective films for appliance applications. Japanese and South Korean manufacturers are driving trials for refrigerator and washing machine panels, supported by infrared-convection hybrid cure systems reducing bake energy.
- Thermal Spray:Metallic and ceramic coatings serve extreme corrosion environments in coastal industrial zones.
- Electrostatic:Advanced application control targets premium automotive and appliance segments.
Liquid technology holds the installed base. Powder systems are expanding most quickly on regulatory compliance and appliance OEM adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MEE anchors regulatory momentum across the Asia-Pacific coil coatings landscape, with national VOC standards cascading through polyester and fluoropolymer reformulation cycles. National carbon neutrality targets and industrial emission enforcement are reshaping factory-applied coating specifications from Vietnam to India.
China
Dual carbon goals and progressive MEE VOC limits are accelerating waterborne system adoption across polyester-dominant commercial construction lines. GB standards for industrial coating solvent content are tightening on a phased schedule through 2025, compelling hybrid infrared-convection cure upgrades. Yangtze River Delta coil coaters are consolidating solvent-borne capacity while reallocating capital toward high-solid alternatives.
India
Greenfield manufacturing facilities and logistics parks are multiplying across western and southern states, driving pre-painted metal roofing procurement. BIS certification requirements for construction materials create qualification barriers for unqualified imports while privileging established domestic producers. Maharashtra and Gujarat metal service centers are expanding inventory positioning for standard color ranges serving accelerated build schedules.
Japan
METI energy-efficiency standards for commercial buildings are elevating solar-reflective coil coating specifications that reduce cooling loads. Fluoropolymer topcoat technology adoption is miniaturizing dry film thickness requirements while maintaining extended color retention warranties. Kanto region architectural metal fabricators are specifying these systems for coastal and high-UV exposure projects.
South Korea
Appliance OEMs are driving powder coating trials for refrigerator and washing machine panels, seeking zero-VOC compliance and thicker protective films. Direct technical service relationships with formulators are displacing distributor-mediated support channels in premium segments. Seoul Capital Area manufacturers are mandating direct formulation accountability for zero-defect film quality.
Vietnam
Greenfield appliance and construction material facilities are creating first-mover advantage for technical service networks establishing local formulation support. Southeast Asian commercial developments are specifying coil-coated cladding for weather-resistant envelopes in humid subtropical conditions. Northern industrial zones are attracting regional challengers seeking proximity to multiplying manufacturing facilities.
Asia-Pacific Coil Coatings Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with multinational formulators leveraging captive resin supply chains against regional challengers constrained by polymer chemist scarcity. The competitive terrain bifurcates between polyester volume plays in Chinese commercial construction and premium polyurethane precision coating for Japanese appliance OEMs. Three archetypes dominate: integrated resin-coating operators, technical service-intensive specialists, and regional price competitors. Capacity expansion and strategic partnerships represent the dominant competitive vectors as waterborne system migration demands reformulation collaboration.
Among integrated leaders, AkzoNobel and BASF exemplify the captive supply chain archetype, leveraging in-house resin production to secure formulation consistency across Chinese and Indian production hubs. Nippon Paint Holdings Co., Ltd represents the technical service-intensive model, anchoring Japan's domestic architectural metal segment while extending networks into Vietnam and Indonesia. These three occupy positions that reflect the broader competitive tension between multinational scale advantages and regional proximity benefits.
| Leading Market Players |
|---|
| AkzoNobel |
| BASF |
| Nippon Paint Holdings Co., Ltd |
| Beckers Group |
| Jotun Group |
| Kansai Paint Co., Ltd |
| Sherwin-Williams Company |
| Guangzhou Willstrong New Material Holding Co. Ltd |
| PPG Industries, Inc. |
| Others |
Value Chain & Pricing Dynamics
Waterborne resin substitution for solvent-borne polyester systems is redrawing procurement geography across the Asia-Pacific coil coatings landscape while compressing margin structures for legacy formulators. China's MEE enforcement accelerates this shift, elevating capital intensity for compliant capacity while stranding unconverted coil lines in inland provinces.
Pricing Analysis
Price spreads between Japanese fluoropolymer topcoats and Chinese polyester formulations now exceed three-to-one on a per-kilogram basis, reflecting warranty differentiation and raw material tiering. Three-tier pricing structure across premium, standard, and economy levels stratifies by resin chemistry, with polyurethane commanding mid-tier premiums for appliance OEMs. Cost compression in polyester construction grades intensifies because titanium dioxide volatility feeds directly into formulation economics. Small-scale metal service centers in India's western states exhibit highest price sensitivity, while Japanese appliance manufacturers prioritize zero-defect film quality over unit cost.
Supply Chain Analysis
Strait of Malacca transit underwrites acrylic acid derivative flows from Northeast Asian petrochemical hubs to Southeast Asian coating lines. Supply concentrates in China, Japan, and South Korea for polyester resin precursors, while India draws from domestic alkyd capacity and imported melamine crosslinkers. Raw material dependencies center on titanium dioxide from Chinese sulfate-process plants, isocyanates from BASF's Ludwigshafen and Shanghai complexes, and fluoropolymer resins from Japanese specialty chemical producers. Single-source vulnerability in captive acrylic acid derivatives at multinational formulators constrains independent regional challengers. Distribution runs through metal service centers and construction material wholesalers for standard color ranges, with direct technical partnerships serving premium appliance segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific coil coatings market functions as a service-attach opportunity where technical service contracts and extended warranty provisions expand faster than base formulation sales. Recurring revenue from on-site formulation support and color-matching services now outpaces hardware growth in Japanese and South Korean appliance segments.
For Market Incumbents: Shield polyester volume positions in China's Yangtze River Delta through backward integration into waterborne resin production, neutralizing titanium dioxide cost swings. Prioritize BIS laboratory relationship investments in Maharashtra and Gujarat to preempt import qualification barriers. Channel control through captive technical service networks displaces distributor-mediated support in premium segments.
For New Entrants and Emerging Players: Differentiate on powder coating system trials for Vietnamese appliance greenfields, where zero-VOC compliance mandates create specification windows. Target northern Vietnam industrial zones for first-mover technical service establishment. Penetrable white space sits with mid-tier construction distributors in India's southern states lacking direct formulator relationships. A technical partnership with local metal service centers accelerates inventory positioning for standard color ranges.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional challengers in Southeast Asia possessing formulation capabilities but lacking captive resin supply. Long-term viability across the analysis window favors targets with waterborne system migration completed and local laboratory certifications secured. Acquisition focus should center on Indian domestic producers with existing BIS relationships and Vietnamese technical service networks. The signal to watch is MEE enforcement intensity accelerating solvent-borne capacity consolidation in China's interior provinces.
| Strategic Initiative | Industry Significance |
|---|---|
| Waterborne System Migration | MEE compliance investments reposition Chinese coil coaters for phased GB standard tightening through 2025. |
| Backward Integration into Acrylic Acid | BASF's captive supply chain anchors formulation consistency across polyester lines in Shanghai and Ludwigshafen. |
| Powder Coating Capacity Expansion | Japanese appliance OEM trials for refrigerator panels drive zero-VOC compliance in Seoul Capital Area manufacturing. |
| Technical Service Network Extension | Nippon Paint's Vietnam and Indonesia expansion captures specification authority from general contractors. |
| BIS Certification Investment | Maharashtra-based producers leverage laboratory relationships to block unqualified import competition in western India. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with polymer chemists, coil coating line operators, appliance OEM procurement leads, and construction material distributors; and secondary validation through customs trade data, MEE regulatory filings, BIS certification records, and SEC disclosures from listed chemical producers. Bottom-up triangulation across resin consumption patterns and top-down verification against coating line capacity installations anchored volume estimates.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning resin chemistry tier, end-use durability requirement, curing mechanism technology, and regional regulatory cluster. CAGRs derived from trend extrapolation of coating line investments and reformulation cycle timing. Forecast inputs incorporated MEE enforcement trajectory assumptions and METI energy-efficiency standard adoption curves for commercial building specifications.
Decision-makers should treat outputs as directional under sustained dual carbon policy commitment and MEE VOC limit progression; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as carbon-border adjustment mechanisms and ASEAN green building code harmonization evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Germany Industrial Coatings Market
Coatings
Cool Roof Coatings Market
Coatings
Italy Automotive OEM Coatings Market
Coatings
Silicate Coatings Market
Coatings
South Korea Marine Coatings Market
Coatings
Global Water-Based Coatings Market
Coatings
Paper Coating Binders Market
Coatings
Global Anti-Smudge Coatings Market
Coatings
Global Automotive Specialty Coatings Market
Coatings
Diamond-Like Carbon Coatings Market
Coatings
North America Epoxy Powder Coatings Market
Coatings
Consumer Appliance Coatings Market
Coatings
Perfluoroalkoxy (PFA) Coatings Market
Coatings
Biopolymer Coatings Market
Coatings
Urethane Surface Coatings Market
Coatings
Marine Nanocoating Market