
 East Africa Flat Glass Market | 2026-2036
East Africa Flat Glass Market Size, Share, and Industry Trends Forecast 2026-2036
East Africa Flat Glass Market Analysis
Market Context
Kenya's National Construction Authority building code revision is pivoting the cost-of-entry calculus toward certified safety glass for commercial structures. Saint-Gobain leverages its regional float glass capacity to supply laminated products across Nairobi's high-rise pipeline. Xinyi Glass Holdings Limited anchors its East African presence through distributor networks serving Ethiopia's state-backed infrastructure programs. AGC Inc. competes on coated glass technology leadership for solar energy installations in Tanzania's emerging utility-scale projects.
Technical Definition and Segment Structure
East Africa flat glass denotes soda-lime silica sheet material manufactured primarily through the float process, achieving thicknesses from 2 mm to 25 mm with optical clarity standards suited for architectural glazing and automotive windscreens. Its primary purpose spans transparent envelope systems in buildings, vehicle safety barriers, and photovoltaic module substrates. Float glass dominates volume throughput across regional distribution channels, while laminated glass commands margin concentration in Nairobi's premium commercial tower segment. Solar energy applications represent the fastest-growing demand vector as Ethiopia and Kenya expand utility-scale photovoltaic procurement.
Regulatory Framework and Outlook
Kenya's National Construction Authority, Ethiopia's Ministry of Urban Development, and Tanzania's Tanzania Bureau of Standards collectively enforce building safety and product quality protocols that determine market access for imported and locally manufactured glass. These frameworks mandate impact resistance and thermal performance thresholds that favor toughened and coated glass categories over basic annealed alternatives. Stakeholders must monitor harmonization pressures between national standards and emerging East African Community technical regulations that could reshape certification requirements and cross-border trade flows.
Market Dynamics
Kenya's National Construction Authority safety glass mandates are compressing procurement timelines for commercial developers while concentrating certified supplier relationships among pre-approved fabricators serving Nairobi's high-rise pipeline.
Growth Catalysts
- Building Code Modernization:Kenya's National Construction Authority updated safety glass requirements for commercial structures above four stories, mandating laminated or toughened specifications that eliminate annealed alternatives from mid-rise procurement.
- Photovoltaic Deployment:Ethiopia's state-backed utility-scale solar programs are generating dedicated demand for coated glass substrates in module assembly, with procurement volumes scaling alongside generation capacity auctions.
- Urban Corridor Concentration:The Nairobi-Mombasa infrastructure corridor anchors regional distribution networks, with logistics consolidation reducing landed costs for imported float glass serving Kenya's commercial construction pipeline.
Market Restraints
- Energy Input Volatility:Natural gas and heavy fuel oil price instability at Mombasa port directly compresses float glass manufacturing margins, as furnace operations consume continuous thermal energy regardless of production scheduling.
- Import Dependency Concentration:Regional flat glass supply concentrates through Mombasa and Djibouti port corridors, exposing procurement timelines to maritime congestion and customs clearance bottlenecks at these entry nodes.
- Technical Specification Gaps:Limited local testing infrastructure for impact resistance and thermal performance certification creates approval delays for imported safety glass variants not pre-registered with national standards bodies.
Strategic Opportunities
- Secondary City Penetration:Tanzania's Dar es Salaam peripheral zones and Rwanda's Kigali commercial district remain underserved by certified safety glass distribution, presenting first-mover positioning for compliant supplier networks.
- Solar Glass Specialization:Anti-reflective coated glass for photovoltaic modules represents an emerging product category where technical differentiation commands margin premiums above commodity float pricing.
- Regional Standards Harmonization:Emerging East African Community technical regulations could streamline cross-border certification, reducing duplicate testing burdens for suppliers serving multiple national markets simultaneously.
Industry Challenges
- Skilled Fabrication Shortage:Local availability of certified laminating and tempering technicians lags behind installation demand, extending project timelines for complex commercial glazing contracts.
- Capex Intensity for Compliance:In-country toughening furnace installation requires substantial capital commitment relative to market size, limiting local value-addition and preserving import dependence for processed safety glass.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | East Africa Flat Glass Market |
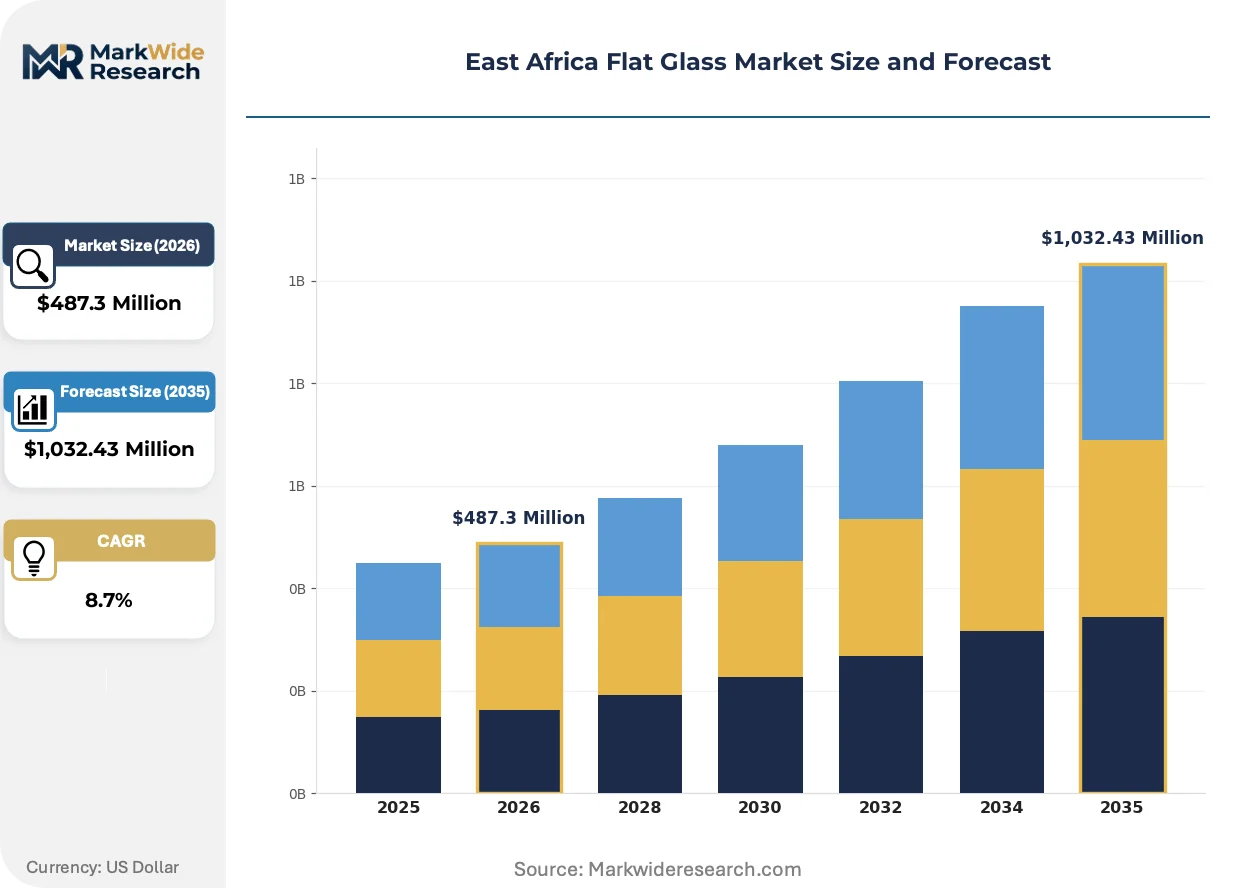
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Float Glass, Laminated Glass, Toughened Glass, Coated Glass Application: Construction, Automotive, Furniture, Solar Energy End User: Architects, Construction Companies, Homeowners, Automotive Manufacturers Distribution Channel: Direct Sales, Distributors, Online Retail, Wholesale |
| Companies Covered | Afrika Glass, East African Glassware Mart Ltd., Saint-Gobain, NSG Group, Xinyi Glass Holdings Limited, AGC Inc., Egyptian Glass Company, Sisecam Group, Guardian Industries, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
East Africa Flat Glass Market Emerging Trajectories
East Africa's flat glass sector is pivoting toward performance-differentiated products as building energy codes tighten and solar deployment accelerates, with technical specifications displacing commodity purchasing criteria in commercial procurement.
Thin-film photovoltaic glass substrates are expanding into utility-scale solar farm specifications across Ethiopia's Rift Valley and Kenya's northern counties. State power purchasers now mandate anti-reflective coating compatibility in module tenders, compressing acceptance timelines for uncoated alternatives. This specification shift is expanding into project finance requirements, with development banks linking disbursement milestones to certified glass sourcing.
Kenya's National Construction Authority has implemented mandatory third-party testing protocols for imported safety glass, requiring laboratory verification of impact resistance before site delivery. Industrial consequence includes pre-shipment inspection delays at origin ports and inventory holding cost accumulation for distributors. Commercial tower developers in Nairobi's Upper Hill district are responding by consolidating procurement through pre-approved fabricators with established certification histories.
Developer procurement patterns are compressing supplier qualification cycles as project timelines tighten under construction finance cost pressure. Tier-one contractors in Ethiopia's Addis Ababa industrial zone are displacing fragmented spot purchasing with annual framework agreements that lock volume commitments and price bands. This consolidation is most visible in Kenya's Nairobi-Mombasa corridor, where repeat-project developers have reduced active supplier rosters from multiple distributors to single-source arrangements with integrated fabricator-distributors.
East Africa Flat Glass Market Segmentation
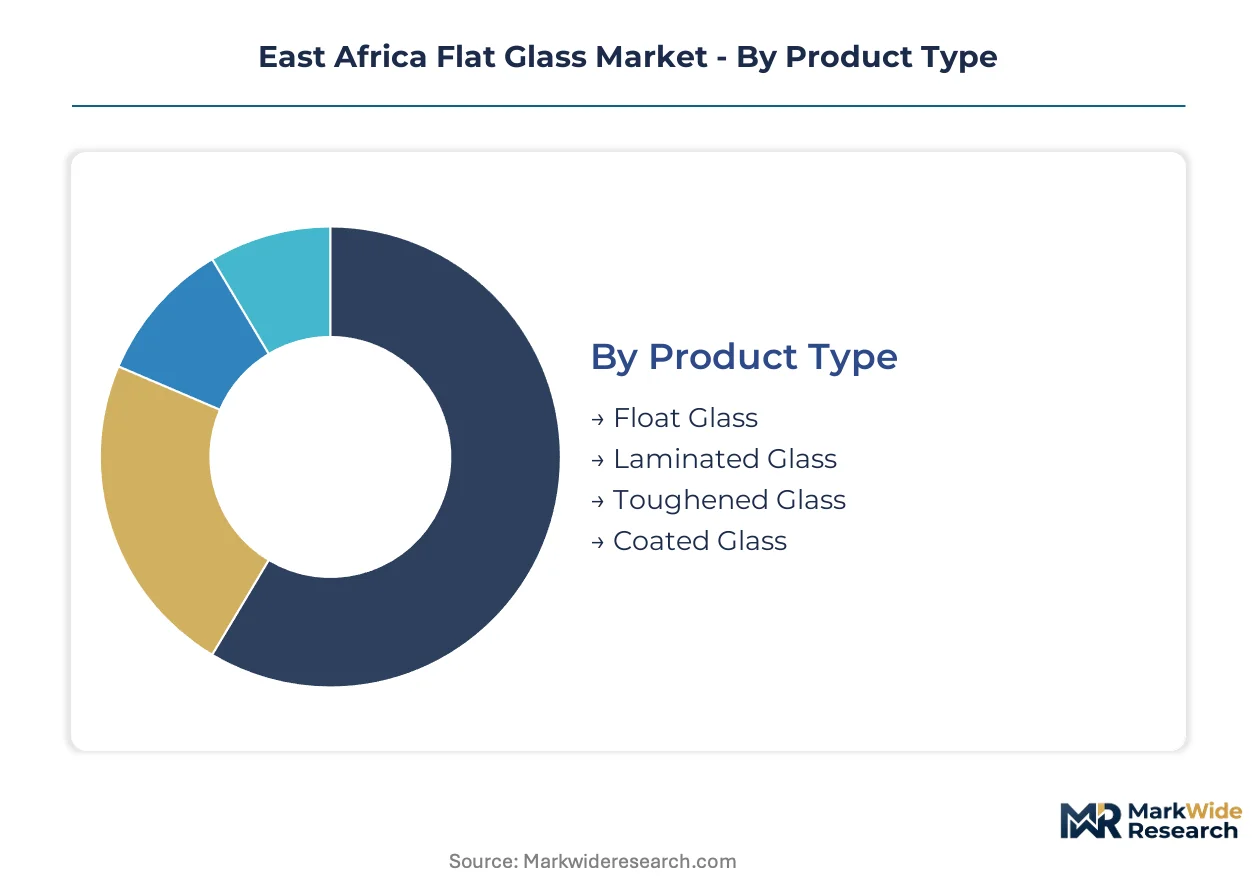
East Africa's flat glass market fragments across four distinct dimensions that determine capital deployment, margin capture, and competitive positioning. Product type differentiation separates commodity volume plays from specialty margin opportunities, while application mix shifts with construction cycle timing and solar procurement waves.
Product Type:
Float glass demands the heaviest capital commitment, requiring continuous furnace operations with thermal energy inputs that dominate manufacturing economics across Mombasa and Djibouti port corridors.
- Float Glass:Soda-lime silica sheet produced through the Pilkington process achieves optical clarity for architectural glazing and automotive windscreens. Volume concentrates in Kenya's Nairobi-Mombasa corridor serving commercial tower developments, though energy input volatility at Mombasa port compresses manufacturing margins unpredictably.
- Laminated Glass:Polyvinyl butyral interlayer bonding creates safety barriers that retain fragmentation upon impact. Procurement is scaling fastest in Nairobi's Upper Hill commercial district where Kenya's National Construction Authority mandates laminated or toughened specifications for structures above four stories.
- Toughened Glass:Thermal or chemical strengthening delivers impact resistance through surface compression layers. Local fabrication capacity remains constrained by skilled technician shortages.
- Coated Glass:Thin-film deposition modifies solar thermal performance for energy-efficient envelopes. Anti-reflective variants are climbing fastest alongside Ethiopia's utility-scale photovoltaic procurement.
Most installed capacity flows through Float Glass. Expansion is steepest in Coated Glass.
Application:
Construction commands absolute volume share, though solar energy applications are gaining share fastest as state-backed procurement programs reshape demand composition.
- Construction:Transparent envelope systems for commercial towers, residential developments, and institutional buildings. Nairobi's high-rise pipeline and Addis Ababa's industrial zone anchor regional offtake, with Kenya's updated building codes eliminating annealed glass from mid-rise procurement.
- Solar Energy:Photovoltaic module substrates and solar thermal collectors. Ethiopia's state power purchasers now mandate anti-reflective coating compatibility in utility-scale tenders, compressing acceptance timelines for uncoated alternatives.
- Automotive:Windscreens, side windows, and rear glazing for vehicle assembly and aftermarket replacement. Demand tracks East African Community vehicle import flows through Mombasa port.
- Furniture:Tabletops, shelving, and decorative applications requiring polished edges and custom dimensions. Procurement fragments across small-scale fabricators with limited certification standardization.
Construction absorbs the majority of regional float glass throughput. Solar Energy is climbing the fastest as development banks link disbursement milestones to certified glass sourcing.
End User:
Construction companies consolidate procurement through annual framework agreements, displacing fragmented spot purchasing as project finance timelines tighten.
- Construction Companies:Tier-one contractors in Ethiopia's Addis Ababa industrial zone and Kenya's commercial developers drive volume through pre-approved fabricator relationships. Framework agreements now lock volume commitments and price bands across multi-project portfolios.
- Architects:Specification authority in premium commercial towers influences safety glass selection before contractor procurement begins. Nairobi's Upper Hill district developments demonstrate concentrated architect influence on laminated glass mandates.
- Automotive Manufacturers:Assembly plants and aftermarket distributors require windscreen and glazing supplies meeting regional safety standards. Local content rules in East African Community markets shape sourcing decisions.
- Homeowners:Residential renovation and self-build projects access glass through distributor retail channels. Price sensitivity favors basic annealed products where building codes permit.
Construction Companies command the largest order values. Architects are gaining specification influence fastest as Kenya's National Construction Authority tightens safety glass protocols.
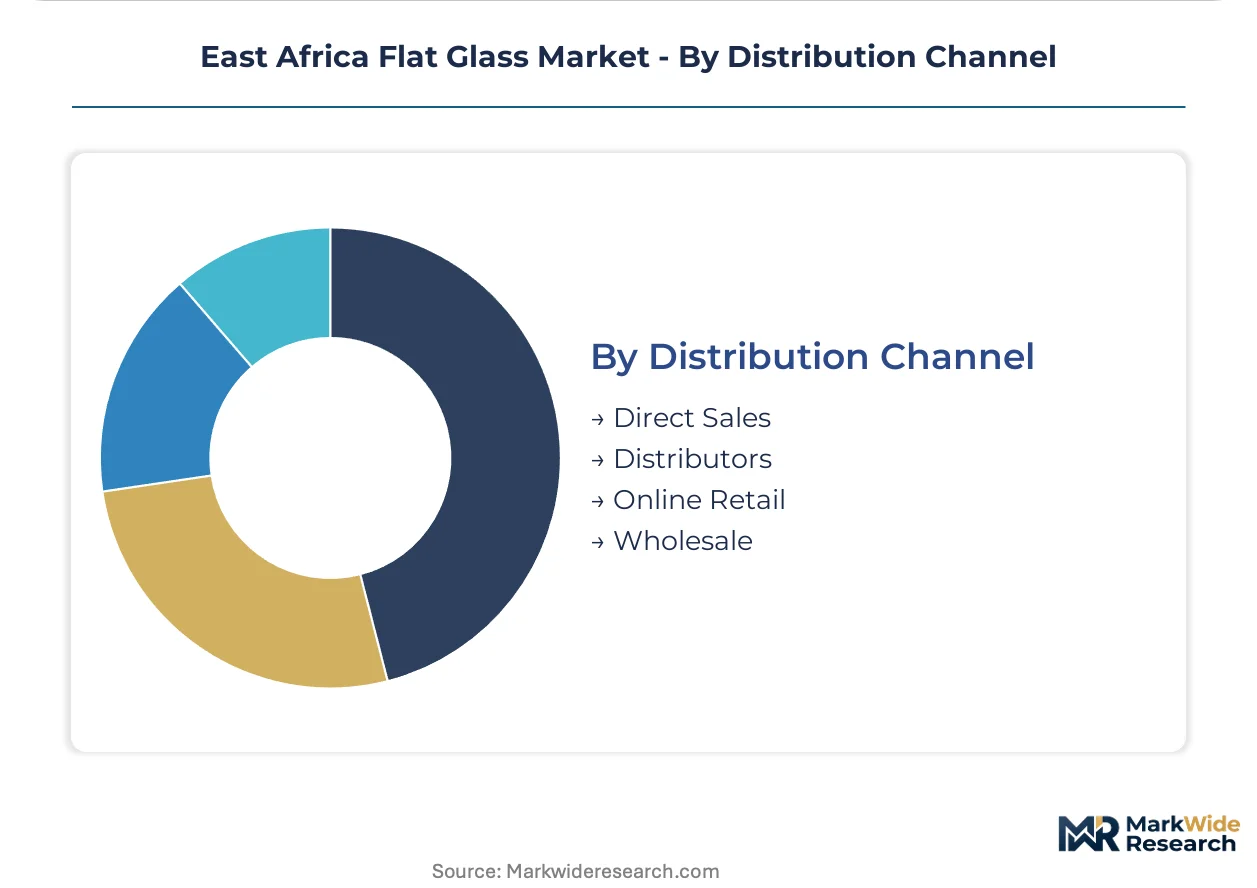
Distribution Channel:
Distributor networks dominate safety glass availability, though direct sales are consolidating among repeat-project developers seeking supply security.
- Distributors:Regional stocking locations in Nairobi, Mombasa, and Addis Ababa hold certified inventory for immediate project delivery. Pre-shipment inspection delays at origin ports create inventory holding cost accumulation that distributors absorb.
- Direct Sales:Large commercial developers bypass intermediaries for annual volume commitments with integrated fabricator-distributors. Kenya's Nairobi-Mombasa corridor demonstrates this consolidation most visibly.
- Wholesale:Bulk procurement for construction material retailers serving secondary city markets. Tanzania's Dar es Salaam peripheral zones remain underserved relative to primary corridor concentration.
- Online Retail:Digital catalog access for standard dimensions and small-lot procurement. Limited penetration reflects specification complexity and breakage risk in last-mile delivery.
Distributors handle the majority of certified safety glass volume. Direct Sales is expanding most quickly as developer procurement patterns consolidate supplier rosters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled laminating technicians and certified tempering specialists concentrate in Kenya's Nairobi-Mombasa corridor, anchoring regional fabrication capacity for safety glass processing.
Kenya
Commercial high-rise development in Nairobi's Upper Hill district and residential tower construction along the Mombasa Road corridor drive laminated glass procurement. The National Construction Authority mandates laminated or toughened specifications for structures above four stories, eliminating annealed alternatives from mid-rise procurement. Nairobi's industrial zone hosts pre-approved fabricator-distributors serving repeat-project developers through annual framework agreements.
Ethiopia
State-backed utility-scale solar programs and industrial zone construction in Addis Ababa generate coated glass demand for photovoltaic module assembly. The Ministry of Urban Development enforces building safety protocols that favor toughened glass categories for commercial structures. Addis Ababa's industrial zone anchors procurement consolidation among tier-one contractors locking volume commitments through multi-project portfolios.
Tanzania
Emerging utility-scale solar installations and commercial development in Dar es Salaam's peripheral zones create underserved demand for certified safety glass distribution. The Tanzania Bureau of Standards maintains product quality protocols determining market access for imported glass variants. Dar es Salaam's logistics corridors remain less consolidated than Kenya's Nairobi-Mombasa axis, presenting first-mover positioning opportunities for compliant supplier networks.
Uganda
Infrastructure rehabilitation and institutional building programs in Kampala generate construction glass demand tracking regional procurement patterns. National standards bodies align technical regulations with emerging East African Community harmonization pressures. Kampala's commercial district relies on distributor networks extending from Kenya's Mombasa port corridor, exposing timelines to maritime congestion.
Rwanda
Kigali's commercial district development and government-backed smart city initiatives drive specification-grade glass demand for premium envelope systems. The Rwanda Standards Board enforces quality protocols that favor certified safety glass over basic annealed alternatives. Kigali's construction pipeline remains underserved by regional distribution networks relative to primary corridor concentration.
East Africa Flat Glass Market Vendor Landscape
The competitive structure tilts toward multinational float glass manufacturers with regional furnace capacity and integrated fabricator-distributors serving pre-approved commercial developer relationships. Player mix spans three strategic tiers: global float glass producers leveraging scale economies, regional distributors holding certified inventory for immediate project delivery, and local fabricators specializing in tempering and laminating value-addition. Dominant competitive moves include backward integration into captive float glass supply and consolidation of distributor networks through strategic partnerships with repeat-project developers.
Among global float glass producers, Saint-Gobain, Xinyi Glass Holdings Limited, and AGC Inc. occupy positions exemplifying scale-driven supply architecture. Saint-Gobain represents the integrated multinational archetype with regional furnace capacity serving laminated product demand. Xinyi Glass Holdings Limited exemplifies Asia-based supply chain extension through distributor network anchoring. AGC Inc. sits within the technology-differentiated tier competing on coated glass specifications for solar energy applications.
| Leading Market Players |
|---|
| Afrika Glass |
| East African Glassware Mart Ltd. |
| Saint-Gobain |
| NSG Group |
| Xinyi Glass Holdings Limited |
| AGC Inc. |
| Egyptian Glass Company |
| Sisecam Group |
| Guardian Industries |
| Others |
Supply Flow & Price Mechanics
Kenya's National Construction Authority laminated glass mandates for commercial structures above four stories are compressing procurement timelines and forcing supply consolidation around pre-approved fabricator-distributors, which in turn elevates pricing power for certified suppliers while squeezing spot-market alternatives.
Pricing Analysis
Glass supply in East Africa separates between bundled fabrication-installation contracts and unbundled commodity sheet transactions. Three-tier pricing structure across premium certified, standard compliant, and economy annealed levels tracks certification grade and volume commitment scale. Pricing pressure stems from energy input volatility at Mombasa port furnace operations, which compresses margins unpredictably. Construction companies in Ethiopia's Addis Ababa industrial zone demonstrate lowest price sensitivity through locked annual framework agreements, while residential homeowners accessing distributor retail channels exhibit highest sensitivity to per-sheet differentials.
Supply Chain Analysis
Single-source vulnerability sits with Mombasa and Djibouti port corridors, which handle the majority of regional float glass imports. Manufacturing capacity concentrates in Egypt, Turkey, and China as source markets for East African offtake. Raw material dependencies include soda ash, silica sand, and natural gas for continuous furnace operations. Maritime congestion and customs clearance bottlenecks at entry nodes constitute the dominant supply chain risk. Distribution runs through regional stocking locations in Nairobi, Mombasa, and Addis Ababa that hold certified inventory for immediate project delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
East Africa's flat glass market offers margin expansion through solar glass specialization, where anti-reflective coated substrates command premium pricing above commodity float as Ethiopia and Kenya scale utility-scale photovoltaic procurement.
For Market Incumbents: Acquire captive tempering and laminating fabrication capacity in Kenya's Nairobi-Mombasa corridor to defend against skilled technician shortages that extend project timelines. Anchor procurement relationships through multi-year framework agreements with repeat-project developers in Ethiopia's Addis Ababa industrial zone, locking volume commitments before competitor pre-approval status consolidates. For New Entrants and Emerging Players: Digital distributor platforms serving Tanzania's Dar es Salaam peripheral zones and Rwanda's Kigali commercial district offer the most penetrable white-space entry. Target certified safety glass distribution in secondary cities underserved by pre-approved fabricator networks. Pursue annual volume commitments with state-backed solar developers in Ethiopia's Rift Valley as the fastest-scaling application segment. For Investors and Strategic Acquirers: Asymmetric upside sits with integrated fabricator-distributors holding pre-approved status with Kenya's National Construction Authority. Long-term viability centers on solar glass specialization and regional standards harmonization across the East African Community. Watch for anti-reflective coating compatibility mandates in state power purchase agreements as the signal for accelerated premium-tier shift.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Float Supply | Reduces import dependency exposure at Mombasa and Djibouti port chokepoints for continuous furnace operations. |
| Solar Glass Specialization | Captures margin premiums from Ethiopia's state-backed utility-scale photovoltaic procurement programs. |
| Regional Standards Harmonization | Streamlines cross-border certification burdens as East African Community technical regulations emerge. |
| Secondary City Distribution Expansion | Secures first-mover positioning in Tanzania's Dar es Salaam peripheral zones and Rwanda's Kigali commercial district. |
| Skilled Technician Certification Investment | Addresses fabrication bottlenecks constraining local toughening and laminating capacity expansion. |
Methodological Framework
Multiple input streams — primary interviews with glass fabricator operations managers, commercial developer procurement leads, and solar EPC contractors; secondary validation through customs trade data, National Construction Authority regulatory filings, and East African Community technical regulation drafts; plus continuous furnace energy cost tracking — were reconciled through bottom-up and top-down triangulation to construct market estimates.
Data-stream reconciliation across product type, application, end user, and distribution channel dimensions anchored the analytical framework over the projection horizon. CAGRs were derived from segment-level volume trajectories and value-per-unit assumptions. Key forecast inputs included Kenya's building code enforcement timelines, Ethiopia's utility-scale solar auction schedules, and Mombasa port logistics capacity utilization.
Regulatory enforcement delays, photovoltaic procurement auction cancellations, and maritime corridor disruptions are the dominant revision risks that could alter trajectory assumptions. Forecasts reflect documented assumptions about standards harmonization progress and energy input cost stabilization. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
North America Flat Glass Market
Glass
Foam Glass Market
Glass
Europe Glassware Market
Glass
Glass Manufacturing Market
Glass
Foam Glass Granulate Market
Glass
Glass Like Carbon Market
Glass
Global Anti-Reflective Glass Market
Glass
Fiberglass Window Market
Glass
Dynamic Glazing Market
Glass
Global Energy Efficient Glass Market
Glass
Technical Glass Market
Glass
Impact Resistant Glass Market
Glass
North America Glass Insulators Market
Glass
Glass Polishing Powder Market
Glass
Asia-Pacific Fiberglass Window Market
Glass
Optical Materials Market