
 Pharma Glass Tubing Market | 2026-2036
Pharma Glass Tubing Market Size, Share, and Industry Trends Forecast 2026-2036
Pharma Glass Tubing Market Analytics
The split between premium borosilicate tubing and commodity soda lime alternatives is shifting as biologics manufacturers reject lower-grade materials for sensitive formulations. Schott AG leverages its vertical furnace technology to dominate high-purity segments. Corning Incorporated anchors North American supply through controlled thermal expansion formulations. Nipro Corporation competes on cost-optimized soda lime volumes for standard vial applications.
Pharma glass tubing consists of hollow cylindrical glass structures manufactured through precision drawing, forming, and annealing processes, typically composed of borosilicate glass with thermal expansion coefficients below 3.3 x 10^-6/K to withstand sterilization and thermal shock during drug filling operations. Borosilicate tubing commands the largest value share due to its chemical durability and compatibility with parenteral biologics, while aluminosilicate segments gain traction in high-temperature vaccine processing where dimensional stability under thermal cycling proves critical. Application demand concentrates in vials and syringes as prefillable formats expand, with cartridges representing a specialized growth pocket driven by pen-injector and auto-injector platform adoption.
US FDA enforces container closure integrity standards under cGMP that mandate glass delamination resistance testing, while Europe's MDR and REACH frameworks impose material composition disclosure and restricted substance limits on pharmaceutical contact materials. China's NMPA aligns with international pharmacopeial standards through updated GB requirements for injectable packaging. Stakeholders must monitor evolving pharmacopeial harmonization between USP, EP, and ChP standards as regulatory divergence threatens cross-border product qualification timelines.
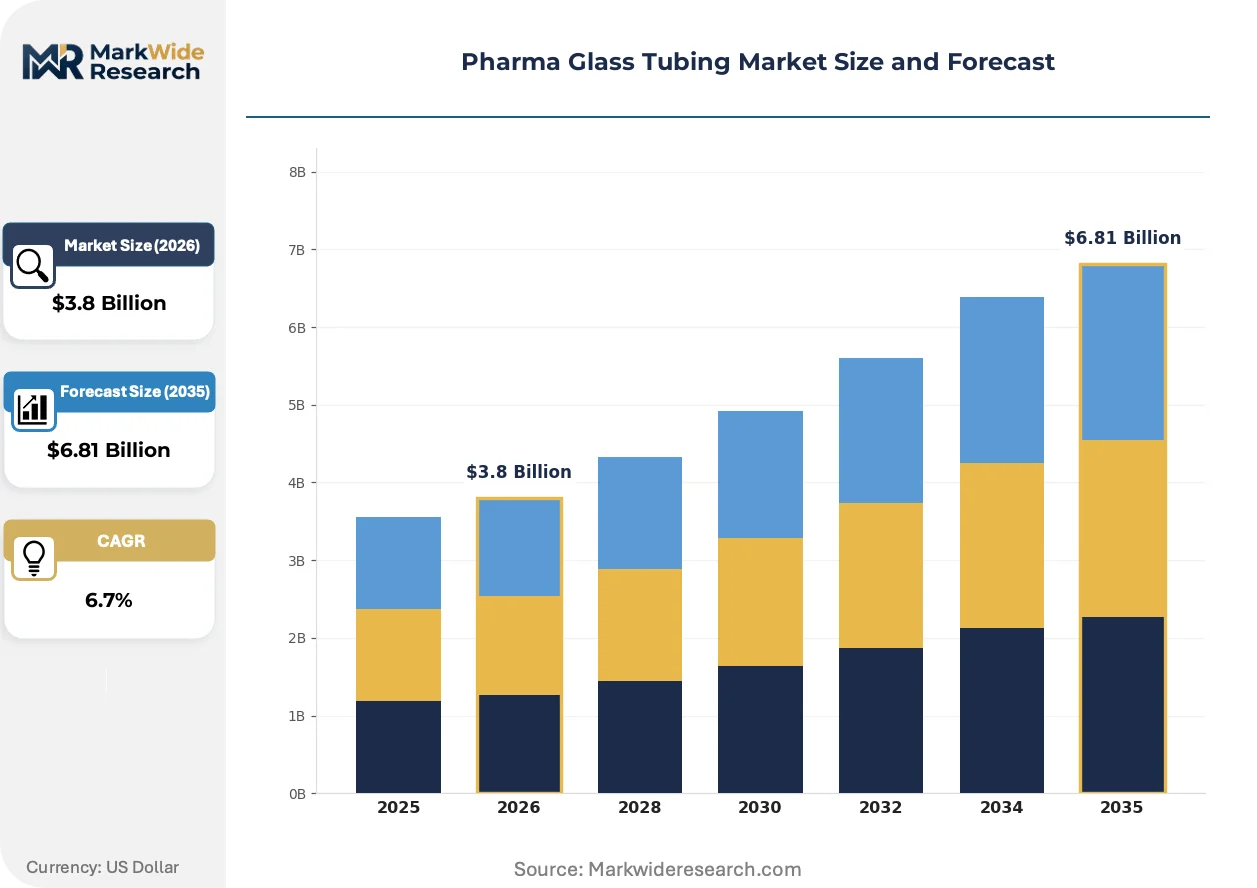
Market Dynamics
The pharma glass tubing market is undergoing a structural compression as biologics manufacturers reject soda lime alternatives, forcing capacity reallocation toward borosilicate and aluminosilicate grades that withstand aggressive sterilization protocols and thermal cycling demands.
Growth Catalysts
- Biologics pipeline expansion:Injectable monoclonal antibodies and cell therapies require chemically inert borosilicate containment, pulling demand from standard vial applications into high-purity segments.
- Europe's MDR material traceability mandates:The Medical Device Regulation forces pharmaceutical contact material disclosure, accelerating substitution of unverified glass sources with certified pharmacopeial-grade tubing.
- Prefillable syringe format adoption:Auto-injector and pen-injector platforms for diabetes and rheumatology therapies consume precision-drawn cartridges, expanding addressable tubing specifications.
Market Restraints
- Specialized sand and boron raw material concentration:High-purity silica deposits and refined boron supply cluster in limited geographic corridors, exposing converters to input cost volatility and qualification delays.
- Oligopolistic furnace technology control:Vertical drawing furnace intellectual property and operational expertise concentrate among a handful of equipment suppliers, constraining new entrant capacity scaling.
- Plastic polymer substitution in standard applications:Cyclic olefin polymers and copolymers displace soda lime glass in non-sensitive oral and topical packaging, compressing commodity tubing volumes.
Strategic Opportunities
- Indian pharmaceutical manufacturing expansion:CDSCO's alignment with ICH guidelines and production-linked incentive schemes for active pharmaceutical ingredients create demand for import-substitute tubing capacity near Mumbai and Hyderabad clusters.
- Continuous manufacturing integration:Real-time release testing and modular fill-finish lines enable tubing specifications tailored to single-use process trains, opening specification partnerships with bioprocess equipment vendors.
- China's NMPA pharmacopeial harmonization:Updated GB standards for injectable glass create pathways for international-grade producers to qualify domestic biopharmaceutical fill-finish operations previously served by local soda lime suppliers.
Industry Challenges
- Glass delamination testing capacity bottleneck:US FDA's cGMP container closure integrity requirements mandate extensive surface analysis, stretching qualified analytical laboratory throughput and extending product qualification timelines.
- Specialized furnace operator skill scarcity:Precision thermal management and defect detection in continuous drawing processes require experienced technicians, with training pipelines failing to match capacity expansion schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pharma Glass Tubing Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Borospilicate, Soda Lime, Aluminosilicate, Lead Glass Application: Vials, Ampoules, Syringes, Cartridges End User: Pharmaceutical Companies, Biotechnology Firms, Research Laboratories, Hospitals Manufacturing Stage: Drawing, Forming, Annealing, Coating |
| Companies Covered | Schott AG, Corning Incorporated, Nipro Corporation, Gerresheimer AG, Stevanato Group, Nippon Electric Glass, Shandong Pharmaceutical Glass, Bormioli Pharma, DWK Life Sciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pharma Glass Tubing Market Evolving Landscape
Material science advances and regulatory stringency are converging to redefine acceptable performance thresholds, with thermal expansion control and surface chemistry stability emerging as the primary axes of product differentiation.
Aluminosilicate glass formulations with enhanced dimensional stability under repeated thermal cycling are absorbing demand from mRNA vaccine manufacturing processes where ultra-cold chain storage and rapid thaw protocols stress conventional borosilicate structures. Fill-finish contractors serving pandemic preparedness stockpiles and seasonal influenza campaigns are specifying these grades despite 15-20% cost premiums. The technology is absorbing share from standard borosilicate in temperature-critical applications while creating specification fragmentation that complicates inventory management for multi-product facilities.
REACH restricted substance limits and Europe's MDR biocompatibility documentation requirements are forcing glass converters to map raw material provenance through smelting and refining stages. Suppliers must now certify absence of heavy metal contaminants and crystalline silica exposure risks across batch records. Small and mid-scale tubing producers lacking analytical infrastructure are outsourcing compliance documentation, eroding margin structures and accelerating consolidation toward integrated producers with captive analytical capabilities.
Biopharmaceutical procurement functions are consolidating supplier panels and demanding long-term volume commitments with fixed pricing mechanisms to hedge against raw material volatility. Large molecule developers in Massachusetts and North Carolina are replacing spot purchasing with three to five-year master service agreements that bundle tubing supply with technical support and delamination testing services. This behavior concentrates purchasing power among the largest fill-finish operators while marginalizing regional converters unable to meet minimum volume thresholds or provide integrated service packages.
Pharma Glass Tubing Market Segmentation
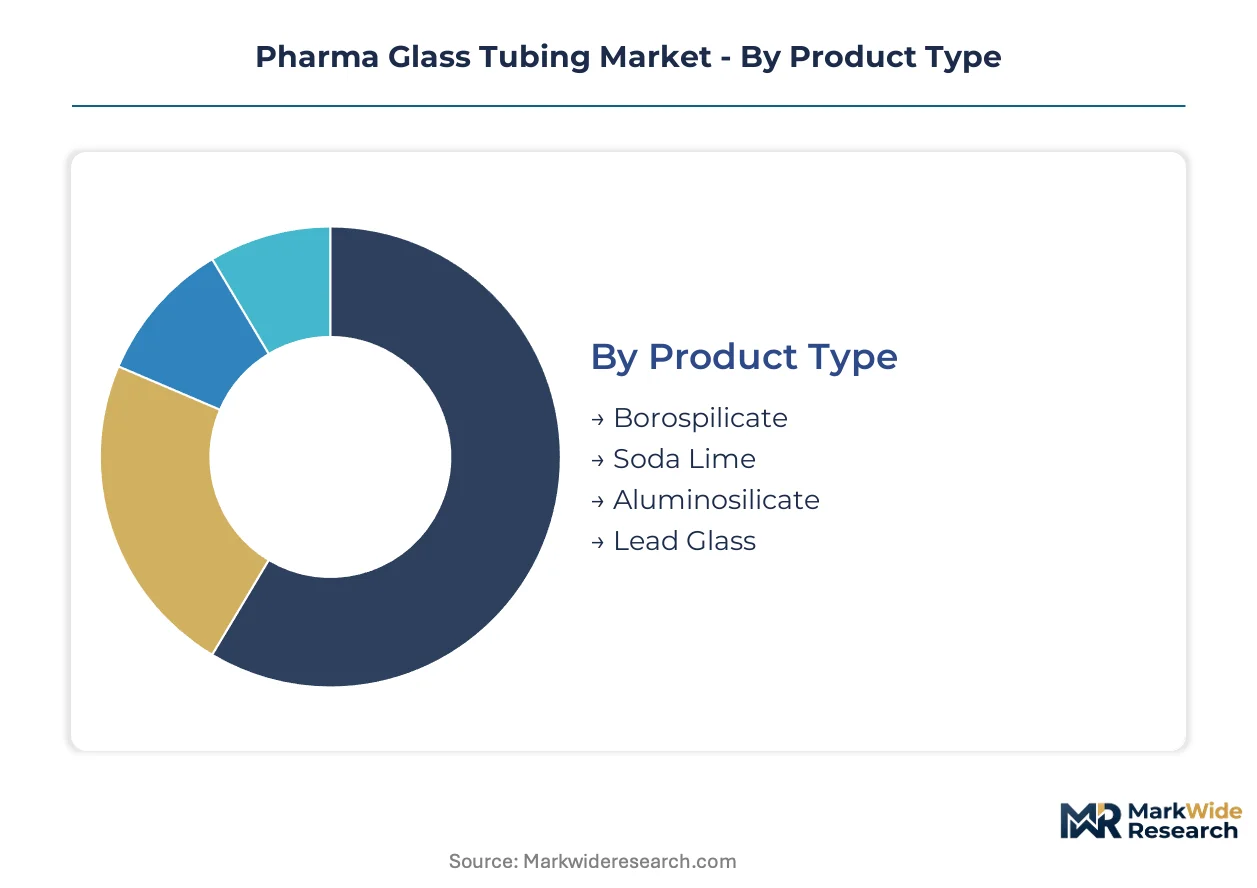
Segmentation in pharma glass tubing reveals how material chemistry, container format, and manufacturing precision stratify value capture. Each axis exposes different competitive dynamics—raw material qualification, fill-finish automation compatibility, and regulatory documentation burdens.
Product Type:
Thermal expansion coefficients and chemical durability separate grades, with biologics manufacturers imposing tighter specifications on parenteral containment materials.
- Borosilicate:Glass with thermal expansion below 3.3 x 10^-6/K dominates parenteral biologics applications. Injectable monoclonal antibody producers in Germany and Massachusetts specify this grade exclusively for delamination resistance under US FDA cGMP.
- Soda Lime:Commodity-grade glass with higher alkali content faces displacement from sensitive formulations. Oral solid dose and topical packaging in India absorb residual volumes as CDSCO enforcement of ICH guidelines lags European MDR stringency.
- Aluminosilicate:Enhanced dimensional stability serves mRNA vaccine ultra-cold chain requirements. Temperature-critical applications command 15-20% cost premiums over standard borosilicate.
- Lead Glass:Radiation shielding properties serve diagnostic reagent containment. Specialized nuclear medicine applications in Switzerland and France sustain niche demand.
Borosilicate leads on scale; aluminosilicate leads on momentum.
Application:
Container format determines precision requirements, with prefillable systems demanding tighter dimensional tolerances than open-vial formats.
- Vials:Standard borosilicate and soda lime volumes concentrate here. Multi-dose biologics and lyophilized formulations in Chinese fill-finish hubs near Shanghai absorb the largest tubing tonnage.
- Syringes:Prefillable formats for auto-injector platforms require precision-drawn tubing with strict inner diameter control. Diabetes and rheumatology therapy producers in North Carolina specify cartridges for pen-injector compatibility.
- Ampoules:Single-dose break-seal containers serve emergency medicine and anesthetic applications. European MDR material traceability mandates accelerate substitution toward certified pharmacopeial-grade sources.
- Cartridges:Pen-injector and auto-injector platforms consume specialized tubing with enhanced dimensional stability. Precision requirements exceed standard vial specifications by factor of two.
Vials dominate absolute volume; cartridges expand most quickly.
End User:
Procurement sophistication varies sharply, with large molecule developers consolidating supplier panels while research buyers remain fragmented.
- Pharmaceutical Companies:Large-scale fill-finish operators in Germany, China, and India drive bulk tubing demand. Three to five-year master service agreements with fixed pricing now replace spot purchasing for volume security.
- Biotechnology Firms:Cell therapy and gene therapy developers impose the strictest material qualification protocols. Massachusetts and North Carolina clusters demand bundled tubing supply with delamination testing services.
- Research Laboratories:Small-batch requirements and specification diversity favor distributors over direct mill relationships. Academic medical centers in Japan and South Korea sustain spot-market volumes.
- Hospitals:Compounding pharmacy and clinical trial material needs generate fragmented, specification-diverse demand. Regional converters serve this tier through distributor networks.
Pharmaceutical companies lead on scale; biotechnology firms lead on specification intensity.
Manufacturing Stage:
Process control sophistication concentrates in continuous drawing and precision annealing, where defect detection capabilities differentiate suppliers.
- Drawing:Vertical furnace technology with precision thermal management produces the highest-purity tubing. Operational expertise concentrates among German and Japanese equipment suppliers, constraining new entrant scaling.
- Forming:Secondary shaping into vial blanks or syringe barrels requires dimensional control within microns. Automation integration with fill-finish lines demands real-time specification feedback.
- Annealing:Controlled cooling eliminates internal stresses that cause thermal shock failure. Vaccine ultra-cold storage protocols stress annealing quality more severely than standard pharmaceutical applications.
- Coating:Interior surface treatments reduce protein adsorption and delamination risk. Siliconization and polymer barrier layers add processing steps that extend qualification timelines under US FDA container closure integrity requirements.
Drawing commands the steepest capability premiums; coating gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized furnace operators and glass technologists cluster near pharmaceutical manufacturing hubs in Germany, China, and the United States, anchoring regional supply capabilities to end-user proximity requirements.
Germany
Injectable monoclonal antibody producers in Bavaria and Baden-Württemberg drive demand for pharmacopeial-grade borosilicate tubing. EMA's MDR material traceability mandates accelerate substitution of unverified glass sources with certified suppliers. Specialized tubing plants concentrate near Stuttgart and Mainz, leveraging vertical furnace expertise developed over decades of optical glass manufacturing heritage.
United States
Cell therapy developers in Massachusetts and North Carolina impose the strictest material qualification protocols for parenteral containment. FDA cGMP container closure integrity standards mandate extensive glass delamination resistance testing, stretching qualified analytical laboratory throughput. Fill-finish contractors in the Research Triangle and Greater Boston regions are consolidating supplier panels under three to five-year master service agreements.
China
Domestic biopharmaceutical fill-finish operations near Shanghai and Suzhou previously served by local soda lime suppliers are upgrading to international-grade borosilicate specifications. NMPA's updated GB standards for injectable glass create qualification pathways for certified producers. Yangtze River Delta manufacturing clusters absorb the largest tubing tonnage for multi-dose biologics and lyophilized formulations.
India
CDSCO's alignment with ICH guidelines and production-linked incentive schemes for active pharmaceutical ingredients create demand for import-substitute tubing capacity. Mumbai and Hyderabad pharmaceutical clusters seek domestic borosilicate supply to reduce dependence on European and Japanese imports. Spot-market volumes persist for oral solid dose packaging as enforcement of pharmacopeial standards lags European stringency.
Switzerland
Radiopharmaceutical and diagnostic reagent manufacturers in Basel and Geneva sustain niche demand for specialized lead glass containment. Swissmedic's stringent biocompatibility documentation requirements favor suppliers with captive analytical capabilities and batch-level provenance mapping. Precision glass converters serving nuclear medicine applications command capability premiums for radiation shielding formulations.
Pharma Glass Tubing Market Competitive Landscape
Capital-heavy producers compete with asset-light converters across a tiered market structure where furnace ownership and vertical thermal management capabilities determine strategic positioning. The vendor base stratifies between integrated manufacturers with captive sand refining and drawing operations, mid-scale converters purchasing glass billet for secondary forming, and regional distributors serving fragmented research and hospital demand. Three archetypes dominate: German and Japanese integrated producers with proprietary furnace technology, Chinese and Indian cost-optimized converters scaling soda lime volumes, and European specialists targeting radiopharmaceutical and diagnostic niches. Competitive moves concentrate on backward integration into high-purity silica and boron raw material sourcing, and specification partnerships with fill-finish automation vendors for real-time dimensional feedback.
Among integrated producers with proprietary vertical furnace technology, Schott AG and Corning Incorporated exemplify the capital-intensive archetype that anchors high-purity borosilicate supply for biologics manufacturers. Nipro Corporation occupies a position within the cost-optimized tier, representing Japanese manufacturing discipline applied to standardized vial and ampoule volumes. These three entities illustrate how geographic concentration of furnace expertise—German optical glass heritage, American materials science capability, and Japanese precision manufacturing—translates into durable competitive positioning despite raw material volatility and qualification timeline pressures.
| Leading Market Players |
|---|
| Schott AG |
| Corning Incorporated |
| Nipro Corporation |
| Gerresheimer AG |
| Stevanato Group |
| Nippon Electric Glass |
| Shandong Pharmaceutical Glass |
| Bormioli Pharma |
| DWK Life Sciences |
| Others |
Value Network & Pricing Analysis
Europe's REACH restricted substance limits and MDR biocompatibility documentation requirements gate qualified supply for premium-tier borosilicate tubing, forcing converters to invest in captive analytical capabilities and batch-level provenance mapping before accessing biologics manufacturer procurement panels.
Pricing Analysis
The bundled-vs-unbundled service split separates Schott AG and Corning Incorporated's integrated offerings from regional converters. Three-tier pricing structure across pharmacopeial-grade, standard borosilicate, and commodity soda lime levels reflects certification intensity and delamination testing inclusion. Cost compression in soda lime segments intensifies because cyclic olefin polymers displace glass in oral packaging. Research laboratories and hospital compounding pharmacies exhibit highest price sensitivity; biotechnology firms in Massachusetts and North Carolina demonstrate lowest sensitivity due to bundled technical support requirements.
Supply Chain Analysis
Dual-sourcing requirements from US FDA cGMP and EMA MDR frameworks compel fill-finish operators to qualify multiple borosilicate suppliers simultaneously. High-purity silica deposits draw from Germany and China; refined boron supply rests on Turkish and US sources. Single-source vulnerability concentrates in vertical drawing furnace technology controlled by German and Japanese equipment suppliers. Distribution runs through direct mill relationships for pharmaceutical companies and distributor networks for fragmented research demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where Europe's MDR material traceability mandates and US FDA container closure integrity standards continuously tighten qualification thresholds and expand addressable demand for certified pharmacopeial-grade tubing.
For Market Incumbents: Anticipate cyclic olefin polymer substitution in standard vial applications by accelerating backward integration into high-purity silica and boron raw material sourcing. Defensive consolidation through specification partnerships with fill-finish automation vendors for real-time dimensional feedback will protect margin structures against emerging Chinese converters scaling borosilicate capacity under NMPA harmonization pathways. For New Entrants and Emerging Players: Digital-channel routes through e-procurement platforms serving research laboratories and hospital compounding pharmacies offer lowest barrier-to-entry access. White-space targets concentrate in India's CDSCO-aligned ICH corridor near Mumbai and Hyderabad, where import-substitute demand outpaces domestic borosilicate supply. Niche positioning through siliconized interior coating capabilities for protein-sensitive biologics provides differentiated go-to-market angle. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale converters with qualified furnace operations because EMA MDR and US FDA documentation burdens are accelerating consolidation toward integrated producers with captive analytical capabilities. Five-to-ten year viability hinges on regulatory divergence rather than demand contraction. Acquisition target archetype: European or Japanese converters with vertical drawing furnace assets and existing pharmacopeial certification. Signal to watch: NMPA GB standard enforcement velocity creating qualification backlog for international-grade producers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into High-Purity Silica | Secures borosilicate raw material supply against Turkish and Chinese export restrictions. |
| Specification Partnership with Fill-Finish Automation Vendors | Enables real-time dimensional feedback for cartridge precision requirements in pen-injector platforms. |
| Delamination Testing Service Bundling | Captures biotechnology firm procurement panels in Massachusetts and North Carolina clusters. |
| CDSCO-Aligned Certification Investment | Unlocks production-linked incentive schemes for API manufacturing near Mumbai and Hyderabad. |
| Aluminosilicate Formulation Development | Addresses mRNA vaccine ultra-cold chain stress on conventional borosilicate structures. |
Research Methodology
Multiple input streams — structured interviews with pharmaceutical manufacturing executives and regulatory affairs directors, trade data from customs filings, and pharmacopeial standard documentation — were reconciled through bottom-up and top-down triangulation. Secondary validation drew from FDA cGMP guidance documents, EMA MDR implementation reports, NMPA GB standard updates, and SEC filings from publicly traded glass converters. Primary fieldwork encompassed fill-finish operators in Germany, China, India, and the United States alongside furnace equipment specialists and analytical laboratory service providers.
Data-stream reconciliation across volume shipments, capacity utilization rates, and procurement contract structures informed the analytical framework. Segmentation dimensions modeled included glass chemistry grade, container format specification, end-user procurement sophistication, and regional regulatory cluster alignment. CAGRs were derived from curve-fitting approaches applied to disclosed capacity expansion timelines and biologics pipeline progression data. Forecast inputs incorporated mRNA manufacturing platform adoption curves and ICH guideline harmonization velocity across emerging markets.
The model assumes a particular technology adoption path; alternative pathways for aluminosilicate glass in temperature-critical vaccine applications would alter the outlook. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and raw material supply continuity. Deviation in EMA MDR audit intensity or NMPA GB standard implementation pace would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
Antiglare Glass Market
Glass
Global Vacuum Insulated Glass Market
Glass
Glass Substrate Market
Glass
Ultra Violet Glass Bottles Market
Glass
Europe Flat Glass Market
Glass
Glass Vials Market
Glass
Middle East and Africa Glassware Market
Glass
Mirrored Glass Market
Glass
Global Energy Efficient Glass Market
Glass
Low Iron Glass Market
Glass
Glass Like Carbon Market
Glass
Flexible Glass Market
Glass
India Flat Glass Market
Glass
Glass Tableware Market
Glass
Global Glassware Market
Glass
Global Vitrification Market