
 Pharmaceutical Glass Tubing Market | 2026-2036
Pharmaceutical Glass Tubing Market Size, Share, and Industry Trends Forecast 2026-2036
Pharmaceutical Glass Tubing Market Analytics
Biopharmaceutical fill-finish operations is repositioning demand toward premium borosilicate and neutral glass formats that withstand aggressive biologic formulations. Schott AG leverages its German manufacturing base to dominate technical-grade borosilicate supply for cartridge and syringe applications. Gerresheimer AG anchors European vial demand through specialized molded glass capacity. Nippon Electric Glass Co. Ltd competes across Asia-Pacific with high-hydrolytic-resistance tubing for ampoule converters.
Pharmaceutical glass tubing denotes borosilicate or aluminosilicate glass cylinders manufactured via horizontal or vertical drawing processes, typically exhibiting thermal expansion coefficients below 5.0 × 10⁻⁶ K⁻¹ and hydrolytic resistance class HGA1 per ISO 719, engineered to contain injectable and biologic drug products without ion exchange or particulate shedding. Neutral glass commands premium positioning in biologics containment due to its superior chemical durability and reduced alkali leaching compared with soda-lime alternatives. Cartridge applications represent the fastest-growing structural segment as pre-filled delivery systems displace traditional vial-and-syringe workflows in chronic disease administration.
FDA enforces Container Closure System guidance and USP <660> glass grain classification, while EMA mandates compliance with EU GMP Annex 1 sterile manufacturing standards; both frameworks elevate barrier performance requirements and disqualify lower-grade soda-lime tubing from parenteral applications. ISO 15378 and pharmacopeial harmonization across USP, EP, and JP chapters further tighten supplier qualification protocols. Stakeholders must monitor evolving extractables testing thresholds and dual-source qualification timelines as regulatory stringency converges with biologic pipeline expansion.
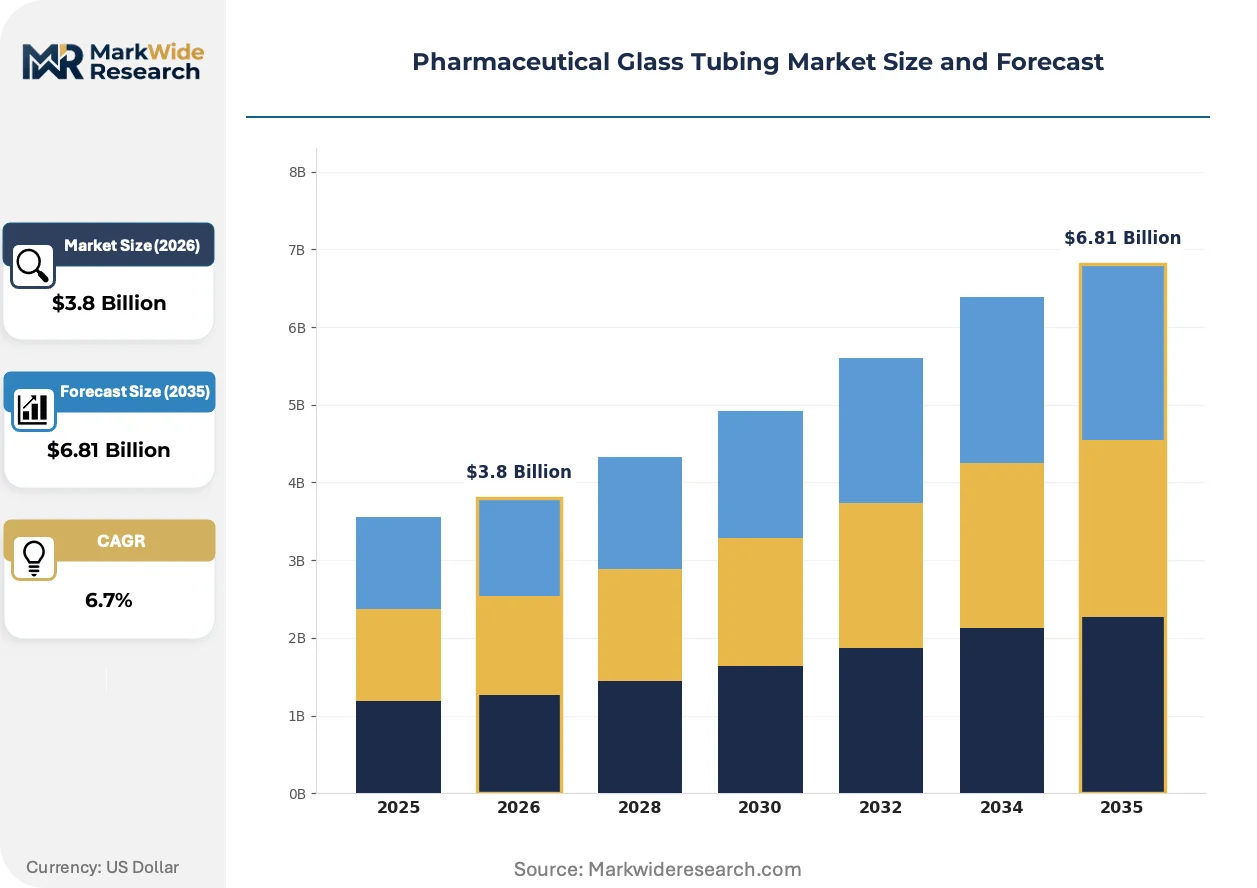
Market Dynamics
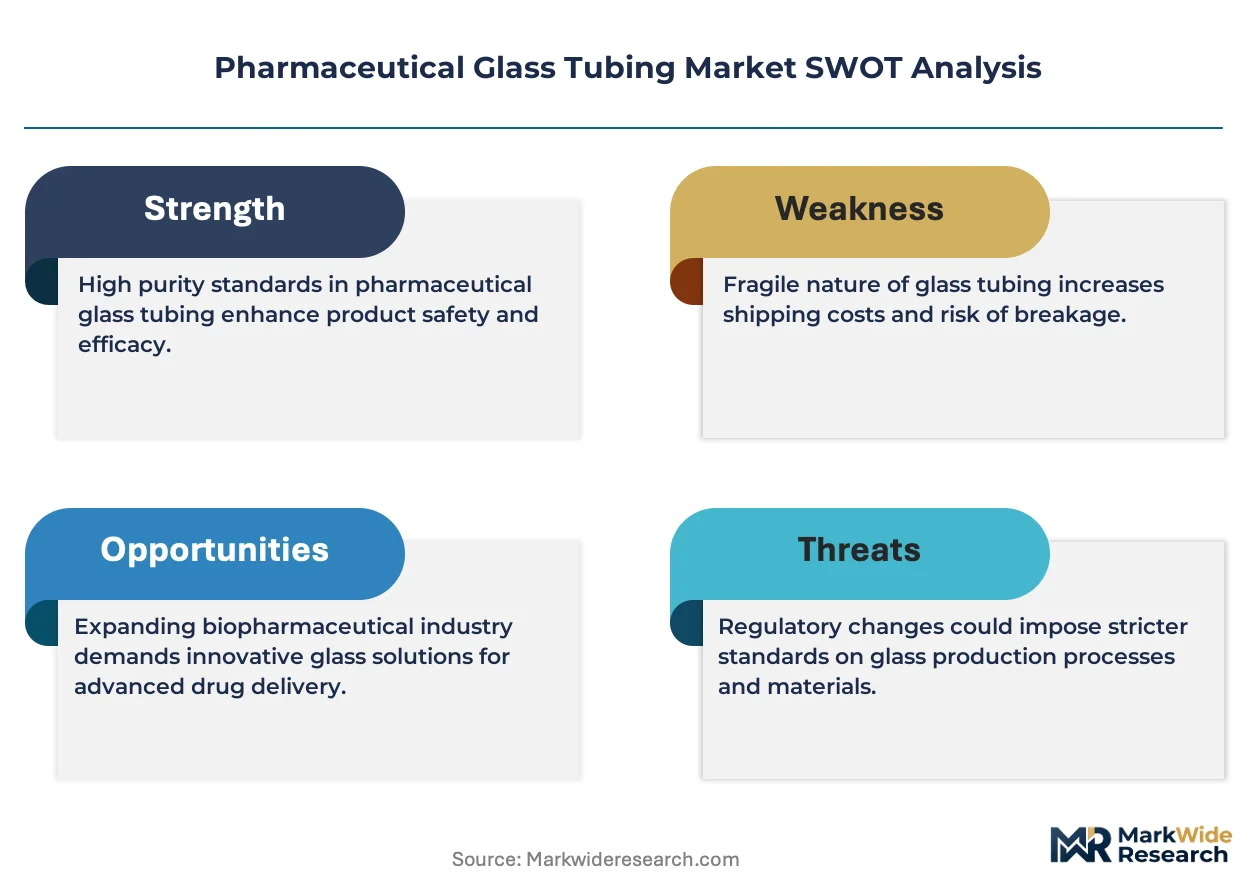
FDA and EMA extractables-leachables enforcement is compressing supplier qualification timelines while biologics pipelines expand, creating a structural bottleneck where qualified borosilicate capacity cannot scale as fast as containment demand.
Growth Catalysts
- EU GMP Annex 1 sterile manufacturing standards:EMA's tightened barrier performance requirements disqualify soda-lime tubing from parenteral applications, forcing converters toward premium borosilicate formats.
- Pre-filled cartridge systems:Chronic disease administration workflows are displacing vial-and-syringe protocols in insulin and biologic delivery, amplifying demand for dimensionally precise tubing.
- German production clusters:Specialized borosilicate drawing operations in Mainz and Mitterteich anchor European fill-finish supply chains with technical-grade capacity.
Market Restraints
- Borosilicate raw material concentration:High-purity silica and boron oxide supply concentrates among limited specialty chemical producers, exposing converters to input cost volatility.
- Horizontal drawing furnace capex intensity:Precision tubing manufacture requires continuous melting and forming equipment that locks capital for decade-long depreciation cycles.
- ISO 15378 supplier qualification timelines:Harmonized pharmacopeial certification across USP, EP, and JP chapters extends approval periods to 18-24 months, freezing new entrants from active sourcing.
Strategic Opportunities
- India CDMO fill-finish expansion:Contract development and manufacturing organizations in Hyderabad and Ahmedabad are building sterile injectable capacity that lacks qualified domestic glass supply.
- Cell and gene therapy containment:Ultra-cold chain requirements for mRNA and viral vector products favor aluminosilicate tubing with thermal shock resistance below -80°C.
- Dual-source qualification mandates:Large molecule sponsors now require redundant tubing suppliers per FDA Container Closure System guidance, opening secondary sourcing slots.
Industry Challenges
- Dimensional tolerance engineering talent:Precision glass drawing requires process engineers with rare expertise in thermal expansion coefficient control and hydrolytic resistance optimization.
- Extractables testing protocol fragmentation:Absence of standardized analytical methods across FDA, EMA, and PMDA jurisdictions forces redundant qualification studies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pharmaceutical Glass Tubing Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Neutral Glass, Borosilicate Glass, Soda-Lime Glass, Specialty Glass Application: Vials, Ampoules, Cartridges, Syringes End User: Pharmaceutical Companies, Contract Manufacturers, Research Laboratories, Biotech Firms Delivery Mode: Bulk, Custom Orders, Pre-sterilized, Standardized |
| Companies Covered | Nippon Electric Glass Co. Ltd, Stevanato Group, Schott AG, DWK Life Sciences GmbH, SGD Pharma, Corning Incorporated, Gerresheimer AG, Shandong Pharmaceutical Glass Co. Ltd, Nipro Pharma Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pharmaceutical Glass Tubing Market Evolving Landscape
Pharmaceutical glass tubing is undergoing material and process transformation as regulatory chemistry thresholds tighten and biologic formulations grow more aggressive. Three developments are restructuring competitive positioning.
Aluminosilicate tubing with thermal expansion coefficients below 3.5 × 10⁻⁶ K⁻¹ is decentralizing high-performance containment supply away from traditional borosilicate strongholds. Cell therapy developers and mRNA vaccine manufacturers are adopting these formats for ultra-low-temperature stability. This material shift is decentralizing procurement patterns as sponsors seek regional alternatives to German supply concentration.
EMA's 2022 revision to EU GMP Annex 1 mandates barrier integrity verification for all sterile drug products, including glass-container interaction studies. Industrial consequence includes mandatory extractables screening for every new tubing qualification batch. Cartridge and pre-filled syringe segments are responding by consolidating supplier relationships with manufacturers holding dedicated analytical laboratories.
Converter procurement is compressing qualification cycles through pre-approved supplier frameworks rather than transactional spot purchasing. Large biopharmaceutical sponsors are disintermediating distributors to negotiate direct volume commitments with tubing manufacturers. This pattern is most visible in Germany and Switzerland where fill-finish operations cluster near glass production facilities.
Pharmaceutical Glass Tubing Market Segmentation
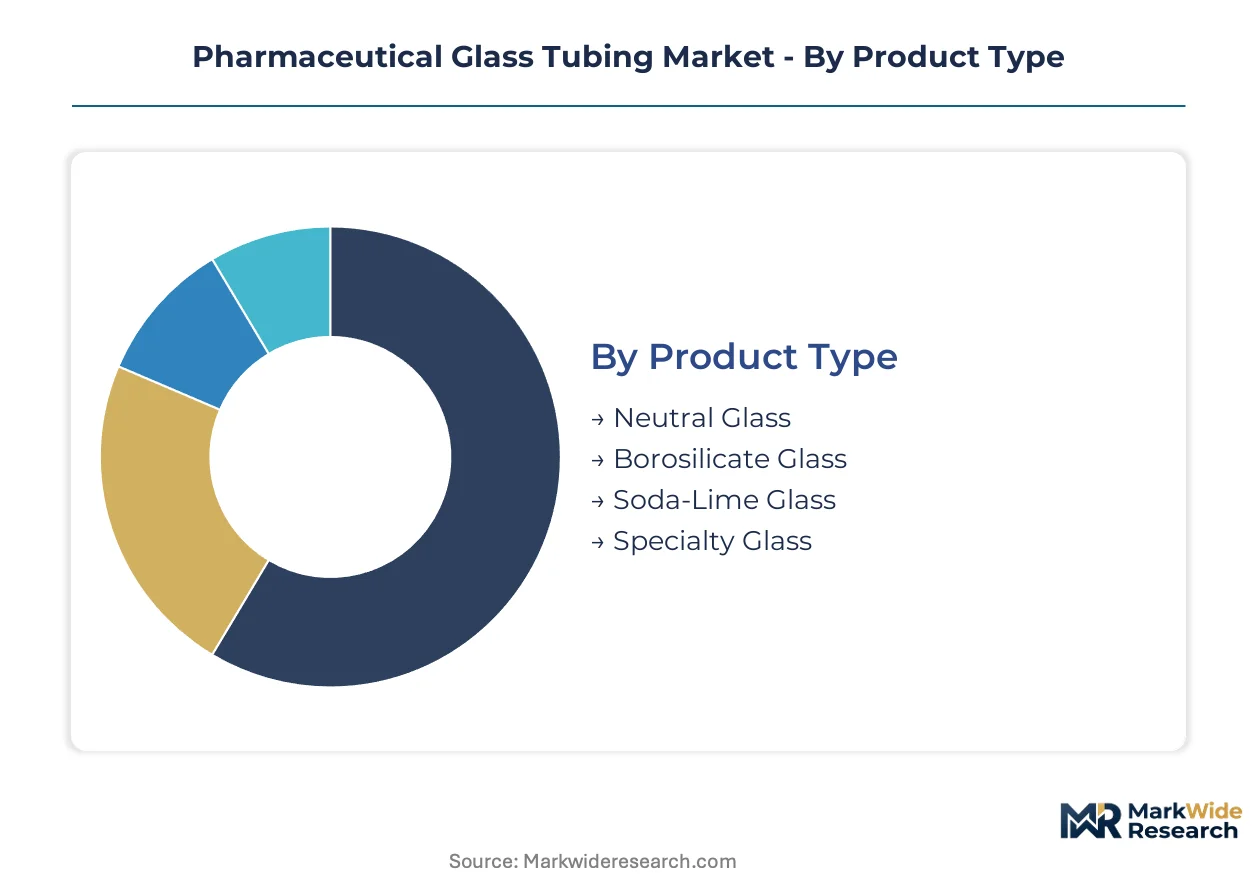
Pharmaceutical glass tubing segmentation reflects the tension between standardized pharmacopeial grades and application-specific performance requirements. Converter procurement patterns diver sharply across biologics containment versus generic injectables, with regulatory chemistry thresholds dictating material selection at the SKU level.
Product Type:
Customization versus standardization spans a spectrum from commodity soda-lime formats to engineered neutral glass compositions with batch-certified hydrolytic resistance.
- Neutral Glass:Chemically inert borosilicate formulations with alkali oxide content below 2% and hydrolytic resistance class HGA1 per ISO 719. German fill-finish operations in Mainz and Mitterteich anchor demand as EMA extractables thresholds tighten for parenteral biologics.
- Borosilicate Glass:Thermal expansion coefficients of 3.3 × 10⁻⁶ K⁻¹ enable rapid thermal cycling during sterilization. Schott AG's FIOLAX Pro and Gerresheimer's GX Elite formats dominate cartridge and syringe applications where dimensional stability under autoclaving is non-negotiable.
- Soda-Lime Glass:Lower-cost formulations with higher alkali leaching profiles increasingly restricted to oral solid dosage packaging and non-parenteral applications as FDA Container Closure System guidance elevates barrier requirements.
- Specialty Glass:Aluminosilicate and surface-modified compositions engineered for ultra-cold chain mRNA and cell therapy containment with thermal shock resistance below -80°C.
Leading the category by volume: Borosilicate Glass. Expanding most quickly: Specialty Glass.
Application:
Volume concentration versus value capture splits this category between high-unit vial demand and precision-engineered cartridge growth.
- Cartridges:Dimensionally precise tubing with inner diameter tolerances of ±0.05mm for pre-filled pen injector and autoinjector systems. Insulin and biologic chronic disease administration in Germany and Switzerland drives fastest expansion as pre-filled formats displace vial-and-syringe workflows.
- Vials:Molded and tubular glass formats for lyophilized and liquid parenteral drugs. European fill-finish clusters maintain dominant share despite Indian CDMO capacity buildout.
- Syringes:Pre-filled and bulk-sterilized formats for acute care and vaccination delivery, with luer-lock compatibility requirements constraining supplier qualification.
- Ampoules:Single-dose break-seal containment for emergency and field medicine applications, concentrated in Asian markets with cost-sensitive procurement.
Volume leadership: Vials. Steepest expansion trajectory: Cartridges.
End User:
Direct procurement versus distributor-mediated purchasing distinguishes sponsor-controlled supply chains from outsourced manufacturing relationships.
- Pharmaceutical Companies:Large molecule sponsors with dual-source qualification mandates per FDA guidance negotiate direct volume commitments with Schott AG and Gerresheimer AG, bypassing distribution layers.
- Contract Manufacturers:CDMO fill-finish operations in Hyderabad and Ahmedabad lack qualified domestic glass supply, creating import dependency on German and Japanese tubing sources.
- Biotech Firms:Cell and gene therapy developers with ultra-cold chain requirements favor aluminosilicate specialty formats for viral vector and mRNA stability.
- Research Laboratories:Small-batch, non-GMP demand for preclinical and clinical trial materials with flexible specification tolerance.
Procurement concentration: Pharmaceutical Companies. Fastest-growing demand source: Contract Manufacturers.
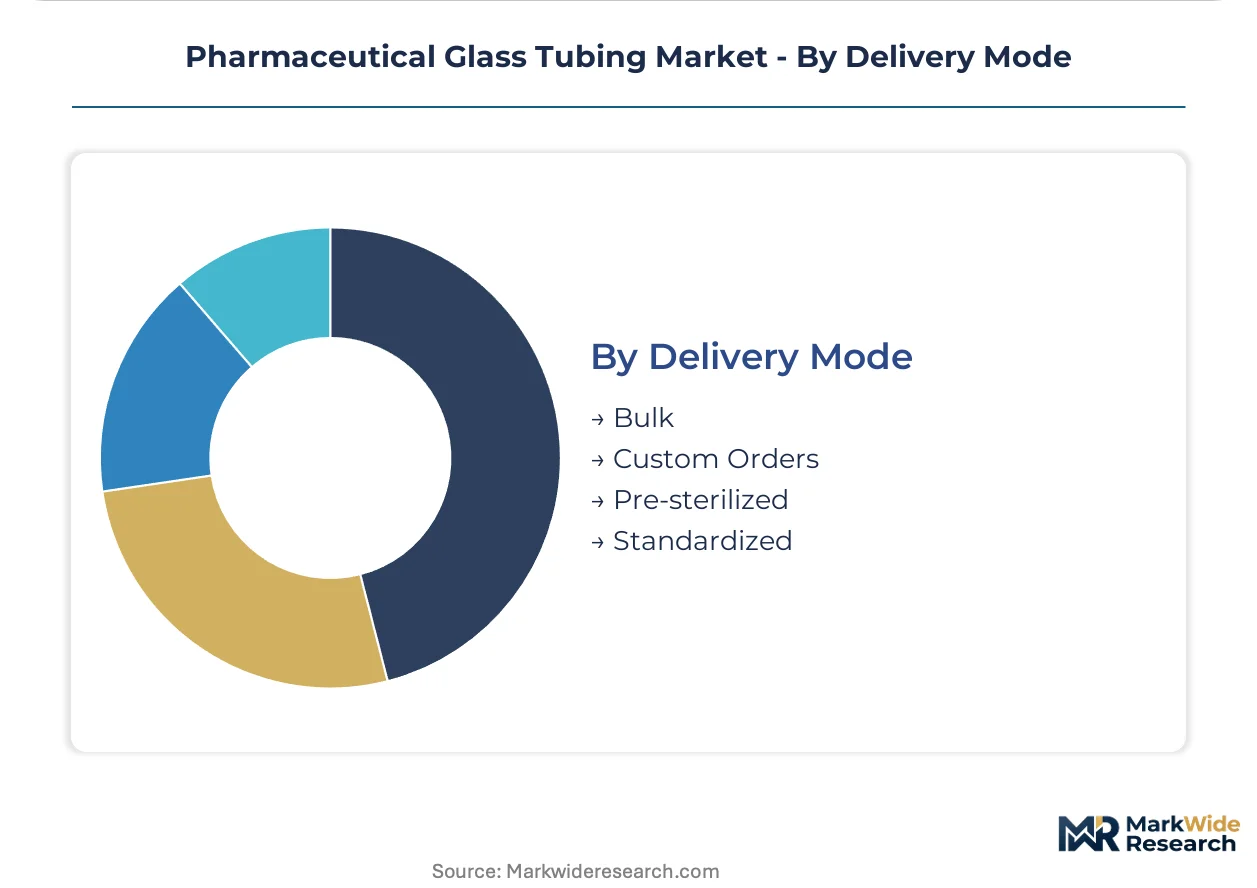
Delivery Mode:
Inventory risk versus specification control shapes converter decisions between bulk commodity purchases and validated pre-sterilized supply.
- Pre-sterilized:Gamma-irradiated or ethylene oxide-treated tubing with certified sterility assurance levels for aseptic fill-finish operations. EMA's EU GMP Annex 1 revision elevates barrier integrity verification requirements, consolidating demand with suppliers holding dedicated sterilization validation.
- Bulk:Unprocessed tubing reels for converters with in-house washing, siliconization, and sterilization capabilities. Cost advantage erodes as ISO 15378 qualification timelines extend.
- Custom Orders:Diameter, wall thickness, and surface chemistry modifications for proprietary drug-device combination products.
- Standardized:Pharmacopeial-grade dimensions per USP <660>, EP 3.2.1, and JP G7 harmonized specifications for multi-source interchangeability.
Dominant procurement format: Bulk. Gaining share fastest: Pre-sterilized.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German borosilicate production clusters supply fill-finish operations across Europe, while Indian CDMO expansion strains qualified domestic glass availability. Demand from biologics containment outpaces regional manufacturing capacity in multiple markets.
Germany
EMA's EU GMP Annex 1 sterile manufacturing standards force converters toward premium borosilicate formats. Schott AG and Gerresheimer AG anchor specialized drawing operations in Mainz and Mitterteich. These technical-grade facilities serve European parenteral drug fill-finish networks with batch-certified hydrolytic resistance tubing.
United States
FDA Container Closure System guidance and USP glass grain classification elevate barrier performance requirements for biologic drug delivery. Large molecule sponsors now mandate dual-source qualification per regulatory precedent. Boston-Cambridge and Research Triangle fill-finish clusters source heavily from German tubing imports.
India
CDMO sterile injectable capacity in Hyderabad and Ahmedabad expands faster than qualified domestic glass supply can match. CDSCO import dependency rules create regulatory friction for German and Japanese tubing sources. Local converters face 18-24 month ISO 15378 qualification timelines for new supplier onboarding.
Japan
PMDA extractables testing protocols for parenteral containers align with USP and EP harmonization trends. Nippon Electric Glass Co. Ltd supplies high-hydrolytic-resistance tubing for ampoule converters across Asia-Pacific. Osaka-Tokyo pharmaceutical manufacturing corridors maintain stringent supplier qualification standards.
China
NMPA tightening of pharmaceutical packaging material standards pressures domestic soda-lime producers toward borosilicate conversion. Shandong Pharmaceutical Glass Co. Ltd represents state-backed capacity buildout in specialty formats. Yangtze River Delta biologics clusters increasingly specify imported neutral glass for export-bound drug products.
Pharmaceutical Glass Tubing Market Competitive Landscape
Top-tier vendors anchor German and Japanese technical-grade supply, while mid-scale specialists and regional fabricators compete on qualification speed and custom dimensions. The vendor base stratifies across three archetypes: integrated borosilicate draw specialists with captive analytical labs, converter-integrated tubing operations serving captive demand, and independent regional mills targeting generic injectables. Dominant competitive moves include backward integration into high-purity raw material sourcing and dedicated sterilization validation capacity.
Among German AG-structured market leaders, Schott AG and Gerresheimer AG exemplify the integrated specialist archetype with Mainz and Mitterteich production clusters. Nippon Electric Glass Co. Ltd represents the Asia-Pacific technical-grade alternative, occupying a position calibrated to regional ampoule and vial converter networks. These three entities anchor the qualified supplier tier that FDA and EMA dual-source mandates now require.
| Leading Market Players |
|---|
| Nippon Electric Glass Co. Ltd |
| Stevanato Group |
| Schott AG |
| DWK Life Sciences GmbH |
| SGD Pharma |
| Corning Incorporated |
| Gerresheimer AG |
| Shandong Pharmaceutical Glass Co. Ltd |
| Nipro Pharma Corporation |
| Others |
Value Network & Pricing Analysis
High-purity silica and boron oxide spot indices cascade through pharmaceutical glass tubing supply chains into three distinct pricing tiers tied to hydrolytic resistance certification and thermal expansion performance. German-drawn borosilicate commands premium positioning as EMA extractables thresholds tighten, while soda-lime alternatives face margin compression from disqualification in parenteral applications.
Pricing Analysis
Margin tightening in standard-grade tubing reflects raw material cost pass-through from concentrated specialty chemical suppliers. Three-tier pricing structure across premium neutral glass, technical-grade borosilicate, and commodity soda-lime segments differentiates by ISO 719 hydrolytic class and USP <660> grain certification. Cost-down pressure on soda-lime formats accelerates because FDA Container Closure System guidance elevates barrier requirements for biologic containment. Generic injectable converters exhibit highest price sensitivity; large molecule sponsors with dual-source mandates prioritize qualification reliability over unit cost.
Supply Chain Analysis
ISO 15378 qualification timelines gating supplier onboarding stretch 18-24 months, freezing new entrants from active sourcing and entrenching incumbent positions. Production gravity centers on Germany, Japan, and China, with Schott AG and Gerresheimer AG anchoring European technical-grade capacity. High-purity silica, boron oxide, and alumina feedstocks draw from limited specialty chemical producers, exposing converters to input cost volatility. Single-source vulnerability concentrates in German borosilicate drawing operations serving FDA and EMA dual-source mandates. Distribution runs through direct volume commitments between tubing manufacturers and large pharmaceutical sponsors, bypassing distributor layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pharmaceutical glass tubing is consolidating around qualified capacity as regulatory chemistry thresholds and dual-source mandates force sub-scale converters toward exit. EMA's EU GMP Annex 1 revision and FDA extractables enforcement are compressing supplier qualification timelines faster than new capacity can achieve certification.
For Market Incumbents: Cement market position by securing captive high-purity raw material supply through backward integration into boron oxide and silica sourcing. Expand dedicated analytical laboratory capacity to accelerate extractables screening for converter qualification batches. Defend against aluminosilicate displacement threats by certifying next-generation thermal shock-resistant formats for ultra-cold chain applications. For New Entrants and Emerging Players: Begin with contract manufacturing fill-finish operations in Hyderabad and Ahmedabad, where CDSCO import dependency rules create demand for qualified domestic tubing supply. Target pre-sterilized cartridge segments as the most penetrable growth vector, bypassing bulk tubing commoditization. Pursue ISO 15378 certification through partnership with established European technical advisors to compress qualification timelines. For Investors and Strategic Acquirers: The window for entry favors mid-scale German and Japanese tubing specialists with existing pharmacopeial certifications and underutilized drawing furnace capacity. Long-term viability rests on positioning for cell and gene therapy containment demand requiring aluminosilicate thermal shock resistance below -80°C. Watch for inflection in Indian CDMO sterile injectable capacity buildout outpacing qualified domestic glass supply as the signal to accelerate deployment.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Raw Materials | Captive boron oxide supply insulates margin from specialty chemical price volatility. |
| Dedicated Sterilization Validation Capacity | Pre-sterilized tubing certification aligns with EMA EU GMP Annex 1 barrier integrity mandates. |
| Aluminosilicate Format Development | Thermal shock resistance below -80°C captures mRNA and cell therapy containment demand. |
| Dual-Source Qualification Partnerships | FDA Container Closure System guidance creates redundant supplier slots for certified entrants. |
| Regional Production Cluster Proximity | Mainz and Mitterteich adjacency reduces logistics friction for European fill-finish networks. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this pharmaceutical glass tubing analysis. Primary interviews with fill-finish operations directors, regulatory affairs specialists at tubing converters, pharmaceutical procurement managers, and glass process engineers combined with FDA 483 observations and EMA inspection reports. Bottom-up tubing volume estimates by application and top-down pharmaceutical packaging spend analysis triangulated market sizing across the projection horizon.
Granularity-level modeling addressed product type, application, end user, and delivery mode segments with regional regulatory cluster differentiation. CAGRs derived from elasticity-adjusted demand projections incorporating biologics pipeline expansion and qualification timeline constraints. Forecast inputs included CDSCO import dependency ratios, ISO 15378 certification velocity, and fill-finish capacity buildout timelines in Hyderabad and Ahmedabad.
Regulatory chemistry threshold revisions, dual-source mandate enforcement intensity, and raw material supply disruptions are the dominant revision risks to pharmaceutical glass tubing demand assumptions. A model refresh is warranted upon material change in EMA extractables testing protocols or FDA Container Closure System guidance implementation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
Asia-Pacific Silica Sand Market
Glass
India Flat Glass Market
Glass
Glass Grade Dolomite Market
Glass
Optical Glass Market
Glass
Screen-Printing Glass Market
Glass
Cellular Glass Market
Glass
Spherical Silica Market
Glass
Global Silicone Structural Glazing Market
Glass
Global Scratch Resistant Glass Market
Glass
Solar PV Glass Market
Glass
Laboratory Glass Container Market
Glass
Optical Lens Material Market
Glass
North America Flat Glass Market
Glass
Decorative Glass Market
Glass
Glass Prepreg Market
Glass
Global Energy Efficient Glass Market