
 Global 4K Camera Market | 2026-2036
Global 4K Camera Market Size, Share, and Industry Trends Forecast 2026-2036
Global 4K Camera Market Analysis
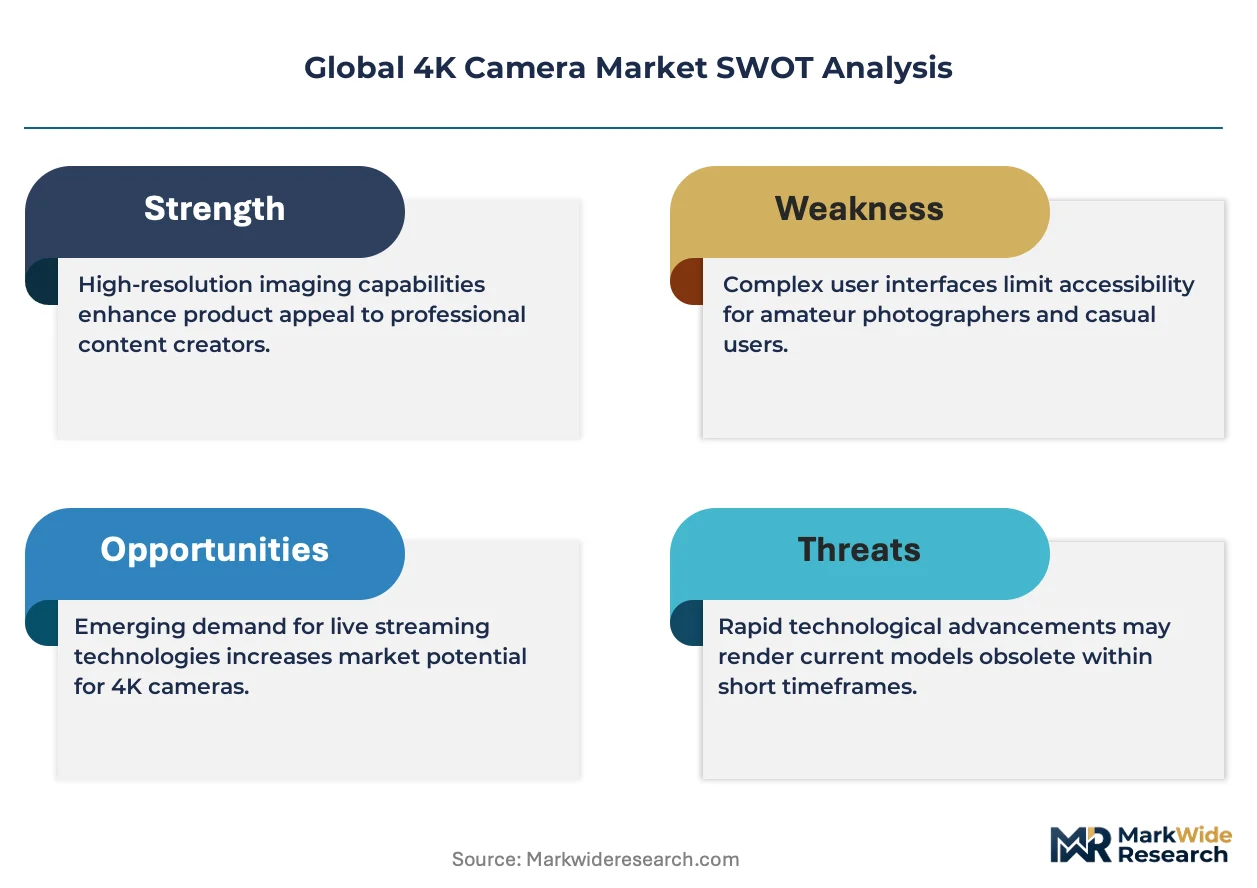
Equipment leasing and subscription-based financing is rewriting competitive dynamics in the 4K camera sector, lowering capital barriers for independent studios and regional broadcasters. Sony leverages its sensor fabrication scale to anchor premium mirrorless supply chains. Canon sustains dominance in professional cinematography through its cinema lens ecosystem. Blackmagic Design competes aggressively on price-performance in digital cinema workflows.
A 4K camera captures moving images at a resolution of approximately 3840 × 2160 pixels, utilizing CMOS or CCD sensors with bit depths of 10-bit or higher to deliver color-graded output for broadcast, cinema, and streaming distribution. Mirrorless camera types lead volume growth due to compact form factors and superior low-light performance, while action cameras command expanding share among content creators in extreme-sport and travel verticals. Streaming technology integration across DSLR and mirrorless bodies is accelerating as platforms mandate higher bitrate uploads.
FCC equipment authorization rules in the United States, CE marking requirements under EU MDR and RoHS frameworks, and China's GB standards administered by SAMR collectively govern wireless transmission modules, battery safety, and electromagnetic compatibility in 4K camera systems. These standards shape product development cycles and determine market access eligibility across major economies. Stakeholders must monitor evolving streaming-platform codec requirements and regional data-localization mandates to align R&D roadmaps with compliance thresholds.
Market Dynamics
Streaming platform bitrate mandates are compressing upgrade cycles for independent creators while equipment leasing spreads capital risk across regional broadcast networks.
Growth Catalysts
- EU AI Act compliance frameworks:Connected camera manufacturers are embedding on-device processing to satisfy data-localization requirements, accelerating sensor-to-edge architecture shifts.
- Content creator vertical expansion:Extreme-sport and travel influencers are driving action camera volume through platform-native monetization tools.
- CMOS sensor fabrication scale:Foundry capacity concentration in East Asia is lowering unit economics for 10-bit color depth modules.
Market Restraints
- Specialized optical glass supply:Cinema lens element sourcing depends on concentrated Japanese and German precision manufacturers.
- FCC equipment authorization timelines:Wireless transmission module certification creates six-to-nine-month launch delays for US-bound products.
- Smartphone computational photography:Multi-frame stacking and AI-enhanced output quality erode casual creator demand for dedicated hardware.
Strategic Opportunities
- India's broadcast infrastructure modernization:Regional sports networks and OTT platforms are upgrading studio equipment under national digital expansion programs.
- Cloud-native live production workflows:Camera-to-cloud encoding eliminates local storage hardware for remote production teams.
- Brazil's ANVISA medical imaging convergence:Surgical visualization standards are creating demand for 4K endoscopic camera modules with broadcast-grade color science.
Industry Challenges
- Color science engineering talent scarcity:Advanced LUT development and HDR pipeline expertise concentrates among senior specialists in Tokyo and Los Angeles.
- RoHS substance restriction compliance:Lead-free solder and restricted flame retardant reformulation extends reliability testing cycles.
- Legacy SDI infrastructure integration:Hybrid production environments require simultaneous 12G-SDI and IP-based output, complicating firmware architecture.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global 4K Camera Market |
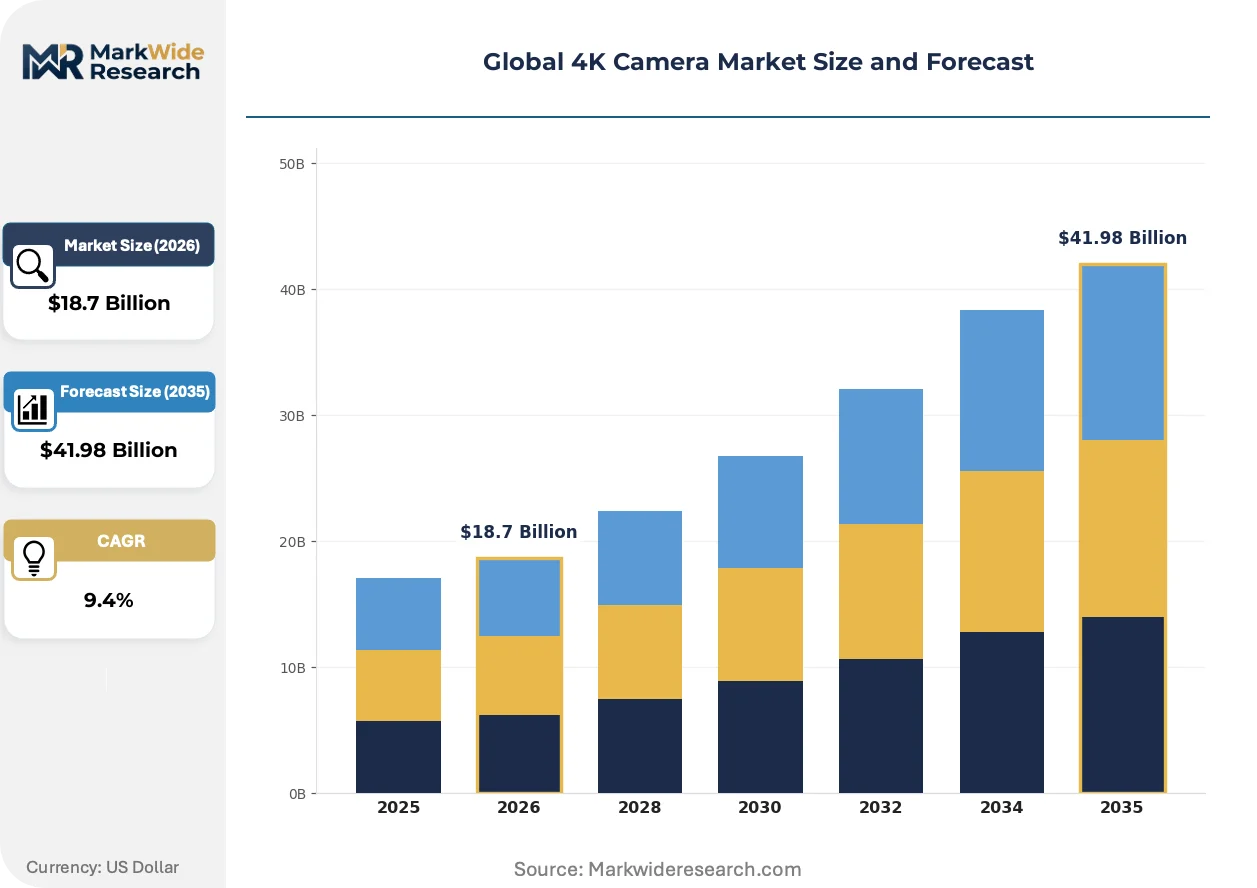
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Camera Type: DSLR, Mirrorless, Action, Camcorder End User: Professional Photographers, Content Creators, Cinematographers, Educators Technology: Digital, Analog, Hybrid, Streaming Feature: Autofocus, Waterproof, Night Vision, Stabilization |
| Companies Covered | Nikon, Blackmagic Design, Canon, Olympus, Fujifilm, Sony, GoPro, JVC, Panasonic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global 4K Camera Market Emerging Trajectories
Computational imaging pipelines and platform-driven encoding standards are compressing traditional hardware differentiation cycles while opening software-defined feature expansion paths.
Global shutter CMOS sensors with stacked readout architectures are rendering obsolete rolling-shutter artifacts in fast-motion capture. Sports broadcasters and automotive test facilities are adopting these sensors for distortion-free analysis. The technology is rendering obsolete post-production warp-stabilization workflows that previously consumed editorial hours.
China's GB standards administered by SAMR now mandate cybersecurity certification for wireless-enabled camera systems before market entry. Manufacturers must submit encryption protocols and firmware update mechanisms for audit. Professional cinema camera lines targeting Chinese rental houses and production companies are prioritizing domestic certification over simultaneous global launches.
Subscription-based firmware feature unlocking is displacing perpetual-license software sales in the prosumer segment. Camera owners in Germany and South Korea are purchasing codec upgrades and advanced autofocus algorithms through recurring payments rather than hardware refreshes. This model concentrates most visibly among mirrorless users generating platform-native content under tight equipment budgets.
Global 4K Camera Market Segmentation
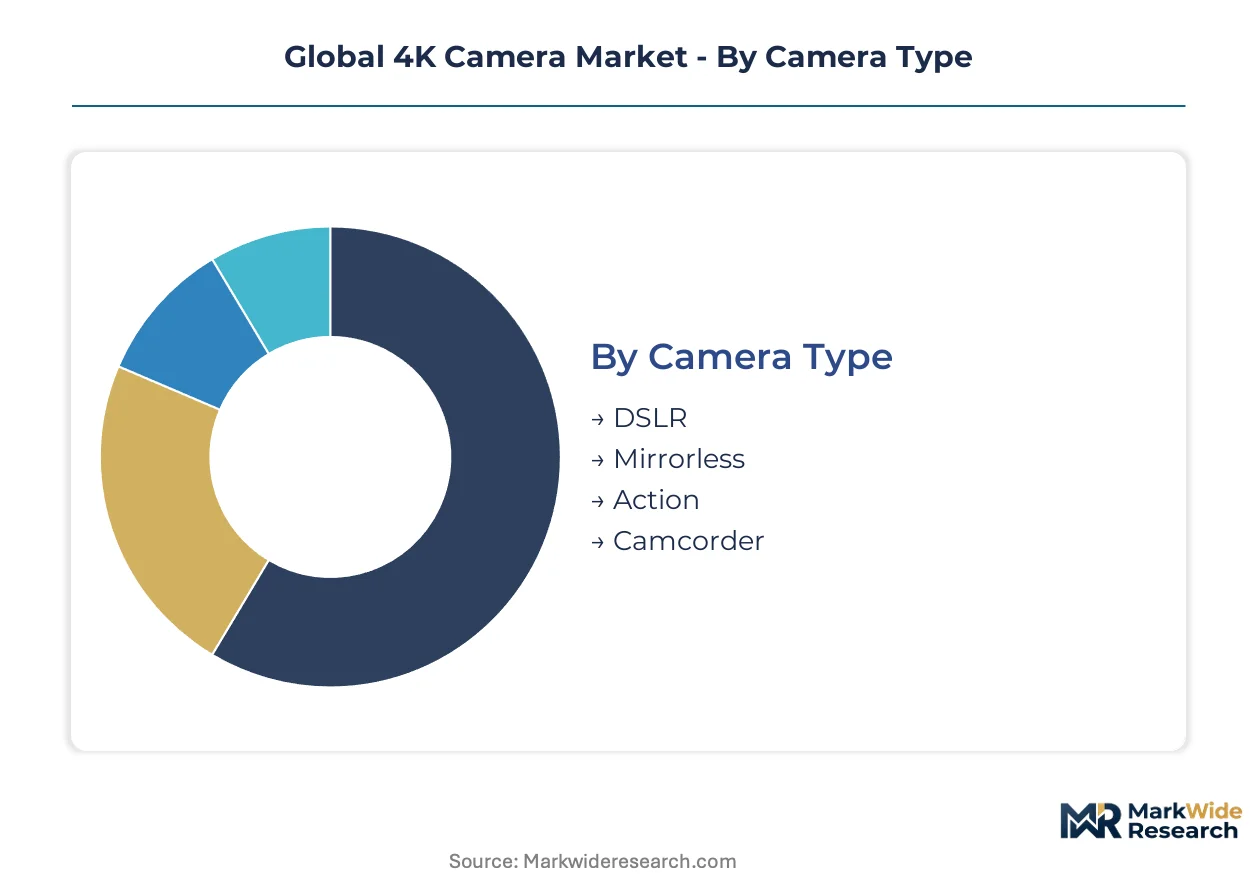
Technical specifications and user workflows diverge sharply across 4K camera categories. Sensor architecture, connectivity protocols, and feature sets determine which segments capture professional broadcast budgets versus independent creator spending.
Camera Type:
Cost tier stratification separates studio capital investments from portable field equipment and entry-level creator tools.
- Mirrorless:Compact bodies with full-frame CMOS sensors and phase-detect autofocus arrays dominate independent production. Demand concentrates among YouTube and TikTok creators in Germany and South Korea seeking shallow depth-of-field aesthetics without cinema camera bulk.
- Action:Ruggedized enclosures with electronic stabilization and waterproofing target extreme-sport documentation. Travel influencers across Southeast Asia drive volume through platform-native monetization requiring first-person perspective footage.
- DSLR:Optical viewfinder systems with established lens mount ecosystems retain wedding and event photography markets. Legacy user bases in the United States and Japan sustain replacement cycles despite mirrorless migration.
- Camcorder:Integrated zoom lenses and broadcast codec support serve ENG (electronic news gathering) workflows. Regional television networks in India and Brazil maintain fleet purchases for field reporting reliability.
Mirrorless commands the established base. The steepest expansion runs through Action.
End User:
Application intensity varies from high-frame-rate cinema production to single-operator streaming setups.
- Content Creators:Solo operators producing platform-native video require compact bodies with vertical grip ergonomics and direct streaming integration. China's Douyin and Kuaishou ecosystems generate concentrated demand for flip-screen mirrorless units.
- Cinematographers:Narrative and commercial productions demand raw codec output, log gamma profiles, and cinema lens compatibility. Los Angeles and Mumbai production houses prioritize global shutter sensors for artifact-free motion capture.
- Professional Photographers:Hybrid stills-video workflows in wedding and corporate verticals favor dual card slots and weather sealing. Tokyo studio clusters sustain medium format 4K medium format adoption for luxury product visualization.
- Educators:Universities and technical institutes procure entry-level 4K bodies for media curriculum standardization. South Korean government digital education mandates accelerate institutional purchasing.
Cinematographers anchor premium pricing. Content Creators are expanding most quickly.
Technology:
Signal processing architecture determines workflow integration and post-production flexibility.
- Digital:Pure CMOS sensor-to-processor pipelines with 10-bit 4:2:2 internal recording dominate professional acquisition. Netflix and Amazon Studios certification requirements mandate specific digital cinema camera models for original content.
- Streaming:Integrated H.264/H.265 encoders with RTMP and SRT protocol support enable direct platform ingestion. Houses of worship and corporate communications teams in the United States adopt these for simplified live production.
- Hybrid:Analog front-end with digital back-end processing serves legacy infrastructure migration. Japanese broadcasters maintain hybrid workflows during SDI-to-IP transition periods.
- Analog:Component and composite output systems persist in surveillance and industrial inspection retrofit markets. Limited to replacement demand in mature installed bases.
Digital commands the established base. Streaming shows the steepest expansion trajectory.
Feature:
Customer type priorities separate motion-capture reliability from environmental durability and low-light performance.
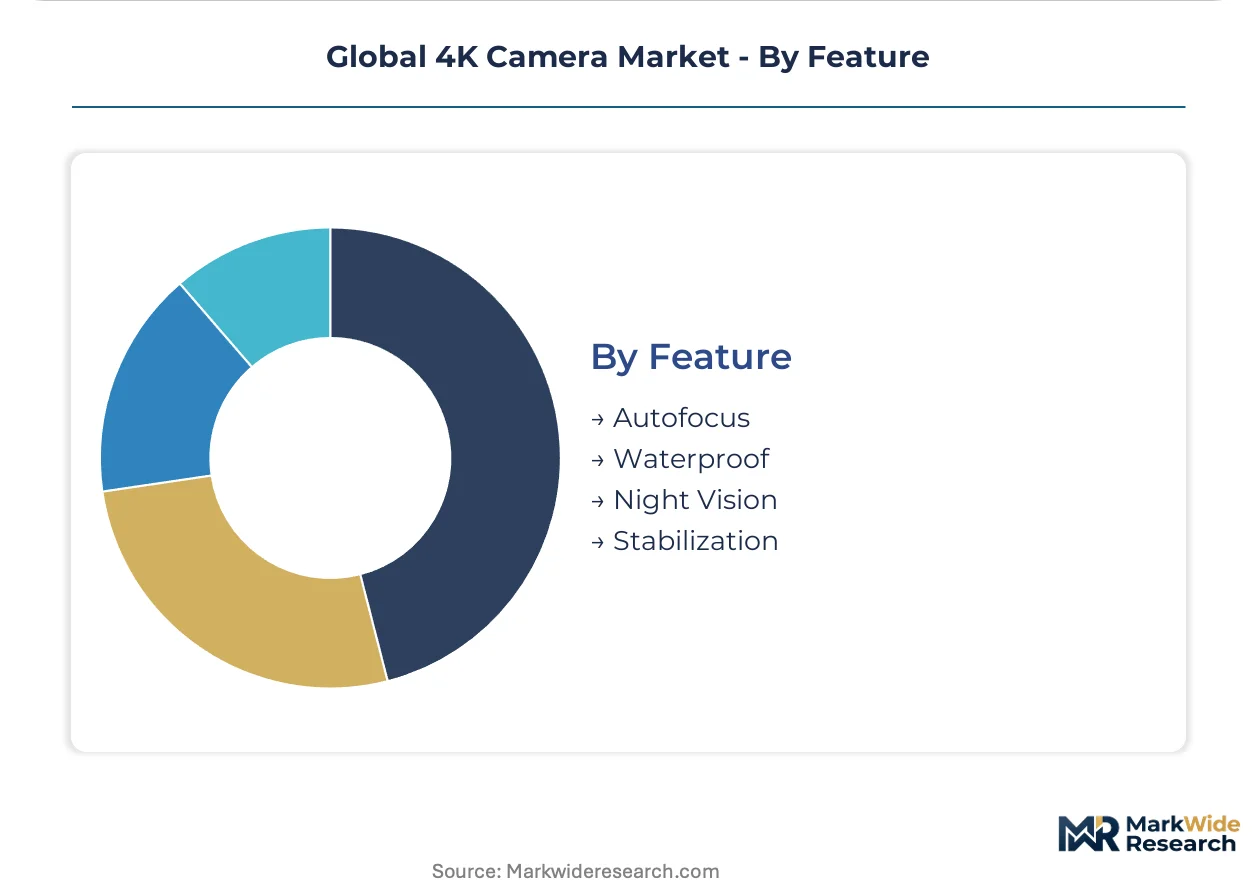
- Stabilization:Sensor-shift and lens-based optical stabilization enable handheld shooting without gimbal support. Documentary crews across East Africa and the Middle East prioritize this for run-and-gun production efficiency.
- Autofocus:Deep-learning subject recognition with eye and vehicle tracking accelerates solo operator workflows. Wildlife documentarians in Kenya and Costa Rica demand this for unpredictable subject acquisition.
- Waterproof:Sealed chassis rated to 10-meter depths without external housing expand underwater cinematography access. Marine biology researchers in Australia and the Maldives drive specialized demand.
- Night Vision:Infrared illumination and extreme ISO amplification support security and surveillance applications. Border patrol and critical infrastructure monitoring in Saudi Arabia and the UAE specify these capabilities.
Autofocus commands the established base. Stabilization gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's GB cybersecurity certification mandates and India's broadcast infrastructure modernization programs are redirecting manufacturer certification priorities and procurement patterns across major production clusters.
United States
FCC equipment authorization timelines for wireless transmission modules compress product launch windows for US-bound camera systems. The IRA's domestic manufacturing incentives are reshaping assembly location decisions for professional cinema lines. Los Angeles production houses anchor premium sensor demand for narrative and commercial workflows.
China
SAMR-administered GB standards now mandate cybersecurity audits for wireless-enabled camera systems before market entry. Domestic certification timelines are prioritizing launches for Chinese rental houses over simultaneous global releases. Shenzhen and Beijing clusters concentrate firmware engineering for platform-native streaming integration.
Japan
METI industrial policy supports precision optical glass fabrication for cinema lens elements. JIS standards govern electromagnetic compatibility in professional broadcast equipment. Tokyo studio clusters sustain demand for medium format 4K systems in luxury product visualization.
Germany
EU AI Act compliance frameworks are accelerating on-device processing architectures for connected camera systems. RoHS substance restrictions extend reliability testing cycles for lead-free solder reformulation. Munich and Stuttgart broadcast technology clusters drive ENG camcorder fleet replacements.
India
TRAI broadcast infrastructure directives and national digital expansion programs are upgrading regional sports network equipment. BIS certification requirements shape import timelines for professional acquisition systems. Mumbai production houses are expanding 4K post-production capacity for OTT platform originals.
Global 4K Camera Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered price-performance segments. The vendor base stratifies between sensor-fabrication scale leaders, cinema ecosystem incumbents, and price-aggressive workflow disruptors. Three archetypes dominate: vertically integrated optical conglomerates, software-defined camera specialists, and modular cinema rig assemblers. Competitive moves concentrate on strategic partnerships for codec licensing and geographic expansion into certified rental house networks.
Within the vertically integrated tier, Sony and Canon anchor premium supply chains through captive sensor fabrication and cinema lens ecosystems. Blackmagic Design occupies a position exemplifying price-performance disruption in digital cinema workflows. These three represent the dominant competitive anchors across professional acquisition, independent production, and streaming-native creator segments.
| Leading Market Players |
|---|
| Nikon |
| Blackmagic Design |
| Canon |
| Olympus |
| Fujifilm |
| Sony |
| GoPro |
| JVC |
| Panasonic |
| Others |
Supply Flow & Price Mechanics
Tariff exposure on precision optical glass from Japan and Germany determines both pricing tier spreads and supply chain shape in the 4K camera sector. FCC equipment authorization timelines for wireless transmission modules create six-to-nine-month launch delays that compress margins on US-bound products while pushing manufacturers toward regional certification strategies.
Pricing Analysis
Certification level creates the primary spread across professional acquisition tiers. Three-tier pricing structure across premium, standard, and economy levels separates cinema-grade bodies with raw codec output from prosumer mirrorless units and entry-level action cameras. Price differentiation hinges on sensor bit depth, global shutter architecture, and platform-native streaming integration. Cost compression in the prosumer tier is intensifying because smartphone computational photography erodes casual creator demand. Independent YouTube operators in Germany and South Korea exhibit highest price sensitivity, while Los Angeles production houses prioritize performance over unit cost.
Supply Chain Analysis
Export-control restrictions on advanced CMOS sensor fabrication equipment limit technology flows to Chinese foundries. Sensor production concentrates in Japan, South Korea, and Taiwan, while precision optical glass draws from concentrated Japanese and German manufacturers. Raw material dependencies include rare-earth elements for sensor coatings, specialized optical glass for cinema lenses, and lithium-ion battery cells. Single-source vulnerability in Japanese optical glass suppliers threatens lens element availability for premium cinema lines. Distribution runs through certified rental house networks in Mumbai, Los Angeles, and Beijing, with direct-to-creator e-commerce gaining share in the action camera segment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform-economics logic now governs hardware value capture as subscription-based firmware unlocking displaces perpetual-license sales. Interoperability with cloud-native live production workflows is rewriting competitive moats around software-defined feature expansion rather than sensor specifications alone.
For Market Incumbents: Entrench sensor-fabrication scale advantages through captive supply of stacked readout architectures. Defend against Blackmagic Design's price-performance disruption by bundling cinema lens ecosystem access with body purchases. Prioritize certification investment for China's GB cybersecurity mandates to secure rental house fleet orders in Shenzhen and Beijing.
For New Entrants and Emerging Players: Establish a beachhead in India's broadcast infrastructure modernization programs. Target regional sports networks upgrading studio equipment under TRAI directives as the most penetrable vertical. Pursue cloud-native encoding partnerships as the primary go-to-market angle, eliminating local storage hardware requirements for remote production teams.
For Investors and Strategic Acquirers: EU AI Act compliance deadlines reshape the acquisition landscape toward on-device processing specialists. Long-term viability centers on sensor-to-edge architecture capabilities rather than traditional optical engineering. Target acquisition archetypes include firmware engineering teams with cybersecurity certification expertise. Watch cloud-native live production workflow adoption rates as the signal for inflection in hardware-software value distribution.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Direct streaming ingestion via RTMP and SRT protocols locks in creator ecosystem loyalty. |
| Geographic Expansion | Domestic certification for China's SAMR-administered GB standards prioritizes local rental house demand. |
| Acquisition of Specialist Firm | Advanced LUT development teams in Tokyo and Los Angeles concentrate scarce color science talent. |
| Product Launch | Global shutter CMOS sensors eliminate rolling-shutter artifacts for sports broadcasters and automotive test facilities. |
| Strategic Partnership | Codec licensing agreements with Netflix and Amazon Studios secure certification for original content acquisition. |
Methodological Framework
A standing panel of cinematography rental house managers, broadcast technology procurement leads, platform encoding engineers, and independent content creators provided ongoing calibration across the study period. Primary interviews with these stakeholders combined with secondary validation from FCC equipment authorization filings, SAMR GB standards documentation, EU AI Act compliance guidance, and streaming platform technical requirement disclosures. Bottom-up demand modeling across camera type, end user, technology, and feature segments triangulated against top-down market sizing from foundry capacity and trade flow data.
Scenario-bracketing around CMOS sensor fabrication capacity expansion, regulatory certification timeline compression, and platform bitrate mandate evolution anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include camera type, end user application intensity, signal processing architecture, and motion-capture reliability features. CAGRs derived from unit economics trajectories in 10-bit color depth modules and platform-native streaming integration adoption curves. Forecast inputs incorporated wireless transmission module certification delays and cloud-native live production workflow penetration rates.
Stress conditions across FCC authorization timelines, EU AI Act compliance cost burdens, and smartphone computational photography substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding foundry capacity allocation and platform encoding standard stability. Material shifts in China's GB cybersecurity certification requirements or India's broadcast infrastructure procurement acceleration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Infrared Imaging Market
Imaging
Global Microbolometer Market
Imaging
India CCTV Camera Market
Imaging
Middle East and Africa Image Sensors Market
Imaging
Handheld Imaging Devices Market
Imaging
Small CCTV Camera Market
Imaging
Europe CT Market
Imaging
Multimodal Imaging Market
Imaging
US Near Infrared Imaging Market
Imaging
Compact Camera Module Market
Imaging
Hybrid Imaging Systems Market
Imaging
Global Phosphor Plate Scanners Market
Imaging
Camera Lens Market
Imaging
Industrial Machine Vision Market
Imaging
PET Scanners Market
Imaging
360-Degree Camera Market