
 Calcium-Fortified Cereals Market | 2026-2036
Calcium-Fortified Cereals Market Size, Share, and Industry Trends Forecast 2026-2036
Calcium-Fortified Cereals Market Analytics
The EU Green Deal's sustainable food system targets is pivoting calcium-fortified cereal demand toward cleaner-label formulations with traceable mineral sourcing. General Mills Inc. leverages its North American manufacturing scale to dominate mainstream retail shelf space. Nestlé S.A. anchors its portfolio in pediatric and senior nutrition science, competing on clinical credibility. Kellogg Company differentiates through dual-fortification platforms that combine calcium with vitamin D in single-serve formats.
Calcium-fortified cereals are grain-based breakfast products engineered with added calcium carbonate or tri-calcium phosphate, typically delivering 10-25% of daily recommended mineral intake per serving through extrusion or coating processes designed to preserve bioavailability during shelf-stable storage. Wheat-based variants occupy the premium tier due to higher protein-calcium synergy and established consumer familiarity in Western diets. Online Retail channels represent the fastest-expanding distribution vector, though Supermarkets still control the majority of volume through promotional bundling with dairy alternatives.
FDA nutrition labeling mandates and EFSA health claim protocols jointly determine which calcium fortification levels qualify for bone-health marketing, creating divergent compliance burdens for multinational versus regional producers. The EU F-Gas Regulation indirectly pressures processing equipment choices, while India's FSSAI fortification standards for staple foods signal emerging export formulation requirements. Stakeholders must monitor evolving bioavailability testing methodologies and preemptive regulatory harmonization between major import jurisdictions.
Market Dynamics
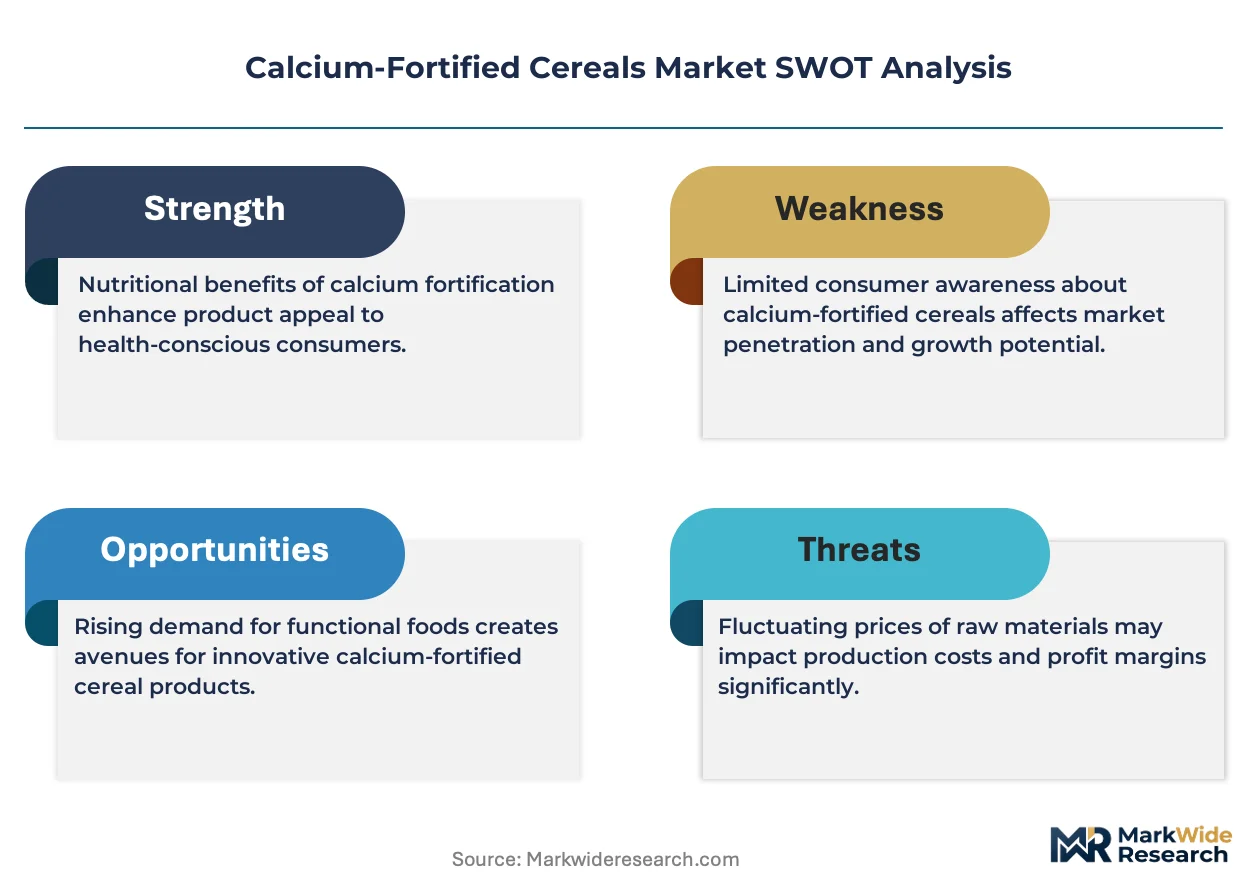
The calcium-fortified cereals sector is restructuring around the FDA's updated nutrition labeling mandates, which are forcing manufacturers to recalibrate fortification levels and bioavailability claims while simultaneously opening pathways for clinical-positioned products.
Growth Catalysts
- Preventive Nutrition Among Aging Populations:The United States and Germany are witnessing concentrated demand from consumers over 55 seeking bone-density maintenance through dietary intervention, converting breakfast cereals into functional health platforms.
- EFSA Health Claim Protocols:Europe's scientific substantiation requirements for calcium-bone health marketing are elevating clinical credibility standards, rewarding manufacturers with robust clinical data portfolios and filtering out unsubstantiated fortification claims.
- Extrusion Technology Advancements:Precision thermal processing is preserving calcium carbonate bioavailability through shelf-stable storage cycles, enabling higher fortification payloads without sensory degradation or mineral precipitation.
Market Restraints
- Input Cost Volatility in Mineral Supply:Pharmaceutical-grade calcium carbonate pricing fluctuates with limestone quarry capacity constraints in Vietnam and Egypt, squeezing margin structures for mid-tier producers without long-term offtake agreements.
- Regulatory Fragmentation Between Jurisdictions:Divergent FDA and EFSA fortification ceilings create formulation complexity, forcing multinational manufacturers to maintain parallel production lines or accept lowest-common-denominator fortification levels.
- Plant-Based Milk Substitution Threat:Oat and almond milk alternatives with native or added calcium are capturing breakfast occasions previously dominated by cereal-plus-dairy combinations, compressing the addressable fortified cereal occasion.
Strategic Opportunities
- India's FSSAI Staple Fortification Mandate:The national food regulator's expanding fortification standards for rice and wheat create export formulation precedents that calcium-fortified cereal manufacturers can leverage for early-mover positioning in emerging Asian markets.
- Pediatric Clinical Nutrition Positioning:Breakfast cereals engineered for bone development windows in children aged 4-12 represent an underserved application segment with premium pricing potential and caregiver-driven purchase authority.
- Direct-to-Consumer Subscription Channels:Online retail platforms with personalized nutrition algorithms are enabling micronutrient customization at scale, bypassing supermarket slotting fee barriers and capturing recurring revenue streams.
Industry Challenges
- Bioavailability Testing Talent Scarcity:Isotope tracer studies and serum calcium response validation require specialized food science and clinical research capabilities that concentrate in academic institutions and contract research organizations, creating recruitment bottlenecks.
- Dual-Fortification Formulation Complexity:Combining calcium with vitamin D or vitamin K2 in stable matrices demands precise moisture control and packaging engineering, extending product development timelines and increasing capex requirements for pilot-scale testing facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Calcium-Fortified Cereals Market |
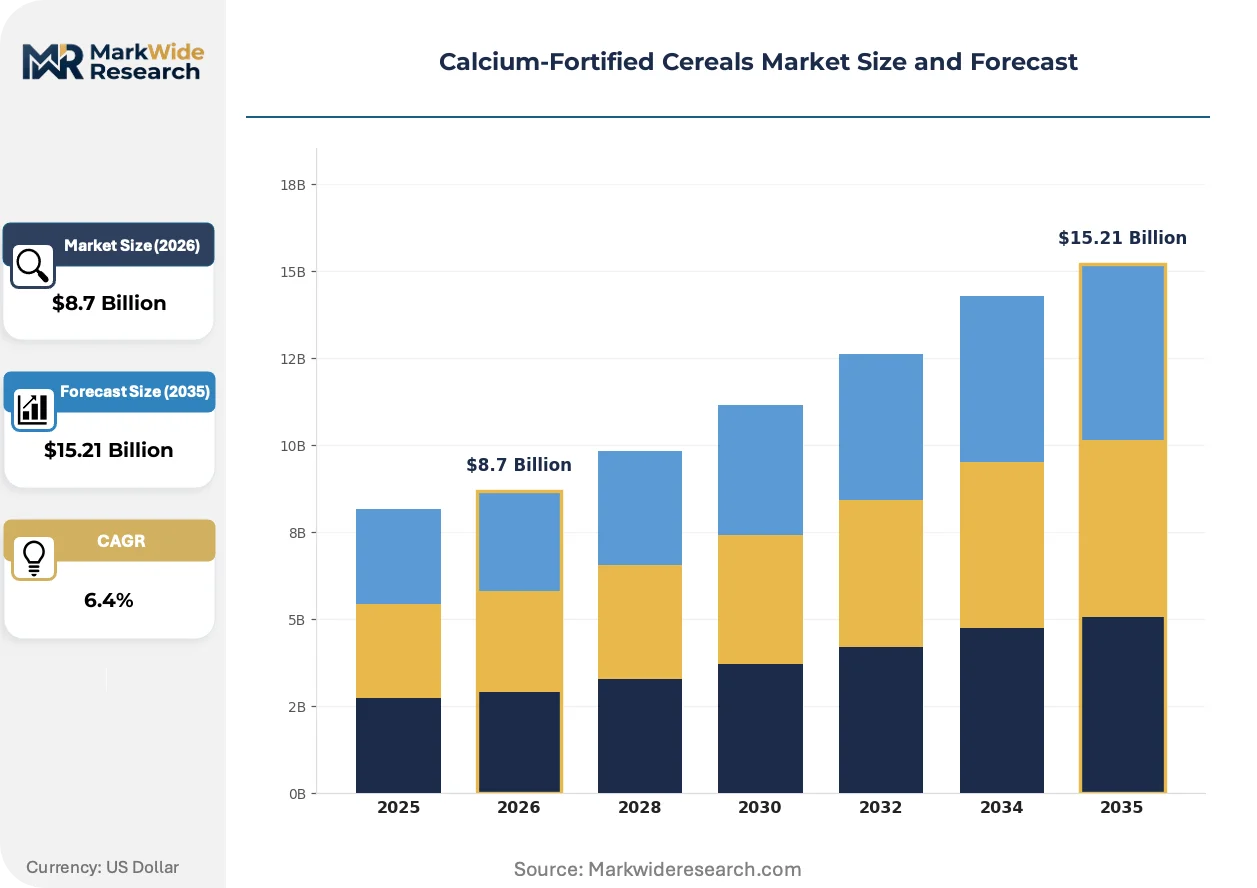
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oat, Corn, Wheat, Rice Target Consumer: Children, Adults, Seniors, Athletes Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Health Food Stores Flavor Profile: Chocolate, Vanilla, Fruity, Nutty |
| Companies Covered | General Mills Inc., Kellogg Company, Nestlé S.A., PepsiCo Inc., Conagra Brands Inc., Post Holdings Inc., Bob’s Red Mill Natural Foods, Danone, Arla Foods amba, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Calcium-Fortified Cereals Market Evolving Landscape
Calcium-fortified cereal innovation is converging on bioavailability verification, clean-label mineral sourcing transparency, and personalized fortification architectures that shift competitive advantage from marketing claims to measurable physiological outcomes.
Microencapsulation technology using lipid-shell calcium carbonate is modularizing fortification delivery systems, enabling time-release mineral absorption that mimics dairy matrix effects. Pediatric and senior nutrition segments are adopting these platforms fastest, seeking to overcome the calcium-iron absorption interference that limits traditional fortification efficacy. This modularization is compressing the advantage window of conventional spray-dried mineral coatings and forcing R&D investment toward pharmaceutical-grade delivery science.
The EU F-Gas Regulation is phasing down hydrofluorocarbon-based refrigeration in cereal processing facilities, indirectly pressuring extrusion equipment manufacturers to redesign thermal management systems. European production lines are retrofitting with ammonia or CO2-based cooling architectures, adding capital intensity but future-proofing compliance positions. Wheat-based premium variants with temperature-sensitive protein-calcium matrices are most affected, as their processing windows demand precise thermal control.
Consumer verification behavior is reshaping purchase patterns, with buyers cross-referencing calcium content claims against third-party bioavailability databases and demanding traceable mineral sourcing from named quarry operations. Subscription-based direct channels are capturing this verification-oriented segment through blockchain-anchored supply chain documentation, displacing traditional retail's opacity. Germany and the Netherlands exhibit the highest concentration of this behavior, where digital literacy and preventive health expenditure intersect.
Calcium-Fortified Cereals Market Segmentation
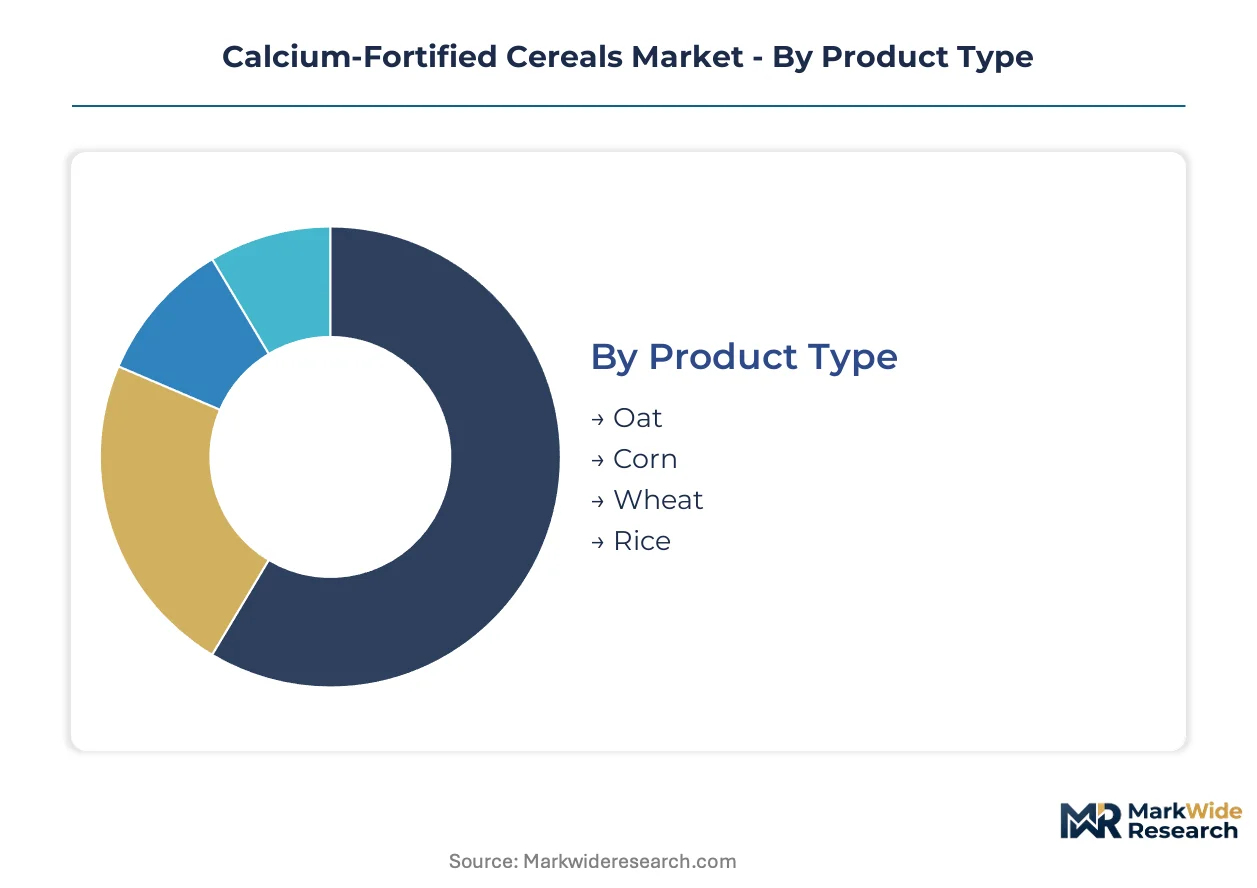
Calcium-fortified cereals segment along nutritional density, sensory preference, and purchase occasion dimensions that determine formulation architecture and channel strategy. Manufacturers calibrate mineral payloads and flavor systems to match distinct consumer life stages and retail environments.
Product Type:
The customization-standardization spectrum in grain bases spans from commodity corn platforms to protein-optimized wheat matrices requiring precision thermal control.
- Wheat:Higher protein-calcium synergy and established Western dietary familiarity position wheat variants in premium tiers. Demand concentrates in Germany and the United States among aging consumers seeking bone-density maintenance through preventive breakfast nutrition.
- Oat:Beta-glucan fiber matrices enhance calcium absorption kinetics while appealing to clean-label seekers. Scandinavian markets and Pacific Northwest urban clusters drive adoption, with consumers cross-referencing fortification claims against third-party bioavailability databases.
- Corn:Cost-optimized extrusion base for mass-market penetration with standardized fortification protocols.
- Rice:Hypoallergenic positioning for pediatric and sensitivity-driven applications in Asian export formulations.
Leading the category by volume: Corn. Growing fastest: Oat.
Target Consumer:
Life-stage segmentation correlates directly with mineral payload requirements, packaging formats, and clinical credibility thresholds.
- Seniors:Bone-density maintenance positioning requires EFSA-substantiated health claims and higher per-serving calcium percentages. Germany and Japan exhibit concentrated demand from consumers over 55 converting breakfast into functional health intervention.
- Children:Pediatric bone development windows demand palatability engineering alongside bioavailability preservation. Caregiver-driven purchase authority in North American households supports premium pricing for clinical-credible formulations.
- Adults:Convenience-oriented standard fortification for routine preventive nutrition without clinical positioning.
- Athletes:Performance recovery framing with electrolyte-calcium synergy for post-training consumption occasions.
Seniors command the highest per-unit margins. Children represent the steepest expansion trajectory.
Distribution Channel:
Channel selection determines packaging architecture, promotional mechanics, and supply chain temperature requirements.
- Online Retail:Subscription algorithms enable micronutrient customization at scale, bypassing supermarket slotting fees. Netherlands and German digital-native consumers drive fastest channel expansion through blockchain-anchored supply chain verification.
- Supermarkets:Promotional bundling with dairy alternatives controls majority volume despite compressing margins. United States retail consolidation limits shelf access for regional producers without national distribution scale.
- Health Food Stores:Clinical credibility and traceable mineral sourcing command premium positioning in specialty retail.
- Convenience Stores:Single-serve portability for grab-and-go breakfast occasions in urban commuter corridors.
Supermarkets retain volume leadership. Online Retail is gaining share fastest.
Flavor Profile:
Sensory engineering must mask mineral off-notes while delivering repeat purchase triggers across demographic segments.
- Chocolate:Cocoa polyphenols provide antioxidant co-positioning with calcium fortification in pediatric and adult indulgence segments. Formulation complexity centers on pH stability to prevent mineral precipitation in milk-reconstituted applications.
- Fruity:Acidic fruit matrices demand encapsulation technology to preserve carbonate bioavailability through shelf-stable storage. Southeast Asian export markets favor tropical fruit profiles for localization strategies.
- Vanilla:Neutral carrier for dual-fortification with vitamin D in clinical-positioned senior nutrition.
- Nutty:Protein-calcium synergy appeals to athletic and clean-label segments with premium ingredient transparency.
Chocolate dominates absolute volume. Nutty profiles climb the fastest among verification-oriented consumer clusters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chicago anchors North American calcium-fortified cereal manufacturing through its Midwest grain processing corridor and CPG headquarters concentration. Demand patterns diverge sharply across regulatory environments, with FDA labeling mandates in the United States, EFSA health claim protocols in Europe, and FSSAI fortification standards in India creating distinct formulation requirements.
United States
Aging demographics in Florida and Arizona drive preventive nutrition demand among consumers over 55 seeking bone-density maintenance through breakfast intervention. FDA updated nutrition labeling requirements force recalibration of fortification levels and bioavailability claims, filtering out unsubstantiated marketing. Minneapolis-St. Paul hosts General Mills and Post Holdings headquarters, concentrating R&D investment in clinical-positioned senior nutrition platforms.
Germany
Digital-native consumers in Berlin and Hamburg cross-reference calcium content against third-party bioavailability databases, demanding traceable mineral sourcing from named quarry operations. EFSA scientific substantiation requirements for bone-health marketing elevate clinical credibility thresholds, rewarding manufacturers with robust data portfolios. The Rhine-Ruhr industrial corridor hosts precision extrusion equipment manufacturers retrofitting for EU F-Gas Regulation compliance.
India
FSSAI expanding fortification standards for rice and wheat create export formulation precedents for early-mover cereal positioning in emerging Asian markets. Caregiver-driven purchase authority in Mumbai and Delhi NCR households supports premium pricing for pediatric bone development formulations. Gujarat and Maharashtra processing clusters adapt pharmaceutical-grade calcium carbonate supply chains originally established for generic drug manufacturing.
Netherlands
Subscription algorithm adoption concentrates in Amsterdam and Rotterdam, enabling micronutrient customization at scale through blockchain-anchored supply chain verification. EU Green Deal sustainable food system targets pivot demand toward cleaner-label formulations with traceable mineral sourcing. Wageningen University bioavailability research partnerships attract contract validation studies for isotope tracer methodologies.
Japan
Consumers over 55 in Tokyo and Osaka convert breakfast cereals into functional health intervention platforms for osteoporosis prevention. METI standards for functional food claims require clinical trial substantiation, creating barriers for unsubstantiated fortification entrants. The Kansai region hosts precision thermal processing equipment manufacturers serving pharmaceutical-grade mineral delivery requirements.
Calcium-Fortified Cereals Market Competitive Landscape
The competitive structure tilts toward multinational CPG conglomerates with North American manufacturing scale and clinical nutrition science portfolios. Three tiers emerge: global breakfast cereal majors leveraging retail shelf space dominance, dairy-nutrition hybrids with pediatric and senior credibility, and clean-label specialists capturing verification-oriented digital-native segments. Dominant competitive moves include dual-fortification platform development combining calcium with vitamin D or K2, and direct-to-consumer subscription channel bypass of supermarket slotting fees.
Among North American CPG conglomerates, General Mills Inc., Kellogg Company, and Nestlé S.A. occupy positions that exemplify divergent strategic archetypes. General Mills represents manufacturing scale leverage through mainstream retail penetration. Kellogg exemplifies dual-fortification platform specialization in single-serve formats. Nestlé anchors clinical credibility positioning in pediatric and senior nutrition science. These three entities collectively illustrate how multinational producers navigate divergent FDA and EFSA regulatory ceilings through parallel production line maintenance or lowest-common-denominator fortification acceptance.
| Leading Market Players |
|---|
| General Mills Inc. |
| Kellogg Company |
| Nestlé S.A. |
| PepsiCo Inc. |
| Conagra Brands Inc. |
| Post Holdings Inc. |
| Bob's Red Mill Natural Foods |
| Danone |
| Arla Foods amba |
| Others |
Value Network & Pricing Analysis
The EU F-Gas Regulation gates qualified supply and premium-tier pricing access by forcing extrusion equipment retrofits that concentrate compliant capacity among capitalized multinationals. Pharmaceutical-grade calcium carbonate sourcing from Vietnam and Egypt limestone quarries creates tiered input cost structures that propagate through finished product pricing.
Pricing Analysis
Value-based pricing anchored to bioavailability outcomes separates clinical-credible formulations from commodity fortification. Three-tier pricing structure across premium, standard, and economy levels stratifies by EFSA health claim substantiation and mineral sourcing transparency. Pricing pressure stems from pharmaceutical-grade calcium carbonate volatility and plant-based milk substitution compressing breakfast occasions. Price-sensitive mass-market corn variants face margin compression while premium wheat and oat segments absorb cost pass-through.
Supply Chain Analysis
Certification gating through FDA nutrition labeling and EFSA health claim protocols concentrates qualified supply among multinationals with parallel production line capacity. Raw material dependencies center on pharmaceutical-grade calcium carbonate from Vietnam and Egypt, beta-glucan oat fiber from Scandinavia, and precision extrusion equipment from Germany and Japan. Single-source vulnerability in limestone quarry capacity creates input cost volatility. Distribution runs through supermarket promotional bundling with dairy alternatives, though direct-to-consumer subscription channels bypass slotting fee barriers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where FDA updated nutrition labeling requirements create a barrier-to-entry moat that filters out unsubstantiated fortification claims and rewards clinical data investment.
For Market Incumbents: Hedge mineral input volatility through long-term offtake agreements with Vietnamese and Egyptian limestone quarry operators. Backward integration into pharmaceutical-grade calcium carbonate processing secures margin stability against mid-tier competitors lacking procurement scale. Defend shelf position by accelerating dual-fortification platform development combining calcium with vitamin D before patent-thinning erodes differentiation. For New Entrants and Emerging Players: Launch via direct-to-consumer subscription algorithms with blockchain-anchored mineral sourcing verification targeting Netherlands and German digital-native consumers. India's FSSAI staple fortification mandate expansion creates white-space positioning for export-formulation early movers in emerging Asian markets. Pediatric bone development cereals for children aged 4-12 offer premium pricing with caregiver-driven purchase authority. For Investors and Strategic Acquirers: FDA enforcement actions against unsubstantiated bioavailability claims are the leading indicator that clinical-credible portfolios will consolidate market share. Acquisition targets should concentrate on contract research organizations with isotope tracer study capabilities and regional producers with FSSAI-compliant formulations for Asian export. Long-term viability favors entities with dual-fortification R&D pipelines and DTC channel infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Fortification Platform Development | Combining calcium with vitamin D in stable matrices captures EFSA-substantiated bone-health positioning. |
| Direct-to-Consumer Subscription Launch | Blockchain-anchored supply chain documentation bypasses supermarket slotting fees in Netherlands and Germany. |
| Pharmaceutical-Grade Mineral Sourcing Integration | Backward integration into calcium carbonate processing hedges Vietnam and Egypt quarry capacity constraints. |
| Pediatric Clinical Nutrition Positioning | Bone development formulations for children aged 4-12 unlock premium pricing with caregiver purchase authority. |
| EU F-Gas Compliance Retrofit | Ammonia and CO2-based cooling architectures future-proof European production lines against regulatory phase-down. |
Research Methodology
Trade databases, regulatory filings, and clinical trial registries formed the secondary backbone, supplemented by customs records and food industry association reports. Primary interviews with R&D directors at cereal manufacturers, procurement leads at calcium carbonate suppliers, category buyers at supermarket chains, and regulatory affairs specialists at multinational CPGs validated demand assumptions. Bottom-up and top-down triangulation cross-checked volume estimates against mineral input consumption and retail scan data.
Bottom-up modeling built from product-level fortification specifications, manufacturing capacity utilization, and channel-specific pricing tiers across wheat, oat, corn, and rice grain bases. Top-down analysis calibrated aggregate market size against preventive nutrition expenditure trends in aging populations. Segmentation dimensions included grain base type, target consumer life stage, distribution channel, and flavor profile. CAGRs derived from regression analysis of historical fortified food adoption curves and regulatory enforcement intensity.
Regulatory harmonization failures, limestone quarry capacity disruptions, and plant-based milk substitution acceleration are the dominant revision risks. Forecasts embed assumptions about EFSA health claim substantiation timelines and FDA labeling enforcement consistency. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vitamin Fortified
Fortified Beverages Market
Vitamin Fortified
North America Vitamin Fortified and Mineral Enriched Food and Beverages Market
Vitamin Fortified
Natural Vitamins Market
Vitamin Fortified
Feed Vitamins Market
Vitamin Fortified
Essential Micronutrients Market
Vitamin Fortified
North America Food Fortifying Agents Market
Vitamin Fortified
Beta Carotene Market
Vitamin Fortified
Vitamin D Market
Vitamin Fortified
Europe Feed Vitamins Market
Vitamin Fortified
Global Vitamins Market
Vitamin Fortified
Esterified Vitamins Market
Vitamin Fortified
Calcium-Fortified Bread Market
Vitamin Fortified
Food Fortifying Agents Market
Vitamin Fortified
Vitamin Premix Market
Vitamin Fortified
North America Vitamin D Market
Vitamin Fortified
Vitamin Fortified and Mineral Enriched Food & Beverage Market