
 Prenatal Vitamin Preparation Market | 2026-2036
Prenatal Vitamin Preparation Market Size, Share, and Industry Trends Forecast 2026-2036
Prenatal Vitamin Preparation Market Analytics
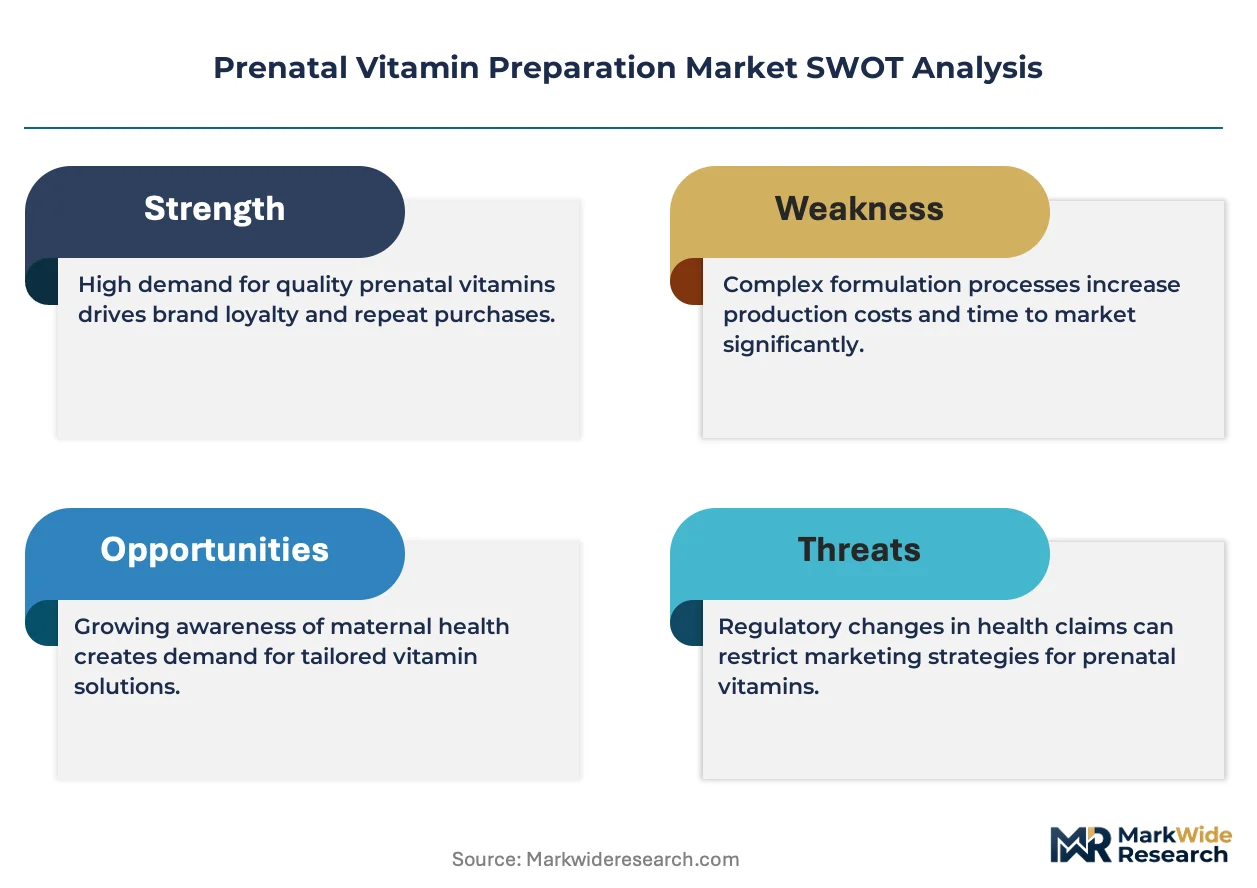
Subscription-based prenatal vitamin replenishment is hardening into a core revenue layer as brands bundle personalized trimester dosing with telehealth consultations. Bayer AG leverages its pharmaceutical heritage to anchor premium positioning in pharmacy channels. Garden of Life differentiates through organic and Non-GMO formulation certifications that command shelf space in health stores. Abbott Laboratories extends its clinical credibility by supplying healthcare professional recommendation networks.
Prenatal vitamin preparations are multicomponent dietary supplements containing folic acid, iron, calcium, DHA, and vitamin D3, manufactured through wet granulation and softgel encapsulation to ensure bioavailability during gestation and lactation. The tablets segment dominates unit volume due to cost-efficient manufacturing and extended shelf stability, while gummies are capturing fastest growth among nausea-sensitive consumers in online retail channels. Organic and vegan formulations concentrate margin pools as clean-label premiums offset higher raw material costs from plant-derived DHA and chelated minerals.
FDA oversight of dietary supplement Good Manufacturing Practices and EMA nutrition and health claims regulation shape product labeling, substantiation requirements, and cross-border market access for prenatal formulations. The EU Green Deal chemical sustainability targets and REACH compliance are forcing reformulation of coating agents and excipients in European production. Stakeholders must monitor evolving pharmacovigilance reporting obligations for adverse event thresholds that could reclassify certain prenatal SKUs as medicinal products rather than supplements.
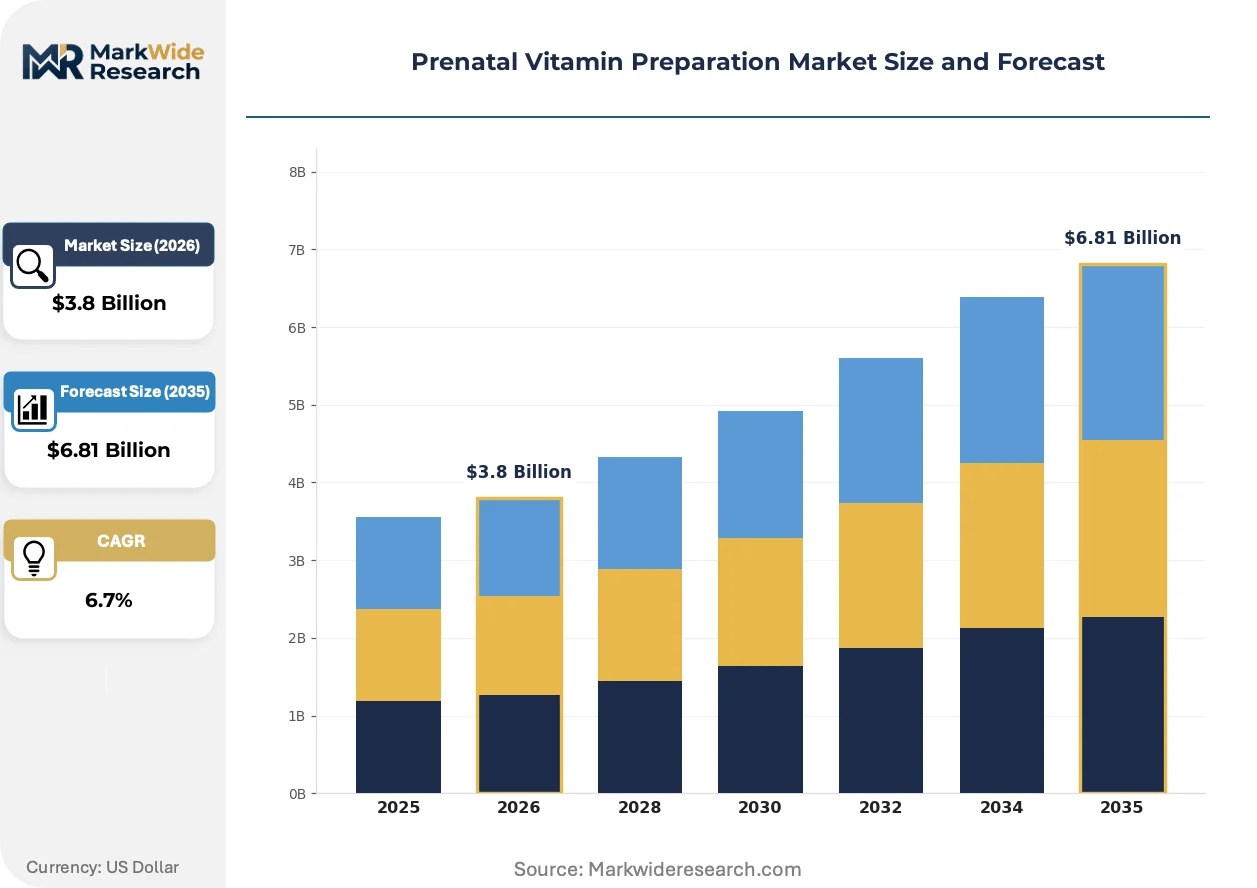
Market Dynamics
Direct-to-consumer subscription models are compressing traditional pharmacy distribution layers, while tightening FDA and EMA folic acid fortification standards force reformulation cycles that favor manufacturers with captive analytical capabilities.
Growth Catalysts
- Telehealth bundling:Virtual prenatal consultation platforms in the United States are integrating vitamin replenishment into care protocols, creating embedded purchase triggers at trimester transitions.
- REACH chemical sustainability targets:EU Green Deal compliance deadlines are accelerating excipient substitution toward plant-derived coating agents that command clean-label premiums.
- Iron deficiency screening mandates:Germany's maternal health programs are expanding reimbursable prenatal supplement categories through statutory health insurance frameworks.
Market Restraints
- Algal DHA supply concentration:Single-source dependency on marine biotechnology suppliers in coastal China creates raw material vulnerability during harvest season volatility.
- Chelated mineral cost premiums:Bisglycinate iron and calcium citrate malate formulations carry 40-60% higher input costs versus inorganic salts, compressing margin at economy price tiers.
- FDA adverse event thresholds:Pharmacovigilance reporting obligations for prenatal formulations with therapeutic-level folic acid create reclassification risk to prescription drug status.
Strategic Opportunities
- Postpartum extension formulations:Lactation-stage vitamin complexes with galactagogue botanicals address the twelve-month nutritional gap following delivery in underpenetrated segments.
- SAMR cross-border e-commerce channels:China's pilot zones for imported health products are reducing registration timelines for foreign prenatal brands with existing FDA or EMA dossiers.
- Personalized micronutrient dosing:Pharmacogenomic testing integration enables trimester-specific folate and B12 adjustments based on MTHFR variant analysis.
Industry Challenges
- Analytical method transfer gaps:Third-party contract laboratories lack validated protocols for simultaneous quantification of fat-soluble and water-soluble vitamins in complex matrices.
- Legacy ERP integration friction:Subscription commerce platforms require real-time inventory synchronization with batch-level traceability systems designed for wholesale pharmaceutical distribution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Prenatal Vitamin Preparation Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Softgels, Gummies, Powders Formulation: Organic, Non-GMO, Vegan, Conventional Distribution Channel: Online Retail, Pharmacies, Supermarkets, Health Stores Target Audience: Pregnant Women, Expecting Couples, Healthcare Professionals, Postpartum Mothers |
| Companies Covered | Nature Made, Bayer AG, Abbott Laboratories, Vitabiotics, Garden of Life, Church & Dwight Co., Inc., Blackmores, Swisse, MegaFood, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Prenatal Vitamin Preparation Market Evolving Landscape
Formulation science and distribution architecture are converging to address nausea tolerance, bioavailability optimization, and direct-channel fulfillment expectations that traditional tablet manufacturing was not designed to serve.
Liposomal encapsulation technology is integrating fat-soluble vitamins D3, E, and K2 into phospholipid bilayers that bypass first-pass hepatic metabolism. Nausea-sensitive consumers in the first trimester are adopting these formats at accelerating rates through online channels. This delivery mechanism is integrating premium positioning into subscription bundles that displace standard tablet regimens.
EMA nutrition and health claims regulation is tightening substantiation requirements for folate-related neural tube defect prevention statements. Manufacturers must now maintain prospective clinical trial data or systematic review documentation to retain permissible claims on packaging and marketing materials. Softgel and gummy formats with modified release profiles are most affected, as their excipient matrices complicate bioequivalence demonstrations.
Expecting couples are consolidating vitamin purchases into trimester-curated subscription boxes that bundle prenatal, DHA, and probiotic SKUs with gestational age tracking apps. Direct-to-consumer brands are displacing pharmacy shelf selection with personalized dosing reminders and auto-replenishment algorithms. This behavioral shift concentrates in United States metropolitan markets with high digital health adoption rates and employer-sponsored fertility benefits.
Prenatal Vitamin Preparation Market Segmentation
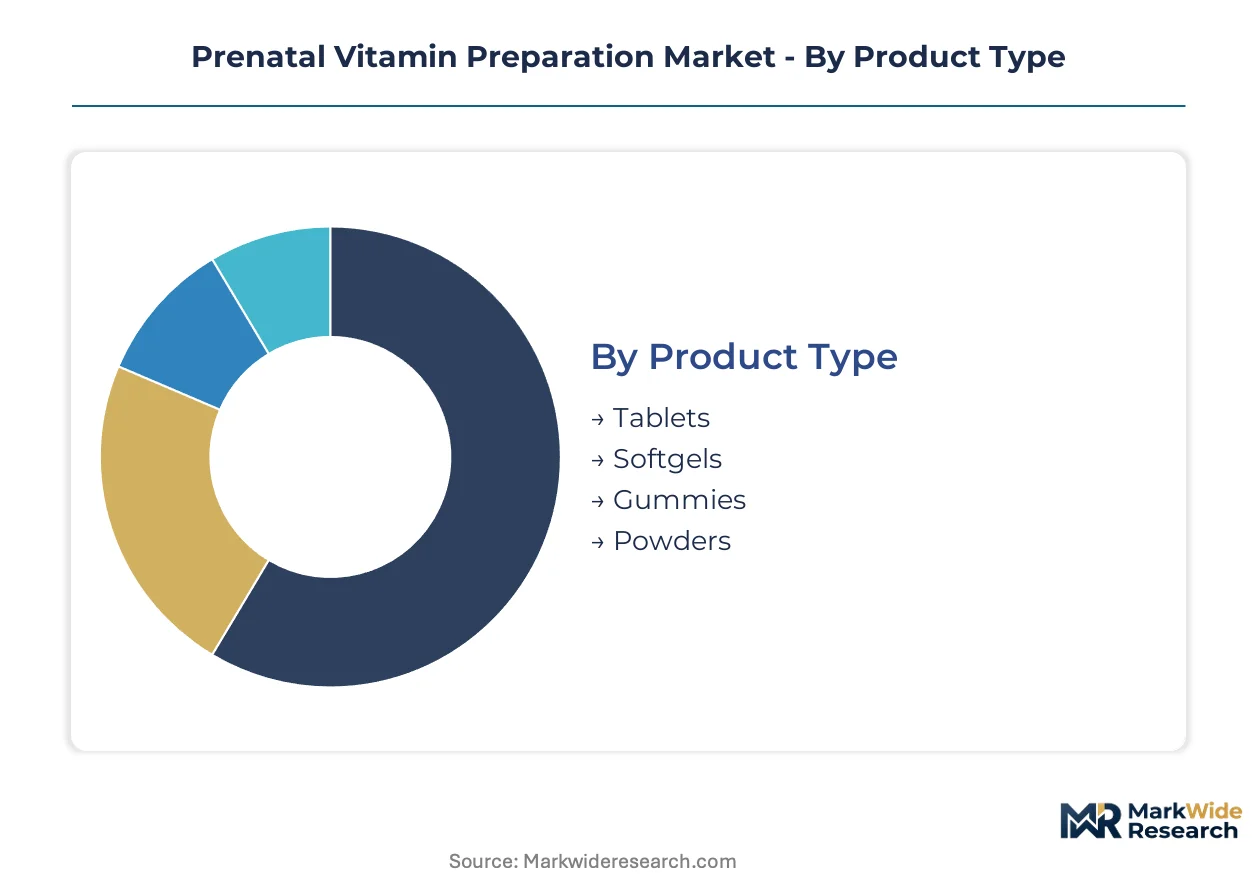
Prenatal vitamin preparation markets fragment across formulation technologies, distribution architectures, and consumer readiness to pay for certification premiums. Segmentation discipline reveals where capital deployment generates durable returns versus commodity exposure.
Product Type:
Capital intensity escalates sharply from conventional tablet presses through specialized softgel encapsulation lines to precision gummy deposition systems requiring climate-controlled environments.
- Tablets:Wet granulation and direct compression equipment dominate installed manufacturing bases, with extended shelf stability supporting pharmacy channel replenishment cycles in Germany and the United States. Cost-efficient unit economics sustain economy-tier positioning despite slower dissolution profiles.
- Softgels:Rotary die encapsulation technology enables lipid-soluble nutrient integration including DHA and vitamin D3 in phospholipid carriers, commanding premium positioning in healthcare professional recommendation networks where bioavailability claims carry diagnostic weight.
- Gummies:Starch-based molding and pectin formulation require humidity-controlled production suites with elevated energy inputs.
- Powders:Spray-drying and micronization equipment supports flexible dosing protocols for personalized nutrition services.
Tablets absorb the bulk of installed capacity; gummies are expanding most quickly.
Formulation:
Certification stacking determines margin architecture, with multi-attribute claims commanding exponential premiums over single-certification products.
- Organic:USDA Organic and EU Organic seal compliance requires certified supply chains for plant-derived excipients and chelated minerals, with audit costs and raw material premiums concentrating production among manufacturers with captive agricultural partnerships.
- Non-GMO:Project Verified and equivalent European certification demands identity-preserved sourcing for soy-derived vitamin E and corn-based excipients, creating procurement complexity that favors vertically integrated operators with multi-year supplier contracts.
- Vegan:Algal DHA substitution for fish oil and plant-derived capsule materials address animal-free positioning in metropolitan United States and United Kingdom markets.
- Conventional:Synthetic vitamin sources and gelatin encapsulation minimize input costs for mass-market penetration.
Conventional formulations retain volume dominance; organic certification claims are climbing the fastest.
Distribution Channel:
Channel selection determines working capital intensity, with subscription models requiring inventory float against auto-replenishment algorithms versus pharmacy consignment arrangements.
- Online Retail:Direct-to-consumer platforms integrate gestational age tracking with auto-ship algorithms, compressing customer acquisition costs through telehealth bundling in United States metropolitan markets with employer-sponsored fertility benefits.
- Pharmacies:Brick-and-mortar chains maintain formulary gatekeeper status through pharmacist consultation protocols, with shelf placement fees and promotional allowances consuming margin in German and Swiss markets.
- Supermarkets:Mass merchandiser placement emphasizes price-per-unit competitiveness and promotional circular visibility.
- Health Stores:Specialty retailers curate clean-label assortments with trained staff consultation, supporting premium price realization for multi-certification products.
Pharmacies retain the largest transaction volume; online retail is gaining share fastest.
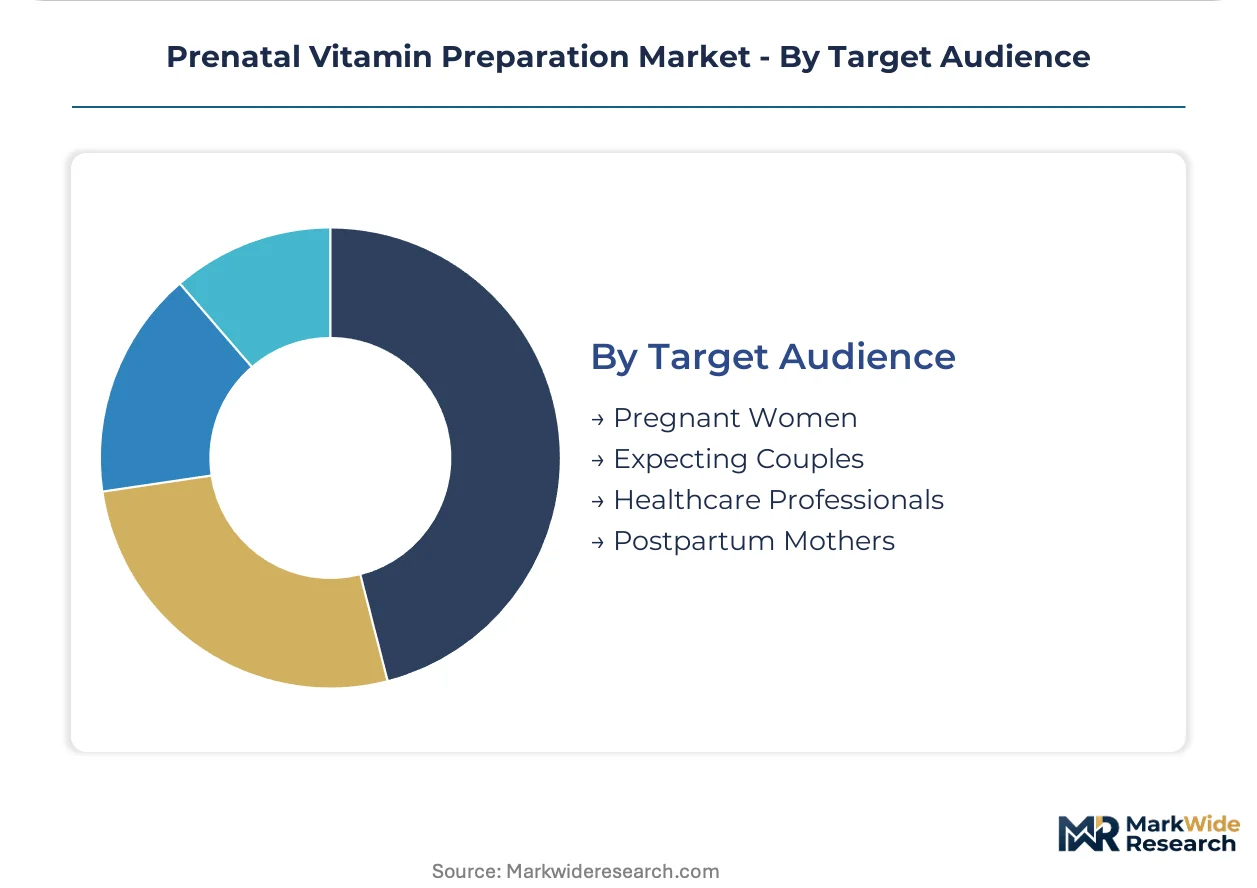
Target Audience:
Audience segmentation dictates messaging architecture, with clinical credibility requirements varying sharply between self-directed consumers and institutional purchasers.
- Pregnant Women:First-trimester nausea tolerance and trimester-specific micronutrient needs drive format preferences, with liposomal and gummy alternatives displacing standard tablets among United States consumers with digital health adoption.
- Expecting Couples:Joint subscription purchasing and partner-inclusive telehealth consultations expand average order values through bundled DHA and prenatal vitamin SKUs.
- Healthcare Professionals:Obstetrician and midwife recommendation networks require clinical trial substantiation and pharmacovigilance documentation, with formulary inclusion decisions concentrated in German statutory health insurance frameworks.
- Postpartum Mothers:Lactation-stage nutritional needs represent underpenetrated extension opportunity with twelve-month consumption windows beyond delivery.
Pregnant women constitute the core addressable population; postpartum mothers present the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Formulation manufacturing clusters in Germany, the United States, and coastal China supply consumption across domestic and export markets, while regulatory divergence between FDA, EMA, and SAMR frameworks shapes product registration strategies and local production requirements.
United States
Telehealth-integrated subscription services and employer-sponsored fertility benefits drive channel migration toward direct-to-consumer platforms. FDA dietary supplement Good Manufacturing Practices enforcement creates compliance thresholds that favor manufacturers with captive analytical laboratories. The New Jersey-Pennsylvania pharmaceutical corridor hosts softgel encapsulation facilities serving healthcare professional recommendation networks.
Germany
Statutory health insurance reimbursement for iron deficiency screening and prenatal supplementation expands addressable demand through pharmacy channels. EMA nutrition and health claims regulation tightens substantiation requirements for folate-related neural tube defect prevention statements. The Baden-Württemberg chemical manufacturing belt concentrates wet granulation capacity for tablet formulations distributed across European pharmacy chains.
China
SAMR pilot zones for cross-border e-commerce reduce registration timelines for imported prenatal brands with existing FDA or EMA dossiers. Dual carbon goals and MEE environmental compliance targets accelerate excipient substitution toward plant-derived coating agents. The Yangtze River Delta marine biotechnology cluster supplies algal DHA to domestic and international formulation manufacturers.
Australia
TGA oversight of complementary medicines creates parallel regulatory pathways for vitamin formulations with therapeutic-level nutrient concentrations. Clean-label certification demand concentrates in Sydney and Melbourne metropolitan markets with high organic and Non-GMO product adoption. The Victorian pharmaceutical manufacturing zone exports softgel and gummy formats to Asia-Pacific markets.
Switzerland
Swissmedic pharmacovigilance requirements for adverse event reporting influence formulation design across premium positioning segments. Precision nutrition services and pharmacogenomic testing integration enable trimester-specific micronutrient adjustments. The Basel biotech corridor anchors clinical trial infrastructure supporting EMA-compliant substantiation documentation.
Prenatal Vitamin Preparation Market Competitive Landscape
Capital-heavy producers with captive manufacturing assets compete with asset-light brand architects outsourcing formulation and encapsulation to contract development organizations. The vendor base stratifies across pharmaceutical heritage companies, organic certification specialists, and direct-to-consumer digital natives. Three archetypes dominate: legacy pharmaceutical manufacturers leveraging clinical credibility, clean-label formulators stacking USDA Organic and Non-GMO certifications, and subscription-commerce operators integrating telehealth consultations. Competitive moves concentrate on portfolio diversification into postpartum extension formulations and strategic partnerships with marine biotechnology suppliers for algal DHA security.
Within the pharmaceutical heritage tier, Bayer AG and Abbott Laboratories occupy positions anchored by healthcare professional recommendation networks and pharmacy channel access. Among clean-label specialists, Garden of Life exemplifies multi-certification stacking that commands premium shelf placement in health store channels. These three companies represent the structural tension between clinical credibility positioning and clean-label premium extraction across diverging consumer segments.
| Leading Market Players |
|---|
| Nature Made |
| Bayer AG |
| Abbott Laboratories |
| Vitabiotics |
| Garden of Life |
| Church & Dwight Co., Inc. |
| Blackmores |
| Swisse |
| MegaFood |
| Others |
Value Network & Pricing Analysis
Pharmaceutical formulation chemists in the New Jersey-Pennsylvania corridor command wage premiums that widen spreads between premium softgel offerings and economy tablet tiers. Labor-cost differentials between captive manufacturing and contract development organizations feed directly into subscription pricing architecture.
Pricing Analysis
Margin tightening in economy-tier tablets reflects chelated mineral cost premiums that compress returns at price-sensitive mass-market positions. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification stacking and bioavailability claims, with organic and liposomal formats capturing clean-label premiums. Cost-down pressure on standard-tier SKUs accelerates because algal DHA supply concentration limits formulation flexibility. Employer-sponsored fertility benefit recipients show lowest price sensitivity, while supermarket channel purchasers drive hardest unit economics negotiations.
Supply Chain Analysis
USDA Organic and EU Organic certification gating concentrates qualified excipient sourcing among manufacturers with multi-year agricultural partnerships. Wet granulation capacity clusters in Germany, softgel encapsulation concentrates in the United States, and algal DHA cultivation anchors in coastal China. Formulation draws from marine biotechnology harvests, chelated mineral deposits, and plant-derived coating agents. Single-source dependency on Yangtze River Delta algal suppliers creates raw material vulnerability during seasonal volatility. Distribution runs through pharmacy consignment networks, direct-to-consumer subscription platforms, and health store specialty channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Prenatal vitamin manufacturing is becoming a vertical-integration race as brands pursue captive algal DHA cultivation to secure supply continuity and margin control.
For Market Incumbents: To counter direct-to-consumer subscription displacement, Bayer AG and Abbott Laboratories should deepen healthcare professional recommendation network lock-in through pharmacovigilance documentation superiority. Backward integration into marine biotechnology partnerships reduces raw material vulnerability while EMA substantiation investments defend premium positioning against clean-label challengers. For New Entrants and Emerging Players: Enter via postpartum lactation-stage formulations, the most penetrable twelve-month extension window with minimal incumbent saturation. SAMR pilot zone cross-border e-commerce offers lowest regulatory barrier entry for foreign brands with existing FDA dossiers. Telehealth bundling partnerships provide immediate channel access without pharmacy slotting fee burdens. For Investors and Strategic Acquirers: Re-rating potential sits with organic-certified contract manufacturers given REACH compliance deadlines accelerating excipient substitution demand. Long-term viability over the next decade favors operators with captive analytical laboratories and validated simultaneous quantification protocols for complex vitamin matrices. Watch for pharmacovigilance reporting threshold revisions that could trigger prescription reclassification inflections.| Strategic Initiative | Industry Significance |
|---|---|
| Algal DHA Supply Partnership | Marine biotechnology alliances in coastal China reduce single-source harvest vulnerability. |
| Telehealth Platform Integration | FDA-compliant virtual consultation bundles embed replenishment triggers at trimester transitions. |
| REACH Excipient Reformulation | EU Green Deal plant-derived coating substitution commands clean-label shelf premiums. |
| Postpartum SKU Extension | Lactation-stage galactagogue complexes address underpenetrated twelve-month consumption windows. |
| Pharmacogenomic Testing Integration | MTHFR variant analysis enables personalized folate dosing that differentiates subscription offerings. |
Research Methodology
FDA 483 inspection records, EMA marketing authorization dossiers, and SAMR cross-border e-commerce registration databases formed the secondary backbone. Primary interviews with pharmaceutical formulation chemists, regulatory affairs specialists at dietary supplement manufacturers, pharmacy chain category managers, and telehealth platform operators combined with customs trade data and hospital procurement records. Bottom-up and top-down triangulation validated segment-level estimates against aggregate market sizing.
Bottom-up modeling anchored volume projections to installed wet granulation, softgel encapsulation, and gummy deposition capacity across manufacturing clusters. Segmentation dimensions included formulation technology, certification tier, distribution channel architecture, and target audience readiness to pay for clinical substantiation. CAGRs were derived from elasticity-adjusted demand curves incorporating birth-rate stabilization trajectories and maternal health program expansion. Algal DHA harvest yield volatility and chelated mineral input cost curves fed scenario-weighted outputs.
Revisions become necessary when pharmacovigilance reporting thresholds trigger prescription reclassification, REACH compliance deadlines accelerate faster than excipient substitution capacity, or SAMR pilot zone policies restrict foreign brand access. Forecasts reflect assumptions about telehealth adoption curves, fertility benefit employer penetration, and organic certification audit capacity expansion. A model refresh is warranted upon material change in algal DHA supply concentration or EMA neural tube defect claim substantiation requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vitamin Fortified
Vitamin Premix Market
Vitamin Fortified
Asia-Pacific Vitamin a Market
Vitamin Fortified
Vitamin B12 Drops Market
Vitamin Fortified
Fortified Beverages Market
Vitamin Fortified
Vitamin C Market
Vitamin Fortified
Food Fortifying Agents Market
Vitamin Fortified
Encapsulated Vitamin C Market
Vitamin Fortified
Calcium-Fortified Bread Market
Vitamin Fortified
Middle East Feed Vitamins Market
Vitamin Fortified
Global Fortified Edible Oils Market
Vitamin Fortified
Middle East and Africa Food Fortifying Agents Market
Vitamin Fortified
Middle East and Africa Vitamin a Market
Vitamin Fortified
Vitamin D3 Market
Vitamin Fortified
Global Mixed Tocopherol Market
Vitamin Fortified
Liquid Vitamins Market
Vitamin Fortified
Fortified Milk and Milk Products Market