

Emergency Venting System Market Size, Share, and Industry Trends Forecast 2026-2036
Emergency Venting System Market Insights
Aftermarket service revenue is reconfiguring margin capture away from pure equipment sales across the emergency venting landscape. Emerson Electric leverages its global instrumentation network to embed predictive maintenance contracts into relief valve installations. Pentair anchors its position through specialized corrosion-resistant alloys for offshore chemical processing environments. Protego differentiates via German-engineered flame arrester integration with emergency venting manifolds.
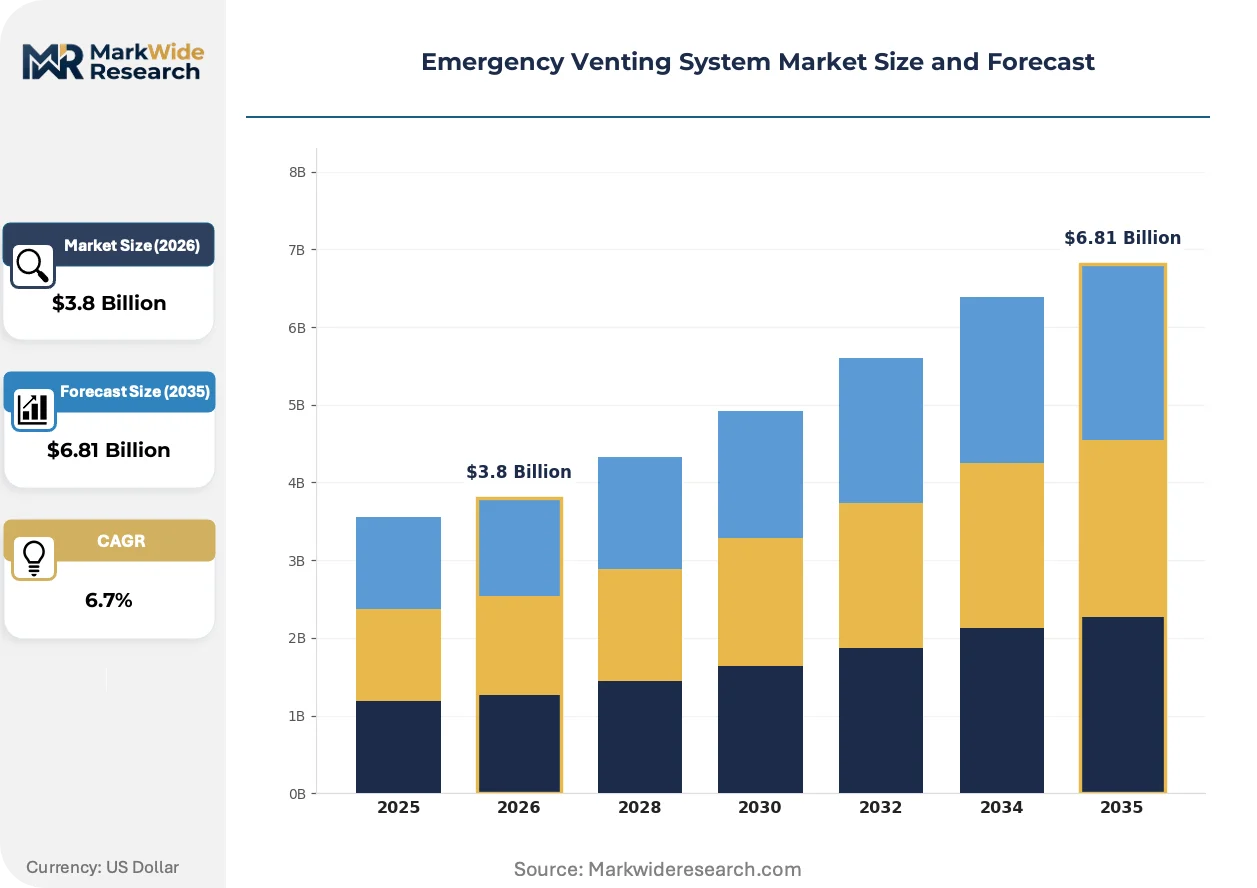
Emergency venting systems are pressure-relief assemblies designed to prevent catastrophic vessel or tank failure by rapidly discharging overpressure events to atmosphere or containment, typically rated for set pressures between 0.5 psig and 15,000 psig depending on application severity. These systems serve critical safety functions in chemical processing, petrochemical storage, and power generation facilities where thermal expansion, runaway reactions, or external fire exposure threaten structural integrity. Pressure relief valves dominate installed base economics due to reseat capability and regulatory recertification cycles, while flameless vents represent the fastest-growing product category as urban-adjacent industrial sites face tighter emissions and noise constraints. Pilot-operated technology leads in large-capacity refinery applications where minimal product loss during normal operation justifies higher capital outlay.
EPA Risk Management Plan requirements and EU Seveso III directives mandate documented emergency relief system integrity assessments at fixed intervals, creating recurring compliance expenditure for facility operators. OSHA Process Safety Management standards in the United States and ATEX directives across European member states further specify venting capacity calculations, material compatibility, and ignition source control that shape product specifications and vendor qualification. Stakeholders must monitor evolving hydrogen economy infrastructure codes, as repurposed storage and pipeline systems introduce novel overpressure scenarios that existing venting standards have not fully addressed.
Market Dynamics
Refinery flaring reduction mandates are compressing replacement cycles for emergency venting infrastructure as operators face simultaneous pressure from EPA enforcement and investor carbon intensity targets. This regulatory-commercial squeeze is restructuring vendor relationships toward long-term service contracts and predictive maintenance integration.
Growth Catalysts
- Seveso III Directive:EU member states mandate documented pressure relief integrity assessments at fixed intervals, forcing systematic retrofit programs across Rotterdam-Antwerp chemical clusters.
- Hydrogen infrastructure codes:Repurposed storage and pipeline systems for hydrogen economy deployment create novel overpressure scenarios requiring upgraded venting capacity calculations.
- Urban-adjacent industrial sites:Flameless vent technology captures demand from facilities facing tightening emissions and noise constraints near population centers.
Market Restraints
- Nickel alloy input costs:Specialized corrosion-resistant materials for offshore chemical processing face price volatility tied to mining supply concentration in Indonesia and Russia.
- Certification timeline friction:ATEX directive compliance testing for flame arrester integration extends product qualification cycles by 8-14 months in European markets.
- Technical limitation in cryogenic service:Existing elastomer sealing technologies degrade below minus 40 degrees Celsius, constraining LNG terminal applications.
Strategic Opportunities
- India refining expansion:Reliance Industries and Indian Oil Corporation tank farm modernization programs create demand for pilot-operated relief systems in Gujarat and Maharashtra.
- Predictive maintenance convergence:Integration of IoT pressure sensors with relief valve monitoring enables condition-based recertification rather than calendar-based replacement.
- Carbon border adjustment mechanism:EU CBAM creates competitive incentive for Middle Eastern exporters to install advanced venting systems that demonstrate methane intensity compliance.
Industry Challenges
- Pressure relief specialist shortage:API 521 and API 526 certified engineers remain concentrated in Houston and Rotterdam, creating project bottlenecks for remote facility upgrades.
- Legacy DCS integration complexity:Digital venting monitoring systems require protocol translation layers to communicate with 1990s-era distributed control systems common in Gulf Coast refineries.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Emergency Venting System Market Trends and Innovations
Digital instrumentation is penetrating emergency venting systems at an accelerating pace, transforming hardware sales into continuous monitoring revenue streams. Three interconnected developments are restructuring competitive positioning.
Pilot-operated pressure relief valve technology is migrating from conventional spring-loaded designs in large-capacity refinery applications. Major integrated operators along the US Gulf Coast now specify pilot-operated systems for new crude distillation unit installations, accepting higher capital outlay to minimize product loss during normal operation and reduce flare event frequency.
EPA Risk Management Plan amendments are tightening documentation requirements for relief system capacity verification. Facility operators must now submit independent third-party assessments of overpressure protection adequacy, driving demand for engineering services that bundle hydraulic analysis with equipment procurement across chemical processing sites.
Service unbundling is fragmenting traditional supply relationships. End-users in petrochemical storage increasingly separate valve procurement from installation and recertification, awarding multi-year predictive maintenance contracts to instrumentation specialists rather than original equipment manufacturers. This pattern is most visible in Texas and Louisiana, where integrated refining clusters concentrate procurement decision-making.
Emergency Venting System Market Segmentation
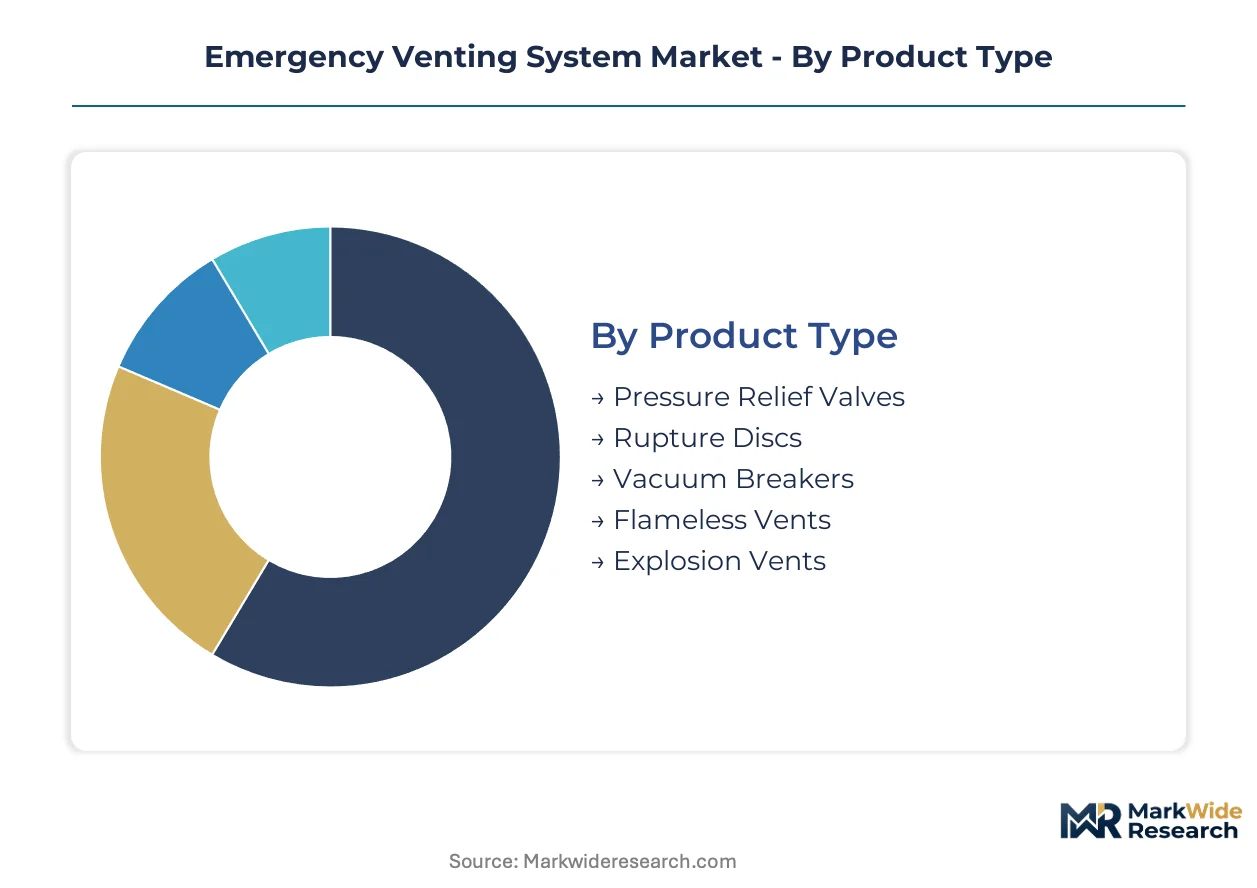
Emergency venting system procurement patterns diverge sharply across pressure ratings, operational cycles, and regulatory exposure levels. Segmentation reveals how technology choices cascade through maintenance economics and compliance burden distribution.
Product Type:
Cost tier structures the installed base, with capital outlay and lifecycle maintenance burden determining selection across facility vintages.
- Pressure Relief Valves:Spring-loaded or pilot-operated assemblies rated for reseat capability after activation dominate refinery and petrochemical installations. Demand concentrates along the US Gulf Coast where EPA Risk Management Plan recertification cycles drive systematic replacement programs.
- Flameless Vents:Catalytic or absorption-based systems eliminate visible flame and reduce noise emissions during emergency discharge. Urban-adjacent chemical facilities in Rotterdam and Antwerp specify these for tank farm expansions facing municipal permitting constraints.
- Rupture Discs:Non-reclosing metal membranes provide instantaneous full-bore relief for runaway reaction scenarios.
- Vacuum Breakers:Protect atmospheric storage tanks against implosion from pump-out or thermal contraction events.
- Explosion Vents:Low-mass panels designed for rapid pressure relief in dust handling and combustible powder operations.
Pressure relief valves hold installed capacity. Flameless vents are rotating up the share rankings.
Technology:
Application severity and allowable product loss during normal operation determine technology selection across process industries.
- Pilot Operated:Auxiliary pressure sensing enables bubble-tight seating until set pressure approaches, minimizing fugitive emissions and product loss. Large-capacity refinery crude units specify these for flare reduction compliance despite 40-60% higher capital cost versus spring-loaded alternatives.
- Spring Loaded:Direct-acting mechanical systems dominate smaller-capacity installations and legacy facility retrofits where simplicity outweighs precision.
- Burst Disc:Single-use metal membranes suit applications with extreme pressure rise rates or corrosion concerns.
- Mechanical:Weight-loaded or lever-operated designs persist in low-pressure atmospheric storage applications.
- Pneumatic:External pressure supply enables remote set pressure adjustment for batch processing flexibility.
Spring loaded maintains broadest deployment. Pilot operated is climbing the fastest in new capital expenditure.
Application:
End-use hazard profiles dictate venting capacity calculations and material specifications across industrial sectors.
- Chemical Processing:Runaway reaction protection and toxic release containment drive specification complexity. Facilities in Germany's Rhine-Neckar chemical cluster invest in redundant relief paths for Seveso III compliance.
- Petrochemical Plants:Large-volume storage and high-pressure reactor systems require staged relief strategies. Gulf Coast ethylene crackers face compressed replacement cycles from simultaneous EPA enforcement and investor carbon intensity targets.
- Power Generation:Boiler and steam system overpressure protection follows ASME Boiler and Pressure Vessel Code requirements.
- Waste Treatment:Anaerobic digester gas management and thermal oxidizer protection create specialized venting scenarios.
- Food Processing:Sanitary design requirements and allergen containment shape relief system specifications.
Chemical processing commands engineering intensity. Petrochemical plants are expanding most quickly in absolute unit demand.
End User:
Customer type concentration determines procurement channel structure and service bundling preferences.
- Refineries:Integrated operators with centralized engineering functions separate equipment procurement from installation and predictive maintenance contracts. Texas and Louisiana facilities drive demand for IoT-enabled condition monitoring.
- Power Utilities:Rate-regulated capital recovery mechanisms and extended asset lifecycles favor proven designs with extensive service history documentation.
- Municipal Facilities:Constrained technical staffing and grant-dependent capital programs prioritize turnkey installation and extended warranty coverage.
- Pharmaceutical Manufacturers:FDA process validation requirements and cleanroom compatibility constrain approved vendor lists.
- Metals & Mining:Remote site locations and harsh operating environments emphasize durability and field service accessibility.
Refineries anchor vendor relationship restructuring toward service contracts. Power utilities maintain longest equipment replacement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in the United States exhibit the lowest price elasticity as EPA enforcement compresses replacement cycles regardless of capital cost, while Indian refiners remain most sensitive to upfront equipment outlay despite expanding tank farm programs. European purchasers occupy a middle position where Seveso III compliance mandates override pure cost considerations but still demand lifecycle value documentation. This demand-elasticity spectrum shapes how vendors structure service contracts versus equipment-only sales across major markets.
United States
Gulf Coast refiners face simultaneous pressure from EPA Risk Management Plan amendments and investor carbon intensity targets, forcing systematic relief valve replacements regardless of commodity price cycles. OSHA Process Safety Management standards mandate documented overpressure protection assessments at fixed intervals. The Texas-Louisiana refining corridor concentrates procurement decision-making for pilot-operated systems in new crude distillation unit installations.
Germany
Rhine-Neckar chemical cluster operators invest in redundant relief paths and flame arrester integration to satisfy Seveso III directive requirements for documented pressure relief integrity. ATEX directive compliance testing extends product qualification cycles, creating preference for established suppliers with certification track records. BASF and Lanxess facility upgrades in Ludwigshafen drive demand for German-engineered venting manifolds with predictive maintenance capability.
China
State-owned refining giants Sinopec and PetroChina accelerate tank farm modernization as GB standards for pressure vessel safety tighten enforcement timelines. The country's national standards regulator pushes alignment with international pressure relief codes for hydrogen infrastructure deployment. Yangtze River Delta petrochemical complexes in Zhenjiang and Ningbo represent the fastest-growing regional demand for large-capacity pilot-operated systems.
India
Reliance Industries and Indian Oil Corporation tank farm expansion programs in Gujarat and Maharashtra create volume opportunity despite buyer price sensitivity. The national standards body issues updated pressure equipment safety regulations that elevate import certification requirements. Jamnagar refinery complex retrofits concentrate demand for corrosion-resistant alloys in marine atmospheric conditions.
Netherlands
Rotterdam-Antwerp chemical corridor facilities specify flameless vent technology to satisfy municipal permitting constraints on visible emissions and noise from urban-adjacent operations. EU Seveso III enforcement through the national environmental agency forces systematic retrofit programs across legacy storage terminals. Port of Rotterdam tank farm operators bundle emergency venting procurement with flare reduction compliance investments.
Emergency Venting System Market Competitive Landscape
Integrated industrial conglomerates and specialized pressure equipment fabricators split the market along service-bundling versus engineering-precision lines. The vendor base concentrates around three strategic archetypes: instrumentation-heavy conglomerates embedding predictive maintenance into relief valve installations, corrosion-resistant alloy specialists capturing offshore chemical processing demand, and German-engineered flame arrester integrators serving Seveso III compliance markets. Competitive moves center on long-term service contract capture and IoT-enabled condition monitoring integration rather than pure equipment price competition.
Among diversified industrial technology providers, Emerson Electric exemplifies the instrumentation-anchored archetype through its global measurement and control network. Pentair occupies a position within corrosion-resistant materials specialization for marine and offshore environments. Protego represents German-engineered flame arrester integration with emergency venting manifolds. These three anchors illustrate how vendor positioning diverges across predictive maintenance, materials science, and regulatory compliance vectors without requiring specific product or financial claims.
| Leading Market Players |
|---|
| Emerson Electric |
| Pentair |
| Elmac Technologies |
| Cashco |
| Motherwell Tank Protection |
| Protego |
| Groth Corporation |
| Valve Concepts |
| Protectoseal Company |
| Others |
Pricing and Supply Chain Analysis
Rotterdam-Antwerp corridor freight costs transmit nickel alloy price volatility from Indonesian mining concentration directly into emergency venting system landed costs, compressing margins for standard-grade equipment while amplifying differentiation premiums for corrosion-resistant offshore specifications. This logistics-cost channel forces buyers to weight total cost of ownership more heavily against upfront capital outlay.
Pricing Analysis
Predictive maintenance contract revenue drives lifetime value capture away from pure equipment transactions. Three-tier pricing structure across premium, standard, and economy levels separates pilot-operated systems with IoT instrumentation from spring-loaded mechanical alternatives and basic rupture disc configurations. Price differentiation centers on certification grade—API 521 recertification bundling versus bare equipment procurement—and geographic delivery cost from Rotterdam or Houston manufacturing clusters. Cost compression in standard-grade spring-loaded valves is intensifying because Indian refiners negotiate aggressively on upfront outlay despite expanding tank farm programs. Municipal facilities exhibit highest price sensitivity due to grant-dependent capital cycles, while US Gulf Coast integrated operators show lowest elasticity under EPA enforcement pressure.
Supply Chain Analysis
Tariff exposure between Indonesia and key manufacturing hubs dominates raw material cost planning for nickel-based corrosion-resistant alloys. Supply concentration rests on Germany for precision flame arrester engineering, the United States for API-certified pressure relief valve casting, and China for GB-standard hydrogen infrastructure components. Critical inputs include Inconel 625 alloy bar stock, elastomer sealing compounds rated for cryogenic service, and precision-machined pilot valve subassemblies. Single-source vulnerability persists in specialized corrosion-resistant material forging capacity concentrated in European specialist foundries. Distribution runs through authorized service contractors who bundle installation with recertification compliance, displacing direct OEM sales in mature markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Flameless vent technology threatens spring-loaded pressure relief valve incumbents in urban-adjacent chemical clusters where municipal permitting constraints intensify. Incumbents must defend installed base economics through service contract capture before substitution accelerates.
For Market Incumbents: Harden aftermarket revenue capture by embedding IoT pressure sensors into relief valve installations under multi-year predictive maintenance contracts. Prioritize API 521 certified engineer training programs in India and China to alleviate project bottlenecks threatening Gulf Coast and Rotterdam service capacity. Vertical integration into corrosion-resistant alloy supply through captive forging partnerships mitigates Indonesian nickel price volatility exposure. For New Entrants and Emerging Players: Build out specialized flame arrester integration capabilities targeting Seveso III compliance markets in Germany's Rhine-Neckar chemical cluster where established German engineering credentials command premium positioning. Target India's Jamnagar refinery complex retrofits with marine-grade corrosion-resistant specifications where Reliance Industries and Indian Oil Corporation expansion programs concentrate demand. Lead with turnkey installation and extended warranty coverage to differentiate against incumbent equipment-only positioning. For Investors and Strategic Acquirers: EU Seveso III enforcement milestones reshape the acquisition landscape by elevating engineering services firms with documented pressure relief integrity assessment capabilities above pure equipment fabricators. Long-term viability favors vendors with installed IoT monitoring infrastructure that enables condition-based recertification revenue streams. Watch hydrogen infrastructure code finalization as the signal indicating which venting capacity calculation specialists will capture repurposed storage and pipeline system demand.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Integration | IoT sensor deployment transforms hardware sales into recurring service revenue across Gulf Coast refineries. |
| Corrosion-Resistant Alloy Backward Integration | Captive forging partnerships insulate margin from Indonesian nickel supply concentration volatility. |
| Seveso III Compliance Engineering Services | Third-party overpressure protection assessments bundle hydraulic analysis with equipment procurement. |
| Hydrogen Infrastructure Code Alignment | GB standards and EU hydrogen codes create novel venting capacity demand for repurposed systems. |
| Flameless Vent Technology Licensing | Catalytic absorption systems capture urban-adjacent chemical facility demand under municipal permitting constraints. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with plant engineers, maintenance directors, and aftermarket service heads at refineries and petrochemical complexes, and secondary validation through API certification databases, EPA Risk Management Plan filings, EU Seveso III compliance registries, and customs trade records for pressure relief equipment. Stakeholder roles included facility engineering managers at integrated refining clusters, procurement leads at tank farm modernization programs, technical directors at flame arrester specialists, and regulatory affairs officers at pressure equipment OEMs. Bottom-up equipment shipment tallies by product type and technology tier were triangulated against top-down facility capital expenditure tracking across the US Gulf Coast, Rotterdam-Antwerp corridor, and India refining expansion zones.
Forecast inputs considered refinery flaring reduction mandate timelines, hydrogen infrastructure code development trajectories, and replacement cycle compression from EPA and EU enforcement intensification. Segmentation dimensions modeled include pressure rating tiers, technology categories from spring-loaded to pilot-operated systems, application severity across chemical processing and petrochemical storage, and end-user procurement structures from integrated operators to municipal facilities. CAGRs were derived from facility-level capital expenditure projections and regulatory-driven replacement schedules rather than macroeconomic extrapolation. Industry-specific inputs incorporated API 521 recertification cycle frequencies and ATEX directive compliance testing duration estimates.
Stress conditions across nickel alloy price volatility bands, hydrogen infrastructure deployment pace variations, and regulatory enforcement intensity scenarios were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding replacement cycle compression and service contract penetration rates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.