
 Valve Cover Gasket Market | 2026-2036
Valve Cover Gasket Market Size, Share, and Industry Trends Forecast 2026-2036
Valve Cover Gasket Market Analysis
Multi-source procurement is decoupling from traditional captive rubber-molding arrangements in the valve cover gasket supply base. ElringKlinger AG leverages its European compound formulation expertise to sustain premium positioning in thermal-resistant silicone grades. Mahle GmbH anchors volume supply through integrated foundry-to-seal operations across German and Czech production nodes. NOK Corporation competes on precision stamping and fiber-composite innovation for Asian OEM programs.
A valve cover gasket seals the interface between an engine's cylinder head and valve cover, typically comprising nitrile rubber, silicone elastomer, cork composite, or aramid fiber bound with synthetic rubber; its primary function is containing crankcase gases and preventing lubricant leakage under cyclic thermal stress between minus forty and two hundred degrees Celsius. Silicone gaskets command the dominant margin pool due to extended service intervals and turbocharger compatibility, while rubber formulations retain volume leadership in cost-sensitive aftermarket channels. Electric vehicle architectures are fragmenting the segment map, as battery thermal management systems displace traditional engine sealing demand yet create adjacent gasket requirements for power electronics housings.
EPA tailpipe regulations and NHTSA corporate average fuel economy standards enforce seal integrity as a compliance variable for evaporative emissions control in the United States. ECHA REACH restrictions on aromatic oil plasticizers and EU F-Gas Regulation phasing constrain compound formulation choices for suppliers serving European OEMs. Stakeholders must monitor how China's MIIT new-energy vehicle mandates and dual carbon goals redirect gasket demand from internal combustion platforms toward battery enclosure sealing technologies.
Market Dynamics
The valve cover gasket market is reconfiguring around thermal management demands from downsized turbocharged engines and the divergent sourcing strategies of aging vehicle parc maintenance versus new powertrain assembly.
Growth Catalysts
- EPA evaporative emissions enforcement:NHTSA corporate average fuel economy standards mandate crankcase seal integrity as a compliance variable, forcing OEMs to specify premium silicone grades over cork composites in gasoline direct injection platforms.
- Turbocharger penetration:Heat-resistant silicone elastomer formulations are displacing nitrile rubber in cylinder head sealing as boost pressures elevate operating temperatures beyond two hundred degrees Celsius.
- China's eastern manufacturing corridor:Domestic OEMs and tier suppliers are localizing gasket procurement, concentrating demand in Jiangsu and Zhejiang provinces where integrated rubber-molding and metal-stamping clusters reduce logistics costs.
Market Restraints
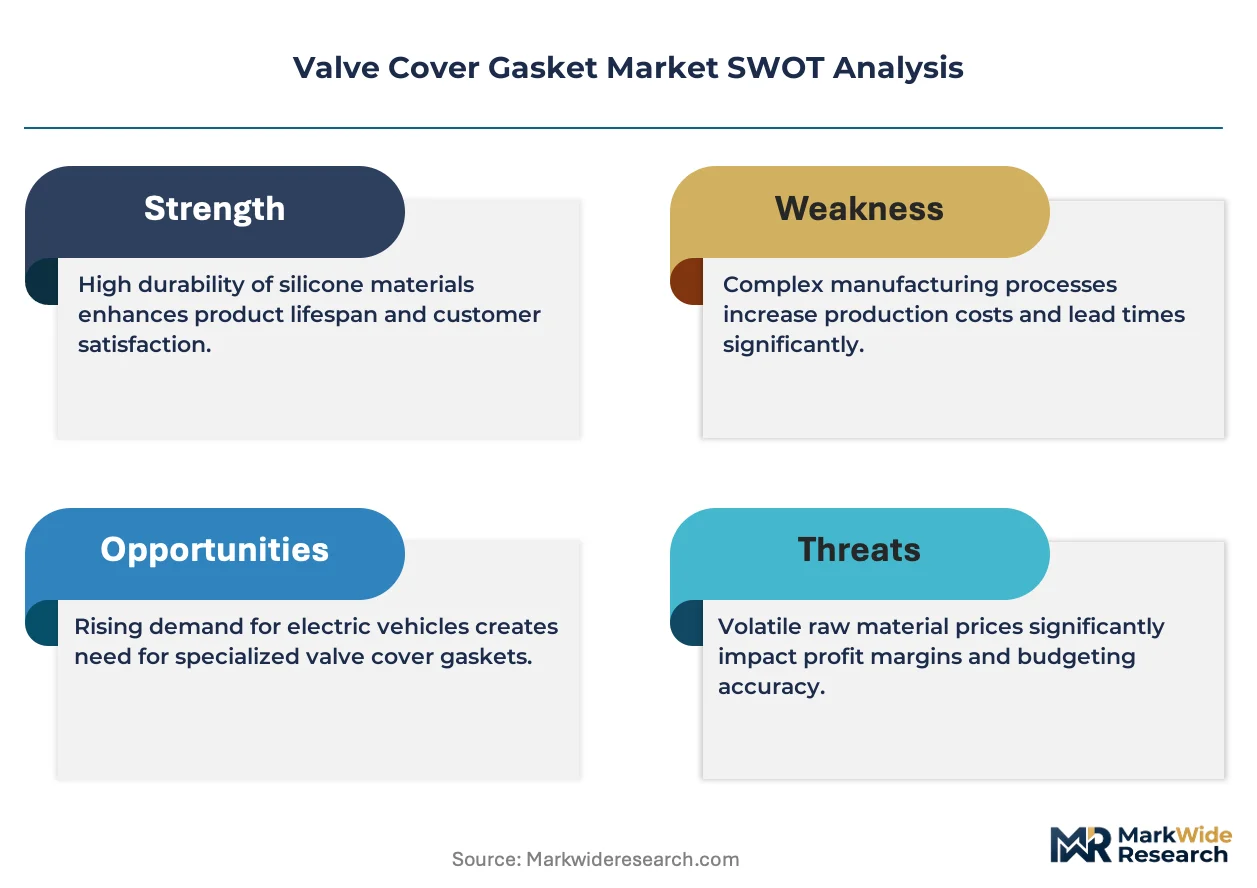
- Raw material volatility:Silicone polymer feedstock prices fluctuate with methyl chloride and silicon metal supply disruptions, compressing compounder margins and forcing pass-through negotiations with automotive tier ones.
- Supplier concentration risk:Precision fiber-composite stamping capacity concentrates among Japanese and Korean specialists, creating bottleneck exposure for European and North American aftermarket distributors.
- Powertrain electrification:Battery electric vehicle architectures eliminate traditional valve train sealing demand, stranding rubber-molding capacity as OEMs redirect capital toward battery enclosure and power electronics housing seals.
Strategic Opportunities
- India's commercial vehicle aftermarket:Aging medium and heavy-duty truck parc in Maharashtra and Tamil Nadu creates replacement demand for fiber-reinforced rubber gaskets as state transport fleets extend service intervals.
- Battery thermal management sealing:Power electronics housings and coolant manifolds in electric vehicles require compression-set resistant elastomers, opening adjacent specification opportunities for compounders with automotive thermal validation.
- ECHA REACH aromatic oil restrictions:Phased constraints on plasticizer formulations force reformulation cycles, rewarding suppliers with in-house polymer synthesis capabilities to capture specification-driven premium positioning.
Industry Challenges
- Compound formulation expertise scarcity:Thermal-aging test protocol knowledge and finite element analysis for multi-material gasket stacks concentrate among aging specialists in Germany and Japan, constraining new entrant qualification timelines.
- Dual certification burden:Suppliers must simultaneously validate to SAE J20 for North American OEMs and GB/T standards for Chinese domestic brands, duplicating test cell investment and extending program launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Valve Cover Gasket Market |
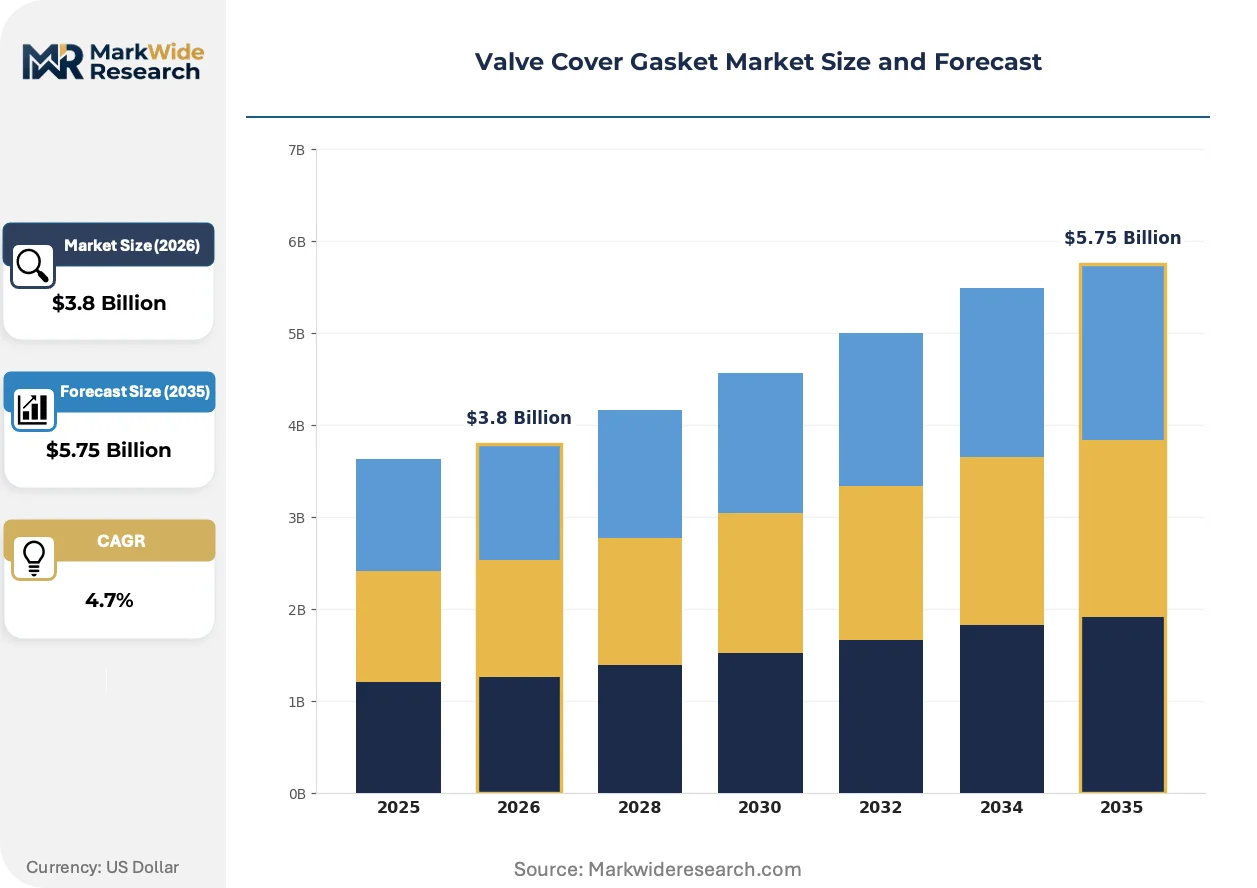
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rubber, Silicone, Cork, Fiber End User: Aftermarket Providers, OEMs, Repair Shops, Distributors Vehicle Type: Passenger Cars, Commercial Vehicles, Motorcycles, Electric Vehicles Installation Type: Standard, Custom, Remanufactured, Reusable |
| Companies Covered | Dana Incorporated, ElringKlinger AG, Mahle GmbH, Federal-Mogul Motorparts, Freudenberg Sealing Technologies, NOK Corporation, Tenneco Inc., Toyoda Gosei Co., Ltd., Hutchinson SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Valve Cover Gasket Market Emerging Trajectories
Material science advances and regulatory stringency are fragmenting the traditional rubber-versus-silicone dichotomy, while procurement centralization among mega-suppliers compresses specification diversity.
Multi-layer steel-silicone hybrid gaskets are decentralizing thermal stress distribution across cylinder head interfaces. OEMs adopting these laminates for high-specific-output engines reduce localized compression set failures. The technology is decentralizing specification authority from captive rubber molders toward integrated metal-forming specialists with elastomer bonding capabilities.
ECHA F-Gas Regulation phasing constrains fluoropolymer content in premium gasket formulations. Compounders are reformulating with peroxide-cured silicone and aramid fiber reinforcement to maintain chemical resistance. European OEMs and their tier suppliers face accelerated validation cycles as 2027 restriction deadlines approach, favoring suppliers with existing thermal-aging databases.
Consolidated procurement desks at Volkswagen Group, Stellantis, and Geely are unbundling aftermarket service parts from original equipment supply agreements. Tier one seal suppliers now face separate commercial negotiations for OE assembly business versus replacement channel distribution. This bifurcation is most visible in Germany and China, where aftermarket platform aggregators are capturing gasket demand through direct-to-workshop digital channels.
Valve Cover Gasket Market Segmentation
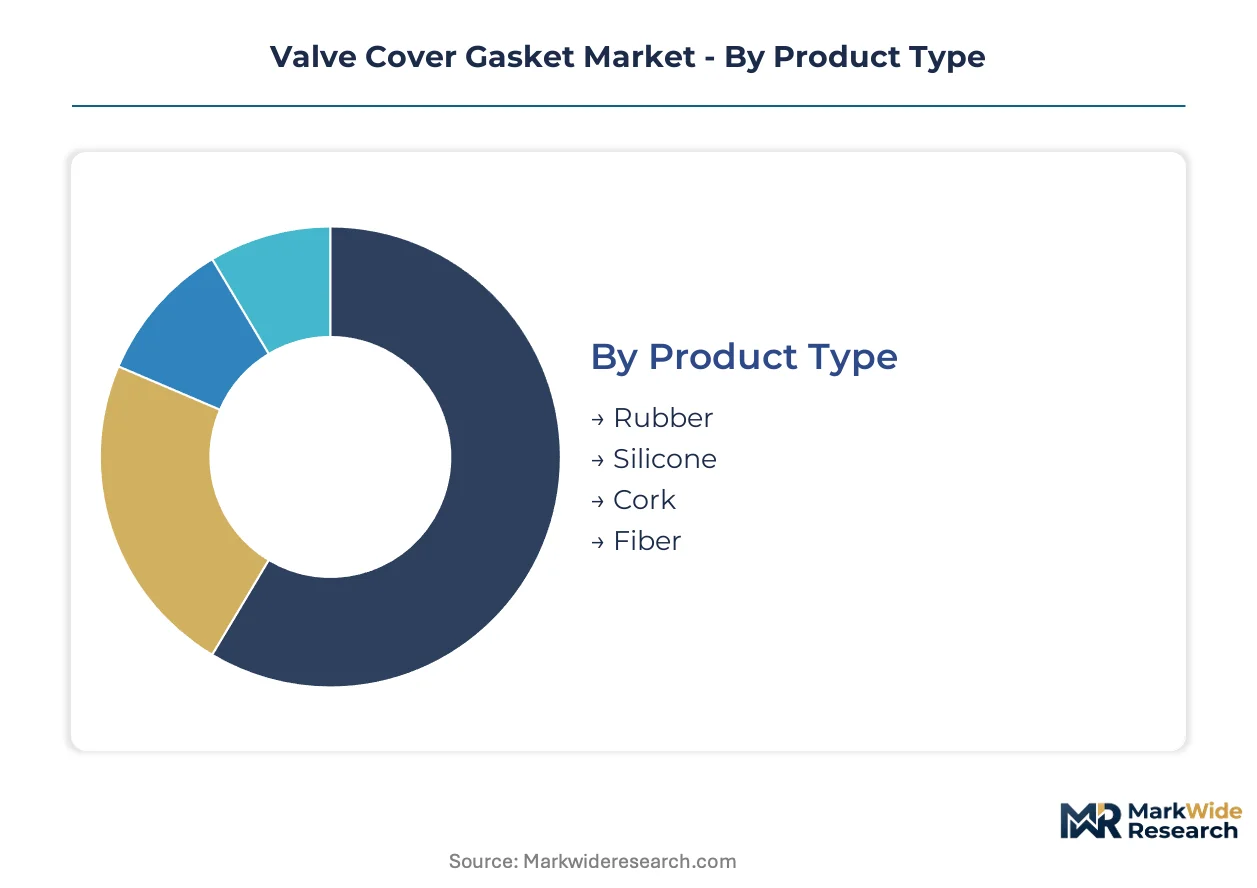
Valve cover gasket procurement splits across material chemistry, channel structure, and powertrain architecture. Specification divergence between thermal-resistant silicone for turbocharged gasoline engines and cost-optimized rubber for aging vehicle parc maintenance creates distinct margin pools within each segment category.
Product Type:
Material selection tracks the customization-standardization spectrum from commodity rubber compounds to application-specific silicone formulations validated for extreme thermal cycling.
- Silicone:Peroxide-cured silicone elastomers withstand sustained operating temperatures above 200°C in turbocharged direct-injection engines. Demand concentrates among German OEMs specifying extended service intervals and EPA evaporative emissions compliance for gasoline platforms.
- Rubber:Nitrile and fluorocarbon rubber compounds dominate cost-sensitive aftermarket channels with adequate performance for naturally aspirated engines below 150°C thermal load. Volume concentrates in China's eastern manufacturing corridor where domestic tier suppliers localize compound sourcing for aging vehicle parc maintenance.
- Cork:Compressed cork composite with synthetic rubber binder serves vintage vehicle restoration and developing-market commercial vehicle segments where specification tolerance permits lower unit costs.
- Fiber:Aramid fiber reinforcement bound with nitrile or silicone elastomer delivers dimensional stability for high-compression cylinder head interfaces in heavy-duty diesel applications.
Leading the category by volume: Rubber. Expanding most quickly: Silicone.
End User:
Channel concentration varies by margin capture potential, with OEM assembly contracts demanding thermal validation investment and aftermarket distributors prioritizing inventory velocity.
- OEMs:Original equipment manufacturers specify compound grades through multi-year platform supply agreements with integrated thermal-aging test protocols. Volkswagen Group, Stellantis, and Geely procurement desks unbundle aftermarket service parts from OE assembly contracts, forcing separate commercial negotiations.
- Aftermarket Providers:Independent distributors and private-label suppliers aggregate demand across aging vehicle parc in North America and Europe, sourcing rubber formulations through Asian compounders to maintain price competitiveness.
- Repair Shops:Workshop-level procurement increasingly flows through digital platform aggregators in Germany and China, bypassing traditional tier-one distribution networks.
- Distributors:Regional warehousing specialists manage inventory for fiber-composite and cork variants where demand fragmentation prevents direct mill sourcing.
Dominant by revenue: OEMs. Gaining share fastest: Aftermarket Providers.
Vehicle Type:
Powertrain architecture determines thermal specification requirements, with internal combustion platforms sustaining traditional sealing demand while electric vehicle adoption fragments the segment map.
- Passenger Cars:Downsized turbocharged gasoline engines in premium and mass-market segments specify silicone grades for 200°C+ thermal stress. China's domestic brands in Jiangsu and Zhejiang provinces localize procurement for compact and mid-size platforms.
- Commercial Vehicles:Medium and heavy-duty diesel fleets in India's Maharashtra and Tamil Nadu states generate replacement demand for fiber-reinforced rubber gaskets as state transport corporations extend service intervals.
- Motorcycles:Small-displacement single and twin-cylinder engines in Southeast Asian markets utilize cork and basic rubber compounds where cost minimization overrides thermal performance.
- Electric Vehicles:Battery electric architectures eliminate traditional valve train sealing entirely, though adjacent demand emerges for power electronics housing and coolant manifold seals using compression-set resistant elastomers.
Highest volume concentration: Passenger Cars. Steepest demand decline: Electric Vehicles (for traditional valve cover applications).
Installation Type:
Installation configuration reflects the standardization-customization tension between mass-production assembly line efficiency and specialized repair scenarios.
- Standard:Pre-formed gasket kits designed for specific engine families dominate OEM assembly and routine maintenance, with dimensional tolerances validated to SAE J20 and GB/T protocols.
- Custom:Application-specific silicone formulations and multi-layer steel hybrids serve high-performance and racing engine builds requiring non-standard compression ratios and thermal profiles.
- Remanufactured:Reclaimed core gaskets with refreshed elastomer surfaces address price-sensitive fleet maintenance in commercial vehicle segments.
- Reusable:Metal-core silicone bonded gaskets with engineered recovery properties support service-interval extension strategies in premium vehicle segments.
Standard installation commands volume leadership. Custom specification shows fastest value growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's eastern manufacturing corridor concentrates the dominant share of valve cover gasket procurement, with domestic OEMs and tier suppliers localizing compound sourcing to reduce logistics costs and capture state-led automotive cluster incentives.
China
Jiangsu and Zhejiang provinces anchor silicone and rubber gasket production through integrated rubber-molding and metal-stamping clusters serving domestic OEMs. MIIT new-energy vehicle mandates redirect supplier investment toward battery enclosure sealing as traditional engine demand plateaus. Domestic brands in the Yangtze River Delta localize procurement for compact and mid-size passenger car platforms.
United States
EPA evaporative emissions enforcement and NHTSA corporate average fuel economy standards mandate premium silicone grades for gasoline direct injection platforms. The Southeast automotive corridor spanning Tennessee and South Carolina concentrates assembly plant demand for thermal-resistant formulations. Aftermarket distributors serve aging vehicle parc across the Midwest and Sun Belt states.
Germany
Volkswagen Group and Stellantis procurement desks unbundle aftermarket service parts from original equipment supply agreements, forcing separate commercial negotiations. ECHA REACH aromatic oil restrictions and F-Gas Regulation phasing constrain compound formulation choices. Bavaria and Baden-Württemberg host thermal-aging test protocol specialists with finite element analysis capabilities for multi-material gasket stacks.
India
Maharashtra and Tamil Nadu generate replacement demand for fiber-reinforced rubber gaskets as state transport corporations extend commercial vehicle service intervals. BIS certification requirements and DGFT import regulations shape local sourcing patterns. The Chennai-Bengaluru industrial corridor attracts compounders seeking to serve both domestic aftermarket and export assembly programs.
Japan
METI industrial standards and JIS certification protocols govern precision fiber-composite stamping for Asian OEM programs. The Aichi prefecture cluster around Nagoya concentrates metal-forming specialists with elastomer bonding capabilities. Domestic suppliers face margin pressure as procurement centralizes among mega-OEMs with consolidated specification authority.
Valve Cover Gasket Market Vendor Landscape
Capacity expansion dominates the current landscape as compounders invest in thermal-aging test cells to meet divergent SAE J20 and GB/T certification requirements. The vendor base stratifies across three tiers: integrated foundry-to-seal operators with captive rubber-molding, precision fiber-composite specialists serving Asian OEM programs, and aftermarket-focused compounders sourcing through Asian distributors. Geographic expansion and portfolio diversification toward battery thermal management seals represent the dominant competitive moves as powertrain electrification fragments traditional demand.
Among European integrated seal manufacturers, ElringKlinger AG and Mahle GmbH occupy positions exemplifying compound formulation expertise and volume supply integration respectively. NOK Corporation anchors the precision stamping archetype for Asian OEM validation programs. These three entities represent distinct strategic postures: thermal-resistant silicone premium positioning, foundry-to-seal operational scale, and fiber-composite innovation for high-compression cylinder head interfaces.
| Leading Market Players |
|---|
| Dana Incorporated |
| ElringKlinger AG |
| Mahle GmbH |
| Federal-Mogul Motorparts |
| Freudenberg Sealing Technologies |
| NOK Corporation |
| Tenneco Inc. |
| Toyoda Gosei Co., Ltd. |
| Hutchinson SA |
| Others |
Supply Flow & Price Mechanics
Compound formulation specialists in Germany's thermal-aging test corridor command wage premiums that widen the spread between silicone gasket tiers and commodity rubber alternatives. Labor-cost differentials between Bavarian validation engineers and Jiangsu molders create a three-tier pricing structure across premium, standard, and economy levels.
Pricing Analysis
Warranty bundling separates OEM assembly contracts from aftermarket service parts, with Volkswagen Group and Stellantis procurement desks now negotiating these channels independently. Pricing stratifies across premium silicone grades validated to SAE J20, mid-tier fiber-composite formulations, and economy rubber compounds sourced through Asian distributors. Cost compression in the aftermarket tier intensifies because digital platform aggregators in Germany and China disintermediate traditional distribution markups. Aftermarket providers exhibit highest price sensitivity, while OEMs prioritize thermal validation investment over unit cost.
Supply Chain Analysis
Freight costs from Jiangsu and Zhejiang provinces to European assembly plants compress margins on rubber formulations not produced locally. Supply concentrates in China, Germany, and the Czech Republic, with methyl chloride and silicon metal feedstock drawing from East Asian chemical complexes. Single-source vulnerability concentrates in Japanese precision fiber-composite stamping capacity. Distribution runs through tier-one seal suppliers with captive rubber-molding operations, though aftermarket channels increasingly source directly from Asian compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market has become a vertical-integration race as compounders pursue upstream control over silicone polymer synthesis to escape methyl chloride price volatility and capture specification-driven premium positioning.
For Market Incumbents: Anchor thermal-aging test protocol capabilities in Germany and Japan to defend against emerging Asian compounders with GB/T certification acceleration. Backward integration into silicon metal sourcing mitigates raw material volatility, while captive supply of peroxide-cured silicone grades protects margin pools from Korean and Chinese volume entrants. For New Entrants and Emerging Players: Aftermarket platform aggregators represent the most penetrable channel entry point, particularly in India's Maharashtra and Tamil Nadu commercial vehicle corridors. White-space exists in battery thermal management sealing for electric vehicle power electronics housings, where compression-set resistant elastomer specifications overlap with existing automotive thermal validation capabilities. Pursue direct-to-workshop digital distribution partnerships to bypass incumbent tier-one networks. For Investors and Strategic Acquirers: Re-rating potential sits with integrated foundry-to-seal operators given OEM procurement consolidation and unbundling of aftermarket service parts. Long-term viability over the next decade hinges on portfolio diversification toward battery enclosure and coolant manifold seals as internal combustion demand fragments. Monitor MIIT new-energy vehicle mandate acceleration as the inflection signal for traditional valve cover gasket demand erosion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicone Polymer Synthesis | Captive supply of methyl chloride derivatives insulates margins from feedstock volatility affecting Asian compounders. |
| GB/T Certification Investment | Dual validation to Chinese domestic standards accelerates qualification timelines for Jiangsu and Zhejiang OEM programs. |
| Battery Thermal Management Seal Development | Adjacent specification opportunities in power electronics housings offset declining valve train demand from electric vehicle adoption. |
| Aftermarket Platform Partnership | Direct-to-workshop digital channels in Germany and China capture replacement demand outside traditional tier-one distribution. |
| Multi-layer Steel-Silicone Hybrid Production | Metal-forming capabilities with elastomer bonding address high-specific-output engine specifications decentralizing from captive rubber molders. |
Methodological Framework
Document review covered customs trade data, SEC filings from automotive tier-one suppliers, vehicle production databases, and IHS Markit registration data, complemented by interviews with OEM platform engineers, Tier 1 procurement leads, aftermarket distributors, thermal-aging test protocol specialists, and compound formulation chemists. Bottom-up triangulation validated against top-down market sizing from rubber-molding capacity assessments and silicone polymer feedstock demand tracking.
Segmentation outputs across material chemistry, channel structure, powertrain architecture, and installation type were modeled over the projection horizon. CAGRs derived from vehicle parc aging curves, turbocharger penetration rates, and electric vehicle adoption scenarios. Forecast inputs incorporated EPA evaporative emissions enforcement stringency and MIIT new-energy vehicle mandate trajectories.
Caveats apply where raw material volatility, powertrain electrification acceleration, or regulatory deadline shifts could materially shift the outlook. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Valve Remote Control System Market
Valves
Orifice Reducers Market
Valves
Global Pressure Relief Valves Market
Valves
Instrumentation Valves and Fittings Market
Valves
Choke and Kill Manifold Market
Valves
Pipeline Pigging Equipment Market
Valves
Middle East and Africa Machined Seals Market
Valves
Motorized Valves Market
Valves
Asia Pacific Pipeline Maintenance Market
Valves
Railway Emergency Valves Market
Valves
Flanges Market
Valves
Electro Pneumatic Positioner Market
Valves
Valve Grinder Market
Valves
Sanitary Valves Market
Valves
North America Residential Ball Valves Market
Valves
Global Valves Market