
 Degassing Valves Market | 2026-2036
Degassing Valves Market Size, Share, and Industry Trends Forecast 2026-2036
Degassing Valves Market Outlook
Modular valve-and-film bundling is restructuring how roasters and co-packers specify packaging systems. Goglio S.p.A. leverages its integrated film-and-valve platform to control specification conversations with European coffee brands. Wipf AG sustains dominance in high-barrier laminates through proprietary welding chemistry that anchors valve performance across humidity extremes. Fres-co System USA, Inc. competes on North American service density, positioning regional technical support as a counterweight to overseas manufacturing scale.
Degassing valves are one-way pressure-relief devices, typically injection-molded from food-grade polyethylene or polypropylene with silicone membranes rated for 0.5–2.0 bar cracking pressure, designed to release carbon dioxide from freshly roasted coffee while blocking oxygen ingress. Pneumatic valves lead unit volume due to compatibility with high-speed form-fill-seal lines, though electric valves are gaining share where IoT-enabled pressure monitoring creates service revenue pools. Food & Beverage applications dominate value capture, while Pharmaceutical end-use demands cleanroom-validated variants that command premium positioning through compliance complexity rather than volume.
FDA food-contact regulations and EU REACH compliance frameworks shape material selection and migration testing protocols for valve components destined for consumable goods. Germany's LFGB and the broader EU Packaging and Packaging Waste Regulation are accelerating design shifts toward recyclable mono-material constructions that eliminate multi-layer barriers. Stakeholders must monitor how California's SB 54 implementation and pending EPA per- and polyfluoroalkyl substance restrictions alter substrate availability and force reformulation timelines across the valve supply base.
Market Dynamics
Roast-to-retail freshness mandates are compressing specification cycles across coffee packaging equipment, forcing valve suppliers to synchronize development timelines with OEM form-fill-seal line upgrades rather than discrete component replacement schedules.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Mono-material compatibility requirements are accelerating valve redesigns that eliminate multi-layer barrier films, creating specification windows for compliant suppliers.
- IoT-enabled pressure monitoring:Electric valves with embedded sensors are generating recurring service revenue streams that extend customer lifetime value beyond hardware margins.
- Brazil and Colombia coffee clusters:Roast-to-retail integration in South American origin markets is embedding degassing valves earlier in supply chains, expanding addressable equipment retrofits.
Market Restraints
- Silicone membrane feedstock concentration:Medical-grade silicone supply chains concentrate in East Asian specialty chemical producers, exposing valve manufacturers to input volatility and qualification delays.
- Cleanroom validation costs:Pharmaceutical-grade variants require ISO 14644-1 Class 7 facility investment that locks out mid-scale converters from premium positioning.
- Welding chemistry IP fragmentation:Proprietary film-to-valve adhesion patents held by laminate specialists create licensing friction for independent valve producers seeking high-barrier applications.
Strategic Opportunities
- California SB 54 implementation:Extended producer responsibility mandates are creating first-mover advantage for valve suppliers with pre-certified recyclable mono-material constructions.
- Pharmaceutical cold-chain expansion:Biologic drug packaging demands pressure-relief functionality that coffee-optimized valves do not satisfy, opening cleanroom-validated product line extensions.
- Modular valve-and-film bundling:Integrated specification conversations with European roasters are shifting procurement from component sourcing to subsystem partnerships.
Industry Challenges
- Migration testing protocol divergence:FDA food-contact notification timelines and EU REACH substance evaluation operate on incompatible cadences, forcing parallel qualification tracks for multi-territory suppliers.
- Legacy form-fill-seal line retrofit compatibility:Pneumatic valve interfaces standardized in 1990s equipment generations constrain electric valve form factor innovation without customer line replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Degassing Valves Market |
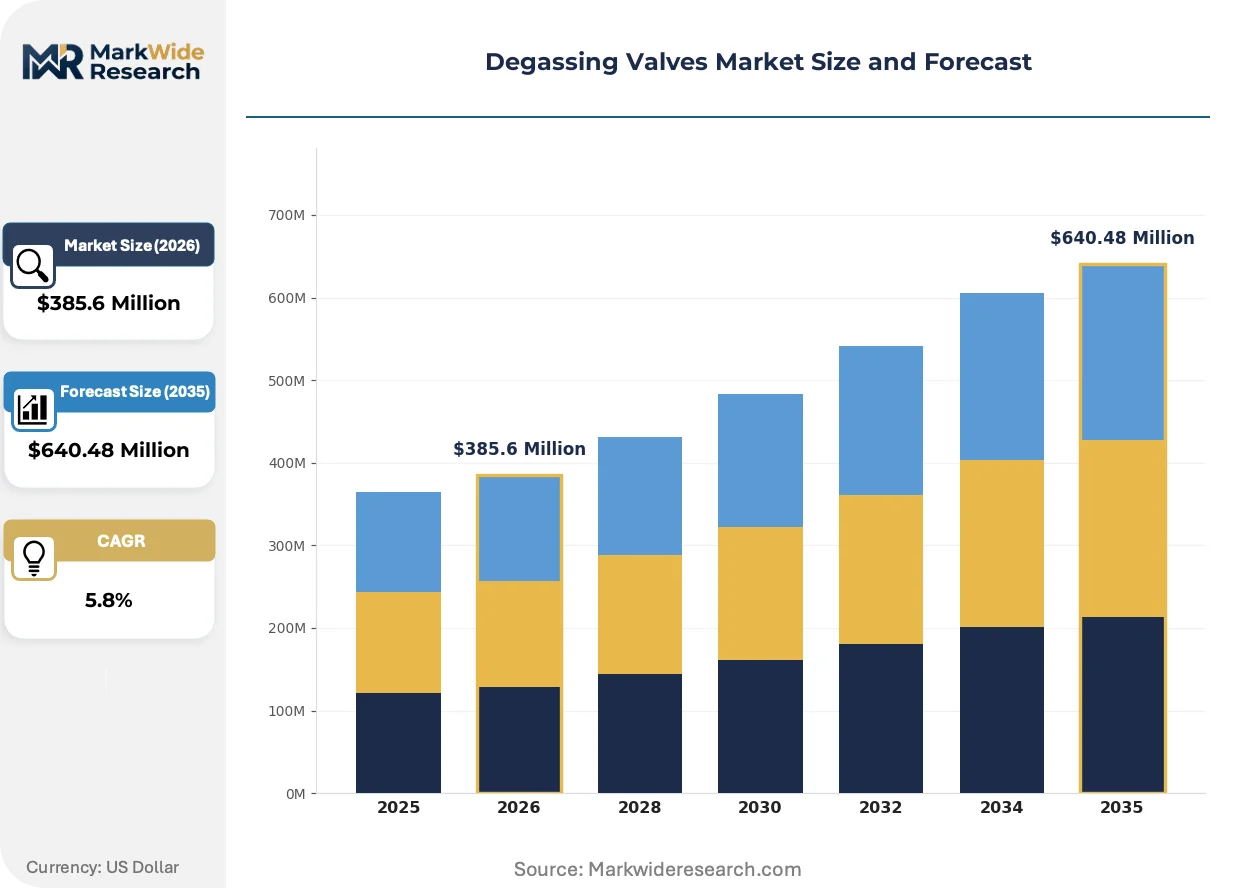
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $640.48 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Valves, Pneumatic Valves, Electric Valves, Vacuum Valves Industry Vertical: Food & Beverage, Pharmaceutical, Chemical Processing, Oil & Gas Installation Type: Inline Installation, Flanged Installation, Welded Installation, Threaded Installation End User: Manufacturers, Contractors, Distributors, Labs |
| Companies Covered | Goglio S.p.A., Wipf AG, Plitek LLC, CCL Industries Inc., Syntegon Technology GmbH, Fres-co System USA, Inc., TricorBraun, Valco Melton, Packaging Concepts & Designs, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Degassing Valves Market Strategic Shifts
Active integration of sensor-enabled hardware with packaging line control systems is redefining how valve performance is monitored, monetized, and maintained across the equipment lifecycle.
Smart valve architectures with embedded pressure transducers and wireless telemetry are integrating real-time CO2 release monitoring into roaster quality management systems. Mid-scale specialty coffee brands in Germany and the Netherlands are piloting these connected variants to document freshness claims with auditable data trails. This connectivity layer is integrating valve suppliers into ongoing service relationships that displace spot-component purchasing with subscription-based performance guarantees.
REACH substance restrictions on per- and polyfluoroalkyl substances are forcing reformulation of barrier coatings that historically enabled high-performance valve adhesion. The European Chemicals Agency's 2023 restriction proposal targets specific fluoropolymer chemistries common in premium laminate constructions. Coffee packaging converters serving EU markets are accelerating qualification of silicone-based alternatives that sacrifice some barrier performance for compliance certainty.
Specification authority is migrating from procurement departments to equipment engineering teams as valve-film-line integration complexity increases. Roasters operating automated filling equipment in Brazil and Germany now require valve suppliers to co-validate performance across complete packaging system configurations. This technical buying pattern concentrates supplier relationships with firms capable of joint development rather than catalog distribution.
Degassing Valves Market Segmentation
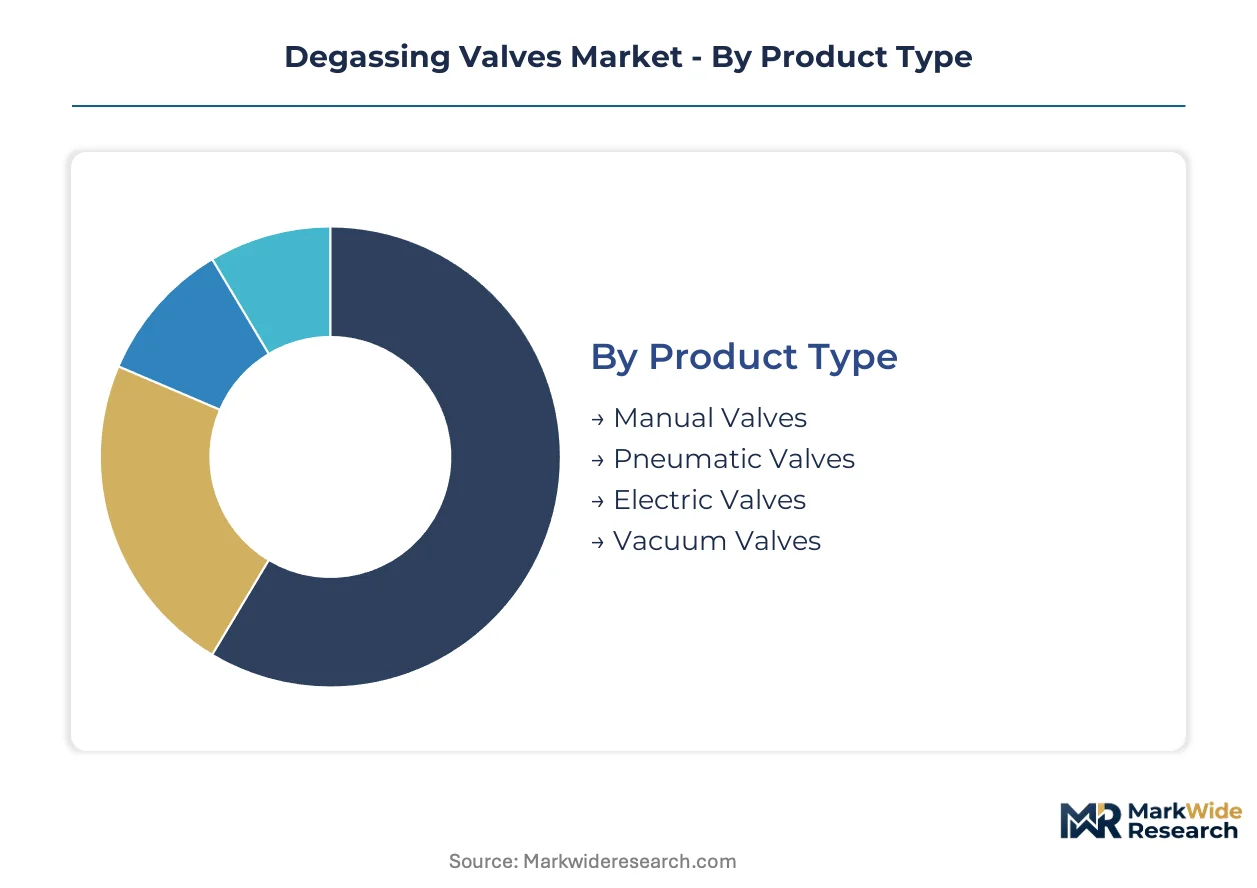
Valve specification authority varies sharply across product categories, with certification burdens and integration complexity determining supplier access. Understanding how technical requirements stratify by segment reveals where procurement power concentrates and which specifications command premium positioning.
Product Type:
FDA food-contact notification and EU REACH substance evaluation requirements apply differentially across valve actuation mechanisms, with pneumatic and electric variants facing distinct migration testing protocols.
- Pneumatic Valves:Compressed air-actuated mechanisms dominate high-speed form-fill-seal line integration in Brazil and Colombia coffee clusters. Roast-to-retail freshness mandates in São Paulo and Bogotá are accelerating specification cycles for these legacy-compatible variants.
- Electric Valves:Motor-driven actuation with embedded pressure transducers enables IoT-enabled CO2 release monitoring that German specialty roasters now pilot for freshness documentation. Embedded sensor architectures generate recurring service revenue pools beyond hardware margins.
- Manual Valves:Hand-operated mechanisms serve laboratory and small-batch roasting applications where automation investment does not justify capital deployment.
- Vacuum Valves:Negative pressure differential designs address pharmaceutical lyophilization and modified atmosphere packaging requiring sub-atmospheric pressure management.
Pneumatic variants sit at the top of the volume ranking, with electric configurations climbing the fastest.
Industry Vertical:
End-use applications stratify sharply by compliance burden, with pharmaceutical and food-contact pathways demanding divergent facility investments and qualification timelines.
- Food & Beverage:Coffee packaging dominates value capture, with Germany's precision engineering corridor supplying automated filling equipment to global roasters. EU Packaging and Packaging Waste Regulation pressure is forcing mono-material compatible valve redesigns that eliminate multi-layer barrier films.
- Pharmaceutical:Cleanroom-validated variants command premium positioning through ISO 14644-1 Class 7 facility requirements rather than volume scale. Biologic drug cold-chain expansion is opening pressure-relief functionality that coffee-optimized designs cannot satisfy.
- Chemical Processing:Corrosive media exposure demands fluoropolymer and stainless steel constructions with extended service intervals.
- Oil & Gas:Explosion-proof enclosures and high-pressure ratings characterize upstream and midstream deployment specifications.
Food & Beverage generates the highest absolute revenue, while Pharmaceutical applications yield the steepest margin expansion trajectory.
Installation Type:
Integration method selection determines welding chemistry requirements and the degree of film-to-valve adhesion IP licensing friction that converters encounter.
- Inline Installation:Direct pipeline integration suits continuous processing environments with standardized flange spacing. Chemical processing facilities in Germany favor these configurations for maintenance accessibility.
- Flanged Installation:Bolted connection standards enable rapid replacement in high-throughput coffee packaging lines where downtime carries freshness penalty costs.
- Welded Installation:Permanent fusion bonding creates hermetic seals for pharmaceutical and high-purity chemical applications where contamination risk must be eliminated.
- Threaded Installation:Screw-type mechanical connection supports field serviceability in remote oil and gas extraction sites.
Inline configurations dominate existing infrastructure retrofit demand, with welded alternatives gaining share fastest in greenfield pharmaceutical facility construction.
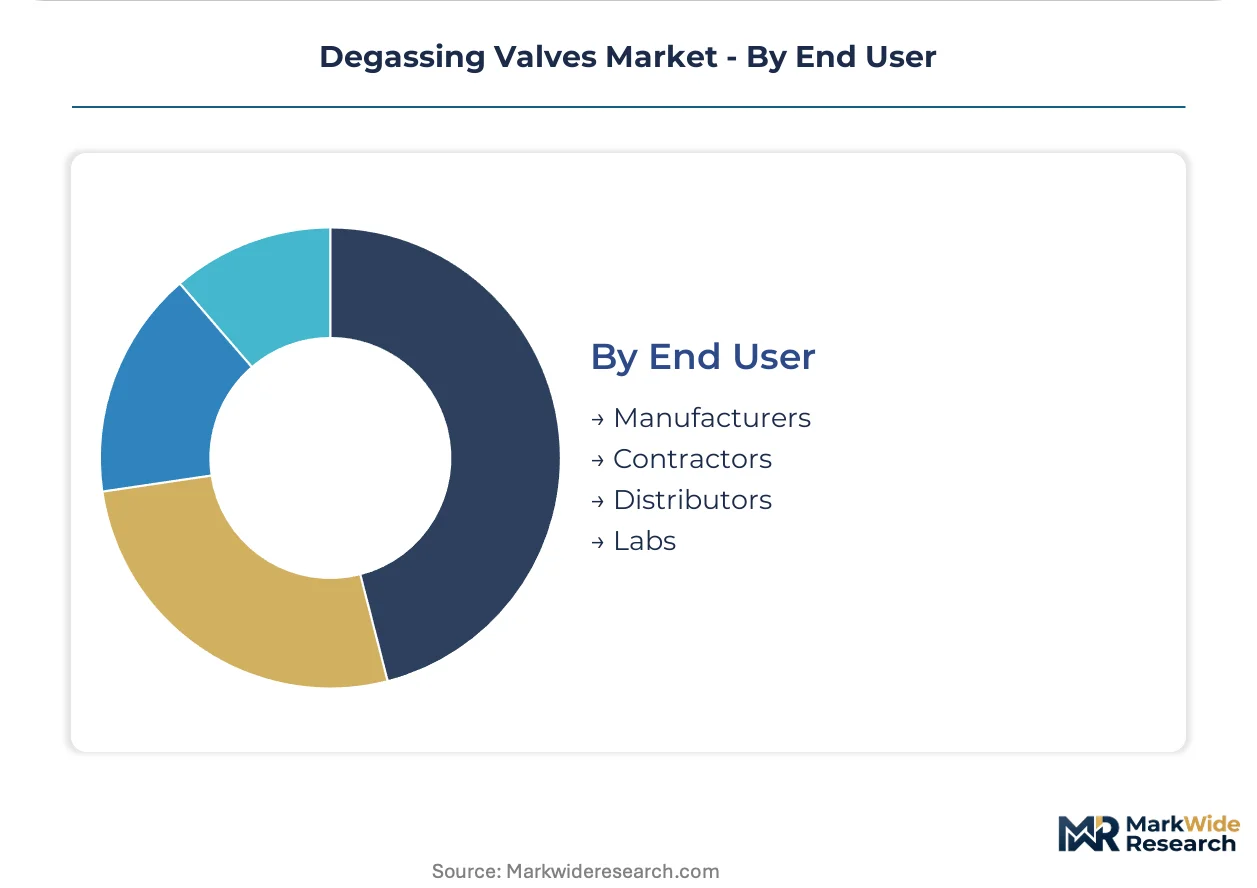
End User:
Procurement authority is migrating from purchasing departments to equipment engineering teams as valve-film-line integration complexity increases, with distributor and contractor roles restructuring accordingly.
- Manufacturers:Roasters and pharmaceutical packers with captive filling equipment now require joint development relationships rather than catalog distribution. Brazilian coffee processors are embedding valve specification earlier in supply chain integration.
- Contractors:System integrators and packaging line builders specify valves as subassembly components within turnkey equipment deliveries.
- Distributors:Inventory-positioning intermediaries face margin compression as direct OEM relationships displace spot-component purchasing.
- Labs:Research and quality control facilities drive small-lot demand for validation and pilot-scale testing.
Manufacturers control the largest procurement volume, with contractor influence expanding most quickly as specification authority consolidates with equipment engineering teams.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Degassing valve manufacturing originated in European precision engineering corridors during the 1980s coffee packaging automation wave. Germany's industrial machinery sector pioneered the first pneumatic valve designs for high-speed form-fill-seal integration. Today production concentrates across four continental manufacturing clusters.
Germany
Precision engineering OEMs in Stuttgart and Munich supply automated filling equipment to global coffee roasters. The EU Packaging and Packaging Waste Regulation accelerates mono-material compatible valve redesigns that eliminate multi-layer barrier films. Baden-Württemberg's machinery corridor hosts joint development programs between valve suppliers and form-fill-seal manufacturers.
United States
Specialty coffee roasting clusters in Seattle and Portland drive demand for IoT-enabled electric valves with embedded pressure monitoring. California's SB 54 extended producer responsibility mandates create first-mover certification windows for recyclable mono-material constructions. Fres-co System USA anchors regional technical support networks as a counterweight to overseas manufacturing scale.
Brazil
São Paulo's roast-to-retail integration embeds degassing valves earlier in supply chains than traditional export models. ANVISA food-contact regulations govern silicone membrane migration testing for domestic packaging. Coffee processing equipment retrofits in Minas Gerais and Espírito Santo expand addressable valve installations beyond greenfield facilities.
Colombia
Bogotá's specialty coffee cluster tightens freshness standards from origin to retail shelf. The national coffee growers federation promotes packaging automation that incorporates one-way valve technology. Antioquia and Caldas departments see expanding equipment retrofit demand as small-batch roasters scale operations.
China
Medical-grade silicone membrane supply chains concentrate in Guangdong and Jiangsu specialty chemical zones. NMPA food-contact notification timelines operate on cadences incompatible with EU REACH substance evaluations. Yangtze River Delta packaging machinery manufacturers serve as contract fabrication partners for European valve designers seeking cost optimization.
Degassing Valves Market Competitive Environment
The competitive structure tilts toward integrated subsystem suppliers over standalone component vendors. Market concentration remains moderate with tiered specialization across film-and-valve bundlers, pneumatic mechanism specialists, and electric sensor-enabled innovators. Strategic archetypes include integrated packaging platform operators, high-barrier laminate chemists, and regional service-density competitors. Dominant competitive moves encompass modular subsystem partnerships and proprietary welding chemistry licensing arrangements.
Among European integrated platform operators, Goglio S.p.A. and Wipf AG exemplify contrasting archetypes: the former represents film-and-valve bundling control over specification conversations, while the latter anchors high-barrier laminate dominance through proprietary adhesion chemistry. Syntegon Technology GmbH occupies a position within German precision engineering corridors where OEM equipment integration determines valve procurement authority. These three entities collectively illustrate how specification power migrates from catalog distribution toward joint development relationships with automated filling equipment operators.
| Leading Market Players |
|---|
| Goglio S.p.A. |
| Wipf AG |
| Plitek LLC |
| CCL Industries Inc. |
| Syntegon Technology GmbH |
| Fres-co System USA, Inc. |
| TricorBraun |
| Valco Melton |
| Packaging Concepts & Designs |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap specialists in Germany's precision engineering corridor maintain pricing discipline through captive control over silicone membrane welding chemistry, insulating high-barrier laminate tiers from commodity cost swings while pressuring independent valve producers into royalty-bearing adhesion licenses.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments buyers by certification burden and after-sales service bundling. Pharmaceutical-grade ISO 14644-1 Class 7 validated variants command the widest spreads due to cleanroom facility amortization, while Brazilian coffee processors show acute price sensitivity in pneumatic valve retrofits. Cost compression in standard-tier pneumatic mechanisms is intensifying because Yangtze River Delta contract fabricators are absorbing margin to secure European design partnerships.
Supply Chain Analysis
Single-source vulnerability sits with East Asian medical-grade silicone membrane producers concentrated in Guangdong and Jiangsu specialty chemical zones. Valve manufacturing draws from German precision machining, Chinese contract fabrication, and Italian film extrusion as core inputs. Tariff exposure on fluoropolymer barrier coatings threatens laminate cost structures as REACH substance restrictions accelerate. Distribution runs through OEM equipment bundlers rather than independent component distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as roast-to-retail freshness mandates in São Paulo and Bogotá shift procurement authority toward equipment engineering teams specifying joint-development partnerships over catalog purchasing.
For Market Incumbents: Extend proprietary welding chemistry licensing networks to lock out independent valve producers from high-barrier coffee applications threatened by REACH fluoropolymer restrictions. Deepen backward integration into medical-grade silicone membrane supply through offtake agreements with Jiangsu specialty chemical producers, securing input priority during qualification delays. For New Entrants and Emerging Players: Mid-scale specialty roasters in the Netherlands piloting IoT-enabled electric valves represent the most penetrable buyer archetype for sensor-enabled freshness documentation subscriptions. Target this segment with wireless telemetry integration services that displace spot-component purchasing, leveraging regional technical support density as a counterweight to established manufacturing scale. For Investors and Strategic Acquirers: Valuations sit cheapest among regional service-density competitors lacking integrated film-and-valve platforms but commanding localized technical support relationships. Long-term viability favors acquisition of electric valve specialists with embedded sensor architectures serving pharmaceutical cold-chain expansion. Watch FDA-EU migration testing protocol divergence as the inflection signal forcing parallel qualification investment that concentrates supplier relationships.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Valve Redesign | EU Packaging and Packaging Waste Regulation compliance secures specification windows with European roasters. |
| IoT Sensor Integration | Embedded pressure transducers enable recurring service revenue pools beyond hardware margins for German specialty brands. |
| Silicone Membrane Supply Security | Medical-grade feedstock offtake agreements with Guangdong producers mitigate East Asian concentration risk. |
| Cleanroom Facility Investment | ISO 14644-1 Class 7 validation unlocks pharmaceutical biologic drug packaging premium positioning. |
| Regional Technical Support Expansion | North American service density anchors Fres-co System USA's competitive position against overseas manufacturing scale. |
Study Parameters
Multiple input streams — primary interviews with valve procurement managers at Brazilian coffee processors, form-fill-seal OEM engineering directors, and pharmaceutical packaging quality leads; secondary validation against EU REACH substance filings, ANVISA food-contact notifications, and German machinery export data — were reconciled through bottom-up installation tracking and top-down laminate demand modeling.
Segment-level value outputs across the projection horizon triangulate pneumatic versus electric actuation mechanisms, pharmaceutical versus food-contact compliance tiers, and welded versus flanged installation methods. CAGRs were derived from equipment retrofit cycle analysis and greenfield facility investment patterns, with coffee roast-to-retail integration timelines and biologic cold-chain expansion serving as industry-specific demand anchors.
Underlying measurement precision varies by segment; pharmaceutical cleanroom-validated variants carry tighter precision than commodity pneumatic retrofits due to visible certification audit trails. Forecasts reflect assumptions on regulatory implementation cadence and silicone membrane supply continuity that could revise trajectories if EPA per- and polyfluoroalkyl substance restrictions accelerate or East Asian specialty chemical capacity tightens. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Global Valves in Chemical Market
Valves
Pinch Valve Market
Valves
Chemical Injection Metering Pumps and Valves Market
Valves
Air Vent Heads Market
Valves
Global Plug Valve Market
Valves
Valve Remote Control System Market
Valves
Asia Pacific Pipeline Maintenance Market
Valves
Blow - Off Valves Market
Valves
Transmission Overload Protectors Market
Valves
Reciprocating Compressor Components Market
Valves
Magnetic Coupler Market
Valves
Pipeline and Process Services Market
Valves
Global Check Valve Market
Valves
Top Drive Systems Market
Valves
Water Draw Off Valves Market
Valves
Cathodic Protection Market