
 Diaphragm Valve Market | 2026-2036
Diaphragm Valve Market Size, Share, and Industry Trends Forecast 2026-2036
Diaphragm Valve Market Analysis
Project finance for municipal water infrastructure is tilting competitive dynamics toward vendors with balance-sheet capacity to underwrite long-service contracts. GEMÜ Gebr. Müller Apparatebau leverages its Swabian manufacturing base to sustain premium positioning in pharmaceutical-grade applications. Christian Burkert GmbH & Co. KG anchors its growth in fluid control systems for hygienic processes, while ITT Inc. competes across diversified industrial end-uses with standardized product platforms.
A diaphragm valve employs a flexible membrane to isolate the operating mechanism from the process fluid, typically achieving bubble-tight shutoff with elastomer or PTFE diaphragms rated for temperatures from minus forty to two hundred degrees Celsius. Its primary purpose is to handle corrosive, abrasive, or sterile media without contamination risk in chemical processing and biopharmaceutical production. Pneumatic actuation variants command the largest installed base due to their compatibility with automated batch control systems, though electric actuation is gaining share in remote monitoring environments. Metal diaphragm configurations dominate high-pressure hydrocarbon service, while rubber and plastic materials capture cost-sensitive water treatment deployments where chemical resistance requirements are moderate.
The US FDA enforces Current Good Manufacturing Practice regulations that mandate validated cleaning protocols, directly stimulating replacement cycles in pharmaceutical diaphragm valve fleets. REACH compliance in Europe restricts certain elastomer chemistries, pushing manufacturers toward perfluoroelastomer and thermoplastic alternatives with superior extraction profiles. China's NMPA alignment with PIC/S standards is tightening import certification requirements for sterile process equipment. Stakeholders must monitor how evolving purity standards across these three regulatory spheres reshape material qualification timelines and supplier qualification burdens.
Market Dynamics
Pharmaceutical-grade purity mandates are compressing replacement cycles across installed valve fleets, forcing facility operators to prioritize validated cleaning protocols over extended asset life. This regulatory pressure is redistributing procurement budgets toward diaphragm configurations with superior extraction profiles and documented compliance trails.
Growth Catalysts
- Bioprocessing expansion:Cell and gene therapy manufacturing is scaling sterile fluid pathway requirements. Single-use bioreactor integration demands aseptic valve architectures with validated steam-in-place capability.
- REACH elastomer restrictions:ECHA's tightening limits on phthalate and nitrosamine content in sealing materials are accelerating perfluoroelastomer adoption. European pharmaceutical operators face material requalification deadlines that stimulate replacement demand.
- Water infrastructure renewal:Municipal treatment facilities in the United States are modernizing chemical dosing systems. Corrosion-resistant PTFE-lined diaphragm valves are displacing legacy gate valves in chloramine and fluoridation circuits.
Market Restraints
- Fluoropolymer feedstock concentration:Virgin PTFE resin supply concentrates among Japanese and Chinese chemical producers. Geopolitical friction threatens price stability for high-purity diaphragm materials.
- Precision casting capacity limits:Forged stainless steel valve bodies require investment-grade foundry capacity that clusters in Germany and northern Italy. Lead times for ASME-certified castings extend beyond eighteen months.
- Metal diaphragm substitution:Bellows-sealed globe valves from specialized metalworking shops capture share in high-pressure hydrocarbon service. These alternatives eliminate elastomer aging risks in refinery hydrogen units.
Strategic Opportunities
- Indian pharmaceutical manufacturing:CDSCO's alignment with PIC/S standards is upgrading domestic sterile processing infrastructure. Contract manufacturing organizations in Hyderabad and Ahmedabad require validated valve fleets for export compliance.
- Digital twin integration:Sensor-embedded diaphragm valves converging with predictive maintenance platforms enable condition-based replacement. This shifts revenue from hardware sales to performance-guaranteed service agreements.
- Green hydrogen electrolysis:Alkaline and PEM electrolyzer stacks demand chemically inert fluid isolation. High-purity water and potassium hydroxide circuits create specification openings for fluoropolymer-diaphragm architectures.
Industry Challenges
- Cleanroom-qualified welder scarcity:Orbital welding of autogenous tube-to-valve joints requires ASME IX-certified technicians. Pharmaceutical fabricators compete for limited labor pools in Basel, Boston, and Singapore.
- Legacy DCS integration friction:Modern electric actuators with EtherNet/IP or PROFINET interfaces must communicate with decades-old pneumatic control systems. Retrofit projects demand custom gateway engineering that extends commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diaphragm Valve Market |
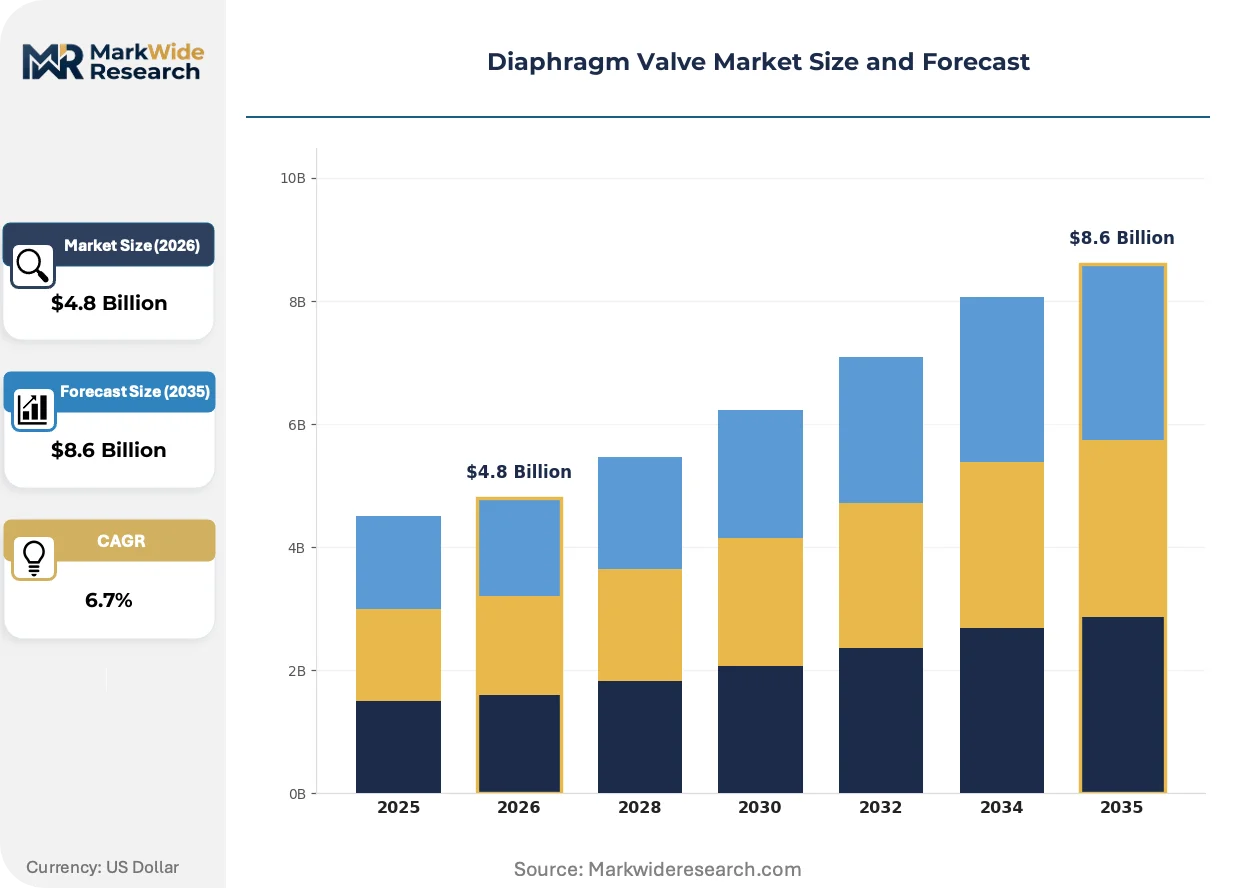
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual, Pneumatic, Electric, Hydraulic Material: Rubber, Metal, Plastic, Composite End User: Chemical, Water Treatment, Oil & Gas, Food & Beverage Application: Flow Control, Pressure Regulation, Isolation, Sampling |
| Companies Covered | GEMÜ Gebr. Müller Apparatebau GmbH & Co. KG, Nippon Daiya Valve Co. Ltd, ITT Inc., CRANE ChemPharma & Energy, Christian Burkert GmbH & Co. KG, Alfa Laval, Formatura Iniezione Polimeri S.p.A., Emerson, Flowserve, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diaphragm Valve Market Emerging Trajectories
Valve architecture is pivoting toward predictive intelligence and material traceability as pharmaceutical and chemical operators demand operational transparency. Three converging developments are compressing traditional specification cycles.
Smart diaphragm valves with integrated pressure and temperature sensors are migrating from pilot installations to standard pharmaceutical specifications. Biologics manufacturers in Switzerland and Massachusetts are specifying IO-Link enabled actuators for real-time seal-wear monitoring. This capability is migrating from premium custom builds to catalog-configurable platforms, collapsing the price premium for diagnostic-enabled hardware.
The FDA's enhanced emphasis on extractables and leachables testing under updated guidance documents is forcing material requalification across installed bases. Suppliers must now provide comprehensive migration data for elastomer compounds in contact with aqueous drug products. High-purity perfluoroelastomer diaphragms from specialized compounders are capturing specification share in parenteral filling lines.
Modular valve block architectures are displacing field-fabricated tube bends in bioprocessing skids. Pre-engineered valve manifolds with standardized face-seal connections reduce cleanroom welding hours and documentation burden. This configuration preference concentrates most visibly in single-use facility expansions across North Carolina and Bavaria.
Diaphragm Valve Market Segmentation
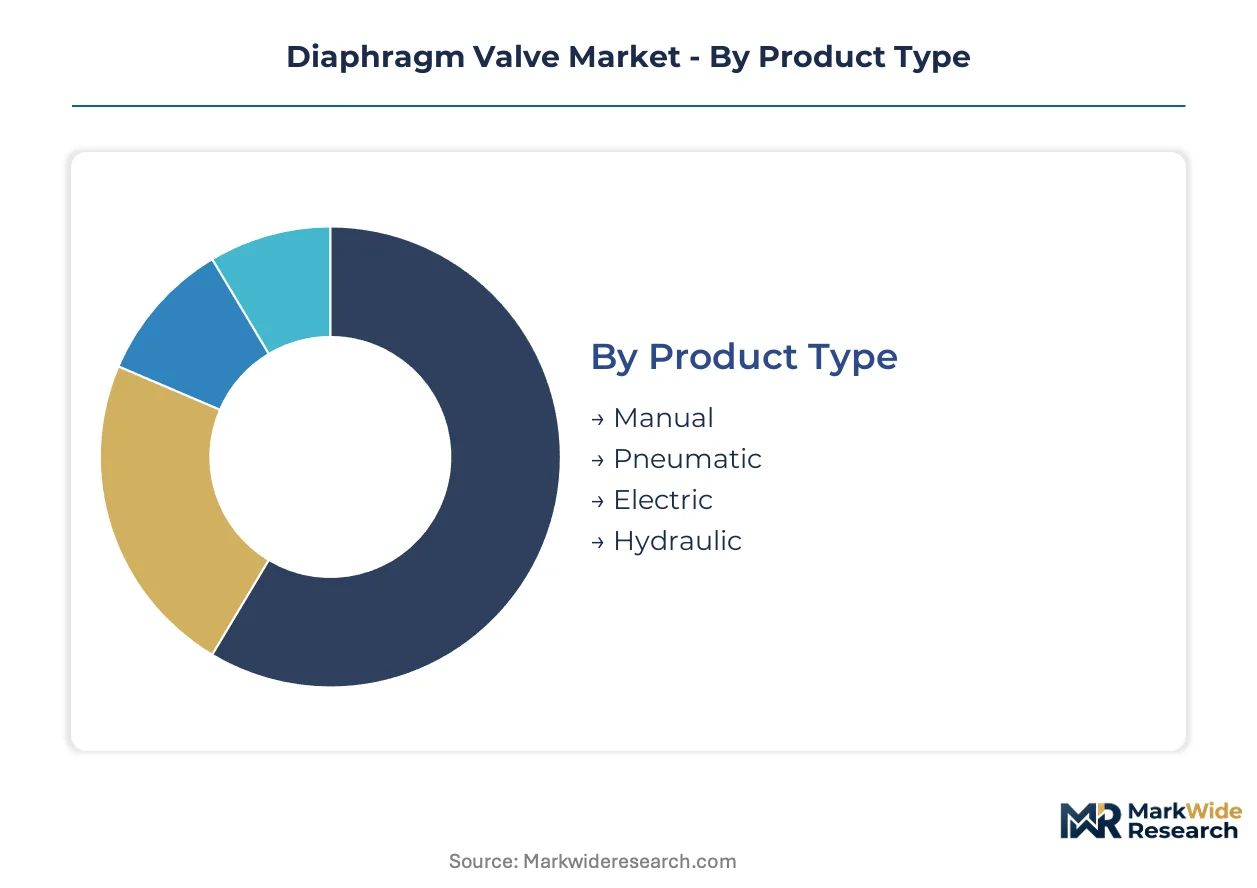
Diaphragm valve procurement patterns diverge sharply across actuation methods, material specifications, and end-use compliance regimes. Understanding these segmentation boundaries clarifies why pharmaceutical buyers prioritize validated perfluoroelastomer configurations while municipal water operators optimize for PTFE-lined economy grades.
Product Type:
Actuation architecture determines integration complexity with distributed control systems and total cost of ownership across facility lifecycles.
- Pneumatic:Compressed-air actuation dominates bioprocessing installations requiring rapid cycling and fail-safe positioning. Swiss and Massachusetts biologics manufacturers specify these variants for steam-in-place sterilization compatibility with automated batch protocols.
- Electric:Motor-driven actuators enable precise positioning feedback and remote diagnostics via industrial Ethernet. Water treatment facilities in Germany and California are retrofitting these for SCADA integration without pneumatic infrastructure.
- Manual:Handwheel-operated designs serve isolated sampling points and maintenance bypass loops where automation delivers minimal value.
- Hydraulic:High-force actuation handles slurry applications in mining tailings and heavy chemical processing where pneumatic pressure proves insufficient.
Pneumatic variants command the established base. The steepest expansion runs through electric actuation in digitally retrofitted infrastructure.
Material:
Diaphragm composition directly governs chemical resistance, extraction profiles, and regulatory qualification burdens.
- Rubber:EPDM and nitrile compounds serve cost-sensitive water treatment where chloramine resistance suffices. REACH restrictions on phthalate plasticizers are accelerating compound reformulation timelines for European municipal contracts.
- Metal:Stainless steel and hastelloy diaphragms withstand hydrogen embrittlement in refinery hydrocracker units. German fabricators in the Ruhr cluster specialize in ASME-certified forgings for these high-pressure hydrocarbon services.
- Plastic:Virgin PTFE and modified PTFE compounds achieve near-universal chemical inertness. Japanese resin suppliers concentrate feedstock supply for pharmaceutical-grade specifications.
- Composite:Multi-layer elastomer-PTFE laminates balance resilience with extraction resistance in parenteral drug filling lines.
Rubber diaphragms retain volume leadership in water infrastructure. Composite architectures are climbing the fastest in pharmaceutical aseptic processing.
End User:
Industry-specific purity mandates and process hazards dictate specification intensity and replacement cycle frequency.
- Chemical:Corrosive media handling in chlor-alkali and specialty chemical production demands fluoropolymer-lined bodies with metal diaphragm options for high-temperature sulfuric acid service.
- Water Treatment:Municipal chlorination and fluoridation circuits favor PTFE-lined economy valves. US EPA compliance deadlines for lead service line replacement are stimulating chemical dosing system upgrades across Midwestern states.
- Oil & Gas:Sour gas processing and hydrogen units specify metal diaphragm configurations eliminating elastomer aging risks. Gulf Coast refineries prioritize NACE-compliant materials for hydrogen sulfide exposure.
- Food & Beverage:Hygienic design with FDA-compliant elastomers supports clean-in-place protocols. Dairy processors in Wisconsin and Bavaria specify 3A-certified sanitary configurations.
Chemical processing anchors material innovation investment. Food and beverage applications are expanding most quickly through craft brewery automation and plant-based protein facility construction.
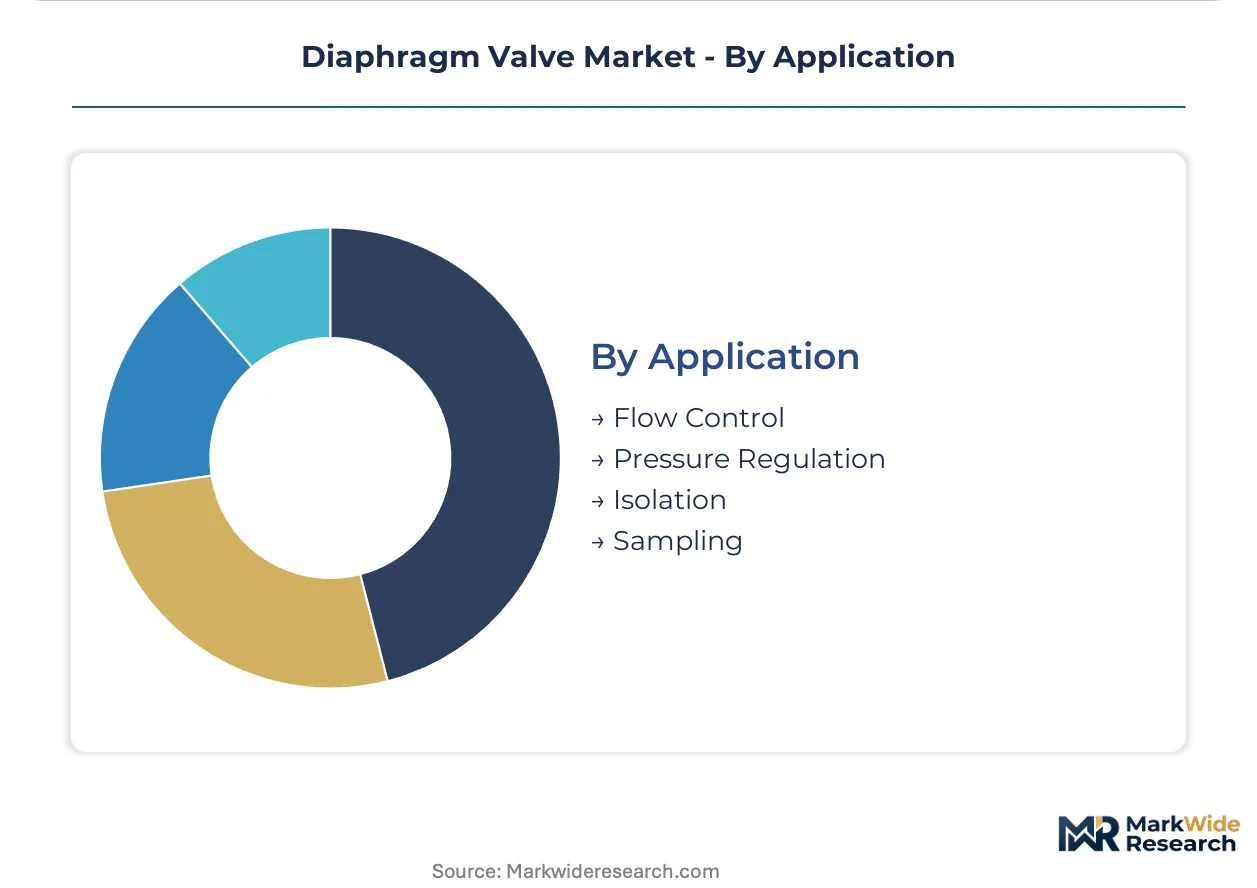
Application:
Functional role within fluid systems determines sealing integrity requirements and actuator precision specifications.
- Isolation:Bubble-tight shutoff capability separates process zones during maintenance or contamination events. Biopharmaceutical manufacturers in Singapore and Basel mandate validated seal integrity for multiproduct facility changeovers.
- Flow Control:Throttling accuracy matters in chemical dosing and blending operations. Pulp and paper mills in Finland deploy characterized diaphragm valves for bleach chemical ratio control.
- Pressure Regulation:Pilot-operated configurations maintain downstream pressure in gas distribution and reactor feed systems.
- Sampling:Representative extraction without process contamination supports quality control laboratories and environmental monitoring points.
Isolation functions dominate unit volume through safety system requirements. Flow control applications are gaining specification share fastest through precision chemical manufacturing expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in diaphragm valve trade reveal a structural surplus concentrated in precision-engineering economies, while pharmaceutical manufacturing hubs in Asia-Pacific and North America drive import intensity for validated aseptic configurations.
United States
FDA-enforced Current Good Manufacturing Practice upgrades are compressing replacement cycles across injectable drug facilities. The US EPA's lead service line replacement deadlines are accelerating municipal water infrastructure modernization. Boston and Research Triangle Park bioprocessing clusters are specifying steam-in-place capable valve architectures for cell therapy manufacturing expansion.
Germany
REACH elastomer restrictions are forcing perfluoroelastomer requalification across pharmaceutical installed bases. ECHA's nitrosamine limits are accelerating material substitution timelines for sealing compounds. The Swabian precision engineering belt around Stuttgart anchors global supply for ASME-certified stainless steel valve forgings serving high-purity applications.
China
NMPA alignment with PIC/S standards is tightening import certification requirements for sterile process equipment. Domestic biologics manufacturing expansion in Suzhou and Shanghai is creating specification demand for validated aseptic fluid pathways. State-backed electrolyzer deployment for green hydrogen is opening specification opportunities for fluoropolymer-diaphragm isolation valves.
India
CDSCO's PIC/S harmonization is upgrading contract manufacturing infrastructure for export compliance. Pharmaceutical clusters in Hyderabad and Ahmedabad are requalifying valve fleets to meet European and US regulatory standards. Domestic precision foundry capacity constraints are extending lead times for ASME-certified castings.
Switzerland
Swissmedic's stringent extractables and leachables requirements are driving perfluoroelastomer adoption in parenteral filling operations. The Basel biopharmaceutical manufacturing corridor is specifying IO-Link enabled smart valves for real-time seal-wear monitoring. Precision machining competence in the Jura arc sustains premium positioning for high-integrity metal diaphragm configurations.
Diaphragm Valve Market Vendor Landscape
On the supply side, the industry is bifurcated between consolidated precision-engineering specialists with captive forging capacity and fragmented regional fabricators serving cost-sensitive water infrastructure. German and Swiss family-owned enterprises anchor the premium tier through validated pharmaceutical-grade offerings, while diversified industrial conglomerates compete on standardized platform economics. Strategic archetypes include precision-forging specialists, fluid control system integrators, and diversified process equipment manufacturers. Competitive intensity centers on foundry capacity access and material qualification speed.
Among German precision-engineering specialists, GEMÜ Gebr. Müller Apparatebau GmbH & Co. KG and Christian Burkert GmbH & Co. KG exemplify the premium-tier archetype through Swabian manufacturing heritage. ITT Inc. represents the diversified industrial conglomerate model with standardized product platforms spanning multiple end-use verticals. These three anchors illustrate how competitive positioning stratifies across validation-intensive pharmaceutical applications versus cost-optimized municipal water deployments.
| Leading Market Players |
|---|
| GEMÜ Gebr. Müller Apparatebau GmbH & Co. KG |
| Nippon Daiya Valve Co. Ltd |
| ITT Inc. |
| CRANE ChemPharma & Energy |
| Christian Burkert GmbH & Co. KG |
| Alfa Laval |
| Formatura Iniezione Polimeri S.p.A. |
| Emerson |
| Flowserve |
| Others |
Supply Flow & Price Mechanics
The Swabian precision engineering belt around Stuttgart concentrates ASME-certified forging capacity for pharmaceutical-grade valve bodies, translating foundry scarcity into sustained pricing power for validated stainless steel configurations. This geographic concentration of investment-grade casting capability creates structural premiums for high-integrity metal diaphragm architectures while compressing margins for standardized water treatment variants.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the diaphragm valve market. Price differentiation centers on certification grade—FDA-validated perfluoroelastomer configurations command substantial premiums over PTFE-lined municipal grades—and geographic delivery cost from German versus Asian fabrication sources. Cost compression in economy-tier water treatment valves is intensifying because municipal procurement teams prioritize lowest-compliant-bid awards. Pharmaceutical operators exhibit the least price sensitivity due to regulatory replacement mandates, while municipal water authorities demonstrate acute sensitivity to upfront capital expenditure.
Supply Chain Analysis
Upstream virgin PTFE resin supply draws from Japanese and Chinese chemical producers, with perfluoroelastomer compounders in Germany and Switzerland adding specialized formulation value. Forged stainless steel valve bodies rest on precision foundry capacity clustering in Germany, northern Italy, and select Indian fabricators. Single-source vulnerability concentrates in high-purity fluoropolymer feedstock where geopolitical friction threatens material availability. Distribution runs through authorized fluid control system integrators serving pharmaceutical OEMs and direct municipal procurement channels for water infrastructure projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity pervades the diaphragm valve landscape as regulatory divergence across FDA, EMA, and NMPA jurisdictions creates specialized qualification niches that resist commoditization. This demand-side complexity rewards targeted capability investments over broad standardization plays.
For Market Incumbents: Harden material qualification speed as the primary defensive moat against emerging Asian fabricators achieving ISO certification. Captive forging capacity in the Swabian cluster should expand to eighteen-month forward coverage given ASME-certified casting lead time extension. Perfluoroelastomer backward integration into specialized compounding insulates margin position from Japanese resin supply volatility.
For New Entrants and Emerging Players: Pursue validated aseptic valve architectures for Indian pharmaceutical contract manufacturing organizations as the most penetrable white-space target. CDSCO's PIC/S alignment creates urgent requalification demand in Hyderabad and Ahmedabad clusters lacking domestic precision forging supply. A go-to-market angle emphasizing rapid material documentation and PIC/S-compliant validation packages distinguishes entrants from incumbent bureaucratic latency.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underperforming fluid control divisions lacking pharmaceutical-grade certification depth. Long-term viability favors specialists with demonstrated EMA and FDA material qualification track records over generalist water infrastructure suppliers facing municipal pricing compression. The signal to watch is NMPA import certification timeline acceleration indicating Chinese bioprocessing infrastructure upgrade intensity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluoropolymer Compounding | Captive perfluoroelastomer supply secures margin against Japanese resin price volatility. |
| ASME-Certified Foundry Capacity Expansion | Swabian forging investment extends pharmaceutical valve body supply security. |
| Smart Valve Digital Twin Integration | IO-Link sensor embedding shifts revenue toward performance-guaranteed service contracts. |
| Indian Pharmaceutical Validation Partnership | CDSCO-aligned documentation accelerates contract manufacturing organization fleet qualification. |
| Green Hydrogen Electrolyzer Specification Entry | Fluoropolymer-diaphragm architectures capture alkaline and PEM isolation valve demand. |
Methodological Framework
Initial hypotheses were tested against primary input from pharmaceutical plant engineers, municipal water procurement officers, fluid control system integrators, and precision foundry operations managers and refined through secondary validation against FDA warning letter databases, ECHA REACH restriction updates, SEC 10-K filings from listed industrial conglomerates, and customs trade flow records. Bottom-up triangulation across regional valve shipment volumes and top-down reconciliation against end-use capital expenditure patterns ensured analytical coherence.
Demand-supply-balance framing anchored the forecast framework across the analysis window, modeling actuation type, material specification, end-use industry, and regional regulatory cluster as core segmentation dimensions. CAGRs were derived from installed base replacement cycle analysis and greenfield facility investment pipelines. Industry-specific forecast inputs incorporated FDA CGMP enforcement intensity indices and municipal water infrastructure bond issuance trajectories.
Macroeconomic conditions sit as an overlay; deviation in interest rate environments affecting municipal project finance availability or pharmaceutical capital expenditure cycles would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory timeline adherence and material substitution elasticity. Cross-checking against ASME certification issuance rates and ECHA substance restriction proposal calendars is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Pneumatic Slide Gates Market
Valves
Flow Computer Market
Valves
Battery Pack Cooling Valve Actuator Systems Market
Valves
Pup Joint Market
Valves
Asia-Pacific Industrial Valves Market
Valves
Global Plastic Valves Market
Valves
North America High Voltage Switchgear Market
Valves
Degassing Valves Market
Valves
Global Valve Positioners Market
Valves
Manual Control Valve Market
Valves
Oil Drain Valves Market
Valves
Motorized Valves Market
Valves
Flanges Market
Valves
North America Industrial Valves Market
Valves
Expansion Valves Market
Valves
Emergency Shut Down Valves (ESDV) Market