
 Asia Pacific Pipeline Maintenance Market | 2026-2036
Asia Pacific Pipeline Maintenance Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Pipeline Maintenance Market Outlook
Japan's METI hydrogen blending roadmap is pivoting pipeline operators toward retrofit-compatible inspection protocols. China National Petroleum Corporation leverages its domestic manufacturing base to supply smart pigging equipment across Central Asian export routes. Sinopec anchors its maintenance strategy through in-house rehabilitation divisions serving the Sichuan shale gas network. Indian Oil Corporation competes on cost structure in the GAIL-operated national grid corridors.
Asia Pacific pipeline maintenance encompasses the technical preservation of steel and composite conduit systems through non-destructive evaluation, pressure-boundary restoration, and structural reinforcement, typically employing wall-thickness measurement tolerances of 0.1 millimeter for corrosion assessment to ensure hydrocarbon and utility fluid containment integrity. Ultrasonic Testing dominates the technology dimension due to its applicability in high-temperature crude environments where radiographic alternatives face operational constraints. Smart Pigs represent the fastest-expanding segment as operators pursue inline inspection of unpiggable lines through electromagnetic acoustic transducer advances. Predictive maintenance commands premium pricing in the Maintenance Type category where sensor-to-cloud architectures reduce unplanned shutdown frequency.
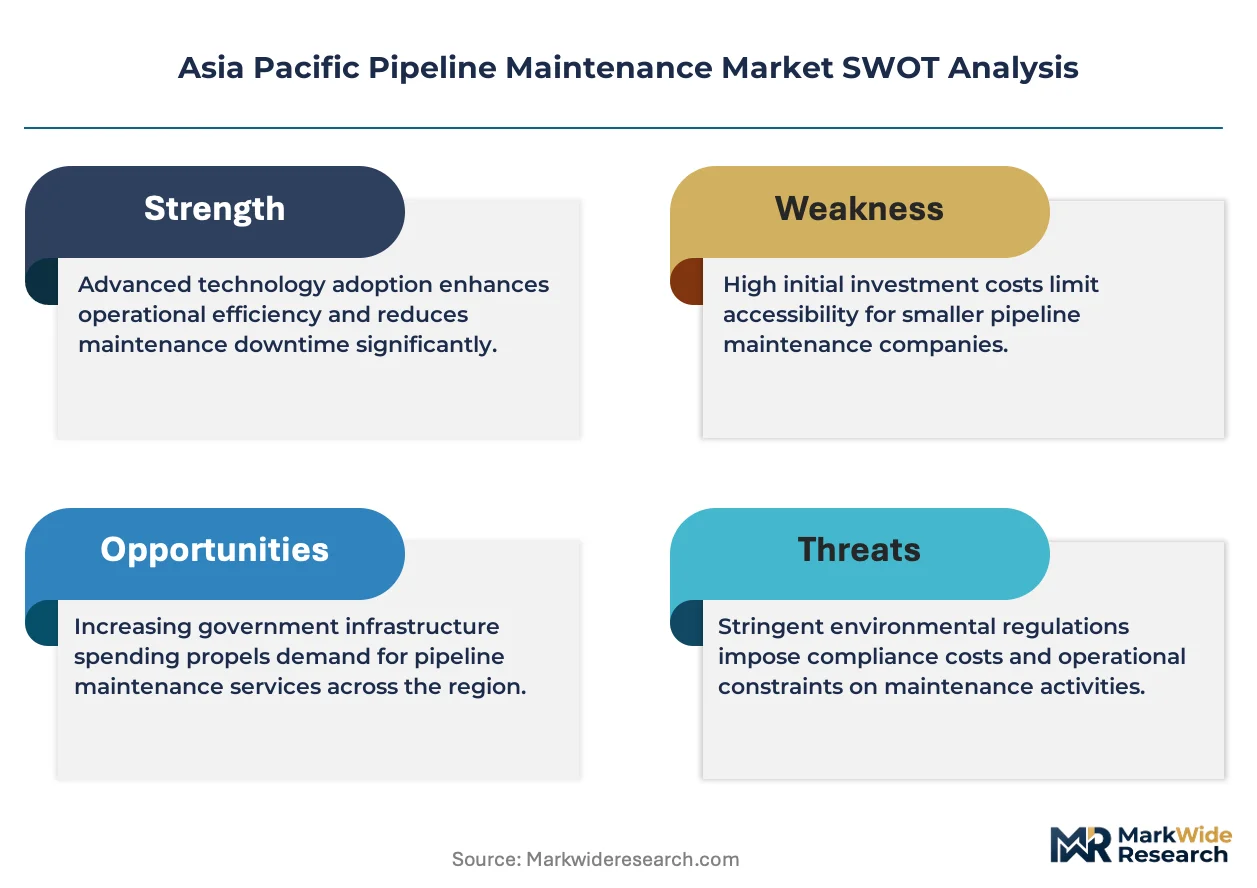
China's SAMR enforces GB standard compliance for pressure pipeline integrity management, while India's PESO mandates hydrostatic retesting intervals for cross-country petroleum lines. Australia's NOPSEMA imposes subsea pipeline inspection frequencies tied to corrosion risk models in the Bass Strait production zone. Stakeholders must evaluate technology transfer partnerships with Japanese NDT specialists before hydrogen infrastructure scale-up alters material degradation profiles.
Market Dynamics
Subsea infrastructure aging across Southeast Asia's gas corridors is forcing transmission operators into accelerated inspection cycles, compressing maintenance intervals from five-year to three-year windows while expanding corrosion monitoring contract scopes.
Growth Catalysts
- Offshore Gas Corridor Expansion:Indonesia's deepwater production fields require continuous wall-thickness monitoring as reservoir pressures decline and flow dynamics shift.
- GB Standard Pressure Compliance:China's SAMR mandates drive rehabilitation spending on legacy crude trunk lines crossing the Sichuan basin.
- Hydrogen Blending Trials:Japan's METI roadmap creates retrofit demand for embrittlement-resistant inspection protocols across existing natural gas networks.
Market Restraints
- Specialized Alloy Supply Concentration:High-grade corrosion-resistant cladding materials concentrate among Japanese and Korean metallurgical suppliers, creating input cost volatility.
- Unpiggable Line Technical Limitations:Tight-radius bends and low-flow segments in Australia's Bass Strait infrastructure block conventional smart pig deployment.
- Cross-Border Permit Friction:India's PESO hydrostatic retesting intervals impose operational shutdown windows that conflict with continuous delivery contracts.
Strategic Opportunities
- Central Asian Export Route Modernization:Kazakhstan-China crude corridors lack inline inspection coverage, creating white space for electromagnetic acoustic transducer deployment.
- Sensor-to-Cloud Convergence:Fiber-optic distributed acoustic sensing paired with edge computing enables real-time leak detection without pipeline shutdown.
- Australian NOPSEMA Subsea Mandates:Risk-model inspection frequencies in the Bass Strait production zone expand specialized diving contractor demand.
Industry Challenges
- Certified NDT Technician Scarcity:Ultrasonic testing specialists with subsea welding qualifications command premium wages across Southeast Asian hubs.
- Legacy SCADA Integration Complexity:Predictive maintenance platforms must interface with 1990s-era control architectures common in India's GAIL-operated corridors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Pipeline Maintenance Market |
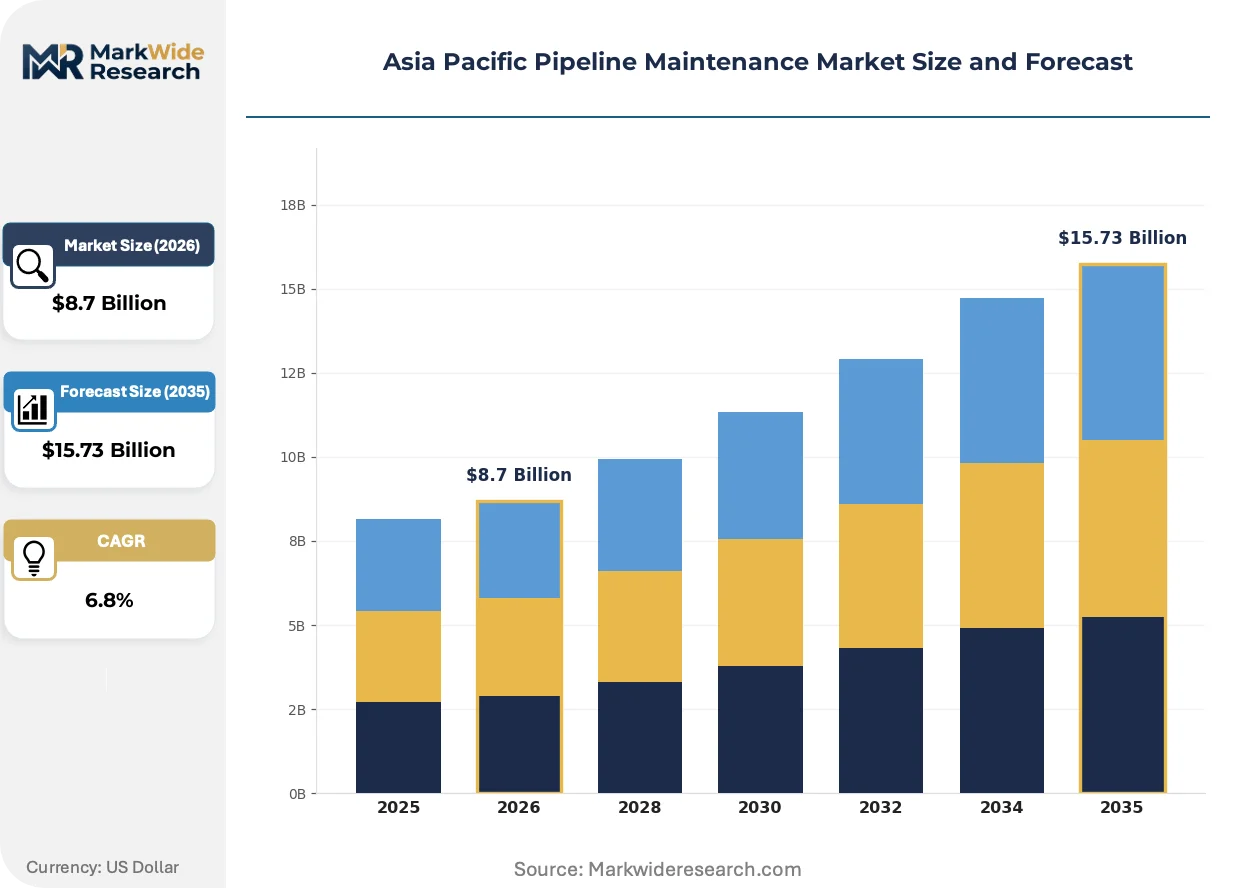
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Inspection, Repair, Rehabilitation, Monitoring Technology: Ultrasonic Testing, CCTV Inspection, Smart Pigs, Hydrostatic Testing End User: Oil & Gas Companies, Water Utilities, Chemical Manufacturers, Energy Sector Maintenance Type: Preventive, Predictive, Corrective, Scheduled |
| Companies Covered | China National Petroleum Corporation, China Petrochemical Corporation, Indian Oil Corporation, Oil and Natural Gas Corporation, Petronas Gas Bhd, Dacon Inspection Services Co. Ltd, EnerMech Ltd, T. D. Williamson Inc, STATS Group, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Pipeline Maintenance Market Strategic Shifts
Pipeline maintenance technology is pivoting from scheduled intervention toward condition-based response systems, compressing detection-to-repair timelines while expanding the addressable infrastructure base.
Electromagnetic acoustic transducer (EMAT) inspection technology eliminates couplant fluid requirements for ultrasonic wall-thickness measurement. Offshore operators in Indonesia's Java Sea blocks are adopting EMAT arrays for riser inspection at twice the speed of conventional methods. This non-contact approach is decentralizing inspection capacity to vessel-based crews rather than shore-based processing centers.
Australia's NOPSEMA has tied subsea pipeline inspection frequencies directly to corrosion risk models rather than fixed calendar intervals. The regulation forces operators to deploy continuous monitoring arrays or face elevated regulatory scrutiny. Bass Strait production infrastructure now requires annual integrity submissions backed by sensor data, compressing traditional survey cycles.
Performance-based service contracting is displacing unit-rate maintenance agreements across Southeast Asian gas transmission networks. National oil companies in Indonesia and Malaysia now tie contractor payments to leak-free operational hours rather than inspection volume. This shift concentrates vendor selection on predictive capability rather than equipment inventory, favoring Japanese and Australian specialists with proprietary analytics platforms.
Asia Pacific Pipeline Maintenance Market Segmentation
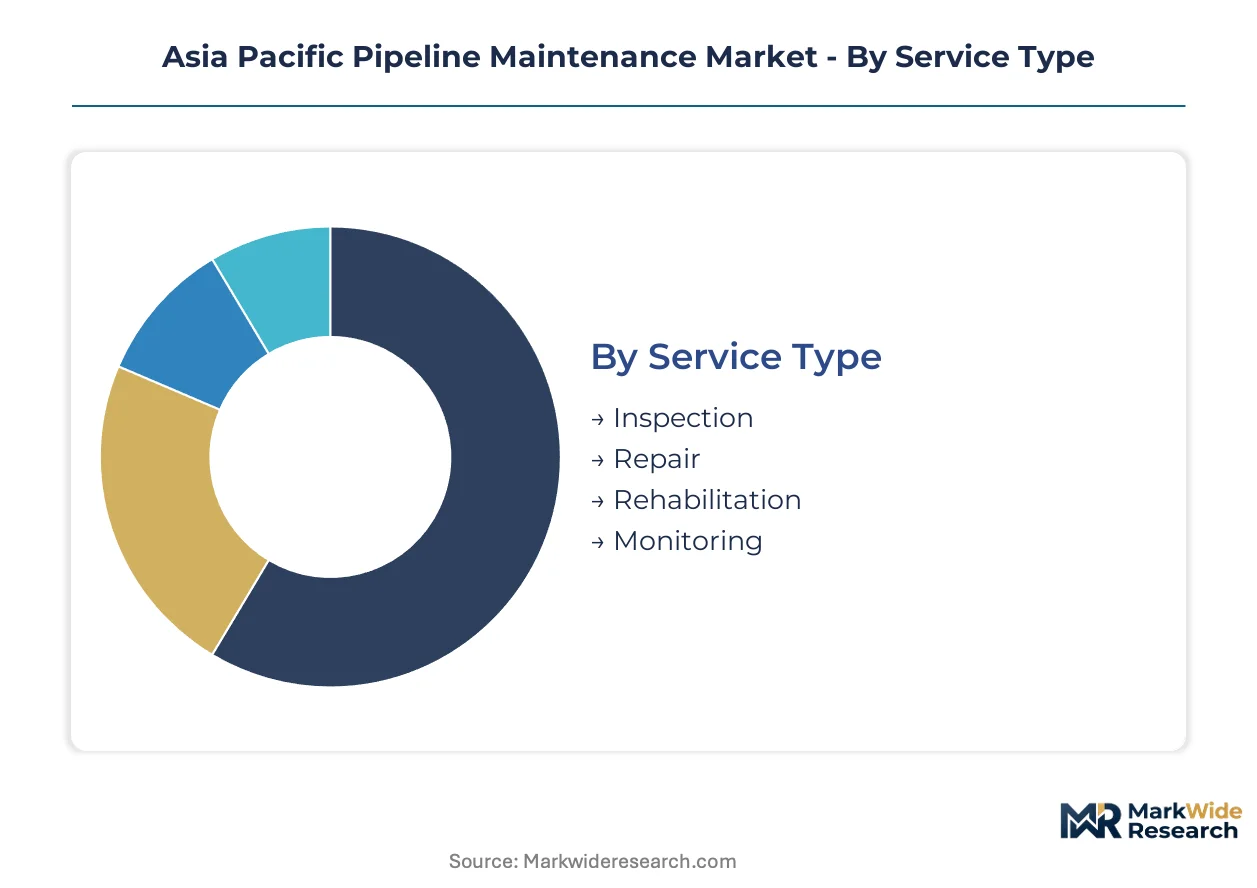
Pipeline maintenance procurement in Asia Pacific splits across service delivery models and technology integration depths. Operators in Indonesia's offshore corridors and Australia's Bass Strait fields select segments based on regulatory mandate alignment and shutdown cost minimization.
Service Type:
Inspection and monitoring services function as standalone contracts with discrete deliverables, while repair and rehabilitation embed within multi-year asset integrity programs.
- Inspection:Non-destructive evaluation protocols encompassing ultrasonic wall-thickness measurement and electromagnetic acoustic transducer arrays for riser assessment. Demand concentrates in Indonesia's Java Sea blocks where NOPSEMA-style risk models compress survey cycles.
- Monitoring:Continuous sensor-to-cloud architectures with fiber-optic distributed acoustic sensing for real-time leak detection. Australia's Bass Strait operators deploy these systems to satisfy annual integrity submission requirements without pipeline shutdown.
- Repair:Pressure-boundary restoration through welded sleeve installation or composite reinforcement wraps.
- Rehabilitation:Structural reinforcement of aging subsea infrastructure across Southeast Asia's declining reservoir pressure fields.
Volume placements concentrate in Inspection; the faster expansion belongs to Monitoring.
Technology:
Cost tiers separate established methods from emerging platforms requiring specialized vessel support and data processing infrastructure.
- Ultrasonic Testing:High-frequency sound wave propagation for wall-thickness measurement in high-temperature crude environments where radiographic alternatives face operational constraints. Chinese trunk lines crossing the Sichuan basin deploy these systems to satisfy SAMR GB standard compliance.
- Smart Pigs:Inline inspection tools with electromagnetic acoustic transducer advances enabling unpiggable line assessment. Japanese operators retrofit these for hydrogen blending trial networks under METI roadmap specifications.
- CCTV Inspection:Visual assessment for internal corrosion mapping in water utility distribution networks.
- Hydrostatic Testing:Pressure-boundary verification mandated by India's PESO for cross-country petroleum line retesting intervals.
Procurement volumes favor Ultrasonic Testing; Smart Pigs gain share fastest through unpiggable line penetration.
End User:
Application severity and fluid containment risk determine maintenance spend intensity across customer categories.
- Oil & Gas Companies:Hydrocarbon transmission operators managing subsea production infrastructure and cross-country trunk lines. Indonesia's national oil company expands corrosion monitoring contracts as deepwater field pressures decline.
- Water Utilities:Municipal distribution system operators with lower pressure-boundary risk tolerances and standardized inspection intervals.
- Chemical Manufacturers:Process pipeline operators requiring specialized alloy compatibility assessment.
- Energy Sector:Hydrogen blending trial participants and power generation coolant system operators.
Contract value concentrates with Oil & Gas Companies; Energy Sector applications expand most quickly through hydrogen infrastructure retrofit.
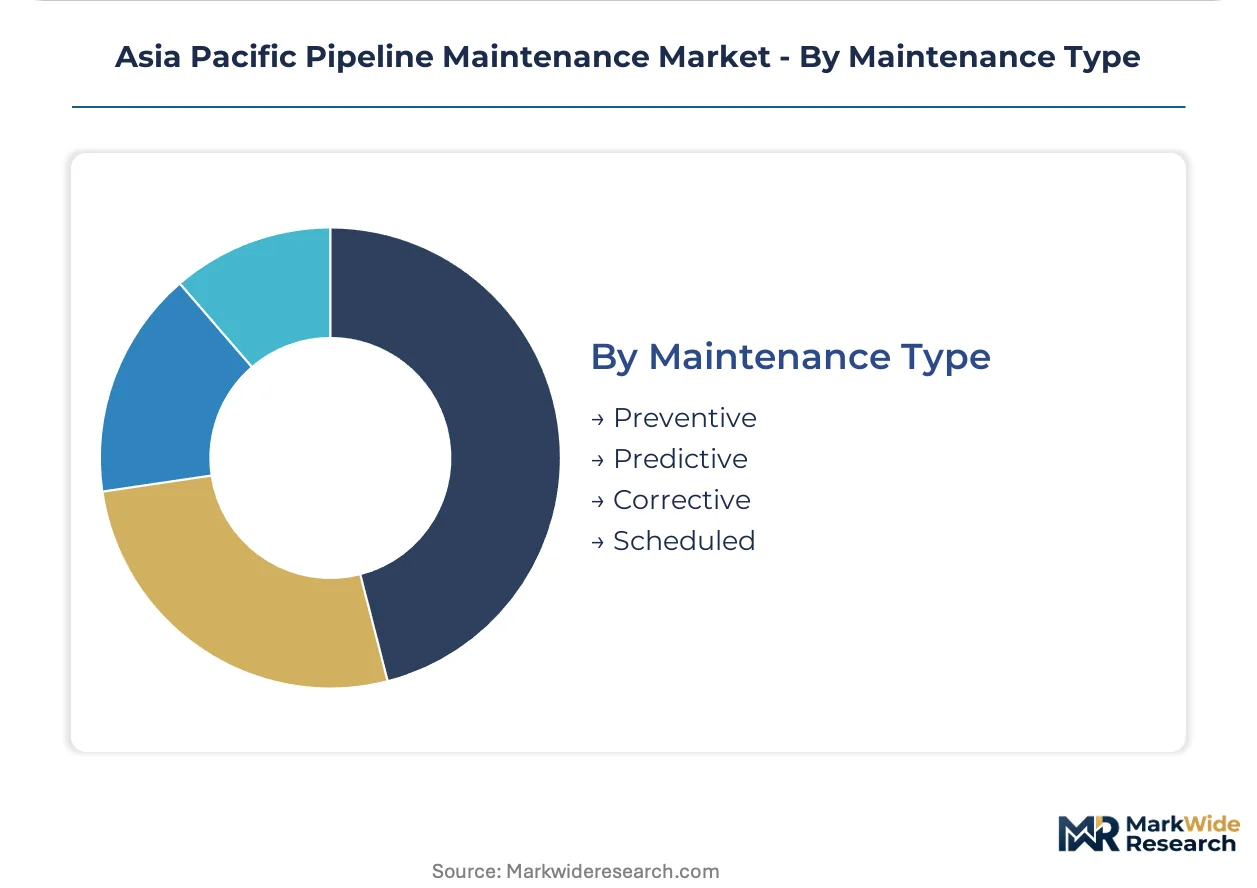
Maintenance Type:
Maturity gradients separate legacy scheduled interventions from data-driven condition-based response systems.
- Predictive:Sensor-to-cloud architectures with edge computing analytics reducing unplanned shutdown frequency. Australian operators adopt these platforms to align with NOPSEMA risk-model inspection frequencies rather than fixed calendar cycles.
- Preventive:Calendar-based inspection and component replacement programs common in India's GAIL-operated corridors with 1990s-era SCADA integration constraints.
- Corrective:Post-failure intervention for leak events and pressure-boundary breaches.
- Scheduled:Fixed-interval maintenance windows tied to hydrostatic retesting mandates.
Service revenues cluster in Preventive programs; Predictive maintenance claims the steepest expansion trajectory through performance-based contracting adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore's Jurong Island petrochemical cluster anchors pipeline integrity service demand across Southeast Asia, with specialist contractors staging subsea inspection campaigns from the port city into Indonesia's offshore gas corridors.
China
Shale gas trunk lines across the Sichuan basin drive ultrasonic testing deployment as reservoir depletion accelerates corrosion risks in high-pressure CO2 environments. SAMR enforces GB standard compliance through mandatory pressure-boundary retesting intervals. Chengdu-based rehabilitation crews execute sleeve installations under continuous flow conditions.
Japan
Hydrogen blending trials on Kanto region natural gas networks create retrofit demand for embrittlement-resistant inspection protocols. METI's roadmap mandates material compatibility verification before pipeline commissioning. Yokohama industrial corridors host specialist NDT firms developing electromagnetic acoustic transducer arrays for unpiggable line assessment.
Australia
Bass Strait subsea infrastructure requires annual integrity submissions tied to corrosion risk models rather than fixed survey cycles. NOPSEMA mandates compress traditional inspection windows from five-year to three-year intervals. Melbourne-headquartered diving contractors deploy vessel-based EMAT systems for riser assessment without production shutdown.
Indonesia
Deepwater gas fields in the Java Sea and Makassar Strait force continuous wall-thickness monitoring as declining reservoir pressures alter flow dynamics and corrosion profiles. Pertamina expands performance-based service contracts linking contractor payments to leak-free operational hours. Surabaya serves as the staging hub for offshore inspection campaigns into eastern archipelago production zones.
India
Cross-country petroleum corridors operated by GAIL face hydrostatic retesting mandates from PESO that conflict with continuous delivery contracts. The Hazira-Vijaipur-Jagdishpur trunk line anchors national grid maintenance spending. Gujarat pipeline clusters concentrate preventive maintenance crews addressing 1990s-era SCADA integration constraints.
Asia Pacific Pipeline Maintenance Market Competitive Environment
Premium-margin players sit above commodity-margin players across technology integration depth, with sensor-to-cloud architectures commanding pricing multiples over conventional inspection contracts. The vendor base stratifies between state-affiliated energy majors with captive maintenance divisions and independent specialists with proprietary analytics platforms. Three archetypes dominate: national oil company in-house divisions, Japanese-Australian technology licensors, and Southeast Asian diving contractors. Competitive moves concentrate on performance-based contracting adoption and electromagnetic acoustic transducer licensing partnerships.
Within the state-affiliated tier, China National Petroleum Corporation and China Petrochemical Corporation anchor captive maintenance capacity across Central Asian export routes and domestic shale networks. Among independent specialists, T. D. Williamson Inc exemplifies technology-licensing positioning through inline inspection tool development, while STATS Group occupies the pressure-isolation service niche. Dacon Inspection Services Co. Ltd represents the Southeast Asian contractor archetype with vessel-based deployment capabilities into Indonesia's offshore corridors.
| Leading Market Players |
|---|
| China National Petroleum Corporation |
| China Petrochemical Corporation |
| Indian Oil Corporation |
| Oil and Natural Gas Corporation |
| Petronas Gas Bhd |
| Dacon Inspection Services Co. Ltd |
| EnerMech Ltd |
| T. D. Williamson Inc |
| STATS Group |
| Others |
Value Chain & Pricing Dynamics
Certified NDT technician scarcity in Southeast Asian hubs widens labor-cost differentials between premium Japanese-Australian specialists and commodity-grade regional contractors, stratifying pricing tiers across predictive maintenance contracts and conventional inspection services.
Pricing Analysis
Outcome-based pricing tied to leak-free operational hours anchors premium contract structures, displacing unit-rate agreements across Indonesian and Malaysian gas transmission networks. Price differentiation separates sensor-to-cloud predictive platforms from calendar-based preventive programs, with certification-grade ultrasonic specialists commanding multiples over standard crews. Pricing pressure stems from performance-based contracting adoption that concentrates vendor selection on analytics capability rather than equipment inventory. National oil companies exhibit lowest price sensitivity for hydrogen-blending retrofit protocols, while municipal water utilities face strict budget caps on CCTV inspection cycles.
Supply Chain Analysis
Dual-sourcing requirements for high-grade corrosion-resistant cladding materials mandate qualification of both Japanese and Korean metallurgical suppliers, mitigating input cost volatility for subsea rehabilitation projects. Geographic supply concentration centers on Japan for EMAT array components, South Korea for specialized alloy feedstock, and China for smart pigging equipment fabrication. Raw material dependencies encompass nickel-based superalloys, fiber-optic sensing cables, and electromagnetic acoustic transducer ceramics. Single-source vulnerability persists in unpiggable line inspection tooling where T. D. Williamson Inc holds proprietary licensing positions. Distribution runs through Singapore's Jurong Island staging hubs into Indonesia's offshore corridors and Australia's Bass Strait fields.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia Pacific pipeline maintenance market sits in a technology-transition phase as electromagnetic acoustic transducer arrays displace conventional ultrasonic couplant methods for riser assessment and unpiggable line evaluation.
For Market Incumbents: Lock in performance-based contracting relationships with Pertamina and Petronas Gas Bhd before hydrogen infrastructure scale-up alters material degradation profiles and inspection protocols. Deepen captive rehabilitation capacity through in-house EMAT licensing partnerships, countering the threat of independent specialists with proprietary analytics platforms displacing commodity inspection providers.
For New Entrants and Emerging Players: Capture white space in Kazakhstan-China crude corridor modernization where inline inspection coverage gaps persist across Central Asian export routes. Target the unpiggable line segment in Australia's Bass Strait infrastructure where tight-radius bends block conventional smart pig deployment, entering through vessel-based EMAT crew services rather than shore-based processing centers.
For Investors and Strategic Acquirers: Re-rating potential sits with Japanese-Australian technology licensors given METI hydrogen blending roadmap acceleration and NOPSEMA risk-model mandate expansion. Long-term viability favors specialists with sensor-to-cloud architectures and proprietary edge computing analytics over equipment-rental contractors. Watch for PESO hydrostatic retesting interval relaxation as the signal indicating regulatory burden reduction and preventive-to-predictive maintenance conversion inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Technology Licensing Partnership | EMAT array transfers from Yokohama specialists enable hydrogen-blending retrofit protocols under METI specifications. |
| Performance-Based Contracting | Pertamina's leak-free operational hour payment structures concentrate vendor selection on predictive analytics capability. |
| Backward Integration into Rehabilitation | Sinopec's in-house sleeve installation crews serve Sichuan shale networks under SAMR GB standard compliance mandates. |
| Geographic Expansion | Dacon Inspection Services stages vessel-based campaigns from Surabaya into eastern Indonesia archipelago production zones. |
| Joint Venture | Central Asian export route modernization creates white space for electromagnetic acoustic transducer deployment partnerships. |
Study Parameters
Multi-period observation of corrosion monitoring contract expansions, hydrogen blending trial progressions, and NOPSEMA inspection frequency compressions anchored the trend analysis, supplemented by interviews with pipeline integrity managers at national oil companies, subsea diving contractors, NDT equipment procurement leads, and SAMR compliance officers. Secondary validation drew from SAMR GB standard filings, NOPSEMA annual integrity submission databases, METI hydrogen roadmap disclosures, and PESO hydrostatic retesting interval records. Bottom-up project pipeline tracking across Indonesia's Java Sea blocks and Australia's Bass Strait fields triangulated against top-down maintenance budget disclosures from China National Petroleum Corporation and Indian Oil Corporation.
Input-output matrices modeled service type, technology, and maintenance type segmentation dimensions alongside regional regulatory framework clusters across the projection horizon. CAGRs were derived from maintenance spend intensity curves tied to subsea infrastructure age profiles and hydrogen infrastructure retrofit conversion rates. Forecast inputs incorporated reservoir pressure decline trajectories in Southeast Asian deepwater fields and SCADA integration complexity constraints in India's GAIL-operated corridors.
The model holds under stable SAMR enforcement intensity and continued METI hydrogen roadmap funding; deviation in alloy supply concentration or PESO mandate relaxation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
High-Purity Fluoropolymer Valves Market
Valves
Air Jet Ejectors Market
Valves
Curb Valves Market
Valves
APAC Valves Market
Valves
Isolator Valves Market
Valves
Sanitary Valves Market
Valves
Mooring Inspection Market
Valves
Global Marine Actuators and Valves Market
Valves
Hydraulic Valves Market
Valves
Hot Blast Valves Market
Valves
Liner Regulators Market
Valves
Hybrid Valve Market
Valves
Global Solenoid Valves Market
Valves
Global Globe Valve Market
Valves
India Industrial Valves Market
Valves
Valve Cover Gasket Market