
 Acoustic Diaphragm Market | 2026-2036
Acoustic Diaphragm Market Size, Share, and Industry Trends Forecast 2026-2036
Acoustic Diaphragm Market Analysis
Buyer concentration in the automotive sector is consolidating as EV manufacturers reduce their supplier bases and demand turnkey acoustic modules rather than commodity diaphragms. Materion Corporation leverages its beryllium-copper alloy expertise to dominate premium tweeter diaphragm supply for high-resolution audio systems. Foster Electric Company, Limited anchors Japanese OEM relationships through integrated speaker-diaphragm design capabilities. Vesper Technologies competes in MEMS-based piezoelectric alternatives, positioning its silicon diaphragm architecture for voice-assistant and noise-cancellation endpoints.
An acoustic diaphragm is a thin, vibrating membrane that converts electrical signals into mechanical sound waves, typically engineered with controlled stiffness-to-mass ratios and damping characteristics measured by total harmonic distortion below one percent at rated excursion. Polymer diaphragms lead consumer electronics volume due to cost-efficient injection molding, while metal variants capture premium margin pools in professional studio monitors where extended frequency response dictates material selection. The composite material segment sustains the fastest growth trajectory as layered aramid-carbon formulations displace single-material designs in automotive and broadcasting applications demanding thermal stability across wide operating temperatures.
The EU RoHS directive and REACH chemical restrictions constrain heavy metal content in diaphragm coatings and voice-coil assemblies, compelling reformulation of traditional surface treatments. China's SAMR enforces GB/T electroacoustic standards that specify harmonic distortion limits and environmental testing protocols for domestically sold components. The US FCC Part 15 emissions framework indirectly shapes diaphragm electromagnetic compatibility requirements in wireless audio devices. Stakeholders must monitor evolving battery-electric vehicle platform architectures, as cabin acoustic redesigns redefine diaphragm specifications for road-noise-compensating audio systems.
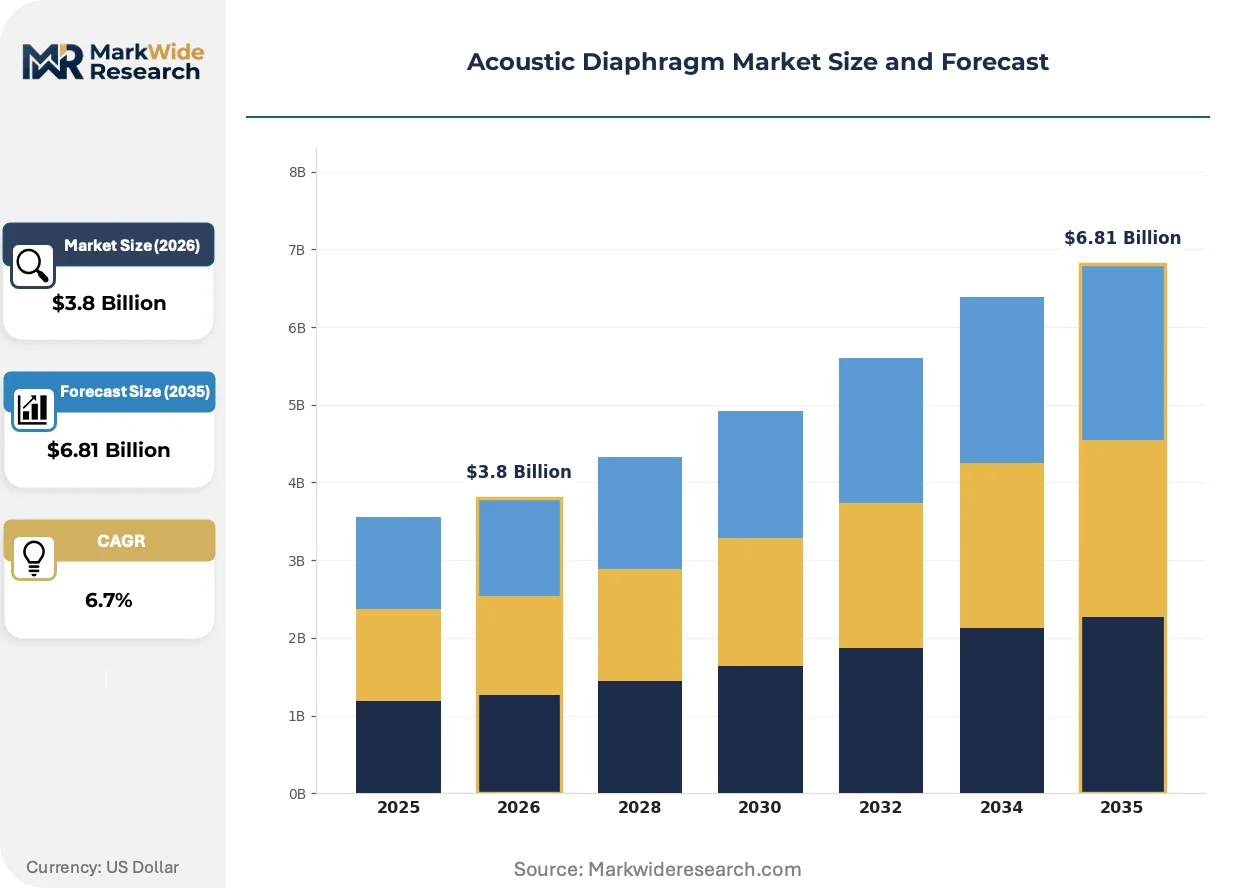
Market Dynamics
Automotive electrification is eliminating engine noise masking, forcing OEMs to redesign cabin acoustic systems from first principles and source diaphragms capable of reproducing extended frequency ranges at lower distortion thresholds.
Growth Catalysts
- EV Audio Redesign Mandates:Battery-electric vehicle platforms require road-noise-compensating audio systems, expanding diaphragm specifications for full-range reproduction in near-silent cabins.
- China's GB/T Electroacoustic Standards:SAMR-enforced harmonic distortion limits and environmental testing protocols for domestically sold components are elevating quality baselines across East Asian supply chains.
- Aramid-Carbon Layering:Composite formulations are displacing single-material designs in automotive and broadcasting applications demanding thermal stability across wide operating temperatures.
Market Restraints
- Beryllium Supply Concentration:Premium tweeter diaphragm production depends on scarce beryllium-copper alloy sources, creating vulnerability to price volatility and export licensing delays.
- REACH Chemical Restrictions:ECHA-enforced limits on hazardous substances in electronics are compelling reformulation of traditional diaphragm coatings and voice-coil surface treatments.
- MEMS Piezoelectric Substitution:Silicon diaphragm architectures for voice-assistant endpoints threaten commodity polymer diaphragm volumes in consumer electronics.
Strategic Opportunities
- India's PLI Scheme for Electronics:Production-linked incentives for component manufacturing are attracting diaphragm suppliers to establish co-located operations near emerging loudspeaker assembly clusters.
- Headphone Noise-Cancellation Convergence:Integration of feedforward microphones with active diaphragm control creates demand for precision-matched transducer modules in premium personal audio.
- Automotive Turnkey Modules:EV manufacturers are consolidating supplier bases and sourcing integrated speaker-diaphragm assemblies rather than commodity components, favoring design-capable partners.
Industry Challenges
- Acoustic Engineer Scarcity:Specialized expertise in vibration analysis and materials damping is concentrated among aging professionals in Japan and Germany, constraining R&D velocity for new entrants.
- RoHS Compliance Timelines:EU restrictions on heavy metal content in electronics are forcing rapid qualification of alternative surface treatments, compressing product development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acoustic Diaphragm Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dynamic, Condenser, Ribbon, Piezoelectric End User: Musical Instruments, Consumer Electronics, Professional Audio, Automotive Material: Polymer, Metal, Ceramic, Composite Application: Sound Reinforcement, Recording, Broadcasting, Noise Cancellation |
| Companies Covered | Poyun Enterprise, Materion Corporation, Vesper Technologies, Foster Electric Company, Limited, Mica Manufacturing Co. Pvt. Ltd., Dr. Kurt Muller GmbH & Co. KG, U-Sonics Power Cone, Shengzhou Kedi Electronics Co., Ltd., Suzhou Sonavox Electronics Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acoustic Diaphragm Market Emerging Trajectories
Material science advances and regulatory chemistry constraints are converging to reshape how diaphragm manufacturers formulate, test, and qualify products for automotive and professional audio end-uses.
Multi-layer composite diaphragms combining aramid fiber cores with carbon fiber skins are rewriting stiffness-to-mass optimization for automotive mid-range drivers. Tier-1 automotive suppliers are adopting these architectures for road-noise-compensating systems in premium EV platforms. The technology is compressing development timelines by enabling thermal performance validation through simulation rather than physical prototyping cycles.
REACH enforcement by ECHA is restricting traditional chrome and nickel surface treatments for voice-coil assemblies. Manufacturers are pivoting to vapor-deposited polymer coatings and laser-structured bonding surfaces to maintain conductivity without hazardous metal content. Professional studio monitor segments in Germany and Scandinavia are absorbing the cost premiums fastest, driven by sustainability procurement mandates from broadcast and recording facility operators.
Automotive OEMs are unbundling speaker module sourcing from vehicle platform engineering, inserting tier-1 acoustic specialists between diaphragm suppliers and final assembly. This disintermediation compresses the direct supplier base while expanding technical collaboration requirements. The pattern is most visible in China's Yangtze River Delta, where EV manufacturers co-locate acoustic engineering teams with diaphragm production facilities to accelerate iteration cycles.
Acoustic Diaphragm Market Segmentation
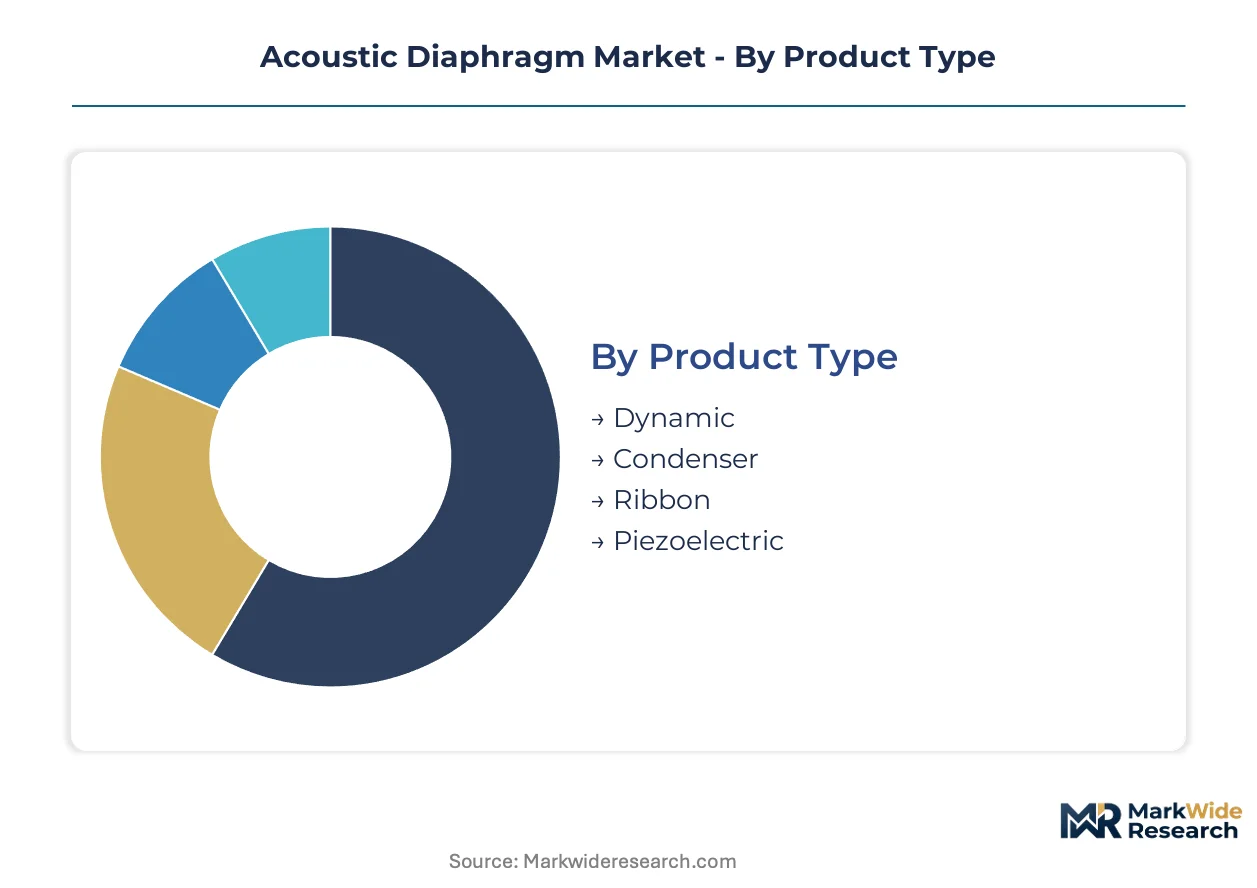
Acoustic diaphragm procurement patterns diverge sharply across end-use specifications, with automotive EV platforms demanding thermal-stable composites while consumer electronics prioritize cost-efficient polymer molding. Material selection and transducer architecture determine upgrade cycles ranging from 3-year smartphone refreshes to 10-year automotive platform lifespans.
Product Type:
Replacement cycles for diaphragm-equipped transducers accelerate as wireless audio protocols obsolete legacy driver architectures in portable and installed sound systems.
- Dynamic:Moving-coil architectures dominate high-SPL applications through stiffened polymer or treated paper cones with optimized surround compliance. Automotive OEMs in Germany and Japan specify these for road-noise-compensating door and deck speakers in near-silent EV cabins.
- Condenser:Thin metallized polymer diaphragms suspended in electrostatic fields deliver extended frequency response for studio recording and measurement microphones. Professional audio facilities in Scandinavia absorb premium unit costs to meet broadcast operator sustainability mandates.
- Ribbon:Corrugated aluminum or beryllium foil elements suspended in magnetic gaps serve high-frequency reproduction in audiophile and broadcast monitoring contexts.
- Piezoelectric:Ceramic or polymer-ceramic composite diaphragms convert electrical energy through crystalline deformation for ultrasonic and voice-assistant applications.
Dynamic transducers sit at the top of the volume ranking, with piezoelectric architectures climbing the fastest on MEMS integration for smart speaker endpoints.
End User:
Cost-tier stratification separates specification-intensive automotive and professional segments from price-sensitive consumer electronics procurement.
- Consumer Electronics:Smartphone, headphone, and portable speaker manufacturers specify polymer diaphragms through injection-molded polypropylene or PET substrates. Shenzhen-based assembly clusters source these through co-located diaphragm suppliers to compress logistics costs.
- Automotive:EV platform engineering teams demand composite diaphragms with aramid-carbon layering for thermal stability across cabin temperature extremes. Tier-1 acoustic specialists in China's Yangtze River Delta co-locate engineering staff with diaphragm production facilities.
- Professional Audio:Studio monitor and broadcast microphone applications specify beryllium-copper or vapor-deposited metal diaphragms for sub-one-percent harmonic distortion thresholds.
- Musical Instruments:Guitar amplifiers and drum microphones employ treated paper or aluminum diaphragms optimized for high-SPL handling and feedback rejection.
Consumer electronics commands the largest shipment volumes, though automotive applications are expanding most quickly on EV audio redesign mandates.
Material:
Margin structures stratify sharply between commodity polymer supply and premium metal formulations serving distortion-critical professional installations.
- Polymer:Injection-molded polypropylene, PET, and PEEK substrates dominate consumer electronics through cost-efficient high-volume production. China's SAMR-enforced GB/T electroacoustic standards are elevating quality baselines for domestically sold polymer diaphragm assemblies.
- Composite:Layered aramid-carbon or glass-carbon hybrids displace single-material designs where thermal expansion coefficients must match automotive operating ranges. ECHA REACH restrictions on hazardous coatings accelerate qualification of polymer-bonded composite surfaces.
- Metal:Aluminum, titanium, and beryllium-copper alloys serve professional tweeter and compression driver applications requiring stiffness-to-mass ratios above polymer limits.
- Ceramic:Piezoelectric ceramics and aluminum oxide substrates enable ultrasonic transduction and high-temperature operation in industrial sensing contexts.
Polymer materials anchor volume production, while composite formulations gain share fastest on automotive thermal performance requirements.
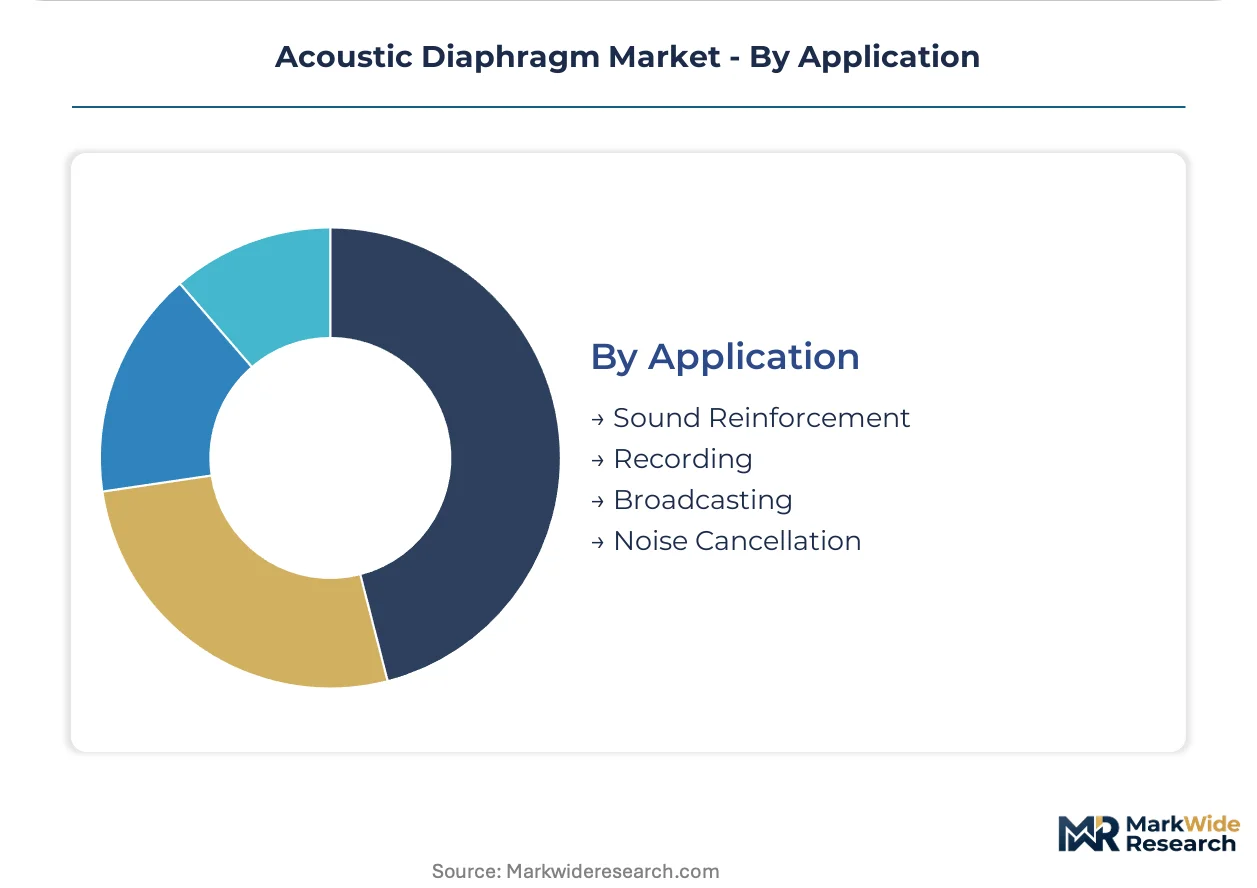
Application:
Geographic concentration of demand clusters around manufacturing hubs for loudspeaker assembly and broadcast content production.
- Noise Cancellation:Feedforward microphone integration with active diaphragm control demands precision-matched transducer modules. Headphone manufacturers in Japan and South Korea specify these for premium personal audio with adaptive ambient suppression.
- Sound Reinforcement:High-SPL compression drivers and woofers for live events and installed venue systems require fatigue-resistant diaphragm materials. German and Japanese OEM relationships anchor supply through integrated speaker-diaphragm design capabilities.
- Recording:Studio condenser and ribbon microphones specify ultra-low-mass diaphragms for transient response and extended frequency reproduction.
- Broadcasting:On-air monitoring and field production equipment demands consistency and durability under continuous operation.
Sound reinforcement leads in unit volume, with noise cancellation applications expanding most rapidly on headphone and automotive cabin integration trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's diaphragm production clusters outpace Japan's legacy precision manufacturing in volume, while Germany's professional audio engineering retains margin leadership through beryllium-copper specialization.
China
Domestic EV manufacturers in the Yangtze River Delta and Pearl River Delta are expanding acoustic module procurement as cabin noise profiles shift with electrification. SAMR-enforced GB/T electroacoustic standards mandate harmonic distortion testing for components sold domestically. Shenzhen and Suzhou host co-located diaphragm suppliers adjacent to loudspeaker and headphone assembly plants, compressing logistics cycles for consumer electronics exports.
Japan
Automotive OEM relationships anchor demand for integrated speaker-diaphragm design capabilities as EV platforms proliferate. METI oversees industrial standards alignment with international electroacoustic testing protocols. Kanto and Kansai manufacturing corridors concentrate aging acoustic engineering expertise, constraining R&D velocity for composite material transitions.
Germany
Professional studio monitor and broadcast equipment manufacturers specify ultra-low-distortion metal diaphragms for recording facility upgrades. ECHA REACH restrictions compel reformulation of chrome and nickel surface treatments in voice-coil assemblies. Bavaria and Baden-Württemberg host precision acoustic engineering clusters serving broadcast operator sustainability mandates.
United States
Voice-assistant hardware deployments and MEMS piezoelectric adoption are reshaping consumer electronics diaphragm procurement patterns. FCC Part 15 emissions frameworks indirectly govern electromagnetic compatibility in wireless audio device architectures. California and Pacific Northwest technology corridors concentrate smart speaker and headphone design engineering.
India
Production-linked incentive schemes for electronics manufacturing are attracting diaphragm suppliers to establish operations near emerging loudspeaker assembly clusters. BIS certification requirements for electroacoustic components are elevating quality baselines for domestically sold products. Maharashtra and Tamil Nadu industrial corridors host expanding contract manufacturing for export-oriented audio equipment.
Acoustic Diaphragm Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across material-grade tiers, creating a bifurcated structure where premium metal alloy capabilities concentrate among established players while polymer volume production fragments across regional fabricators. Three strategic archetypes dominate: integrated acoustic module suppliers, specialty metal alloy processors, and MEMS-based silicon diaphragm innovators. Competitive moves center on automotive tier-1 qualification partnerships and composite material R&D alliances.
Within the specialty alloy tier, Materion Corporation occupies a position representing beryllium-copper expertise for premium tweeter applications, while Dr. Kurt Muller GmbH & Co. KG exemplifies German precision manufacturing archetypes in professional audio contexts. Foster Electric Company, Limited anchors Japanese integrated design capabilities. These three entities collectively represent the geographic and technological diversification patterns visible across the supplier base.
| Leading Market Players |
|---|
| Poyun Enterprise |
| Materion Corporation |
| Vesper Technologies |
| Foster Electric Company, Limited |
| Mica Manufacturing Co. Pvt. Ltd. |
| Dr. Kurt Muller GmbH & Co. KG |
| U-Sonics Power Cone |
| Shengzhou Kedi Electronics Co., Ltd. |
| Suzhou Sonavox Electronics Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Acoustic engineering expertise concentrated in Japan's Kanto corridor and Germany's Bavaria region feeds labor-cost differentials that widen pricing-tier spreads between premium metal-alloy diaphragms and commodity polymer alternatives. These geographic skill clusters enable tier-1 suppliers to command sustained premiums while East Asian manufacturing bases absorb volume-tier cost compression.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for polymer diaphragm tiers. Three-tier pricing structure across premium, standard, and economy levels separates beryllium-copper formulations from aramid-carbon composites and injection-molded polypropylene. Price differentiation hinges on certification grade under GB/T electroacoustic standards and volume scale commitments. Pricing pressure stems from MEMS piezoelectric substitution in consumer electronics voice-assistant endpoints. Consumer electronics OEMs in Shenzhen exhibit highest price sensitivity, while German broadcast operators absorb premium unit costs for REACH-compliant surface treatments.
Supply Chain Analysis
Single-source vulnerability sits with beryllium-copper alloy processors in the United States and Kazakhstan. Geographic supply concentration centers on China, Japan, and Germany for finished diaphragm production. Raw material dependencies draw from aramid fiber sources, carbon fiber prepregs, and metallized polymer films. Supply chain risk rests on export licensing delays for strategic metal alloys. Distribution runs through tier-1 acoustic module suppliers co-located with EV platform engineering teams in China's Yangtze River Delta and Pearl River Delta manufacturing corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in acoustic diaphragms rests on composite material transitions that displace single-material designs at lower per-unit cost than beryllium-copper alternatives, while premium-tier demand from EV cabin redesigns sustains pricing power for thermal-stable formulations.
For Market Incumbents: Anchor automotive tier-1 relationships through integrated speaker-diaphragm design capabilities as EV manufacturers consolidate supplier bases. Defend against MEMS piezoelectric substitution by accelerating aramid-carbon composite R&D alliances with East Asian material suppliers. Prioritize REACH-compliant surface treatment qualification to maintain German broadcast operator access. For New Entrants and Emerging Players: India's PLI-attracted loudspeaker assembly clusters present an underserved buyer archetype seeking co-located diaphragm supply. Target Maharashtra and Tamil Nadu industrial corridors for contract manufacturing partnerships with export-oriented audio equipment producers. Pursue BIS certification pathways to qualify for domestically sold component procurement. For Investors and Strategic Acquirers: Valuations sit cheapest among regional polymer diaphragm fabricators lacking automotive tier-1 qualification. Long-term viability favors specialty metal alloy processors with captive beryllium-copper sourcing and integrated acoustic module capabilities. Watch EV platform architecture standardization across Chinese OEMs as inflection indicator for composite diaphragm demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Composite Material R&D Alliance | Aramid-carbon layering partnerships with automotive tier-1s accelerate thermal performance validation timelines. |
| REACH-Compliant Surface Treatment Qualification | Vapor-deposited polymer coatings secure German broadcast operator procurement under ECHA enforcement. |
| Automotive Tier-1 Integration Partnership | Co-located engineering teams in China's Yangtze River Delta compress EV platform iteration cycles. |
| MEMS Piezoelectric Platform Development | Silicon diaphragm architectures capture voice-assistant endpoint demand from smart speaker OEMs. |
| India PLI Scheme Manufacturing Entry | Production-linked incentives attract diaphragm suppliers to Maharashtra and Tamil Nadu assembly clusters. |
Methodological Framework
Coverage spans China, Japan, Germany, the United States, and India, with primary inputs from each market's manufacturing and regulatory environments. Primary interviews combined insights from acoustic engineering directors, automotive tier-1 procurement managers, electroacoustic testing laboratory heads, and polymer composite R&D leads. Secondary validation drew from SAMR GB/T standard filings, ECHA REACH substance restriction updates, FCC Part 15 emissions databases, and automotive platform engineering disclosures. Bottom-up diaphragm shipment estimates triangulated against top-down EV audio system content value analyses.
Rate-of-change decomposition across the analysis window separated volume growth from average selling price evolution by material tier and end-use segment. Segmentation dimensions modeled include product architecture, end-user industry, material formulation, and application context. CAGRs derived from year-over-year progression of installed base replacement cycles and new platform adoption curves. Industry-specific forecast inputs incorporated EV cabin noise compensation engineering specifications and MEMS piezoelectric penetration assumptions for voice-assistant endpoints.
Underlying measurement precision varies by segment; automotive and professional audio applications carry tighter precision than consumer electronics given standardized testing protocols and longer platform lifespans. Forecasts reflect assumptions around regulatory enforcement timelines for REACH surface treatment restrictions and GB/T electroacoustic standard adoption rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Pulse Width Modulation Controllers Market
Electronic Components
North America Touch Screen Controllers Market
Electronic Components
AC Adapter Market
Electronic Components
Dual Relay Board Market
Electronic Components
Asia-Pacific USB Retimer Market
Electronic Components
Global Industrial Media Converters Market
Electronic Components
Automation Component Market
Electronic Components
Metal Composite Power Inductor Market
Electronic Components
Handheld Devices Battery Market
Electronic Components
Power Resistor Market
Electronic Components
Stretchable Conductors in Electronics Market
Electronic Components
Global Capacitive Stylus Market
Electronic Components
Digital Audio Processor Market
Electronic Components
Wearable Technology Component Market
Electronic Components
IF Digital Attenuator Market
Electronic Components
Electronic Speed Controllers Market