
 Oral Controlled Release Drug Delivery Technology Market | 2026-2036
Oral Controlled Release Drug Delivery Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Oral Controlled Release Drug Delivery Technology Market Analytics
Project finance partnerships between contract development organizations and specialty API suppliers is reconfiguring capital requirements for controlled-release formulation entrants. Merck & Co. Inc. leverages its polymer science capabilities to sustain leadership in osmotic pump platforms. Pfizer Inc. anchors North American manufacturing scale for matrix-based extended-release tablets. Sun Pharmaceutical Industries Ltd. competes on cost-optimized granule production for emerging markets.
Oral Controlled Release Drug Delivery Technology encompasses pharmaceutical systems engineered to modulate drug release kinetics through polymeric barriers, osmotic gradients, or biodegradable matrices, typically achieving therapeutic plasma concentrations over 12-24 hour intervals. These platforms reduce dosing frequency and minimize peak-trough fluctuations for chronic therapies. Tablets dominate current volume due to established compression tooling and patient familiarity, though osmotic systems command premium positioning for narrow-therapeutic-index drugs. Biodegradable polymers represent the fastest-expanding technology segment as manufacturers seek to eliminate residual excipient burden.
The US FDA, EMA, and Japan's PMDA each enforce distinct dissolution profile validation requirements that dictate regional formulation strategies and bioequivalence study designs. REACH compliance in Europe restricts certain phthalate-based polymer plasticizers, redirecting R&D toward citrate and adipate alternatives. Stakeholders must monitor evolving pharmacopeial harmonization between ICH member regulators to preempt redundant stability testing investments.
Market Dynamics
Polymeric matrix erosion kinetics and osmotic pump engineering advances are compressing formulation development timelines while FDA quality-by-design mandates force parallel validation investments.
Growth Catalysts
- Chronic disease prevalence:Aging demographics in Japan, Germany, and the United States sustain prescription volumes for once-daily cardiovascular and diabetes regimens requiring extended-release platforms.
- EMA bioequivalence harmonization:Streamlined dissolution profile validation across ICH member states reduces redundant stability testing burdens for multi-regional filings.
- Biodegradable polymer advances:PLGA and polycaprolactone matrices eliminate residual excipient accumulation concerns in long-term neurological and psychiatric therapies.
Market Restraints
- API supply concentration:Specialty controlled-release excipient production clusters in Western European chemical corridors, exposing formulations to energy cost volatility and REACH compliance escalation.
- Dissolution apparatus standardization:USP Type I-IV apparatus validation requirements create capital intensity barriers for emerging market entrants lacking established analytical infrastructure.
- Immediate-release substitution:Orally disintegrating tablets and sublingual films capture portions of the antiemetic and acute pain segments where rapid onset outweighs duration benefits.
Strategic Opportunities
- Pediatric extension formulations:Mini-tablet and multiparticulate platforms address unmet needs in juvenile epilepsy and attention-deficit therapies across European and North American markets.
- India CDMO expansion:Cost-optimized granulation and coating capacity in Hyderabad and Ahmedabad clusters attracts Western sponsor technology transfers seeking manufacturing arbitrage.
- Digital twin integration:In-silico dissolution modeling converging with real-time release testing enables predictive scale-up, compressing development cycles for complex generic filings.
Industry Challenges
- Formulation scientist scarcity:Specialized expertise in polymer rheology and diffusion mathematics concentrates within established pharmaceutical hubs, constraining talent acquisition for mid-scale entrants.
- Equipment qualification timelines:Installation and operational qualification for continuous manufacturing lines extends facility readiness by 18-24 months, delaying revenue recognition.
- Excipient master file coordination:DMF reference letter negotiations between API suppliers and finished dose sponsors introduce regulatory submission friction and timeline uncertainty.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oral Controlled Release Drug Delivery Technology Market |
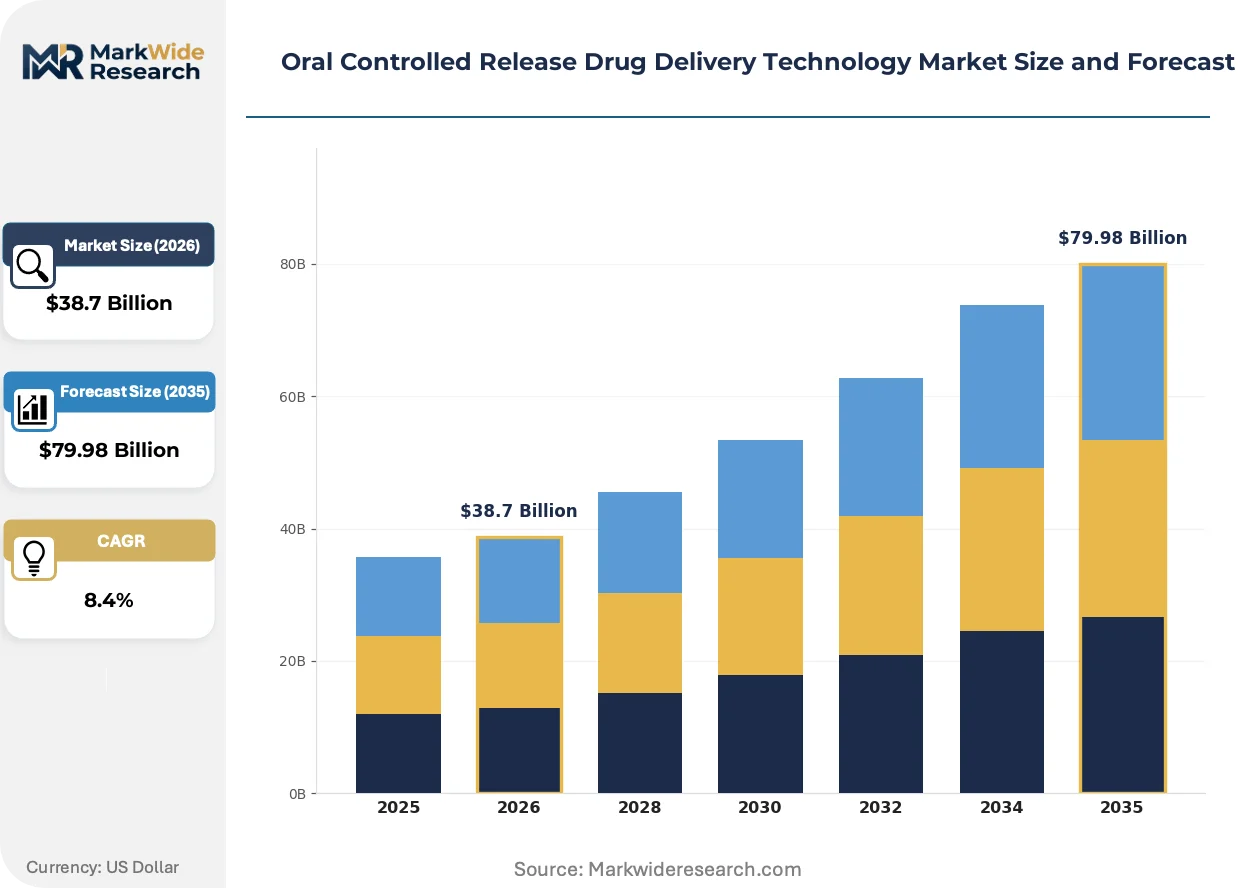
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $79.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Capsules, Granules, Mini-tablets Technology: Diffusion-Controlled, Osmotic Systems, Biodegradable Polymers, Matrix Systems End User: Pharmacies, Hospitals, Clinics, Research Institutions Delivery Mode: Oral, Sublingual, Buccal, Esophageal |
| Companies Covered | Merck & Co. Inc., Johnson & Johnson, Pfizer Inc., F. Hoffmann-La Roche Ltd., GlaxoSmithKline Plc, Novartis AG, Bristol-Myers Squibb Company, Sun Pharmaceutical Industries Ltd., AstraZeneca Plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oral Controlled Release Drug Delivery Technology Market Evolving Landscape
Three-dimensional printing of personalized dosage geometries and machine-learning-guided polymer selection are compressing traditional formulation development paradigms.
Multilayered osmotic pump architectures with laser-drilled precision orifices are rendering obsolete conventional matrix tablets for narrow-therapeutic-index drugs. Neurology and transplant therapeutic areas adopt these platforms fastest. The shift compresses bioequivalence study failure rates and accelerates generic substitution timelines.
REACH restrictions on phthalate-based plasticizers redirect European formulation R&D toward citrate and adipate polymer modifiers. ECHA substance evaluation schedules force preemptive excipient substitution in coating and membrane applications. German and French manufacturers lead citrate adoption, while Italian suppliers specialize in adipate alternatives.
Hospital procurement consortia in the United States now mandate real-world adherence data as contract award criteria, unbundling traditional volume-based purchasing. Integrated delivery networks favor formulations with documented persistence advantages. This behavioral shift concentrates demand among manufacturers with health economics and outcomes research capabilities.
Oral Controlled Release Drug Delivery Technology Market Segmentation
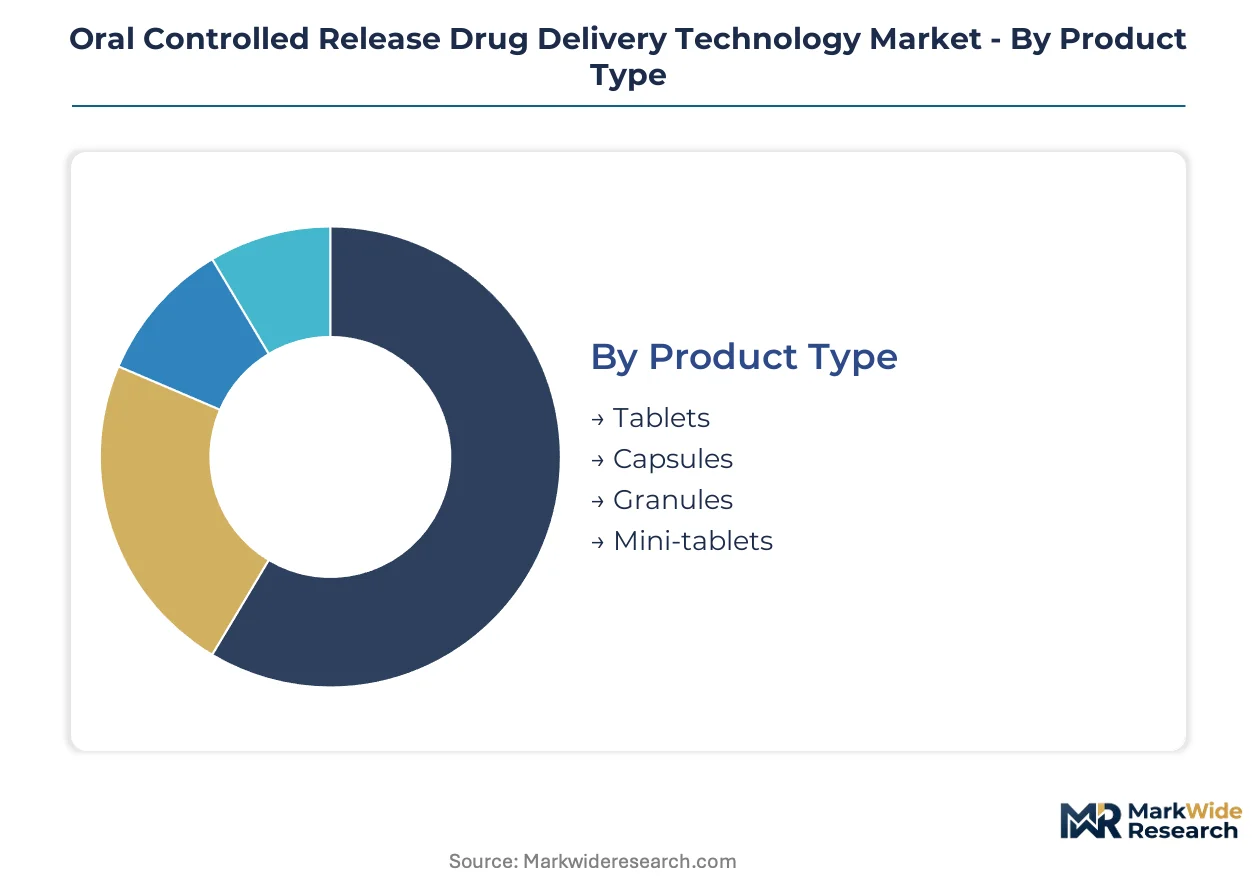
Segmentation in oral controlled-release platforms reveals distinct technical and commercial fault lines. Product geometry, release mechanism, and institutional procurement patterns each dictate manufacturing investment priorities and regulatory pathway complexity.
Product Type:
After-sales service intensity varies sharply across oral dosage geometries, with complex multiparticulate systems demanding sustained technical support versus commodity tablet formats.
- Tablets:Compression-molded monolithic matrices dominate current volume through established high-speed tooling infrastructure at Pfizer and Merck manufacturing sites. Demand concentrates in United States Medicare Part D channels for once-daily cardiovascular regimens where patient familiarity reduces adherence program costs.
- Capsules:Hard gelatin or HPMC shells enable taste masking and moisture protection for moisture-sensitive APIs. German and Japanese manufacturers favor capsule platforms for narrow-therapeutic-index drugs requiring precise dose titration flexibility.
- Granules:Multiparticulate spheres offer dosing flexibility through sachet or sprinkle administration. Sun Pharmaceutical leverages Hyderabad coating capacity for cost-optimized granule exports to Latin American markets.
- Mini-tablets:Sub-4mm compressed units enable pediatric and geriatric dosing precision. European EMA pediatric investigation plans are accelerating mini-tablet platform investments for juvenile epilepsy therapies.
Tablets hold the largest share; momentum sits with mini-tablets.
Technology:
Technology selection determines capital intensity and development timeline, with osmotic systems requiring precision laser drilling versus simpler matrix erosion platforms.
- Diffusion-Controlled:Polymeric membrane barriers regulate drug release through Fickian diffusion kinetics. Japanese PMDA dissolution profile requirements favor diffusion-controlled platforms for generic filings seeking bioequivalence pathway efficiency.
- Osmotic Systems:Semipermeable membranes with laser-drilled orifices deliver zero-order release kinetics independent of gastrointestinal pH variability. Demand concentrates in United States transplant and neurology therapeutic areas where plasma level precision determines therapeutic outcomes.
- Biodegradable Polymers:PLGA and polycaprolactone matrices eliminate residual excipient accumulation through enzymatic hydrolysis. German manufacturers lead citrate-plasticizer adoption following ECHA REACH restrictions on phthalate alternatives.
- Matrix Systems:Hydrophilic or lipophilic monolithic cores erode or dissolve to release active pharmaceutical ingredients. Indian CDMO clusters in Ahmedabad specialize in cost-optimized matrix tablet production for emerging market sponsors.
Matrix systems anchor current volume; biodegradable polymers are climbing the fastest.
End User:
Procurement sophistication and volume concentration diverge across institutional channels, with integrated delivery networks imposing adherence documentation requirements absent in retail pharmacy.
- Pharmacies:Community and chain retail dispensaries handle the majority of outpatient chronic disease prescriptions. United States pharmacy benefit managers favor extended-release formulations with documented persistence advantages in formulary placement negotiations.
- Hospitals:Inpatient and discharge medication supply chains prioritize unit-dose packaging and barcode verification compatibility. Hospital procurement consortia now mandate real-world adherence data as contract award criteria.
- Clinics:Outpatient specialty practices in cardiology and endocrinology drive prescriber preference for patient-friendly once-daily regimens.
- Research Institutions:Academic medical centers and contract research organizations source specialized formulations for bioequivalence and clinical pharmacology studies.
Pharmacies command the dominant channel position; hospitals are gaining procurement leverage fastest.
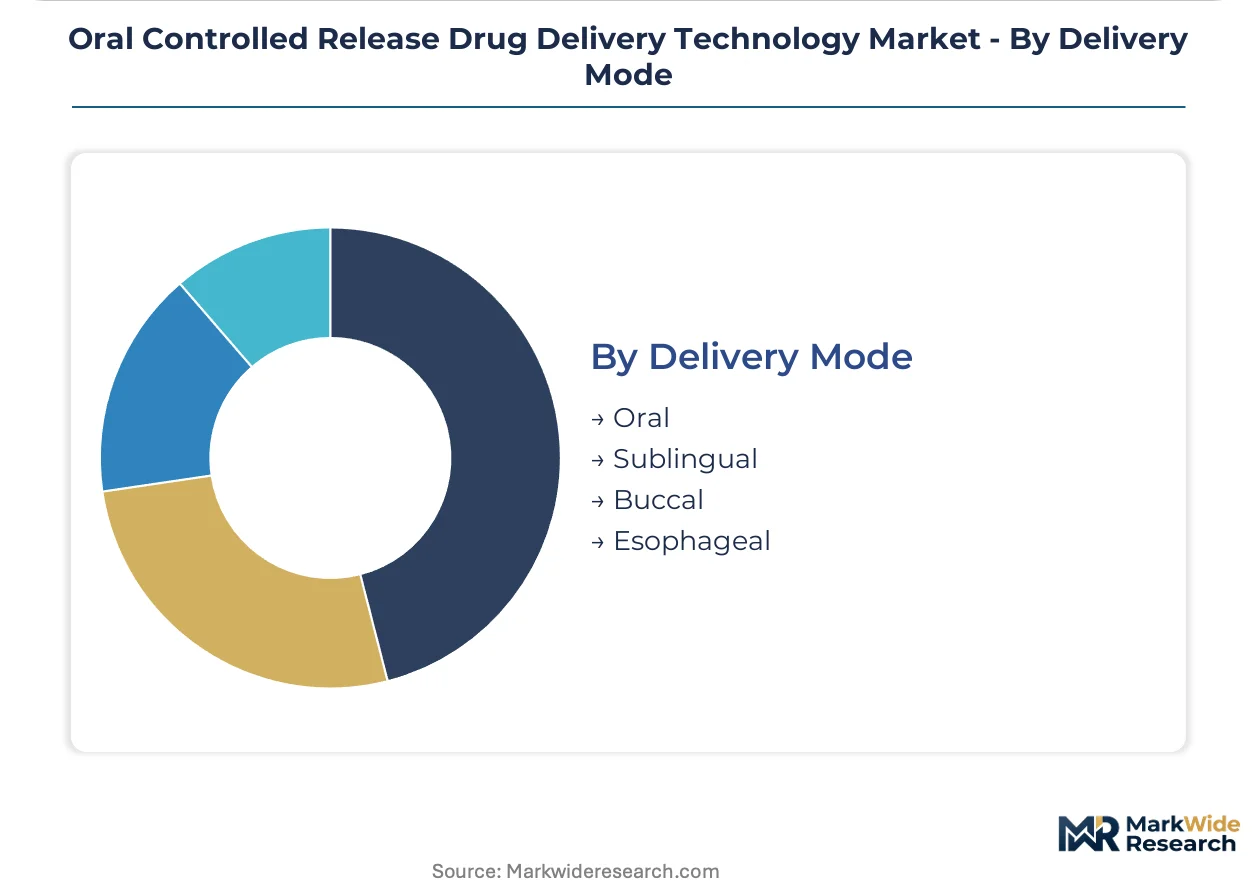
Delivery Mode:
Anatomical placement determines release kinetics and regulatory classification, with sublingual and buccal routes offering bypass of first-pass hepatic metabolism.
- Oral:Gastrointestinal tract delivery remains the standard for extended-release platforms achieving 12-24 hour plasma concentration maintenance. FDA quality-by-design guidelines for modified-release dosage forms govern oral platform development.
- Sublingual:Venous drainage from the floor of the mouth enables rapid systemic absorption for acute breakthrough pain management. Sublingual films capture portions of the antiemetic segment where rapid onset outweighs duration benefits.
- Buccal:Adhesive patches or tablets positioned against the cheek mucosa suit drugs with extensive first-pass metabolism or poor gastric stability.
- Esophageal:Specialized stent or band formulations target local drug delivery to esophageal tissue for oncology applications.
Oral delivery retains overwhelming volume dominance; sublingual platforms are expanding most quickly in acute care segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German and Japanese manufacturing corridors, while Indian production clusters compete on cost-optimized granulation capacity. The United States sustains premium positioning through FDA-validated osmotic platforms. Regulatory divergence between EMA dissolution harmonization and PMDA bioequivalence requirements fragments formulation strategies across Atlantic and Pacific markets.
United States
Medicare Part D channels sustain prescription volumes for once-daily cardiovascular regimens requiring extended-release platforms. FDA quality-by-design guidelines for modified-release dosage forms accelerate formulation investments and compress generic approval timelines. Boston and New Jersey pharmaceutical corridors concentrate osmotic pump manufacturing capacity for narrow-therapeutic-index drugs.
Germany
Aging demographics drive sustained demand for chronic disease therapies with adherence-optimized dosing schedules. ECHA REACH restrictions on phthalate-based polymer plasticizers redirect R&D toward citrate and adipate coating alternatives. Frankfurt and Ludwigshafen chemical clusters lead biodegradable polymer adoption for neurological and psychiatric applications.
Japan
Super-aged population structures sustain prescription volumes for diabetes and hypertension management requiring 24-hour plasma concentration maintenance. PMDA dissolution profile validation requirements favor diffusion-controlled platforms for bioequivalence pathway efficiency. Osaka and Tokyo pharmaceutical hubs concentrate laser-drilled osmotic pump engineering for transplant and neurology therapeutic areas.
India
Cost-optimized manufacturing capacity attracts Western sponsor technology transfers seeking granulation and coating arbitrage. CDSCO regulatory alignment with ICH guidelines streamlines multi-regional filing pathways for domestic exporters. Hyderabad and Ahmedabad CDMO clusters specialize in matrix tablet production for emerging market sponsors.
Oral Controlled Release Drug Delivery Technology Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying polymeric excipients and precision coating equipment. Market structure tilts toward consolidated leadership among vertically integrated pharmaceutical majors with captive polymer science capabilities, while mid-scale entrants face capital intensity barriers from dissolution apparatus standardization requirements. Three archetypes dominate: polymer science integrators, high-volume matrix manufacturers, and emerging market cost optimizers. Competitive moves concentrate on strategic partnerships between contract development organizations and specialty API suppliers, alongside digital twin integration for predictive scale-up acceleration.
Among North American majors, Merck & Co. Inc., Pfizer Inc., and Johnson & Johnson occupy positions spanning osmotic pump platforms and matrix-based extended-release manufacturing. These companies exemplify the polymer science integrator archetype through sustained investment in controlled-release formulation capabilities. Sun Pharmaceutical Industries Ltd. represents the cost-optimization vector, leveraging Indian manufacturing clusters for granule production serving emerging market demand. The competitive terrain rewards health economics and outcomes research capabilities as hospital procurement consortia mandate real-world adherence documentation for contract awards.
| Leading Market Players |
|---|
| Merck & Co. Inc. |
| Johnson & Johnson |
| Pfizer Inc. |
| F. Hoffmann-La Roche Ltd. |
| GlaxoSmithKline Plc |
| Novartis AG |
| Bristol-Myers Squibb Company |
| Sun Pharmaceutical Industries Ltd. |
| AstraZeneca Plc |
| Others |
Value Network & Pricing Analysis
Overcapacity in Indian CDMO coating clusters is compressing contract manufacturing margins while simultaneously expanding Western sponsors' negotiating leverage for technology transfers. This utilization asymmetry rewards buyers who consolidate volume commitments across Hyderabad and Ahmedabad facilities.
Pricing Analysis
The customization-premium spread between standard matrix tablets and configured-to-order osmotic pump platforms exceeds threefold across United States Medicare channels. Three-tier pricing structure across premium, standard, and economy levels reflects FDA validation tier and laser-drilling precision grade. Price erosion runs through commodity tablet formats as Indian manufacturers expand high-speed compression capacity. Hospital procurement consortia exhibit lowest price sensitivity due to adherence-documentation contract requirements, while emerging market distributors face acute cost compression.
Supply Chain Analysis
Extended payment terms from German polymer suppliers to finished-dose sponsors now stretch 90-120 days, reflecting working capital stress in Ludwigshafen chemical corridors. Specialty excipient production draws from Germany, India, and the United States, with PLGA resin supply anchored in Frankfurt-Rhine-Main clusters. Single-source vulnerability concentrates in laser-drilling equipment for osmotic pump orifices. Distribution runs through regional pharmaceutical wholesale networks with cold-chain requirements for moisture-sensitive APIs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized formulation expertise in polymer rheology and diffusion mathematics concentrates within established Boston and New Jersey pharmaceutical hubs, creating acquisition premiums for mid-scale entrants seeking talent access.
For Market Incumbents: Insulate osmotic pump platform margins through captive polymer science capabilities and backward integration into PLGA resin production. Add precision laser-drilling capacity in United States corridors to preempt Indian CDMO cost arbitrage. FDA quality-by-design validation investments create switching costs that protect formulary positioning against matrix tablet substitutes. For New Entrants and Emerging Players: Southeast Asian hospital procurement consortia represent underpenetrated demand for documented adherence formulations. Target pediatric mini-tablet platforms for European EMA pediatric investigation plan compliance. Establish technology transfer partnerships with Hyderabad coating specialists to compress capital requirements. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among contract development organizations with captive polymer science capabilities and FDA master file portfolios. Five-to-ten year viability favors CDMOs integrating digital twin dissolution modeling. Monitor hospital procurement contract award criteria shifts toward real-world adherence data as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Polymer Science Backward Integration | Captive PLGA resin supply insulates German manufacturers from ECHA REACH plasticizer restrictions. |
| Pediatric Mini-Tablet Platform Launch | EMA pediatric investigation plan compliance opens European formulary access for juvenile epilepsy therapies. |
| Digital Twin Scale-Up Integration | In-silico dissolution modeling compresses FDA generic approval timelines for complex osmotic filings. |
| Hospital Procurement Consortium Partnership | Real-world adherence data contracts secure United States integrated delivery network volume commitments. |
| Hyderabad CDMO Technology Transfer | Cost-optimized granulation capacity attracts Western sponsor manufacturing arbitrage opportunities. |
Research Methodology
The analysis maps osmotic pump, matrix erosion, and biodegradable polymer sub-sectors, each validated through formulation scientists, regulatory affairs leads, and hospital procurement managers. Primary interviews with polymer R&D directors and CDMO operations heads combined with secondary triangulation against FDA filings, EMA submissions, ClinicalTrials.gov records, and United States Pharmacopeia dissolution standards. Bottom-up excipient demand modeling and top-down pharmaceutical manufacturing capacity assessments converge through iterative reconciliation.
Assumptions held fixed include ICH pharmacopeial harmonization trajectory and REACH phthalate restriction enforcement timelines, while energy cost volatility and API supply concentration were varied across sensitivity scenarios. Segmentation dimensions span release mechanism technology, dosage form geometry, end-user procurement channel, and regional regulatory cluster. CAGRs derive from patent expiry schedules for branded extended-release formulations and corresponding generic substitution elasticities. Forecast inputs incorporate PMDA bioequivalence pathway efficiency differentials and Medicare Part D prescription volume demographics.
Practitioners should monitor ECHA substance evaluation schedules and FDA quality-by-design guideline revisions for early signals requiring forecast adjustment. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Endovascular Aneurysm Repair Devices Market
Medical Devices
Global Healthcare Nanotechnology (Nanomedicine) Market
Medical Devices
Blood Collection Vacuum Devices Market
Medical Devices
Capsular Tension Rings Market
Medical Devices
Europe Ventilator Market
Medical Devices
Implantable Port Devices Market
Medical Devices
Echogenic Catheters Market
Medical Devices
South Africa General Surgical Devices Market
Medical Devices
Ovulation Microscope Market
Medical Devices
Oxygen Concentrators Market
Medical Devices
Ultra High Definition (UHD) Surgical Display Market
Medical Devices
Tracheostomy Tubes Market
Medical Devices
Middle East and Africa Surgical Equipment Market
Medical Devices
United States Anesthesia Devices Market
Medical Devices
Intelligent Electronic Sphygmomanometers Market
Medical Devices
Needle-Free Injectors Market