
 Global Medical Sensor Market | 2026-2036
Global Medical Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Global Medical Sensor Market Foresight
Multi-source procurement among tier-one device OEMs is broadening the addressable base for specialized component suppliers. TE Connectivity leverages its interconnect portfolio to anchor high-reliability patient monitoring platforms. Medtronic sustains captive manufacturing scale across glucose and cardiac sensor lines. Texas Instruments Incorporated competes on signal conditioning integration for portable diagnostic hardware.
Medical sensors are transducers that convert physiological, biochemical, or physical parameters into measurable electrical signals, typically operating within precision tolerances of ±0.1°C for temperature or ±1 mmHg for pressure applications, and serve to enable real-time clinical decision-making and automated therapeutic feedback. Optical sensors command premium positioning in pulse oximetry and spectroscopic diagnostic imaging where photodetector sensitivity directly determines measurement fidelity. Wireless communication modules represent the fastest-expanding technology layer as ambulatory surgical centers and home healthcare providers prioritize untethered patient data streams.
FDA 510(k) clearance requirements and EU MDR technical documentation standards impose validation burdens that favor established suppliers with dedicated regulatory affairs infrastructure. ISO 13485 quality management certification functions as a baseline market access filter across all major jurisdictions. Stakeholders must weigh the capital requirements of dual FDA-EMA regulatory pathways against the volume potential of single-market specialization strategies.
Market Dynamics
Wireless telemetry architectures are compressing the traditional hospital-centric care model, enabling real-time physiological monitoring outside institutional settings and forcing sensor manufacturers to redesign power budgets, form factors, and cybersecurity postures for ambulatory deployment.
Growth Catalysts
- EU MDR Article 10 technical documentation mandates:Stringent clinical evidence requirements for Class IIa and above devices accelerate consolidation toward suppliers with dedicated regulatory affairs infrastructure, filtering out undercapitalized entrants.
- Home healthcare provider expansion:Reimbursement codes in the United States and Germany now cover remote patient monitoring for chronic conditions, creating pull-through demand for wearable biosensors with extended battery life.
- Photodetector sensitivity advances:Improvements in indium gallium arsenide and silicon photomultiplier technologies enable non-invasive glucose monitoring and tissue oxygenation mapping, opening spectroscopic diagnostic applications previously requiring invasive sampling.
Market Restraints
- Specialized semiconductor foundry concentration:Precision analog CMOS and MEMS fabrication for medical-grade sensors concentrates in Taiwan and South Korea, exposing supply chains to geopolitical friction and capacity allocation constraints.
- Platinum-group metal cost volatility:Electrochemical glucose sensors and certain pH electrodes rely on iridium and ruthenium catalyst layers, with price swings directly compressing gross margins on disposable consumables.
- FDA 510(k) predicate device pathway limitations:Novel sensing modalities without clear predicate matches face extended de novo review timelines, delaying commercialization and consuming capital reserves.
Strategic Opportunities
- Japan's Society 5.0 super-aged society initiatives:METI funding streams and regulatory sandboxes in Kanagawa and Fukuoka prefectures support pilot deployments of ambient fall-detection and medication-adherence sensors in municipal housing complexes.
- AI-enabled predictive analytics integration:Convergence of edge-computing microcontrollers with time-series anomaly detection algorithms enables sensor-embedded early warning systems for sepsis and arrhythmia, creating subscription revenue models beyond hardware sales.
- Direct-to-consumer pharmacy channel expansion:CVS Health and Walgreens Boots Alliance shelf space for over-the-counter continuous glucose monitors and pulse oximeters bypasses traditional durable medical equipment distributor markups.
Industry Challenges
- Biocompatibility certification bottlenecks:ISO 10993 cytotoxicity and sensitization testing backlog at contract research organizations extends product development timelines by six to twelve months for novel materials.
- Legacy hospital IT system interoperability:HL7 FHIR implementation gaps and proprietary electronic health record data schemas force sensor manufacturers to maintain multiple integration codebases, inflating software engineering headcount.
- Radiofrequency coexistence engineering:Dense 2.4 GHz spectrum utilization in clinical environments demands sophisticated adaptive frequency hopping algorithms, requiring specialized firmware expertise in short supply.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Medical Sensor Market |
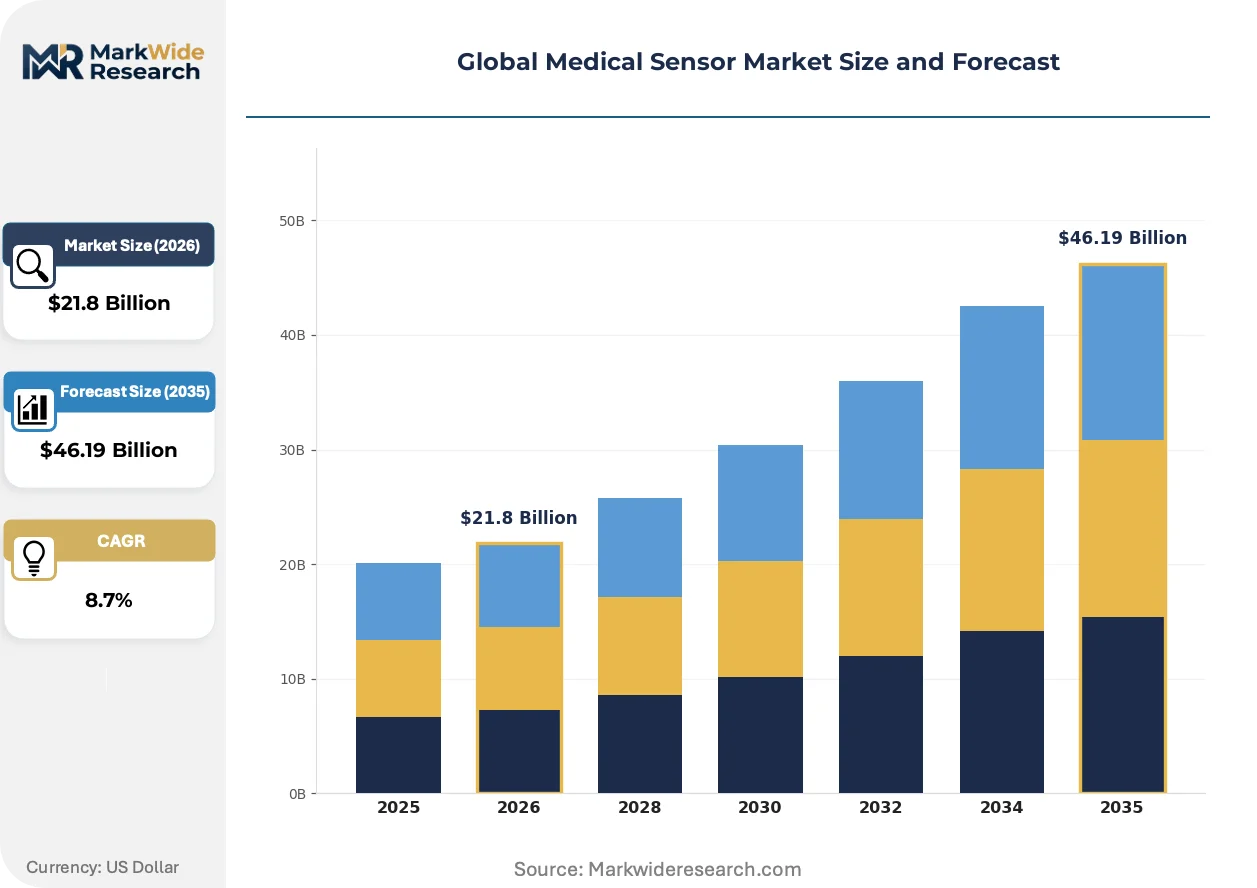
| Market Size in 2026 | $21.8 Billion |
| Market Size in 2035 | $46.19 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrochemical Sensors, Optical Sensors, Piezoelectric Sensors, Capacitive Sensors, Thermoelectric Sensors Application: Patient Monitoring, Diagnostic Imaging, Respiratory Monitoring, Glucose Monitoring, Blood Pressure Measurement End User: Hospitals, Ambulatory Surgical Centers, Diagnostic Laboratories, Home Healthcare Providers, Research Institutes Technology: Nanotechnology, MEMS Technology, Wireless Communication, IoT Integration, Bio-compatible Materials |
| Companies Covered | TE Connectivity, Medtronic, Analog Devices, Inc., Honeywell International Inc., GE Healthcare, Danaher Corporation, Sensirion AG, Texas Instruments Incorporated, NXP Semiconductors, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Medical Sensor Market Shifts & Advancements
Sensor fusion architectures and ambient intelligence networks are dissolving the boundary between acute and post-acute care, embedding diagnostic capability into everyday objects and surfaces while raising novel data governance questions.
Continuous-wave and time-domain near-infrared spectroscopy systems are electrifying non-invasive tissue characterization, with academic medical centers in the United States and Germany deploying wearable cerebral oximeters during high-risk cardiac surgery. The technology enables real-time detection of cerebral desaturation events that precede ischemic injury, compressing the window between physiological insult and clinical intervention from minutes to seconds.
EU MDR Annex XIV post-market surveillance requirements now mandate periodic safety update reports and proactive vigilance data analysis for all active implantable and Class III devices. Manufacturers must maintain dedicated quality management personnel and contracted notified body relationships across the product lifecycle, raising fixed cost structures and favoring scale players with established European authorized representative networks.
Hospital procurement committees are unbundling sensor hardware from data platform subscriptions, reversing the bundled-device-and-software contracts that dominated the 2015-2020 period. Academic medical centers in the United States now issue separate RFPs for physical sensing layers, edge computing infrastructure, and cloud analytics services, enabling best-of-breed vendor selection but complicating system integration accountability.
Global Medical Sensor Market Segmentation
Medical sensor procurement patterns diverge sharply across clinical settings, with hospital capital budgets favoring multi-parameter platforms while home healthcare channels prioritize single-use disposables with extended battery autonomy. Understanding these segment boundaries reveals where component suppliers can defend margin versus where scale manufacturing dominates.
Product Type:
Replacement cycles vary from six months for disposable electrochemical strips to seven-year service intervals for installed optical systems, creating divergent revenue recognition profiles across supplier portfolios.
- Electrochemical Sensors:These devices transduce ionic activity into measurable current through enzyme-immobilized electrodes, typically employing glucose oxidase or lactate oxidase catalytic layers. Demand clusters in home glucose monitoring programs across the United States and Germany, where reimbursement codes for continuous monitoring drive patient self-testing volume.
- Optical Sensors:Photodetector arrays measuring absorbance, reflectance, or fluorescence emission enable pulse oximetry and near-infrared spectroscopy applications. Japanese academic medical centers in Osaka and Tokyo deploy wearable cerebral oximeters during cardiac surgery, capitalizing on indium gallium arsenide sensitivity improvements for real-time tissue oxygenation mapping.
- Piezoelectric Sensors:Quartz crystal microbalances and ceramic transducers convert mechanical stress into electrical signals for pressure and vibration monitoring.
- Capacitive Sensors:Dielectric variation detection enables non-contact proximity sensing and humidity measurement in sterile field applications.
- Thermoelectric Sensors:Thermopile arrays and resistance temperature detectors provide contactless temperature measurement for fever screening and patient warming systems.
Volume placements concentrate in electrochemical disposables; the faster expansion belongs to optical sensing modalities.
Application:
Cost tier stratification separates capital-intensive imaging installations from consumable-dominated chronic disease management segments.
- Patient Monitoring:Multi-parameter bedside systems integrate ECG, SpO2, and invasive pressure transducers for continuous surveillance. Ambulatory surgical centers in the United States favor wireless telemetry architectures that untether patients from fixed monitoring stations, compressing recovery room length-of-stay.
- Diagnostic Imaging:Sensor arrays for MRI, CT, and ultrasound modalities demand electromagnetic interference shielding and precision calibration. German university hospitals in Munich and Heidelberg pioneer photon-counting CT detector deployments, leveraging cadmium zinc telluride direct-conversion layers for dose reduction.
- Respiratory Monitoring:Flow sensors and capnography modules track ventilation parameters in anesthesia and critical care.
- Glucose Monitoring:Enzymatic and emerging optical non-invasive approaches serve diabetes management protocols.
- Blood Pressure Measurement:Oscillometric and arterial line transducers support hypertension diagnosis and hemodynamic monitoring.
Revenue concentration favors patient monitoring hardware; diagnostic imaging claims the steepest expansion trajectory through detector technology upgrades.
End User:
Customer type determines procurement authority structures, with hospital value analysis committees imposing capital equipment approval thresholds that ambulatory settings bypass entirely.
- Hospitals:Integrated delivery networks negotiate enterprise-wide sensor contracts spanning telemetry, anesthesia, and point-of-care testing. South Korean tertiary centers in Seoul and Busan deploy AI-enabled early warning systems, combining edge-computing microcontrollers with time-series anomaly detection for sepsis prediction.
- Ambulatory Surgical Centers:Freestanding facilities prioritize compact, multi-function devices with rapid sterilization compatibility. United States ASC chains in Texas and Florida favor disposable pressure transducer kits that eliminate reprocessing labor costs.
- Diagnostic Laboratories:High-throughput analyzers demand precision liquid handling and optical detection subsystems.
- Home Healthcare Providers:Reimbursement-dependent channels require FDA-cleared devices with patient-friendly interfaces and cellular connectivity.
- Research Institutes:Preclinical and clinical trial applications drive demand for experimental sensing modalities and custom form factors.
Procurement volume aggregates in hospital systems; home healthcare channels are gaining share fastest through remote patient monitoring reimbursement expansion.
Technology:
Supply concentration for specialized fabrication processes shapes which technology layers command premium positioning versus commodity pricing.
- Nanotechnology:Quantum dots, gold nanoparticles, and carbon nanotubes enable enhanced sensitivity and specificity in biosensing applications. Swiss research consortia in Basel and Zurich advance plasmonic nanoparticle assays for early cancer biomarker detection, leveraging localized surface plasmon resonance shifts.
- MEMS Technology:Micromachined pressure sensors, accelerometers, and gyroscopes integrate mechanical and electronic functions on silicon substrates. Taiwanese foundry capacity constraints for medical-grade MEMS expose supply chains to geopolitical friction and allocation prioritization.
- Wireless Communication:Bluetooth Low Energy, NFC, and proprietary protocols enable untethered data transmission.
- IoT Integration:Cloud-connected sensor ecosystems require cybersecurity architectures and API standardization.
- Bio-compatible Materials:ISO 10993-certified substrates and coatings ensure long-term implant safety and minimize foreign body response.
Commercial deployment concentrates in MEMS pressure and inertial sensors; nanotechnology-enabled diagnostics represent the fastest-climbing technology layer through sensitivity breakthroughs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States, Germany, and Japan concentrate demand through aging demographics and established reimbursement frameworks for sensor-enabled care. Hospital procurement committees and home healthcare providers drive divergent volume patterns across these markets.
United States
FDA 510(k) clearance pathways and remote patient monitoring reimbursement codes accelerate wearable biosensor deployment. Ambulatory surgical centers in Texas and Florida prioritize wireless telemetry architectures that compress recovery room length-of-stay. The FDA's de novo review process for novel sensing modalities without predicate matches extends timelines for breakthrough technologies.
Germany
EU MDR technical documentation mandates and statutory health insurance reimbursement for continuous glucose monitoring sustain electrochemical sensor demand. University hospitals in Munich and Heidelberg pioneer photon-counting CT detector deployments leveraging cadmium zinc telluride direct-conversion layers. The BfArM federal institute maintains stringent post-market surveillance requirements for active implantable devices.
Japan
METI's Society 5.0 super-aged society initiatives fund ambient fall-detection and medication-adherence sensor pilots in municipal housing complexes. Academic medical centers in Osaka and Tokyo deploy wearable cerebral oximeters during cardiac surgery, capitalizing on indium gallium arsenide sensitivity improvements. The PMDA's regulatory sandboxes in Kanagawa and Fukuoka prefectures accelerate pilot-to-commercialization timelines.
South Korea
MFDS certification requirements and national health insurance coverage for AI-enabled diagnostic devices stimulate edge-computing microcontroller adoption. Tertiary centers in Seoul and Busan combine time-series anomaly detection algorithms with sensor arrays for sepsis prediction. Domestic MEMS foundry capacity constraints expose supply chains to geopolitical friction and allocation prioritization.
China
NMPA innovation approval pathways and provincial reimbursement expansion for chronic disease management drive glucose monitoring volume. Research consortia in Beijing and Shanghai advance non-invasive optical glucose sensing through near-infrared spectroscopy. The country's dual carbon goals pressure manufacturers to redesign power budgets for extended battery autonomy in wearable devices.
Global Medical Sensor Market Competitive Landscape
Strategic partnerships dominate the current landscape as sensor manufacturers seek regulatory affairs infrastructure and specialized fabrication access. The vendor base organizes around three tiers: diversified electronics conglomerates with medical-grade certification, captive device OEMs with in-house sensor production, and specialized component suppliers focused on precision analog or optical subsystems. Consolidation pressures favor scale players with established European authorized representative networks and ISO 13485 quality management systems. M&A activity and technology licensing agreements represent the primary competitive moves for capability acquisition.
Within the diversified electronics tier, TE Connectivity and Texas Instruments Incorporated exemplify component suppliers leveraging interconnect and signal conditioning portfolios to anchor high-reliability patient monitoring platforms. Medtronic occupies a position representing captive manufacturing scale across glucose and cardiac sensor lines. These three entities illustrate the structural divergence between independent suppliers serving multiple device OEMs and vertically integrated healthcare conglomerates controlling end-to-end sensor-to-therapy value chains.
| Leading Market Players |
|---|
| TE Connectivity |
| Medtronic |
| Analog Devices, Inc. |
| Honeywell International Inc. |
| GE Healthcare |
| Danaher Corporation |
| Sensirion AG |
| Texas Instruments Incorporated |
| NXP Semiconductors |
| Others |
Supply & Pricing Matrix
Platinum-group metal indices cascade through electrochemical sensor manufacturing, compressing margins on disposable glucose strips while optical sensing platforms command premium positioning through indium gallium arsenide photodetector scarcity. Buyers in hospital procurement committees and home healthcare channels face divergent cost structures as raw material volatility feeds into tiered pricing architectures.
Pricing Analysis
Volume placements in electrochemical disposables run on razor-thin unit economics, while optical sensing platforms defend wider margins through photodetector sensitivity differentiation. Pricing stratifies across FDA-cleared premium tiers, ISO 13485-certified standard tiers, and economy tiers serving direct-to-consumer pharmacy channels. Cost compression in disposable consumables is intensifying because platinum-group metal catalyst layers expose manufacturers to iridium and ruthenium price swings. Home healthcare providers exhibit acute price sensitivity due to reimbursement code dependency, whereas academic medical centers prioritize measurement fidelity over unit cost.
Supply Chain Analysis
Domestic-content mandates in China's NMPA innovation pathways and South Korea's MFDS certification requirements are reshaping sourcing strategies for edge-computing microcontrollers and MEMS fabrication. Precision analog CMOS and MEMS manufacturing concentrates in Taiwan, South Korea, and Germany, drawing from iridium catalyst deposits, indium phosphide substrates, and biocompatible polymer feedstocks. Single-source vulnerability in Taiwanese foundry capacity exposes sensor OEMs to geopolitical friction and allocation prioritization. Distribution runs through tier-one device manufacturers, specialized component distributors, and direct hospital procurement contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The medical sensor sector is consolidating around scale players with dedicated regulatory affairs infrastructure, as EU MDR technical documentation mandates and FDA 510(k) predicate pathway limitations filter out undercapitalized entrants lacking ISO 13485 certification and European authorized representative networks.
For Market Incumbents: To counter MEMS foundry capacity constraints in Taiwan, TE Connectivity and Analog Devices should deepen backward integration into precision analog CMOS fabrication while securing long-term offtake agreements with South Korean alternative suppliers. Captive manufacturing scale across glucose and cardiac sensor lines, exemplified by Medtronic's vertical control, defends margin against commodity pricing pressure in disposable electrochemical strips. For New Entrants and Emerging Players: AI-enabled predictive analytics integration offers a technology-first wedge for sepsis and arrhythmia early warning systems, where edge-computing microcontroller convergence with time-series anomaly detection algorithms remains underpenetrated in ambulatory surgical centers. Target Japan's Society 5.0 municipal housing pilot programs in Kanagawa and Fukuoka prefectures for ambient fall-detection sensors, leveraging METI funding streams and regulatory sandboxes to bypass entrenched hospital procurement committee gatekeeping. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized optical subsystem suppliers with indium gallium arsenide photodetector expertise in Germany and Switzerland, where EU MDR Annex XIV post-market surveillance requirements have raised fixed cost structures beyond smaller players' capital reserves. Long-term viability hinges on acquisition targets maintaining contracted notified body relationships and ISO 10993 biocompatibility certification infrastructure. Monitor FDA de novo review timeline extensions for novel sensing modalities as the inflection indicator for distressed asset availability.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Investment | Annex XIV post-market surveillance mandates favor scale players with dedicated quality management personnel. |
| Backward Integration into MEMS Fabrication | Taiwanese foundry concentration risks expose supply chains to geopolitical friction and capacity allocation constraints. |
| AI-Enabled Predictive Analytics Development | Edge-computing microcontroller convergence enables subscription revenue models beyond hardware sales. |
| Hospital System Partnership Expansion | Unbundled procurement committees now issue separate RFPs for sensing layers, edge infrastructure, and cloud analytics. |
| Direct-to-Consumer Pharmacy Channel Entry | CVS Health and Walgreens Boots Alliance shelf space bypasses traditional durable medical equipment distributor markups. |
Research Methodology
Document review covered FDA 510(k) clearance databases, EU MDR technical documentation filings, and ISO 13485 certification registries, complemented by interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and regulatory affairs specialists at notified bodies. Secondary validation drew from CMS Medicare reimbursement data, hospital procurement databases, and customs records for platinum-group metal and indium phosphide trade flows. Bottom-up sensor shipment estimates and top-down healthcare expenditure triangulation anchored market sizing.
Segment-level projections across electrochemical, optical, piezoelectric, capacitive, and thermoelectric product types, patient monitoring and diagnostic imaging applications, and hospital versus home healthcare end users were synthesized over the projection horizon. CAGRs were derived from regression analysis against aging demographic trajectories, reimbursement code expansion patterns, and semiconductor foundry capacity utilization. Forecast inputs incorporated EU MDR implementation timelines, FDA review pathway velocity, and METI Society 5.0 funding disbursement rates.
Several conditions sit outside the modeled scope, including unannounced regulatory sandbox expansions beyond Kanagawa and Fukuoka prefectures, breakthrough device designation accelerations for novel sensing modalities, and geopolitical disruptions to Taiwanese foundry operations. Forecasts reflect documented assumptions regarding reimbursement code stability and raw material price index trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Incontinence Devices and Ostomy Market
Medical Devices
Electric Heated Eye Mask Market
Medical Devices
Erectile Dysfunction Shockwave Generators Market
Medical Devices
Global Suture Anchor Devices Market
Medical Devices
PET Injectors Market
Medical Devices
Buccal Drug Delivery System Market
Medical Devices
Brazil Clear Aligners Market
Medical Devices
Liquid Oxygen Devices Market
Medical Devices
Global Micro Guide Catheters Market
Medical Devices
Pericardial Patches Market
Medical Devices
Implantable Port Market
Medical Devices
Middle East and Africa Aligner Sheet Market
Medical Devices
Transportable Ventilator Market
Medical Devices
Alexandrite Gemstone Lasers Market
Medical Devices
Flexible and Semi-Rigid Ureteroscopy Market
Medical Devices
North America Intraocular Lens Market