
 Global Automatic Stair Climbing Wheelchair Market | 2026-2036
Global Automatic Stair Climbing Wheelchair Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automatic Stair Climbing Wheelchair Market Foresight
Carbon fiber composites are displacing aluminum alloy frames and is realigning unit economics toward lighter, higher-load platforms. Permobil leverages Scandinavian design heritage to sustain premium positioning across European long-term care contracts. Sunrise Medical anchors North American distribution through durable medical equipment networks. Scewo AG differentiates via gyroscopic balance algorithms that navigate spiral staircases where track-based systems fail.
An automatic stair climbing wheelchair is a motorized mobility device employing electromechanical tracks, articulated wheel clusters, or gyroscopic stabilization to ascend and descend staircases under operator or automated control, typically supporting passenger weights exceeding 120 kilograms across variable step geometries. Its primary purpose is eliminating architectural barriers for users with limited ambulatory function in buildings lacking elevator access. Powered wheelchairs command the largest revenue share due to battery density improvements and joystick precision, while track-based systems lead technology adoption because of proven traction on wet outdoor steps. Sensor-assisted navigation represents the fastest-expanding technology segment as LiDAR and IMU fusion enables autonomous stair detection.
The FDA classifies stair-climbing wheelchairs as Class II medical devices requiring 510(k) premarket notification, while the EU MDR mandates notified body intervention for electromechanical mobility aids with active therapeutic functions. Japan's METI enforces JIS T 9204 structural integrity standards for powered stair climbers used in public transit stations. Stakeholders must monitor reimbursement code expansions by Germany's statutory health insurers and the U.S. Centers for Medicare & Medicaid Services, as coverage determinations will decide whether institutional procurement volumes translate into individual consumer purchases.
Market Dynamics
The EU Medical Device Regulation is compressing certification timelines for Class II mobility aids, forcing manufacturers to consolidate track-based platform development and abandon legacy wheeled prototypes before notified body deadlines expire.
Growth Catalysts
- Aging Demographics:Municipal accessibility budgets in Germany, Japan, and Italy are expanding procurement quotas for powered stair-climbing units in public housing retrofits.
- Battery Density Gains:Lithium-silicon anode chemistry is extending operational range per charge, reducing institutional hesitancy over deployment downtime.
- Reimbursement Expansion:Germany's statutory health insurers are revising barrier-free home modification codes to cover stair-climbing assistive technology for individual consumers.
Market Restraints
- Carbon Fiber Supply Concentration:Toray Industries and Hexcel Corporation control premium aerospace-grade composite supply, creating input bottlenecks for frame manufacturers.
- Technical Limitation:Track-based systems fail on spiral staircases with riser angles exceeding 42 degrees, excluding historic European building stock.
- Regulatory Friction:FDA 510(k) premarket notification timelines for Class II medical devices average 180 days, delaying North American commercialization.
Strategic Opportunities
- Underpenetrated Geography:India's urban metro expansion and Aging Gracefully program create first-mover potential for track-based systems in Mumbai and Delhi transit stations.
- Technology Convergence:LiDAR-IMU sensor fusion is converging with gyroscopic stabilization algorithms to enable autonomous stair detection without operator joystick control.
- Channel Innovation:Direct-to-consumer digital platforms are bypassing durable medical equipment distributors in Germany, capturing margin previously lost to intermediary networks.
Industry Challenges
- Certification Timeline Compression:EU MDR technical documentation requirements for electromechanical mobility aids demand clinical evidence packages that strain small manufacturer resources.
- Integration Complexity:Stair-climbing wheelchairs must interface with legacy elevator control systems in retrofit installations, requiring site-specific engineering that defies standardization.
- Talent Scarcity:Mechatronics engineers with electromechanical track and gyroscopic stabilization expertise command premium compensation in Stuttgart and Munich, constraining R&D scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automatic Stair Climbing Wheelchair Market |
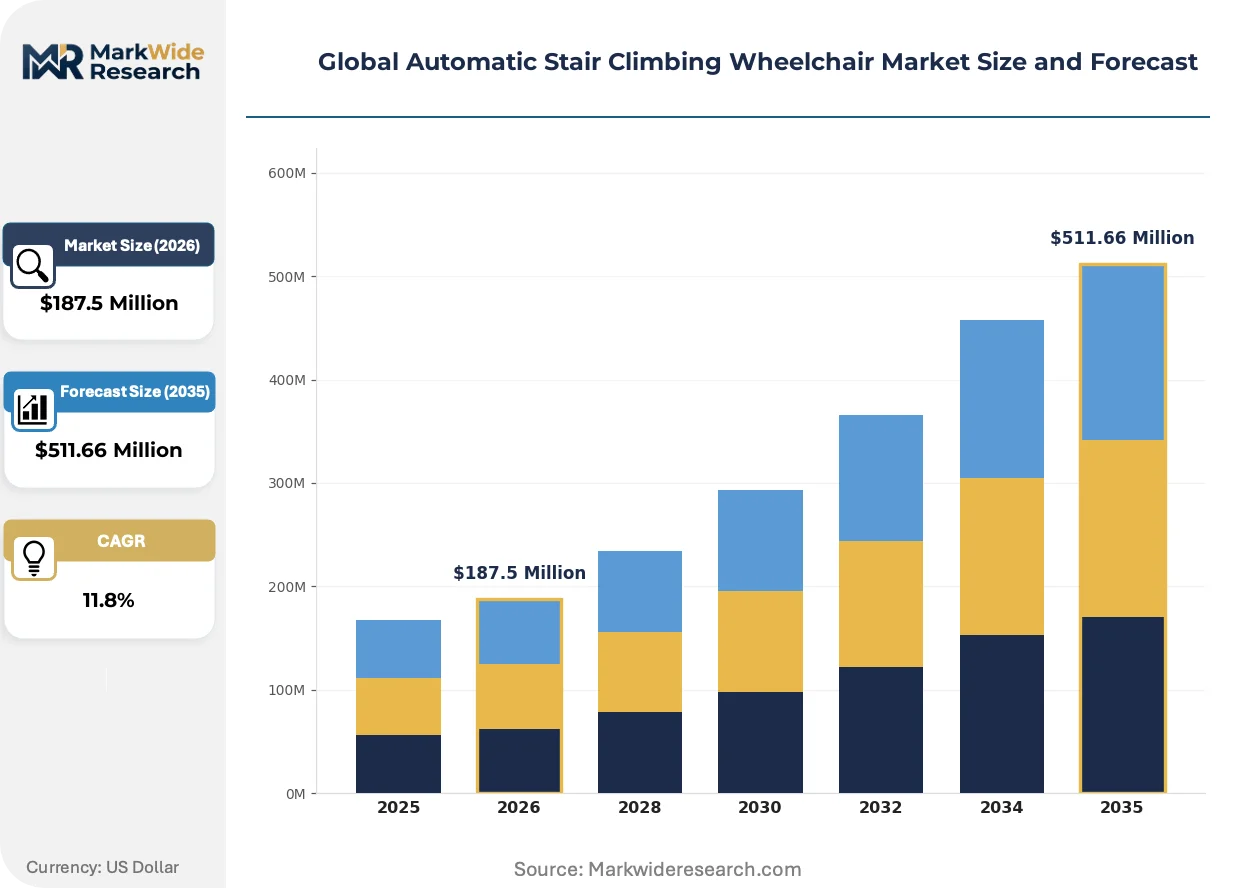
| Market Size in 2026 | $187.5 Million |
| Market Size in 2035 | $511.66 Million |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Control Wheelchairs, Powered Wheelchairs, Hybrid Models, Lightweight Wheelchairs Technology: Track-Based Systems, Wheel-Based Climbing, Gyroscopic Balance, Sensor-Assisted Navigation Application: Personal Mobility, Rehabilitation Facilities, Elderly Care Centers, Special Education Institutes End User: Individuals with Disabilities, Home Care Providers, Physical Therapy Clinics, Accessibility Equipment Vendors |
| Companies Covered | Scewo AG, AATGB Ltd., BFree Technology Ltd., TopChair, Permobil, Invacare Corporation, Sunrise Medical, Garaventa Lift Group, Mobius Mobility, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automatic Stair Climbing Wheelchair Market Shifts & Advancements
Sensor-assisted navigation architectures are displacing manual joystick control as the dominant human-machine interface, while reimbursement code expansions reshape procurement authority from institutions toward individual consumers.
LiDAR-IMU fusion systems are converging with gyroscopic balance algorithms to enable real-time stair geometry mapping without pre-programmed building surveys. Rehabilitation facilities in Germany are piloting these autonomous navigation packages for spiral staircase deployments where track-based electromechanical platforms previously failed. The structural consequence is converging with demand for retrofit accessibility in historic European building stock, compressing the addressable market gap between wheeled and track-based technologies.
The EU MDR is tightening clinical evidence requirements for electromechanical mobility aids with active therapeutic functions, mandating notified body intervention for stair-climbing wheelchairs previously self-certified under MDD. Manufacturers are consolidating technical documentation and post-market surveillance systems to satisfy Article 10 general safety and performance requirements. Class II device producers with existing MDD certificates are accelerating renewal submissions ahead of 2028 expiration deadlines to avoid market withdrawal.
Institutional procurement of powered stair-climbing units is fragmenting from centralized municipal tendering toward individual home modification assessments. Germany's statutory health insurers are reimbursing barrier-free retrofits directly to consumers, bypassing durable medical equipment networks that previously controlled distribution. This behavioral shift is most visible in Bavaria and Baden-Württemberg, where aging-in-place policy mandates accelerate individual ownership over facility-based deployment.
Global Automatic Stair Climbing Wheelchair Market Segmentation
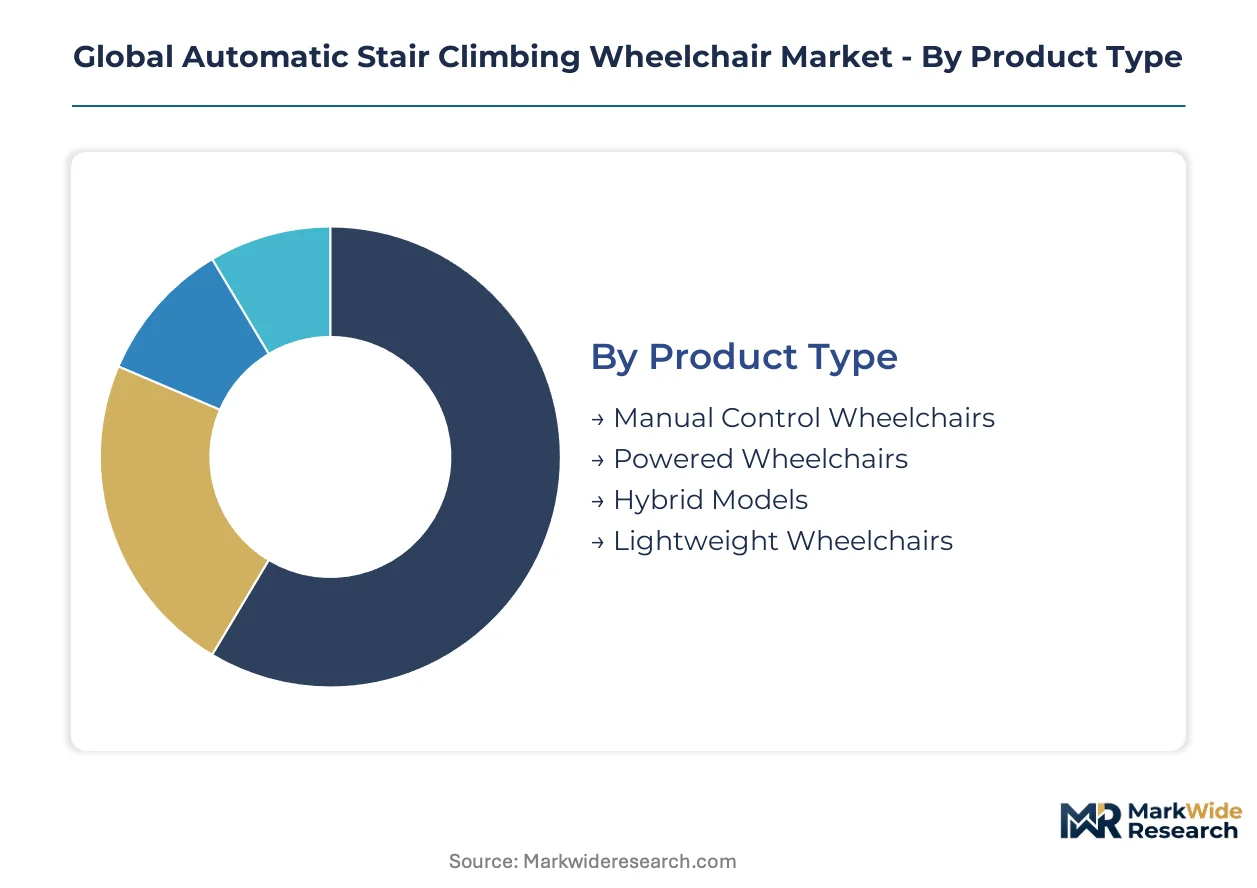
Segmentation in the automatic stair climbing wheelchair market reveals how technical specifications, reimbursement pathways, and end-use environments fragment demand. Procurement authority varies sharply across personal, institutional, and commercial channels, each imposing distinct performance and certification requirements.
Product Type:
Standardization dominates the low-cost tier while premium customization concentrates in clinical-grade configurations.
- Powered Wheelchairs:These units integrate lithium-silicon battery packs with electromechanical track drives, supporting passenger loads above 120 kilograms across variable step geometries. Demand clusters in German rehabilitation facilities where statutory health insurers reimburse barrier-free home modifications under federal accessibility codes. Battery density improvements are extending operational range per charge, reducing institutional hesitancy over deployment downtime.
- Manual Control Wheelchairs:Lever-operated mechanical systems requiring attendant assistance for stair navigation, constructed from aluminum alloy or carbon fiber composite frames. Procurement concentrates in Italian and Japanese elderly care centers where municipal accessibility budgets prioritize low-maintenance equipment for facility-based deployment. These systems avoid the regulatory complexity of powered medical devices while sacrificing independent operation.
- Hybrid Models:Dual-mode platforms switch between conventional wheeled mobility and stair-climbing track configurations.
- Lightweight Wheelchairs:Carbon fiber frame constructions optimized for portability and manual transport between sites.
Most installed capacity flows through Powered Wheelchairs. Expansion is steepest in Hybrid Models.
Technology:
Cost tiers separate proven track-based electromechanical platforms from emerging sensor fusion architectures commanding R&D premiums.
- Track-Based Systems:Electromechanical crawler mechanisms with rubberized treads grip step edges at angles up to 42 degrees, dominating outdoor and wet-condition deployments. Adoption concentrates in German and Japanese transit station retrofits where JIS T 9204 and EU MDR certification requirements favor proven traction systems over experimental alternatives. The EU MDR is compressing certification timelines for Class II mobility aids, forcing manufacturers to consolidate track-based platform development.
- Sensor-Assisted Navigation:LiDAR-IMU fusion architectures enable real-time stair geometry mapping without pre-programmed building surveys. Demand is accelerating in Bavarian rehabilitation facilities piloting autonomous navigation for spiral staircase deployments where track-based systems previously failed. Germany's statutory health insurers are reimbursing these premium configurations for individual consumers under revised barrier-free home modification codes.
- Wheel-Based Climbing:Articulated wheel clusters with independent motor control for each contact point.
- Gyroscopic Balance:Stabilization algorithms maintaining platform orientation during ascent and descent.
Track-Based Systems carry the majority of current installations. Sensor-Assisted Navigation is gaining share fastest.
Application:
Volume concentrates in institutional procurement while margin expansion follows the shift toward individual ownership.
- Rehabilitation Facilities:Clinical-grade deployments requiring FDA 510(k) or EU MDR Class II certification, with procurement governed by durable medical equipment networks in North America and statutory health insurance reimbursement in Germany. These installations prioritize patient transfer safety and compatibility with existing elevator control systems.
- Personal Mobility:Individual ownership models bypassing institutional procurement channels through direct-to-consumer digital platforms in Germany. Germany's statutory health insurers are revising reimbursement codes to cover stair-climbing assistive technology directly for consumers, fragmenting procurement authority from centralized municipal tendering.
- Elderly Care Centers:Facility-based deployments in Japan and Italy where aging demographics strain municipal accessibility budgets.
- Special Education Institutes:School and university installations requiring compliance with accessibility mandates.
Rehabilitation Facilities account for the largest installed base. Personal Mobility shows the steepest expansion trajectory.
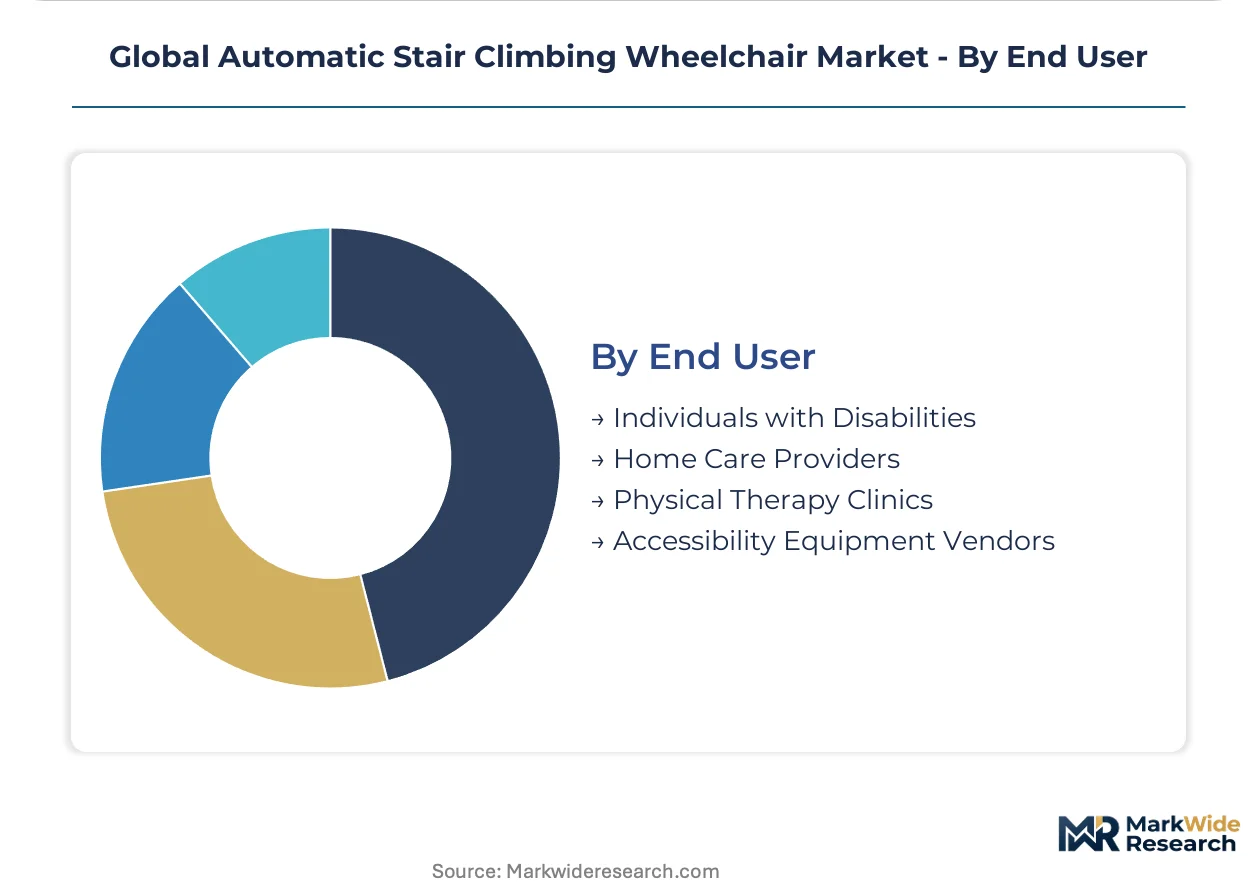
End User:
Customer type determines whether procurement flows through clinical reimbursement codes, municipal tenders, or commercial distribution networks.
- Individuals with Disabilities:End consumers navigating reimbursement pathways for home modification coverage, increasingly direct purchasers in Germany's Bavaria and Baden-Württemberg regions where aging-in-place policies accelerate individual ownership.
- Home Care Providers:Agencies deploying equipment across multiple client residences, prioritizing lightweight configurations for transport efficiency.
- Physical Therapy Clinics:Outpatient facilities integrating stair-climbing units into rehabilitation protocols.
- Accessibility Equipment Vendors:Distributors and rental operators serving retrofit construction projects.
Individuals with Disabilities represent the dominant addressable population. Home Care Providers are expanding procurement most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors the global automatic stair climbing wheelchair industry through its concentration of mechatronics engineering talent and proximity to German statutory health insurance reimbursement authorities. Procurement patterns concentrate in four countries where regulatory frameworks and aging demographics create distinct commercial environments.
United States
FDA 510(k) premarket notification timelines averaging 180 days delay commercialization for Class II medical device entrants. Medicare coverage determinations for stair-climbing assistive technology remain inconsistent across regional contractors, constraining individual consumer purchases despite institutional procurement growth. The Boston-Cambridge corridor hosts rehabilitation engineering research clusters advancing sensor fusion algorithms for autonomous navigation.
Germany
Statutory health insurers in Bavaria and Baden-Württemberg now reimburse barrier-free home modifications covering stair-climbing wheelchairs for individual consumers. EU MDR certification requirements compress technical documentation timelines for electromechanical mobility aids, favoring established track-based platform manufacturers. Munich's medical technology cluster concentrates notified body relationships and post-market surveillance expertise for Class II device compliance.
Japan
METI enforces JIS T 9204 structural integrity standards for powered stair climbers deployed in public transit stations. Municipal accessibility budgets in Tokyo and Osaka prioritize track-based systems for outdoor wet-condition reliability. Nagoya's industrial automation ecosystem supplies precision electromechanical components for crawler mechanism manufacturing.
Italy
Historic building stock with spiral staircases exceeding 42-degree riser angles excludes track-based systems from significant retrofit addressable market. Regional health authorities in Lombardy and Veneto procure lever-operated manual control wheelchairs for elderly care center deployment. Milan's rehabilitation engineering institutes pilot gyroscopic stabilization prototypes for constrained architectural environments.
India
The Aging Gracefully program and urban metro expansion in Mumbai and Delhi create first-mover potential for track-based transit station installations. Central Drugs Standard Control Organization medical device regulations are harmonizing with ISO standards for powered mobility aids. Bangalore's medical electronics manufacturing cluster attracts component suppliers serving domestic assembly operations.
Global Automatic Stair Climbing Wheelchair Market Competitive Landscape
Strategic partnerships dominate the current landscape as manufacturers consolidate track-based platform development ahead of EU MDR certification deadlines. The vendor base separates into three tiers: Scandinavian design heritage premium positioning, North American durable medical equipment network anchoring, and specialized gyroscopic stabilization engineering. Two competitive vectors define positioning: technology licensing agreements for sensor fusion architectures and backward integration into carbon fiber composite frame production.
Among European specialists, Scewo AG represents the algorithm-driven navigation archetype, while Permobil exemplifies premium-tier positioning through long-term care contract penetration. Sunrise Medical anchors North American distribution scale. These three occupy distinct competitive spaces without direct product overlap, reflecting market segmentation between autonomous navigation capability, institutional procurement relationships, and durable medical equipment channel control.
| Leading Market Players |
|---|
| Scewo AG |
| AATGB Ltd. |
| BFree Technology Ltd. |
| TopChair |
| Permobil |
| Invacare Corporation |
| Sunrise Medical |
| Garaventa Lift Group |
| Mobius Mobility |
| Others |
Supply & Pricing Matrix
Aerospace-grade carbon fiber composite pricing indices from Toray Industries and Hexcel Corporation cascade through frame manufacturing into three-tier pricing structures across premium, standard, and economy levels. Battery cell cost volatility from lithium-silicon anode chemistry suppliers feeds directly into powered wheelchair unit economics, compressing margins for mid-tier manufacturers while premium brands absorb fluctuations through long-term care contract pricing.
Pricing Analysis
Input-cost pass-through from carbon fiber suppliers dominates pricing dynamics for frame manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates EU MDR-certified clinical-grade units from self-certified institutional models and lever-operated manual alternatives. Pricing pressure stems from statutory health insurer reimbursement ceilings in Germany that cap consumer-facing prices despite rising certification compliance costs. Rehabilitation facilities demonstrate lowest price sensitivity due to bundled procurement budgets, while individual consumers in emerging markets exhibit highest elasticity.
Supply Chain Analysis
Single-source vulnerability sits with Japanese precision electromechanical component suppliers serving crawler mechanism manufacturers. Manufacturing concentrates in Germany, Japan, and China, with carbon fiber frames drawing from aerospace composite specialists in the United States and Japan. Supply chain risk centers on tariff exposure for battery cells crossing from South Korean cell plants into European assembly operations. Distribution runs through durable medical equipment networks in North America and direct-to-consumer digital platforms in Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story where reimbursement code expansions in Germany are shifting procurement authority toward premium sensor-assisted navigation configurations. The structural transition from institutional tendering to individual ownership rewards manufacturers with clinical evidence packages and notified body relationships.
For Market Incumbents: Deepen backward integration into carbon fiber composite frame production to escape Toray-Hexcel supply bottlenecks. Consolidate technical documentation systems ahead of EU MDR Article 10 compliance deadlines to defend against emerging sensor fusion specialists threatening track-based platform dominance. Prioritize Munich and Stuttgart engineering talent retention through captive R&D facilities.
For New Entrants and Emerging Players: Enter via India's Aging Gracefully program and Mumbai-Delhi metro expansion projects where CDSCO harmonization with ISO standards creates first-mover windows before established track-based manufacturers localize production. Target transit station retrofit applications with simplified electromechanical platforms that bypass spiral staircase complexity. Deploy through government procurement channels rather than DME networks to circumvent entrenched distribution.
For Investors and Strategic Acquirers: Asymmetric upside sits with gyroscopic stabilization algorithm developers possessing autonomous navigation IP applicable to constrained European historic building stock. Five-to-ten-year viability hinges on reimbursement code convergence across German statutory health insurers and CMS coverage determination harmonization. Watch for FDA 510(k) clearance acceleration signals as the inflection indicator for North American consumer market unlock.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Certification Acceleration | Notified body relationships in Munich compress technical documentation timelines for Class II electromechanical mobility aids. |
| LiDAR-IMU Sensor Fusion Development | Autonomous stair detection algorithms enable spiral staircase deployments where track-based systems fail in Italian historic stock. |
| Direct-to-Consumer Platform Launch | Digital distribution in Bavaria captures margin previously lost to durable medical equipment intermediary networks. |
| Carbon Fiber Frame Backward Integration | In-house composite production insulates against Toray-Hexcel aerospace-grade supply concentration and pricing volatility. |
| Indian Transit Station Partnership | Mumbai metro accessibility mandates under Aging Gracefully create installed base for service contract annuity streams. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged rehabilitation facility procurement directors, biomedical engineers specializing in electromechanical mobility aids, statutory health insurance reimbursement officers in Germany, and durable medical equipment network category managers. Secondary validation drew from FDA 510(k) premarket notification databases, EU MDR notified body technical documentation filings, JIS T 9204 structural integrity test records, and CMS Medicare coverage determination archives. Bottom-up unit shipment modeling triangulated against top-down reimbursement expenditure analysis.
Historical reference periods anchored volume and value projections across the modeling period. Segmentation dimensions spanned product type, technology architecture, application environment, and end-user procurement authority. CAGRs were derived from polynomial trend fitting of installed base expansion correlated with reimbursement code adoption curves. Forecast inputs incorporated battery energy density improvement trajectories and EU MDR certification timeline compression effects.
Inputs from regulatory filing databases and health insurer reimbursement bulletins were available through the study window; gaps in real-time municipal procurement tender outcomes introduce uncertainty bands around institutional volume assumptions. Forecasts reflect documented assumptions regarding statutory health insurance code expansion velocity and FDA review timeline normalization. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Neuroendoscopy Devices Market
Medical Devices
Lancing Devices and Lancets Market
Medical Devices
Lung Preservation Systems Market
Medical Devices
Engine-Driven Endodontic File Market
Medical Devices
India Respiratory Devices Market
Medical Devices
Neurovascular Microcatheter Market
Medical Devices
Japan Artificial Organs and Bionic Implants Market
Medical Devices
Muscle Stimulation Devices Market
Medical Devices
Double-Lumen Biliary Catheters Market
Medical Devices
Canada Contraceptive Devices Market
Medical Devices
Foot Ulcer Sensors Market
Medical Devices
Bioimpedance Analyzers Market
Medical Devices
Germany Drug Delivery Devices Market
Medical Devices
Middle East and Africa Electroencephalography Devices Market
Medical Devices
Medical Devices Clinical Trials Market
Medical Devices
Airotar Handpiece Market