
 Cyberknife Technology Market | 2026-2036
Cyberknife Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Cyberknife Technology Market Outlook
Buyer concentration among hospital networks is decoupling from traditional equipment vendor relationships as integrated delivery systems centralize radiation oncology capital decisions. Accuray Incorporated leverages its installed base of robotic linac platforms to sustain service revenue streams across North American academic medical centers. Elekta AB competes through linear accelerator interoperability with existing vault infrastructure, while Varian Medical Systems anchors proton therapy adjacencies that complement photon-based stereotactic programs.
Cyberknife technology denotes a frameless robotic radiosurgery system employing a compact linear accelerator mounted on a six-axis robotic arm, delivering sub-millimeter precision through real-time image guidance and adaptive beam tracking. The platform synchronizes radiation delivery with patient respiratory motion, enabling single-session or hypofractionated treatment of tumors previously considered inoperable or requiring conventional fractionation. Robotic systems command the dominant share of product value given capital intensity and recurring service contracts, while oncology applications generate the majority of procedure volume across brain, lung, liver, and prostate indications. Software solutions represent the fastest-expanding margin pool as artificial intelligence-enabled treatment planning reduces physicist labor hours per fraction.
The FDA's breakthrough device designation pathway and the EU Medical Device Regulation's Class III requirements for active therapeutic devices shape product development timelines and market access conditions across the United States and European Union. Japan's Ministry of Health, Labour and Welfare maintains distinct reimbursement categories for stereotactic body radiation therapy that influence hospital adoption thresholds. Stakeholders must monitor evolving CMS national coverage determinations for hypofractionated regimens and their direct impact on capital equipment return-on-investment models.
Market Dynamics
Hospital procurement centralization is the dominant structural force reshaping vendor relationships in the Cyberknife Technology Market. Integrated delivery networks now consolidate radiation oncology capital decisions across multiple sites, decoupling purchasing from traditional equipment vendor lock-ins and compressing sales cycles for robotic linac platforms.
Growth Catalysts
- CMS National Coverage Determinations:Expanded reimbursement for hypofractionated regimens accelerates hospital capital equipment return-on-investment models across United States tertiary care centers.
- Japan's MHLW Reimbursement Categories:Distinct stereotactic body radiation therapy payment tiers lower hospital adoption thresholds and sustain procedure volume growth.
- Artificial Intelligence-Enabled Planning:Machine learning algorithms reduce physicist labor hours per fraction, expanding treatment capacity without proportional staffing increases.
Market Restraints
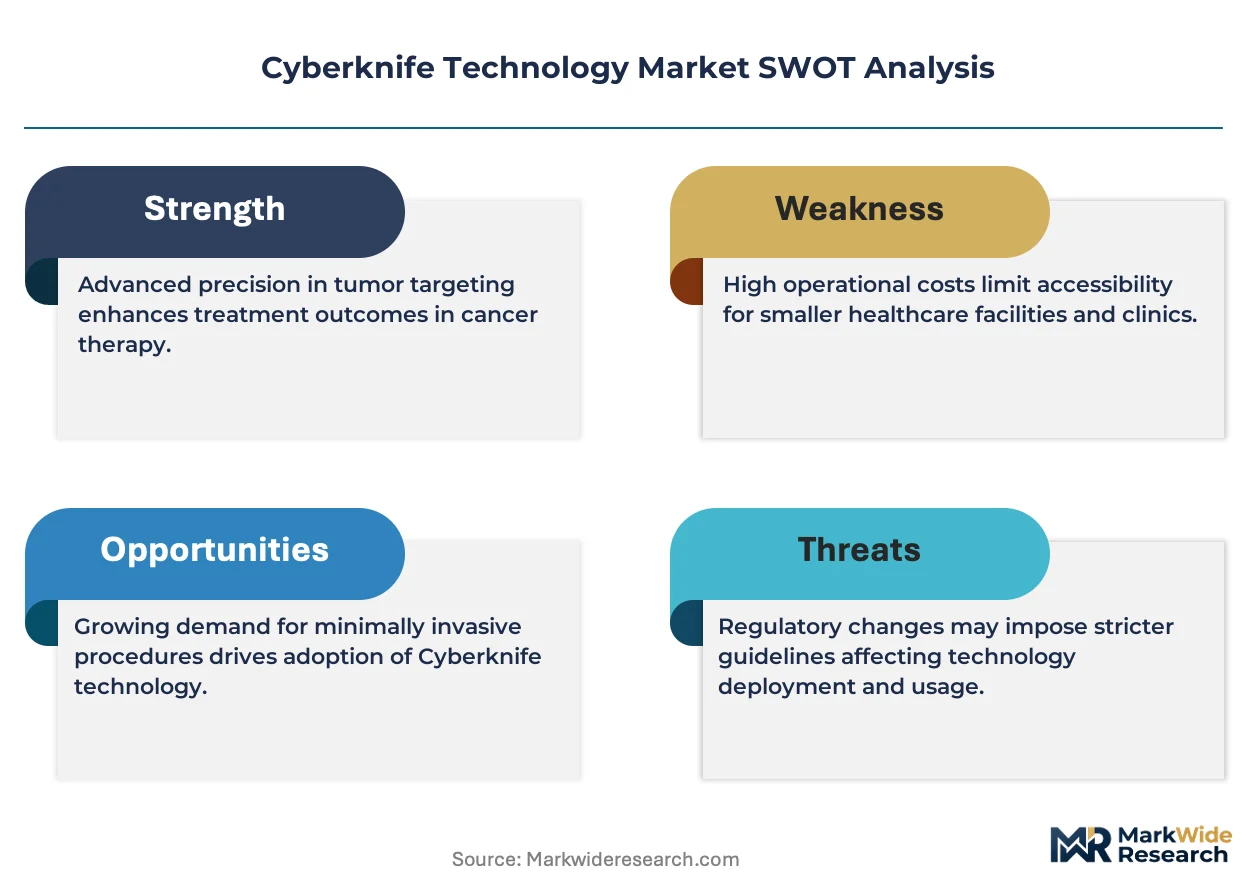
- Vault Infrastructure Requirements:Existing radiation shielding specifications limit installation sites to purpose-built facilities or expensive retrofit projects.
- EU MDR Class III Certification:Active therapeutic device requirements extend product development timelines and increase regulatory compliance costs for stereotactic systems.
- Linear Accelerator Supply Concentration:Specialized magnetron and klystron component sourcing depends on a limited supplier base concentrated in Germany and Japan.
Strategic Opportunities
- India's Tertiary Care Expansion:Government hospital infrastructure programs create installation sites for precision oncology platforms outside saturated North American and European markets.
- Real-Time MRI Integration:Convergence of magnetic resonance imaging with robotic delivery systems enables soft-tissue tracking during treatment.
- Software-as-a-Service Distribution:Cloud-based treatment planning and adaptive protocol updates reduce upfront capital barriers for smaller oncology networks.
Industry Challenges
- Medical Physicist Talent Scarcity:Specialized training requirements for stereotactic quality assurance and commissioning create bottlenecks for new site activation.
- PACS and EMR Integration Complexity:Legacy hospital information system architectures require custom interface development for seamless robotic treatment workflow.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cyberknife Technology Market |
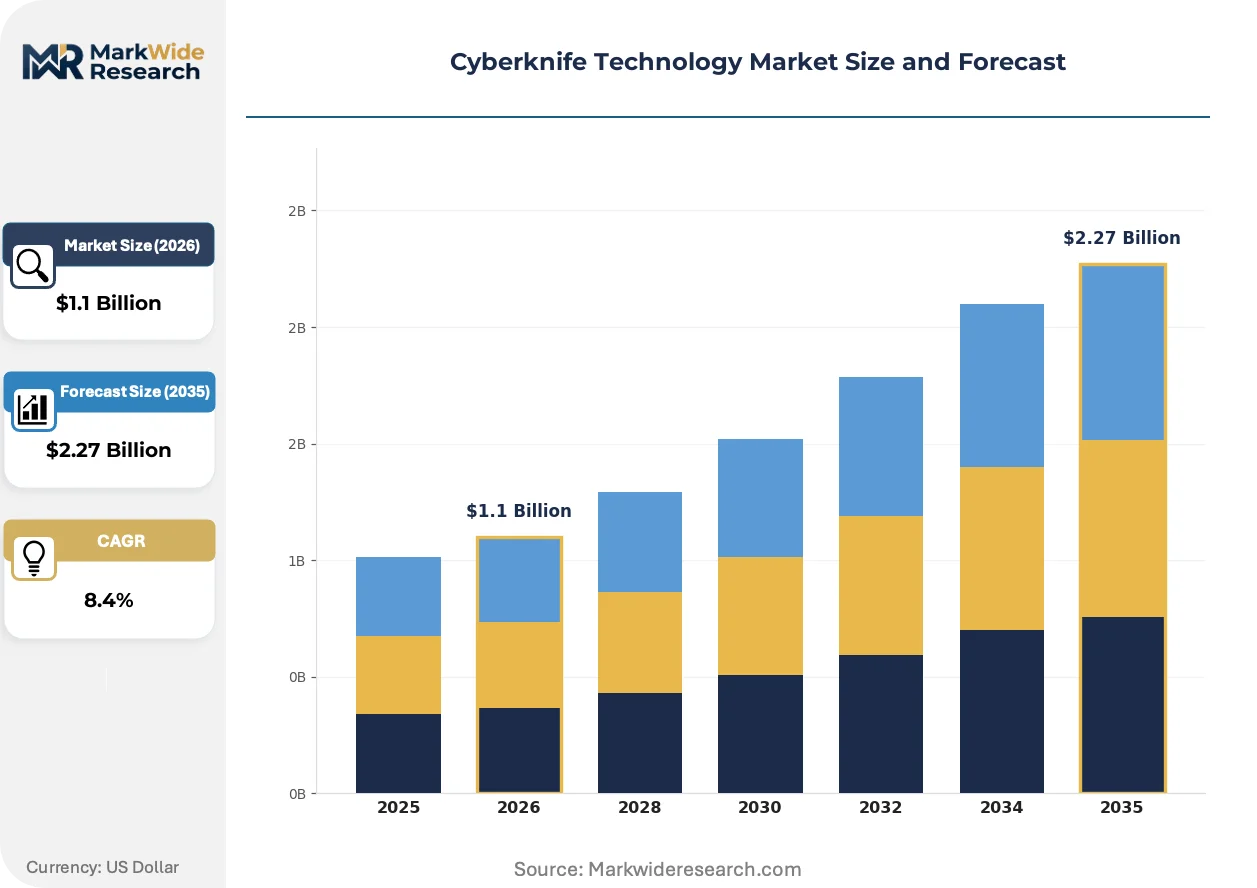
| Market Size in 2026 | $1.1 Billion |
| Market Size in 2035 | $2.27 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Robotic Systems, Radiation Delivery Systems, Treatment Planning Systems, Software Solutions Application: Oncology, Neurosurgery, Palliative Care, Orthopedic Surgery End User: Hospitals, Ambulatory Surgical Centers, Oncology Clinics, Research Institutions Technology: Image Guidance, Motion Tracking, Advanced Visualization, Multi-Modal Imaging |
| Companies Covered | BrainLab, ViewRay, Inc., Accuray Incorporated, GE Healthcare, Nucletron B.V., Elekta AB, Siemens Healthineers, Hitachi America, Varian Medical Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cyberknife Technology Market Strategic Shifts
Real-time adaptive delivery systems are compressing the gap between imaging and treatment execution. Three concurrent developments—hardware miniaturization, regulatory pathway acceleration, and procurement model transformation—are restructuring competitive positioning across robotic radiation platforms.
Compact linear accelerator designs mounted on six-axis robotic arms are electrifying precision oncology workflows. Academic medical centers in Germany and Japan deploy these systems for single-session treatments of previously inoperable lesions. The technology is electrifying margins by reducing total treatment fractions while maintaining reimbursement parity with conventional regimens.
The FDA's breakthrough device designation pathway compresses clinical trial timelines for stereotactic systems. Manufacturers submit predicate device comparisons rather than full pivotal studies, accelerating market access for next-generation platforms. United States hospital networks respond by compressing vendor evaluation cycles and prioritizing systems with existing designation status.
Service contract unbundling is fragmenting traditional vendor revenue streams. North American integrated delivery networks now separately negotiate hardware, software, and maintenance components, pressuring bundled pricing structures. This shift is most visible among United States academic medical centers with in-house biomedical engineering capabilities.
Cyberknife Technology Market Segmentation
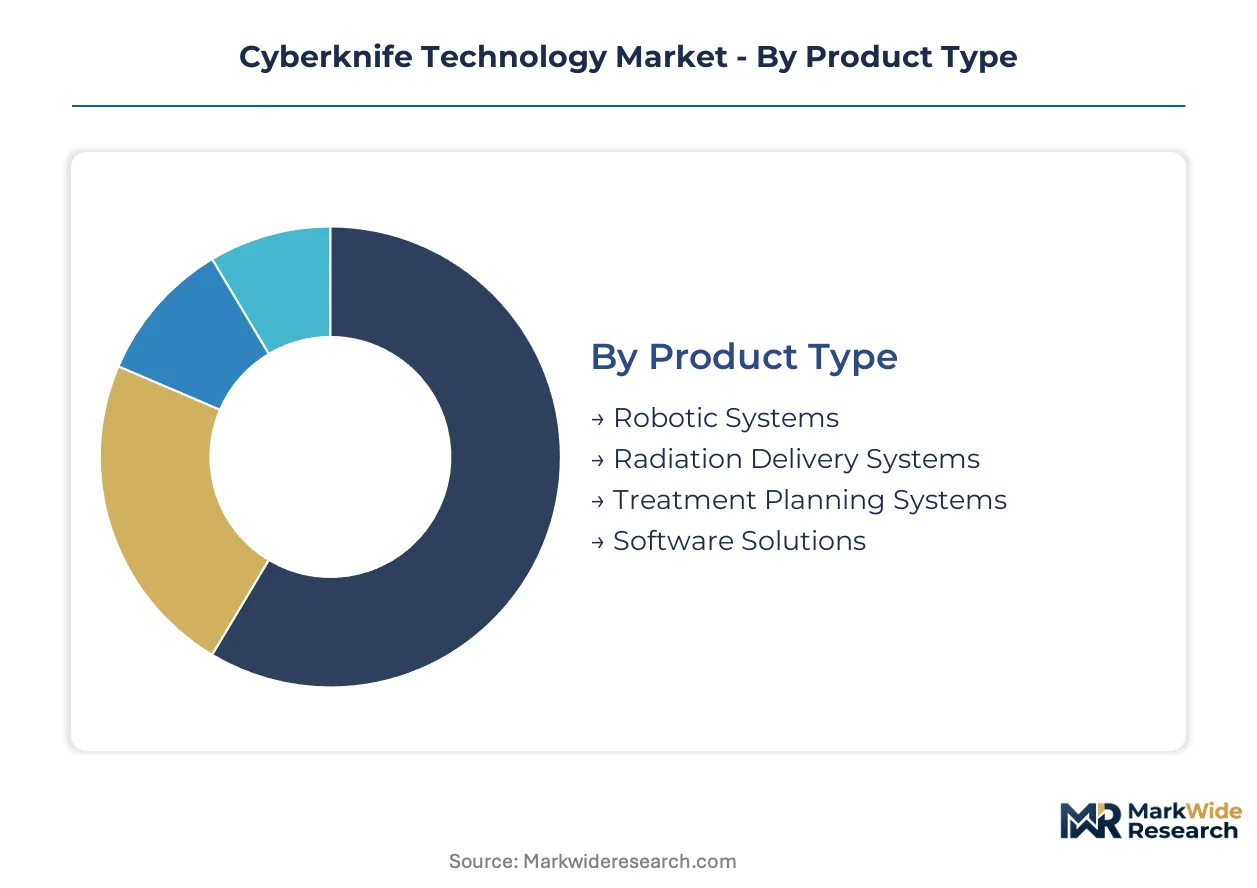
Segmentation in the Cyberknife Technology Market reveals how capital intensity, clinical workflow integration, and reimbursement structures concentrate value across distinct product and customer configurations. Understanding these partitions exposes where procurement centralization and regulatory pathways create divergent margin profiles.
Product Type:
Supply concentration in precision oncology hardware tilts procurement leverage toward vendors with captive manufacturing of robotic linac platforms and proprietary software ecosystems.
- Robotic Systems:Six-axis robotic arms mounting compact linear accelerators deliver sub-millimeter targeting precision through real-time respiratory synchronization. Demand clusters in United States academic medical centers where capital budgets for precision oncology infrastructure remain prioritized and service contracts extend vendor relationships over decade-long depreciation cycles.
- Radiation Delivery Systems:Specialized magnetron and klystron components generate therapeutic photon beams with intensity-modulated arc capabilities. Supply chain sourcing concentrates in Germany and Japan, creating procurement vulnerability for hospital networks seeking to diversify vendor relationships.
- Treatment Planning Systems:Dose calculation engines integrating CT, MRI, and PET imaging datasets for fractionation optimization.
- Software Solutions:Artificial intelligence-enabled contouring and adaptive planning modules reducing physicist labor hours per fraction.
Today's leader: Robotic Systems. Tomorrow's challenger: Software Solutions.
Application:
Clinical adoption patterns track reimbursement parity between hypofractionated stereotactic regimens and conventional fractionation, with procedure volume concentrating where payment tiers reward reduced treatment sessions.
- Oncology:Brain, lung, liver, and prostate tumors treated through single-session or hypofractionated protocols previously requiring surgical resection or conventional radiation. Demand concentrates in tertiary care centers across the United States, Germany, and Japan where stereotactic body radiation therapy reimbursement categories sustain procedure volume growth.
- Neurosurgery:Arteriovenous malformations, trigeminal neuralgia, and functional disorders addressed through frameless radiosurgical alternatives to open craniotomy. Academic medical centers in Japan deploy these systems for lesions considered inoperable through conventional surgical approaches.
- Palliative Care:Pain management and symptom control for metastatic disease through targeted radiation delivery.
- Orthopedic Surgery:Bone metastases and soft-tissue sarcomas treated with precision dose escalation.
Oncology commands current revenue concentration. Neurosurgery presents the steepest expansion trajectory as frameless protocols displace invasive alternatives.
End User:
Customer concentration among integrated delivery networks is compressing sales cycles and fragmenting traditional vendor lock-ins across hardware, software, and maintenance components.
- Hospitals:Tertiary care centers and academic medical centers with dedicated radiation oncology departments and existing vault infrastructure. Procurement centralization across United States hospital networks decouples purchasing from traditional equipment vendor relationships.
- Ambulatory Surgical Centers:Outpatient facilities seeking to expand oncology service lines without full hospital capital commitment. India's government hospital infrastructure programs create installation sites for these platforms outside saturated developed markets.
- Oncology Clinics:Specialized cancer treatment centers focusing on precision radiation protocols.
- Research Institutions:Clinical trial sites investigating hypofractionated regimens and adaptive delivery techniques.
Hospitals dominate current installed base. Ambulatory Surgical Centers are climbing the fastest as site-of-care migration accelerates.
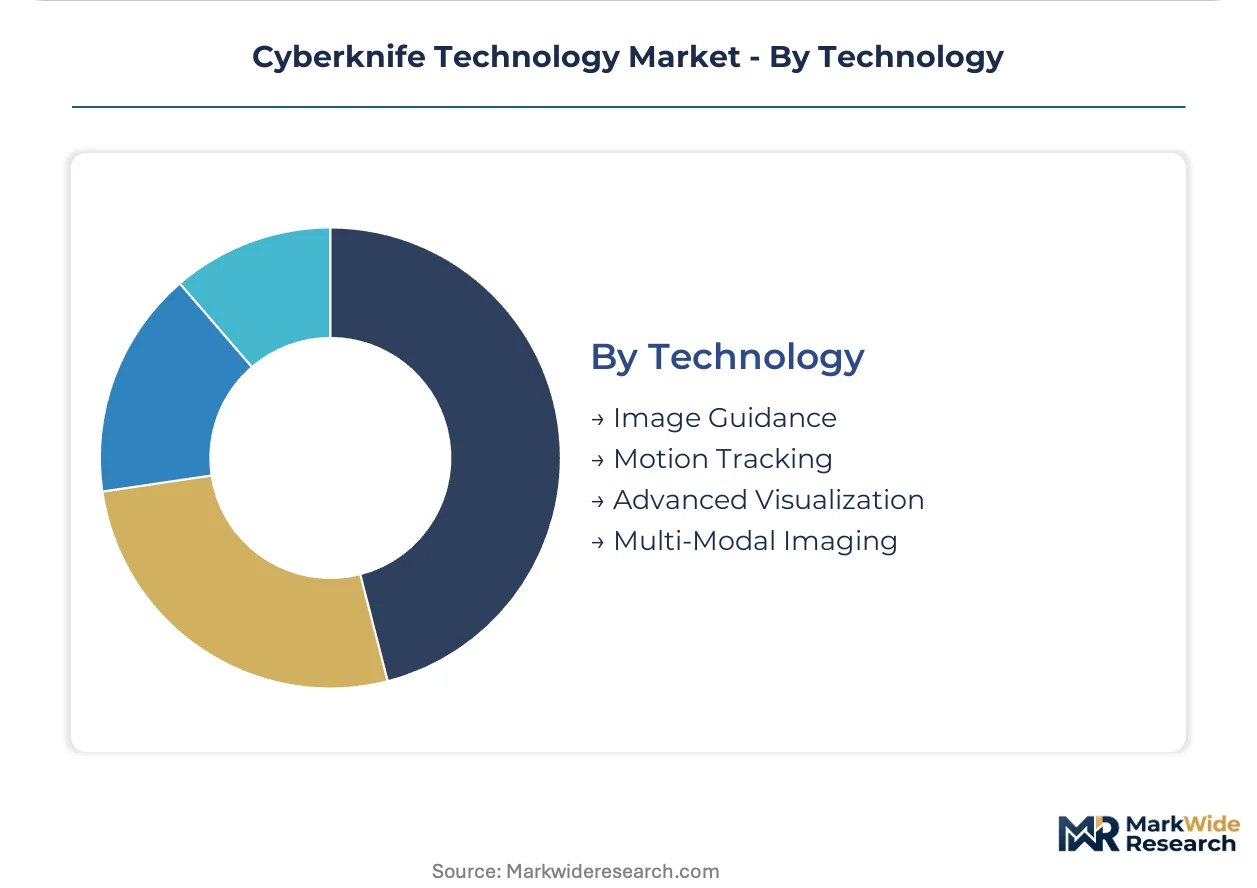
Technology:
Technology differentiation increasingly hinges on real-time integration between imaging modalities and beam delivery, with regulatory pathways for breakthrough device designation compressing development timelines for convergent platforms.
- Image Guidance:Stereoscopic X-ray and cone-beam CT systems enabling sub-millimeter patient positioning verification. FDA breakthrough device designation pathways accelerate clinical trial timelines for next-generation stereotactic platforms incorporating these capabilities.
- Motion Tracking:Respiratory and intrafraction motion compensation through robotic beam adaptation. Germany's academic medical centers deploy these systems for lung and liver lesions where organ motion previously precluded single-session treatment.
- Advanced Visualization:Three-dimensional dose display and biological effective dose mapping for physician decision support.
- Multi-Modal Imaging:Real-time MRI integration enabling soft-tissue tracking during treatment delivery.
Image Guidance anchors current competitive positioning. Multi-Modal Imaging represents the fastest-growing trajectory as magnetic resonance convergence enables new clinical indications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's precision oncology infrastructure outpaces Japan's installed base density, yet both markets concentrate procurement decisions among consolidated hospital networks. The United States maintains the largest aggregate capital commitment to robotic radiation platforms. India's government hospital expansion programs are creating installation opportunities outside saturated developed markets.
United States
Tertiary care centers and academic medical centers drive capital equipment demand through prioritized precision oncology budgets. FDA breakthrough device designation pathways compress clinical trial timelines for stereotactic systems seeking market access. The Greater Boston and Houston medical corridors host concentrated deployments of frameless robotic radiosurgery platforms for single-session tumor treatments.
Germany
Academic medical centers deploy robotic linac systems for lung and liver lesions where respiratory motion previously precluded single-session treatment. EU MDR Class III certification requirements for active therapeutic devices extend product development timelines but establish quality benchmarks for hospital procurement. The Munich and Heidelberg oncology clusters anchor stereotactic body radiation therapy procedure volume growth through integrated research-treatment workflows.
Japan
Ministry of Health, Labour and Welfare reimbursement categories for stereotactic body radiation therapy sustain hospital adoption thresholds and procedure volume. Capital budgets at tertiary care centers prioritize precision oncology infrastructure for inoperable lesions. Tokyo and Osaka medical centers lead frameless radiosurgical alternatives to open craniotomy for arteriovenous malformations and functional disorders.
India
Government hospital infrastructure programs create installation sites for precision oncology platforms outside saturated North American and European markets. Ambulatory surgical centers seek to expand oncology service lines without full hospital capital commitment. Maharashtra and Karnataka tertiary care networks are consolidating procurement decisions for robotic radiation platforms across multiple metropolitan sites.
Cyberknife Technology Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across hardware, software, and service contract segments. The vendor base organizes around three strategic archetypes: integrated radiation therapy conglomerates with proton and photon portfolios, robotic platform pure-plays with captive software ecosystems, and imaging-system incumbents expanding into therapeutic delivery. Dominant competitive moves include service contract unbundling to fragment traditional vendor lock-ins and real-time MRI integration partnerships to enable soft-tissue tracking capabilities.
Among integrated therapy conglomerates, Siemens Healthineers and GE Healthcare occupy positions spanning diagnostic imaging through therapeutic delivery, while Accuray Incorporated exemplifies the robotic pure-play archetype with its installed base of frameless radiosurgery platforms. Elekta AB and Varian Medical Systems sit within the radiation therapy specialist tier, with the former competing through linear accelerator interoperability and the latter anchoring proton therapy adjacencies that complement photon-based stereotactic programs.
| Leading Market Players |
|---|
| BrainLab |
| ViewRay, Inc. |
| Accuray Incorporated |
| GE Healthcare |
| Nucletron B.V. |
| Elekta AB |
| Siemens Healthineers |
| Hitachi America |
| Varian Medical Systems |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up radiation therapy specialists have consolidated service contract portfolios across North American hospital networks, compressing vendor pricing power while extending payment terms for magnetron and klystron component procurement.
Pricing Analysis
Capacity additions in Germany and Japan are reshaping price floors for robotic linac platforms as Elekta AB and Hitachi America expand manufacturing footprints. Three-tier pricing structure across premium, standard, and economy levels separates academic medical centers with full-service contracts from ambulatory surgical centers seeking unbundled software subscriptions. Cost compression in the standard tier is intensifying because integrated delivery networks now separately negotiate hardware, software, and maintenance components. Ambulatory surgical centers exhibit the highest price sensitivity due to capital constraints, while United States academic medical centers prioritize clinical capability over procurement cost.
Supply Chain Analysis
EU MDR Class III certification requirements for active therapeutic devices gate component sourcing to qualified suppliers with established quality management systems. Manufacturing concentrates in Germany, Japan, and the United States for specialized magnetron and klystron components. Raw material dependencies rest on high-purity copper for waveguide fabrication, rare-earth magnets for beam steering, and precision-machined tungsten for collimation. Single-source vulnerability persists for compact linear accelerator tubes sourced from two Japanese suppliers. Distribution runs through authorized service organizations with certified biomedical engineering capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through artificial intelligence-enabled treatment planning software that reduces physicist labor hours per fraction while maintaining reimbursement parity with conventional regimens.
For Market Incumbents: Deepen vertical integration into magnetron and klystron component manufacturing to reduce supply vulnerability from Japanese suppliers. Secure FDA breakthrough device designation for next-generation real-time MRI integration platforms before competitor submissions compress evaluation windows. Lock in decade-long service contracts with United States academic medical centers before procurement centralization fragments vendor relationships. For New Entrants and Emerging Players: FDA breakthrough device designation in the United States opens a window for software-as-a-service distribution models that bypass capital-intensive hardware manufacturing. Target India's government hospital infrastructure programs where procurement decisions are consolidating across metropolitan tertiary care networks. Deploy cloud-based adaptive planning modules to ambulatory surgical centers seeking oncology service line expansion without vault infrastructure investment. For Investors and Strategic Acquirers: Diversified medical device conglomerates are the most active acquirer in this space, seeking robotic platform pure-plays with captive software ecosystems. Five-to-ten year viability hinges on reimbursement durability for hypofractionated regimens. Watch CMS national coverage determinations for stereotactic body radiation therapy as the signal indicating capital equipment return-on-investment inflection.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Accelerates clinical trial timelines for stereotactic systems seeking United States market access. |
| Real-Time MRI Integration Partnership | Enables soft-tissue tracking capabilities for lung and liver lesions in German academic centers. |
| Service Contract Unbundling | Fragments traditional vendor lock-ins across hardware, software, and maintenance components. |
| Software-as-a-Service Distribution | Reduces upfront capital barriers for ambulatory surgical centers in India's expanding infrastructure. |
| Artificial Intelligence-Enabled Planning | Reduces physicist labor hours per fraction while expanding treatment capacity. |
Study Parameters
Direct dialogue with radiation oncologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers grounded the qualitative assessment, supplemented by FDA 510(k) filings, CMS national coverage determination databases, hospital procurement records, and EU MDR notified body documentation. Bottom-up installed base enumeration across United States, German, and Japanese tertiary care centers triangulated against top-down capital expenditure flows from integrated delivery network disclosures.
Market size and growth trajectory outputs reflect segment-level modeling across robotic systems, radiation delivery systems, treatment planning systems, and software solutions, with further disaggregation by oncology, neurosurgery, palliative care, and orthopedic surgery applications. CAGRs derive from regression analysis of historical capital equipment procurement cycles, reimbursement policy shifts, and technology adoption S-curves. Procedure volume forecasts incorporate physicist staffing ratios, vault infrastructure capacity constraints, and hypofractionation protocol penetration assumptions.
Revisions become necessary when CMS reimbursement determinations for stereotraction regimens, EU MDR certification timelines for active therapeutic devices, or supply disruptions in German and Japanese magnetron manufacturing materialize. Forecasts reflect documented assumptions regarding hospital capital budget prioritization and integrated delivery network procurement centralization. A model refresh is warranted upon material change in FDA breakthrough device designation grant rates or Japan's MHLW stereotactic body radiation therapy reimbursement categories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Brazil Respiratory Devices Market
Medical Devices
Mexican Intraocular Lens Market
Medical Devices
Brazil Artificial Organs and Bionic Implants Market
Medical Devices
Medical Device Outsourcing Market
Medical Devices
Zygomatic and Pterygoid Implants Market
Medical Devices
Intrauterine Devices (IUD) Market
Medical Devices
Pectus Bar System Market
Medical Devices
Motorized Prosthesis Market
Medical Devices
Acute External Ventricular Drain Market
Medical Devices
Global Diagnostic Catheter Market
Medical Devices
Transabdominal Retrieval Kits Market
Medical Devices
AI Colonoscopy Withdrawal Quality Monitoring System Market
Medical Devices
Italy Medical Device Regulatory Affairs Market
Medical Devices
Cryoablation System Market
Medical Devices
Global Refractive Surgery Devices Market
Medical Devices
Polyglyconate Sutures Market